
 Rare Neurological Disease Treatment Market | 2026-2036
Rare Neurological Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Neurological Disease Treatment Market Outlook
Buyer concentration among specialty neurology centers is hardening as hospital networks consolidate rare disease referral pathways into designated centers of excellence. Biogen sustains its leadership in spinal muscular atrophy through antisense oligonucleotide platforms. Roche dominates the multiple sclerosis landscape with its ocrelizumab franchise. Sarepta Therapeutics specializes in Duchenne muscular dystrophy gene therapy development, occupying a narrow but defensible niche.
Rare neurological disease treatment encompasses pharmacological and biologic interventions targeting conditions with prevalence below one in two thousand individuals, including antisense therapies, recombinant enzymes, and adeno-associated viral vectors designed to modify disease progression or restore functional protein expression. Gene therapies command premium reimbursement due to one-time administration models and curative intent, while enzyme replacement therapies represent the mature revenue base with established infusion infrastructure. Monoclonal antibodies lead the amyotrophic lateral sclerosis pipeline, and small molecule drugs retain dominance in epilepsy management where chronic oral administration remains standard.
The FDA orphan drug program and EMA's committee for orphan medicinal products shape clinical trial incentives and market exclusivity frameworks, directly influencing developer prioritization and investment timelines. HIPAA governs patient data flows in US-based precision neurology programs, while the EU AI Act imposes conformity requirements on algorithmic diagnostic tools used in rare disease identification. Stakeholders must monitor evolving gene therapy manufacturing standards and adaptive reimbursement mechanisms as treatment modalities shift from chronic administration to single-intervention models.
Market Dynamics
The transition from chronic administration to single-intervention gene therapies is compressing reimbursement timelines and forcing manufacturers to absorb multi-million-dollar production costs before revenue recognition, fundamentally altering capital deployment strategies across the value chain.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates clinical trial timelines and grants seven-year market exclusivity, directly shortening developer cash runway requirements.
- Antisense Oligonucleotide Platforms:These RNA-targeting modalities enable disease modification in previously untreatable conditions, expanding addressable patient populations in spinal muscular atrophy and Huntington's disease.
- Specialty Neurology Center Consolidation:Hospital networks in the United States and Germany are centralizing rare disease referrals into designated centers of excellence, concentrating high-value prescribing decisions.
Market Restraints
- Plasmid DNA Supply Concentration:Manufacturing of gene therapy starting material depends on a limited network of GMP-certified facilities, creating single-source vulnerability.
- EMA Adaptive Pathway Friction:Conditional approval mechanisms require extensive post-authorization evidence generation, extending commercial uncertainty windows.
- Enzyme Replacement Therapy Substitution:Established infusion-based regimens for lysosomal storage disorders present a lower-risk clinical alternative to unproven gene therapy candidates.
Strategic Opportunities
- Japan's Sakigake Designation:Priority review pathways for regenerative medicines offer first-mover advantages in the world's third-largest pharmaceutical market.
- Adeno-Associated Viral Vector Manufacturing:Contract development organizations with spare bioreactor capacity can capture value from developers lacking in-house production infrastructure.
- At-Home Subcutaneous Administration:Self-injection formulations for chronic therapies reduce infusion center burden and expand rural patient access.
Industry Challenges
- Gene Therapy Manufacturing Skill Gap:Viral vector production requires specialized expertise in transfection optimization and empty capsid separation that exceeds current workforce supply.
- HIPAA-Compliant Real-World Evidence Collection:Long-term outcome tracking for one-time therapies demands interoperable data infrastructure that most health systems lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Neurological Disease Treatment Market |
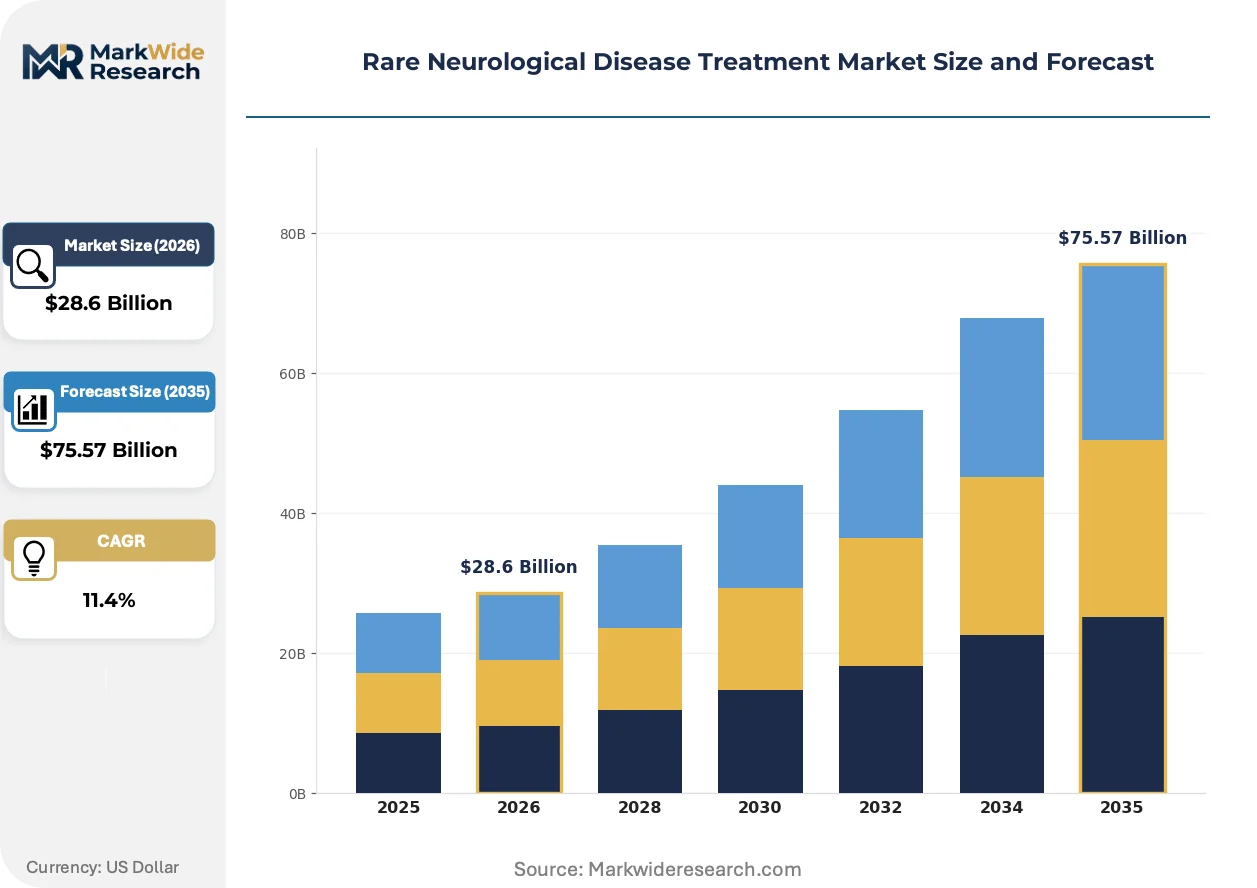
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Drugs, Gene Therapies, Enzyme Replacement Therapies Administration Route: Intravenous, Subcutaneous, Oral, Intraosseous Target Patient Group: Pediatric Patients, Adults, Gerontology, Special Needs Therapeutic Area: Epilepsy, Amyotrophic Lateral Sclerosis, Dystonia, Huntington's Disease |
| Companies Covered | Biogen, Roche, Novartis, Sanofi, CSL Behring, Merz Pharma, Kedrion Biopharma, Ionis Pharmaceuticals, Sarepta Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Neurological Disease Treatment Market Strategic Shifts
Gene therapy manufacturing scale-up and regulatory science harmonization are converging to compress development timelines, while reimbursement innovation struggles to keep pace with curative intent pricing models.
Adeno-associated viral vectors are absorbing the majority of gene therapy pipeline investment due to their established safety profile and tissue-specific tropism. Specialty neurology centers in the United States and Germany are adopting these platforms at accelerating pace for conditions including Duchenne muscular dystrophy and spinal muscular atrophy. The technology is absorbing development resources from small-molecule programs, reshaping competitive positioning across the rare disease landscape.
The EU AI Act imposes conformity assessment requirements on algorithmic diagnostic tools used in rare disease identification, mandating documentation of training data provenance and performance validation. Developers of machine learning-based patient finding systems must now navigate notified body review processes before commercial deployment. Germany's precision neurology networks are responding by establishing internal compliance functions ahead of enforcement timelines.
Buyer concentration among consolidated hospital networks is compressing negotiation cycles and demanding outcome-based warranty structures for high-cost one-time therapies. Traditional fee-for-service reimbursement models are yielding to indication-specific value frameworks in United States Medicare Advantage plans. This shift is most visible in Medicaid programs managing spinal muscular atrophy gene therapy access through prior authorization carve-outs.
Rare Neurological Disease Treatment Market Segmentation
Rare neurological disease treatment markets fragment across therapeutic modality, delivery mechanism, and patient demographics. Each segmentation axis carries distinct regulatory pathways, reimbursement structures, and manufacturing requirements that shape commercial strategy.
Product Type:
Product type segmentation reflects the upgrade cycle from chronic maintenance toward curative intervention, with developers reallocating R&D investment toward platforms promising disease modification.
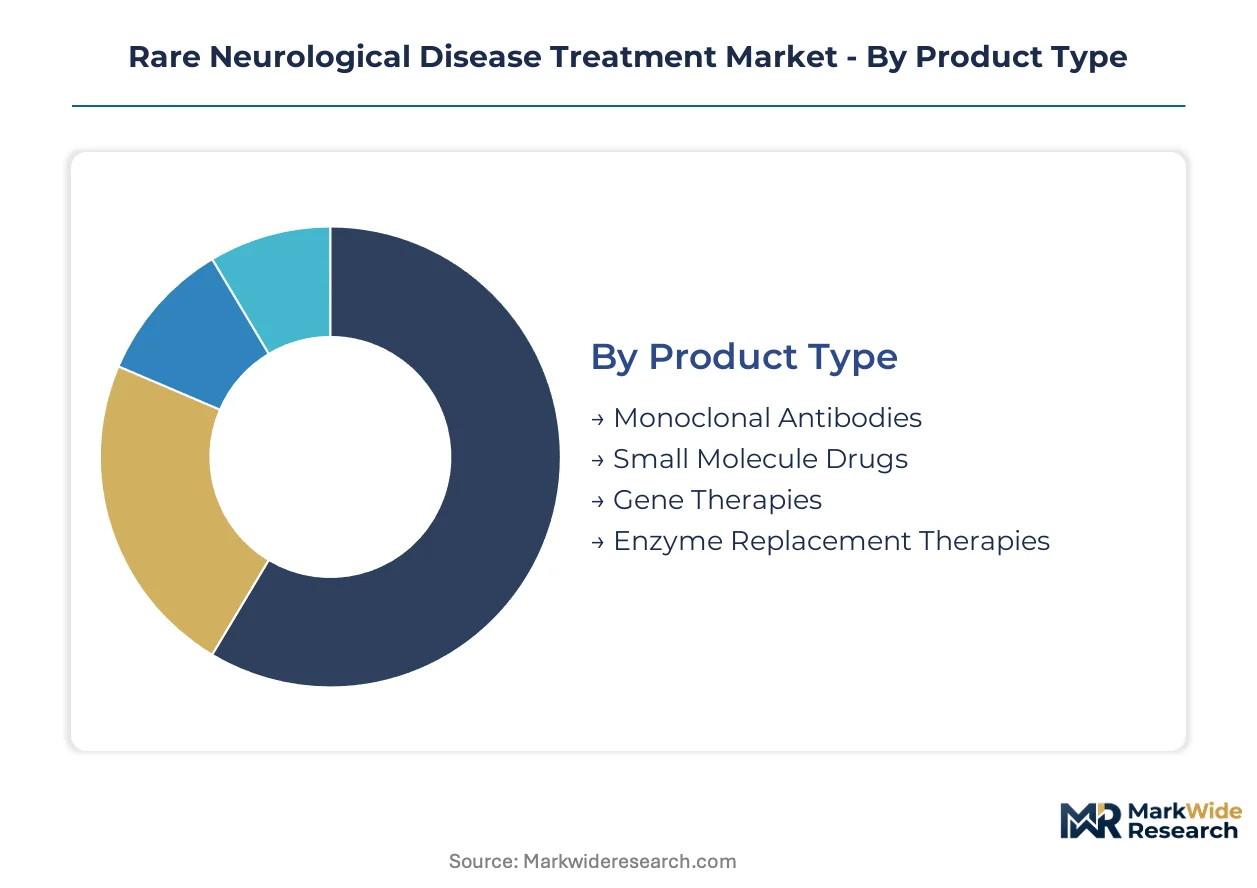
- Gene Therapies:Adeno-associated viral vectors deliver functional gene copies to neural tissue, enabling one-time administration. Demand concentrates in spinal muscular atrophy and Duchenne muscular dystrophy programs across United States and Germany, driven by FDA orphan drug exclusivity and EMA conditional approval pathways.
- Monoclonal Antibodies:Engineered immunoglobulins target specific protein pathways in amyotrophic lateral sclerosis and multiple sclerosis. Roche's ocrelizumab franchise commands prescribing decisions at consolidated United States neurology centers, where infusion infrastructure supports chronic administration models.
- Small Molecule Drugs:Oral bioavailable compounds modulate neurotransmitter systems and ion channel function for epilepsy management.
- Enzyme Replacement Therapies:Recombinant protein infusions address lysosomal storage disorders with established supply chains and predictable reimbursement.
Gene therapies sit at the top of the volume ranking, with monoclonal antibodies climbing the fastest as biosimilar competition intensifies in multiple sclerosis.
Administration Route:
Route selection tracks patient convenience preferences and healthcare system capacity constraints, with subcutaneous formulations gaining development priority for chronic conditions.
- Intravenous:Hospital-based infusion delivery for high-potency biologics and enzyme replacement therapies, requiring specialized nursing staff and adverse event monitoring infrastructure.
- Subcutaneous:Self-administered injection devices reduce clinic burden and expand rural access for chronic therapies.
- Oral:Small molecule formulations dominate epilepsy and Huntington's disease maintenance, with bioavailability challenges in blood-brain barrier penetration.
- Intraosseous:Emergency vascular access for acute neurological crises, limited to hospital and pre-hospital settings.
Intravenous administration retains the largest procedure volume, though subcutaneous delivery is expanding most quickly as home-care programs mature.
Target Patient Group:
Patient group segmentation aligns developmental toxicology requirements with disease natural history, as pediatric indications often precede adult approvals for congenital conditions.
- Pediatric Patients:Spinal muscular atrophy gene therapies and antisense oligonucleotides target developmental windows, with FDA pediatric voucher incentives accelerating timelines. Prescribing concentrates at United States children's hospitals with specialized neuromuscular programs.
- Adults:Amyotrophic lateral sclerosis and multiple sclerosis interventions address progressive disability in working-age populations, where return-to-work outcomes influence payer value assessments.
- Gerontology:Late-onset neurological conditions including certain Parkinson's variants and vascular dementia presentations.
- Special Needs:Non-verbal and cognitively impaired populations requiring adapted diagnostic protocols and caregiver-administered therapies.
Adult populations generate the highest treatment volume, while pediatric segments gain share fastest as newborn screening expands rare disease identification.
Therapeutic Area:
Therapeutic area concentration follows unmet medical need and addressable patient population size, with amyotrophic lateral sclerosis attracting investment despite clinical trial failure rates.
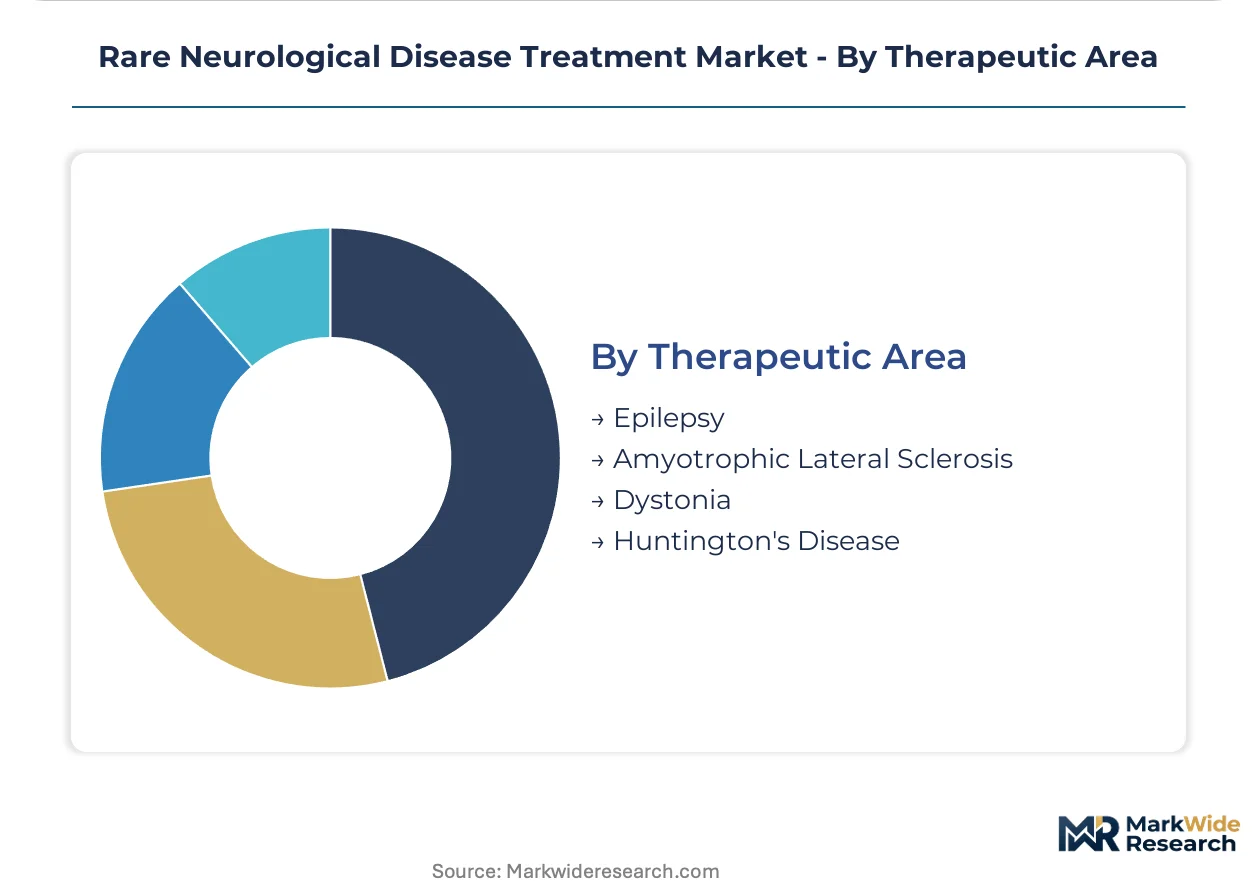
- Amyotrophic Lateral Sclerosis:Progressive motor neuron degeneration with no approved disease-modifying therapy until recent antisense and monoclonal antibody entrants. United States and Germany host the majority of active clinical trials.
- Epilepsy:Chronic seizure disorders maintain the largest treated population, with small molecule drugs retaining standard-of-care status despite gene therapy pipeline expansion.
- Dystonia:Movement disorders including cervical and generalized forms, with botulinum toxin injections and emerging deep brain stimulation alternatives.
- Huntington's Disease:Inherited neurodegeneration with antisense oligonucleotide trials targeting mutant huntingtin protein reduction.
Epilepsy sits at the top of the volume ranking, with amyotrophic lateral sclerosis climbing the fastest as regulatory pathways adapt to accelerated approval for terminal conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates gene therapy demand while the United States dominates antisense oligonucleotide development, creating divergent investment patterns across the Atlantic. Japan's regenerative medicine pathway accelerates commercial timelines in Asia. Regulatory fragmentation between FDA orphan drug exclusivity and EMA conditional approval shapes where developers prioritize clinical trials.
United States
Specialty neurology centers in Boston and San Francisco drive prescribing decisions for spinal muscular atrophy gene therapies. FDA orphan drug designation grants seven-year market exclusivity, shortening developer cash runway requirements. The Greater Philadelphia corridor hosts contract manufacturing organizations producing adeno-associated viral vectors for pipeline candidates.
Germany
Precision neurology networks in Munich and Heidelberg centralize rare disease referrals into designated centers of excellence. EMA's committee for orphan medicinal products governs conditional approval frameworks and post-authorization evidence requirements. Bavaria's biotech cluster attracts gene therapy developers seeking proximity to GMP-certified plasmid DNA facilities.
Japan
PMDA's Sakigake designation offers priority review for regenerative medicines targeting amyotrophic lateral sclerosis and Huntington's disease. The Tokyo-Osaka corridor concentrates demand for one-time administration therapies. METI funding programs support domestic viral vector manufacturing capacity expansion to reduce import dependence.
Switzerland
Swissmedic's streamlined approval pathways attract developers seeking early European market access for enzyme replacement therapies. Basel's pharmaceutical cluster houses antisense oligonucleotide research operations serving global clinical trial networks. The country's precision medicine infrastructure supports real-world evidence collection for outcome-based reimbursement negotiations.
United Kingdom
NHS England's specialized commissioning frameworks govern access to high-cost one-time therapies for pediatric neuromuscular conditions. The Golden Triangle research corridor between London, Oxford, and Cambridge hosts early-stage gene therapy development programs. MHRA's post-Brexit regulatory autonomy enables accelerated approval pathways diverging from EMA timelines.
Rare Neurological Disease Treatment Market Competitive Environment
United States biotechs anchor the gene therapy tier; European pharmaceutical conglomerates hold established positions in enzyme replacement and monoclonal antibodies. Market structure concentrates around three strategic archetypes: antisense platform specialists, viral vector manufacturers, and integrated rare disease commercializers. Capacity expansion into GMP-certified plasmid production and strategic partnerships with contract development organizations dominate competitive moves.
Within the antisense platform tier, Ionis Pharmaceuticals exemplifies RNA-targeting modality development, while Sarepta Therapeutics occupies a narrow but defensible position in Duchenne muscular dystrophy gene therapy. Biogen and Roche sit within the integrated commercializer archetype, leveraging established neurology sales infrastructure across United States and European specialty centers.
| Leading Market Players |
|---|
| Biogen |
| Roche |
| Novartis |
| Sanofi |
| CSL Behring |
| Merz Pharma |
| Kedrion Biopharma |
| Ionis Pharmaceuticals |
| Sarepta Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Curative-intent gene therapy premiums diverge sharply from chronic enzyme replacement maintenance costs, creating a bifurcated pricing landscape where United States Medicare Advantage plans negotiate outcome-based warranties for one-time spinal muscular atrophy interventions while German statutory insurers maintain per-infusion reimbursement schedules for established lysosomal storage regimens. This tier divergence manifests in supply chain configurations: premium-tier viral vector production demands GMP-certified plasmid DNA from Bavarian facilities, while maintenance-tier recombinant protein manufacturing draws from established global fermentation networks with predictable batch economics.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for adeno-associated viral vector manufacturing as contract development organizations expand bioreactor availability. Pricing stratifies across curative gene therapy, chronic monoclonal antibody infusion, and generic small molecule maintenance tiers, with FDA orphan drug exclusivity and EMA conditional approval pathways serving as primary differentiation drivers. Cost compression in the enzyme replacement segment intensifies as biosimilar entrants challenge incumbent recombinant protein franchises. Pediatric neurology centers exhibit lowest price sensitivity due to limited therapeutic alternatives and caregiver urgency, while adult multiple sclerosis clinics face tightening formulary scrutiny.
Supply Chain Analysis
Return flows for cryopreserved viral vector lots and expired biologic materials require specialized cold-chain logistics coordination between United States specialty neurology centers and contract manufacturing organizations. Plasmid DNA supply concentrates in Germany, the United States, and Switzerland, with GMP-certified facility capacity serving as the constraining input. Raw material dependencies include recombinant enzymes, synthetic oligonucleotide building blocks, and fetal bovine serum for cell culture media. Single-source vulnerability in plasmid production creates structural risk exposure. Distribution runs through consolidated hospital network procurement offices and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare neurological disease treatment functions as a regulatory compounder where FDA orphan drug designation and EMA conditional approval frameworks directly accelerate developer timelines and expand addressable patient populations. The FDA's seven-year market exclusivity provision serves as the pivotal demand catalyst, shortening cash runway requirements and attracting venture allocation toward antisense and gene therapy platforms.
For Market Incumbents: Anticipate antisense oligonucleotide substitution pressure in spinal muscular atrophy as next-generation gene therapy candidates advance through clinical validation. Biogen and Roche should prioritize backward integration into plasmid DNA manufacturing to secure GMP-certified supply against Bavarian facility bottlenecks. Capacity expansion in the Greater Philadelphia corridor offers defensive positioning against emerging contract development organization competitors.
For New Entrants and Emerging Players: Direct-to-patient digital platforms for at-home subcutaneous administration represent the most penetrable route into United States rural markets underserved by infusion center infrastructure. White-space targets include Japan's Sakigake-designated regenerative medicine pathway and Medicaid prior authorization carve-outs for spinal muscular atrophy gene therapy access. Telemedicine-enabled prescriber education programs offer differentiated go-to-market positioning against established neurology sales forces.
For Investors and Strategic Acquirers: Consolidation pressure builds where contract manufacturing organizations possess spare viral vector bioreactor capacity and established FDA inspection histories. Long-term viability favors developers with diversified modality pipelines spanning gene therapy, antisense, and small molecule platforms rather than single-technology bets. The signal to watch is EMA adaptive pathway friction resolution, which would compress commercial uncertainty windows and revalue late-stage European pipeline assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA orphan drug designation accelerates amyotrophic lateral sclerosis antisense candidate timelines. |
| Manufacturing Scale-Up | GMP-certified plasmid DNA capacity expansion in Bavaria reduces single-source supply risk. |
| Regulatory Approval Pathway | Japan's Sakigake designation offers priority review for Huntington's disease gene therapies. |
| Strategic Partnership | Specialty neurology center alliances concentrate high-value prescribing decisions in Boston and San Francisco. |
| Reimbursement Strategy | Outcome-based warranty structures align United States Medicare Advantage plan interests with curative intent pricing. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers with secondary validation against FDA orphan drug filings, EMA committee for orphan medicinal products submissions, ClinicalTrials.gov protocol records, and CMS Medicare Advantage formulary databases. Bottom-up patient population sizing and top-down pharmaceutical revenue triangulation anchored market estimates.
Historical reference periods spanning gene therapy commercial launches and antisense oligonucleotide regulatory approvals established baseline growth trajectories across the projection horizon. The analytical framework modeled treatment modality, administration route, patient demographics, therapeutic area, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from patent expiry curves, biosimilar entry timelines, and newborn screening expansion rates. Forecast inputs included viral vector manufacturing capacity buildouts and EMA adaptive pathway utilization trends.
The model assumes a particular technology adoption path; alternative pathways for adeno-associated viral vector manufacturing scale-up would alter the outlook if plasmid DNA supply constraints persist longer than baseline assumptions. Forecasts reflect assumptions about FDA orphan drug designation retention and EMA conditional approval conversion rates. Practitioners should monitor EMA post-authorization evidence generation requirements and United States Medicaid gene therapy prior authorization carve-out adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Muckle-Wells Syndrome Market