
 Artificial Intelligence (AI) in Medical Diagnostics Market | 2026-2036
Artificial Intelligence (AI) in Medical Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Medical Diagnostics Market Insights
The AI medical diagnostics sector is consolidating around two distinct performance tiers. Premium platforms integrate deep learning models with real-time clinical decision support, while commodity offerings deliver basic image classification without workflow embedding. Siemens Healthineers leverages its imaging hardware installed base to bundle AI modules directly into CT and MRI consoles. Aidoc competes through emergency radiology specialization, sustaining rapid triage algorithms for pulmonary embolism and intracranial hemorrhage detection.
Artificial intelligence in medical diagnostics encompasses computational systems that analyze clinical data—radiological images, histopathological slides, laboratory values, and electronic health records—to detect disease patterns with specified sensitivity and specificity thresholds, primarily to augment clinician decision-making and reduce diagnostic latency. Image analysis currently anchors revenue generation as legacy PACS vendors retrofit convolutional neural networks into existing radiology workflows. Deep learning within the technology dimension is capturing disproportionate R&D investment due to its superior performance in computer vision tasks across pathology and cardiology applications.
The FDA regulates AI diagnostic software under its software-as-a-medical-device pathway, requiring predetermined change control plans for algorithms that learn from new data. The EU AI Act classifies most diagnostic AI as high-risk, mandating conformity assessments before CE marking under MDR requirements. Stakeholders must monitor whether regulatory divergence between American and European premarket review timelines fragments product launch sequencing and inflates compliance overhead for multi-jurisdictional developers.
Market Dynamics
Deep learning architectures are compressing diagnostic latency from hours to minutes, forcing radiology departments to restructure workflows around real-time algorithmic triage rather than batch image review. Siemens Healthineers and Aidoc exemplify divergent competitive responses—hardware bundling versus emergency specialization—each extracting value from distinct points in the imaging value chain.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The predetermined change control plan requirement accelerates regulatory clarity for adaptive algorithms, reducing premarket uncertainty for developers targeting the United States.
- Convolutional Neural Network Integration:Legacy PACS vendors retrofit deep learning modules into existing radiology infrastructure, lowering deployment friction for hospital systems with sunk capital in imaging hardware.
- China's AI Health Infrastructure Buildout:Government-directed investment in smart hospital networks concentrates procurement authority at provincial health commissions, streamlining bulk purchasing of diagnostic algorithms.
Market Restraints
- EU AI Act Conformity Costs:High-risk classification mandates MDR-aligned conformity assessments before CE marking, inflating compliance overhead for multi-jurisdictional developers relative to single-market pathways.
- Training Data Concentration:Curated medical imaging datasets cluster at academic medical centers in the United States, Germany, and China, creating access asymmetries for developers outside these nodes.
- Interpretability Limitations:Black-box deep learning models face resistance from liability-averse hospital legal departments requiring auditable decision trails for malpractice defense.
Strategic Opportunities
- Pathology Digitalization Lag:Histopathological slide analysis remains underpenetrated relative to radiology, offering first-mover advantage for computer vision platforms targeting oncology biomarker detection.
- Cardiology Workflow Embedding:Echocardiography and cardiac MRI algorithm deployment trails CT and chest X-ray adoption, presenting whitespace for vendors with cardiovascular specialization.
- Germany's DVG Reimbursement Pathway:The Digital Health Applications framework creates explicit reimbursement codes for approved diagnostic algorithms, reducing hospital procurement risk.
Industry Challenges
- Clinical Validation Timeline Compression:Retrospective algorithm training on biased datasets produces performance degradation in prospective deployment, forcing costly prospective trial redesigns.
- PACS Integration Complexity:Legacy radiology information systems require custom API development for seamless AI module embedding, extending sales cycles and inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Medical Diagnostics Market |
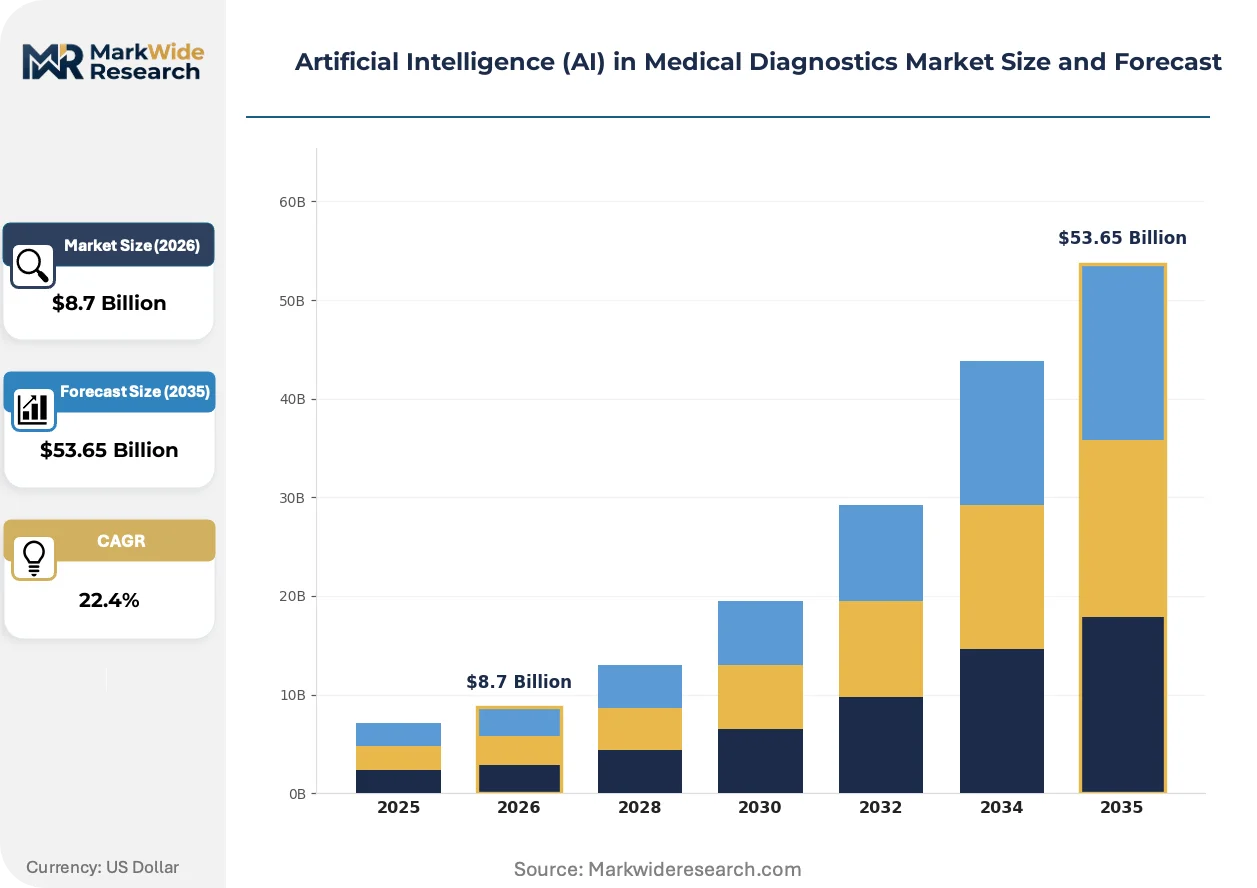
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Image Analysis, Predictive Analytics, Clinical Decision Support, Natural Language Processing Application: Radiology, Pathology, Laboratory Diagnostics, Cardiology End User: Hospitals, Diagnostic Centers, Research Laboratories, Health Clinics Technology: Machine Learning, Deep Learning, Neural Networks, Computer Vision |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Aidoc, NVIDIA Corporation, Microsoft, Digital Diagnostics, Vuno, PathAI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Medical Diagnostics Market Trends and Innovations
Foundation models trained on multimodal clinical data are collapsing the traditional segmentation between imaging and non-imaging diagnostics, enabling unified diagnostic platforms that span radiology, pathology, and laboratory medicine.
Federated learning architectures are absorbing distributed training protocols that preserve data locality at hospital sites while aggregating model updates centrally. Academic medical centers in the United States and Germany are piloting these frameworks to circumvent cross-border data transfer restrictions. The structural consequence is a shift from centralized data lake models toward edge-computing deployments that reduce bandwidth costs and regulatory exposure.
The EU AI Act's high-risk classification for diagnostic algorithms is forcing developers to maintain comprehensive risk management systems and post-market surveillance protocols. Manufacturers targeting European markets must now document algorithm performance across diverse demographic subgroups before CE marking. Cardiology applications face particular scrutiny given the clinical consequence of false-negative detection in acute coronary syndrome triage.
Hospital procurement committees are consolidating vendor relationships around integrated platform providers rather than point-solution specialists. Radiology departments in China and the United States increasingly demand bundled contracts spanning hardware, software, and maintenance. This concentration favors incumbent imaging equipment manufacturers with established service infrastructure over pure-play AI developers lacking field engineering networks.
Artificial Intelligence (AI) in Medical Diagnostics Market Segmentation
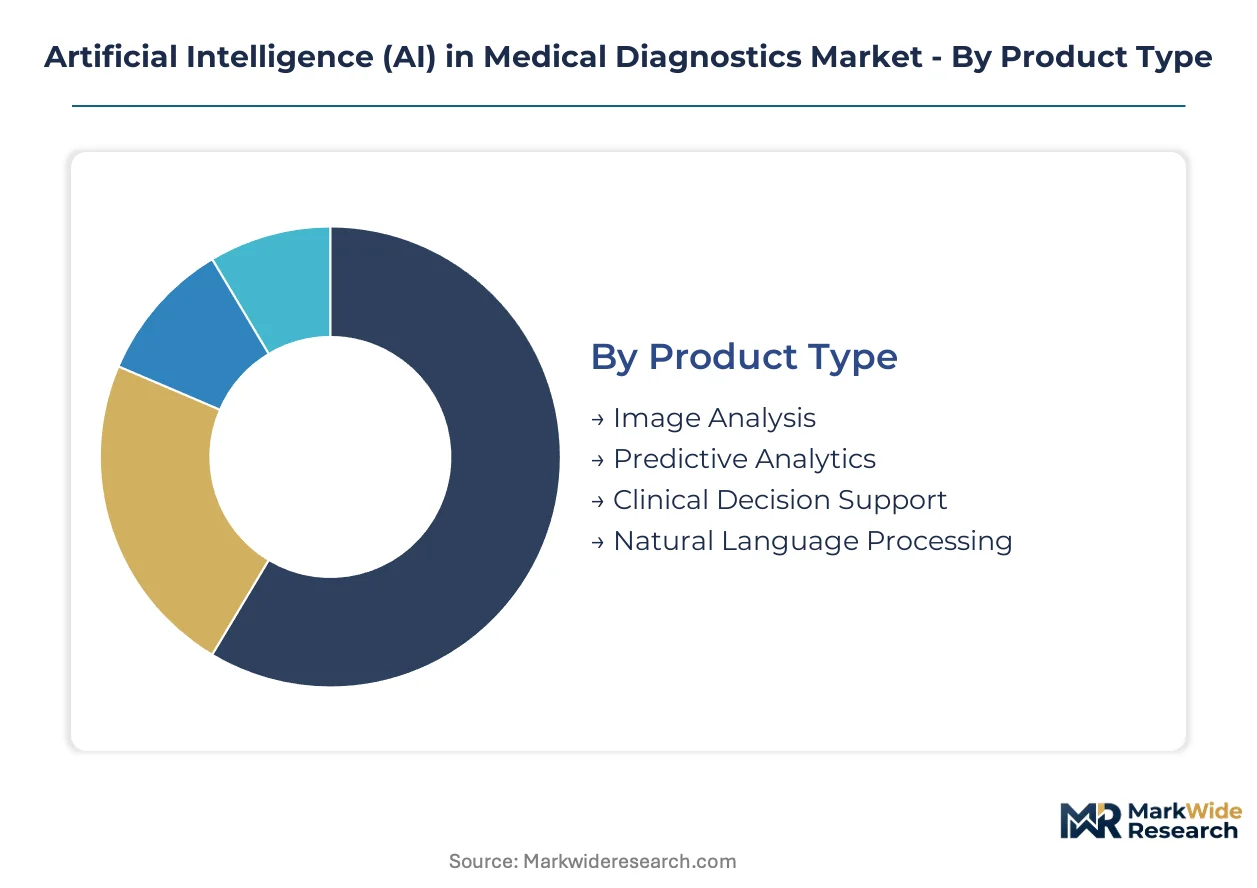
Segmentation in AI medical diagnostics reveals how value accrues unevenly across technical architectures and clinical workflows. Product type and application dimensions expose where algorithmic performance commands premium pricing versus commodity deployment.
Product Type:
Volume concentration clusters in image classification modules, while premium capture sits with integrated clinical decision systems that embed directly into electronic health records.
- Image Analysis:Convolutional neural networks process radiological scans and histopathological slides with specified sensitivity thresholds. Demand concentrates in the United States and Germany where academic medical centers retrofit legacy PACS infrastructure with AI modules.
- Clinical Decision Support:Real-time algorithmic recommendations trigger at point-of-care through integration with hospital information systems. China's smart hospital buildout drives procurement of these embedded platforms at provincial health commissions.
- Predictive Analytics:Risk stratification algorithms forecast disease progression from longitudinal patient data.
- Natural Language Processing:Clinical documentation mining extracts diagnostic insights from unstructured electronic health records.
Mature deployment sits with Image Analysis. Newer deployment is concentrated in Clinical Decision Support.
Application:
Radiology absorbs the majority of algorithmic deployment, while pathology and cardiology present whitespace for specialized platforms.
- Radiology:CT, MRI, and chest X-ray analysis dominates current revenue as FDA-cleared algorithms proliferate for pulmonary embolism and intracranial hemorrhage detection. Siemens Healthineers bundles these modules directly into imaging hardware consoles.
- Pathology:Digital slide analysis for oncology biomarker detection remains underpenetrated relative to radiology. First-mover advantage accrues to computer vision platforms targeting histopathological workflows.
- Cardiology:Echocardiography and cardiac MRI algorithm deployment trails other modalities.
- Laboratory Diagnostics:Automated interpretation of laboratory values integrates with existing LIS infrastructure.
Established clinical validation sits with Radiology. Steepest expansion trajectory is emerging in Pathology.
End User:
Procurement authority centralizes at hospital systems with capital budgets for integrated platform contracts, fragmenting across smaller diagnostic facilities.
- Hospitals:Radiology and pathology departments purchase bundled hardware-software contracts spanning CT consoles and AI modules. China's provincial health commissions streamline bulk purchasing for smart hospital networks.
- Diagnostic Centers:Standalone imaging facilities deploy point-solution algorithms without deep EHR integration. Germany's DVG reimbursement pathway reduces procurement risk for these mid-scale operators.
- Research Laboratories:Academic medical centers in the United States and Germany pilot federated learning frameworks.
- Health Clinics:Primary care settings adopt lightweight screening tools with lower computational requirements.
Consolidated purchasing power sits with Hospitals. Emerging demand is concentrating in Diagnostic Centers.
Technology:
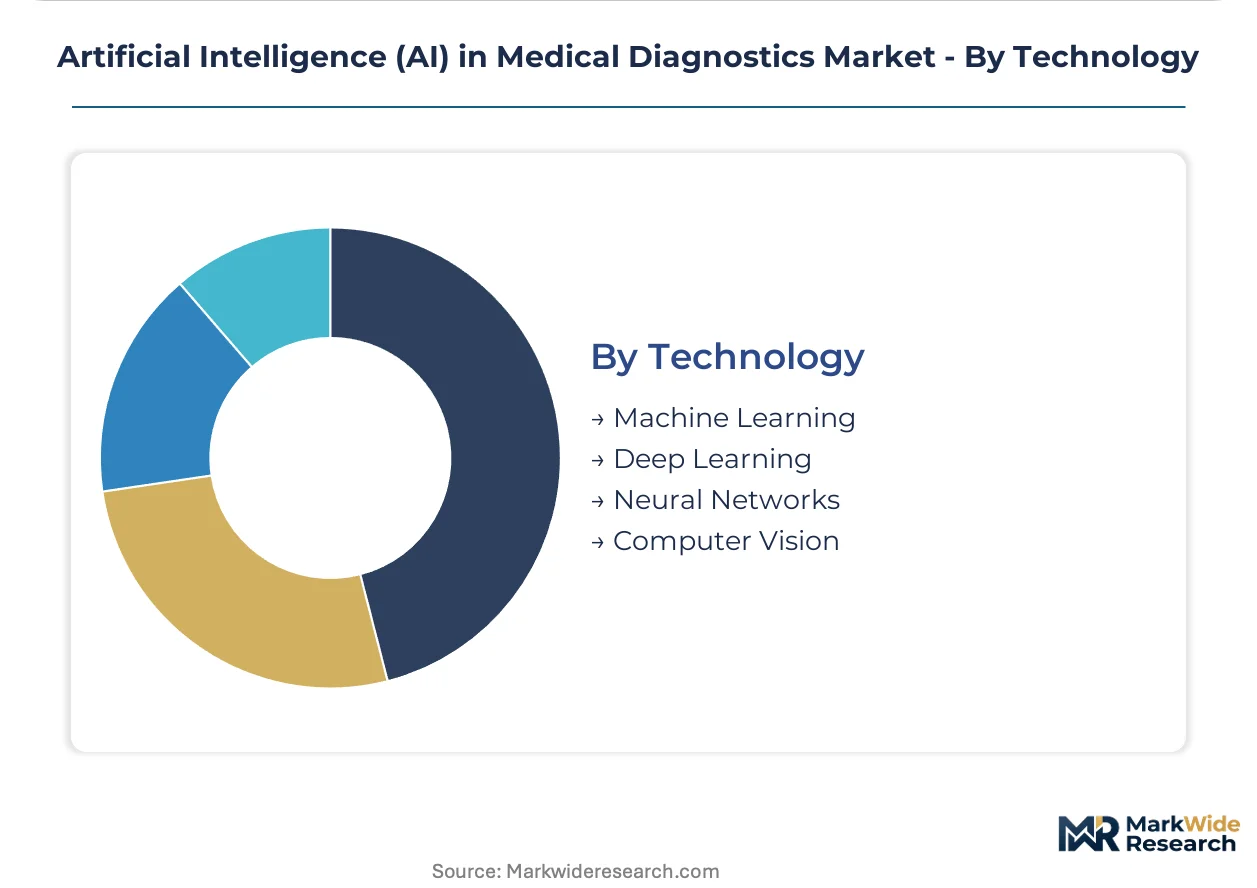
Deep learning architectures capture disproportionate R&D investment, while traditional machine learning persists in regulated applications requiring interpretable decision trails.
- Deep Learning:Multi-layer neural networks achieve superior performance in computer vision tasks across pathology and cardiology applications. The FDA's predetermined change control plan requirement accelerates regulatory clarity for these adaptive algorithms.
- Computer Vision:Specialized architectures process medical imaging with pixel-level precision for lesion detection and segmentation. Integration with legacy PACS systems drives deployment friction in hospital radiology departments.
- Machine Learning:Traditional statistical methods persist where model interpretability is mandated for liability defense.
- Neural Networks:Feedforward and recurrent architectures support non-imaging diagnostic tasks.
Regulatory headwinds concentrate on Deep Learning. Fastest technical maturation is occurring in Computer Vision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American AI diagnostic development through its concentration of academic medical centers and venture-backed algorithm developers clustered around MIT and Harvard-affiliated hospitals.
United States
FDA's software-as-a-medical-device framework accelerates regulatory clarity for adaptive algorithms, while Medicare reimbursement pathways for computer-aided detection reduce hospital procurement risk. The predetermined change control plan requirement enables faster premarket review for deep learning diagnostics. Massachusetts General Hospital and Stanford Medicine pilot federated learning frameworks to preserve data locality while training multicenter algorithms.
Germany
The Digital Health Applications framework creates explicit reimbursement codes for approved diagnostic algorithms, reducing procurement friction for hospital systems. EU AI Act high-risk classification mandates MDR-aligned conformity assessments before CE marking, inflating compliance overhead relative to single-market pathways. Berlin and Munich host concentrated development clusters where Siemens Healthineers integrates AI modules directly into CT and MRI console hardware.
China
Government-directed investment in smart hospital networks concentrates procurement authority at provincial health commissions, streamlining bulk purchasing of diagnostic algorithms. NMPA regulatory pathways for AI medical devices prioritize domestic developers with established clinical validation partnerships. Shanghai and Beijing medical centers deploy real-time clinical decision support systems integrated with hospital information infrastructure.
United Kingdom
NHS England's AI Lab accelerates validation and deployment of diagnostic algorithms through structured procurement frameworks and real-world testing environments. MHRA regulatory alignment with FDA breakthrough device pathways reduces dual-market submission burdens for transatlantic developers. London's academic medical centers concentrate histopathological dataset curation for oncology biomarker detection platforms.
Japan
PMDA regulatory guidelines for AI medical devices emphasize clinical performance validation across diverse patient populations, extending premarket review timelines relative to US pathways. METI industrial policy directs investment toward diagnostic imaging AI as part of broader healthcare digitization targets. Tokyo and Osaka hospital networks prioritize integration of echocardiography algorithms into existing cardiac imaging workflows.
Artificial Intelligence (AI) in Medical Diagnostics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification and clinical validation depth. Hardware-integrated vendors extract value from imaging console bundling, while pure-play algorithm developers compete on emergency specialization and triage speed. Three archetypes dominate: incumbent imaging equipment manufacturers with installed base leverage, emergency radiology specialists with FDA-cleared triage algorithms, and cloud infrastructure providers supplying computational substrate. Dominant competitive moves include strategic partnerships between algorithm developers and PACS vendors, plus backward integration by hardware manufacturers into proprietary AI module development.
Among diversified healthcare conglomerates, Siemens Healthineers and GE Healthcare exemplify the hardware-bundling archetype, leveraging imaging equipment installed bases to embed diagnostic algorithms directly into modality consoles. Aidoc occupies a position within the emergency specialization tier, sustaining rapid triage algorithms for acute conditions. NVIDIA Corporation anchors the computational infrastructure layer, supplying GPU architectures that enable real-time inference for deep learning diagnostic models.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Aidoc |
| NVIDIA Corporation |
| Microsoft |
| Digital Diagnostics |
| Vuno |
| PathAI |
| Others |
Pricing and Supply Chain Analysis
GPU compute cycles from NVIDIA's foundry partners in Taiwan and South Korea cascade through cloud infrastructure providers before reaching hospital procurement committees, with each tier extracting margin based on algorithmic performance guarantees and regulatory certification depth.
Pricing Analysis
Value-based pricing anchored to diagnostic throughput and clinical outcome guarantees dominates algorithm licensing contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared triage modules with real-time EHR integration from basic image classification tools lacking workflow embedding. Cost compression in the commodity tier intensifies as legacy PACS vendors bundle convolutional neural networks at marginal cost. Diagnostic centers with constrained capital budgets exhibit highest price sensitivity, while academic medical centers prioritize clinical validation depth over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate qualified secondary suppliers for GPU hardware and cloud inference capacity. Manufacturing concentration clusters in Taiwan, South Korea, and the United States for semiconductor fabrication. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized cooling substrates. Single-source vulnerability persists at the advanced node lithography tier where TSMC dominates leading-edge production. Distribution runs through hyperscale cloud providers including AWS, Azure, and Google Cloud before reaching institutional end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
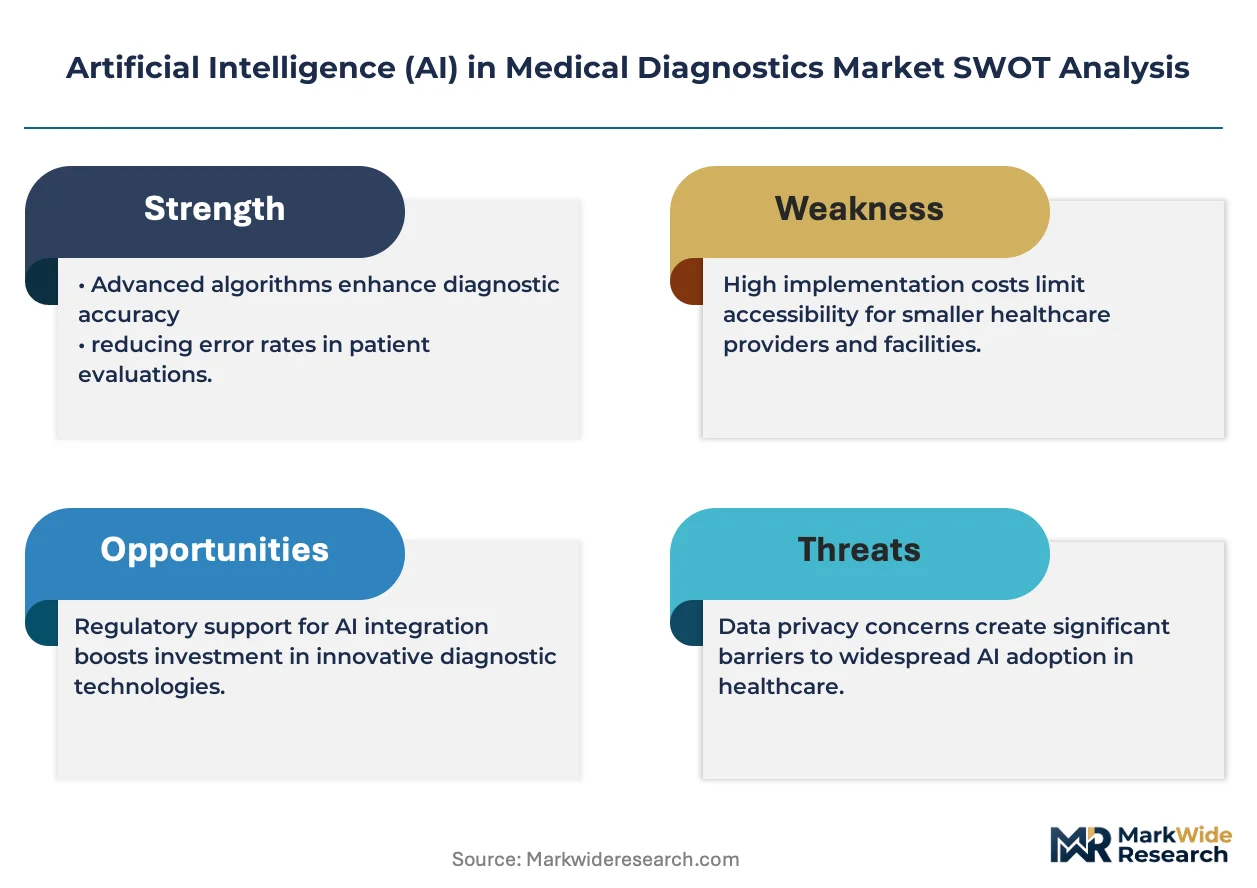
The FDA's predetermined change control plan requirement functions as a cost-of-compliance moat, elevating regulatory affairs investment into a barrier-to-entry mechanism that favors incumbent developers with established 510(k) submission track records.
For Market Incumbents: Acquire federated learning deployment capabilities to neutralize data localization requirements from Germany's BfArM and China's NMPA. Consolidate around pathology digitalization platforms before first-mover windows close. Threat from emergency radiology specialists with rapid triage algorithms demands defensive bundling of clinical decision support into existing PACS relationships. Certification investment in EU AI Act conformity assessment procedures protects European revenue streams. For New Entrants and Emerging Players: Premium-economy price-point gaps in cardiology algorithm deployment create entry corridors for specialized echocardiography platforms. Target Germany's diagnostic center segment where DVG reimbursement codes reduce procurement friction for mid-scale operators. White-space concentration in histopathological oncology biomarker detection offers penetrable terrain ahead of radiology saturation. Go-to-market leverage rests on provincial health commission relationships in China's smart hospital buildout corridors. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play algorithm developers with FDA-cleared 510(k) portfolios in the United States over hardware-dependent incumbents facing margin compression. Long-term viability across the analysis window hinges on regulatory certification durability rather than technical performance alone. Acquisition target archetype: emergency radiology specialists with established hospital system contracts and adaptive algorithm architectures. Signal to watch: NMPA approval velocity for domestic versus foreign developers as proxy for Chinese market access trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predetermined change control plans from FDA compress premarket review timelines for adaptive algorithms. |
| EU AI Act Conformity Assessment | MDR-aligned documentation requirements from notified bodies inflate compliance overhead for multi-jurisdictional developers. |
| Hospital System Partnership Expansion | Provincial health commissions in China streamline bulk purchasing through smart hospital network mandates. |
| Pathology Platform Development | Digital slide analysis for oncology biomarker detection remains underpenetrated relative to radiology workflows. |
| Federated Learning Deployment | Edge-computing architectures preserve data locality at German and US academic medical centers while enabling multicenter training. |
Research Methodology
FDA 510(k) filings, EU MDR conformity assessment databases, and hospital procurement contract records formed the secondary backbone. Primary interviews with radiology department heads, biomedical engineers, GPO contracts managers, and regulatory affairs leads at algorithm developers supplied forward-looking deployment timelines. Bottom-up triangulation across installed base estimates for CT and MRI consoles combined with top-down validation against health system IT expenditure surveys.
Historical trendline analysis of algorithm approval velocity and reimbursement code creation established baseline growth parameters. Segmentation modeling spanned product type, clinical application, end-user facility scale, and technology architecture across the projection horizon. CAGR derivation incorporated regulatory pathway duration, hospital capital budget cycles, and provincial procurement authorization patterns. Forecast inputs included NMPA approval rates for domestic versus foreign developers and DVG reimbursement expansion trajectories.
Inputs from FDA, EMA, and NMPA regulatory databases were available through the study window; gaps in real-world performance surveillance data introduce uncertainty bands around algorithm effectiveness claims. Forecasts reflect assumptions regarding sustained reimbursement pathway expansion and cloud infrastructure cost curves. Deviation in EU AI Act enforcement intensity or NMPA domestic preference policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Global HLA Typing for Transplant Market