
 Liver Biopsy Market | 2026-2036
Liver Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Liver Biopsy Market Outlook
Software-defined imaging guidance is rebalancing how liver biopsy procedures are packaged and reimbursed, shifting value from disposable instruments toward integrated visualization workflows. BD leverages its interventional radiology portfolio to sustain leadership in automated needle systems. Cook Medical anchors its position through deep specialization in percutaneous access devices for hepatology applications.
A liver biopsy extracts hepatic tissue samples via percutaneous, transjugular, or laparoscopic approaches using hollow needles ranging from 14 to 18 gauge, with specimen lengths of 15–25 mm required for adequate histopathological assessment of fibrosis staging and neoplastic infiltration. Needle biopsy products occupy the largest revenue pool given their ubiquity in cirrhosis detection workflows, while guided imaging delivery modes represent the fastest-expanding segment as ultrasound and CT-navigation reduce sampling variability. Diagnostic laboratories compete for outpatient referrals by positioning rapid turnaround on fibrosis evaluation protocols.
FDA 510(k) clearance requirements and the EU MDR framework govern device safety and clinical performance claims, compelling manufacturers to generate substantial equivalence data or clinical evidence for new needle designs. Japan's PMDA enforces JIS standards for metallic instrument biocompatibility that directly affect import eligibility for Asian suppliers. Stakeholders must monitor how reimbursement authorities in Germany and the United States classify image-guided biopsy codes, as these determinations will dictate capital allocation between disposable innovation and platform-based imaging integration.
Market Dynamics
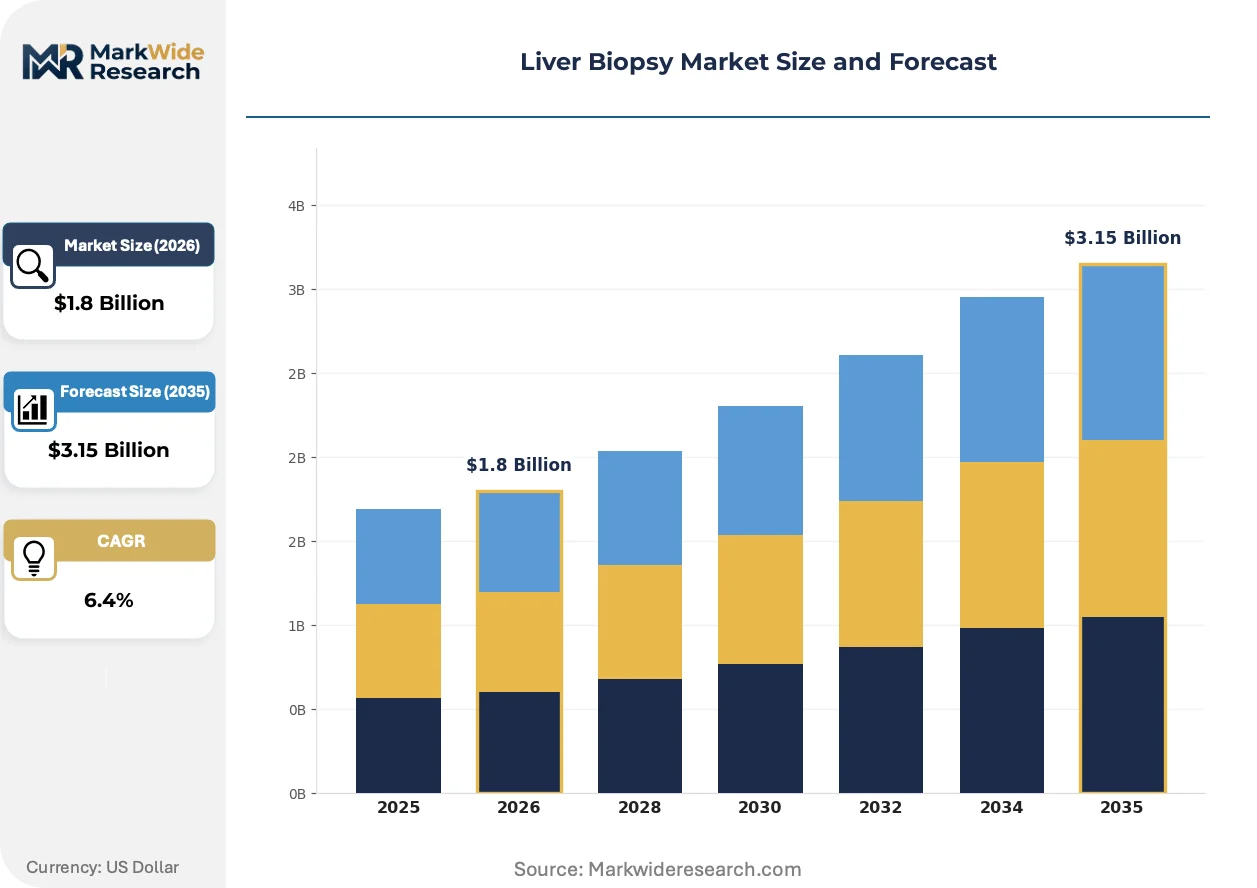
Software-defined imaging guidance is compressing procedure variability while shifting procurement value from standalone needles toward integrated visualization platforms that bundle navigation, sampling, and documentation workflows.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating clinical evidence generation for needle safety claims, creating demand for next-generation biopsy systems with embedded tracking sensors.
- Japan hepatology screening expansion:PMDA reimbursement revisions for image-guided procedures are pulling ultrasound-integrated systems into hospital procurement cycles.
- Transjugular access protocols:Interventional radiology departments adopting specialized catheter systems for patients with coagulopathy, expanding addressable procedure volumes beyond percutaneous candidates.
Market Restraints
- Stainless steel price volatility:Needle raw material costs fluctuate with nickel and chromium spot markets, squeezing margin structures for disposable instrument suppliers.
- Single-supplier dependence for imaging cores:Ultrasound transducer manufacturing concentrates in South Korean and Japanese component houses, creating vulnerability for integrated system vendors.
- Histopathological workforce constraints:Certified liver pathologist availability limits throughput for diagnostic laboratories processing fibrosis staging requests.
Strategic Opportunities
- German outpatient clinic networks:Ambulatory surgical centers seek rapid-turnaround biopsy services with same-day pathology reporting, opening channel expansion for disposable instrument distributors.
- Artificial intelligence-histopathology convergence:Automated fibrosis scoring algorithms are creating demand for standardized tissue acquisition protocols that ensure specimen adequacy for machine learning pipelines.
- US IRA diagnostic access provisions:Medicare reimbursement adjustments for early liver disease detection are redirecting capital toward point-of-care ultrasound systems with biopsy guidance modules.
Industry Challenges
- Cross-platform imaging compatibility:Needle navigation systems must integrate with heterogeneous ultrasound and CT vendor architectures, requiring extensive protocol validation.
- EU MDR technical documentation timelines:Clinical performance studies for modified needle geometries extend certification cycles by 18-24 months, compressing product refresh rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver Biopsy Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy, Surgical Biopsy, Laparoscopic Biopsy, Tru-Cut Biopsy Delivery Mode: Invasive Procedures, Outpatient Services, Hospitalization Services, Guided Imaging End User: Hospitals, Diagnostic Laboratories, Outpatient Clinics, Research Institutes Application: Cirrhosis Detection, Tumor Analysis, Liver Disease Assessment, Fibrosis Evaluation |
| Companies Covered | BD, Argon Medical Devices, Cook Medical, Merit Medical, Boston Scientific, TSK, HAKKO CO., LTD., RI.MOS, Veran Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver Biopsy Market Strategic Shifts
Navigation technology is displacing tactile skill as the primary determinant of sampling adequacy, while regulatory frameworks on both sides of the Atlantic accelerate consolidation around platform-based procurement models.
Real-time electromagnetic needle tracking is absorbing the technical burden of lesion targeting from operator hand-eye coordination. Academic medical centers in the United States and Germany are deploying these systems for cirrhotic liver sampling where anatomical distortion complicates conventional ultrasound visualization. The technology is absorbing market share from freehand techniques by reducing repeat biopsy rates and associated complication liability.
FDA 510(k) substantial equivalence pathways for minimally invasive biopsy devices are tightening evidentiary requirements for needle safety claims. Manufacturers must now submit controlled clinical data on core retention and fragmentation rates, elevating development costs for new instrument geometries. Interventional radiology departments are responding by consolidating purchases around established platforms with cleared predicate histories.
Hospital procurement committees are bundling biopsy needle contracts with imaging system service agreements, unbundling the historical separation between capital equipment and disposable supply purchasing. Integrated delivery networks in Japan and the United States are negotiating multi-year platform commitments that lock in needle sourcing. This concentration is most visible in tertiary hepatology centers where procedure volumes justify dedicated interventional radiology suites.
Liver Biopsy Market Segmentation
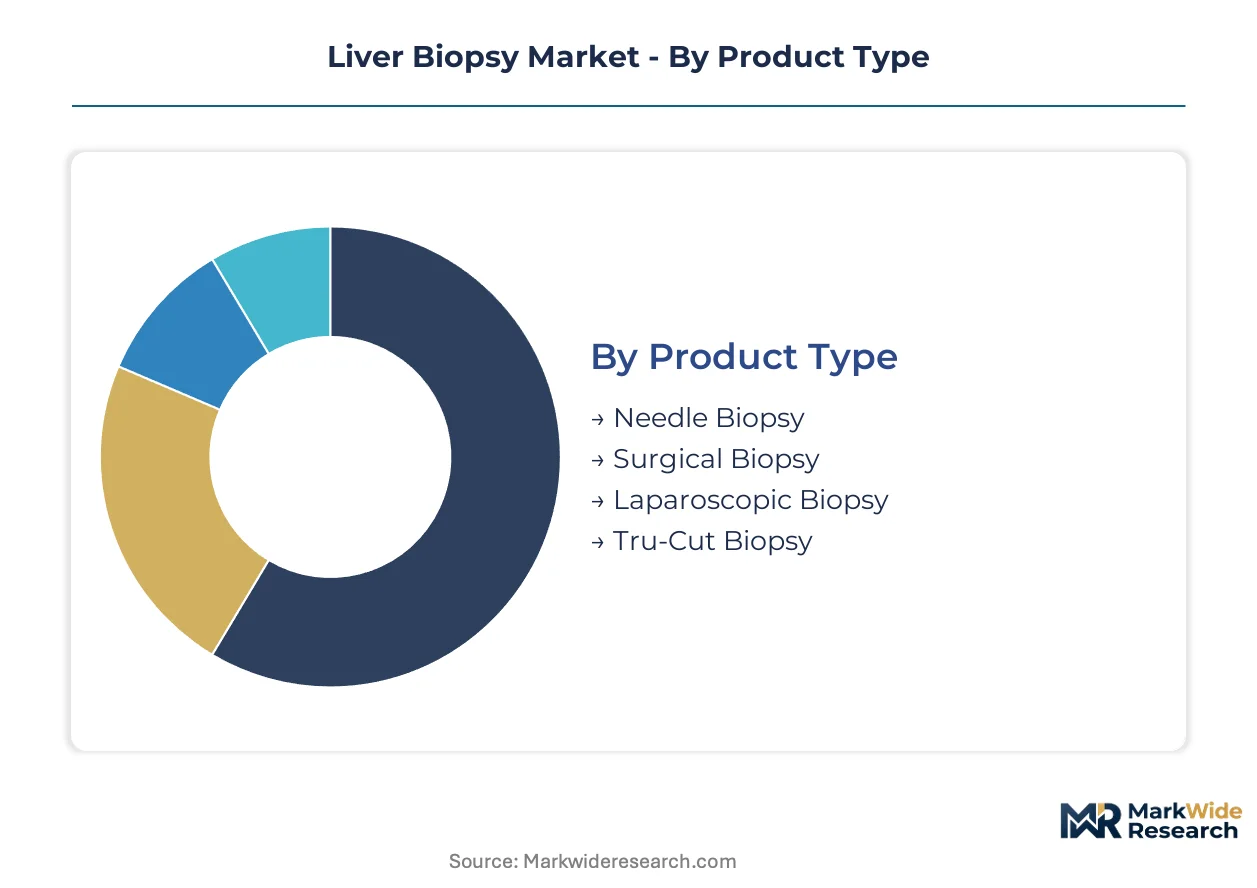
Procurement committees in tertiary hepatology centers bundle needle contracts with imaging platforms, collapsing the historical separation between disposable and capital equipment purchasing. Segment boundaries blur as software-defined guidance reclassifies what constitutes a biopsy "product" versus a "service."
Product Type:
Cost tier determines procurement channel—premium automated systems flow through interventional radiology capital budgets while economy manual needles distribute via surgical supply catalogs.
- Needle Biopsy:Hollow 14–18 gauge instruments deliver 15–25 mm core specimens for histopathological staging. Demand concentrates in United States hospital systems where Medicare reimbursement for image-guided percutaneous procedures incentivizes high-volume workflows.
- Surgical Biopsy:Open operative tissue extraction via laparotomy or targeted wedge resection. German university hospitals maintain specialized hepatobiliary surgery units for complex cases with anatomical distortion, preserving procedural volume despite minimally invasive alternatives.
- Laparoscopic Biopsy:Minimally invasive tissue sampling through trocar ports with direct visualization. Japanese centers integrate these into same-day diagnostic pathways.
- Tru-Cut Biopsy:Spring-loaded cutting needle design with specimen notch retention. Research institutes favor this mechanism for standardized core quality in multi-site studies.
Needle biopsy leads on scale; guided imaging integration is gaining share fastest.
Delivery Mode:
Application urgency reshapes site-of-service decisions—same-day outpatient pathways compete with inpatient observation protocols for coagulopathic patients.
- Invasive Procedures:Percutaneous, transjugular, and surgical access routes requiring tissue penetration. United States interventional radiology departments are expanding transjugular capacity for patients with elevated bleeding risk, extending addressable volumes beyond conventional candidates.
- Outpatient Services:Ambulatory biopsy with observation discharge protocols. German outpatient clinic networks are consolidating procurement around rapid-turnaround vendors offering same-day pathology reporting.
- Hospitalization Services:Inpatient admission with overnight monitoring. Japan's PMDA reimbursement revisions favor shorter stays, compressing this segment's growth trajectory.
- Guided Imaging:Ultrasound, CT, or electromagnetic navigation during tissue acquisition. Academic medical centers in Germany and the United States deploy these systems for cirrhotic liver sampling where anatomical distortion complicates freehand techniques.
Invasive procedures lead on scale; guided imaging climbs the fastest.
End User:
Volume concentration follows hepatology screening program expansion—tertiary centers absorb complex cases while community sites handle routine surveillance.
- Hospitals:Integrated delivery networks with dedicated interventional radiology suites. United States health systems negotiate multi-year platform commitments that lock in needle sourcing alongside imaging service agreements.
- Diagnostic Laboratories:Centralized histopathology processing with fibrosis staging protocols. Certified liver pathologist scarcity constrains throughput in Japan and Germany.
- Outpatient Clinics:Ambulatory surgical centers offering point-of-care ultrasound with biopsy guidance. US IRA diagnostic access provisions redirect capital toward these sites.
- Research Institutes:Multi-site clinical trials requiring standardized tissue acquisition. Automated fibrosis scoring algorithms create demand for specimen adequacy protocols.
Hospitals lead on scale; outpatient clinics show steepest expansion trajectory.
Application:
Reimbursement code definitions determine which indications attract capital investment versus routine screening workflows.
- Cirrhosis Detection:Fibrosis staging for chronic liver disease surveillance. United States hepatology screening expansion drives volume through Medicare-covered protocols.
- Tumor Analysis:Neoplastic infiltration assessment for oncology staging. German comprehensive cancer centers integrate biopsy into multidisciplinary tumor board workflows.
- Liver Disease Assessment:Broad diagnostic evaluation for unexplained hepatic dysfunction. Japanese PMDA revisions for image-guided procedures pull ultrasound-integrated systems into hospital procurement.
- Fibrosis Evaluation:Quantitative staging for treatment response monitoring. Artificial intelligence-histopathology convergence demands standardized acquisition for machine learning pipelines.
Cirrhosis detection leads on scale; fibrosis evaluation shows strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production and clinical trial activities to jurisdictions with streamlined regulatory pathways, exploiting gaps between FDA 510(k) evidentiary demands and EU MDR technical documentation timelines. This arbitrage concentrates investment in markets where hepatology screening expansion coincides with favorable reimbursement mechanics.
United States
Medicare reimbursement codes for image-guided percutaneous procedures incentivize high-volume hospital workflows. The FDA tightens substantial equivalence requirements for needle safety claims, compelling controlled clinical data submissions. Academic medical centers in Boston and Baltimore deploy electromagnetic tracking systems for cirrhotic liver sampling.
Germany
Comprehensive cancer centers integrate biopsy into multidisciplinary tumor board workflows, preserving demand for surgical biopsy alternatives. The EU MDR framework governs device safety claims with extended certification cycles. University hospitals in Munich and Heidelberg maintain specialized hepatobiliary surgery units for anatomically complex cases.
Japan
PMDA reimbursement revisions for image-guided procedures accelerate ultrasound-integrated system procurement. METI screening program expansion pulls capital toward point-of-care diagnostics. Tokyo and Osaka medical centers adopt same-day diagnostic pathways with rapid pathology turnaround.
China
NMPA streamlined review pathways for innovative medical devices attract multinational clinical trial investment. The national hepatology screening initiative expands addressable procedure volumes. Shanghai and Beijing hospital networks consolidate purchasing around integrated imaging platforms.
United Kingdom
NHS England fibrosis pathway standardization creates demand for automated needle systems with embedded quality tracking. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR timelines. London and Manchester tertiary centers negotiate multi-year platform service agreements.
Liver Biopsy Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with interventional radiology capital budgets favoring established platform vendors while surgical supply catalogs sustain commodity needle distributors. The vendor base concentrates around three tiers: integrated imaging-needle platform providers, disposable instrument specialists, and regional OEM fabricators. Dominant competitive moves include strategic partnerships bundling needle contracts with imaging service agreements, and portfolio diversification into AI-histopathology convergence plays.
Within the integrated platform tier, BD and Boston Scientific exemplify archetypes that anchor procurement committee negotiations through interventional radiology portfolio breadth. Cook Medical and Merit Medical occupy positions among percutaneous access specialists with deep hepatology application focus. Argon Medical Devices represents the mid-scale disposable instrument segment where distribution reach determines competitive viability.
| Leading Market Players |
|---|
| BD |
| Argon Medical Devices |
| Cook Medical |
| Merit Medical |
| Boston Scientific |
| TSK |
| HAKKO CO., LTD. |
| RI.MOS |
| Veran Medical |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States and Japan concentrate procurement authority for liver biopsy systems, locking in multi-year platform commitments that collapse historical separation between capital equipment and disposable supply purchasing. This buyer consolidation shifts pricing power toward vendors with cleared predicate histories and imaging-needle bundling capabilities.
Pricing Analysis
Capacity additions in South Korean ultrasound transducer manufacturing are reshaping price floors for integrated guidance platforms while stainless steel spot market volatility squeezes margin structures for standalone needle suppliers. Three-tier pricing structure across premium automated systems, standard manual needles, and economy catalog instruments reflects FDA 510(k) certification tier and embedded navigation sensor density. Cost compression in the economy manual tier intensifies because nickel and chromium raw material costs fluctuate with commodity markets. Community hospital procurement committees exhibit highest price sensitivity, while academic medical centers prioritize electromagnetic tracking accuracy over per-unit instrument cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean component houses for ultrasound transducer cores, creating procurement risk for integrated system vendors assembling guidance platforms. Manufacturing concentrates in the United States for automated needle systems, Germany for precision surgical instruments, and China for economy disposable catalog. Raw material dependencies include surgical-grade stainless steel, nickel-titanium alloys for shape-memory biopsy needles, and piezoelectric ceramics for imaging transducers. Tariff exposure on Chinese-sourced instrument components threatens margin structures for mid-scale disposable suppliers. Distribution runs through interventional radiology capital budgets for premium platforms and surgical supply catalogs for economy needles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
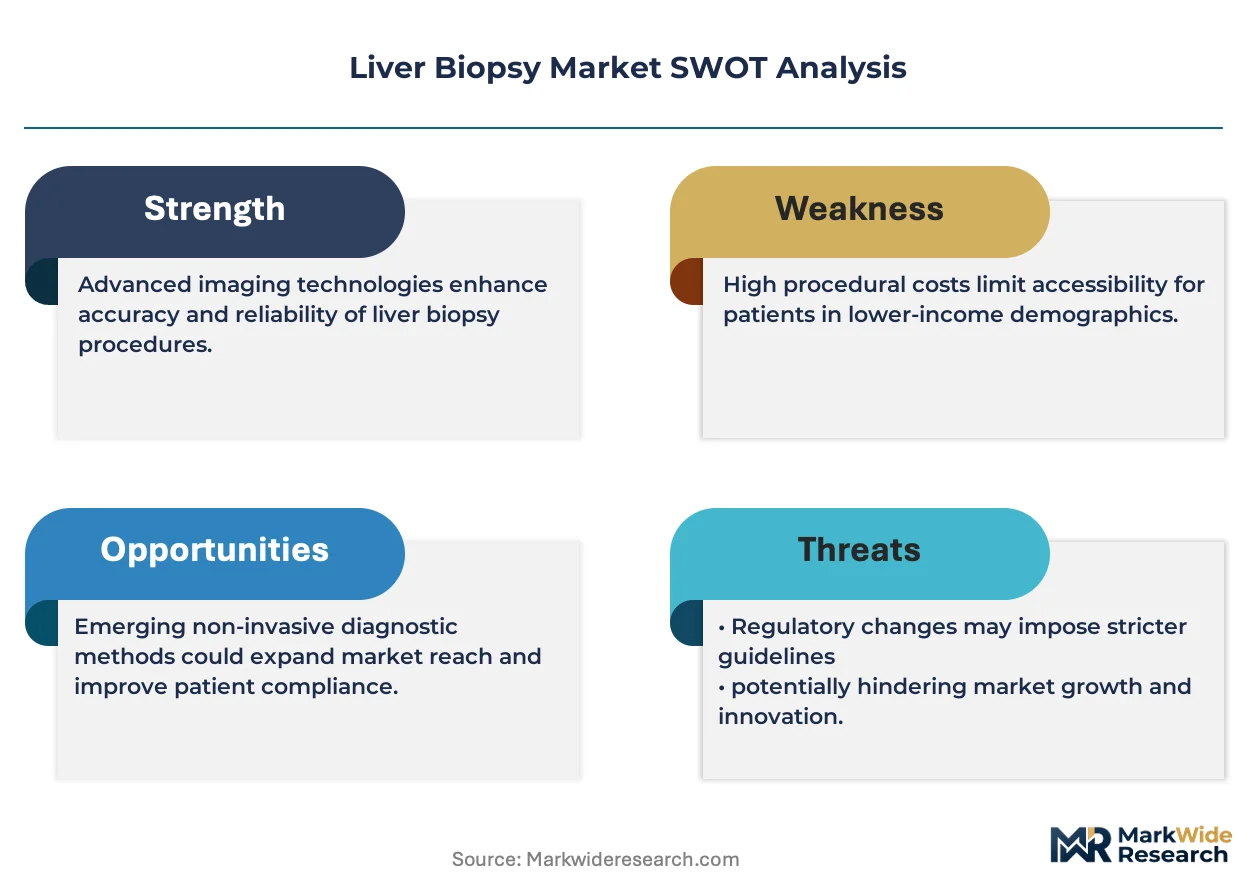
The liver biopsy market reads as a late-cycle quality story where procurement committees prioritize electromagnetic tracking precision and specimen adequacy protocols over per-unit cost minimization. Demand is shifting toward premium integrated platforms that bundle navigation, sampling, and AI-histopathology documentation workflows.
For Market Incumbents: Extend platform service agreements into diagnostic laboratory partnerships, embedding automated fibrosis scoring compatibility as a retention mechanism against emerging entrants with software-native architectures. Deepen backward integration into ultrasound transducer sourcing to mitigate single-supplier vulnerability from South Korean and Japanese component houses. Lock in multi-year commitments with United States integrated delivery networks before Medicare reimbursement adjustments redirect capital toward outpatient clinic point-of-care systems. For New Entrants and Emerging Players: Begin with German outpatient clinic networks where ambulatory surgical centers seek rapid-turnaround biopsy services with same-day pathology reporting, a segment where established platform vendors maintain weaker presence. Target research institute procurement for multi-site clinical trials requiring standardized Tru-Cut specimen quality, leveraging this demand for machine learning pipeline compatibility as entry wedge. Pursue CE marking pathway under EU MDR as faster alternative to FDA 510(k) substantial equivalence timelines for novel needle geometries. For Investors and Strategic Acquirers: Interventional radiology platform consolidators are the most active acquirer in this space, seeking disposable instrument specialists with deep hepatology application focus to complete imaging-needle bundling capabilities. Acquisition target archetype: mid-scale percutaneous access specialists with cleared predicate histories and distribution reach into tertiary hepatology centers. Signal to watch: PMDA reimbursement revisions accelerating ultrasound-integrated system procurement in Japanese hospital networks, indicating platform concentration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Controlled clinical data on core retention rates satisfies tightening substantial equivalence requirements for needle safety claims. |
| CE Marking Pathway | EU MDR technical documentation offers faster certification cycles than FDA predicates for modified instrument geometries. |
| Hospital System Partnership | Multi-year platform commitments with United States integrated delivery networks lock in needle sourcing alongside imaging service agreements. |
| Software Companion Development | Automated fibrosis scoring algorithm compatibility creates demand for standardized tissue acquisition protocols in research institutes. |
| Reimbursement Strategy | Medicare code positioning for image-guided percutaneous procedures directs capital toward high-volume hospital workflows. |
Study Parameters
Multiple input streams — primary interviews with interventional radiologists and hospital procurement managers, secondary validation through FDA 510(k) filings and CMS Medicare reimbursement databases, and trade data on stainless steel instrument imports — were reconciled to construct segment-level demand estimates. Conversations with biomedical engineers at academic medical centers in Boston and Baltimore, GPO contracts managers at United States health systems, and regulatory affairs leads at percutaneous access specialists informed technology adoption assumptions. Bottom-up procedure volume modeling and top-down capital equipment expenditure analysis were cross-referenced for triangulation.
Data-stream reconciliation across product type, delivery mode, end user, and application dimensions anchored the analytical framework over the projection horizon. Segmentation modeling incorporated needle gauge specifications, imaging integration complexity, and site-of-service reimbursement mechanics. CAGRs were derived from fitted growth curves applied to hospital-based procedure volume expansion and outpatient clinic network consolidation patterns. Forecast inputs included PMDA reimbursement revision timelines and EU MDR compliance deadline effects on product refresh rates.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance changes, raw material commodity price shocks beyond historical volatility bands, and disruptive non-invasive fibrosis staging technologies. Forecasts reflect documented assumptions about hepatology screening program expansion trajectories and procurement committee bundling behavior. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market