
 US Molecular Diagnostics Market | 2026-2036
US Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US Molecular Diagnostics Market Insights
Multi-source assay procurement is pivoting toward vertically integrated in-house manufacturing among top-tier diagnostics firms. Abbott leverages captive reagent production to insulate margins from supply volatility. Thermo Fisher Scientific Inc. anchors its position through end-to-end workflow control spanning instruments, consumables, and bioinformatics. Illumina Inc. specializes in sequencing platform ecosystems that lock in downstream analytical demand.
US molecular diagnostics encompasses nucleic acid-based testing methods that detect genetic sequences, mutations, and pathogen-specific biomarkers through amplification, hybridization, or sequencing chemistries, typically operating at sensitivity thresholds of single-copy detection per reaction. These technologies serve clinical decision-making in oncology, infectious disease management, and inherited disorder screening. PCR-based platforms sustain the largest installed base across hospital laboratories, while next-generation sequencing captures the fastest expansion in oncology companion diagnostic applications. Bioinformatics segments command outsized margin pools as data interpretation complexity outpaces hardware commoditization.
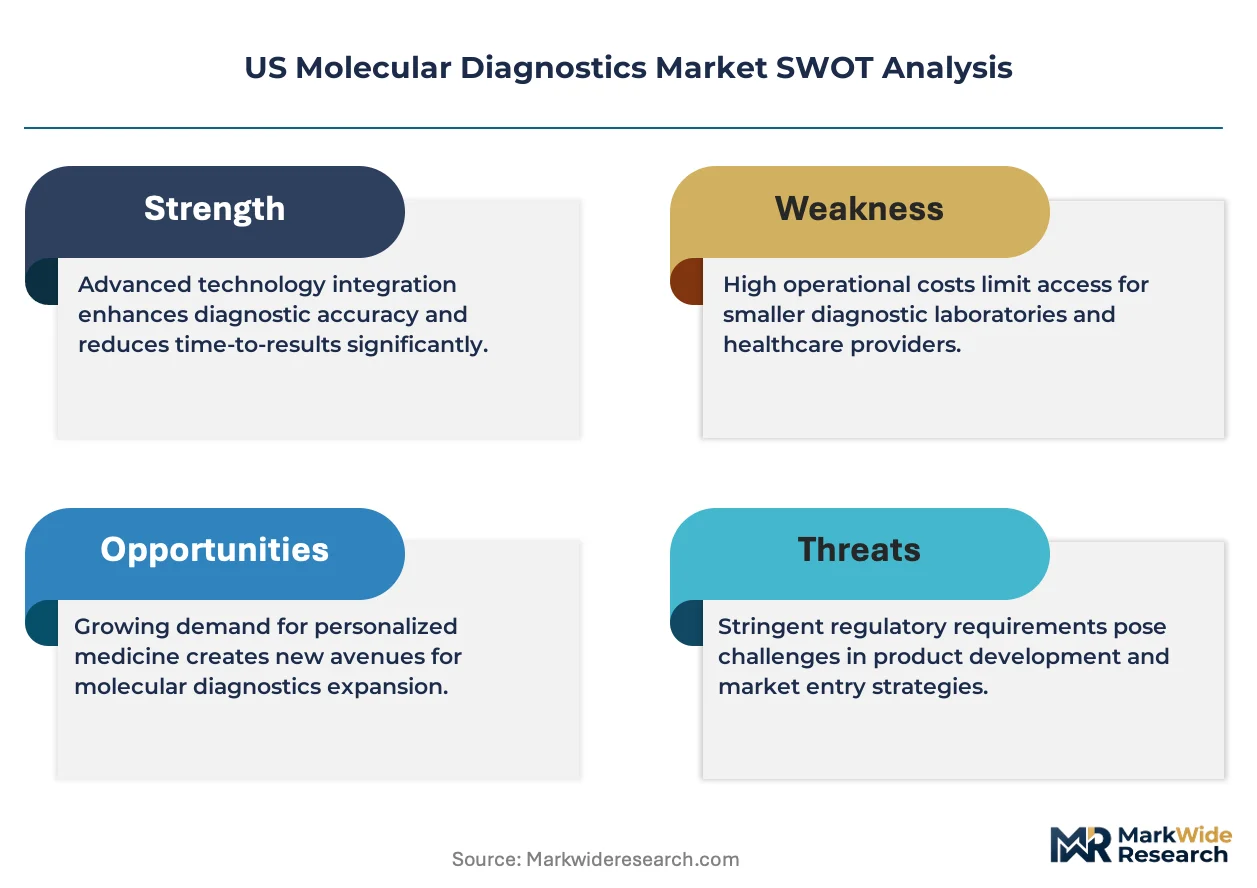
FDA oversight through premarket approval and 510(k) pathways shapes product development timelines and clinical validation requirements for molecular assay manufacturers. The Clinical Laboratory Improvement Amendments framework governs laboratory-developed test standards, while CMS reimbursement determinations directly influence hospital and reference laboratory adoption velocity. Stakeholders must monitor evolving FDA guidance on artificial intelligence-integrated diagnostic algorithms and parallel CMS coverage decisions that will determine commercial viability for automated interpretation platforms.
Market Dynamics
Hospital laboratories are consolidating infectious disease testing capabilities internally, reversing decades of reference laboratory outsourcing as reimbursement pressures and turnaround time requirements intensify. This structural reconfiguration is compressing vendor margins while elevating platform stickiness as a competitive weapon.
Growth Catalysts
- CLIA Laboratory-Developed Test Framework:Moderate complexity classification under CLIA permits hospital systems to validate and deploy molecular assays without full FDA premarket review, accelerating test availability for emerging pathogens.
- Oncology Companion Diagnostic Mandates:FDA labeling requirements for targeted therapies increasingly stipulate mandatory biomarker testing, creating automatic demand pull for PCR and NGS-based oncology panels across academic medical centers.
- California Biotech Corridor Concentration:Venture deployment and talent density in the San Francisco-San Diego corridor sustains disproportionate innovation velocity in CRISPR-based diagnostic platforms and liquid biopsy development.
Market Restraints
- Reagent Supply Concentration:Taq polymerase and modified nucleotide production concentrates among three global chemical suppliers, exposing assay manufacturers to input cost volatility and allocation risk during demand surges.
- CMS Reimbursement Compression:MolDX program coverage determinations and gap fill pricing methodologies constrain realized revenue per test, particularly for novel proprietary assays lacking established CPT codes.
- Technical Limitation in Point-of-Care Sensitivity:Isothermal amplification chemistries at the point-of-care currently fail to achieve single-copy detection thresholds required for early-stage oncology screening applications.
Strategic Opportunities
- Texas Medical Center Expansion:Houston's consolidated health system procurement creates concentrated demand for automated molecular platforms capable of high-throughput respiratory and sepsis panel processing.
- AI-Integrated Algorithm Clearance Pathway:FDA's evolving guidance on software-as-a-medical-device creates regulatory tailwind for automated variant interpretation and reporting tools in hereditary cancer screening workflows.
- Pharmacogenomics Convergence:Integration of CYP450 genotyping with electronic prescribing systems in Veterans Affairs and large integrated delivery networks opens pharmacy-benefit-funded reimbursement channels.
Industry Challenges
- Bioinformatics Pipeline Validation:Clinical laboratories face protracted timelines for analytical validation of variant calling pipelines across NGS platforms, delaying test launch and revenue recognition.
- Interoperability with Legacy LIS:Molecular diagnostic instruments require custom middleware development to interface with aging laboratory information systems prevalent in mid-sized community hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Molecular Diagnostics Market |
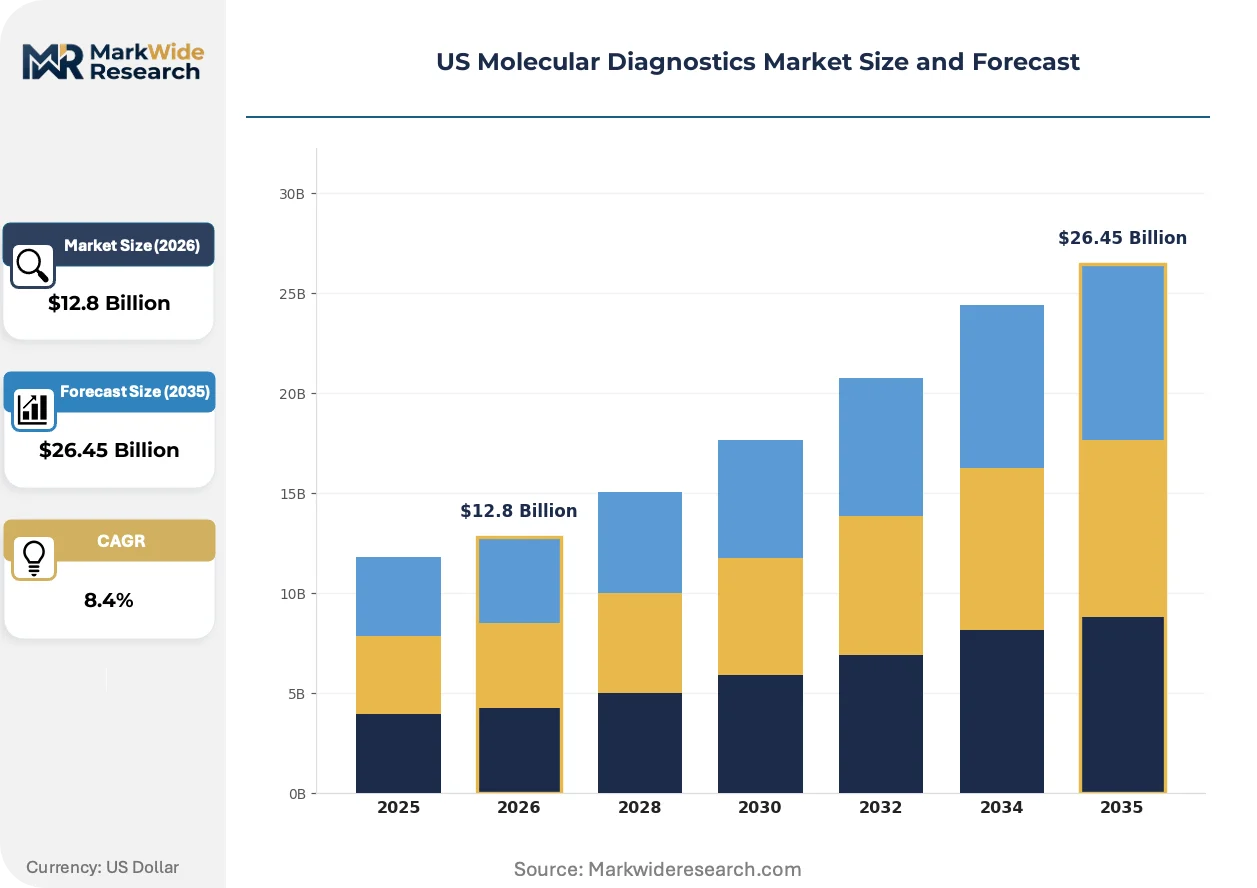
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, NGS, Microarrays, RT-PCR Technology: Sequencing, Amplification, Hybridization, Bioinformatics End User: Hospitals, Laboratories, Research Institutes, Clinics Application: Oncology, Infectious Diseases, Genetic Testing, Blood Screening |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Danaher, Thermo Fisher Scientific Inc., QIAGEN, Hologic Inc., Illumina Inc., Siemens Healthcare GmbH, Quest Diagnostics Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Molecular Diagnostics Market Trends and Innovations
Digital PCR platforms are migrating from research-only to clinical diagnostic applications, while artificial intelligence tools compress variant interpretation timelines. These shifts are reconfiguring capital deployment patterns and technical competency requirements across hospital laboratory networks.
CRISPR-based detection chemistry is integrating programmable nucleic acid recognition with signal amplification, enabling single-reaction multiplexing for respiratory pathogen panels. Large integrated delivery networks in the Northeast are piloting these platforms for syndromic surveillance applications. The technology is integrating diagnostic specificity previously requiring sequential testing into consolidated workflows, reducing per-patient reagent consumption.
FDA's 2023 guidance on breakthrough devices for infectious disease diagnostics compresses premarket review timelines for assays addressing unmet antimicrobial resistance detection needs. Manufacturers are restructuring clinical validation protocols to align with streamlined evidentiary requirements. Hospital laboratories in the Boston-Cambridge research cluster are prioritizing platform procurement from holders of these designations to secure preferential technical support and assay pipeline commitments.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for routine reagent contracts. Academic medical centers are unbundling instrument placement from consumable supply agreements, negotiating separate pricing tiers for high-volume versus low-complexity testing menus. This behavioral shift is most pronounced in the Midwest, where health system mergers have concentrated purchasing authority under centralized supply chain functions with dedicated molecular diagnostics category managers.
US Molecular Diagnostics Market Segmentation
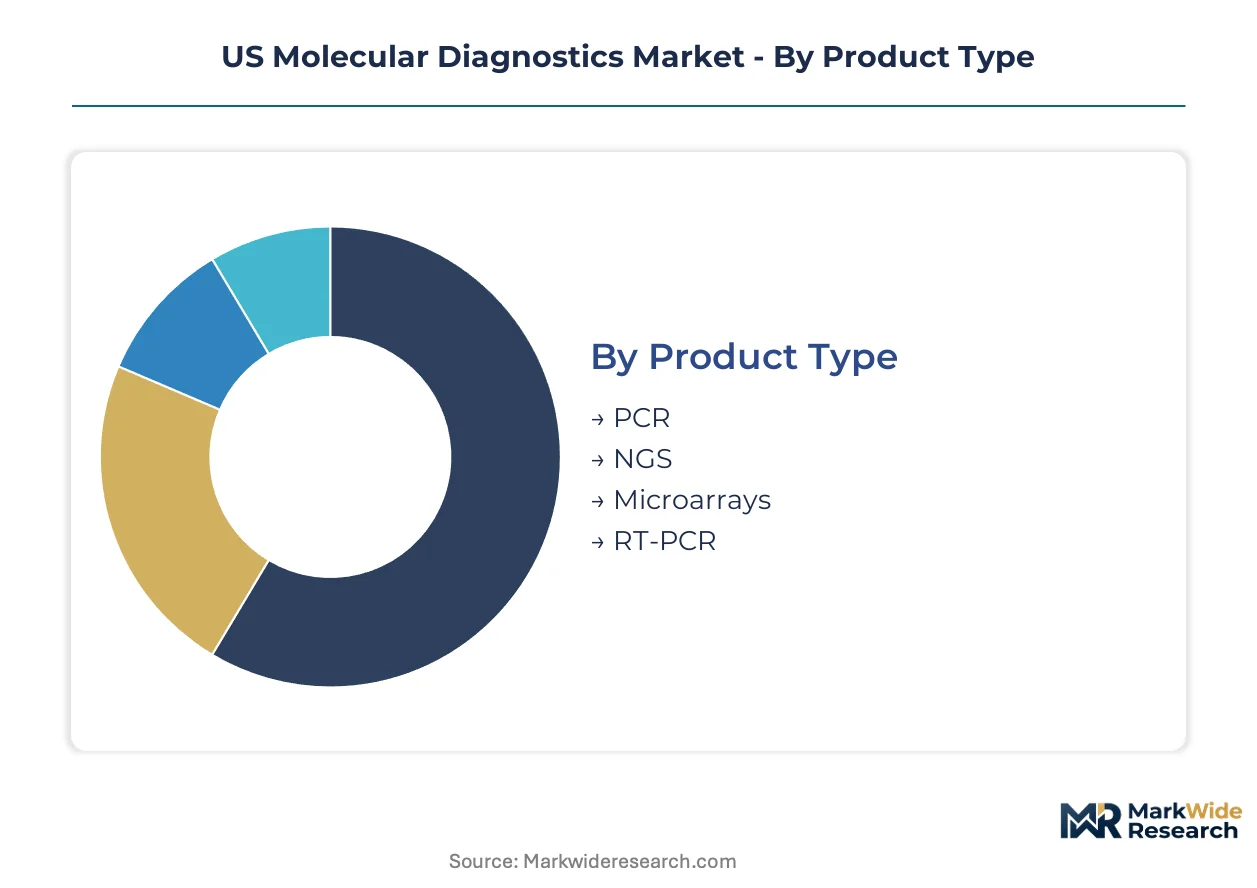
Molecular diagnostics segmentation reveals distinct technology maturation curves and reimbursement pathways that determine capital deployment priorities across hospital systems. Product architecture and analytical chemistry choices lock customers into multi-year consumable commitments, making segment selection a strategic commitment rather than a tactical procurement decision.
Product Type:
Platform selection hinges on sensitivity thresholds, multiplexing capacity, and FDA clearance status for specific diagnostic indications.
- PCR:Real-time amplification platforms sustain the largest installed base across US hospital laboratories, with thermal cycling instrumentation dominating infectious disease and hereditary testing workflows. Demand concentrates in community hospital networks seeking moderate-complexity CLIA certification for respiratory panel deployment.
- NGS:Next-generation sequencing captures the steepest expansion trajectory in oncology companion diagnostic applications, driven by FDA-mandated biomarker testing for targeted therapies. Academic medical centers in the Boston-Cambridge corridor prioritize platform procurement from manufacturers with breakthrough device designations.
- Microarrays:Array-based detection serves pharmacogenomics and copy number variation analysis with established reimbursement through MolDX.
- RT-PCR:Reverse transcription chemistry enables RNA virus detection and gene expression profiling with streamlined workflow integration.
Mature deployment sits with PCR platforms in infectious disease screening. Newer deployment is concentrated in NGS oncology panels.
Technology:
Technical architecture determines margin distribution between hardware manufacturers and analytical service providers.
- Sequencing:Massively parallel readout technologies command premium pricing in hereditary cancer and rare disease diagnostics. California's biotech corridor sustains disproportionate innovation velocity in CRISPR-integrated detection chemistry.
- Amplification:Isothermal and PCR-based amplification sustains the highest test volume throughput across US hospital laboratories. Texas Medical Center procurement creates concentrated demand for high-throughput respiratory and sepsis panel processing.
- Hybridization:Probe-based target capture enables specific mutation detection with reduced bioinformatics overhead.
- Bioinformatics:Variant interpretation pipelines capture outsized margin pools as data complexity outpaces hardware commoditization.
Established revenue concentration aligns with amplification chemistry in routine infectious disease testing. Emerging value capture is shifting toward bioinformatics in hereditary screening.
End User:
Customer type dictates purchasing authority structure and instrument placement strategy.
- Hospitals:In-house laboratory consolidation is reversing decades of reference laboratory outsourcing as reimbursement pressures intensify. CMS coverage determinations directly influence platform adoption velocity in integrated delivery networks.
- Laboratories:Independent reference laboratories face margin compression from hospital system insourcing and CMS gap fill pricing methodologies.
- Research Institutes:Academic medical centers unbundle instrument placement from consumable supply agreements, negotiating separate pricing tiers for high-volume versus low-complexity testing menus.
- Clinics:Point-of-care molecular testing remains limited by technical constraints in achieving single-copy detection thresholds for oncology applications.
Procurement authority concentrates in hospital supply chain functions. Decentralized testing expansion is constrained in clinic settings.
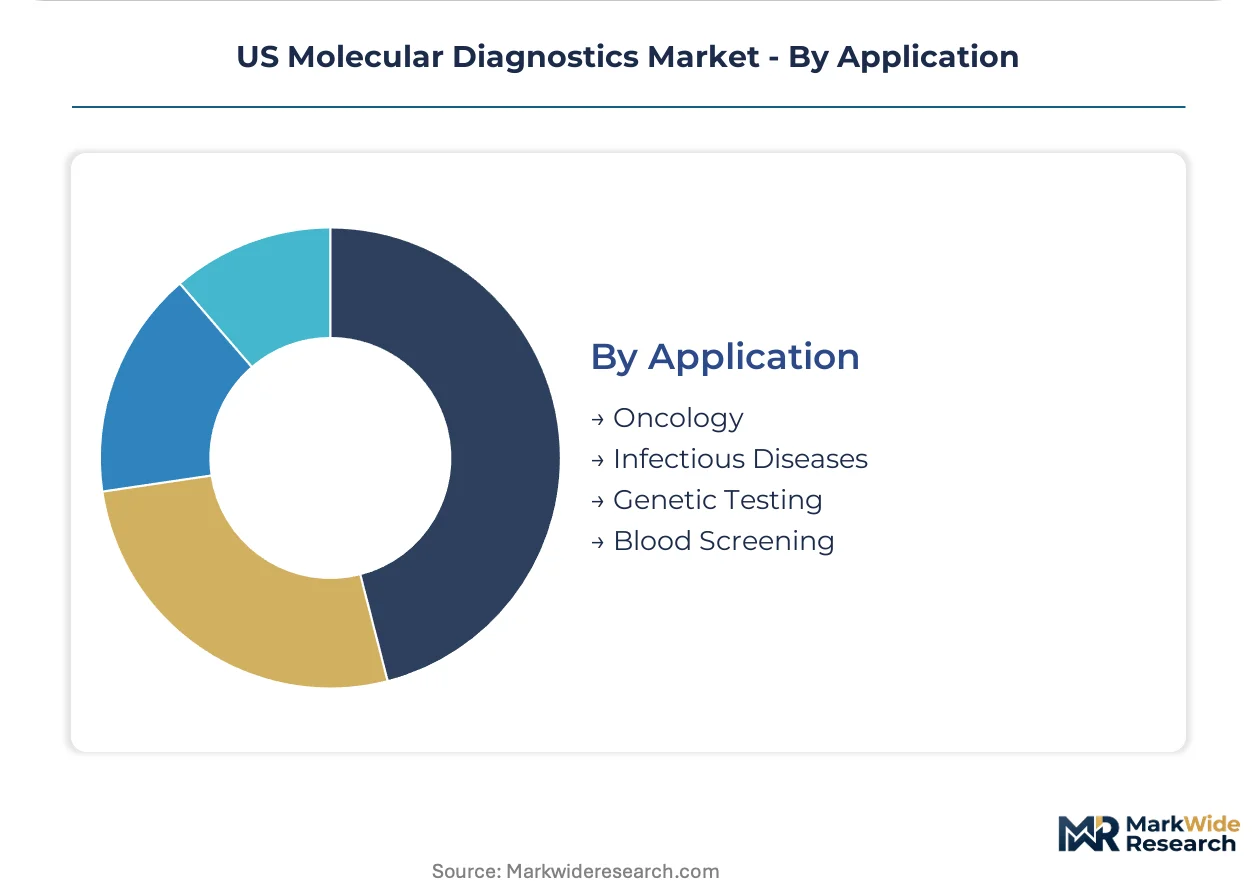
Application:
Disease area selection determines regulatory pathway complexity and reimbursement stability.
- Oncology:Companion diagnostic mandates create automatic demand pull for PCR and NGS-based panels across academic medical centers. FDA labeling requirements for targeted therapies stipulate mandatory biomarker testing.
- Infectious Diseases:Syndromic panel deployment is accelerating in large integrated delivery networks seeking antimicrobial resistance detection capabilities. FDA breakthrough device pathways compress premarket review timelines for unmet resistance detection needs.
- Genetic Testing:Hereditary screening workflows are integrating AI-integrated algorithm clearance pathways for automated variant interpretation.
- Blood Screening:Nucleic acid testing for transfusion-transmitted infections maintains stable demand through blood center consolidation.
Revenue stability characterizes infectious disease testing. Technology transition is most pronounced in oncology biomarker detection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized reagent manufacturing concentrates in Massachusetts and California, anchoring the geographic distribution of molecular diagnostics demand across the United States.
California
San Diego and San Francisco biotech corridors sustain disproportionate innovation velocity in CRISPR-based diagnostic platforms and liquid biopsy development. FDA breakthrough device designations cluster among California-headquartered developers seeking accelerated premarket pathways. Venture deployment in the San Francisco-San Diego corridor funds early-stage detection chemistry ventures targeting oncology companion diagnostics.
Massachusetts
Greater Boston's academic medical centers prioritize platform procurement from manufacturers with FDA breakthrough device status to secure preferential technical support. The state's concentration of NIH-funded research institutes drives demand for research-use-only sequencing platforms transitioning to clinical applications. Cambridge-based bioinformatics developers anchor variant interpretation pipeline commercialization.
Texas
Houston's Texas Medical Center creates concentrated procurement demand for automated molecular platforms processing high-throughput respiratory and sepsis panels. CMS reimbursement determinations for molecular diagnostic procedures directly influence hospital system adoption velocity across the state's integrated delivery networks. Dallas-Fort Worth health system mergers concentrate purchasing authority under centralized supply chain functions.
New York
New York State's clinical laboratory licensing requirements exceed federal CLIA standards, creating regulatory complexity for out-of-state reference laboratories seeking market entry. The New York City metropolitan area's density of academic medical centers sustains demand for NGS-based oncology panels. Buffalo-Rochester hospital networks consolidate infectious disease testing capabilities internally, reversing prior outsourcing patterns.
Illinois
Chicago's consolidated health system procurement patterns favor vendors offering unbundled instrument placement and consumable supply agreements. Midwest health system mergers concentrate molecular diagnostics category management under centralized supply chain functions. Illinois hospital laboratories expand moderate-complexity CLIA certification for respiratory panel deployment.
US Molecular Diagnostics Market Competitive Landscape
Global majors compete with regional champions across platform ecosystems and reagent supply chains, producing a tiered structure where scale-driven conglomerates anchor high-throughput instrument markets while specialized developers capture niche assay segments. Three archetypes dominate: vertically integrated life science conglomerates controlling end-to-end workflows, sequencing platform specialists locking in downstream analytical demand, and reference laboratory operators insourcing test development. Consolidation proceeds through strategic acquisitions of complementary assay portfolios and exclusive distribution partnerships for automated platforms.
Within the integrated conglomerate tier, Abbott, Thermo Fisher Scientific Inc., and Danaher exemplify archetypes of captive reagent production, end-to-end workflow control, and diversified life science instrumentation respectively. These entities occupy positions that insulate margins from supply volatility through backward integration into critical input manufacturing. Illumina Inc. sits within the platform specialist category, anchoring sequencing ecosystem strategies that capture recurring consumable revenue. F. Hoffmann-La Roche Ltd represents the European-headquartered multinational archetype competing across both instrument and reagent domains.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Danaher |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Hologic Inc. |
| Illumina Inc. |
| Siemens Healthcare GmbH |
| Quest Diagnostics Incorporated |
| Others |
Pricing and Supply Chain Analysis
Taq polymerase and modified nucleotide procurement costs cascade through three distinct pricing tiers as assay manufacturers negotiate volume-based consumable contracts with hospital laboratories and reference networks. The concentration of enzymatic reagent production among specialized chemical suppliers in Massachusetts and California creates geographic cost differentials that amplify margin pressure for mid-tier platform vendors lacking backward integration into critical input manufacturing.
Pricing Analysis
Instrument placement bundled with multi-year consumable commitments dominates pricing architecture, though academic medical centers increasingly unbundle these arrangements to negotiate separate service tiers. Price differentiation hinges on FDA clearance status and CLIA complexity certification, with moderate-complexity assays commanding premium positioning against laboratory-developed tests. Cost compression in the reference laboratory tier is intensifying as hospital insourcing accelerates and CMS gap-fill methodologies constrain realized revenue per test. Community hospital networks exhibit highest price sensitivity due to constrained capital budgets, while integrated delivery networks leverage consolidated procurement volume for preferential tier placement.
Supply Chain Analysis
Regional distribution centers in Boston-Cambridge and San Diego function as hub nodes for specialized reagent fulfillment to hospital networks across the Northeast and West Coast. Manufacturing concentration rests on Massachusetts and California for CRISPR guide RNA synthesis and sequencing flowcell production, with critical enzymatic inputs drawing from contract fermentation facilities in North Carolina and Texas. Single-source vulnerability characterizes modified nucleotide supply, where sole qualified suppliers expose assay manufacturers to allocation risk during respiratory panel demand surges. Distribution runs through manufacturer-direct field service organizations for high-throughput platforms, complemented by third-party logistics for routine consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US molecular diagnostics sector sits in a technology-transition phase as next-generation sequencing displaces PCR-based platforms in oncology companion diagnostic applications. This shift reconfigures competitive positioning around bioinformatics capabilities and automated interpretation workflows.
For Market Incumbents: Cement platform stickiness through exclusive assay pipeline commitments with Texas Medical Center and other consolidated health systems facing high-throughput respiratory processing demands. Deepen backward integration into Taq polymerase manufacturing to insulate margins from chemical supplier allocation decisions. Prioritize FDA breakthrough device designation acquisition to secure preferential technical support relationships with Boston-Cambridge academic medical centers.
For New Entrants and Emerging Players: Enter via pharmacogenomics convergence opportunities in Veterans Affairs electronic prescribing integration, where pharmacy-benefit-funded reimbursement channels remain underpenetrated by established vendors. Target AI-integrated variant interpretation tools for hereditary cancer screening workflows, leveraging FDA software-as-a-medical-device guidance to compress regulatory timelines. Pursue hospital laboratory middleware development partnerships to address legacy LIS interoperability pain points in Midwest community hospital networks.
For Investors and Strategic Acquirers: FDA breakthrough device designation announcements for infectious disease resistance detection platforms are the leading indicator that premarket review timeline compression will accelerate platform procurement decisions among academic medical centers. Position acquisition strategy around bioinformatics pipeline developers with validated variant calling algorithms across multiple NGS platforms. Monitor CMS MolDX coverage determinations for novel proprietary assays as the signal for reimbursement stability in emerging test categories.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review timelines for antimicrobial resistance detection assays targeting unmet clinical needs. |
| Hospital System Partnership | Secures preferential instrument placement and consumable supply agreements with Texas Medical Center procurement functions. |
| Software Companion Development | Aligns automated variant interpretation tools with FDA software-as-a-medical-device guidance for hereditary screening. |
| Reimbursement Strategy | Navigates CMS MolDX gap-fill methodologies to establish coverage for novel oncology companion diagnostic panels. |
| CLIA Laboratory Certification | Enables moderate-complexity molecular assay deployment without full FDA premarket review in community hospital networks. |
Research Methodology
Independent corroboration across hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists underwrites the qualitative findings on procurement behavior and platform adoption drivers. Secondary validation draws from FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and CLIA laboratory certification registries. Bottom-up instrument placement estimates triangulate against top-down market sizing derived from manufacturer revenue disclosures and installed base analysis.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon, modeling technology substitution effects between PCR and NGS platforms. Segmentation dimensions include product architecture, analytical chemistry, end-user type, and disease application area, with geographic clustering around biotech corridor concentration. CAGRs derive from instrument replacement cycles, assay menu expansion rates, and reimbursement pathway maturation. Forecast inputs incorporate FDA guidance evolution on AI-integrated diagnostics and parallel CMS coverage decision timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt CMS reimbursement compression or supply chain disruption in enzymatic reagent manufacturing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Global Circulating Tumor Cells Market