
 AI Medical Service Market | 2026-2036
AI Medical Service Market Size, Share, and Industry Trends Forecast 2026-2036
AI Medical Service Market Insights
Modular bundling of diagnostic tools with workflow automation suites is recalibrating how hospital procurement committees evaluate vendor proposals. NVIDIA Corporation leverages its GPU cloud infrastructure to anchor AI training workloads for medical imaging networks. Siemens Healthineers competes through integrated hardware-software pathways that extend from scanner to diagnostic read. Microsoft positions its Azure health data platform to control enterprise AI deployment pipelines across multi-site hospital systems.
AI medical service denotes the provision of algorithm-driven clinical functions including diagnostic pattern recognition, treatment protocol optimization, and predictive patient risk stratification, typically delivered via cloud-hosted or edge-deployed software operating on structured and unstructured health data. These systems process medical imaging at sub-millimeter resolution thresholds, natural language clinical notes through transformer architectures, and real-time telemetry streams from wearable sensors to augment physician decision velocity. Diagnostic tools command the deepest margin pools where FDA 510(k) clearance creates defensible commercial positions, while workflow automation segments expand fastest as labor shortages force operational restructuring. Machine learning applications in clinical decision support occupy mature adoption curves among academic medical centers, whereas computer vision for radiology is accelerating through regulatory harmonization.
The FDA's software-as-a-medical-device framework and the EU AI Act's risk classification for clinical AI jointly determine market access conditions and validation burdens for developers. HIPAA in the United States and GDPR in Europe constrain cross-border training data flows, pushing vendors toward federated learning architectures that keep patient records within jurisdictional boundaries. Stakeholders must monitor how reimbursement codes for AI-assisted diagnosis evolve relative to traditional professional fees, as this alignment will determine whether hospital capital budgets absorb these tools as cost centers or revenue enablers.
Market Dynamics
FDA 510(k) clearance velocity for machine-learning diagnostic algorithms is compressing vendor sales cycles and forcing hospital procurement committees to restructure evaluation frameworks around algorithmic performance benchmarks rather than hardware specifications.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The FDA's streamlined premarket pathway for AI diagnostics accelerates commercialization timelines for radiology algorithms, reducing validation burdens for developers who demonstrate substantial equivalence.
- Cloud GPU Infrastructure Concentration:NVIDIA Corporation's medical imaging training clusters enable federated learning architectures that keep patient data within hospital firewalls while pooling model improvements across multi-site health systems.
- Diagnostic Labor Shortages:Radiologist workforce gaps in the United States and Germany are forcing health systems to adopt computer-aided detection tools as throughput multipliers rather than optional enhancements.
Market Restraints
- Cross-Border Data Friction:HIPAA and GDPR divergence blocks centralized training datasets, fragmenting model development across jurisdictional silos and degrading algorithm generalizability.
- Reimbursement Code Misalignment:Current CPT coding structures in the United States bundle AI-assisted reads into professional fees, preventing separate billing that would justify capital deployment.
- Edge Hardware Cost Concentration:Inference-optimized GPU modules for real-time surgical guidance carry 40-60% premiums over general-purpose accelerators, squeezing margins for ambulatory surgical centers.
Strategic Opportunities
- EU AI Act Risk Classification:The EU's high-risk system designation for clinical AI creates compliance service demand for algorithmic audit and post-market monitoring infrastructure.
- Point-of-Care Ultrasound Integration:Handheld imaging devices with embedded neural networks are penetrating emergency departments and rural clinics previously unserved by radiology subspecialists.
- Transformer-Native Clinical NLP:Large language models fine-tuned on unstructured electronic health records are expanding into automated prior authorization and clinical trial matching workflows.
Industry Challenges
- Ground Truth Annotation Bottleneck:Pathology and dermatology AI development stalls on limited access to consensus-labeled training sets from academic medical centers with restrictive data use agreements.
- Legacy PACS Integration Friction:Picture archiving systems from the 2010s lack API standardization, forcing middleware development that delays AI deployment by 12-18 months in mid-tier hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Medical Service Market |
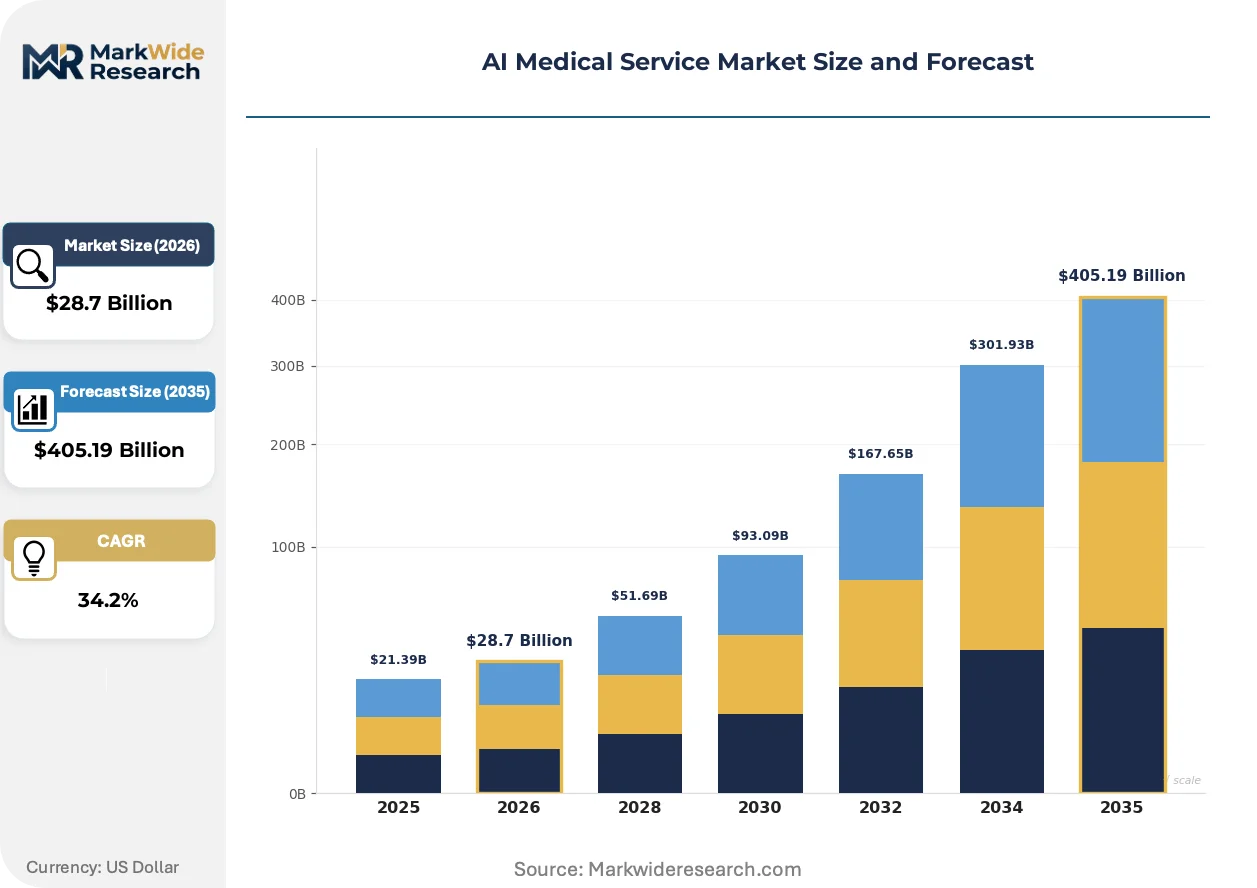
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $405.19 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Treatment Management, Virtual Health Assistants, Predictive Analytics Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Application: Telemedicine, Clinical Decision Support, Remote Monitoring, Workflow Automation End User: Hospitals, Clinics, Outpatient Centers, Research Institutions |
| Companies Covered | Microsoft, NVIDIA Corporation, Siemens Healthineers, Intel Corporation, GE HealthCare, Google DeepMind, Medtronic, Koninklijke Philips, Aidoc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Medical Service Market Trends and Innovations
Foundation models trained on multi-modal health data are displacing narrow task-specific algorithms, compressing development timelines while raising questions about liability allocation and clinical validation scope.
Federated learning architectures are expanding into multi-hospital consortia, enabling model training on distributed datasets without centralizing protected health information. Academic medical centers in Massachusetts, California, and Bavaria are pooling de-identified imaging studies through differential privacy protocols. This approach preserves HIPAA and GDPR compliance while achieving sample sizes that rival single-institution repositories.
The EU AI Act's conformity assessment requirements for high-risk clinical applications are forcing developers to implement post-market performance monitoring systems. Manufacturers must establish quality management systems with algorithm change control protocols. Diagnostic imaging vendors targeting European health systems are restructuring regulatory affairs teams to manage ongoing vigilance obligations rather than one-time CE marking.
Hospital procurement committees are unbundling AI software licenses from radiology equipment service contracts, creating direct vendor relationships that bypass original equipment manufacturer intermediaries. Health systems in Texas and Pennsylvania are piloting subscription-based algorithm access with usage-based pricing tied to study volume. This shift transfers financial risk from capital expenditure to operational budgets while demanding new internal competencies for vendor performance management.
AI Medical Service Market Segmentation
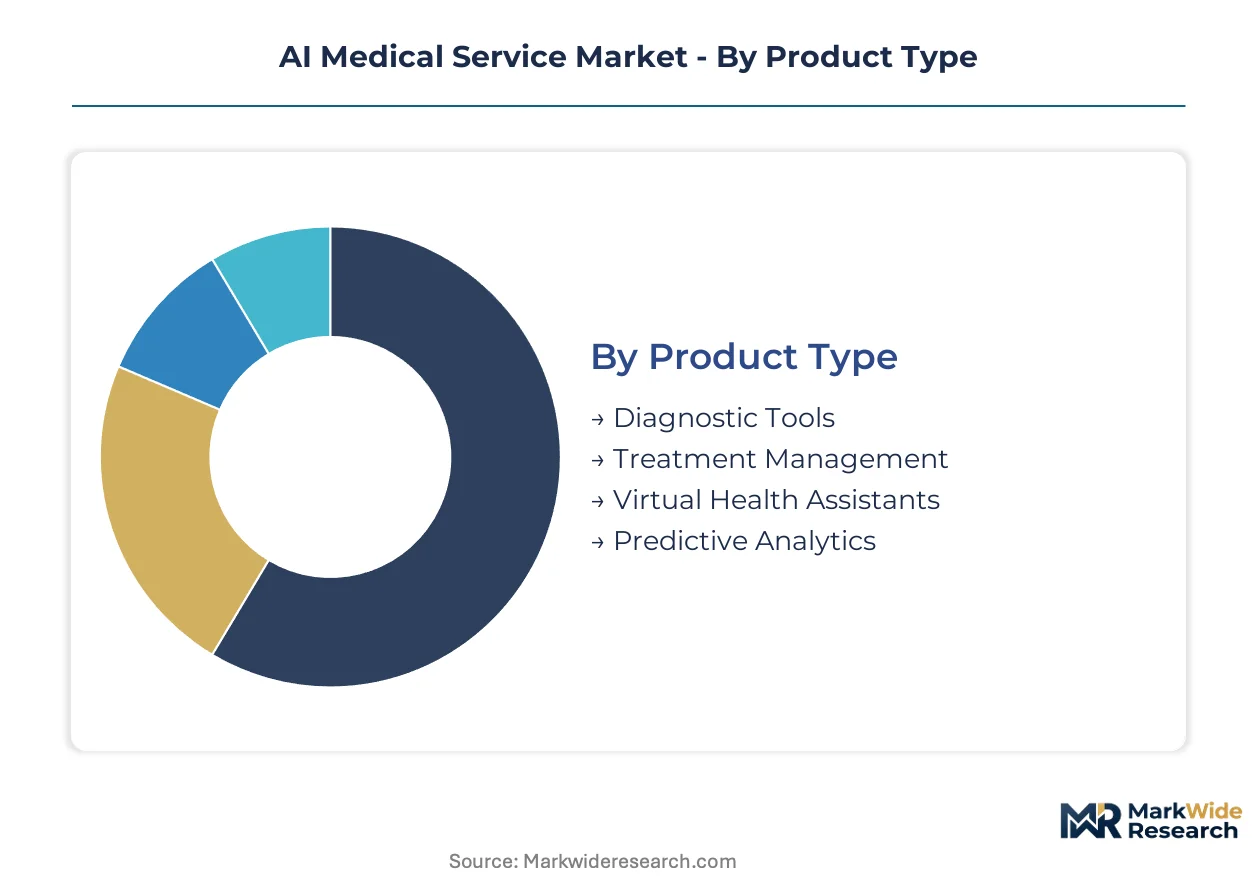
AI medical service procurement varies sharply by institutional capability and regulatory exposure. Hospital capital committees weight FDA clearance status against integration complexity, while outpatient operators prioritize subscription elasticity over upfront deployment.
Product Type:
Hospital procurement committees differentiate AI tools by margin contribution and liability exposure rather than technical sophistication alone.
- Diagnostic Tools:Computer vision algorithms for radiology and pathology interpretation operate at sub-millimeter resolution thresholds. United States academic medical centers concentrate demand here as FDA 510(k) clearances create defensible vendor positions and reimbursement pathways stabilize.
- Treatment Management:Protocol optimization engines adjust chemotherapy dosing and surgical planning based on real-time patient biomarkers. German university hospitals drive adoption where diagnostic labor shortages force operational restructuring.
- Virtual Health Assistants:Conversational agents triage patient inquiries and automate appointment scheduling through transformer architectures.
- Predictive Analytics:Risk stratification models forecast readmission probability and sepsis onset from electronic health record streams.
Volume sits with Diagnostic Tools; growth tilts toward Predictive Analytics.
Technology:
Technology selection tracks data modality and computational infrastructure rather than algorithmic novelty.
- Machine Learning:Supervised and unsupervised methods dominate clinical decision support with established validation frameworks. Cloud GPU clusters from NVIDIA Corporation anchor training workloads across Massachusetts and California health systems.
- Computer Vision:Convolutional and vision transformer architectures process medical imaging at diagnostic resolution. FDA clearance velocity for radiology algorithms compresses sales cycles in the United States.
- Natural Language Processing:Clinical note extraction and prior authorization automation leverage large language models fine-tuned on unstructured records.
- Robotics:Surgical guidance systems integrate real-time inference for instrument positioning and tissue classification.
Machine Learning captures current deployment volume; Computer Vision climbs the fastest as regulatory harmonization accelerates.
Application:
Application prioritization reflects workforce constraints and reimbursement code alignment.
- Clinical Decision Support:Alert systems for drug interactions and diagnostic suggestions occupy mature adoption curves at academic medical centers. HIPAA compliance requirements shape architecture choices for patient data handling.
- Workflow Automation:Scheduling, billing, and documentation acceleration expand fastest as labor shortages force operational restructuring across Texas and Pennsylvania health systems.
- Telemedicine:Remote consultation platforms with embedded diagnostic aids penetrate rural clinics previously unserved by subspecialists.
- Remote Monitoring:Wearable telemetry streams enable continuous patient surveillance outside acute care settings.
Clinical Decision Support holds established volume; Workflow Automation gains share fastest.
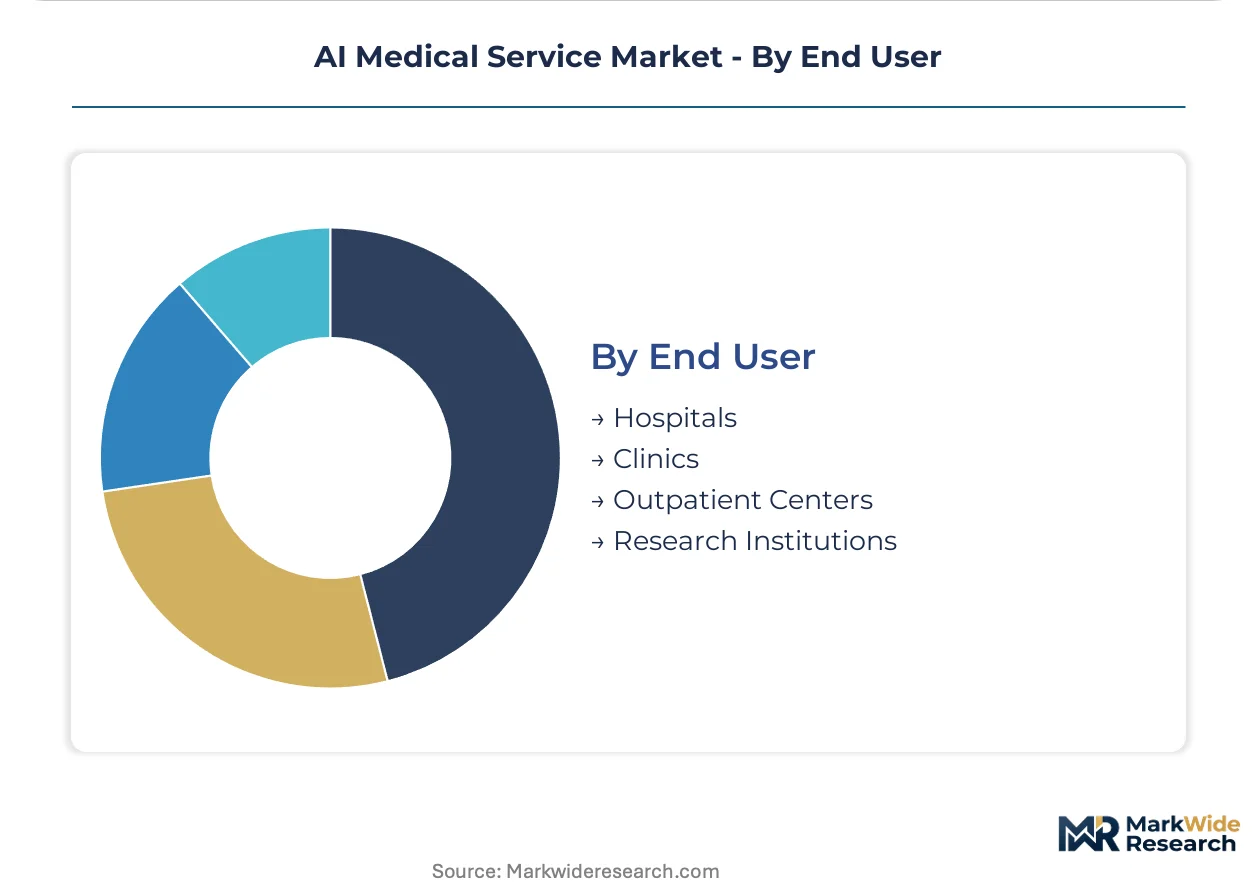
End User:
End user category determines contract structure and implementation timeline.
- Hospitals:Multi-site health systems negotiate enterprise licenses with usage-based pricing tied to study volume. Procurement committees unbundle AI software from radiology equipment service contracts.
- Clinics:Ambulatory operators favor subscription models that transfer financial risk from capital expenditure to operational budgets.
- Outpatient Centers:Surgical and imaging facilities prioritize edge deployment for real-time guidance without cloud latency.
- Research Institutions:Academic medical centers in Bavaria and California pool de-identified datasets through federated learning architectures.
Hospitals dominate procurement volume; Research Institutions show steepest expansion trajectory as consortia scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of AI medical service infrastructure concentrates in cloud computing clusters and semiconductor fabrication centers, while consumption spreads across hospital systems seeking diagnostic labor multipliers. The United States hosts dominant training infrastructure, Germany anchors European regulatory validation, and East Asian markets scale deployment through concentrated health system networks.
United States
FDA 510(k) clearance velocity for radiology algorithms accelerates hospital procurement cycles in Massachusetts and California health systems. HIPAA compliance requirements push vendors toward federated learning architectures that keep patient records within jurisdictional firewalls. NVIDIA Corporation's GPU cloud clusters in Santa Clara and Austin anchor training workloads for multi-site medical imaging networks.
Germany
Radiologist workforce gaps in Bavarian university hospitals drive adoption of computer-aided detection tools as throughput multipliers. The EU AI Act's high-risk system designation for clinical AI forces developers to implement post-market performance monitoring systems. Siemens Healthineers leverages integrated hardware-software pathways from Erlangen to extend scanner-to-diagnostic-read workflows across German health networks.
China
NMPA regulatory harmonization with international standards accelerates clearance timelines for domestic AI diagnostic developers. National hospital digitization programs concentrate procurement authority at provincial health commissions. Beijing and Shanghai medical centers pool de-identified imaging studies through differential privacy protocols to achieve training sample sizes rivaling single-institution repositories.
United Kingdom
NHS England's AI Award program provides funding and regulatory support for diagnostic algorithm deployment across integrated care systems. MHRA convergence with FDA validation standards reduces duplicate clinical trials for US-cleared products. London academic medical centers in the Golden Triangle cluster lead European adoption of transformer-native clinical NLP for automated prior authorization workflows.
Japan
PMDA's Sakigake designation fast-tracks breakthrough AI diagnostics for aging-population disease screening priorities. METI subsidies for smart hospital infrastructure concentrate demand in Kanto and Kansai metropolitan medical zones. Osaka-based health systems pilot edge-deployed surgical guidance systems with inference-optimized GPU modules for real-time instrument positioning.
AI Medical Service Market Competitive Landscape
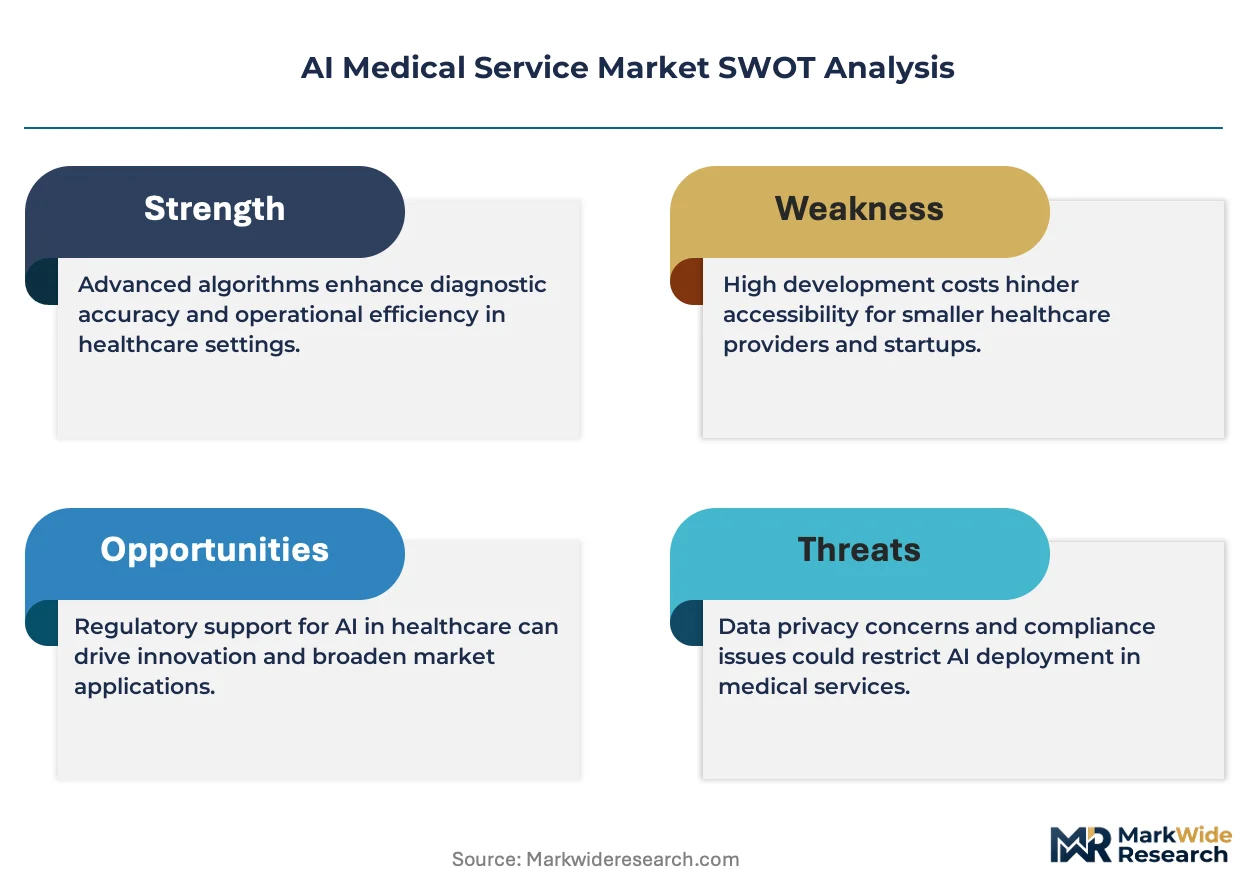
Diversified conglomerates compete with focused pure-play specialists across hardware, cloud infrastructure, and algorithm development domains. Cloud hyperscalers leverage existing enterprise relationships to control AI deployment pipelines, while medical device incumbents defend through integrated scanner-software bundles. Three archetypes dominate: infrastructure providers anchoring training workloads, diagnostic hardware-software integrators, and algorithm-native vendors seeking direct hospital contracts. Competitive intensity centers on M&A activity absorbing point-solution developers and strategic partnerships securing exclusive data access for model training.
Within the infrastructure-provider tier, NVIDIA Corporation and Microsoft exemplify divergent approaches to health system engagement. NVIDIA leverages GPU cloud concentration to anchor federated learning architectures across multi-site networks, while Microsoft positions Azure health data platforms to control enterprise deployment pipelines. Siemens Healthineers occupies the integrated-systems archetype, extending from imaging hardware through diagnostic software pathways. These three entities represent the dominant competitive vectors reshaping vendor-hospital contracting relationships.
| Leading Market Players |
|---|
| Microsoft |
| NVIDIA Corporation |
| Siemens Healthineers |
| Intel Corporation |
| GE HealthCare |
| Google DeepMind |
| Medtronic |
| Koninklijke Philips |
| Aidoc |
| Others |
Pricing and Supply Chain Analysis
EU AI Act high-risk system designation gates qualified supply access for clinical AI vendors seeking premium-tier hospital contracts across European health systems. Compliance service investments in algorithmic audit infrastructure separate defensible pricing positions from commodity software margins, while HIPAA-constrained data architectures in the United States fragment training infrastructure costs across federated learning deployments.
Pricing Analysis
Margin tightening in diagnostic AI tools reflects FDA 510(k) clearance velocity compressing vendor sales cycles and forcing subscription-based pricing models over perpetual licenses. Three-tier pricing structure across FDA-cleared premium, CE-marked standard, and uncertified economy levels differentiates algorithm performance guarantees and liability coverage. Cost-down pressure on workflow automation segments accelerates because labor shortages force operational restructuring into operational budgets. Mid-tier hospitals exhibit highest price sensitivity due to capital expenditure constraints, while academic medical centers prioritize clearance status over unit economics.
Supply Chain Analysis
Specialized GPU module engineering talent scarcity in Taiwan, South Korea, and the United States constrains inference-optimized hardware availability for real-time surgical guidance systems. NVIDIA Corporation's Santa Clara and Austin cloud clusters anchor training workloads, while edge deployment draws from TSMC-fabricated semiconductor supply. Single-source vulnerability concentrates in advanced packaging nodes for medical-grade accelerators. Distribution runs through radiology equipment OEM service contracts unbundling into direct hospital vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI medical service competitive dynamics favor consolidation plays as reimbursement code misalignment forces capital-constrained point-solution developers toward strategic exits. Hospital procurement committee restructuring around algorithmic performance benchmarks eliminates hardware-agnostic vendors lacking FDA clearance velocity.
For Market Incumbents: Extend integrated hardware-software pathways from scanner to diagnostic read to defend against cloud hyperscaler disintermediation. Siemens Healthineers leverages Erlangen-based manufacturing integration as a defensive moat. Anchor federated learning infrastructure investments to lock multi-site health systems into training workload dependencies. Certification maintenance in EU AI Act high-risk categories preserves European market access against algorithm-native challengers. For New Entrants and Emerging Players: FDA software-as-a-medical-device framework in the United States opens a window for narrow-task algorithms in point-of-care ultrasound integration previously unserved by radiology subspecialists. Target handheld imaging device embedded neural networks in emergency departments and rural clinics. Pursue usage-based subscription pricing tied to study volume to bypass capital expenditure approval barriers. Transformer-native clinical NLP for automated prior authorization workflows offers lowest competitive density. For Investors and Strategic Acquirers: Hospital procurement committee unbundling of AI software licenses from radiology equipment service contracts is the leading indicator that direct vendor relationship models are achieving pricing power. Five-to-ten year viability centers on algorithm-native vendors with FDA 510(k) clearance velocity and federated learning deployment experience. Acquisition target archetype: point-solution developers with 510(k) submissions pending and academic medical center training data partnerships. Watch for CPT coding structure alignment with professional fees as reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Clearance velocity compresses sales cycles for radiology algorithm vendors in Massachusetts health systems. |
| EU AI Act Compliance Infrastructure | Post-market monitoring systems defend European market access against regulatory exclusion. |
| Hospital System Partnership | Enterprise licenses with usage-based pricing transfer financial risk from capital to operational budgets. |
| Federated Learning Architecture Deployment | Multi-site consortia preserve HIPAA compliance while achieving training scale rivaling single-institution repositories. |
| Reimbursement Strategy Alignment | CPT code unbundling from professional fees determines whether AI tools deploy as cost centers or revenue enablers. |
Research Methodology
Independent corroboration across hospital procurement committees, FDA regulatory affairs leads, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, CMS Medicare reimbursement data, hospital procurement databases, and hyperscaler capex disclosures. Bottom-up algorithm deployment tracking triangulates against top-down health system IT spending analysis.
Comparable-period anchoring to historical FDA clearance timelines and cloud infrastructure investment cycles establishes forecast baseline integrity across the analysis window. Segmentation dimensions model deployment model, health system size, diagnostic modality, regulatory clearance tier, and regional reimbursement pathway. CAGRs derive from algorithm adoption curve velocity and radiologist workforce gap projections. Forecast inputs include FDA software-as-a-medical-device framework evolution and EU AI Act implementation timelines.
Caveats apply where reimbursement code restructuring or cross-border data friction could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization and hospital capital budget elasticity. Material deviation in FDA clearance velocity or CPT coding alignment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Global Medical Terminology Software Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Medical Alert Systems Market