
 Medical Marker Bands Market | 2026-2036
Medical Marker Bands Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Marker Bands Market Outlook
The capability gap between vertically integrated material suppliers and assembly-only device firms is collapsing as platinum-iridium alloy sourcing becomes a decisive cost lever. Medtronic Plc. leverages captive metallurgy partnerships to secure radiopaque feedstock continuity across its catheter portfolio. Cook Medical anchors its competitive stance through deep specialization in custom band geometries for neurovascular access devices. Stanford Advanced Materials competes on rare earth and precious metal purification capabilities that underpin marker band radiopacity consistency.
Medical marker bands are thin radiopaque rings, typically composed of platinum, gold, or tantalum alloys, that are swaged, crimped, or adhesively bonded onto catheter shafts to enable fluoroscopic visualization during minimally invasive procedures. Band wall thickness commonly ranges from 0.025 mm to 0.127 mm depending on the imaging modality and vessel diameter requirements, with surface finish specifications critical to preventing thrombogenicity or endothelial damage upon deployment. Silicone bands occupy the mature volume tier in cardiovascular applications where flexibility and biocompatibility dominate procurement criteria, while platinum-iridium configurations command premium positioning in neurovascular and electrophysiology segments where radiopacity density per unit mass determines clinical utility. Direct sales channels sustain the highest margin pools through long-term supply agreements with original equipment manufacturers, whereas distributor networks handle fragmented demand from smaller device startups and regional contract manufacturers.
FDA 510(k) premarket notification requirements govern permanent implantable marker bands in the United States, with biocompatibility testing under ISO 10993 standards serving as a parallel gating factor for market access across all major geographies. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for Class III devices incorporating marker bands, pushing manufacturers toward notified body partnerships in Germany, the Netherlands, and Ireland. Stakeholders must monitor evolving EPA precious metal reporting obligations and REACH candidate list expansions for tantalum compounds, as these frameworks increasingly dictate alloy formulation choices and supplier qualification timelines.
Market Dynamics
Platinum-iridium feedstock scarcity is compressing margins across catheter supply chains as refiners prioritize aerospace and automotive offtake agreements over medical alloy contracts.
Growth Catalysts
- Electrophysiology catheter expansion:Ablation procedure volumes in the United States are pulling radiopaque marker band consumption toward higher-density platinum configurations.
- EU MDR Class III pathways:Stricter clinical evidence requirements for permanent implants are consolidating procurement toward qualified German and Irish notified body partnerships.
- Tantalum nitride sputtering:Thin-film deposition techniques are enabling sub-50-micron marker layers that reduce vessel trauma in neurovascular access devices.
Market Restraints
- Precious metal volatility:Platinum group metal price swings from South African mining disruptions destabilize annual contract pricing for catheter OEMs.
- Notified body bottlenecks:EU MDR transition delays at TÜV SÜD and BSI are extending certification timelines for new marker band geometries.
- Polymer radiopacity substitutes:Bismuth-loaded Pebax catheter shafts are displacing metal bands in diagnostic coronary procedures where fluoroscopy requirements are moderate.
Strategic Opportunities
- Japan neurovascular segment:PMDA fast-track designations for stroke intervention devices are opening premium positioning for ultra-thin iridium marker configurations.
- Direct-to-hospital consignment:Catheter manufacturers are bypassing distributors to capture margin pools through sterile field inventory programs at high-volume stroke centers.
- ISO 13485:2016 recertification wave:Quality management system upgrades are creating vendor consolidation windows for metallurgy specialists with existing MDSAP scope.
Industry Challenges
- Micro-welding technician scarcity:Precision laser joining of 0.025 mm wall bands requires specialized skills concentrated in southern German and Swiss manufacturing clusters.
- Biocompatibility test queue compression:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization studies face 14-18 week backlogs at accredited laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Marker Bands Market |
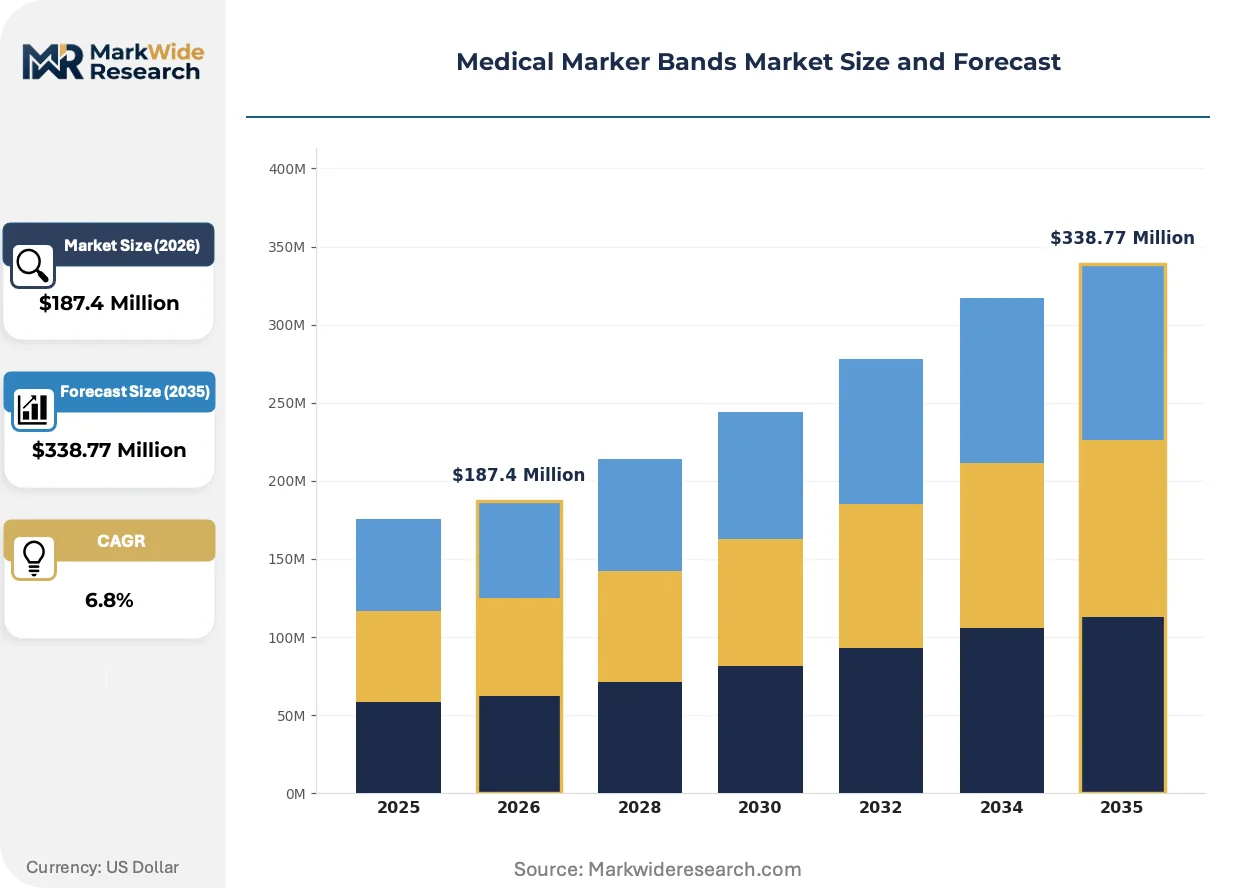
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Bands, PVC Bands, Nylon Bands, Rubber Bands Application: Healthcare Facilities, Laboratories, Diagnostic Centers, Research Institutions End User: Hospitals, Clinics, Diagnostic Labs, Rehabilitation Centers Distribution Channel: Online Retail, Direct Sales, Distributors, Medical Supply Stores |
| Companies Covered | Stryker Corporation, Cook Medical, Medtronic Plc., Stanford Advanced Materials, Biomerics, Boston Scientific Corporation, Teleflex Incorporated, Resonetics, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Marker Bands Market Strategic Shifts
Marker band fabrication is bifurcating between legacy swaged metal rings and additive-deposited thin films, with process selection increasingly dictated by catheter shaft material compatibility rather than radiopacity density alone.
Laser-cut hypotube marker integration is fragmenting the traditional crimped-band attachment paradigm. Neurovascular catheter engineers at specialized device firms are adopting this approach to eliminate mechanical stress risers at band-shaft interfaces. The shift is compressing demand for conventional platinum-iridium ring geometries in the smallest French sizes.
REACH candidate list expansion for tantalum compounds is forcing alloy reformulation across European supply chains. ECHA's 2023-2024 substance evaluations are compelling catheter manufacturers to document supply chain due diligence for conflict-mined tantalum feedstock. German OEMs are responding by qualifying Australian and Canadian tantalum sources ahead of potential authorization restrictions.
Hospital procurement teams are consolidating catheter suppliers around vendors offering sterile field consignment with usage-based invoicing. This model displaces traditional purchase-order cycles at high-volume interventional cardiology departments in the United States. The shift concentrates purchasing power among integrated delivery networks with direct vendor-managed inventory agreements.
Medical Marker Bands Market Segmentation
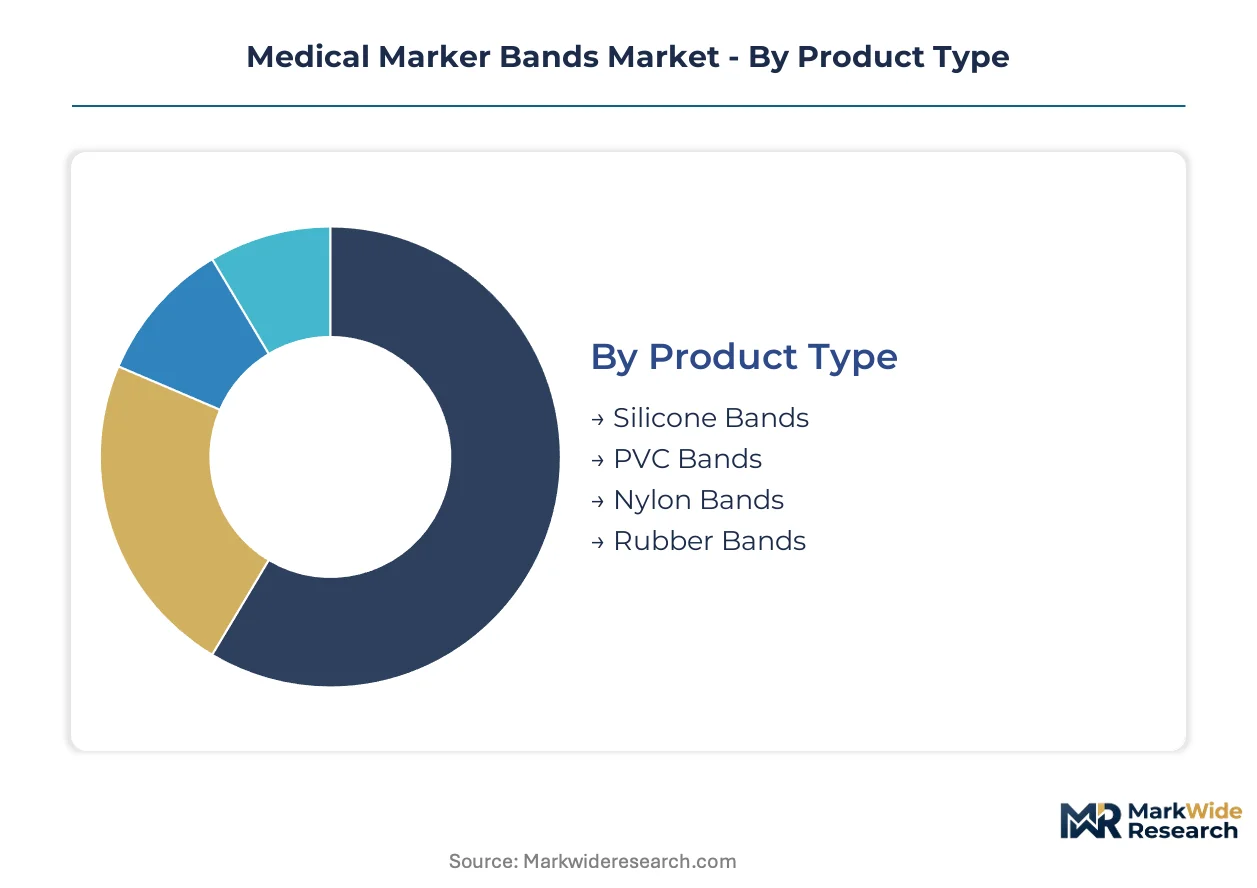
Segmentation in medical marker bands reveals how material substitution pressures and procurement channel shifts reshape competitive boundaries across catheter supply chains. Understanding these divides exposes where platinum-iridium configurations defend premium positioning against polymer-based displacement.
Product Type:
Silicone and PVC configurations face the strongest substitution threat from bismuth-loaded polymer shafts that eliminate separate band components entirely.
- Silicone Bands:Platinum-cured elastomer formulations deliver flexibility for cardiovascular catheters requiring repeated flexion without radiopacity degradation. Demand concentrates in United States electrophysiology labs where biocompatibility certification under FDA 510(k) pathways favors established silicone suppliers.
- PVC Bands:Plasticized vinyl compounds with barium sulfate loading provide economy-tier radiopacity for diagnostic coronary procedures. German catheter OEMs are phasing PVC out of neurovascular lines ahead of anticipated ECHA substance evaluations.
- Nylon Bands:Radiopaque polyamide grades suit high-torque delivery systems in peripheral vascular applications.
- Rubber Bands:Natural and synthetic latex variants persist in emerging market price-sensitive procurement.
Silicone bands anchor the volume base while platinum-iridium thin films gain share at the steepest rate in neurovascular segments.
Application:
End-use concentration tracks catheter procedure volumes, with stroke intervention and cardiac ablation pulling divergent material specifications.
- Healthcare Facilities:Hospital-based interventional suites drive bulk procurement of standardized band geometries for inventory efficiency. United States integrated delivery networks negotiate multi-year supply agreements with usage-based invoicing terms.
- Laboratories:Preclinical testing facilities require traceable radiopacity calibration standards for imaging system validation.
- Diagnostic Centers:Outpatient cardiac catheterization labs prioritize rapid-turnaround consignment models over capital-intensive inventory.
- Research Institutions:Academic medical centers developing next-generation catheter platforms source custom band geometries in limited volumes.
Healthcare facilities dominate procurement tonnage while research institutions command the highest per-unit customization premiums.
End User:
Customer scale determines whether direct manufacturer relationships or distributor intermediaries capture margin pools.
- Hospitals:Tertiary stroke centers and academic medical centers in Germany and the United States qualify suppliers through sterile field consignment programs. FDA-cleared devices with MDSAP scope receive preference in vendor consolidation waves.
- Clinics:Ambulatory surgical centers purchase through regional distributors with limited technical specification involvement.
- Diagnostic Labs:Independent imaging facilities source replacement bands for refurbished catheter systems.
- Rehabilitation Centers:Post-acute settings represent minimal addressable demand for invasive procedure accessories.
Hospitals concentrate purchasing power while clinics expand most quickly as ambulatory migration accelerates.
Distribution Channel:
Channel selection reflects customer technical sophistication and inventory carrying cost tolerance.
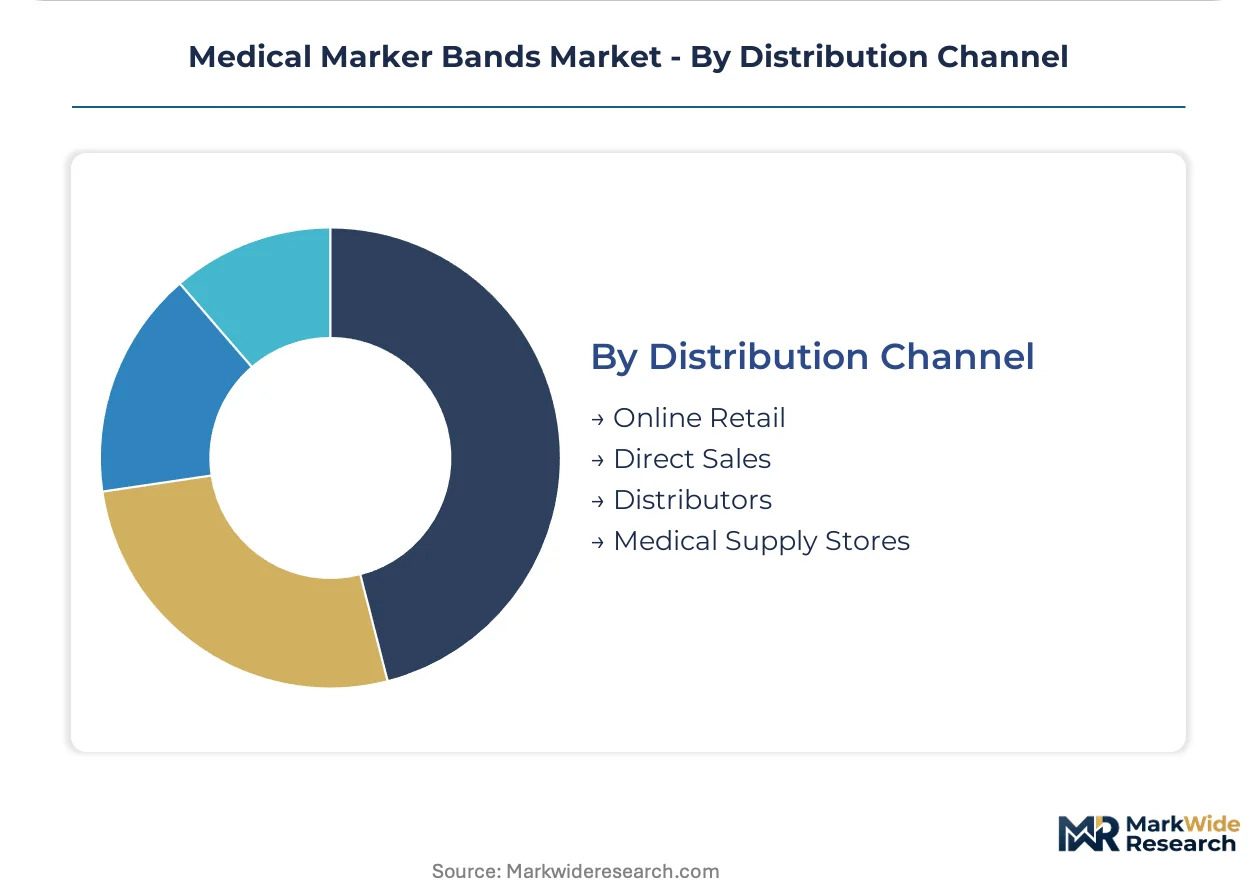
- Direct Sales:Long-term supply agreements with Medtronic, Cook Medical, and specialized neurovascular OEMs sustain the highest margin pools through technical collaboration on custom geometries.
- Online Retail:E-procurement platforms serve smaller device startups and regional contract manufacturers with standardized catalog offerings.
- Distributors:Medical device distributors handle fragmented demand across Asia-Pacific and Latin American markets where direct sales infrastructure remains uneconomical.
- Medical Supply Stores:Brick-and-mortar channels persist for emergency replacement procurement in secondary markets.
Direct sales channels capture premium positioning while online retail expands accessibility for emerging market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German catheter OEMs while United States manufacturers absorb platinum-iridium volatility through long-term metallurgy contracts. This asymmetry reflects divergent regulatory pathways and supply chain configurations across major producing regions.
United States
Electrophysiology procedure volumes at Cleveland Clinic and Mayo Clinic stroke centers drive consumption of high-density platinum marker configurations. FDA 510(k) clearance pathways favor established suppliers with MDSAP scope, compressing vendor qualification timelines for new entrants. Minnesota and Massachusetts clusters host captive metallurgy partnerships that secure radiopaque feedstock continuity.
Germany
Notified body concentration at TÜV SÜD and BSI in Munich consolidates EU MDR Class III certification leverage for catheter manufacturers. REACH candidate list evaluations for tantalum compounds force alloy reformulation toward Australian and Canadian feedstock sources. Freiburg and southern German manufacturing clusters concentrate micro-welding technician expertise for 0.025 mm wall precision.
Japan
PMDA fast-track designations for stroke intervention devices at Tokyo and Osaka academic medical centers accelerate premium adoption of ultra-thin iridium markers. METI industrial policy supports domestic precious metal refining capacity for medical alloy contracts. Nagoya-area catheter engineers pioneer laser-cut hypotube integration to eliminate mechanical stress risers.
China
NMPA priority review pathways for neurovascular devices expand addressable demand for radiopaque marker bands in Shanghai and Beijing hospital systems. Domestic platinum group metal refining investments reduce import dependency for catheter OEMs. Yangtze River Delta manufacturing bases scale silicone band production for cardiovascular volume tiers.
Switzerland
Swissmedic certification reciprocity with EU notified bodies positions Basel and Zurich clusters as regulatory arbitrage points for Class III device manufacturers. Precision metallurgy heritage supports thin-film deposition capabilities for sub-50-micron marker layers. Geneva-area research institutions source custom band geometries for next-generation catheter platform development.
Medical Marker Bands Market Competitive Environment
Concentration sits with diversified medical device conglomerates that leverage captive precious metal supply agreements across catheter portfolios. Three to four vertically integrated OEMs command premium positioning through metallurgy partnerships, while specialized component suppliers compete on rare earth purification and custom geometry fabrication. Strategic moves center on backward integration into platinum-iridium feedstock and sterile field consignment programs at high-volume stroke centers.
Among diversified device manufacturers, Medtronic Plc. and Boston Scientific Corporation exemplify scale-driven archetypes with upstream control over radiopaque material sourcing. Cook Medical occupies a specialist position anchored in custom band geometries for neurovascular access. Stanford Advanced Materials represents the purification-focused tier competing on feedstock consistency rather than device integration.
| Leading Market Players |
|---|
| Stryker Corporation |
| Cook Medical |
| Medtronic Plc. |
| Stanford Advanced Materials |
| Biomerics |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Resonetics |
| Johnson Matthey |
| Others |
Value Chain & Pricing Dynamics
Ninety-day platinum-iridium feedstock lead times concentrate pricing power with German and United States metallurgy partners who anchor catheter OEM procurement strategies. Inventory carrying costs for precious metal alloys amplify margin sensitivity across contract manufacturers lacking backward integration into refining capacity.
Pricing Analysis
The customization-premium spread separates configured-to-order platinum-iridium geometries from standard silicone band catalogs by factors reflecting metallurgical complexity and ISO 10993 certification tiers. Three-tier pricing structure across premium, standard, and economy levels tracks radiopacity density per unit mass, with neurovascular specifications commanding the widest spreads. Cost compression in economy-tier PVC and barium-loaded configurations intensifies as bismuth-polymer catheter shafts displace separate band components. Ambulatory surgical centers exhibit the highest price sensitivity through distributor purchasing, while tertiary stroke centers prioritize technical collaboration over unit cost.
Supply Chain Analysis
South Africa and Russia anchor platinum group metal extraction, while Germany and the United States concentrate precision alloy fabrication and micro-welding expertise. Feedstock draws from South African mining operations, Russian refining output, and secondary recovery from aerospace scrap streams. Single-source vulnerability sits with South African platinum concentrators subject to electricity grid instability and labor disruptions. Distribution runs through direct long-term supply agreements with Medtronic, Boston Scientific, and Cook Medical for high-volume OEMs, with distributor networks handling fragmented Asia-Pacific and Latin American demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
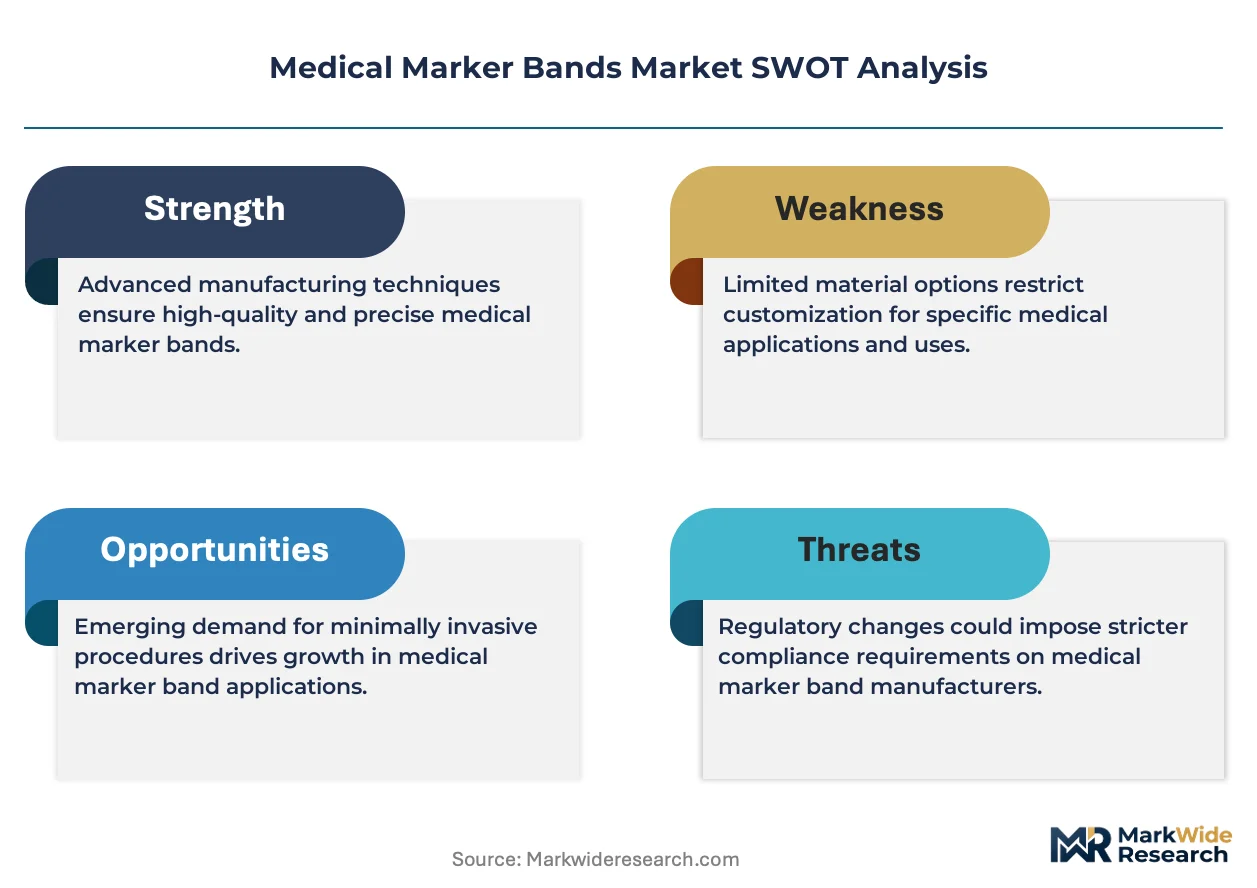
Medical marker bands face sustained substitution pressure from polymer-based radiopacity solutions that eliminate discrete metal components entirely. Incumbents must navigate this threat while defending premium positioning in neurovascular and electrophysiology segments where imaging density requirements exclude polymer alternatives.
For Market Incumbents: Shield platinum-iridium premium tiers by deepening captive metallurgy partnerships that secure feedstock continuity against South African supply disruptions. Accelerate sterile field consignment programs at Cleveland Clinic and Mayo Clinic stroke centers to lock in hospital system purchasing power before polymer substitutes penetrate diagnostic coronary segments. Prioritize ISO 13485:2016 recertification with MDSAP scope to capture vendor consolidation windows as notified body bottlenecks compress competitor timelines. For New Entrants and Emerging Players: Differentiate on tantalum nitride sputtering capabilities for sub-50-micron marker layers that reduce vessel trauma in next-generation neurovascular access devices. Target Japan's PMDA fast-track pathway for stroke intervention devices, where domestic precious metal refining capacity and METI industrial policy support premium iridium marker adoption. Pursue direct-to-hospital consignment models at high-volume United States integrated delivery networks as the primary go-to-market angle, bypassing distributor margin extraction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized precious metal purification capabilities applicable to medical radiopacity standards. Long-term viability hinges on defensible positioning in neurovascular segments where polymer substitutes fail to meet fluoroscopic density requirements. Signal to watch: REACH authorization restrictions on tantalum compounds that would force alloy reformulation and consolidate procurement toward qualified Australian and Canadian feedstock sources.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Metallurgy Partnership | Secures platinum-iridium feedstock continuity against South African mining volatility for catheter OEMs. |
| Sterile Field Consignment Program | Captures margin pools at Cleveland Clinic and Mayo Clinic through usage-based invoicing models. |
| Tantalum Nitride Sputtering Scale-Up | Enables sub-50-micron marker layers for neurovascular devices requiring minimal vessel trauma. |
| ISO 13485:2016 MDSAP Recertification | Qualifies suppliers for vendor consolidation waves as notified body bottlenecks extend competitor timelines. |
| REACH-Compliant Feedstock Qualification | Positions German OEMs ahead of potential ECHA authorization restrictions on conflict-mined tantalum sources. |
Study Parameters
Cross-validation between catheter OEM procurement executives and precious metal refinery technical directors anchors the qualitative findings on alloy specification trends. Primary interviews with biomedical engineers at academic medical centers, GPO contracts managers, and FDA regulatory consultants combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, and hospital procurement records. Bottom-up demand modeling triangulates against top-down precious metal consumption estimates across medical device applications.
Sensitivity analysis across platinum price volatility bands and notified body certification delay scenarios tests forecast robustness. Segmentation dimensions span material composition, catheter application, end-user scale, and distribution channel structure throughout the forecast period. CAGRs derive from procedure volume trajectories in electrophysiology and neurovascular segments, weighted by radiopacity density requirements per device category. Industry-specific inputs include REACH candidate list evaluation timelines and PMDA fast-track designation patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance pathway stability or abrupt South African platinum supply disruption would require recalibration. Forecasts reflect assumptions on polymer substitution rates in diagnostic coronary applications and EU MDR transition completion timelines. Recalibration cycles align with material shifts in ECHA substance evaluations and PMDA regulatory guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Stem Cell Panel Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Fluorescence Cell Market