
 Real-Time PCR, Digital PCR, and End-Point PCR Market | 2026-2036
Real-Time PCR, Digital PCR, and End-Point PCR Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time PCR, Digital PCR, and End-Point PCR Market Intelligence
Synthetic polymer optical components are decoupling from traditional glass-based detection modules in mid-range quantitative PCR systems, cutting per-unit sensor costs while maintaining fluorescence sensitivity thresholds. Thermo Fisher Scientific leverages its vertical integration across thermal cyclers and reagent chemistries to sustain margin capture across the instrument-to-consumable lifecycle. F. Hoffmann-La Roche Ltd. anchors its position through proprietary TaqMan probe ecosystems that lock diagnostic laboratories into recurring reagent contracts. Danaher Corporation competes by extending its Beckman Coulter automation expertise into high-throughput dPCR workflows for liquid biopsy applications.
Real-time PCR, digital PCR, and end-point PCR constitute nucleic acid amplification technologies that quantify or detect DNA/RNA targets through thermal cycling with fluorescence monitoring, achieving detection sensitivities down to single-digit copies per microliter. These platforms serve clinical diagnostics, pharmaceutical research, and forensic identification by enabling precise genetic mutation detection, viral load quantification, and gene expression profiling. Digital PCR systems command premium positioning due to absolute quantification without standard curves, while real-time PCR dominates installed-base volume across hospital and reference laboratory settings. Forensic analysis applications are maturing with established capillary electrophoresis complements, whereas environmental testing represents an emerging growth vector for portable end-point PCR configurations.
FDA's in vitro diagnostic and 510(k) clearance frameworks shape product development timelines and clinical claim substantiation for US market entry, while EMA's IVDR transition in Europe is forcing manufacturers to rebuild technical documentation and performance validation dossiers. China's NMPA has tightened registration requirements for imported nucleic acid detection instruments, creating compliance barriers that favor domestic producers or joint-venture structures. Stakeholders must monitor regulatory divergence across FDA, EMA, and NMPA pathways when allocating R&D resources and determining regional product launch sequencing.
Market Dynamics
Synthetic polymer optical components are displacing glass-based detection modules in mid-range quantitative PCR systems, compressing per-unit sensor costs while preserving fluorescence sensitivity thresholds for clinical diagnostic laboratories.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearance frameworks for companion diagnostics are pulling qPCR and dPCR platforms into infectious disease and oncology testing workflows at expanded hospital and reference laboratory sites.
- China NMPA registration reforms:Tightened requirements for imported nucleic acid detection instruments are redirecting procurement toward domestic producers and joint-venture structures, stimulating local manufacturing scale.
- Liquid biopsy automation:Beckman Coulter's high-throughput dPCR workflows are anchoring demand from pharmaceutical research segments pursuing absolute quantification without standard curves.
Market Restraints
- Reagent lock-in economics:Proprietary probe ecosystems like TaqMan create switching costs that fragment laboratory procurement autonomy and inflate lifetime ownership expenses.
- Input cost volatility:Fluorescent dye and polymer supply concentration in German and Chinese chemical manufacturing clusters exposes instrument producers to raw material price swings.
- Technical sensitivity floors:End-point PCR systems face hard detection limits below single-digit copy thresholds, constraining deployment in ultra-low viral load quantification applications.
Strategic Opportunities
- Environmental testing expansion:Portable end-point PCR configurations are penetrating water quality and agricultural surveillance segments underserved by laboratory-bound platforms.
- EMA IVDR technical documentation rebuild:Manufacturers investing early in performance validation dossiers capture first-mover positioning as European diagnostic laboratories rebid instrument contracts.
- Forensic capillary electrophoresis convergence:Integrated PCR-CE workflows are consolidating identification workflows for law enforcement agencies seeking single-platform solutions.
Industry Challenges
- Bioinformatics integration complexity:Laboratory information management systems require costly middleware development to synchronize dPCR absolute quantification outputs with existing electronic health record architectures.
- Thermal cycler calibration certification:ISO 17025 traceability demands for temperature uniformity validation extend deployment timelines and strain field service engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-Time PCR, Digital PCR, and End-Point PCR Market |
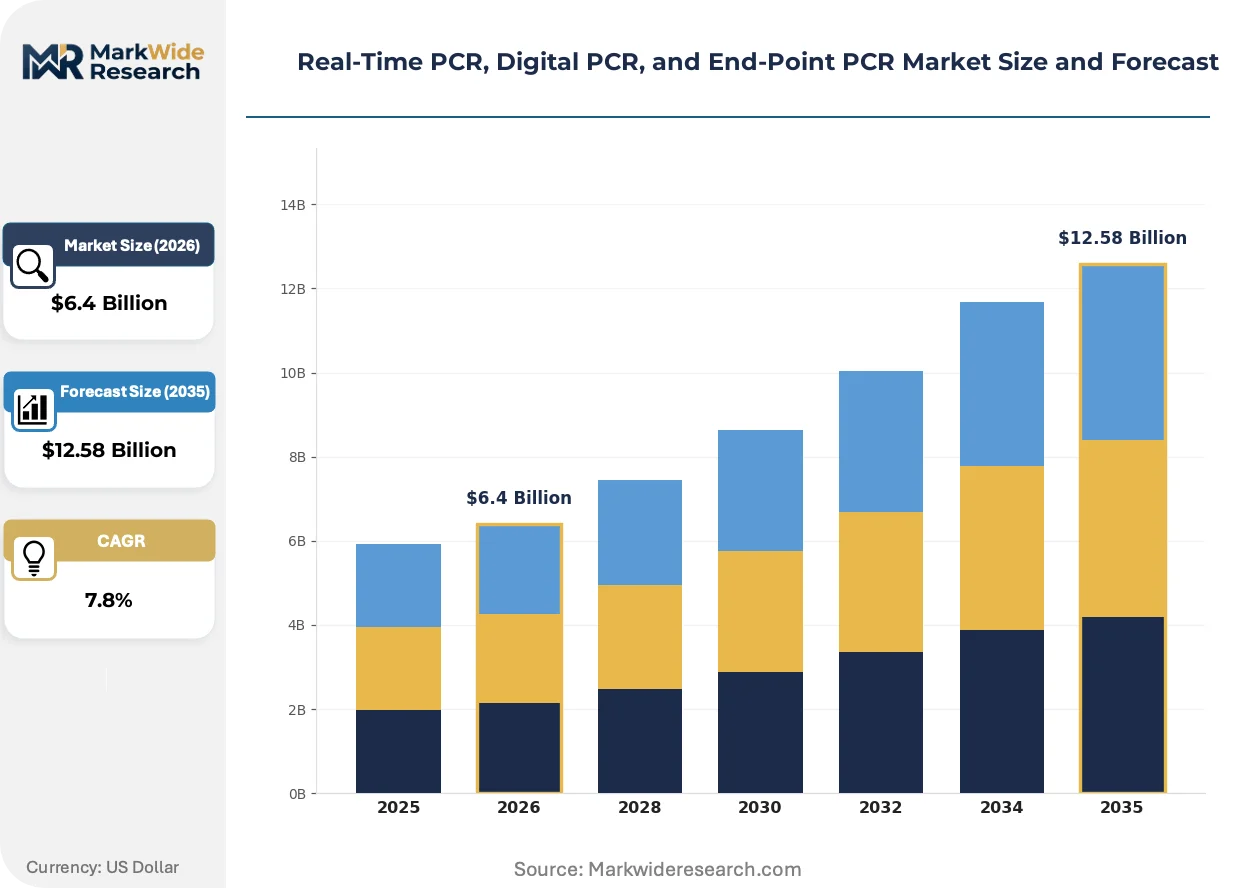
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time PCR, Digital PCR, End-Point PCR, Standard PCR Technology: Fluorescent Probes, SYBR Green, TaqMan, LAMP Application: Clinical Diagnostics, Research & Development, Forensic Analysis, Environmental Testing End User: Hospitals, Academic Institutions, Diagnostic Laboratories, Pharmaceutical Companies |
| Companies Covered | Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., Danaher Corporation, Bio-Rad Laboratories Inc., Abbott, QIAGEN, Agilent Technologies Inc., Merck KGaA, Fluidigm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time PCR, Digital PCR, and End-Point PCR Market Strategic Shifts & Innovations
Microfluidic cartridge miniaturization and cloud-connected instrument telemetry are compressing the boundary between centralized reference laboratories and distributed point-of-care testing environments.
Synthetic polymer optical detection modules are absorbing the cost-performance tradeoff previously occupied by precision-ground glass lenses in quantitative PCR systems. Hospital procurement committees are specifying these configurations for mid-throughput infectious disease panels. The technology is absorbing margin pressure from reagent bundling contracts by lowering upfront instrument capital requirements.
EMA's In Vitro Diagnostic Regulation transition is forcing manufacturers to reconstruct technical documentation and clinical performance validation dossiers for European market access. This regulatory friction is delaying product launches by 12-18 months for instruments lacking pre-IVDR legacy certifications. Oncology companion diagnostic platforms face the steepest compliance burden as notified bodies prioritize high-risk device reviews.
Reference laboratory procurement committees are unbundling after-sales service contracts from instrument acquisition agreements, compressing vendor recurring revenue streams. Thermo Fisher Scientific and Danaher are responding with modular service tiers priced by uptime guarantees rather than fixed annual contracts. This pattern is most visible in United States hospital systems where capital equipment committees have gained procurement autonomy from centralized supply chain functions.
Real-Time PCR, Digital PCR, and End-Point PCR Market Segmentation
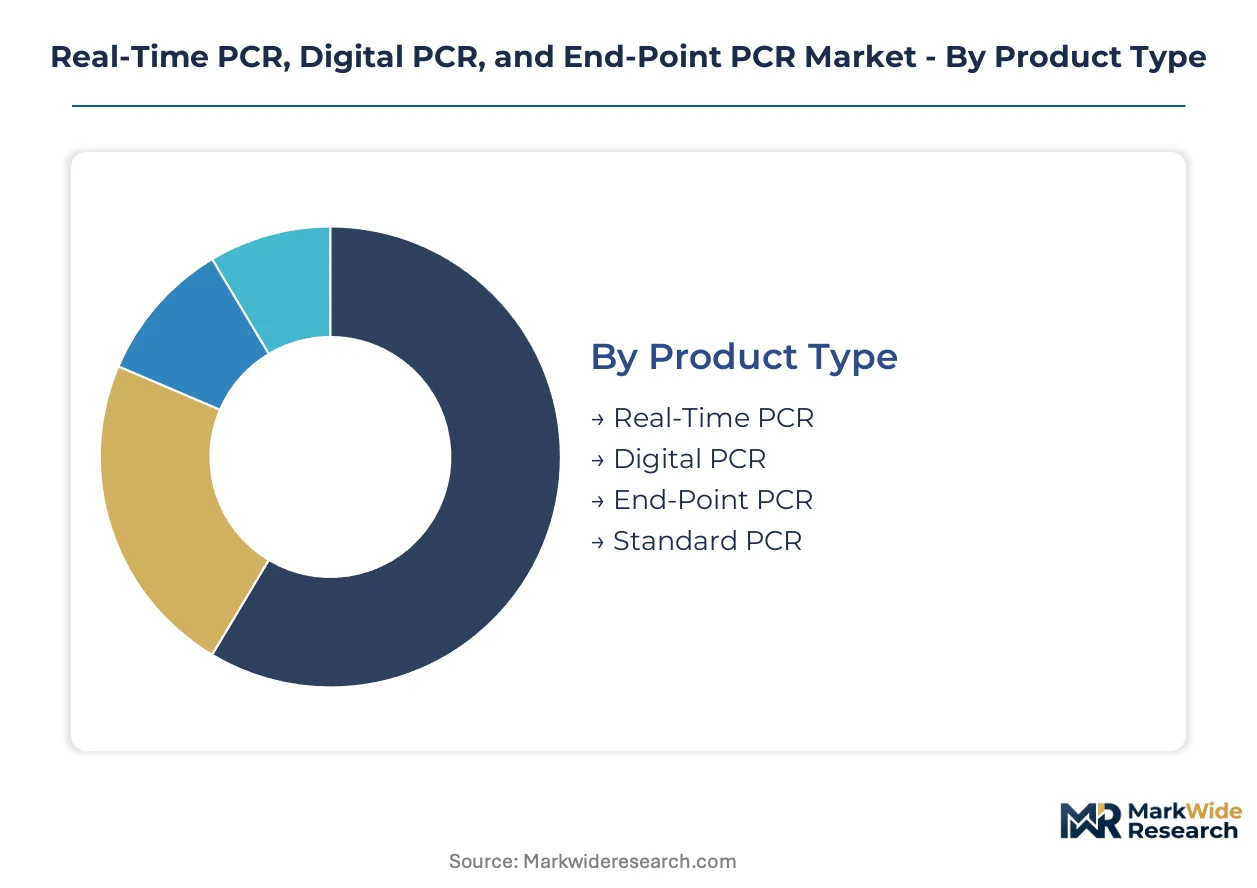
PCR platform segmentation reveals distinct supply chain configurations across product architectures, detection chemistries, and end-use environments. Each dimension carries specific procurement patterns, regulatory burdens, and margin structures that shape vendor positioning strategies.
Product Type:
Supply concentration clusters around thermal cycler manufacturing in Germany, the United States, and China, with domestic content requirements in Beijing and Shanghai favoring local assembly partnerships.
- Real-Time PCR:Continuous fluorescence monitoring during thermal cycling enables quantitative viral load measurement and gene expression analysis. Hospital laboratories in the United States and Germany specify these platforms for infectious disease panels, though reagent bundling contracts from Thermo Fisher and Roche inflate lifetime ownership costs. Today's leader: Real-Time PCR. Tomorrow's challenger: Digital PCR.
- Digital PCR:Absolute quantification through single-molecule partitioning eliminates standard curve dependencies, commanding premium positioning in pharmaceutical liquid biopsy workflows. Beckman Coulter's high-throughput configurations anchor demand from Danaher's installed base in reference laboratories pursuing rare mutation detection.
- End-Point PCR:Post-cycling gel or capillary electrophoresis analysis serves forensic identification and basic research with lower capital thresholds.
- Standard PCR:Conventional thermal cycling without real-time detection occupies educational and entry-level research segments in academic institutions.
Real-Time PCR dominates installed-base economics. Digital PCR is climbing the fastest through absolute quantification premiums.
Technology:
Detection chemistry supply chains concentrate fluorescent dye production in German and Chinese chemical manufacturing clusters, exposing instrument producers to input cost volatility and purity grade variability.
- Fluorescent Probes:Sequence-specific hybridization probes deliver single-nucleotide discrimination for companion diagnostic applications. Oncology testing workflows in the United States drive specification of these chemistries for FDA 510(k) cleared assays.
- SYBR Green:Intercalating dye chemistry offers cost-efficient melt curve analysis for research applications lacking proprietary probe requirements. Academic institutions in Germany favor SYBR Green for gene expression screening where absolute specificity is secondary to throughput economics.
- TaqMan:Roche's proprietary hydrolysis probe ecosystem locks diagnostic laboratories into recurring reagent contracts with switching costs that fragment procurement autonomy.
- LAMP:Isothermal amplification bypasses thermal cycler requirements, enabling portable point-of-care configurations for environmental field testing and resource-limited settings.
TaqMan chemistry captures the highest reattach rates. LAMP is gaining share fastest through miniaturization and ambient-temperature stability.
Application:
End-use demand fragments across regulated clinical environments, unregulated research settings, and emerging field deployment scenarios with divergent performance validation requirements.
- Clinical Diagnostics:FDA and EMA cleared assays for infectious disease and oncology require instrument qualification, software validation, and traceable calibration protocols. Hospital laboratories in the United States concentrate procurement authority in capital equipment committees that unbundle service contracts from instrument acquisition.
- Research & Development:Pharmaceutical discovery workflows prioritize flexibility over regulatory compliance, with absolute quantification from digital PCR platforms supporting biomarker validation studies.
- Forensic Analysis:Capillary electrophoresis integration for short tandem repeat profiling serves law enforcement agencies seeking single-platform identification solutions.
- Environmental Testing:Portable end-point PCR configurations penetrate water quality and agricultural surveillance segments underserved by laboratory-bound platforms.
Clinical Diagnostics commands premium pricing. Environmental Testing shows the steepest expansion trajectory through regulatory sampling mandates.
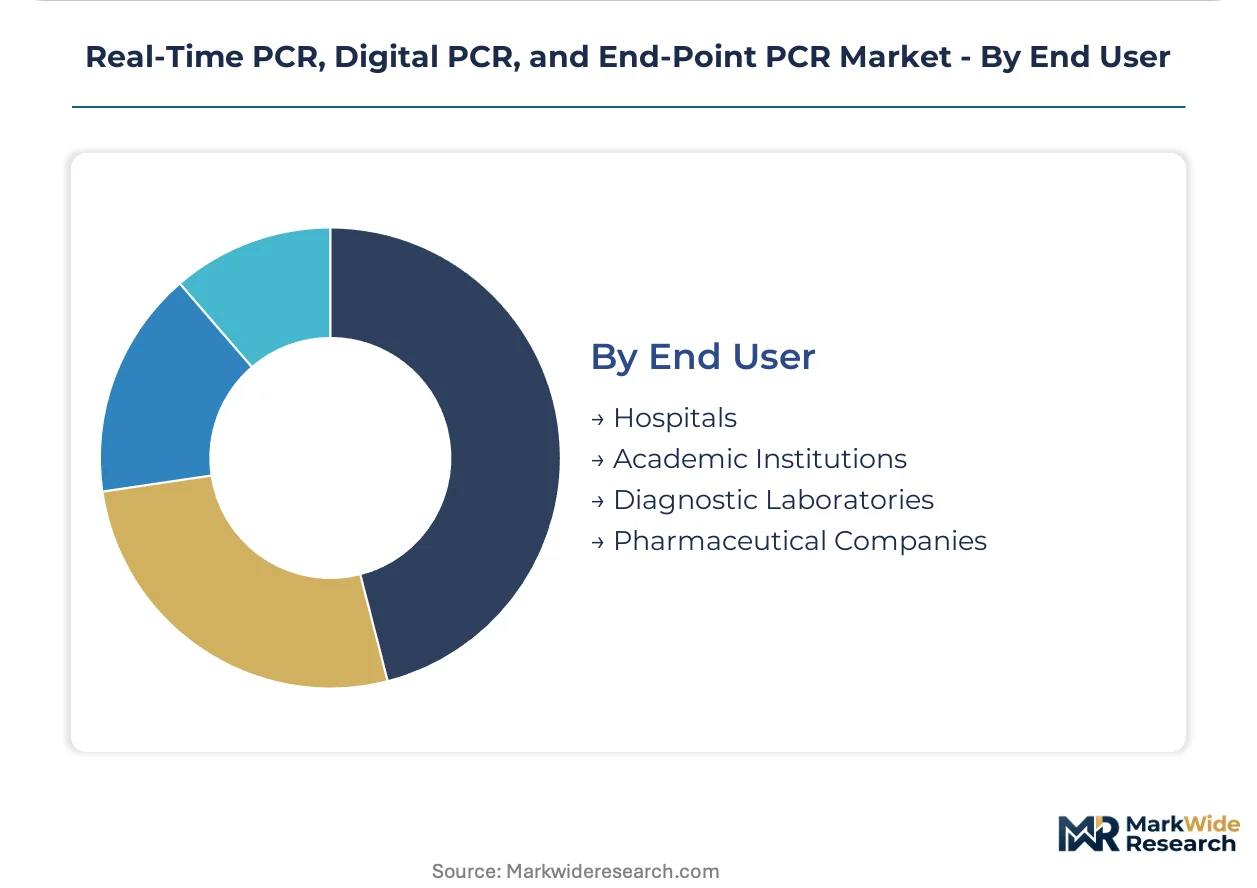
End User:
Procurement autonomy varies sharply across centralized hospital systems, decentralized academic purchasing, and reference laboratory consolidation trends reshaping vendor account management.
- Hospitals:Integrated delivery networks in the United States consolidate PCR platform decisions through supply chain committees with ISO 17025 calibration requirements extending deployment timelines.
- Academic Institutions:Grant-funded research laboratories prioritize capital efficiency over throughput, favoring open-platform reagent compatibility.
- Diagnostic Laboratories:Reference lab consolidation in Germany and China concentrates volume with multi-year service contracts tied to uptime guarantees rather than fixed annual fees.
- Pharmaceutical Companies:Drug development pipelines require GMP-compliant instrumentation with extensive qualification documentation for regulatory submission support.
Diagnostic Laboratories anchor recurring revenue. Pharmaceutical Companies offer the highest per-unit margins through companion diagnostic co-development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area houses the densest concentration of digital PCR innovation labs, while hospital procurement committees in Boston and New York Metro drive instrument specification standards. FDA 510(k) clearance timelines and NMPA registration reforms are redrawing competitive access maps across three continents.
United States
Hospital capital equipment committees in Massachusetts and California unbundle service contracts from instrument purchases, compressing vendor recurring revenue. FDA's streamlined companion diagnostic pathway accelerates qPCR platform adoption for infectious disease panels. The Boston-Cambridge corridor anchors pharmaceutical liquid biopsy demand from Danaher's installed base.
Germany
Reference laboratory consolidation in North Rhine-Westphalia concentrates multi-year procurement authority with uptime-guarantee pricing. EMA's IVDR transition forces manufacturers to rebuild technical documentation, delaying launches 12-18 months for instruments lacking legacy certifications. The Munich-Stuttgart axis dominates thermal cycler manufacturing supply chains.
China
Domestic producers in Beijing and Shanghai capture redirected procurement from tightened NMPA registration requirements for imported nucleic acid detection instruments. Hospital procurement cycles in Guangdong and Jiangsu provinces are shortening for mid-range quantitative PCR systems. Joint-venture structures with German and US partners accelerate local manufacturing scale.
Japan
PMDA's quality management system inspections extend deployment timelines for foreign instrument manufacturers seeking clinical diagnostic market access. Academic institutions in the Kanto region prioritize capital-efficient SYBR Green chemistries for gene expression screening. The Osaka-Kobe industrial zone supplies precision optical components for fluorescence detection modules.
United Kingdom
NHS procurement frameworks specify ISO 17025 traceability for temperature uniformity validation, straining field service engineering capacity. Research laboratories in the Cambridge-Oxford arc drive demand for open-platform reagent compatibility. MHRA's post-Brexit regulatory divergence from EMA pathways creates parallel compliance burdens for instrument dossiers.
Real-Time PCR, Digital PCR, and End-Point PCR Market Key Industry Players
Global majors compete with regional champions across reagent chemistry ecosystems and thermal cycler manufacturing. The market structures around three tiers: integrated life science conglomerates with captive consumable streams, specialized diagnostic instrument manufacturers, and emerging domestic producers in regulated Asian markets. Consolidation pressure concentrates in the middle tier as reference laboratory procurement committees demand end-to-end workflow validation. Competitive moves center on backward integration into fluorescent dye supply and strategic partnerships for microfluidic cartridge miniaturization.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and F. Hoffmann-La Roche Ltd. occupy positions defined by vertical control across instrument and reagent lifecycles. Danaher Corporation exemplifies the automation-forward archetype extending reference laboratory workflows into high-throughput configurations. These three entities anchor competitive dynamics through distinct lock-in mechanisms: thermal cycler-to-consumable bundling, proprietary probe ecosystems, and liquid biopsy workflow integration respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| Bio-Rad Laboratories Inc. |
| Abbott |
| QIAGEN |
| Agilent Technologies Inc. |
| Merck KGaA |
| Fluidigm Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up diagnostic specialists have compressed procurement timelines for mid-range quantitative PCR systems by consolidating hospital purchasing authority, simultaneously squeezing vendor margins and forcing supply chain reconfiguration toward lower-cost polymer optical components.
Pricing Analysis
Fluorescent dye and polymer supply concentration in German and Chinese chemical manufacturing clusters drives input-cost pass-through volatility into instrument pricing. Pricing stratifies across premium digital PCR configurations, standard real-time PCR platforms, and economy end-point PCR tiers based on detection sensitivity thresholds and ISO 17025 calibration certification. Cost compression in the economy tier is intensifying because domestic Chinese producers exploit NMPA registration reforms to undercut imported instruments. Academic institutions exhibit the highest price sensitivity, while pharmaceutical companies pursuing companion diagnostic co-development show minimal elasticity.
Supply Chain Analysis
ISO 17025 traceability certification for temperature uniformity validation gates supplier participation in clinical diagnostic procurement, favoring established thermal cycler manufacturers with documented quality systems. Manufacturing concentrates in Germany, the United States, and China, with precision optical component fabrication anchored in Japan's Osaka-Kobe industrial zone. The supply chain draws from fluorescent dye chemistries, polymer injection molding feedstocks, and semiconductor-based photodetector arrays. Single-source vulnerability runs through German specialty chemical producers of high-purity fluorescent probes. Distribution feeds through hospital capital equipment committees, reference laboratory consolidation entities, and academic grant procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
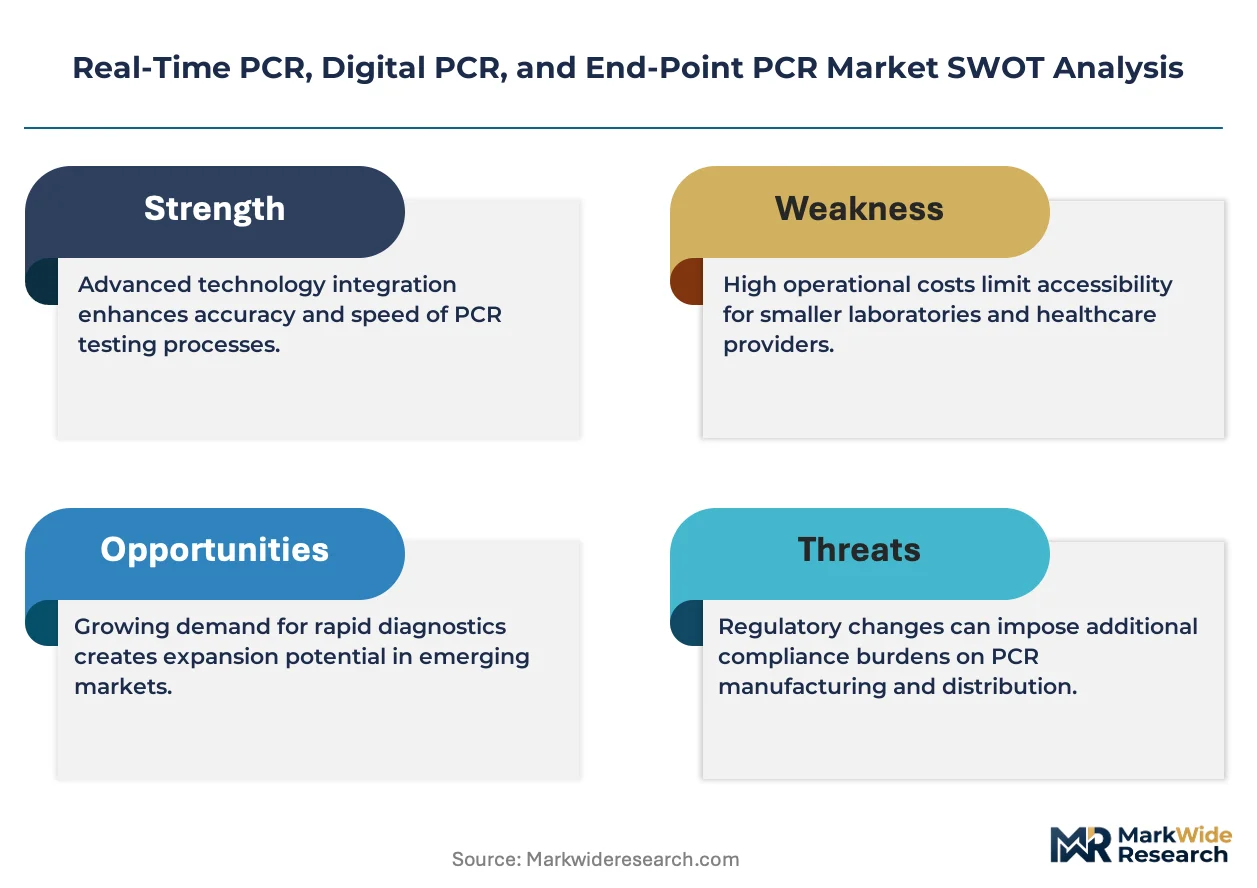
The Real-Time PCR, Digital PCR, and End-Point PCR Market functions as a regulatory compounder where EMA's IVDR transition is forcing diagnostic laboratories to rebid instrument contracts, generating replacement demand regardless of underlying test volume growth.
For Market Incumbents: Extend proprietary reagent ecosystems into high-throughput dPCR workflows to lock reference laboratories into recurring consumable contracts before Beckman Coulter consolidates liquid biopsy automation. Thermo Fisher Scientific should deepen backward integration into fluorescent dye supply to defend margin position against Chinese domestic producers exploiting NMPA registration barriers. ISO 17025 calibration service infrastructure represents the critical lever for differentiation as procurement committees unbundle after-sales agreements.
For New Entrants and Emerging Players: EMA's IVDR technical documentation rebuild in Europe opens a window for first-mover positioning among manufacturers investing early in performance validation dossiers for oncology companion diagnostic platforms. Target environmental testing applications with portable end-point PCR configurations, the most penetrable segment given regulatory sampling mandates for water quality and agricultural surveillance. Pursue joint-venture structures with Beijing or Shanghai partners to circumvent NMPA import restrictions and access domestic hospital procurement channels.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized diagnostic instrument manufacturers lacking captive reagent chemistry ecosystems, as reference laboratory consolidation pressures standalone hardware vendors. The five-to-ten-year viability window favors acquisition targets with microfluidic cartridge miniaturization capabilities and cloud-connected instrument telemetry platforms. Watch FDA 510(k) clearance velocity for liquid biopsy companion diagnostics as the inflection signal indicating which dPCR platforms will capture pharmaceutical research budgets.
| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Cartridge Miniaturization | Compresses boundary between centralized laboratories and point-of-care testing environments in infectious disease panels. |
| Cloud-Connected Instrument Telemetry | Enables predictive maintenance pricing and uptime guarantee contracts that hospital procurement committees now specify. |
| Backward Integration into Fluorescent Dye Supply | Reduces exposure to German and Chinese chemical manufacturing cluster volatility while capturing reagent margin. |
| Joint Venture Manufacturing in China | Circumvents NMPA registration barriers for imported nucleic acid detection instruments through domestic production. |
| ISO 17025 Calibration Service Infrastructure | Addresses NHS and German reference laboratory requirements for temperature uniformity traceability validation. |
Research Approach
Direct dialogue with hospital laboratory directors, reference lab procurement managers, biomedical engineers, and regulatory affairs specialists at diagnostic instrument manufacturers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) clearance databases, EMA IVDR technical documentation filings, NMPA registration records, and hospital capital equipment committee procurement protocols. Bottom-up instrument shipment modeling and top-down diagnostic testing demand estimation were triangulated against reagent chemistry consumption patterns.
Segmented outputs across real-time PCR, digital PCR, end-point PCR, and standard PCR product architectures were projected over the analysis window. Detection chemistry segmentation incorporated fluorescent probes, SYBR Green, TaqMan, and LAMP technology pathways. Application modeling spanned clinical diagnostics, pharmaceutical research, forensic analysis, and environmental testing with divergent regulatory validation requirements. CAGRs were derived from instrument replacement cycles, laboratory expansion capex, and companion diagnostic co-development pipeline density.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory divergence between FDA, EMA, and NMPA pathways or sustained fluorescent dye supply disruption. A model refresh is warranted upon material change in IVDR notified body review capacity or NMPA joint-venture policy enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Medical Isotope Market