
 North America Nuclear Medicine Market | 2026-2036
North America Nuclear Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nuclear Medicine Market Analytics
Hospital procurement of radiopharmaceuticals is tilting toward consolidated purchasing agreements and direct manufacturer contracts. Cardinal Health leverages its distribution infrastructure to anchor supply chain control across the United States. Curium competes through vertical integration into isotope production, while Lantheus Medical Imaging specializes in PET agent development for oncology diagnostics.
Nuclear medicine encompasses the clinical use of radioactive substances for both diagnostic imaging and targeted therapy, requiring precise half-life management, radiochemical purity above 95 percent, and sterile manufacturing under cGMP conditions to ensure patient safety and diagnostic accuracy. SPECT and PET technologies dominate current installed bases, though hybrid imaging systems command premium positioning as they merge functional and anatomical data in a single session. Therapeutic agents represent the fastest-expanding product category as alpha-emitting radiopharmaceuticals displace conventional external beam approaches in selective oncology indications.
The FDA governs radiopharmaceutical approval under 21 CFR Part 315, while the Nuclear Regulatory Commission enforces dose limits and handling protocols; Health Canada and its radiopharmaceutical regulator impose parallel standards that manufacturers must satisfy for cross-border market access. State-level nuclear pharmacy licensing boards add operational complexity, particularly for PET agent distribution with short half-lives. Stakeholders must monitor reimbursement policy evolution for theranostic pairings, as coding decisions will determine whether therapeutic radioisotopes achieve sustainable utilization rates.
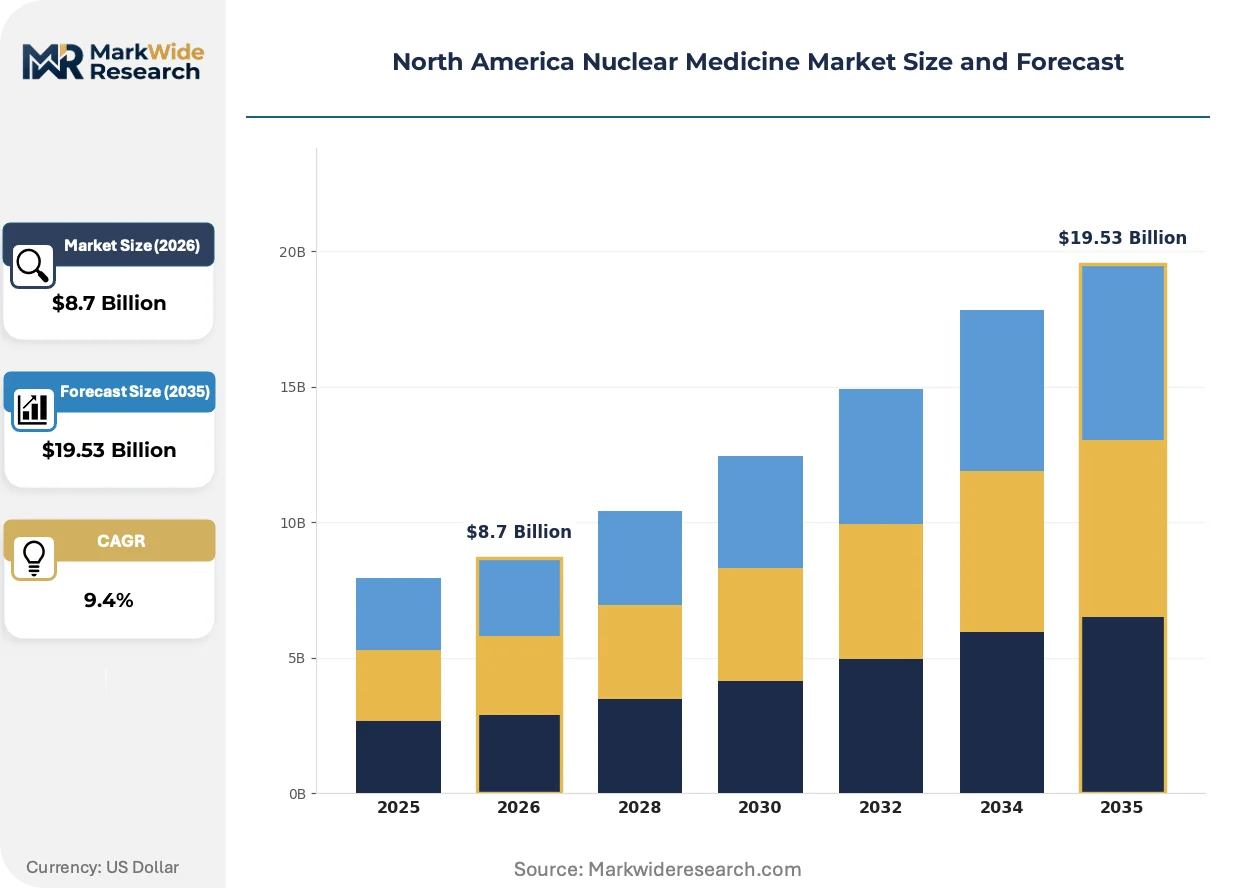
Market Dynamics
Theranostic protocol adoption is restructuring radiopharmaceutical demand patterns across North America, forcing cancer treatment centers to synchronize diagnostic and therapeutic isotope procurement under unified clinical pathways.
Growth Catalysts
- FDA 21 CFR Part 315 Streamlining:Accelerated approval pathways for novel radioisotopes compress commercialization timelines from investigational new drug to market distribution.
- Alpha-Emitter Therapeutics:Targeted alpha therapy displaces external beam radiation in selective oncology indications, expanding therapeutic radiopharmaceutical pipelines.
- Northeast Corridor Concentration:Academic medical center clustering in Boston, New York, and Philadelphia drives clinical adoption through research-to-practice translation networks.
Market Restraints
- Reactor Dependency:Molybdenum-99 supply concentrates in aging North American research reactors, creating single-point vulnerability for technetium-99m generators.
- Half-Life Logistics:Fluorine-18's 110-minute decay window imposes geographic radius constraints on PET agent distribution, limiting rural market access.
- Reimbursement Coding Lag:CMS and private payers maintain separate coding for diagnostic and therapeutic isotopes, fragmenting theranostic pair reimbursement.
Strategic Opportunities
- Canadian Isotope Production:Ontario's Chalk River successor facilities and TRIUMF cyclotron infrastructure offer alternative supply sources for U.S. distributors.
- Hybrid Imaging Convergence:PET-MRI and SPECT-CT system integration creates bundled radiopharmaceutical demand for multimodal tracer protocols.
- Direct-to-Hospital Contracts:Manufacturer bypass of group purchasing organizations enables customized half-life scheduling and volume commitment pricing.
Industry Challenges
- Radiochemist Workforce Scarcity:Nuclear pharmacy residency programs graduate fewer than 50 specialists annually across the United States, constraining production facility staffing.
- cGMP Capital Intensity:Aseptic manufacturing suites for sterile radiopharmaceuticals require $15-25 million facility investments with 18-24 month validation timelines.
- State Licensing Fragmentation:Nuclear pharmacy boards in Texas, California, and Florida impose non-uniform compounding standards, complicating multi-state distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nuclear Medicine Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Imaging Agents, Therapeutic Agents, Diagnostic Agents End User: Hospitals, Diagnostic Centers, Research Institutions, Cancer Treatment Centers Application: Oncology, Cardiology, Neurology, Thyroid Disorders Technology: SPECT, PET, Hybrid Imaging, 3D Imaging |
| Companies Covered | Cardinal Health, Curium, GE HealthCare, Lantheus Medical Imaging, Siemens Healthineers, Novartis, Bayer, Bracco Diagnostics, Nordion, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nuclear Medicine Market Evolving Landscape
Radioisotope production technology and clinical protocol design are converging to compress the gap between diagnostic visualization and therapeutic intervention, eliminating traditional sequential care delays.
Cyclotron-based isotope production is collapsing the supply geography for fluorine-18 and carbon-11 tracers. Hospital-installed medical cyclotrons enable on-site PET agent synthesis, eliminating courier-dependent distribution for high-volume centers. This decentralization is compressing Cardinal Health's hub-and-spoke model into localized production nodes.
FDA's streamlined 21 CFR Part 315 pathways for radiopharmaceuticals are accelerating novel radioisotope commercialization. The reduced clinical trial burden for diagnostic agents is expanding investigational new drug filings. PET imaging suites in academic medical centers are absorbing the regulatory review workload through expanded institutional review board infrastructure.
Consolidated purchasing agreements are displacing fragmented hospital procurement of SPECT and PET agents. Cancer center networks in the U.S. Northeast are negotiating direct manufacturer contracts for theranostic pairs. This concentration is visible in Memorial Sloan Kettering and MD Anderson's radiopharmaceutical sourcing patterns, where volume commitments secure priority half-life scheduling.
North America Nuclear Medicine Market Segmentation
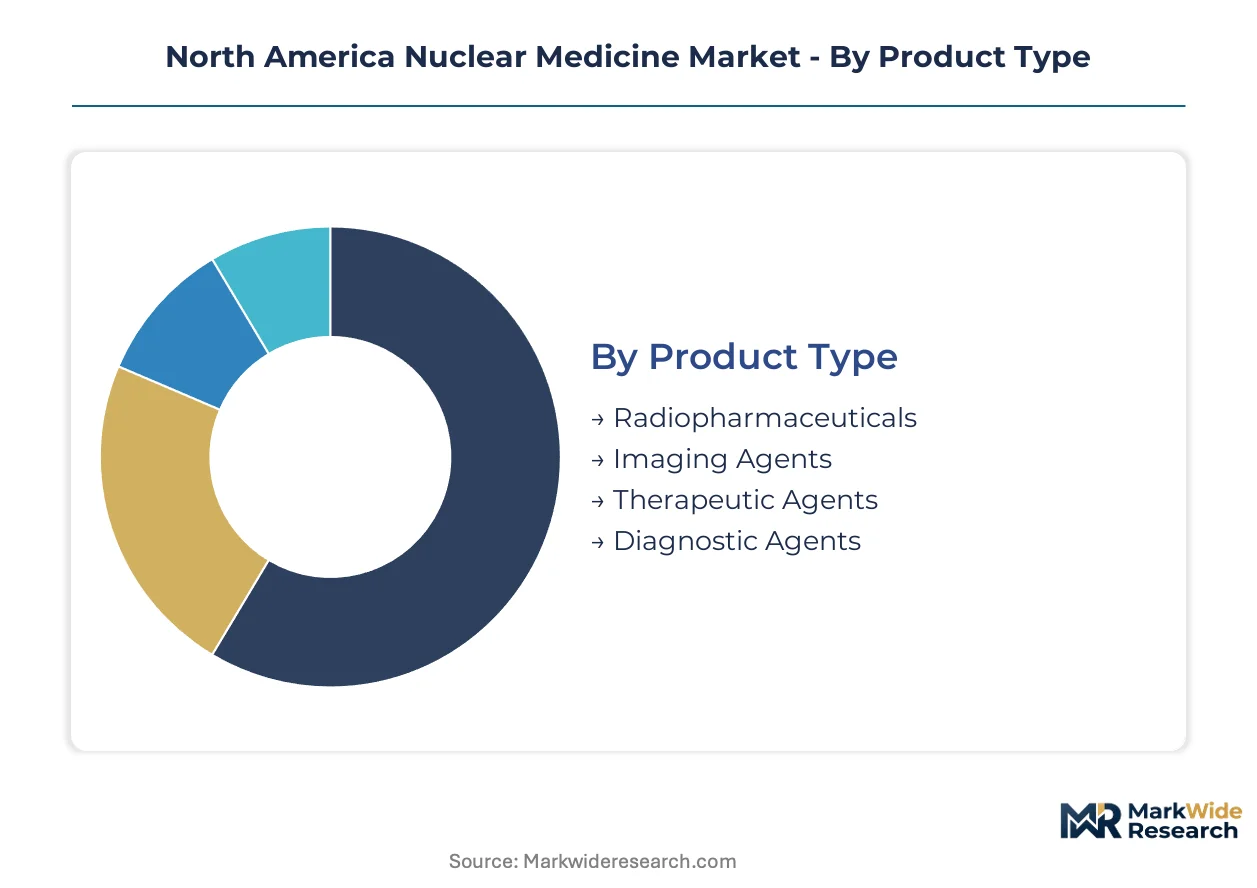
Radiopharmaceutical procurement patterns diverge sharply across product categories and clinical settings, with half-life constraints and reimbursement codes dictating purchasing behavior. Service intensity varies from emergency generator restocking to scheduled theranostic pair deliveries, reshaping vendor relationships across the value chain.
Product Type:
After-sales service intensity peaks with therapeutic agents requiring cold-chain custody documentation and dose calibration support, while diagnostic agents demand rapid-response courier networks.
- Radiopharmaceuticals:Encompass both diagnostic and therapeutic radioactive compounds with half-lives ranging from minutes to days, requiring specialized handling protocols. Demand concentrates in academic medical centers across the U.S. Northeast corridor, where theranostic protocol adoption drives synchronized procurement of matched isotope pairs.
- Imaging Agents:Include technetium-99m and fluorine-18 labeled compounds for SPECT and PET visualization, with radiochemical purity standards exceeding 95 percent. Cancer treatment centers in Boston and New York absorb the highest volumes as hybrid imaging suites expand installed capacity.
- Therapeutic Agents:Alpha-emitting radiopharmaceuticals for targeted oncology treatment with escalating service requirements for patient-specific dosing.
- Diagnostic Agents:Single-photon and positron-emitting tracers for organ function assessment with compressed logistics windows.
Radiopharmaceuticals hold the largest share; momentum sits with therapeutic agents.
End User:
Customer type determines contract structure, with hospital systems negotiating enterprise-wide agreements while research institutions require flexible batch sizing for investigational protocols.
- Hospitals:Integrated delivery networks with centralized nuclear pharmacy operations and group purchasing organization leverage. The U.S. Northeast corridor's academic medical centers—Massachusetts General, Memorial Sloan Kettering, Johns Hopkins—anchor procurement volume through research-to-practice translation networks.
- Cancer Treatment Centers:Specialized oncology facilities with concentrated theranostic demand and direct manufacturer contracting preferences. MD Anderson and Dana-Farber drive adoption of alpha-emitter therapies through protocol development partnerships with isotope suppliers.
- Diagnostic Centers:Outpatient imaging facilities with high SPECT throughput and price-sensitive generator sourcing.
- Research Institutions:Universities and national laboratories with cyclotron infrastructure and investigational new drug filing requirements.
Hospitals dominate procurement volume; cancer treatment centers are expanding most quickly.
Application:
Clinical indication shapes isotope selection, with oncology applications commanding premium pricing for targeted alpha therapy while cardiology maintains volume leadership through stress test protocols.
- Oncology:Prostate-specific membrane antigen targeting and neuroendocrine tumor therapy with lutetium-177 and actinium-225. Demand clusters at specialized cancer centers in Philadelphia and Houston, where FDA streamlined approval pathways accelerate novel radioisotope access.
- Cardiology:Myocardial perfusion imaging with technetium-99m sestamibi and rubidium-82 for coronary artery disease assessment. Community hospitals across Florida and Texas maintain the highest procedure volumes through established stress testing protocols.
- Neurology:Amyloid and tau imaging for Alzheimer's disease staging with florbetapir and flortaucipir.
- Thyroid Disorders:Iodine-131 therapy for hyperthyroidism and differentiated thyroid cancer with established reimbursement codes.
Cardiology maintains procedure volume leadership; oncology shows the steepest expansion trajectory.
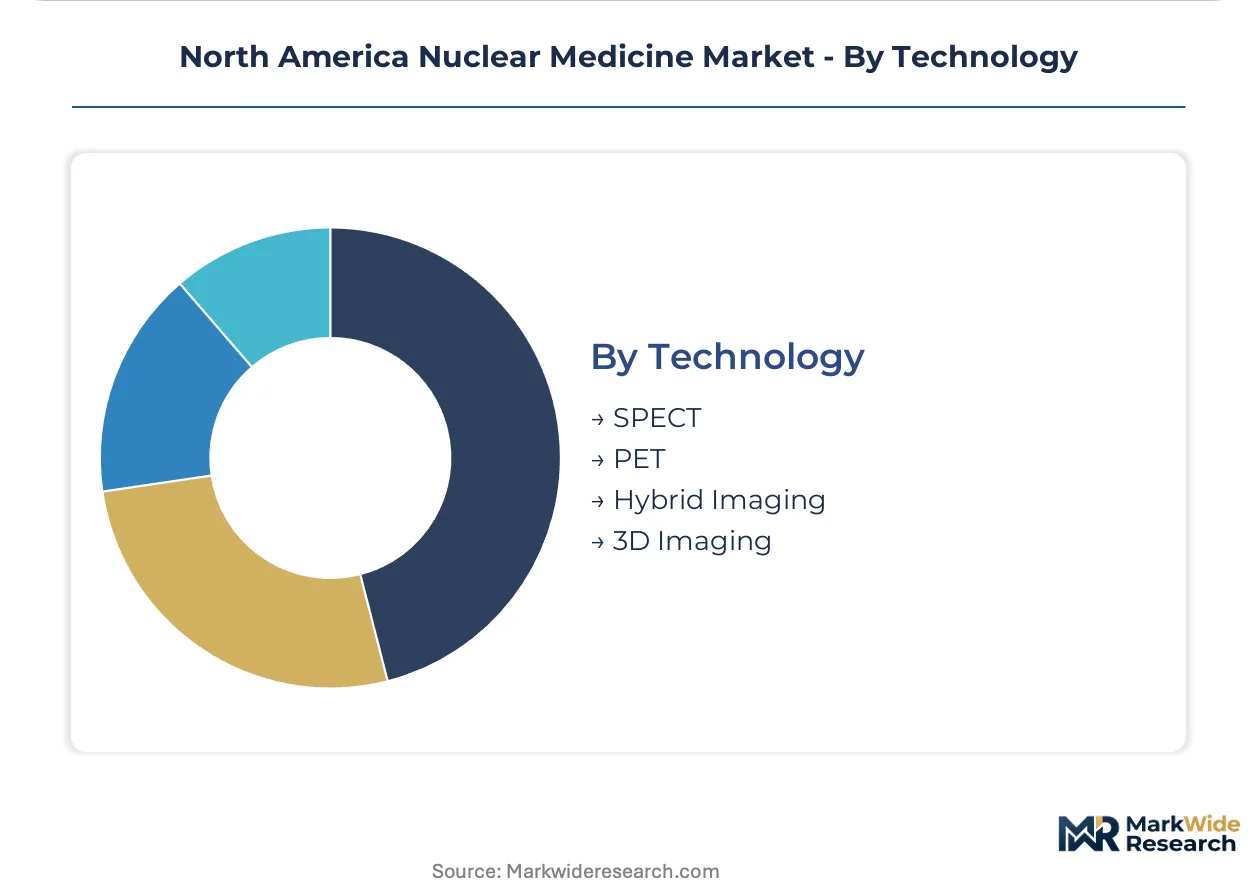
Technology:
Installed base configuration determines radiopharmaceutical form factor, with hybrid systems creating bundled tracer demand while standalone SPECT faces commoditization pressure.
- PET:Positron emission tomography with fluorine-18, carbon-11, and gallium-68 tracers requiring cyclotron or generator supply chains. Major metropolitan markets—New York, Los Angeles, Chicago—support dedicated production facilities with 110-minute half-life logistics.
- Hybrid Imaging:PET-CT and PET-MRI systems merging functional and anatomical data acquisition. Academic medical centers in the Northeast corridor command premium positioning through multimodal tracer protocols and research collaborations.
- SPECT:Single-photon emission computed tomography with technetium-99m generators and widespread rural penetration.
- 3D Imaging:Tomographic reconstruction algorithms enhancing quantitative accuracy for dosimetry applications.
SPECT retains installed base dominance; hybrid imaging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chalk River Laboratories infrastructure underwrites Canada's strategic position in North American isotope supply chains, while the U.S. Northeast Corridor's dense academic medical center clustering anchors clinical demand concentration.
United States
Memorial Sloan Kettering, MD Anderson, and Dana-Farber drive theranostic protocol adoption through research-to-practice translation networks. FDA 21 CFR Part 315 streamlined approval pathways compress investigational new drug-to-market timelines for novel radioisotopes. Boston, New York, and Philadelphia concentrate procurement volume as hybrid imaging suites expand installed capacity across academic medical centers.
Canada
Ontario's Chalk River successor facilities and TRIUMF cyclotron infrastructure offer alternative molybdenum-99 and technetium-99m supply sources for U.S. distributors. Health Canada and its radiopharmaceutical regulator impose parallel standards to FDA requirements for cross-border market access. Vancouver's TRIUMF laboratory anchors western Canadian isotope production capacity, supporting fluorine-18 and carbon-11 tracer synthesis for Pacific Northwest distribution.
Mexico
Mexico City Metro anchors diagnostic imaging demand through Instituto Nacional de Ciencias Médicas y Nutrición Salvador Zubirán and Hospital General de México. COFEPRIS, the country's national pharmaceutical regulator, enforces radiopharmaceutical licensing aligned with international standards. Northern border states concentrate generator restocking operations for cross-border patient referrals from Texas and California cancer treatment networks.
North America Nuclear Medicine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in isotope production and tracer synthesis. The vendor base stratifies across three tiers: diversified healthcare conglomerates with imaging system installed bases, pure-play radiopharmaceutical manufacturers with cyclotron or reactor assets, and regional nuclear pharmacy operators with last-mile distribution networks. Dominant competitive moves include direct-to-hospital contract negotiations bypassing group purchasing organizations, and backward integration into isotope production to secure supply chain control.
Within the diversified healthcare tier, GE HealthCare and Siemens Healthineers exemplify platform integrators leveraging hybrid imaging system installed bases to bundle radiopharmaceutical demand. Cardinal Health occupies a position as the dominant distribution archetype, while Lantheus Medical Imaging represents the specialized PET agent development segment. Curium anchors the vertical integration archetype through captive isotope production assets.
| Leading Market Players |
|---|
| Cardinal Health |
| Curium |
| GE HealthCare |
| Lantheus Medical Imaging |
| Siemens Healthineers |
| Novartis |
| Bayer |
| Bracco Diagnostics |
| Nordion |
| Others |
Value Network & Pricing Analysis
Undercapacity in North American research reactor infrastructure is compressing molybdenum-99 availability and amplifying spot-price volatility for technetium-99m generators. This utilization squeeze simultaneously tightens supplier pricing discipline and accelerates hospital procurement migration toward long-term offtake contracts with guaranteed volume allocation.
Pricing Analysis
Volume-discount tiering structures separate academic medical center consortia from standalone community hospitals and outpatient diagnostic centers. Price differentiation rests on cyclotron proximity, cold-chain custody requirements, and priority half-life scheduling guarantees. Cost compression in the diagnostic agent tier is intensifying as Cardinal Health's hub-and-spoke distribution faces hospital-installed cyclotron displacement. Community hospitals exhibit highest price sensitivity due to thin nuclear pharmacy margins, while cancer treatment centers absorb premium therapeutic agent pricing for alpha-emitter access.
Supply Chain Analysis
Export-control regimes on highly enriched uranium feedstock constrain molybdenum-99 flows between Canada and the United States under bilateral non-proliferation protocols. Geographic supply concentration centers on Ontario's Chalk River successor facilities, the Missouri-based National Isotope Development Center, and South African reactor imports. Raw material dependencies include uranium-235 targets, helium-3 neutron detection systems, and specialized lead-shielded transport casks. Single-source vulnerability pervades the generator assembly tier. Distribution runs through Cardinal Health's centralized nuclear pharmacy network with last-mile radiopharmacy satellite coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America nuclear medicine market is cycling through a supply-constrained recovery phase. Reactor refurbishment timelines and FDA 21 CFR Part 315 approval acceleration constitute the primary cyclical drivers reshaping competitive positioning.
For Market Incumbents: Entrench cyclotron infrastructure ownership as the priority defensive lever against hospital on-site production displacement. Secure backward integration into isotope generation assets to neutralize reactor dependency risk. Anchor long-term contracts with Memorial Sloan Kettering and MD Anderson to lock priority scheduling capacity before Canadian TRIUMF expansion captures cross-border volume.
For New Entrants and Emerging Players: Rural cancer treatment centers in Texas and Florida with limited PET agent access represent the most penetrable entry point for decentralized cyclotron deployment. Canadian isotope export licensing under Health Canada parallel standards offers regulatory arbitrage opportunity. Pursue direct-to-hospital contracting bypassing group purchasing organization intermediaries to capture margin compression value.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across alpha-emitter therapeutic manufacturing suites requiring cGMP aseptic validation. The 5-10 year viability window favors platform-integrated radiopharmaceutical developers with FDA streamlined approval track records over pure-play distribution assets. Monitor CMS reimbursement coding convergence for theranostic pairs as the critical inflection signal for therapeutic isotope utilization sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Infrastructure Deployment | Hospital-installed production collapses distribution radius constraints for fluorine-18 tracers. |
| FDA 21 CFR Part 315 Submission | Streamlined approval compresses investigational new drug timelines for novel radioisotopes. |
| Direct-to-Hospital Contracting | Manufacturer bypass of group purchasing organizations enables customized half-life scheduling. |
| Theranostic Pair Development | Matched diagnostic-therapeutic isotope protocols synchronize procurement under unified clinical pathways. |
| Canadian Isotope Supply Agreement | Chalk River successor facilities offer alternative molybdenum-99 sources for U.S. distributors. |
Research Methodology
Operator-level perspectives from nuclear pharmacy directors, cyclotron facility managers, GPO contracts specialists, and FDA regulatory affairs leads anchored the qualitative base. Primary interviews with hospital procurement committees and cancer center supply chain executives combined with secondary validation from FDA 21 CFR Part 315 filings, CMS reimbursement coding databases, and Health Canada radiopharmaceutical approval records. Bottom-up radiopharmaceutical volume modeling and top-down market sizing triangulation converged on segment-level estimates.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end user category, clinical application, and imaging technology platform. CAGRs derived from installed base expansion rates, procedure volume trajectories, and average selling price evolution. Forecast inputs incorporated reactor production capacity schedules, cyclotron deployment pipelines, and theranostic protocol adoption curves.
Practitioners should monitor reactor outage frequency, FDA approval velocity, and CMS coding decisions for early signals of forecast deviation. Forecasts reflect documented assumptions regarding isotope supply continuity and reimbursement policy stability. Material shifts in North American reactor operational status or theranostic pair coding consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
Preclinical Brain Imaging Market