
 Distributed Power Generation Market | 2026-2036
Distributed Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Power Generation Market Intelligence
The division between custom-engineered, grid-support systems and standardized, off-the-shelf backup power units is shifting the competitive landscape. Siemens Energy AG focuses on large-scale, integrated solutions for industrial clients and utilities. Caterpillar Inc. leverages its extensive dealer network to supply reliable backup generators for commercial and residential applications. Schneider Electric specializes in microgrid management software and controls, integrating various distributed energy resources.
Distributed power generation refers to the production of electricity from small-scale sources located at or near the point of use. These systems typically have capacities below 10 megawatts and utilize technologies from solar panels to natural gas turbines. Their primary purpose is to provide reliable on-site power, reduce transmission losses, and support grid stability. Within the technology segment, solar and natural gas solutions lead in new deployments, while the industrial and commercial end-user categories constitute the largest revenue base.
Government policies are central to market development. The US Inflation Reduction Act provides significant tax credits for clean energy projects, while the EU Green Deal sets ambitious decarbonization targets. In China, national dual carbon goals are driving investment in renewables and efficient gas generation. Navigating the evolving interplay between grid interconnection standards, local permitting, and carbon pricing will be critical for all stakeholders.
Market Dynamics
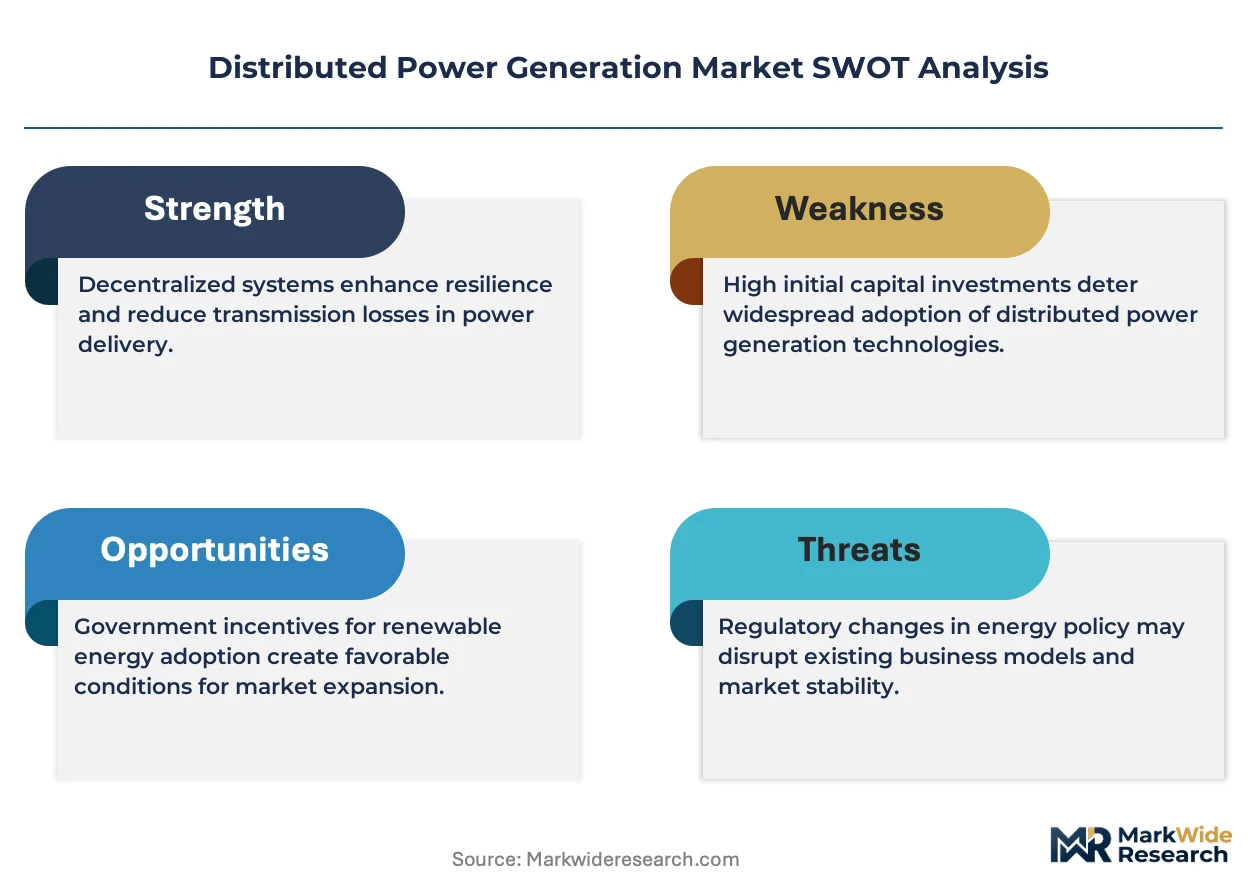
The central tension shaping the distributed power generation market is the accelerating shift from centralized grid dependency to decentralized, on-site energy resilience, driven by the increasing frequency of grid failures and volatile energy prices.
Growth Catalysts
- Supportive Government Policies:The US Inflation Reduction Act provides substantial tax credits for clean distributed energy projects, while China's dual carbon goals accelerate investment in rooftop solar and high-efficiency natural gas turbines to meet decarbonization targets.
- Commercial Sector Demand:Data centers, hospitals, and large-scale manufacturing facilities are increasingly investing in on-site generation to ensure uninterrupted power for critical operations, mitigating the financial impact of grid outages.
- Energy Storage Advancements:Continuous improvements in the cost and performance of battery energy storage systems (BESS) are making intermittent renewable sources like solar PV more reliable and dispatchable, increasing their viability for baseload and peak-shaving applications.
Market Restraints
- High Initial Capital Outlay:The significant upfront investment required for installing distributed generation systems, including solar panels, turbines, and storage, remains a major barrier for small to medium-sized enterprises and residential customers without access to financing.
- Intermittency of Renewables:The inherent variability of solar and wind power generation poses a challenge to grid stability and requires sophisticated management systems or costly energy storage solutions to ensure a consistent power supply.
- Complex Interconnection Standards:Navigating the diverse and often cumbersome technical requirements, administrative processes, and permitting for connecting distributed systems to the public utility grid can cause significant project delays and increase costs.
Strategic Opportunities
- Emerging Market Electrification:Underpenetrated regions in Southeast Asia and sub-Saharan Africa present significant opportunities for deploying off-grid and microgrid solutions to support industrial development and provide electricity access to remote communities.
- EV Charging Infrastructure:The global expansion of electric vehicle adoption creates a new demand for localized power generation and storage at charging depots to manage peak loads and reduce strain on the existing grid infrastructure.
- Digitalization and AI:Integrating artificial intelligence and machine learning into energy management platforms offers the potential to optimize the performance of entire fleets of distributed energy resources, enabling predictive analytics and participation in virtual power plant markets.
Industry Challenges
- Skilled Labor Shortages:A persistent lack of qualified engineers, technicians, and system integrators capable of designing, installing, and maintaining complex microgrid and hybrid energy systems constrains the pace of deployment, particularly for custom-engineered projects.
- Grid Integration Complexity:Integrating a high penetration of variable, bi-directional distributed energy resources with legacy grid infrastructure designed for one-way power flow presents significant technical and cybersecurity challenges for utility operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Power Generation Market |
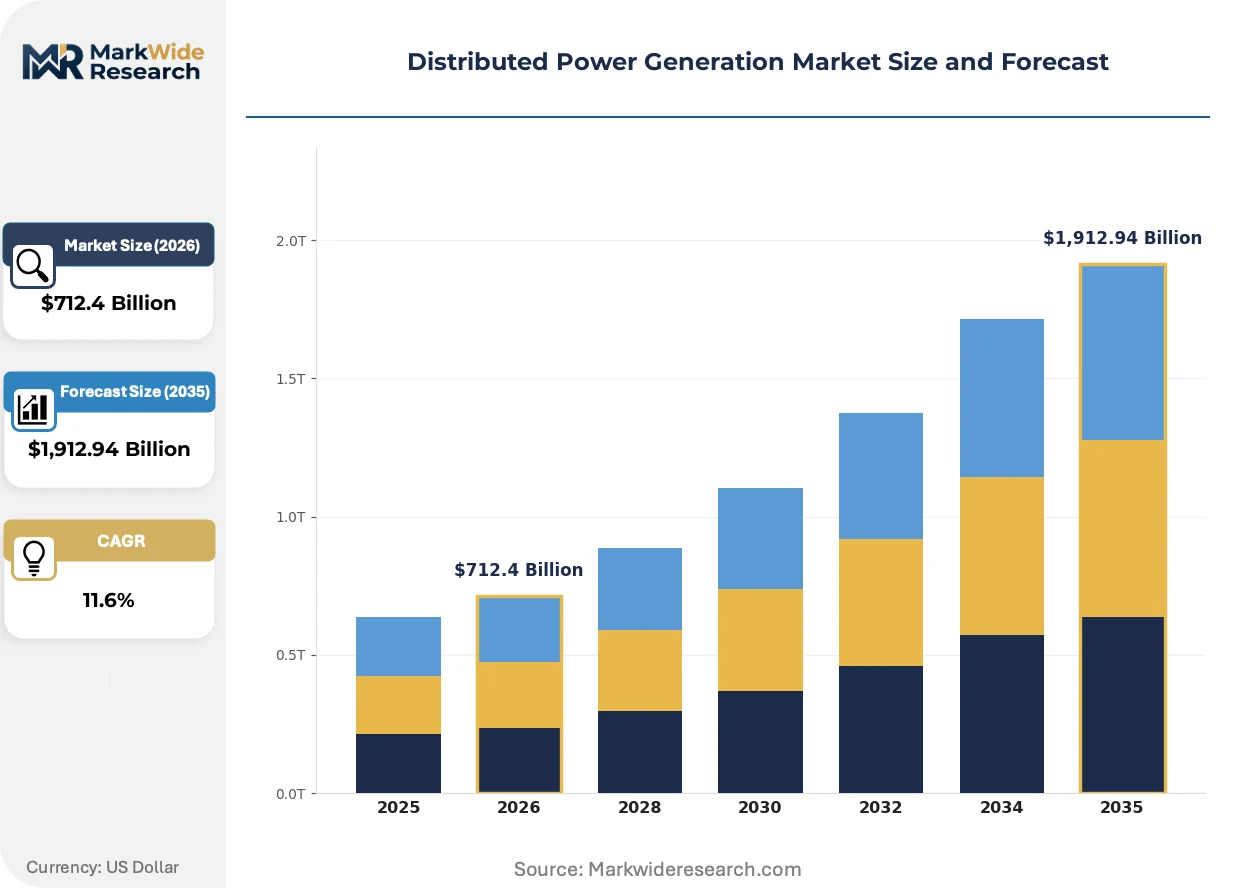
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,912.94 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Natural Gas End User: Residential, Commercial, Industrial, Institutional Deployment: On-site, Off-site, Microgrid, Remote Application: Grid Support, Energy Storage, Backup Power, Combined Heat and Power |
| Companies Covered | Caterpillar Inc., Cummins Inc., General Electric Company, Siemens Energy AG, Mitsubishi Heavy Industries, Ltd., Schneider Electric, Bloom Energy, ABB Ltd., Wärtsilä Oyj Abp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Power Generation Market Strategic Shifts & Innovations
A fundamental reevaluation of energy security is driving innovation. The market is shifting from deploying simple backup generators to creating intelligent, grid-interactive energy ecosystems that can optimize cost, enhance reliability, and participate in broader energy markets.
Digital twin technology provides a virtual replica of physical distributed energy resources and their operating environment. Utilities and industrial campus operators are the primary adopters, using these models to test scenarios and predict system behavior without physical risk. This technology is automating predictive maintenance schedules and optimizing real-time energy dispatch decisions across complex, multi-asset microgrids.
The European Union's 'Clean Energy for all Europeans' package establishes a common framework for prosumers and renewable energy communities. This policy mandates that transmission and distribution system operators provide non-discriminatory grid access and fair remuneration for electricity exports from distributed sources. The solar PV and small-scale combined heat and power (CHP) segments in Germany and Italy are most affected, spurring new business models.
A transition toward Energy-as-a-Service (EaaS) models is altering procurement patterns for commercial and industrial customers. This structure bypasses traditional capital equipment sales by having a third-party provider own, operate, and maintain the on-site generation assets in exchange for a long-term service fee. This trend is most visible in North America for multi-site retail and logistics companies seeking to offload asset management risk.
Distributed Power Generation Market Segmentation
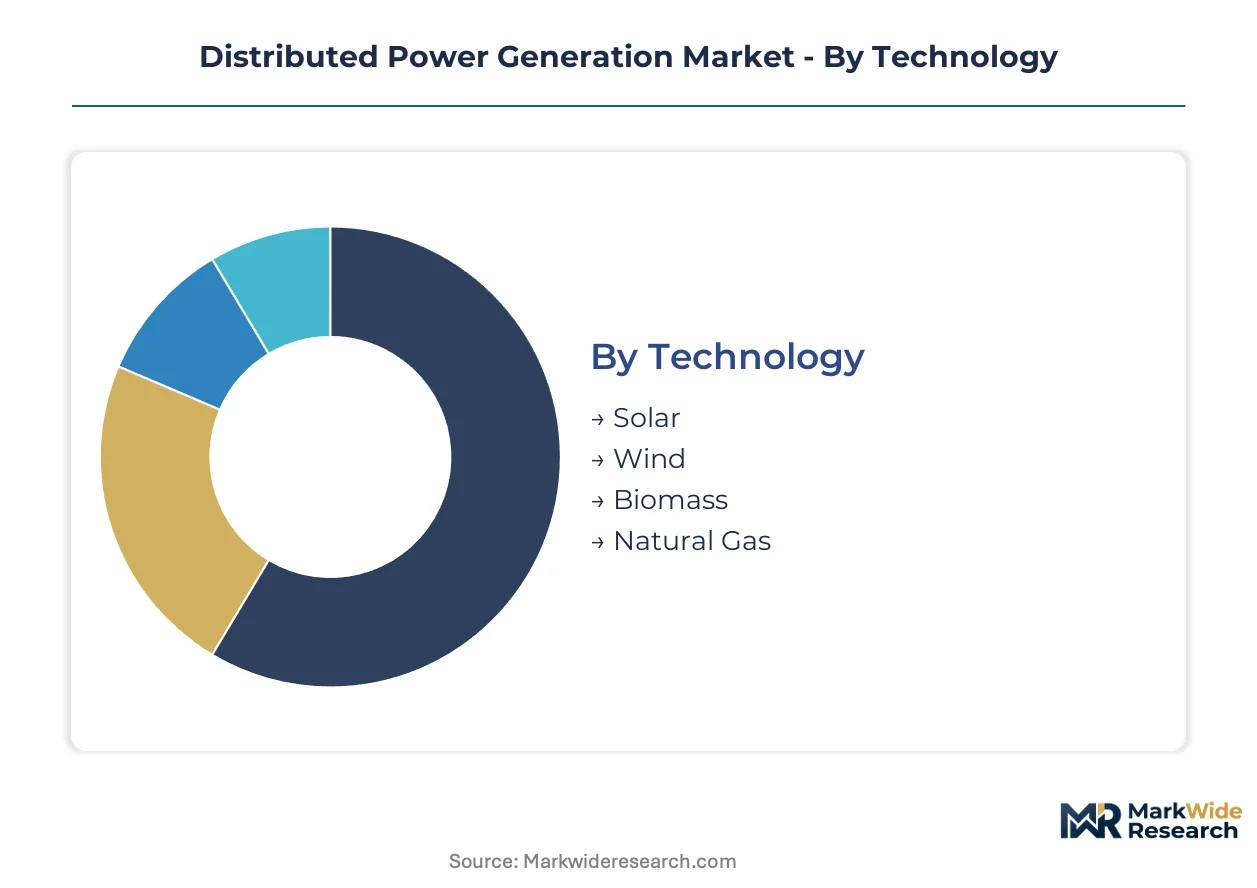
The Distributed Power Generation Market segmentation highlights the diverse technologies, end-user applications, and deployment strategies driving energy independence. Understanding these distinct segments allows stakeholders to tailor solutions that address specific operational needs and regulatory environments across various regions.
Technology:
The technological foundation of distributed power generation defines its operational characteristics and resource utilization.
- Solar:This segment includes photovoltaic (PV) panels that convert sunlight directly into electricity, suitable for rooftop and ground-mounted installations. Demand concentrates in the commercial and residential sectors, driven by tax credits from the US Inflation Reduction Act and declining equipment costs.
- Natural Gas:Comprising natural gas turbines and reciprocating engines, these systems offer reliable, on-demand power generation with high efficiency. Demand is strong in the industrial sector and for data centers, driven by the need for continuous power and grid stability.
- Wind:Small-scale wind turbines capture kinetic energy from wind to generate electricity, often used in hybrid systems or remote applications. This technology provides a renewable energy source for locations with consistent wind resources.
- Biomass:Utilizing organic matter such as agricultural waste or dedicated energy crops, biomass systems generate electricity through combustion or gasification processes. Biomass offers a dispatchable renewable power source, particularly in regions with abundant organic waste streams.
Natural Gas leads on scale; Solar leads on momentum.
End User:
Customer type determines the scale and specific requirements for distributed power solutions.
- Commercial:This category encompasses businesses, retail establishments, and office buildings requiring reliable power for daily operations. Data centers and multi-site retail companies are significant consumers, seeking uninterrupted power to mitigate the financial impact of grid outages.
- Industrial:This segment includes manufacturing plants, processing facilities, and heavy industries with high energy demands and critical operational continuity needs. Industrial users prioritize energy cost management and operational resilience, especially in regions like China with national dual carbon goals.
- Residential:Homeowners and small communities constitute this segment, typically deploying rooftop solar or small-scale backup generators. Residential demand is influenced by energy bill savings and protection against local grid failures.
- Institutional:Hospitals, universities, government facilities, and other public service entities fall into this category, requiring highly reliable power for essential services. These institutions often invest in microgrids to ensure continuous operation during emergencies.
Commercial users prioritize uptime, while industrial customers focus on energy cost efficiency.
Deployment:
Deployment models reflect the physical location and operational scope of distributed generation assets.
- On-site:Power generation systems are located directly at the point of consumption, such as a factory or commercial building. This model significantly reduces transmission losses and provides immediate power resilience for critical operations.
- Microgrid:A localized energy grid that can disconnect from the traditional grid and operate autonomously, integrating various distributed energy resources. Campuses and remote communities are increasingly adopting microgrids to enhance energy independence and resilience.
- Off-site:Generation assets are located away from the primary consumption point but still serve a defined set of users or a local distribution network. This allows for optimized siting of larger-scale distributed resources.
- Remote:Distributed power solutions specifically designed for isolated areas lacking access to the main utility grid. These deployments are crucial for electrification in underpenetrated regions of Southeast Asia and sub-Saharan Africa.
On-site deployment represents a mature segment, while Microgrid solutions exhibit expanding most quickly.
Application:
The intended application dictates the specific design and operational priorities of distributed power systems.
- Backup Power:Systems designed to provide electricity during grid outages, ensuring continuous operation for critical loads. Data centers and hospitals rely heavily on backup power to maintain essential services and prevent costly downtime.
- Grid Support:Distributed generation assets that provide ancillary services to the main grid, such as voltage regulation, frequency response, and peak shaving. These applications enhance grid stability and facilitate higher penetration of intermittent renewable energy sources.
- Energy Storage:This application involves storing excess generated electricity, primarily from intermittent renewables like solar, for later dispatch. Battery energy storage systems (BESS) improve reliability and enable better integration of renewable sources into the grid.
- Combined Heat and Power:CHP systems simultaneously produce electricity and useful thermal energy from a single fuel source. This application offers high overall energy efficiency, particularly in industrial and institutional settings requiring both power and heat.
Backup Power solutions drive immediate operational continuity, while Grid Support applications enhance overall system resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled engineering workforce in the United States anchors innovation across the distributed power generation landscape. This talent pool drives advancements in microgrid design and energy storage integration. Market expansion accelerates as grid resilience becomes a critical national priority.
United States
Commercial sector demand for reliable on-site power drives significant distributed generation deployments. The US Inflation Reduction Act provides substantial tax credits for clean distributed energy projects. Data centers in Virginia and Texas are rapidly expanding their on-site generation capabilities to ensure continuous operation.
Germany
Decentralized energy production is expanding, driven by ambitious decarbonization targets and prosumer models. The EU Green Deal mandates non-discriminatory grid access for distributed sources. Renewable energy communities in Bavaria are integrating solar PV and small-scale CHP systems into local grids.
India
Industrial growth and grid resilience initiatives are fueling demand for distributed power solutions. India's PLI scheme supports domestic manufacturing of advanced energy technologies. Manufacturing hubs in Gujarat are investing in captive power plants to ensure uninterrupted production.
China
National dual carbon goals accelerate investment in efficient gas generation and rooftop solar. The MIIT promotes localized renewable energy deployment across industrial parks. Industrial zones in the Yangtze River Delta are adopting distributed natural gas turbines for energy efficiency.
Japan
Energy security concerns and disaster preparedness drive investment in resilient on-site power systems. METI policies encourage the deployment of fuel cells and combined heat and power systems. Industrial complexes in the Kansai region are implementing microgrids to enhance operational continuity.
Distributed Power Generation Market Key Industry Players
Top-tier vendors anchor the integrated solutions segment, while specialized providers address niche applications and regional demands. The market structure exhibits a tiered consolidation, with established industrial giants alongside agile technology developers and software innovators. Strategic archetypes include large-scale system integrators, reliable backup power providers, and advanced microgrid management specialists. Companies are pursuing portfolio diversification, capacity expansion, and strategic partnerships to expand their market reach and technological capabilities.
Specialists in integrated solutions include Siemens Energy AG, which anchors the large-scale projects segment for industrial and utility clients, emphasizing comprehensive energy systems. Caterpillar Inc. exemplifies a strong presence in reliable backup power generation, leveraging its extensive global dealer network to supply commercial and residential applications with robust units. Schneider Electric occupies a position as a leader in microgrid management software and controls, integrating diverse distributed energy resources for optimized performance and enhanced grid stability across various deployments.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| General Electric Company |
| Siemens Energy AG |
| Mitsubishi Heavy Industries, Ltd. |
| Schneider Electric |
| Bloom Energy |
| ABB Ltd. |
| Wärtsilä Oyj Abp |
| Others |
Cost & Logistics Intelligence
The shift towards intelligent, grid-interactive energy ecosystems simultaneously reshapes cost economics and concentrates supply in specialized software and integration services.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing in distributed power generation. Project-based pricing dominates for large-scale industrial systems, while Energy-as-a-Service models utilize subscription-tiered structures for commercial clients. Price differentiation stems from system complexity and the depth of after-sales service contracts. Cost compression in standardized solar PV components exerts downward pressure on system prices. Residential customers exhibit the highest price sensitivity, whereas institutional buyers prioritize reliability over upfront cost.
Supply Chain Analysis
Skilled labor availability in Germany, Japan, and the United States anchors advanced manufacturing for microgrid components. Geographic supply concentration for solar PV components centers in China and parts of Southeast Asia, while gas turbines originate largely from Germany and Japan. Raw material dependencies include rare earth elements for battery energy storage systems and specialized electronics for control units. Logistics chokepoint vulnerability represents a structural risk for global component flows. Downstream distribution runs through direct sales channels for large industrial projects and extensive dealer networks for commercial and residential applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with sustained growth driven by the increasing frequency of grid failures and volatile energy prices.
For Market Incumbents:Deepen vertical integration into battery energy storage systems to mitigate supply chain risks for critical components. Acquire specialized microgrid software firms to enhance control capabilities, countering the threat from agile technology developers. Expand service contracts and maintenance offerings, leveraging existing customer relationships. Focus R&D on advanced grid management and AI-driven optimization to maintain a competitive edge.
For New Entrants and Emerging Players:Digital twin technology offers a potent technology-first wedge for new entrants targeting industrial campus optimization. White-space targets include remote microgrid deployments in underpenetrated regions of Southeast Asia and localized power generation for EV charging infrastructure. The commercial facilities segment, particularly those seeking Energy-as-a-Service models, represents a highly penetrable market. Partner with local utilities for grid support services to establish early market presence.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional specialists offering off-grid and remote electrification solutions in emerging markets. The market presents strong long-term viability, driven by global decarbonization and resilience imperatives. Acquisition targets should be mid-cap providers with established installation bases and robust service networks. A key signal to watch is rapid policy shifts towards carbon pricing in new geographies, indicating accelerated investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for BESS | This ensures a stable supply of critical energy storage components for integrated solutions. |
| Technology Licensing Agreements | These accelerate market penetration for innovative distributed generation technologies in new regions. |
| Vertical Integration into Microgrid Controls | This provides end-to-end control over system performance and enhances solution differentiation. |
| Strategic Partnerships with Utilities | These facilitate grid interconnection and enable participation in broader energy markets. |
| Green Certification Programs | These validate sustainability claims, attracting environmentally conscious commercial and institutional clients. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the market analysis. Stakeholders included utility planning officers, EPC contractors, industrial plant managers, and energy management software developers. Secondary sources such as EIA data, EU Green Deal reports, national energy agency publications, and company financial filings provided extensive validation. Bottom-up and top-down triangulation validated all market figures.
Rate-of-change decomposition framed the quantitative model, projecting market evolution across the analysis window. Segmentation dimensions modeled included technology, end-user, deployment, application, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and future policy impacts. Forecast inputs included clean energy investment trends and grid modernization expenditure.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical stability and technological breakthroughs. Forecasts reflect assumptions regarding regulatory support and raw material costs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Canada Power EPC Market
Power Generation
Peaking Power Plant Market
Power Generation
Subsea Power Grid System Market
Power Generation
Microturbine Market
Power Generation
Global Power Generation Market
Power Generation
Indonesia Power Market
Power Generation
India Gas Generator Market
Power Generation
Global Gas Turbines Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
LAMEA Microturbine Market
Power Generation
Global Power to Gas Market
Power Generation
Hydrogenerators Market