
 Global Shale Gas Market | 2026-2036
Global Shale Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shale Gas Market Foresight
Midstream processing revenue is reconfiguring margin pools away from pure commodity extraction toward integrated gas-to-liquids value chains. ExxonMobil leverages its Permian infrastructure network to capture downstream spreads on wet gas fractions. Shell PLC anchors its North American portfolio through Appalachian Basin dry gas positions with pipeline offtake agreements. EQT Corporation dominates Appalachian pure-play production with scale advantages in horizontal laterals.
Shale gas comprises thermogenic natural gas trapped within low-permeability organic-rich sedimentary formations, typically requiring hydraulic fracturing and horizontal drilling to achieve commercial flow rates of one to thirty million cubic feet per day. Its primary purpose is to serve as a dispatchable feedstock for power generation, petrochemical manufacturing, and residential heating applications. Unconventional gas extraction through multi-stage fracturing now commands the largest share of incremental supply growth, while wet gas applications in chemical feedstock represent the fastest-expanding demand segment. Power generation from dry gas retains mature volume leadership but faces margin compression as renewable capacity expands.
The EPA regulates methane emissions under the Clean Air Act New Source Performance Standards, compelling operators to deploy leak detection and repair systems across well pads and compressor stations. The EU's Methane Regulation imposes import standards that condition market access for non-European suppliers on certified emissions intensity. China's National Energy Administration promotes shale development through production subsidies and pipeline tariff reform. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate capital allocation and certification investments.
Market Dynamics
Coal-to-gas switching at power generation utilities is compressing legacy fuel demand while hydraulic fracturing efficiency gains expand supply elasticity beyond conventional reservoir constraints.
Growth Catalysts
- EPA New Source Performance Standards:Methane emission limits under the Clean Air Act accelerate leak detection system deployment across well pads, creating compliance-driven equipment demand.
- Wet gas fractionation:Petrochemical feedstock applications for ethane and propane expand cracking capacity utilization at Gulf Coast facilities.
- Permian Basin infrastructure density:Pipeline connectivity and water disposal networks sustain drilling economics through shared service cost amortization.
Market Restraints
- Proppant cost volatility:Northern White Sand supply concentration in Wisconsin and Minnesota exposes fracturing operations to rail logistics bottlenecks.
- Water sourcing constraints:Freshwater withdrawal permits face tightening limits in drought-prone Texas and New Mexico jurisdictions.
- EU Methane Regulation import standards:Certified emissions intensity thresholds threaten market access for uncertified suppliers.
Strategic Opportunities
- Argentina Vaca Muerta formation:Underdeveloped shale resources await pipeline export infrastructure to liquefaction terminals.
- CCUS integration:Carbon capture retrofitting at gas processing plants qualifies for IRA tax credit monetization.
- Digital twin adoption:Real-time reservoir modeling converges with automated frac fleet coordination to optimize stage sequencing.
Industry Challenges
- Directional drilling specialist shortage:Geosteering expertise gaps constrain lateral length optimization in emerging basins.
- Fugitive emissions certification timelines:Third-party verification protocols for EU market access require 18-24 month documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shale Gas Market |
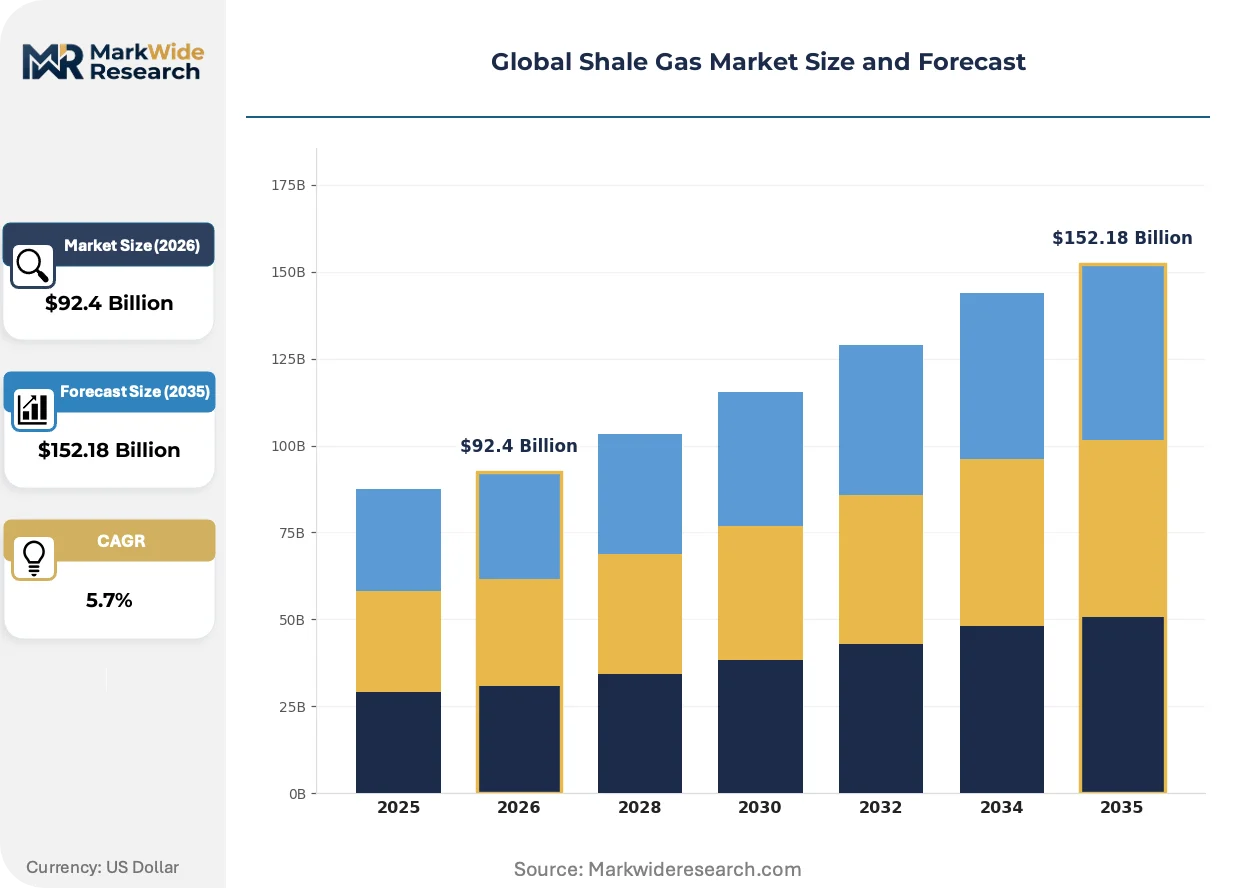
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $152.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Conventional Gas, Unconventional Gas, Dry Gas, Wet Gas, Associated Gas, Non-Associated Gas Application: Power Generation, Chemical Feedstock, Residential Heating, Industrial Fuel, Transportation Fuel, Fertilizer Production Extraction Technology: Hydraulic Fracturing, Horizontal Drilling, Acidizing, Enhanced Recovery, Gas Injection, Multi-Stage Fracturing End User: Independent Producers, Integrated Energy Companies, Energy Traders, Utility Providers, Refiners, Petrochemical Manufacturers |
| Companies Covered | ExxonMobil, Chevron Corporation, Shell PLC, ConocoPhillips, EQT Corporation, Antero Resources Corporation, Chesapeake Energy Corporation, Occidental Petroleum Corporation, Pioneer Natural Resources Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shale Gas Market Shifts & Advancements
Electrification of frac fleets and methane monitoring automation are compressing operational emissions profiles while digital integration reconfigures field coordination protocols.
Dual-fuel turbine technology is hybridizing diesel and natural gas combustion at hydraulic fracturing sites, cutting particulate emissions while maintaining horsepower density. Pressure pumping contractors in the Permian and Appalachian basins are retrofitting legacy diesel units with field gas substitution capability. This hybridization is compressing fuel logistics costs and reducing dependency on remote diesel supply chains.
The EU Methane Regulation imposes import certification requirements conditioning market access on verified emissions intensity data across the supply chain. European buyers must demonstrate contractual assurance of leak detection and repair protocols for non-European suppliers. LNG offtake agreements now incorporate methane performance clauses with penalty mechanisms for uncertified cargoes.
Integrated service contracts now bundle directional drilling, completions, and artificial lift under single-provider accountability structures. Exploration and production companies are consolidating vendor relationships to reduce interface risk and accelerate spud-to-sales timelines. This procurement consolidation is most visible among Permian Basin operators seeking to compress drilling cycle times below 15 days per well.
Global Shale Gas Market Segmentation
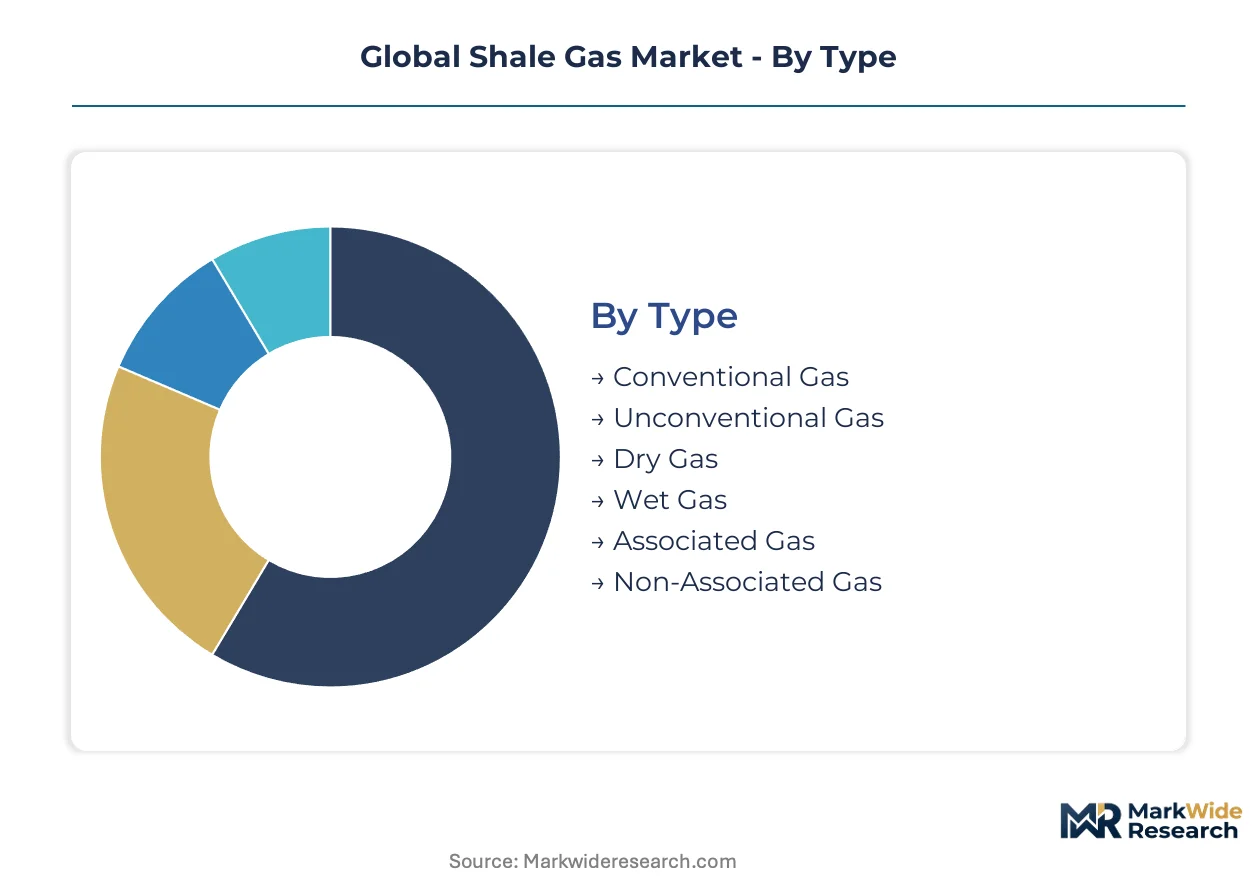
Segmentation in shale gas markets determines capital allocation cycles and infrastructure lock-in periods. Reservoir type and extraction method dictate payback horizons, while end-user concentration shapes offtake contract structures and price discovery mechanisms.
Type:
Cycle times vary dramatically across reservoir categories, with conventional legacy assets turning over slowly while unconventional drilling programs refresh supply bases annually.
- Unconventional Gas:Thermogenic methane trapped in low-permeability shale matrices requires artificial stimulation to achieve commercial flow rates. Horizontal laterals in the Permian Basin and Appalachian Basin sustain production growth through continuous drilling programs that compress spud-to-sales intervals below three weeks.
- Wet Gas:Reservoirs containing significant natural gas liquids fractions including ethane, propane, and butane yield higher per-mcf economics through fractionation value capture. Gulf Coast petrochemical complexes concentrate demand for these feedstocks, though NGL price volatility introduces margin uncertainty against dry gas benchmarks.
- Conventional Gas:Traditional sandstone and carbonate reservoirs with natural permeability require minimal stimulation. These mature assets face terminal decline curves without infill drilling.
- Dry Gas:Methane-dominant production streams bypass liquids processing infrastructure. Pipeline specifications in the northeastern United States favor this composition for direct residential and power generation delivery.
- Associated Gas:Natural gas produced as a byproduct of crude oil extraction from liquid-rich shale formations. Flaring constraints in Texas and North Dakota force operators to prioritize gathering infrastructure deployment.
- Non-Associated Gas:Gas-prone reservoirs developed without oil co-production. These targets dominate Appalachian Basin drilling programs where Marcellus and Utica formations yield minimal condensate.
Dry gas dominates installed base. Wet gas is where expansion concentrates.
Application:
End-use applications stratify by margin stability and contract duration, with industrial offtake offering price predictability while transportation fuel remains speculative.
- Power Generation:Combined-cycle gas turbines dispatch shale gas into baseload and peaking electricity supply. EPA emissions rules accelerate coal-to-gas switching at utilities from Texas to Ohio, creating structural demand growth independent of commodity price cycles.
- Chemical Feedstock:Ethane cracking at Gulf Coast steam crackers converts wet gas fractions into ethylene and derivative petrochemicals. Dow Chemical and ExxonMobil have announced capacity expansions tied to Permian Basin supply commitments.
- Residential Heating:Local distribution companies in the northeastern United States contract for winter peak supply through interstate pipeline capacity reservations. Weather-driven demand volatility requires storage injection programs during summer months.
- Industrial Fuel:Cement, steel, and glass manufacturers consume gas for process heat. These offtakers prioritize supply security through long-term purchase agreements with minimum volume guarantees.
- Transportation Fuel:Compressed natural gas and liquefied natural gas compete with diesel in heavy-duty trucking and marine applications. Infrastructure gaps at refueling stations constrain adoption outside California and New York corridor routes.
- Fertilizer Production:Ammonia synthesis requires hydrogen derived from methane steam reforming. Louisiana and Iowa facilities source gas through pipeline interconnects with midcontinent supply basins.
Power generation commands volume leadership. Chemical feedstock is climbing the fastest.
Extraction Technology:
Technology selection determines capital intensity and recovery factors, with multi-stage fracturing enabling tier-one economics while acidizing addresses marginal well rejuvenation.
- Multi-Stage Fracturing:Sequential isolation and stimulation of horizontal wellbore segments maximizes reservoir contact surface area. Permian Basin operators now routinely execute 50-plus stage completions with engineered diversion systems that improve cluster efficiency.
- Horizontal Drilling:Directional wellbores extending one to three miles laterally through target formations multiply recoverable reserves per surface location. Geosteering technologies using gamma ray and resistivity logging while drilling keep laterals within productive zones.
- Hydraulic Fracturing:High-pressure fluid injection creates conductive fracture networks in tight rock. Water sourcing constraints in New Mexico and Texas jurisdictions force recycling program investments.
- Acidizing:Matrix acid stimulation dissolves carbonate damage near wellbore without fracturing the formation. This technique addresses skin damage in existing wells at lower cost than refracturing.
- Enhanced Recovery:Huff-and-puff gas injection cycles improve liquid recovery in shale oil wells. Pilot programs in the Eagle Ford formation test methane and carbon dioxide injection efficacy.
- Gas Injection:Produced gas reinjection maintains reservoir pressure in condensate-rich systems. This technique sees limited application in dry gas windows where pressure depletion drive is preferred.
Horizontal drilling dominates installed base. Multi-stage fracturing is gaining share fastest.
End User:
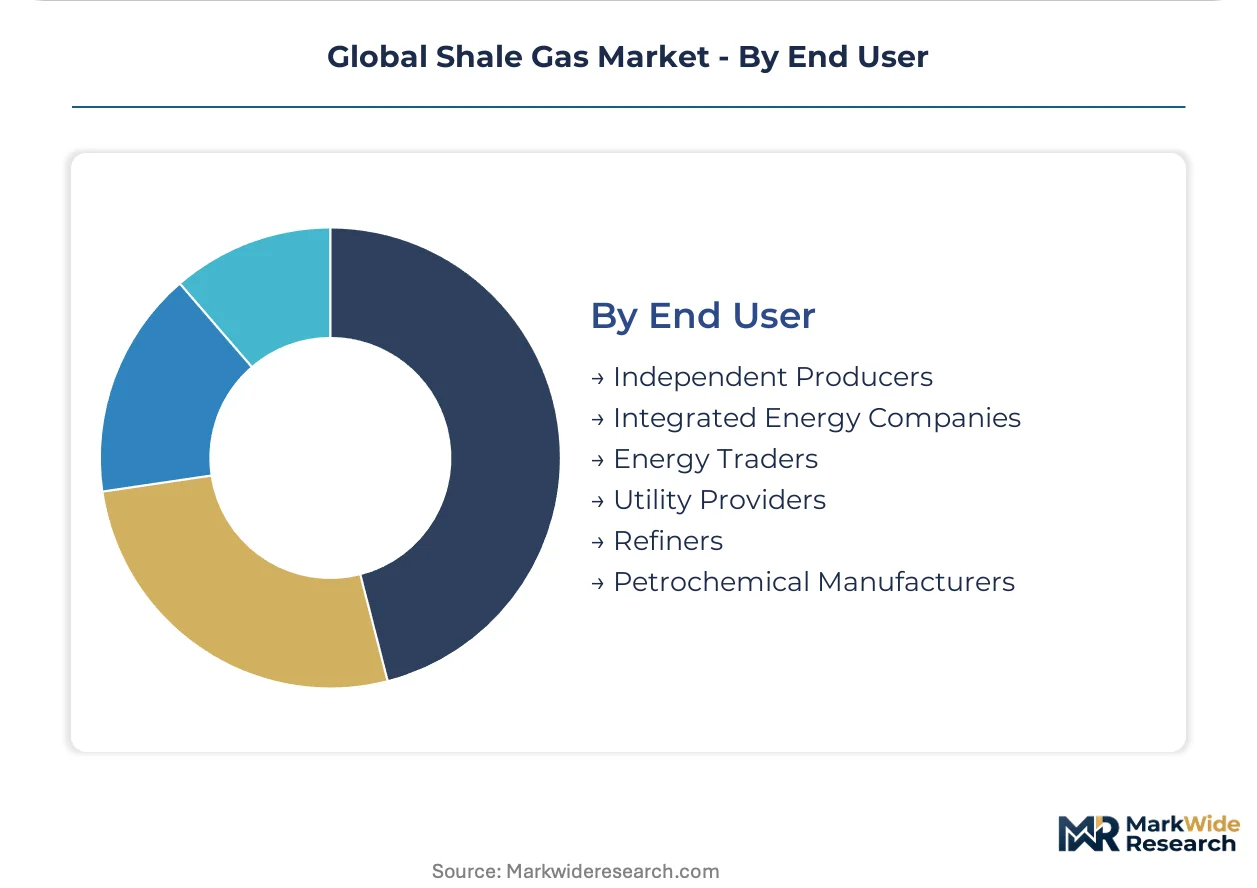
Customer type segmentation reveals procurement sophistication gradients, with integrated majors self-executing drilling programs while independents rely on service company bundling.
- Integrated Energy Companies:Vertically structured operators control upstream production through midstream gathering to downstream processing and marketing. ExxonMobil and Shell internalize value chain margins across Permian and Appalachian positions.
- Independent Producers:Pure-play exploration and production companies focus exclusively on reservoir development and hydrocarbon extraction. EQT Corporation concentrates Appalachian dry gas output through scaled horizontal programs.
- Utility Providers:Regulated electric and gas distribution utilities contract for long-term supply to serve ratepayer demand. These offtakers prioritize price stability through index-linked purchase agreements with floor and ceiling provisions.
- Petrochemical Manufacturers:Ethylene crackers and methanol plants require dedicated feedstock supply with composition specifications for NGL content and sulfur limits. Gulf Coast complexes negotiate pipeline direct connections to processing plants.
- Energy Traders:Merchant intermediaries arbitrage regional price differentials and seasonal spreads. These participants provide liquidity at hubs including Henry Hub and Dominion South.
- Refiners:Complex fuel manufacturers consume gas for hydrogen production and process heat. These industrial offtakers integrate supply with crude oil procurement logistics.
Integrated energy companies dominate installed base. Independent producers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States deploys shale gas primarily for power generation and petrochemical feedstock. China channels production toward industrial fuel substitution. Argentina and Saudi Arabia target export liquefaction capacity.
United States
The Permian Basin and Appalachian Basin anchor domestic supply growth. EPA methane regulations under the Clean Air Act compel leak detection investments across Texas and Pennsylvania well pads. Houston-Galveston petrochemical complexes consume wet gas fractions for ethylene cracking expansion.
China
Sichuan Basin development targets industrial coal-to-gas switching in manufacturing corridors. The National Energy Administration subsidizes production targets through pipeline tariff reform. Chongqing municipality concentrates drilling service contracts for state-backed operators.
Argentina
Vaca Muerta formation resources await pipeline connectivity to Atlantic liquefaction terminals. The national energy secretary promotes foreign investment through fiscal stability contracts. Neuquén province hosts international joint ventures for unconventional pilot programs.
Saudi Arabia
Jafurah Basin shale development supports domestic hydrogen and ammonia synthesis feedstock. The Ministry of Energy prioritizes gas-to-liquids integration over crude oil expansion. Eastern Province industrial cities anchor methanol and fertilizer manufacturing clusters.
Canada
Montney and Duvernay formations supply Alberta petrochemical and oil sands upgrading demand. Environment and Climate Change Canada methane regulations mandate venting reductions across British Columbia drilling sites. Calgary-headquartered operators consolidate acreage positions for export pipeline access.
Global Shale Gas Market Competitive Landscape
Capability concentration sits with integrated majors commanding full value chain control; scale advantage sits with independent pure-plays optimizing horizontal lateral economics. The structure tiers between vertically integrated energy companies and focused exploration specialists. Two archetypes dominate: infrastructure-heavy integrators leveraging midstream networks, and drilling-scale independents compressing spud-to-sales cycles. Competitive moves center on Permian Basin acreage consolidation and Appalachian pipeline offtake contracting.
Within the integrated tier, ExxonMobil occupies a position exemplifying infrastructure-network leverage, while Shell PLC represents European-headquartered portfolio anchoring through North American dry gas positions. Among pure-play independents, EQT Corporation exemplifies Appalachian scale concentration in horizontal programs. These three entities represent distinct strategic postures: captive midstream integration, transatlantic regulatory arbitrage, and regional drilling density optimization.
| Leading Market Players |
|---|
| ExxonMobil |
| Chevron Corporation |
| Shell PLC |
| ConocoPhillips |
| EQT Corporation |
| Antero Resources Corporation |
| Chesapeake Energy Corporation |
| Occidental Petroleum Corporation |
| Pioneer Natural Resources Company |
| Others |
Supply & Pricing Matrix
Proppant cost volatility from Northern White Sand supply concentration in Wisconsin and Minnesota determines both Henry Hub basis differentials and midstream contracting structures across the Permian and Appalachian basins. Water sourcing constraints in drought-prone Texas jurisdictions compress drilling economics while amplifying price spreads between wet gas and dry gas benchmarks.
Pricing Analysis
Long-term offtake agreements with floor-and-ceiling provisions dominate utility procurement, insulating power generators from Henry Hub volatility while locking in baseload supply commitments. Spot market liquidity concentrates at the Henry Hub and Dominion South trading points, where energy traders arbitrage regional differentials and seasonal storage spreads. Price differentiation rests on methane certification intensity under EU import standards, with certified low-emissions cargoes commanding premium spreads over uncertified supply. Pricing pressure stems from renewable capacity expansion in Texas and California grid zones, eroding gas-fired capacity factors and compressing spark spreads for marginal generators.
Supply Chain Analysis
Export control regimes on directional drilling telemetry and geosteering software limit technology transfer to emerging shale basins in Argentina and Saudi Arabia. Supply concentration sits with the United States, Canada, and China as the primary equipment manufacturing and reservoir services hubs. Raw material dependencies include high-grade proppant from Wisconsin mines, specialized steel for drill pipe from domestic mills, and rare-earth magnets for downhole motors. Single-source vulnerability runs through Northern White Sand rail corridors, where logistics bottlenecks constrain fracturing fleet deployment. Distribution runs through integrated midstream networks that gather, process, and fractionate production at Gulf Coast and Northeast market hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to EPA methane compliance deadlines accelerating capital deployment into leak detection and repair infrastructure.
For Market Incumbents: Build regulatory certification moats through third-party methane intensity verification protocols that satisfy EU Methane Regulation import thresholds. Consolidate Permian Basin acreage positions to amortize water recycling and pipeline gathering costs across extended lateral programs. Defensive moves center on securing pipeline offtake agreements with Gulf Coast petrochemical complexes before independent competitors capture fractionation capacity. Threat vectors include renewable capacity expansion eroding gas-fired power demand and emerging Argentine supply competing for Asian LNG market share. For New Entrants and Emerging Players: Mid-scale wet gas positions in the Appalachian Basin with direct pipeline interconnects to Gulf Coast ethylene crackers represent the most penetrable entry point for capital-constrained operators. Argentina's Vaca Muerta formation awaits pipeline export infrastructure, offering greenfield development opportunities for international joint ventures with Neuquén provincial authorities. Go-to-market positioning should emphasize carbon capture integration at gas processing plants to qualify for IRA tax credit monetization and differentiate supply for European offtake. For Investors and Strategic Acquirers: EPA New Source Performance Standards enforcement timelines reshape the acquisition landscape toward operators with deployed leak detection systems and certified emissions profiles. Long-term viability favors integrated positions spanning upstream production through midstream gathering infrastructure, capturing margin pools that pure-play independents cannot access. Acquisition targets include Appalachian pure-plays with scaled horizontal programs and existing pipeline offtake agreements. The signal to watch is EU import certification completion rates, which will bifurcate market access between certified and uncertified supply sources.| Strategic Initiative | Industry Significance |
|---|---|
| Methane Certification Program | EU Methane Regulation compliance unlocks premium European LNG offtake contracts with penalty-protected pricing. |
| Permian Infrastructure Consolidation | Shared water disposal and pipeline networks compress spud-to-sales cycles below 15 days per well. |
| CCUS Retrofit Integration | Carbon capture at gas processing plants qualifies for IRA tax credits while reducing emissions intensity benchmarks. |
| Digital Twin Deployment | Real-time reservoir modeling converges with automated frac fleet coordination to optimize stage sequencing efficiency. |
| Argentina Export Pipeline Development | Vaca Muerta connectivity to Atlantic liquefaction terminals positions supply for Asian and European demand growth. |
Research Methodology
A spread of perspectives from upstream operations executives, midstream infrastructure planners, utility fuel procurement officers, and petrochemical feedstock managers converged on the working assumptions driving supply elasticity and demand substitution models. Primary field engagement combined structured interviews with directional drilling contractors and completions specialists with secondary validation against EIA production data, FERC pipeline filings, EPA emissions inventories, and IEA natural gas market reports. Bottom-up well economics modeling triangulated against top-down regional demand projections to anchor volume and value forecasts.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with segmentation modeling across reservoir type, gas composition, extraction technology, end-use application, and customer archetype. CAGRs derived from regression analysis of historical production growth rates against regulatory compliance cost curves and infrastructure deployment timelines. Industry-specific forecast inputs included EPA methane rule implementation schedules, EU import certification adoption curves, and Permian Basin drilling permit issuance patterns.
Practitioners should monitor EPA enforcement intensity, EU certification completion rates, and renewable capacity addition announcements for early signals of demand trajectory revision. Forecasts reflect assumptions regarding regulatory stability and infrastructure completion timelines. Material shifts in federal methane policy stringency or Atlantic LNG export capacity commissioning would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Middle-East and Africa Pigging Services Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Slickline Services Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market