
 Australia Thermal Power Market | 2026-2036
Australia Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Thermal Power Market Outlook
Queensland's gas turbine fleet is expanding as coal retirement timelines compress. AGL Energy Limited leverages its integrated generation and retail platform to sustain margin capture across volatile wholesale prices. Origin Energy Ltd anchors its portfolio with large-scale gas peaking assets that compete for capacity payments in the National Electricity Market. Stanwell Corporation Limited operates state-backed baseload coal units while navigating transition pathways toward lower-emission dispatch.
Australia thermal power encompasses electricity generation facilities that combust fossil fuels or biomass to produce steam-driven turbine output, typically operating at thermal efficiencies between 35% and 48% depending on cycle configuration and fuel quality. These plants serve as the backbone of grid reliability, providing synchronous inertia and frequency control that variable renewable sources cannot replicate. Coal technology dominates installed capacity but faces structural decline as natural gas units capture growing share in intermediate and peaking roles. Base load generation applications retain volume leadership while distributed generation and grid-scale battery hybridization represent emerging margin pools for equipment suppliers and project developers.
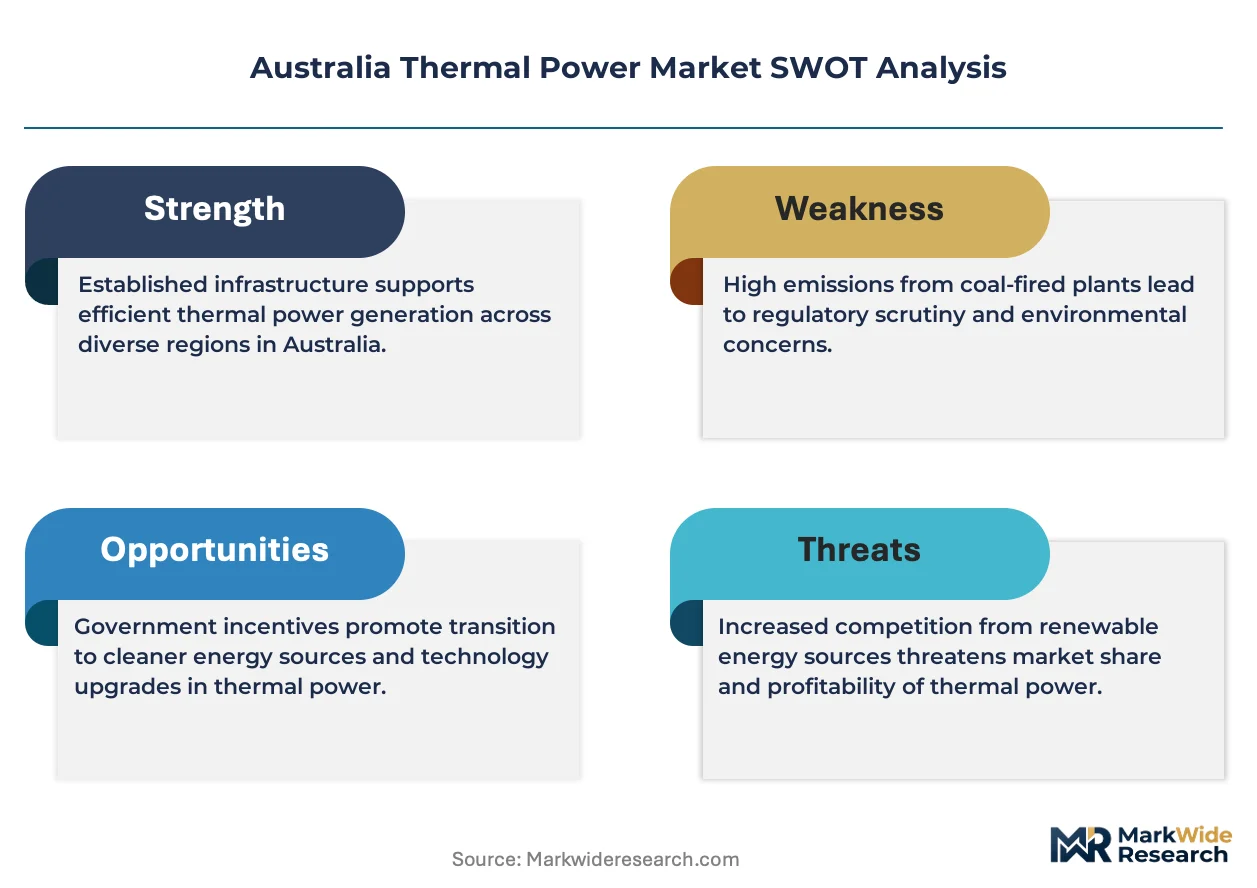
The Australian Energy Market Operator enforces reliability standards that preserve thermal plant dispatch rights during supply shortfalls, while state environmental regulators impose emissions intensity benchmarks that accelerate efficiency retrofits. The Clean Energy Regulator's Safeguard Mechanism creates compliance-driven demand for gas turbine upgrades and co-firing modifications across covered facilities. Stakeholders must weigh residual asset valuations against carbon border adjustment risks and the accelerating build-out of transmission-linked renewable zones.
Market Dynamics
The National Electricity Market reliability standards and state renewable integration targets are compressing dispatch windows for baseload thermal units while elevating gas peaking assets to grid-critical status.
Growth Catalysts
- Industrial Mining Demand:Western Australia and Queensland mining corridors sustain 24/7 baseload requirements that renewable sources cannot yet fulfill, preserving coal and gas dispatch priority.
- Clean Energy Regulator Safeguard Mechanism:Compliance obligations for covered facilities drive retrofit investments in gas turbine efficiency upgrades and co-firing modifications.
- Grid Inertia Services:Synchronous condensers and spinning reserves from thermal plants command premium ancillary service payments as renewable penetration rises.
Market Restraints
- Carbon Price Exposure:The Safeguard Mechanism baseline reductions impose escalating compliance costs on coal-fired units without carbon capture retrofits.
- Gas Supply Concentration:Eastern Australia gas production centers on Queensland coal seam gas fields and Bass Strait offshore platforms, creating pipeline capacity bottlenecks during demand spikes.
- Intermittency Integration Limits:Technical constraints on minimum stable generation levels prevent thermal plants from cycling rapidly enough to match renewable output swings.
Strategic Opportunities
- Queensland Gas Peaking Expansion:State government procurement of firming capacity creates tender opportunities for combined-cycle and open-cycle gas turbine developers.
- Biomass Co-firing Retrofits:Agricultural waste supply chains in Victoria's Latrobe Valley enable partial fuel substitution for existing coal units seeking emissions intensity reductions.
- Hybrid Battery-Thermal Configurations:Grid-scale battery coupling with gas turbines allows faster ramping and synthetic inertia provision, qualifying for enhanced NEM market payments.
Industry Challenges
- Specialized Maintenance Workforce Shortages:Gas turbine blade repair and hot gas path inspection capabilities concentrate among a handful of OEM-authorized service providers.
- Retirement Synchronization Risks:AGL Energy and Origin Energy face overlapping coal closure timelines that strain transmission system planning and replacement capacity sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Thermal Power Market |
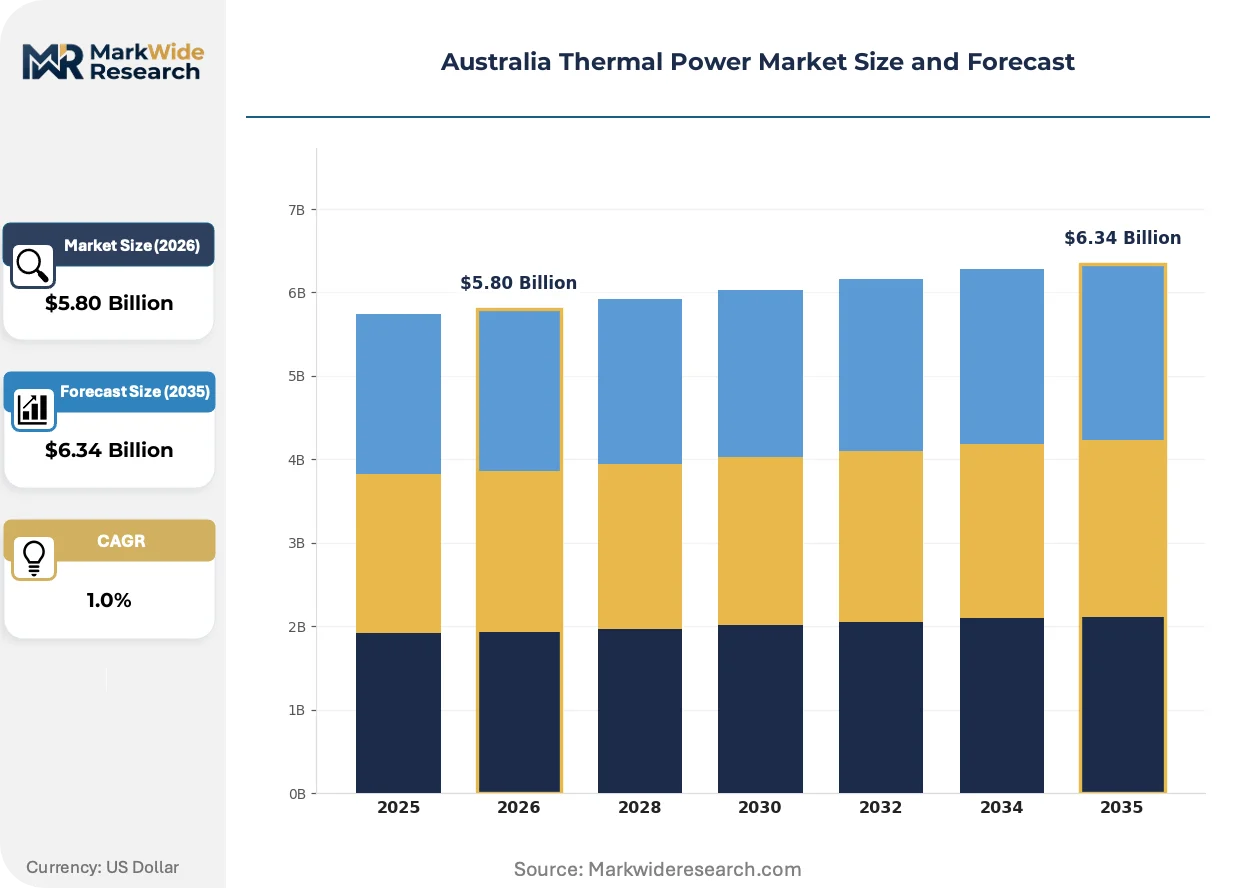
| Market Size in 2026 | $5.80 Billion |
| Market Size in 2035 | $6.34 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Coal, Natural Gas, Biomass, Oil Application: Base Load Generation, Peak Load Generation, Standby Power, Distributed Generation End User: Industrial, Commercial, Residential, Utilities Installation: New Build, Upgrade, Retrofit, Decommissioning |
| Companies Covered | AGL Energy Limited, Origin Energy Ltd, Stanwell Corporation Limited, EnergyAustralia Holdings Ltd, InterGen Services, Inc, CS Energy Limited, Snowy Hydro Limited, ATCO Australia Pty Ltd, Zenith Energy Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Thermal Power Market Strategic Shifts
Technology convergence between thermal generation and energy storage is redefining plant economics, while regulatory pressure on emissions intensity accelerates fuel-switching and efficiency investments across the NEM.
Advanced gas turbine inlet air chilling is rewriting summer peak performance economics for Queensland and New South Wales combined-cycle units. AGL Energy and Origin Energy deploy these systems to sustain output during heat waves that degrade standard thermal efficiency. The technology is compressing the cost gap between gas peaking and battery storage for 2-4 hour firming requirements.
The Australian Energy Market Operator's Integrated System Plan mandates transmission upgrades linking renewable zones to load centers, directly affecting thermal plant dispatch geography. This framework reallocates firming value toward gas units located near demand hubs rather than remote coal stations. Queensland and Victoria generators are repositioning maintenance schedules to align with projected transmission completion timelines.
Corporate power purchase agreements now specify 24/7 carbon-free energy matching rather than annual renewable energy certificate offsets. Large electricity users in Gladstone's industrial corridor negotiate contracts blending firm thermal output with renewable generation to meet Scope 2 reporting requirements. This procurement evolution favors gas turbines with verified emissions intensity benchmarks over unabated coal supply.
Australia Thermal Power Market Segmentation
Thermal power asset configurations in Australia diverge sharply by dispatch role and fuel source, with each segment commanding distinct capital intensity profiles and regulatory exposure. Understanding these fault lines clarifies where equipment suppliers and project developers can extract margin amid the National Electricity Market's transition.
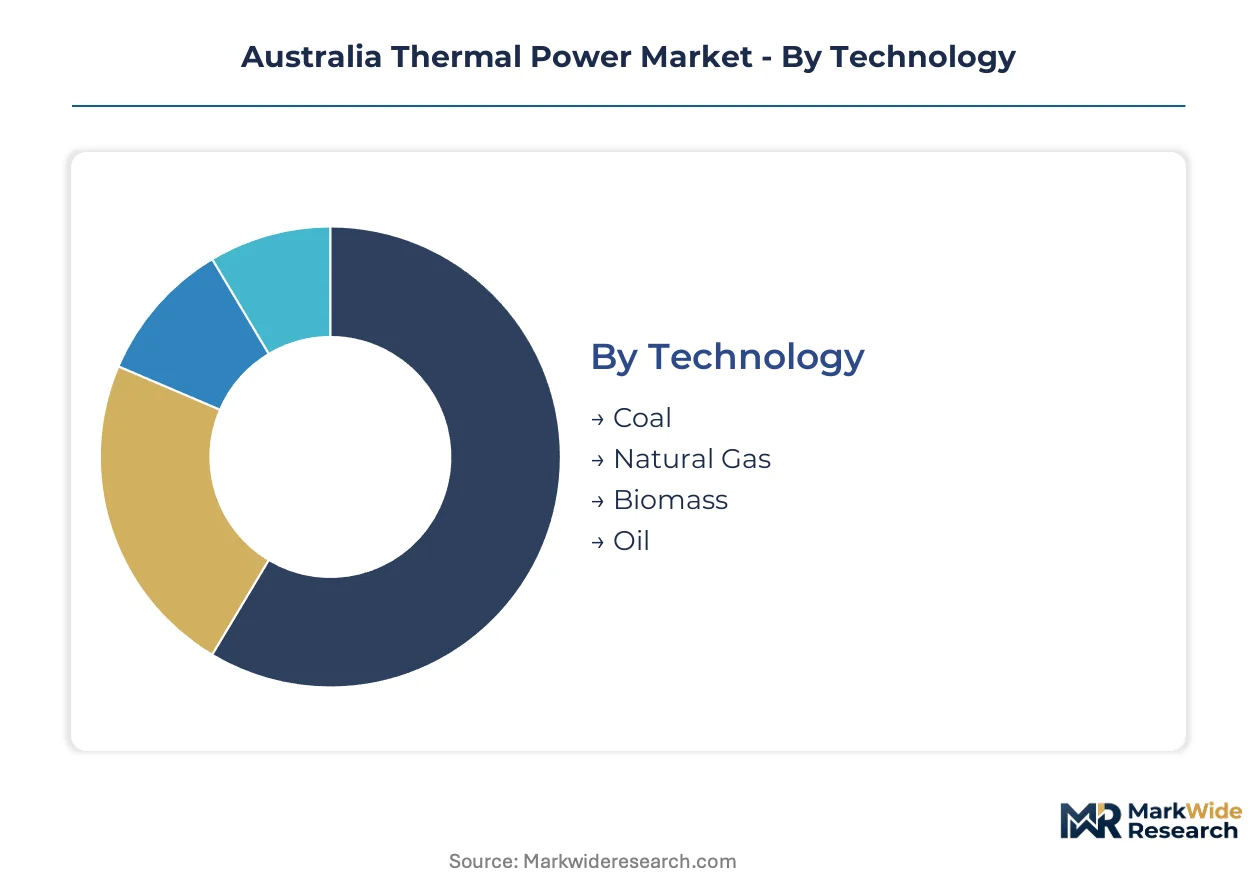
Technology:
Integration depth varies substantially: coal and gas units operate as standalone grid-scale assets, while biomass and oil technologies embed more frequently within hybrid or distributed configurations.
- Coal:Subcritical and supercritical pulverized fuel plants dominate installed capacity across Queensland and Victoria. The Latrobe Valley's brown coal stations and Queensland's black coal units face compressed dispatch windows under state renewable targets, though mining corridor demand in the Hunter Valley and Gladstone preserves baseload economics for retained capacity.
- Natural Gas:Combined-cycle and open-cycle gas turbines deliver intermediate and peaking flexibility with lower emissions intensity than coal. Queensland's gas turbine fleet expansion accelerates as coal retirement timelines compress, with AEMO reliability standards elevating these assets to grid-critical status for frequency control and spinning reserves.
- Biomass:Agricultural waste and wood pellet co-firing retrofits enable partial fuel substitution in existing coal units. Victorian agricultural supply chains support pilot projects, though feedstock logistics constrain standalone deployment.
- Oil:Distillate-fired reciprocating engines and gas turbines serve remote mining operations and islanded grids where pipeline gas access is absent. Western Australia's Pilbara region and offshore platforms anchor residual demand.
Coal leads volumes today; natural gas is gaining share fastest.
Application:
Cost tier stratification separates capital-intensive baseload investments from lower-capex peaking and standby configurations.
- Base Load Generation:Continuous 24/7 operation at high capacity factors requires subcritical, supercritical, or combined-cycle configurations with extended maintenance intervals. Western Australia and Queensland mining corridors sustain demand that renewable sources cannot yet fulfill, preserving dispatch priority for retained thermal units.
- Peak Load Generation:Rapid-start open-cycle gas turbines and reciprocating engines capture price spikes during demand surges and renewable shortfalls. Queensland government procurement of firming capacity creates tender opportunities for developers targeting 2-4 hour dispatch windows.
- Standby Power:Emergency backup systems for critical infrastructure including hospitals, data centers, and telecommunications. Distributed diesel and gas generator sets serve this segment with minimal utilization requirements.
- Distributed Generation:On-site thermal plants for industrial facilities and remote communities. Hybrid battery-thermal configurations allow faster ramping and synthetic inertia provision, qualifying for enhanced NEM market payments.
Base load generation retains revenue concentration; distributed generation shows the steepest expansion trajectory.
End User:
Customer type determines contracting structure, with utilities procuring under regulated frameworks and industrial users negotiating bilateral agreements.
- Industrial:Mining, smelting, and manufacturing operations in Gladstone's industrial corridor and Western Australia's Pilbara region require firm, high-availability power. Corporate power purchase agreements now specify 24/7 carbon-free energy matching, blending thermal output with renewable generation to meet Scope 2 reporting requirements.
- Commercial:Office complexes, retail centers, and hospitality facilities prioritize standby resilience over continuous thermal dispatch. Behind-the-meter gas cogeneration captures value where retail electricity tariffs exceed on-site generation costs.
- Residential:Minimal direct thermal power exposure; grid-supplied electricity dominates. Standby generators serve remote properties beyond distribution network reach.
- Utilities:State-owned and private generators participating in the National Electricity Market wholesale pool. AEMO reliability standards and state renewable integration targets reshape dispatch priorities and capacity payment eligibility.
Utilities dominate capacity ownership; industrial procurement is expanding most quickly.
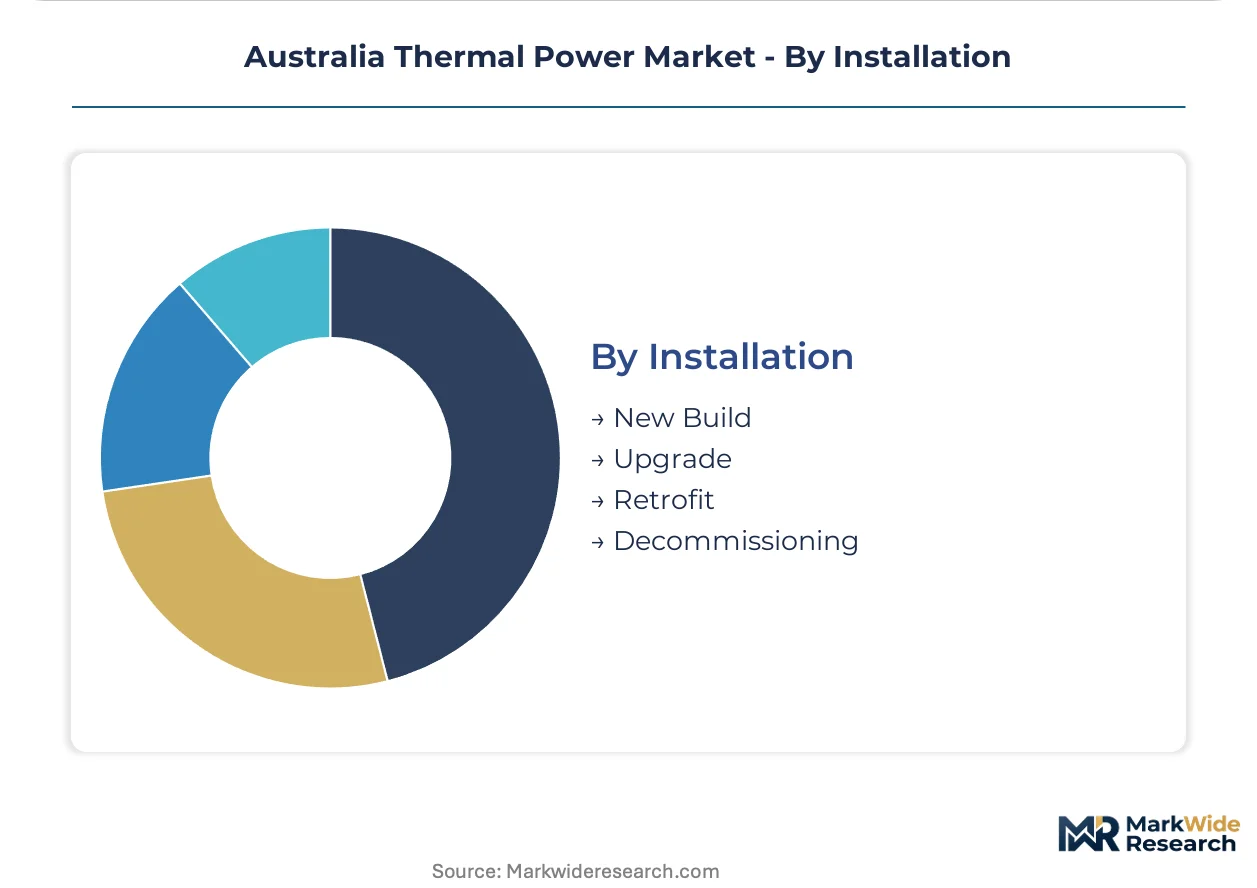
Installation:
Maturity stage segmentation separates greenfield development from asset life extension strategies.
- New Build:Greenfield gas turbine and combined-cycle projects, concentrated in Queensland where state government firming capacity tenders attract developer interest. Transmission-linked renewable zones in the Integrated System Plan reallocate firming value toward gas units located near demand hubs.
- Upgrade:Efficiency retrofits including advanced inlet air chilling and hot gas path component replacement. AGL Energy and Origin Energy deploy these systems to sustain summer peak performance during heat waves that degrade standard thermal efficiency.
- Retrofit:Biomass co-firing modifications and emissions control additions driven by Clean Energy Regulator Safeguard Mechanism compliance obligations. Covered facilities face escalating baseline reductions that accelerate investment timelines.
- Decommissioning:Coal plant closure execution and site remediation, with AGL Energy and Origin Energy managing overlapping retirement timelines that strain transmission system planning and replacement capacity sequencing.
Upgrade and retrofit activity leads capital deployment today; new build gas capacity is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance divergence between states is redistributing thermal generation investment toward jurisdictions with softer emissions baselines and more generous firming capacity procurement programs.
Queensland
Coal seam gas fields and Gladstone's industrial corridor anchor baseload demand that renewable sources cannot yet fulfill. The state government's firming capacity tenders create procurement pathways for combined-cycle and open-cycle gas turbine developers. Brisbane-based generators reposition maintenance schedules to align with projected transmission completion timelines under AEMO's Integrated System Plan.
Victoria
The Latrobe Valley's brown coal stations face compressed dispatch windows under state renewable targets approaching 95% by 2035. Agricultural waste supply chains enable biomass co-firing pilot projects seeking Safeguard Mechanism compliance. Melbourne's manufacturing belt negotiates corporate power purchase agreements blending thermal output with renewable generation for Scope 2 reporting.
New South Wales
Advanced inlet air chilling systems sustain summer peak performance for Sydney-adjacent combined-cycle units during heat waves. The state's Electricity Infrastructure Roadmap mandates 12 gigawatts of renewable and firming capacity by 2030. Hunter Valley coal generators manage overlapping retirement timelines that strain transmission system planning.
Western Australia
Pilbara mining operations sustain 24/7 baseload requirements preserving dispatch priority for retained gas and diesel units. The Wholesale Electricity Market operates outside NEM jurisdiction with distinct reliability standards. Perth's isolated grid configuration elevates spinning reserve values for synchronous thermal plant.
South Australia
World-leading renewable penetration has elevated gas peaking assets to grid-critical status for frequency control services. The state's big battery deployment compresses dispatch windows for thermal units to extreme price spike events. Adelaide's industrial users procure hybrid battery-thermal configurations qualifying for enhanced ancillary service payments.
Australia Thermal Power Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid battery-thermal configurations and behind-the-meter distributed generation. The market structure concentrates around vertically integrated utilities with captive retail platforms and state-backed generation corporations with transmission-linked asset portfolios. Three archetypes dominate: integrated energy retailers leveraging wholesale-retail margin capture, government-owned corporations managing public interest transition pathways, and independent power producers targeting firming capacity tenders. Competitive dynamics center on strategic partnerships for technology licensing and portfolio diversification into renewable zones.
Within the integrated retail tier, AGL Energy Limited and Origin Energy Ltd exemplify wholesale-retail platform operators navigating coal retirement synchronization. Stanwell Corporation Limited occupies a position representing state-backed baseload management with transition pathway obligations. These three anchors illustrate how generation ownership structure—private integrated, private independent, and public corporation—determines strategic optionality under accelerating emissions intensity benchmarks.
| Leading Market Players |
|---|
| AGL Energy Limited |
| Origin Energy Ltd |
| Stanwell Corporation Limited |
| EnergyAustralia Holdings Ltd |
| InterGen Services, Inc |
| CS Energy Limited |
| Snowy Hydro Limited |
| ATCO Australia Pty Ltd |
| Zenith Energy Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
State government firming capacity procurement in Queensland anchors contract-based long-term offtake structures that dominate transaction economics across the National Electricity Market. Generator-retailers with integrated platforms capture wholesale-retail margin spreads unavailable to independent power producers, compressing competitive pricing flexibility for standalone developers.
Pricing Analysis
Direct-to-utility tender discounts compress developer margins below the standard 15-20 percent retailer markup observed in bilateral industrial contracts. Three-tier pricing structure across premium, standard, and economy levels separates grid-scale combined-cycle units from open-cycle peakers and behind-the-meter distributed configurations. Cost compression in gas turbine equipment stems from OEM oversupply in the Asia-Pacific region. Industrial mining offtakers in Western Australia exhibit lowest price sensitivity due to 24/7 baseload requirements, while commercial standby generators face acute cost pressure from battery storage alternatives.
Supply Chain Analysis
Domestic-content mandates under Australia's Powering Australia plan reshape sourcing toward local EPC contractors and qualified service technicians for maintenance contracts. Heavy gas turbine components concentrate manufacturing in Japan, Germany, and the United States, while hot gas path blades and combustion hardware draw from specialized foundries in Italy and Sweden. Nickel superalloy forgings and precision-cast turbine blades represent critical input dependencies. Single-source vulnerability runs through OEM-authorized blade repair capabilities concentrated among fewer than five global service hubs. Distribution runs through original equipment manufacturer direct sales for grid-scale units and regional electrical distributors for sub-10MW distributed generation packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Australian thermal power rests on efficiency retrofit demand driven by Clean Energy Regulator baseline reductions and the premium-tier shift toward hybrid battery-thermal configurations commanding enhanced ancillary service payments.
For Market Incumbents: Cement grid-critical positioning by securing spinning reserve and frequency control ancillary service contracts before transmission-linked renewable zones dilute locational value. Accelerate hot gas path upgrade cycles to sustain heat rate performance during intensifying summer peaks. Vertical integration into battery storage coupling preserves dispatch priority as pure thermal units face compressed duty cycles. For New Entrants and Emerging Players: The Safeguard Mechanism in Australia opens a window for biomass co-firing retrofit specialists targeting Victoria's Latrobe Valley brown coal stations seeking emissions intensity compliance. Queensland government firming capacity tenders represent the most penetrable procurement channel for combined-cycle developers without legacy coal exposure. A go-to-market angle anchored to verified 24/7 carbon-free energy matching for Gladstone industrial corridor offtakers bypasses established generator-retailer incumbency. For Investors and Strategic Acquirers: Integrated energy retailers are the most active acquirer in this space, seeking distributed generation platforms to defend retail customer bases against behind-the-meter competition. Long-term viability favors gas-peaking and hybrid battery-thermal assets over unabated coal exposure across the investment horizon. Acquisition target archetype: Queensland and New South Wales combined-cycle developers with secured gas pipeline interconnection and AEMO reliability status designation. The signal to watch is accelerating corporate power purchase agreement procurement specifying hourly carbon-free energy matching rather than annual certificate offsets.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Battery-Thermal Deployment | Grid-scale battery coupling with gas turbines qualifies for enhanced NEM ancillary service payments. |
| Advanced Inlet Air Chilling Retrofit | AGL Energy and Origin Energy deploy these systems to sustain summer peak output during heat waves. |
| Biomass Co-firing Modification | Victorian agricultural waste supply chains enable partial fuel substitution for Safeguard Mechanism compliance. |
| Firming Capacity Tender Participation | Queensland government procurement creates developer pathways for combined-cycle and open-cycle gas turbines. |
| Spinning Reserve Contract Securement | Synchronous inertia services from thermal plants command premium payments as renewable penetration rises. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against AEMO market data, Clean Energy Regulator filings, IEA power sector reports, and state government electricity infrastructure roadmaps. Bottom-up capacity and dispatch modeling triangulated against top-down market value estimates derived from NEM wholesale price pool analysis.
Comparable-period anchoring linked the projection horizon to historical dispatch patterns, capacity factor trends, and fuel price trajectories across the analysis window. Segmentation dimensions modeled include fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from installed capacity evolution, retirement timeline execution rates, and new build commissioning schedules. Forecast inputs incorporated gas supply contract pricing, carbon compliance cost trajectories, and transmission completion timelines under the Integrated System Plan.
Revisions become necessary when state renewable target acceleration, unplanned coal unit retirements, or gas supply infrastructure delays materialize beyond baseline assumptions. Forecasts reflect documented parameters regarding emissions intensity benchmarks, reliability standard enforcement, and firming capacity procurement volumes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Captive Power Generation Market
Power Generation
Power Generation Technologies Market
Power Generation
United Kingdom Power Market
Power Generation
Global Power to Gas Market
Power Generation
Oman Power Market
Power Generation
Residential Solar Generator Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Wind Power EPC Market
Power Generation
Global Gensets Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Captive Power Plant Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Cogeneration System Market
Power Generation
Marine Power Plant Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Hydrogenerators Market