
 Asia-Pacific Gas Turbine Service Market | 2026-2036
Asia-Pacific Gas Turbine Service Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gas Turbine Service Market Analytics
Advanced hot-path component refurbishment is redrawing competitive boundaries across the Asia-Pacific Gas Turbine Service Market. GE Vernova leverages its HA-class turbine expertise to anchor long-term service agreements in Japan and South Korea. Mitsubishi Power dominates domestic overhaul demand through captive knowledge of J-class airfoil metallurgy and combustion system retrofits. Siemens Energy competes aggressively on digital inspection platforms that reduce unplanned outage frequency for utility operators.
Asia-Pacific gas turbine service encompasses scheduled maintenance, unplanned repair, component overhaul, and lifecycle inspection of industrial gas turbines operating above 1,000 degrees Celsius firing temperatures. These services restore thermal efficiency, extend operational intervals, and ensure compliance with emissions limits for power generation and oil and gas applications. Maintenance and overhaul segments command the largest revenue pools due to recurring contractual obligations on installed bases exceeding fifteen years of operation. Repair services represent the fastest-growing category as operators defer capital replacement in favor of hot-section component restoration. CCGT technology drives the majority of service demand given higher utilization rates and stricter efficiency requirements compared with open-cycle units.
Japan's METI enforces periodic inspection standards that mandate combustion hardware replacement cycles, while India's CEA imposes grid-code compliance testing that accelerates generator rewind schedules. Australia's NEM reliability frameworks and South Korea's KEPCO technical specifications further shape service procurement patterns across the region. Stakeholders must monitor evolving carbon-border adjustment mechanisms and hydrogen-blending readiness requirements that will redefine turbine upgrade priorities and service contract scopes.
Market Dynamics
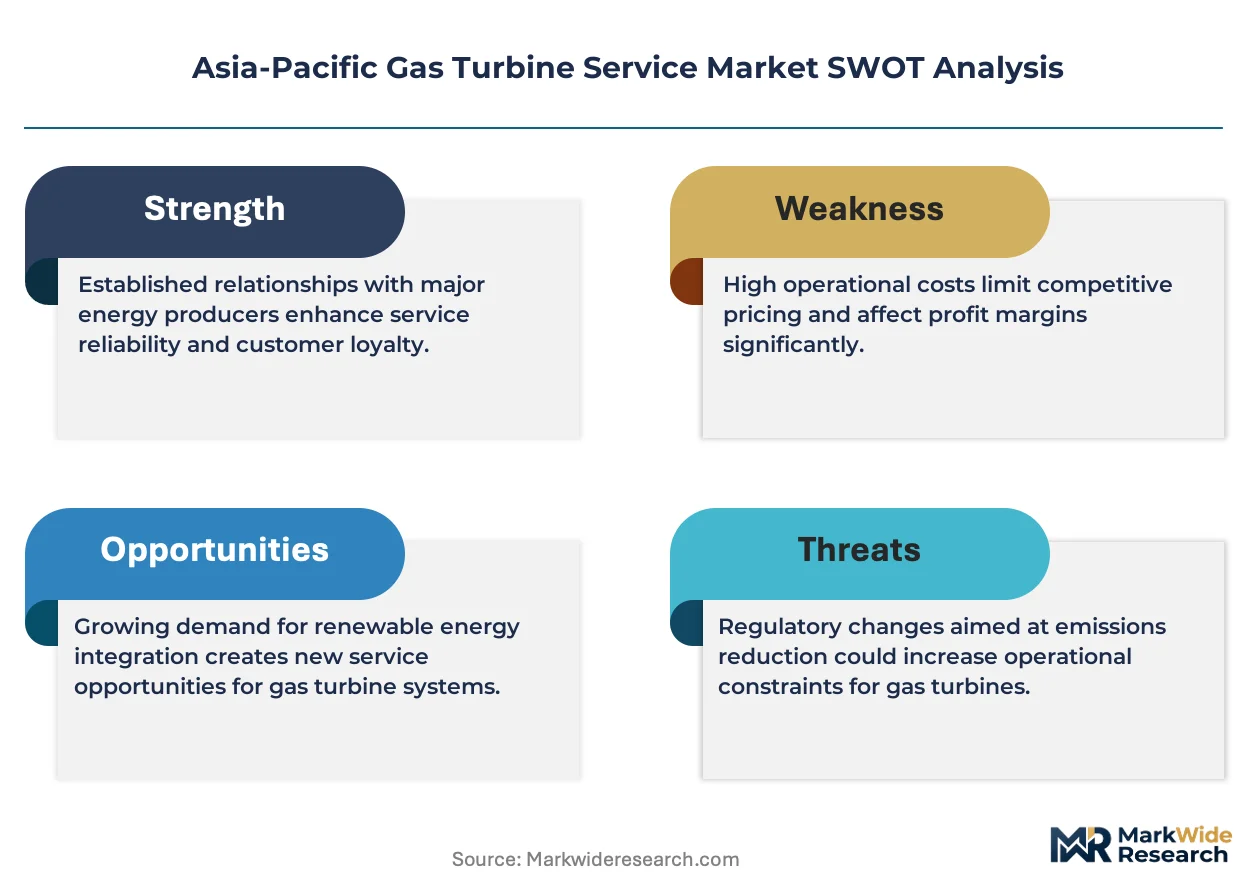
Japan's METI efficiency mandates and India's CEA grid-code compliance testing are compressing inspection intervals and forcing simultaneous hardware replacement cycles across aging combined cycle gas turbine fleets.
Growth Catalysts
- India's CEA grid-code compliance testing:State-run power producers and independent power producers accelerate generator rewind schedules and combustion hardware replacement to meet reliability standards.
- Hydrogen-blending readiness requirements:Australia's emissions reduction frameworks and South Korea's KEPCO technical specifications drive turbine upgrade priorities and expanded service contract scopes.
- Aging CCGT fleets:Power generation utilities across Southeast Asia expand long-term service agreements as installed bases exceed fifteen years of operation.
Market Restraints
- Specialized hot-path component supply concentration:Captive knowledge of J-class airfoil metallurgy and HA-class turbine expertise concentrates among a limited supplier base in Japan and South Korea.
- Superalloy input cost volatility:Nickel and cobalt price fluctuations directly impact refurbishment economics for combustion hardware and turbine blades operating above 1,000 degrees Celsius.
- Extended certification timelines:Australia's NEM reliability frameworks impose rigorous approval processes for component retrofits that delay revenue recognition on overhaul contracts.
Strategic Opportunities
- Indonesia's underpenetrated independent power producer segment:New capacity additions and foreign direct investment in gas-fired generation create greenfield service agreement potential.
- Digital inspection platform convergence:Integration of remote monitoring systems with predictive analytics reduces unplanned outage frequency for utility operators seeking operational certainty.
- Vietnam's PDP8 power development plan:LNG-to-power project commitments under the national energy roadmap expand the addressable installed base requiring lifecycle service support.
Industry Challenges
- Certified gas turbine technician scarcity:Specialized welding and coating expertise for hot-section component restoration lags fleet expansion rates across Southeast Asia.
- Legacy control system integration complexity:Digital retrofit packages must interface with analog turbine control architectures installed during 1990s capacity buildouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gas Turbine Service Market |
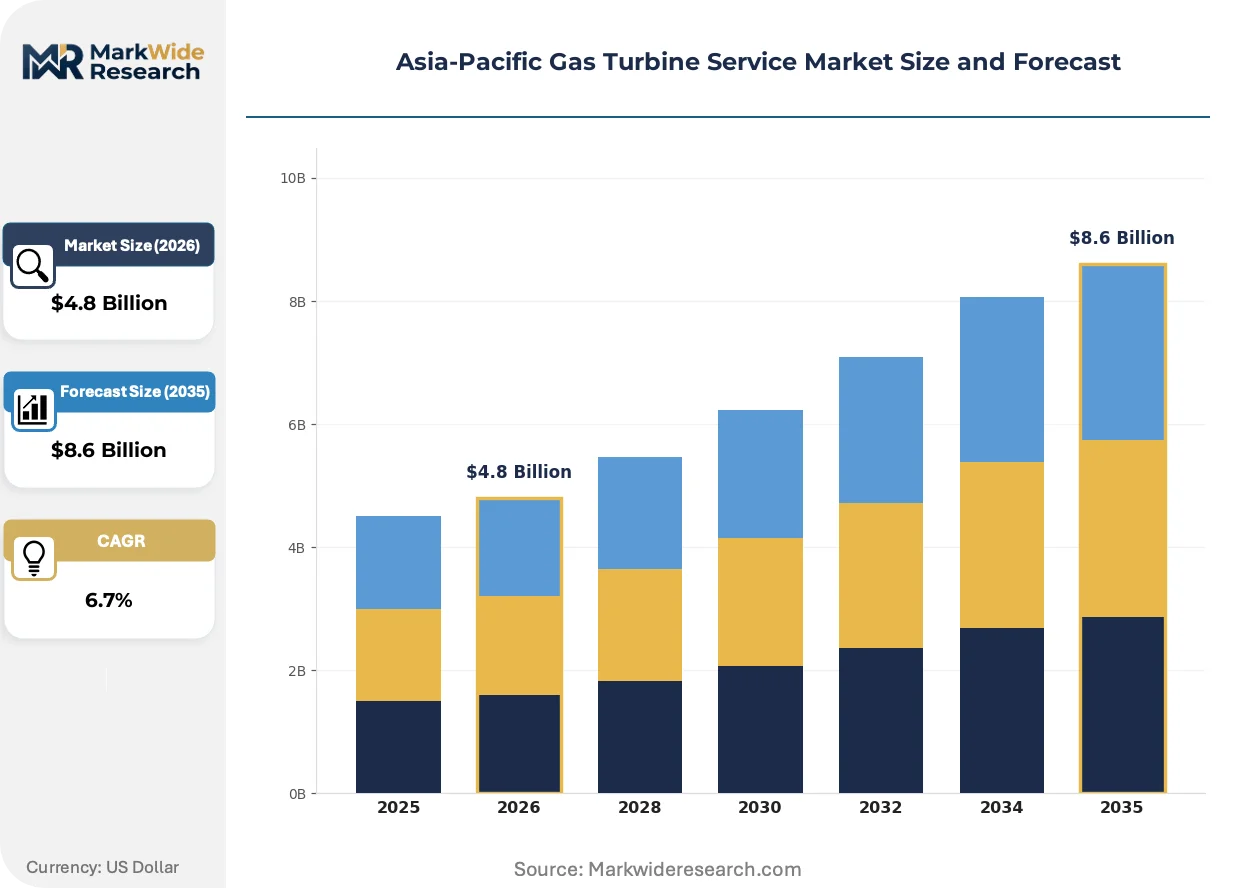
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Overhaul, Repair, Inspection End User: Power Generation, Oil & Gas, Marine, Aerospace Technology: CCGT, Open Cycle, Traditional, Hybrid Component: Turbine, Compressor, Generator, Exhaust System |
| Companies Covered | GE Vernova, Siemens Energy, Mitsubishi Power, Kawasaki Heavy Industries, Ansaldo Energia, Bharat Heavy Electricals, Shanghai Electric Gas Turbine, MAN Energy Solutions, IHI Power Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gas Turbine Service Market Evolving Landscape
Advanced coating technologies and remote diagnostic platforms are compressing maintenance intervals while extending component life, fundamentally altering how operators balance capital replacement against refurbishment economics.
Additive manufacturing of superalloy turbine blades is supplanting conventional casting and forging methods for hot-path component restoration. Independent power producers in India and Thailand adopt printed replacement airfoils to shorten lead times from eighteen months to eight weeks. This technology is supplanting traditional spare parts procurement channels and enabling just-in-time inventory models that reduce working capital requirements.
Japan's METI periodic inspection standards now mandate combustion hardware replacement cycles tied to cumulative firing hours rather than calendar time. This regulatory shift forces synchronous overhaul scheduling across utility fleets and concentrates service demand into predictable windows. Combined cycle gas turbine operators respond by negotiating multi-unit framework agreements that secure technician allocation and parts availability.
Long-term service agreements are unbundling from original equipment manufacturer exclusivity as utility procurement teams develop technical evaluation capabilities. State-run power producers in India and Australia now tender overhaul contracts separately from parts supply, fragmenting vendor relationships that previously ran fifteen to twenty years. This behavioral shift is most visible in India's National Capital Region, where independent technical inspection firms validate third-party refurbishment quality.
Asia-Pacific Gas Turbine Service Market Segmentation
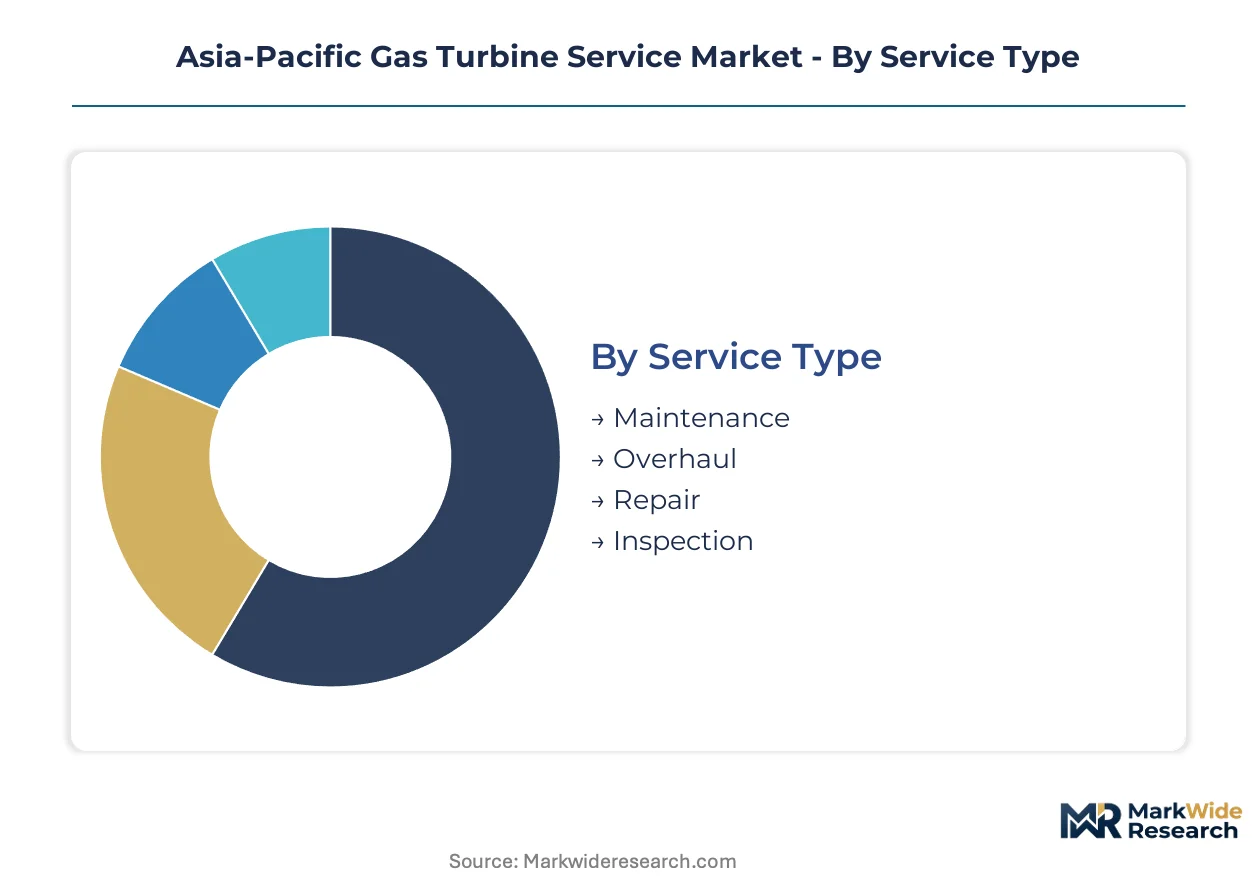
Segmentation in the Asia-Pacific Gas Turbine Service Market reveals how service intensity, component criticality, and technology vintage shape procurement budgets across utility and industrial fleets. Distinct value pools emerge where firing temperatures, utilization rates, and regulatory compliance requirements diverge.
Service Type:
Overhaul services face acute substitution pressure from in-situ repair technologies that extend component life without full disassembly.
- Maintenance:Scheduled intervals for lubrication system servicing, filter replacement, and control system calibration preserve baseline availability. India's state-run power producers concentrate demand here under CEA-mandated preventive schedules.
- Overhaul:Complete disassembly, hot-path component refurbishment, and reassembly restore thermal efficiency to design specifications. Japan's METI periodic inspection standards compress these cycles for combined cycle fleets exceeding fifteen years of operation.
- Repair:Additive manufacturing of superalloy airfoils and combustion hardware shortens lead times from conventional casting. Thailand's independent power producers adopt printed replacements to defer capital replacement.
- Inspection:Borescope examinations, non-destructive testing, and digital twin validation identify degradation before failure. Australia's NEM reliability frameworks mandate these protocols for grid-connected assets.
Overhaul anchors the volume base while Repair gains share at the steepest rate.
End User:
Cost tier segmentation separates capital-intensive utility procurement from project-driven industrial contracting.
- Power Generation:Combined cycle gas turbine fleets dominate service contract value with recurring long-term agreements tied to heat rate guarantees. Southeast Asian utilities expanding LNG-to-power capacity drive regional demand concentration.
- Oil & Gas:Mechanical drive applications for compression and pumping require specialized offshore service logistics. Australia's offshore LNG facilities and Indonesia's upstream developments concentrate procurement.
- Marine:Naval and commercial propulsion systems demand compact overhaul windows during dry-docking schedules. South Korean shipyards and Singapore's repair hubs anchor regional service capacity.
- Aerospace:Aero-derivative gas turbines for power generation and mechanical drive require distinct airfoil metallurgy expertise. Japan's industrial gas turbine manufacturers leverage captive knowledge here.
Power Generation commands the largest contract values while Oil & Gas expands most quickly on offshore project commitments.
Technology:
Volume concentration tracks with installed base age and utilization intensity across firing temperature classes.
- CCGT:Combined cycle configurations above 1,000 degrees Celsius firing temperature generate the densest service demand through higher annual operating hours. India's aging fleet modernization and Vietnam's PDP8 project pipeline concentrate procurement.
- Open Cycle:Peaking and emergency power applications require less frequent hot-section attention but face efficiency upgrade pressure. Australia's grid reliability reserves and Indonesia's islanded generation systems sustain demand.
- Traditional:Legacy frame units installed during 1990s capacity buildouts require control system retrofits and analog-to-digital migration. India's National Capital Region and Thailand's industrial estates anchor this segment.
- Hybrid:Hydrogen-blending readiness and carbon capture integration are reshaping upgrade specifications. South Korea's KEPCO technical specifications and Australia's emissions reduction frameworks drive early adoption.
CCGT dominates installed base value while Hybrid climbs the fastest on decarbonization roadmaps.
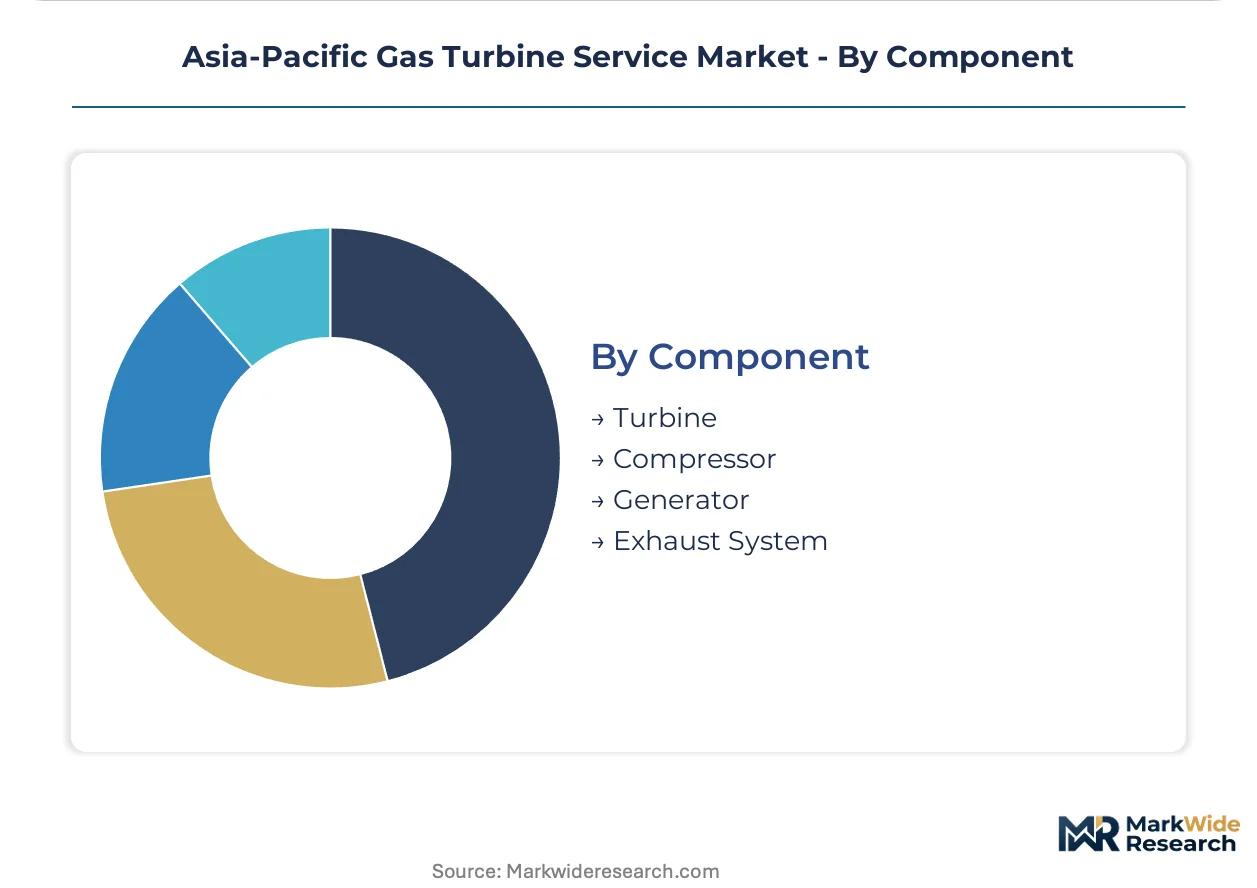
Component:
Margin concentration aligns with superalloy content and specialized refurbishment expertise requirements.
- Turbine:Hot-section airfoils, combustion liners, and transition pieces operating above 1,000 degrees Celsius require coating restoration and metallurgical repair. Japan's METI mandates replacement cycles tied to cumulative firing hours.
- Compressor:Blade erosion and fouling restoration improves pressure ratio and mass flow capacity. Coastal installations across Southeast Asia concentrate demand for corrosion-resistant coatings.
- Generator:Stator rewinds, rotor balancing, and excitation system upgrades respond to grid-code compliance requirements. India's CEA testing protocols accelerate these schedules for state-run assets.
- Exhaust System:Ducting, silencers, and heat recovery steam generator interfaces require corrosion inspection and expansion joint replacement. Australia's NEM reliability frameworks mandate specific inspection intervals.
Turbine captures the highest service contract values while Generator shows the steepest expansion trajectory on grid-code tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service capacity clusters around established manufacturing hubs and coastal power generation corridors. Japan and South Korea anchor high-technology overhaul demand. India's aging fleet drives volume expansion. Australia's offshore LNG facilities and Vietnam's new project pipeline concentrate emerging procurement.
Japan
Domestic OEMs command captive overhaul demand through proprietary J-class airfoil metallurgy expertise. METI periodic inspection standards mandate combustion hardware replacement cycles tied to cumulative firing hours. Tokyo-Osaka industrial corridor hosts dense service infrastructure for utility-scale combined cycle fleets.
India
State-run NTPC and independent power producers modernize gas turbine assets exceeding fifteen years of operation. CEA grid-code compliance testing accelerates generator rewind schedules and hot-section component replacement. National Capital Region and Maharashtra industrial clusters concentrate procurement for aging frame unit retrofits.
South Korea
KEPCO technical specifications drive turbine upgrade priorities for hydrogen-blending readiness. Domestic heavy industrial conglomerates maintain integrated service capabilities for utility and marine propulsion applications. Busan-Ulsan shipbuilding corridor anchors marine gas turbine overhaul capacity.
Australia
Offshore LNG compression trains and grid reliability reserves sustain mechanical drive and peaking power service demand. NEM reliability frameworks impose rigorous certification timelines for component retrofits. Western Australia LNG precincts and Queensland power corridors concentrate procurement.
Vietnam
PDP8 power development plan commitments expand LNG-to-power capacity requiring lifecycle service support. Foreign direct investment in gas-fired generation creates greenfield service agreement opportunities. Southern economic region around Ho Chi Minh City anchors emerging demand concentration.
Asia-Pacific Gas Turbine Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Gas Turbine Service Market. The vendor base organizes into three functional tiers: original equipment manufacturers with captive metallurgy expertise, independent service providers with additive manufacturing capabilities, and national champions serving domestic utility fleets. Consolidation pressure intensifies as long-term service agreements unbundle from OEM exclusivity. Strategic moves center on digital inspection platform development and hydrogen-ready upgrade certification.
Within the OEM tier, GE Vernova and Mitsubishi Power occupy positions defined by proprietary turbine class expertise. Siemens Energy exemplifies the digital-first competitive vector. Bharat Heavy Electricals anchors the national champion archetype serving India's state-run power producers under localized procurement mandates.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Mitsubishi Power |
| Kawasaki Heavy Industries |
| Ansaldo Energia |
| Bharat Heavy Electricals |
| Shanghai Electric Gas Turbine |
| MAN Energy Solutions |
| IHI Power Systems |
| Others |
Value Network & Pricing Analysis
Eighteen-month lead times for conventional superalloy turbine blade casting compress procurement windows and concentrate pricing power among Japanese and South Korean OEMs with captive metallurgy expertise. This supply bottleneck forces utility operators to absorb premium surcharges for expedited hot-path component delivery or accept extended outage schedules.
Pricing Analysis
Japan's METI periodic inspection standards dictate the pricing tier structure across the Asia-Pacific Gas Turbine Service Market. Three-tier pricing structure across premium, standard, and economy levels separates OEM-exclusive long-term service agreements from independent provider overhaul contracts and spot repair transactions. Cost compression in the standard tier is intensifying because additive manufacturing entrants from Thailand and India are shortening printed airfoil delivery cycles. State-run power producers in India exhibit the highest price sensitivity due to CEA-mandated procurement thresholds, while Japanese utilities under METI compliance deadlines show the least.
Supply Chain Analysis
Container availability constraints on the Shanghai-Singapore and Busan-Melbourne trade lanes elevate inbound logistics costs for nickel and cobalt superalloy feedstock. Geographic supply concentration centers on Japan for J-class airfoil metallurgy, South Korea for HA-class turbine expertise, and India for generator rewind capacity. The supply chain draws from specialty steel mills in Germany, precision casting foundries in the United States, and coating material suppliers in Switzerland. Single-source vulnerability around IGT-class hot-path component refurbishment creates structural risk. Distribution runs through OEM-authorized service depots in Tokyo, Seoul, and Mumbai, with secondary channels via independent technical inspection firms in Australia's NEM-connected regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Gas Turbine Service Market functions as a defensive-moat industry where regulatory entrenchment creates substantial switching costs for utility operators locked into fifteen-to-twenty-year service agreements.
For Market Incumbents: Compound captive metallurgy advantages by securing exclusive superalloy supply agreements with Japanese and German specialty steel producers before additive manufacturing scales. Expand digital inspection platform deployment across Southeast Asian utility fleets to preempt independent provider encroachment. The threat of unbundled procurement mandates from India's CEA and Australia's NEM requires proactive multi-unit framework pricing to retain contract renewal rates. For New Entrants and Emerging Players: Additive manufacturing service gaps in Indonesia's independent power producer segment offer the most penetrable entry point for printed airfoil specialists. Vietnam's PDP8 project pipeline creates greenfield demand for lifecycle service support without incumbent lock-in. Target Australia's offshore LNG mechanical drive segment through specialized corrosion-resistant coating capabilities that reduce compressor blade replacement frequency. For Investors and Strategic Acquirers: Carve-out targets emerge from heavy industrial conglomerates in South Korea and Japan seeking to divest non-core gas turbine service divisions. Long-term viability rests on hydrogen-blending readiness certification capabilities that will dominate upgrade specifications across the projection horizon. Watch for KEPCO technical specification revisions and Australia's emissions reduction framework tightening as inflection indicators for contract scope expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Upgrade Certification | KEPCO technical specifications and Australia's NEM frameworks will mandate turbine combustion system retrofits for fuel blending readiness. |
| Additive Manufacturing Scale-Up | Printed superalloy airfoil production in Thailand and India shortens lead times from eighteen months to eight weeks for independent power producers. |
| Digital Inspection Platform Integration | Siemens Energy's remote monitoring systems reduce unplanned outage frequency for CCGT operators under Japan's METI inspection mandates. |
| Backward Integration into Superalloy Supply | Mitsubishi Power's captive J-class metallurgy expertise anchors domestic overhaul demand against independent provider price competition. |
| Multi-Unit Framework Agreement Expansion | India's NTPC and state-run utilities negotiate consolidated procurement to secure technician allocation under CEA grid-code compliance testing. |
Research Methodology
Desk research of EIA power generation databases, IEA gas turbine deployment statistics, and FERC-equivalent regulatory filings preceded structured interviews with utility planning officers, independent power producer asset managers, EPC contractors, and aftermarket service heads. Primary fieldwork with maintenance directors at CCGT facilities in Japan, India, and Australia validated overhaul scheduling patterns and procurement decision criteria. Secondary triangulation incorporated customs records for superalloy trade flows, OEM service contract disclosures, and national energy regulator technical specifications. Bottom-up installed base modeling and top-down service revenue estimates were cross-referenced to establish market sizing boundaries.
Variance decomposition across service type, end user, technology class, and component criticality shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include firing temperature tier, utilization intensity, regulatory compliance regime, and OEM-original versus third-party service provider status. CAGRs were derived from historical contract value trajectories and forward-looking capacity addition pipelines. Industry-specific forecast inputs incorporated METI-mandated inspection interval compressions and India's CEA generator rewind acceleration schedules.
Forecasts assume regulatory continuity in Japan's METI efficiency mandates, India's CEA grid-code frameworks, and Australia's NEM reliability standards; material policy shifts would require re-modeling of overhaul cycle frequencies and contract scope definitions. Superalloy input cost volatility and certified technician scarcity across Southeast Asia represent specific risk factors that could revise service pricing trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Induction Heating System Market
Power Equipment
United States Power Rental Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Thailand Power Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Power Infrastructure Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Romania Power EPC Market
Power Equipment
Digital Power Conversion Market
Power Equipment
US Power EPC Market
Power Equipment
Deaerators Market
Power Equipment
AC Power Sources Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
G-3 PLC Solutions Market