
 Thailand Power Generation EPC Market | 2026-2036
Thailand Power Generation EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Power Generation EPC Market Analytics
The premium EPC tier is consolidating around integrated design-build capabilities with full commissioning accountability, while commodity contracting fragments into single-service procurement. Mitsubishi Heavy Industries, Ltd. leverages gas turbine technology leadership to anchor large-scale combined-cycle projects. BCPG PCL competes through renewable specialization and domestic regulatory familiarity. General Electric Company sustains global supply chain scale across gas and emerging hydrogen-ready turbine platforms.
Thailand Power Generation EPC encompasses the full engineering, procurement, and construction lifecycle for electricity generation facilities, typically spanning feasibility studies through grid synchronization with performance guarantees of 85-92% plant availability. Solar and biomass segments attract accelerated developer interest under Thailand's renewable energy feed-in tariff revisions, while gas turbine EPC retains dominant value share through baseload reliability requirements. Commissioning services command premium margins as grid code compliance tightens under utility technical specifications, and mega projects concentrate risk capital among consortia with proven financial closure track records.
Thailand's Ministry of Energy and Energy Regulatory Commission shape contractor eligibility through power purchase agreement terms and domestic content requirements. The Department of Alternative Energy Development and Efficiency enforces biomass sustainability certification and solar performance standards that filter EPC prequalification pools. Stakeholders must monitor how Thailand's carbon neutrality commitments redirect gas turbine project pipelines toward hydrogen blending readiness and carbon capture integration obligations.
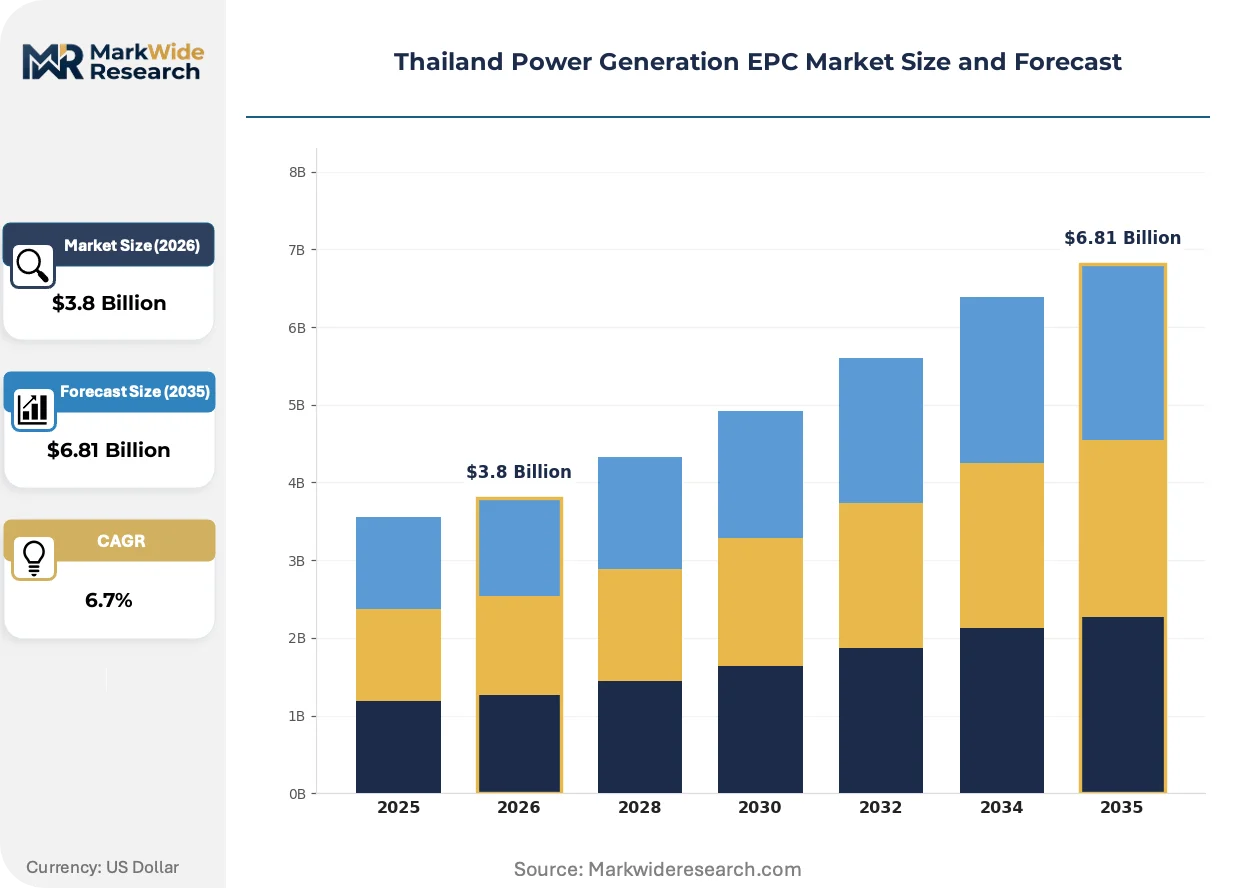
Market Dynamics
Thailand's Power Development Plan 2018-2037 revision is compressing project timelines and forcing EPC contractors to pre-qualify for integrated renewable-gas hybrid builds. The Energy Regulatory Commission's domestic content requirements are reshaping subcontractor selection criteria across the Eastern Economic Corridor.
Growth Catalysts
- Renewable Portfolio Standards:Thailand's Alternative Energy Development Plan mandates biomass and solar capacity additions, creating dedicated procurement streams for contractors with proven grid synchronization capabilities.
- Eastern Economic Corridor industrialization:Petrochemical and automotive clusters in Rayong, Chonburi, and Chachoengsao are driving captive power plant investments with baseload reliability requirements.
- Feed-in Tariff Revisions:The Energy Regulatory Commission's adjusted tariff structures for solar and biomass projects are accelerating developer financial closure timelines and EPC award velocity.
Market Restraints
- Steel and copper price volatility:Fluctuations in raw material input costs are compressing fixed-price EPC contract margins and triggering force majeure renegotiations.
- Specialized turbine component concentration:Heavy gas turbine rotor and blade supply is concentrated among Japanese and German original equipment manufacturers, creating single-source vulnerability for combined-cycle projects.
- Biomass feedstock certification complexity:The Department of Alternative Energy Development and Efficiency's sustainability verification requirements are extending pre-construction approval timelines by 8-14 months.
Strategic Opportunities
- Hydrogen-ready turbine retrofits:Thailand's carbon neutrality 2050 commitment is creating early-mover advantage for EPC contractors with hydrogen blending and carbon capture integration expertise.
- Greater Bangkok distributed solar:Rooftop and floating solar installations in Samut Prakan and Pathum Thani industrial zones represent underpenetrated volume for mid-scale EPC specialists.
- Performance-based O&M bundling:State utilities are piloting 15-20 year availability guarantees that reward contractors with commissioning accountability and predictive maintenance platforms.
Industry Challenges
- Grid code compliance engineering shortage:Thailand's utility technical specifications for frequency response and reactive power management exceed regional training program output, creating bidding bottlenecks.
- Financial closure coordination:Consortium structures required for mega-projects demand synchronized equity, debt, and EPC contract execution that few local contractors have managed end-to-end.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Power Generation EPC Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Procurement, Construction, Commissioning Technology: Solar, Wind, Gas Turbine, Biomass End User: Utilities, Industrial, Commercial, Residential Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Black & Veatch Corporation, BCPG PCL, General Electric Company, DP Cleantech Group, Toshiba Corporation, Mitsubishi Heavy Industries, Ltd., Electricity Generation Authority of Thailand, Grimm Power Public Company Limited, Marubeni Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Power Generation EPC Market Evolving Landscape
Digitization of project controls and prefabrication methods are compressing construction schedules for Thai power infrastructure. Contractors are adopting manufacturing-derived workflows to manage labor scarcity and quality consistency.
Containerized solar PV and battery storage systems are modularizing utility-scale renewable deployment. Industrial developers in the Eastern Economic Corridor are adopting skid-mounted substations and pre-wired inverter stations to reduce on-site civil works duration. This approach is compressing traditional 18-month construction windows into 10-14 month execution phases.
Thailand's Energy Regulatory Commission has tightened grid code compliance testing protocols for synchronous generation assets. The new technical specifications require enhanced frequency ride-through capabilities and reactive power control ranges that exceed previous standards. Combined-cycle and biomass turbine EPC contractors are responding by embedding factory acceptance test expansions and extended commissioning periods into project schedules.
Industrial offtakers in Thailand's automotive and electronics sectors are unbundling long-term service agreements from initial EPC contracts. Buyers are negotiating separate predictive maintenance and spare parts procurement arrangements, compressing upfront capital commitments. This pattern is most visible among Japanese and Korean manufacturing joint ventures in the Eastern Economic Corridor.
Thailand Power Generation EPC Market Segmentation
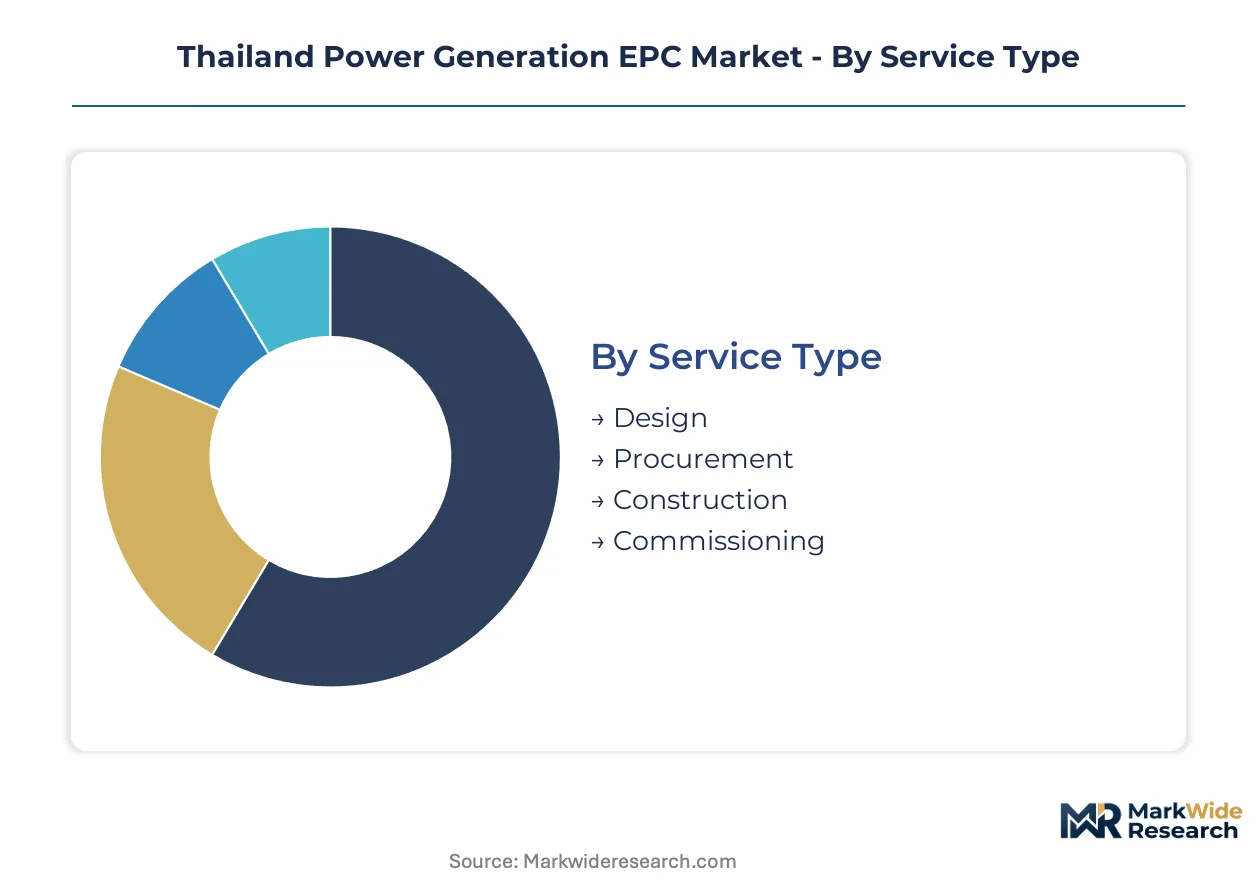
Thailand's power generation EPC market segments along four operational dimensions that determine contractor qualification requirements and margin profiles. Service type and technology selection drive capital deployment intensity, while end user and project size shape risk allocation structures across the procurement lifecycle.
Service Type:
Capital intensity peaks in integrated multi-service contracts that bundle engineering accountability with long-term performance guarantees.
- Design:Front-end engineering packages establish plant performance baselines through heat balance modeling and equipment specification. Thailand's Energy Regulatory Commission mandates domestic engineering participation for projects exceeding 100 MW, concentrating demand around Bangkok-based design firms with utility pre-qualification status.
- Procurement:Long-lead equipment sourcing commands the highest working capital requirements, with gas turbine and generator sets requiring 18-24 month order horizons. State utilities now require documented supply chain transparency for critical rotating equipment, filtering procurement specialists by financial bonding capacity.
- Construction:Civil and mechanical installation absorbs peak labor deployment, with Eastern Economic Corridor projects competing for scarce welders and electrical technicians certified to Thai industrial standards.
- Commissioning:Grid synchronization and performance testing services carry premium margins tied to availability guarantee enforcement. Tightened frequency ride-through requirements are extending commissioning durations for combined-cycle assets.
Most installed capacity flows through Construction. Expansion is steepest in Commissioning.
Technology:
Technology choice determines equipment supply chain complexity and domestic content compliance burden.
- Gas Turbine:Combined-cycle configurations anchor baseload reliability for Eastern Economic Corridor industrial clusters. Heavy frame turbines require specialized rotor handling and foreign OEM technical supervision, concentrating EPC awards among consortia with proven Japanese or German manufacturer relationships.
- Solar:Utility-scale and distributed photovoltaic installations dominate renewable procurement volume under feed-in tariff revisions. Floating solar on Thai reservoirs and rooftop industrial systems in Samut Prakan are gaining developer interest for shortened permitting timelines.
- Biomass:Agricultural residue and energy crop combustion systems serve provincial industrial heat and power demand. Department of Alternative Energy Development and Efficiency sustainability certification requirements are extending pre-construction approval cycles.
- Wind:Onshore turbine deployment remains limited by Thailand's moderate wind resource profile, with activity concentrated in Nakhon Ratchasima and Chaiyaphum highland zones.
Gas Turbine retains dominant value share. Solar is gaining share fastest.
End User:
Customer type dictates contract structure, payment security, and operational performance specifications.
- Utilities:State-owned generators and distribution utilities drive procurement volume through power purchase agreement frameworks. Domestic content mandates and 15-20 year availability guarantees shape contractor pre-qualification criteria.
- Industrial:Petrochemical, automotive, and electronics manufacturers in Rayong and Chonburi provinces invest in captive power for supply reliability. Japanese and Korean manufacturing joint ventures are unbundling long-term service agreements from initial EPC contracts.
- Commercial:Shopping centers, hospitals, and data centers deploy distributed generation for tariff arbitrage and backup security.
- Residential:Rooftop solar installations represent fragmented, low-margin volume for small-scale EPC specialists.
Utilities command the largest project scale. Industrial applications are climbing the fastest.
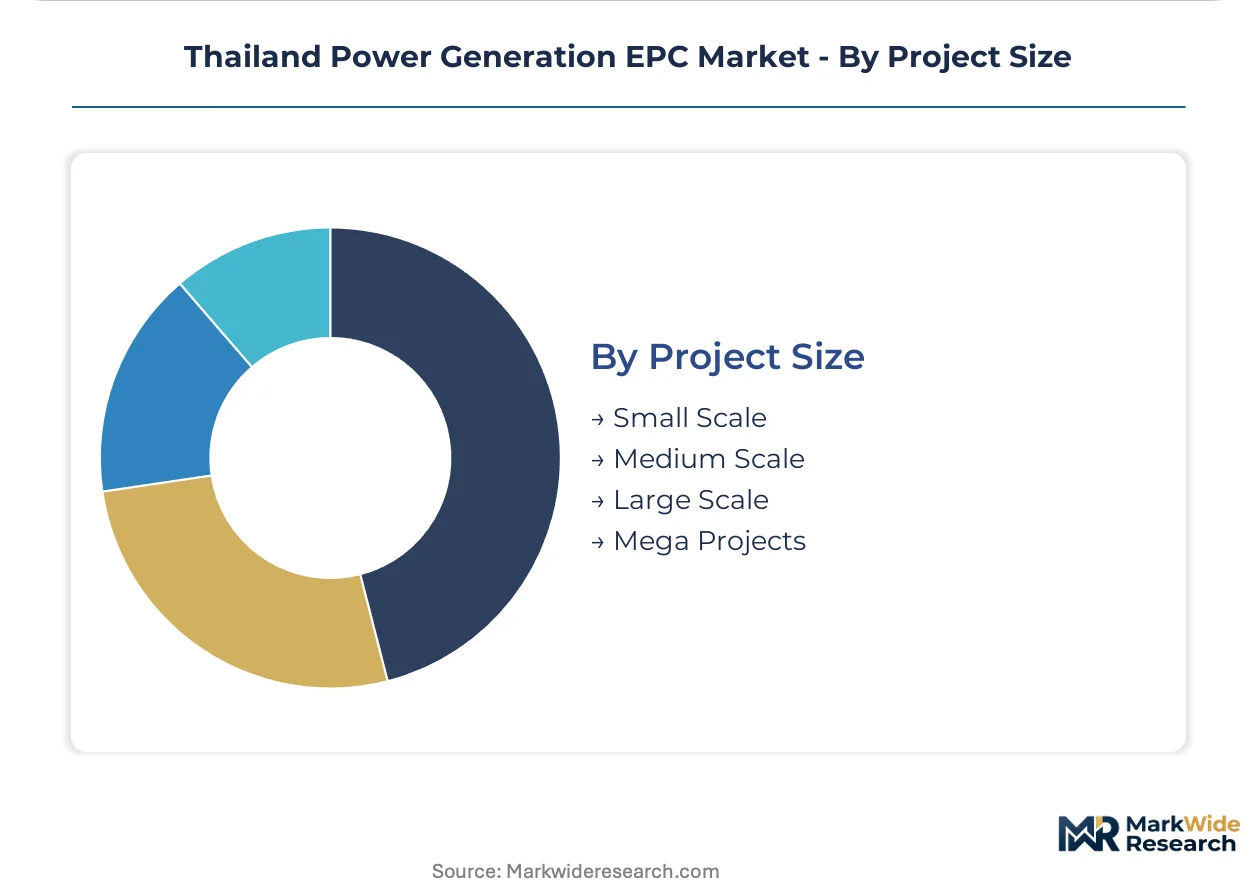
Project Size:
Scale tier determines consortium structure requirements and financial closure complexity.
- Mega Projects:Installations exceeding 1,000 MW require synchronized equity, debt, and EPC execution that few Thai contractors have managed end-to-end. State utility procurement concentrates risk capital among proven international consortia.
- Large Scale:300-1,000 MW combined-cycle and utility solar developments represent the core revenue base for established EPC players with integrated design-build capabilities.
- Medium Scale:50-300 MW industrial captive plants and distributed renewable clusters attract mid-tier contractors with regional execution track records.
- Small Scale:Sub-50 MW commercial and residential systems fragment procurement among local installation specialists with limited balance sheet capacity.
Large Scale absorbs majority capital deployment. Medium Scale is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's geothermal EPC pipeline rivals Thailand's solar expansion in Southeast Asian contractor attention, though Vietnam's offshore wind auctions have drawn more international consortium interest than either market.
Bangkok Metropolitan Region
Captive power demand from automotive electronics plants in Samut Prakan and Pathum Thani drives distributed solar procurement. Thailand's Energy Regulatory Commission enforces domestic content thresholds for projects exceeding 50 MW. Floating solar installations on reservoirs surrounding the capital are compressing permitting timelines compared to land-based alternatives.
Eastern Economic Corridor
Petrochemical complexes in Rayong and Chonburi provinces anchor combined-cycle baseload investments with 24-hour reliability requirements. The Board of Investment's tax incentive packages for energy-intensive manufacturing redirect EPC contractor pre-qualification toward hybrid renewable-gas configurations. Japanese and Korean automotive joint ventures in Chonburi are unbundling long-term service agreements from initial construction contracts.
Central Plains
Rice husk and bagasse biomass facilities serve provincial food processing clusters in Suphan Buri and Nakhon Pathom. The Department of Alternative Energy Development and Efficiency's sustainability certification requirements extend pre-construction approval cycles by 8-14 months. Agricultural residue supply chain consolidation around mill complexes is concentrating EPC awards among contractors with feedstock logistics expertise.
Northeastern Highlands
Moderate wind resources in Nakhon Ratchasima and Chaiyaphum provinces attract niche turbine deployments below 100 MW scale. The Power Development Plan's transmission corridor extensions into the region are unlocking previously constrained project sites. Local cement and mining operations are piloting hybrid wind-solar captive plants to offset diesel generator dependence.
Southern Peninsula
Gas turbine maintenance and upgrade cycles at Songkhla and Surat Thani industrial zones sustain aftermarket EPC revenue streams. The Ministry of Energy's island grid stability programs prioritize distributed generation with frequency response capabilities. Rubber processing cooperatives in Krabi and Trang are evaluating small-scale biomass gasification for off-grid factory supply.
Thailand Power Generation EPC Market Competitive Landscape
Top-tier vendors anchor integrated design-build contracts with full commissioning accountability, while commodity specialists fragment across single-service procurement. The market structure concentrates risk capital among consortia with proven financial closure track records for mega-projects. Three archetypes dominate: Japanese heavy industrial conglomerates with gas turbine OEM relationships, Thai renewable specialists leveraging regulatory familiarity, and global contractors scaling hydrogen-ready platforms. Competitive positioning hardens through strategic partnerships with state utilities and technology licensing arrangements for carbon capture integration.
Within the heavy industrial tier, Mitsubishi Heavy Industries, Ltd. and Toshiba Corporation represent Japanese conglomerates with established OEM technical supervision networks. BCPG PCL exemplifies domestic renewable specialists competing through regulatory pre-qualification depth. General Electric Company occupies a position among global contractors sustaining supply chain scale across gas and emerging hydrogen-blending turbine platforms. These three anchors illustrate how contractor selection filters toward proven grid synchronization capabilities and domestic content compliance.
| Leading Market Players |
|---|
| Black & Veatch Corporation |
| BCPG PCL |
| General Electric Company |
| DP Cleantech Group |
| Toshiba Corporation |
| Mitsubishi Heavy Industries, Ltd. |
| Electricity Generation Authority of Thailand |
| Grimm Power Public Company Limited |
| Marubeni Corporation |
| Others |
Value Network & Pricing Analysis
Welder and electrical technician shortages across Thailand's Eastern Economic Corridor widen pricing spreads between premium integrated contracts and commodity single-service procurement. Labor-cost differentials between Bangkok-certified specialists and provincial crews translate into tiered EPC quotations that separate guaranteed availability packages from basic construction-only awards.
Pricing Analysis
The bundled-vs-unbundled service split defines Thailand's EPC pricing architecture. Integrated design-build-commissioning contracts with 15-20 year availability guarantees command premium positioning against fragmented single-service awards. Price differentiation rests on domestic content compliance depth and grid synchronization certification tier. Pricing pressure stems from steel and copper input volatility forcing fixed-contract renegotiations. State utilities demonstrate lowest price sensitivity due to PPA-backed payment security, while small-scale commercial developers squeeze mid-tier contractors on upfront capital commitments.
Supply Chain Analysis
Freight costs for heavy gas turbine rotors and generator sets from Japan and Germany anchor landed equipment premiums for combined-cycle projects. Geographic supply concentration centers on Japanese and German OEMs for heavy frame turbines, Chinese manufacturers for solar PV components, and domestic mill complexes for biomass feedstock. Raw material dependencies span specialty steel alloys, copper windings, and high-grade concrete additives. Single-source vulnerability for critical rotating equipment creates procurement bottlenecks. Distribution runs through state utility tender frameworks and industrial captive power direct negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's power generation EPC market represents a late-cycle quality story as carbon neutrality commitments and tightened grid codes elevate technical specification thresholds. Developer demand is shifting toward hydrogen-ready turbine platforms and predictive maintenance bundling that rewards proven commissioning track records.
For Market Incumbents: Deploy performance-based O&M bundling as the primary defensive lever. Extend commissioning accountability into 15-20 year availability guarantees to lock out commodity competitors. Deepen relationships with the Electricity Generation Authority of Thailand through domestic content compliance investments that filter pre-qualification pools. Counter emerging renewable specialists by anchoring integrated design-build capabilities with full financial closure coordination. For New Entrants and Emerging Players: Digital-channel routes through industrial offtaker direct procurement offer white-space penetration outside state utility tender congestion. Target Greater Bangkok distributed solar installations in Samut Prakan and Pathum Thani industrial zones where permitting timelines compress against land-based alternatives. Pursue floating solar specialization on Thai reservoirs to bypass land acquisition bottlenecks. Lead with modular containerized PV and battery storage systems that reduce on-site civil works duration. For Investors and Strategic Acquirers: Japanese heavy industrial conglomerates are the most active acquirer in this space, seeking EPC capabilities to anchor regional gas turbine maintenance and hydrogen retrofit pipelines. Long-term viability over the coming decade hinges on carbon capture integration expertise and regulatory pre-qualification depth. Acquisition targets should display proven financial closure track records for mega-projects and established OEM technical supervision networks. Monitor Thailand's Power Development Plan revision cycles as the critical inflection signal for pipeline redirection toward hybrid renewable-gas configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Retrofit | Positions contractors for Thailand's 2050 carbon neutrality compliance and hydrogen blending mandates. |
| Performance-Based O&M Bundling | Captures 15-20 year revenue streams through availability guarantees tied to predictive maintenance platforms. |
| Domestic Content Compliance Investment | Secures pre-qualification status for projects exceeding 100 MW under Energy Regulatory Commission mandates. |
| Floating Solar Specialization | Exploits compressed permitting timelines on Thai reservoirs surrounding Bangkok metropolitan demand clusters. |
| Modular Prefabrication Adoption | Compresses 18-month construction windows to 10-14 months through manufacturing-derived project controls. |
Research Methodology
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, grid operators, and fuel supply specialists grounded qualitative findings in operational reality. Primary intelligence combined with secondary validation from Thailand's Energy Regulatory Commission procurement disclosures, Department of Alternative Energy Development and Efficiency certification records, Power Development Plan documentation, and industrial zone investment board filings. Bottom-up project pipeline aggregation and top-down macroeconomic triangulation cross-verified market sizing assumptions.
Segmented outputs across service type, technology, end user, and project scale dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from installed capacity buildout trajectories, feed-in tariff revision impacts, and Eastern Economic Corridor industrialization pacing. Forecast inputs incorporated steel and copper price volatility scenarios, biomass feedstock certification timeline distributions, and grid code compliance engineering scarcity effects.
Raw material cost spikes, regulatory approval delays, and specialized workforce availability constraints are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding state utility procurement velocity and industrial captive power investment cycles. A model refresh is warranted upon material change in Thailand's Power Development Plan revision schedule or carbon neutrality implementation pathway.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Europe Distributed Power Generation Market
Power Generation
Indonesia Power Market
Power Generation
Power Plant EPC Market
Power Generation
Global Power Grid System Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
India Thermal Power Plant Market
Power Generation
Power Generation Technologies Market
Power Generation
Venezuela Power Market
Power Generation
Thermal Power Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Solar Generator Market
Power Generation
South America Thermal Power Market
Power Generation
Marine Power Plant Market
Power Generation
Vietnam Power Generation EPC Market
Power Generation
Stirling Engine Market
Power Generation
Japan Combined Heat and Power Market