
 Global Power Generation Market | 2026-2036
Global Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Generation Market Outlook
Chinese state-owned utilities is hardening their grip on global coal and renewable capacity additions. Siemens leverages its turbine manufacturing scale across European and Asian grids. NextEra Energy anchors its position through utility-scale solar and battery storage dominance in North America. TotalEnergies competes by extending its offshore wind development pipeline across multiple basins.
Power generation encompasses the conversion of primary energy sources into electrical power through thermal combustion, nuclear fission, photovoltaic conversion, or kinetic energy capture, typically operating at voltages from 11 kV to 765 kV for grid transmission to serve industrial, commercial, and residential loads. Hydropower retains the largest installed base among technology categories while solar leads new capacity additions. Thermal generation occupies the mature margin pool in conventional markets. Distributed installation is gaining share as commercial and residential end users deploy rooftop solar and behind-the-meter storage.
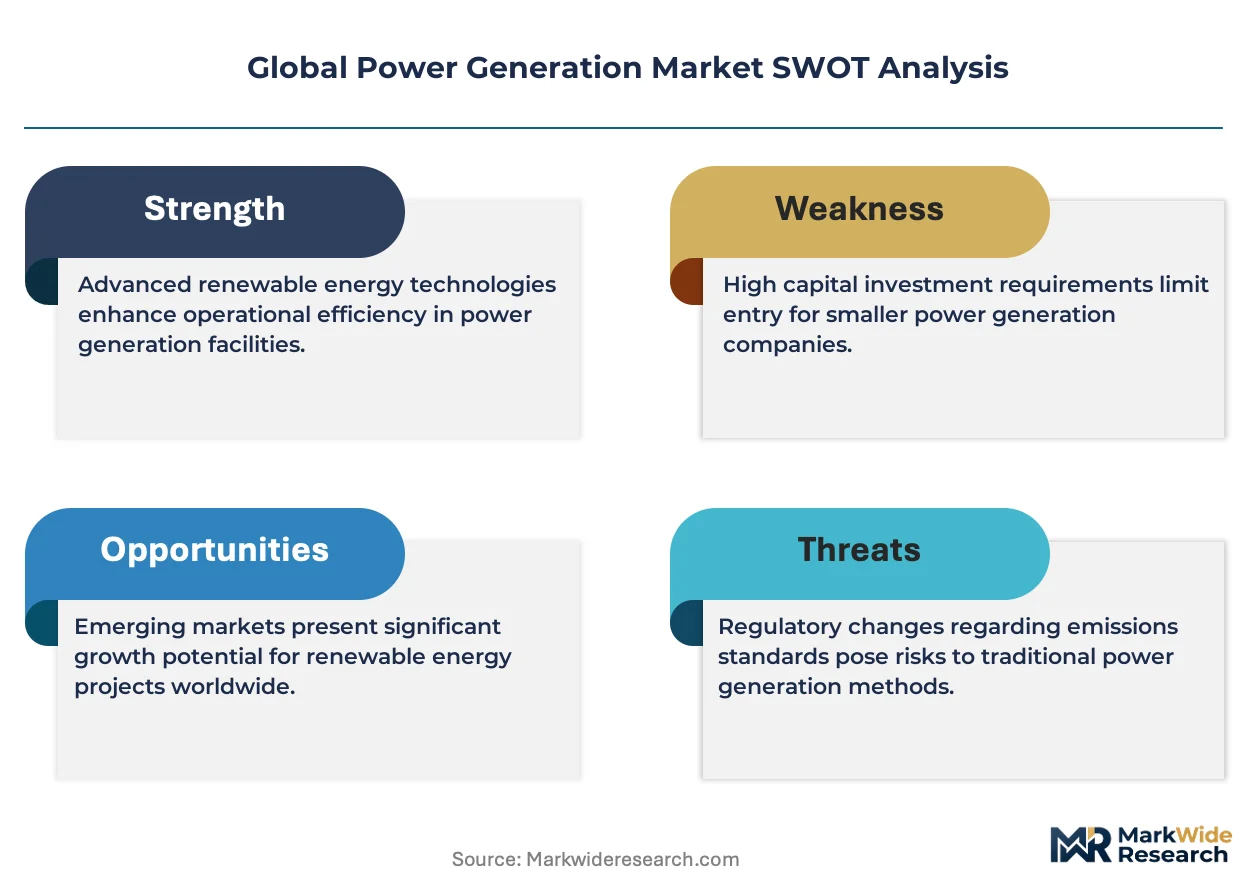
The EPA enforces emissions standards that force coal plant retirements across the United States. EMA and REACH in Europe mandate efficiency benchmarks and chemical safety protocols for generation equipment. China's MEE implements dual carbon goals that restrict new coal permits and accelerate renewable quotas. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustments reshape equipment sourcing and power export competitiveness.
Market Dynamics
Data center electricity procurement is compressing development timelines across multiple continents, forcing generators to restructure offtake contracts around 24/7 clean power matching rather than annual renewable energy credits.
Growth Catalysts
- EU Green Deal carbon border adjustments:European importers now face embedded emissions tariffs, accelerating coal-to-renewable conversions in supplier countries.
- India's PLI scheme for solar manufacturing:Production-linked incentives are scaling domestic photovoltaic module output, reducing import dependency for utility-scale projects.
- Offshore wind technology maturation:Turbine sizes exceeding 15 MW are unlocking deeper water sites in the North Sea and East Asian basins.
Market Restraints
- Critical mineral supply concentration:Cobalt and rare earth processing remains concentrated in China, creating vulnerability for battery storage and permanent magnet generators.
- Interconnection queue backlogs:Grid connection delays in the United States now average 3-5 years for new renewable projects, freezing capital deployment.
- Baseload displacement physics:Wind and solar variability without sufficient long-duration storage forces thermal plant cycling that degrades efficiency and accelerates maintenance costs.
Strategic Opportunities
- Green hydrogen offtake contracts:Industrial clusters in Germany and the Netherlands are signing power purchase agreements tied to electrolyzer operations, creating new demand anchors.
- Behind-the-meter commercial storage:Retail electricity rate structures in California and Australia are making on-site battery economics viable for large manufacturing facilities.
- Grid-enhancing technologies:Dynamic line rating and topology optimization software can unlock 20-40% additional transmission capacity without new infrastructure permitting.
Industry Challenges
- High-voltage transformer manufacturing bottleneck:Lead times for 765 kV grid infrastructure now exceed 24 months due to specialized steel and copper winding capacity constraints.
- Grid code harmonization complexity:Inverter-based resources must comply with divergent fault-ride-through requirements across ISOs, multiplying certification costs for equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Generation Market |
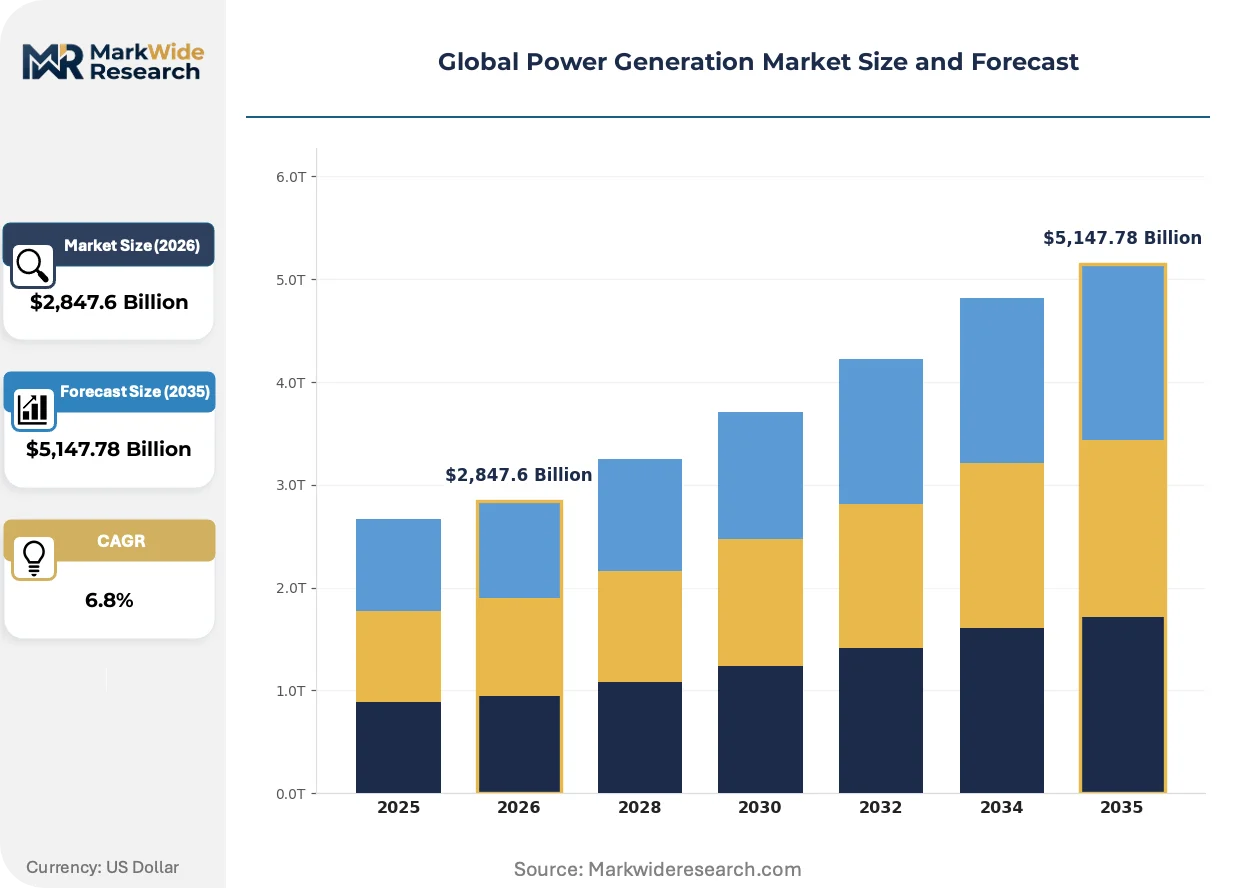
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $5,147.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-Renewable, Nuclear, Conventional Technology: Hydropower, Wind, Solar, Thermal Installation: Onshore, Offshore, Distributed, Centralized End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | GE, Siemens, NextEra Energy, China Shenhua Energy, TotalEnergies, Shell, PetroChina, ExxonMobil, Chevron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Generation Market Strategic Shifts
Power generation technology trajectories are diverging between mature markets optimizing existing infrastructure and emerging economies building clean capacity without legacy asset burdens.
Perovskite tandem solar cell architectures are expanding into utility-scale deployment after years of laboratory promise. NextEra Energy and other IPPs are piloting bifacial perovskite-silicon stacks that push module efficiency beyond 26% in high-irradiance conditions. This technology is expanding into previously marginal sites where conventional silicon economics failed, compressing land requirements for gigawatt-scale solar complexes.
China's MEE dual carbon enforcement mechanisms are tightening coal plant utilization hour caps while accelerating provincial renewable portfolio mandates. Industrial users in Jiangsu and Guangdong provinces now face mandatory green power procurement quotas or production curtailments. Heavy electricity consumers are responding by contracting directly with offshore wind developers, bypassing state grid intermediaries.
Corporate buyers are restructuring power purchase agreements around 24/7 carbon-free energy matching rather than annual volumetric accounting. Data center operators in Northern Virginia and Frankfurt are demanding hourly synchronization of generation with load, forcing developers to bundle solar with battery storage or geothermal baseload. This pattern is most visible in markets with granular emissions tracking infrastructure and large technology sector procurement teams.
Global Power Generation Market Segmentation
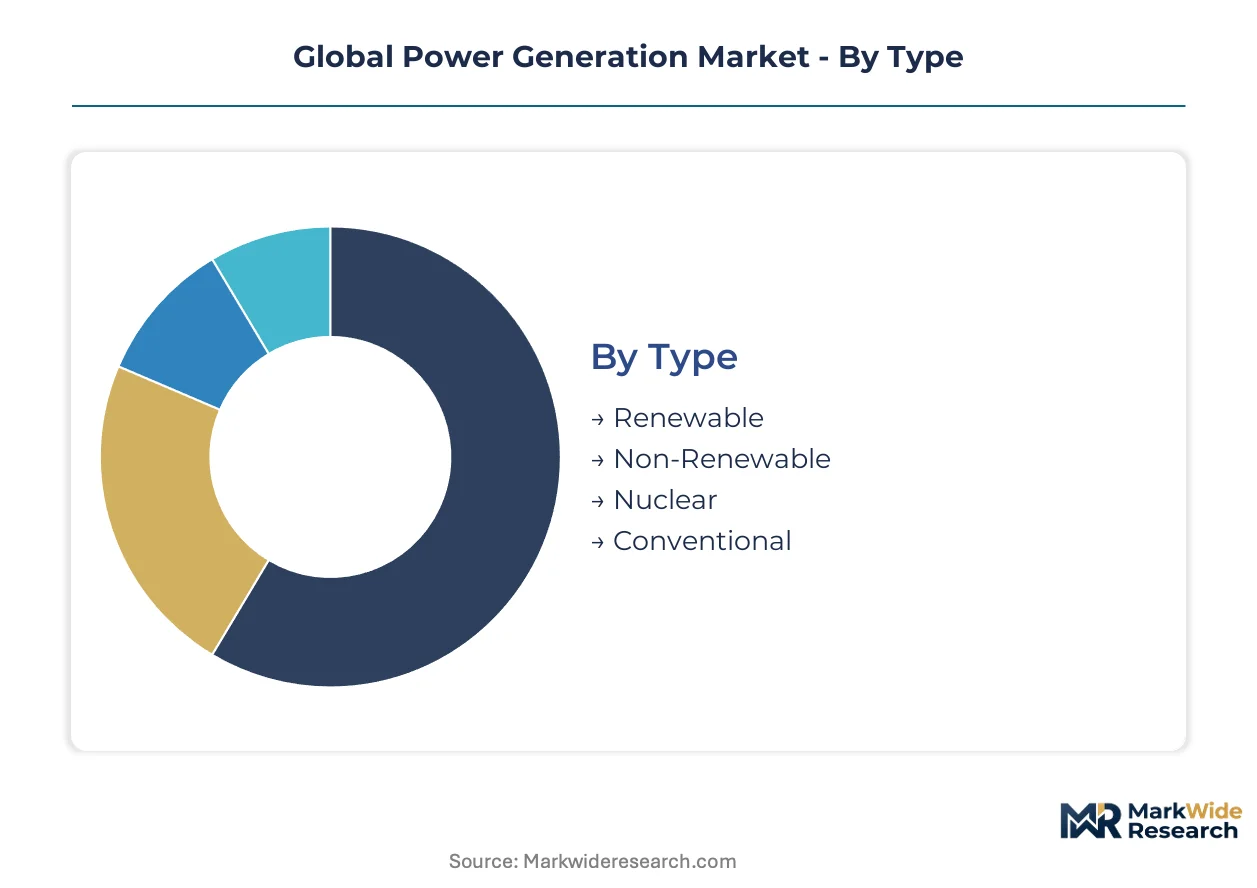
Power generation markets fragment across multiple technical and commercial dimensions that determine equipment specifications, financing structures, and regulatory exposure. Buyers in each segment face distinct interconnection timelines, fuel price volatility, and carbon accounting requirements that reshape procurement priorities.
Type:
Cost tier differentiation separates baseload-dependent buyers from those seeking price stability through zero-fuel technologies.
- Renewable:Solar photovoltaic and wind assets dominate new capacity additions with zero marginal generation costs. Data center operators in Northern Virginia and Frankfurt are contracting 24/7 clean power matching that forces developers to bundle solar with battery storage or geothermal baseload.
- Non-Renewable:Coal and natural gas plants provide dispatchable capacity where grid flexibility remains constrained. China's MEE dual carbon enforcement mechanisms are tightening coal plant utilization hour caps while accelerating provincial renewable portfolio mandates.
- Nuclear:Fission reactors deliver carbon-free baseload with capacity factors exceeding 90%. Regulatory approval timelines in the United States and France extend construction schedules beyond a decade.
- Conventional:Oil-fired peaking plants serve remote grids and emergency reserves. Caribbean island utilities and Arctic communities maintain these assets for seasonal demand spikes.
Non-Renewable leads volumes today; Renewable is gaining share fastest.
Technology:
Application context determines whether projects prioritize land efficiency, water access, or dispatchability.
- Hydropower:Retains the largest installed base globally with pumped-storage variants providing grid-balancing services. Norwegian and Brazilian utilities leverage alpine and Amazon basin topography for multi-gigawatt complexes.
- Wind:Turbine sizes exceeding 15 MW are unlocking deeper water sites in the North Sea and East Asian basins. Ørsted and Equinor are deploying floating platforms off Scotland and South Korea where seabed depths exceed 60 meters.
- Solar:Perovskite tandem architectures are pushing module efficiency beyond 26% in high-irradiance conditions. NextEra Energy and other IPPs are piloting bifacial perovskite-silicon stacks that expand into previously marginal sites.
- Thermal:Combined-cycle gas turbines occupy the mature margin pool in conventional markets. Siemens leverages its turbine manufacturing scale across European and Asian grids.
Hydropower anchors installed capacity; Solar exhibits the steepest expansion trajectory.
Installation:
Customer type and grid access shape whether projects connect at transmission voltage or serve behind-the-meter loads.
- Onshore:Land-based wind and solar farms connect directly to high-voltage transmission networks. Interconnection queue backlogs in the United States now average 3-5 years for new renewable projects.
- Offshore:Marine installations exploit stronger, steadier wind resources without land-use conflicts. China's state-owned utilities are hardening their grip on global offshore wind capacity additions across multiple basins.
- Distributed:Rooftop solar and behind-the-meter storage serve commercial and residential end users. Retail electricity rate structures in California and Australia are making on-site battery economics viable for large manufacturing facilities.
- Centralized:Utility-scale plants feed bulk power into national grids at voltages from 11 kV to 765 kV. Lead times for 765 kV grid infrastructure now exceed 24 months due to specialized steel and copper winding capacity constraints.
Centralized dominates current output; Distributed is climbing the fastest.
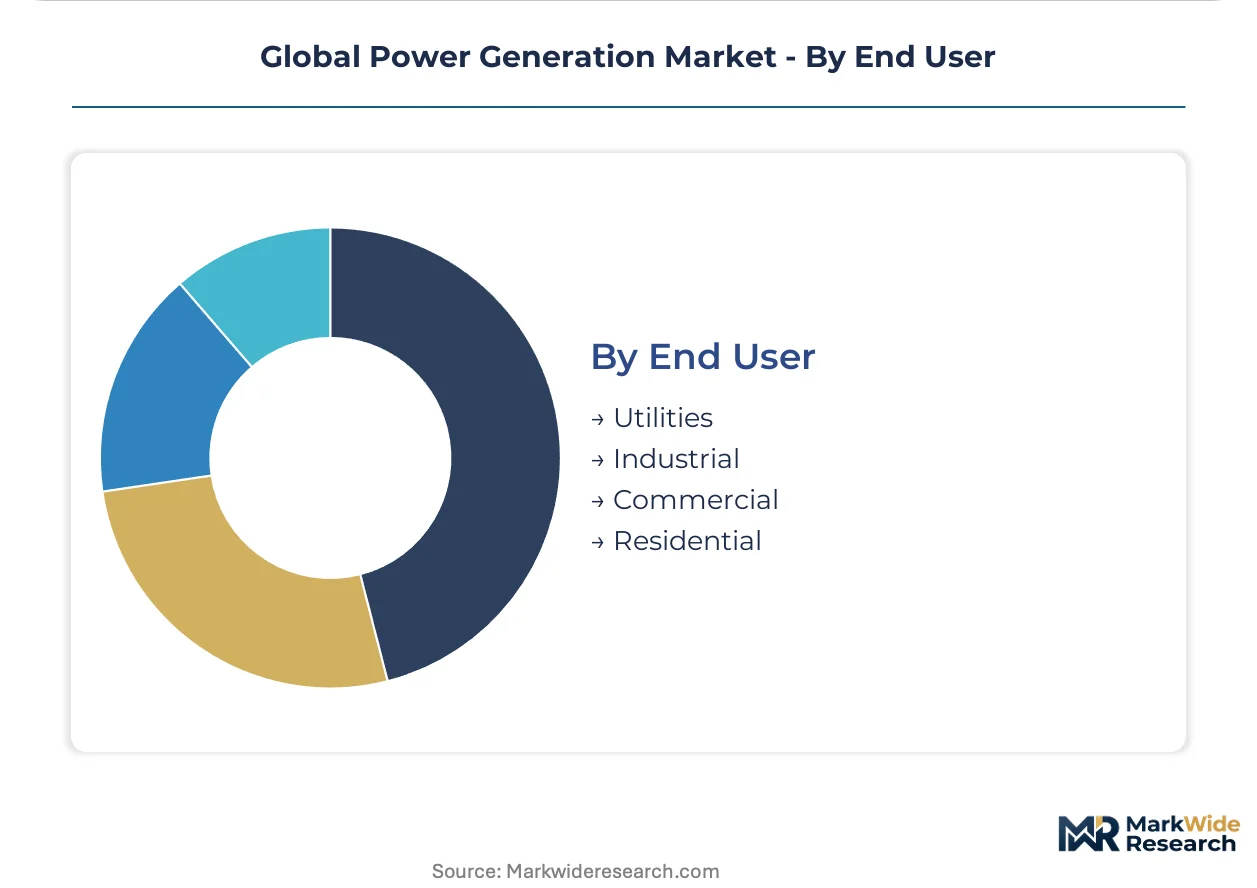
End User:
Volume scale and creditworthiness determine offtake contract structures and development risk allocation.
- Utilities:Vertically integrated power companies procure generation to meet regulated load obligations. State grid intermediaries in Jiangsu and Guangdong provinces face bypass as industrial users contract directly with offshore wind developers.
- Industrial:Heavy electricity consumers seek price hedges and carbon compliance for manufacturing operations. German and Dutch industrial clusters are signing power purchase agreements tied to electrolyzer operations for green hydrogen production.
- Commercial:Data center operators, retailers, and office complexes procure renewable energy certificates and physical power. Northern Virginia and Frankfurt data center markets are compressing development timelines across multiple continents.
- Residential:Homeowners deploy rooftop solar with net metering arrangements. Australia's high retail electricity tariffs have driven residential battery adoption rates exceeding most developed markets.
Utilities transact the largest volumes; Industrial procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping capacity investment flows as developers migrate toward jurisdictions with faster permitting timelines and weaker carbon compliance costs. China's MEE dual carbon enforcement and India's PLI manufacturing subsidies are compressing project economics in Asia relative to European REACH and EU Green Deal stringency.
United States
Data center load growth in Northern Virginia and Texas is forcing 24/7 clean power matching requirements into offtake contracts. EPA emissions standards accelerate coal plant retirements across the Midwest and Southeast. Grid interconnection queues now average 3-5 years, freezing capital deployment in ERCOT and PJM territories.
China
Provincial renewable portfolio mandates in Jiangsu and Guangdong provinces now carry mandatory green power procurement quotas for industrial users. MEE dual carbon enforcement mechanisms tighten coal plant utilization hour caps while accelerating offshore wind development. State-owned utilities harden control over gigawatt-scale solar and wind complex deployment across multiple coastal basins.
Germany
Industrial clusters in the Rhine-Ruhr and Hamburg regions are signing power purchase agreements tied to electrolyzer operations for green hydrogen production. EU Green Deal carbon border adjustments force coal-to-renewable conversions in supplier-facing energy-intensive industries. Offshore wind development in the North Sea exploits turbine sizes exceeding 15 MW at deeper water sites.
India
Gujarat and Rajasthan states concentrate utility-scale solar deployment leveraging high irradiance and available land banks. PLI scheme production-linked incentives scale domestic photovoltaic module output, reducing import dependency. Central Electricity Authority mandates are accelerating renewable purchase obligations for discoms in Maharashtra and Karnataka.
Brazil
Amazon basin topography supports multi-gigawatt hydropower complexes with pumped-storage variants providing grid-balancing services. ANEEL regulatory frameworks govern distributed generation net metering for commercial and residential rooftop solar in São Paulo and Minas Gerais. Bioelectricity from sugarcane bagasse anchors dispatchable renewable capacity in the Southeast region.
Global Power Generation Market Competitive Environment
Chinese state-owned utilities anchor one tier through integrated coal and renewable capacity control; European turbine manufacturers and North American independent power producers hold specialized positions in technology licensing and utility-scale development. Market structure tilts toward consolidated state-backed players in generation ownership while equipment supply fragments across technology-specific niches. Three archetypes dominate: integrated energy majors with fuel-to-wire portfolios, pure-play renewable developers with storage bundling capabilities, and state-owned grid-connected utilities with preferential site access. Competitive moves center on vertical integration into critical mineral supply chains and strategic partnerships for long-duration storage deployment.
Within the integrated energy major tier, TotalEnergies and Shell exemplify offshore wind pipeline extension across multiple basins alongside legacy thermal asset optimization. Among turbine manufacturers, Siemens occupies a position representing European grid-scale equipment supply with manufacturing scale across continental and Asian markets. At the renewable developer end, NextEra Energy anchors North American utility-scale solar and battery storage dominance through bundled offtake structures.
| Leading Market Players |
|---|
| GE |
| Siemens |
| NextEra Energy |
| China Shenhua Energy |
| TotalEnergies |
| Shell |
| PetroChina |
| ExxonMobil |
| Chevron |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon border adjustments gate qualified supply for European grid equipment and anchor premium-tier pricing access for certified low-carbon generation assets. This environmental mandate compresses margins for uncertified manufacturers while rewarding vertically integrated developers with validated supply chains.
Pricing Analysis
Distributor margins for turbine components and solar modules typically range 8-15% before installation services. Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation resting on module efficiency tier and grid-code certification level. Pricing pressure stems from polysilicon cost compression in China and module oversupply. Industrial offtakers in Germany and India exhibit highest price sensitivity; data center operators in Northern Virginia demonstrate lowest sensitivity due to 24/7 clean power matching requirements.
Supply Chain Analysis
Specialized electrical steel winding and rare earth magnet manufacturing face acute workforce constraints in China, Vietnam, and Germany. Permanent magnet generators for offshore wind draw from neodymium processing concentrated in China and Myanmar. Single-source vulnerability for high-voltage transformer cores creates structural risk given 24-month fabrication timelines. Distribution runs through state grid intermediaries in China and India, direct EPC contracting in the United States, and developer-led procurement in European offshore wind basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where developers exploit the cost differential between China's streamlined MEE permitting and Europe's REACH chemical compliance burdens.
For Market Incumbents: Lock in critical mineral offtake through backward integration into rare earth processing or long-term cobalt supply agreements. State-owned utilities in China must defend against industrial user bypass in Jiangsu and Guangdong by accelerating direct contracting platforms. Siemens and Vestas should prioritize grid-code certification investment to maintain European turbine pricing power.
For New Entrants and Emerging Players: Capture behind-the-meter commercial storage deployment in California and Australia where retail rate structures support viable battery economics. Distributed generation in Brazil's São Paulo and Minas Gerais states offers the most penetrable entry point given ANEEL net metering frameworks. Pursue green hydrogen offtake partnerships with German industrial clusters as anchor demand.
For Investors and Strategic Acquirers: Roll-up economics work for pure-play renewable developers with storage bundling capabilities because interconnection queue backlogs in the United States freeze capital deployment for uncontracted projects. Target acquisition archetypes include IPPs with secured site control and permitted offshore wind pipelines. Monitor FERC interconnection rulemaking and MEE dual carbon enforcement intensity as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Restructuring | 24/7 clean power matching in Northern Virginia and Frankfurt compresses developer timelines. |
| Backward Integration into Critical Minerals | Cobalt and rare earth supply security hedges against China's processing concentration. |
| Grid-Enhancing Technology Deployment | Dynamic line rating unlocks 20-40% transmission capacity without new permitting. |
| Green Hydrogen Offtake Contracting | German and Dutch electrolyzer operations create new demand anchors for renewable baseload. |
| Perovskite Tandem Manufacturing Scale-Up | NextEra Energy pilots push module efficiency beyond 26% in high-irradiance conditions. |
Study Parameters
Coverage spans China, the United States, Germany, India, and Brazil, with primary inputs from each region's stakeholder base. The study combines interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition tracking and top-down macroeconomic modeling triangulate market size estimates.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. The analytical framework models segmentation by fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from fitted growth curves applied to announced project pipelines and interconnection queue data. Forecast inputs include data center load growth trajectories and provincial renewable portfolio mandate enforcement intensity.
Policy reversals, interconnection queue reform, and critical mineral export restrictions are the dominant revision risks to the outlook. Forecasts reflect assumptions about continued MEE dual carbon enforcement and sustained IRA incentive structures. Practitioners should monitor FERC interconnection rulemaking and China's rare earth processing quota announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
North America Distributed Power Generation Market
Power Generation
India Gensets Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Micro CHP Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Solar Generator Market
Power Generation
Microturbine Market
Power Generation
Variable Speed Generator Market
Power Generation
Indonesia Power Market
Power Generation
Algeria Power Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Venezuela Power Market
Power Generation
India Gas Generator Market
Power Generation
Gas Gensets Market
Power Generation
Wind Power EPC Market