
 Combined Cycle Gas Turbine Market | 2026-2036
Combined Cycle Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Combined Cycle Gas Turbine Market Analysis
Independent power producers is unwinding the historical dominance of utility-owned generation fleets in procurement decisions. General Electric leverages its HA-class turbine platform to anchor large-scale projects across North American independent power channels. Siemens competes through integrated plant solutions that bundle gas turbines with heat recovery systems and digital controls. Mitsubishi Heavy Industries sustains its position in Asian markets through manufacturing scale and localized assembly footprints.
A combined cycle gas turbine integrates a gas turbine with a heat recovery steam generator and steam turbine to extract energy from exhaust heat, achieving thermal efficiencies exceeding 60 percent in advanced configurations. The assembly converts natural gas or hydrogen blends into electricity through sequential Brayton and Rankine cycles, serving baseload and peaking roles in modern grids. Gas turbines occupy the dominant value share within product type segmentation due to precision manufacturing requirements and material intensity in blade and combustor components. Multi-shaft configurations lead technology segmentation for large utility applications, while single-shaft designs gain traction in industrial cogeneration settings where footprint constraints matter.
FERC interconnection rules in the United States shape market access timelines and grid stability obligations for new combined cycle entrants. EPA emissions standards and evolving hydrogen blending mandates in Europe force combustor redesigns and material upgrades across manufacturer portfolios. India's CEA technical standards for grid-connected thermal plants dictate efficiency floors and emission control requirements for domestic installations. Stakeholders must monitor regulatory divergence on hydrogen readiness timelines to avoid stranded asset risk in turbine procurement cycles.
Market Dynamics
Grid operators worldwide face mounting pressure to firm intermittent renewable capacity, forcing combined cycle gas turbine procurement toward hydrogen-ready configurations and rapid-start flexibility rather than pure baseload economics.
Growth Catalysts
- India CEA Efficiency Mandates:India's Central Electricity Authority mandates minimum thermal efficiency thresholds for new thermal installations, compelling state power boards to retire subcritical coal units in favor of advanced combined cycle blocks.
- Asia-Pacific Renewable Integration:Utility procurement departments across Thailand, Vietnam, and the Philippines are ordering gas turbines specifically for grid stabilization services as solar and wind penetration exceeds 25% in several provincial networks.
- Hydrogen Co-firing Standards:Evolving hydrogen blending requirements in the European Union and United States are accelerating combustor retrofit programs and new equipment specifications that accommodate 30% hydrogen by volume.
Market Restraints
- Specialized Alloy Supply Concentration:Precision-cast single-crystal turbine blades rely on nickel-based superalloys sourced from a concentrated supplier base in Germany, Japan, and the United States, exposing lead times to geopolitical friction.
- Natural Gas Price Volatility:Input fuel cost swings in European and Asian spot markets erode project finance assumptions for merchant combined cycle plants, compressing equity returns below hurdle rates in several jurisdictions.
- Utility-Scale Battery Substitution:Four-hour lithium-ion battery installations are capturing peak-shaving and frequency regulation contracts previously awarded to gas turbine peakers in California, Australia, and the United Kingdom.
Strategic Opportunities
- Saudi Arabia Power Sector Privatization:The kingdom's unbundling of generation assets creates openings for independent power producers to develop greenfield combined cycle capacity under long-term offtake structures.
- Industrial Cogeneration Retrofit:Petrochemical complexes and refineries in the United States Gulf Coast are repowering aging steam hosts with single-shaft combined cycle configurations to capture waste heat and reduce carbon intensity.
- EU Carbon Border Adjustment:The CBAM mechanism creates competitive advantage for low-carbon hydrogen production, positioning hydrogen-ready gas turbines as bridge infrastructure for green hydrogen offtake agreements.
Industry Challenges
- Combustor Engineering Talent Scarcity:The specialized workforce capable of designing dry low-NOx combustors for hydrogen blends is concentrated at a handful of OEM engineering centers, constraining product development velocity.
- Interconnection Queue Backlogs:FERC Order 2023 reforms have not eliminated multi-year transmission access delays in the United States, stranding completed turbine installations without revenue commencement.
- Legacy Control System Integration:Digital turbine control upgrades must interface with decades-old distributed control systems at existing power stations, multiplying commissioning complexity and cybersecurity exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combined Cycle Gas Turbine Market |
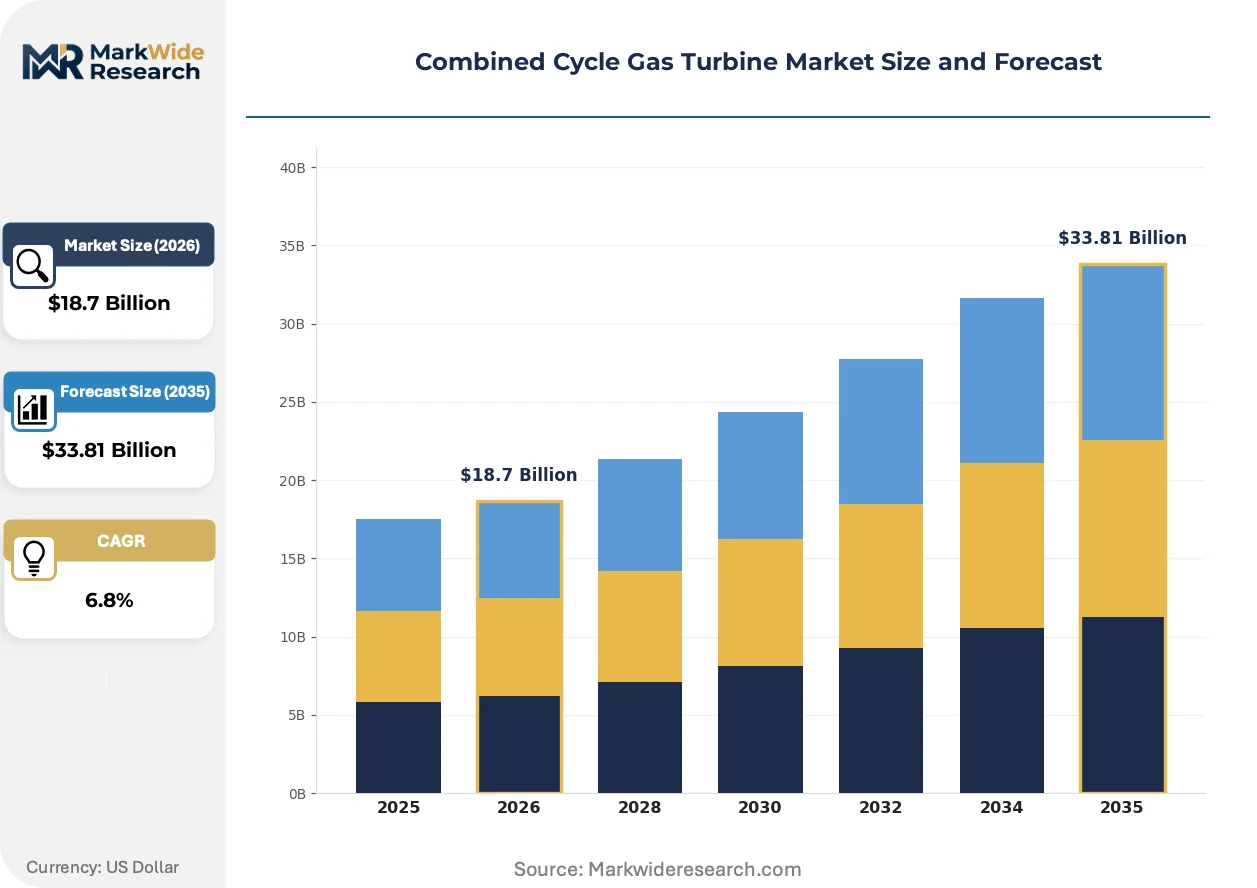
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Turbines, Steam Turbines, Heat Recovery Steam Generators, Auxiliary Systems Application: Power Generation, Industrial Processing, Oil & Gas, Renewable Integration End User: Utilities, Independent Power Producers, Manufacturing, Mining Technology: Single-Shaft, Multi-Shaft, O&M Services, Advanced Control Systems |
| Companies Covered | General Electric, Siemens, Mitsubishi Heavy Industries, Ansaldo Energia, Bharat Heavy Electricals Limited, Doosan, Solar Turbines, MAN Energy Solutions, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combined Cycle Gas Turbine Market Emerging Trajectories
Equipment specifications are bifurcating between hydrogen-ready advanced class turbines for new markets and modular rapid-response units for renewable-balancing roles, with digital twin deployment accelerating across both categories.
Additive manufacturing is decomposing traditional supply chain constraints for turbine hot-section components. Laser powder bed fusion now produces complex internal cooling geometries in nickel superalloy blades that conventional investment casting cannot replicate. Siemens and GE are qualifying additively manufactured combustor liners for field deployment, compressing spare parts lead times from months to weeks while enabling design iterations previously uneconomical at production scale.
EPA carbon rules under Section 111 of the Clean Air Act are forcing fundamental combustor redesigns across manufacturer portfolios. The regulations establish emission intensity benchmarks that effectively require carbon capture readiness or hydrogen co-firing capability for new gas-fired capacity. Combined cycle projects in Texas, Florida, and Ohio are now specifying turbines with 50% hydrogen blending capability as standard, with engineering contracts including future upgrade paths to 100% hydrogen combustion.
Independent power producers are consolidating procurement authority previously dispersed across utility generation departments. Merchant developers in the United States and United Kingdom now specify equipment packages through competitive tender processes that unbundle turbines, heat recovery steam generators, and digital controls, forcing OEMs to compete on component pricing rather than integrated plant solutions. This fragmentation is most visible in Texas ERCOT and the United Kingdom capacity market, where project sponsors prioritize capital efficiency over single-source accountability.
Combined Cycle Gas Turbine Market Segmentation
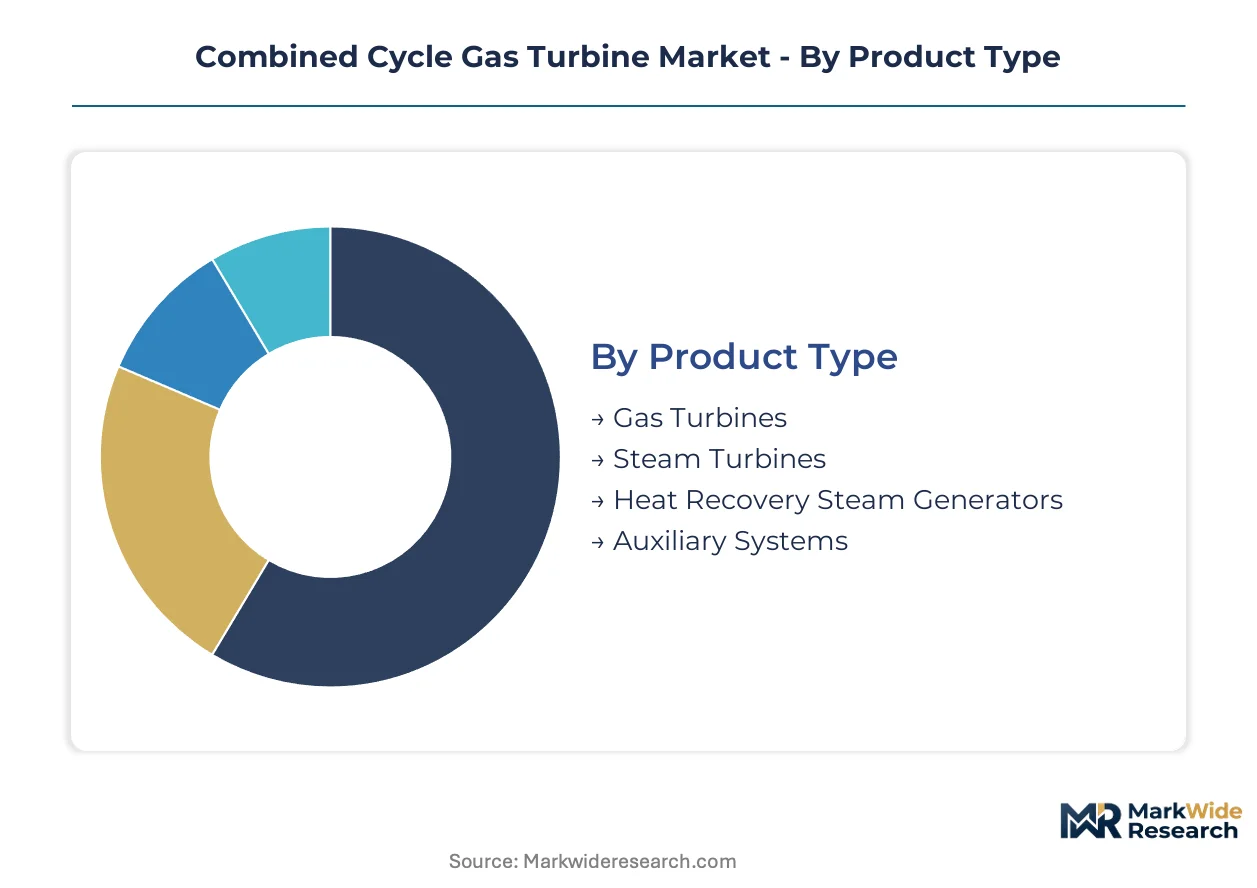
Segmentation in the combined cycle gas turbine market exposes where capital intensity, regulatory pressure, and fuel flexibility requirements concentrate procurement decisions. Equipment buyers prioritize thermal efficiency thresholds and hydrogen readiness over pure nameplate capacity, reshaping vendor pricing power across component categories.
Product Type:
Margin pools concentrate in hot-section components where precision manufacturing and superalloy metallurgy create defensible supplier positions.
- Gas Turbines:Precision-cast single-crystal blades and advanced combustor assemblies convert fuel into mechanical energy through high-temperature Brayton cycles. Demand clusters in India and Saudi Arabia where state power boards and privatized generators specify advanced-class units above 300 MW for grid stabilization duties against renewable intermittency.
- Heat Recovery Steam Generators:These unfired boilers capture exhaust heat from gas turbines to produce steam for secondary power generation. Procurement is accelerating across the United States Gulf Coast as petrochemical complexes repower with single-shaft configurations to capture waste heat and reduce carbon intensity under EPA carbon rules.
- Steam Turbines:Condensing and non-condensing designs extract residual energy from HSG-supplied steam. Rankine cycle equipment sees steady replacement demand in aging European thermal fleets.
- Auxiliary Systems:Fuel skids, inlet air filtration, and cooling packages complete plant integration. These components face price compression from standardized modular designs.
Gas turbines hold installed capacity. Heat recovery steam generators are rotating up the share rankings.
Application:
Application segmentation tracks where fuel cost volatility and carbon regulation intensity reshape project finance assumptions.
- Power Generation:Utility-scale baseload and peaking installations dominate procurement volume, with specifications increasingly demanding rapid-start flexibility and hydrogen blending capability above 30% by volume. Thailand and Vietnam utilities are ordering gas turbines specifically for grid stabilization as solar penetration exceeds 25% in provincial networks.
- Renewable Integration:Firming capacity for intermittent wind and solar requires turbines capable of multiple daily starts with minimal thermal cycling damage. This segment is climbing the fastest as battery substitution limits pure peaker economics in California and the United Kingdom.
- Industrial Processing:Cogeneration applications in cement, steel, and paper industries capture process steam alongside electricity. European carbon border adjustments are redirecting investment toward hydrogen-ready configurations.
- Oil & Gas:Upstream and midstream operations use turbines for mechanical drive and onsite power. Capital discipline among supermajors is compressing greenfield orders.
Power generation anchors equipment shipments. Renewable integration is accelerating most quickly in procurement pipelines.
End User:
Customer type segmentation reveals shifting procurement authority from integrated utilities to merchant developers with different risk tolerances and equipment specifications.
- Independent Power Producers:Merchant developers in Texas ERCOT and the United Kingdom capacity market now unbundle turbine, HRSG, and control system procurement through competitive tender, prioritizing capital efficiency over single-source accountability. These buyers specify hydrogen-ready equipment with future upgrade paths to 100% hydrogen combustion.
- Utilities:Vertically integrated state power boards in India and Thailand retain bundled procurement preferences, leveraging long-term OEM relationships for integrated plant solutions with performance guarantees.
- Manufacturing:Industrial self-generation operators in chemicals and refining seek single-shaft configurations for cogeneration retrofits. United States Gulf Coast complexes are repowering aging steam hosts.
- Mining:Remote operations in Australia and Chile require modular rapid-response units for off-grid power. Diesel displacement economics drive limited turbine adoption.
Utilities retain the largest installed base. Independent power producers are gaining procurement share fastest.
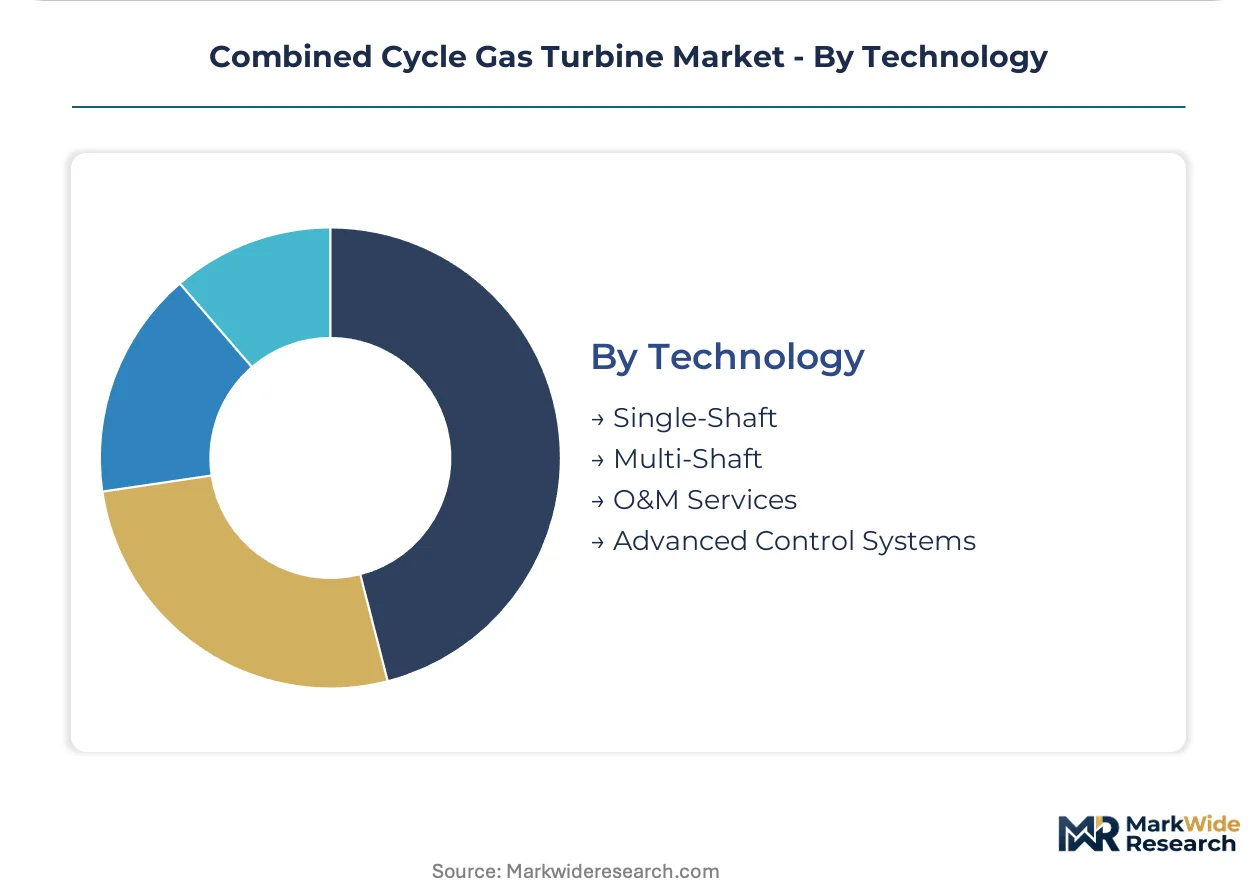
Technology:
Technology segmentation distinguishes between configurations optimized for baseload efficiency versus flexibility services.
- Multi-Shaft:Separate gas turbine and steam turbine shafts allow independent operation and maintenance scheduling, maximizing availability for baseload duty cycles. Large utility applications in India and Saudi Arabia favor this architecture for units above 400 MW where efficiency floors mandated by CEA technical standards apply.
- Single-Shaft:Integrated rotor designs reduce footprint and capital cost, suiting industrial cogeneration and space-constrained installations. United States Gulf Coast petrochemical retrofits specify these configurations for waste heat capture.
- Advanced Control Systems:Digital twin deployment and predictive analytics optimize maintenance intervals and dispatch decisions. Cybersecurity requirements complicate integration with legacy distributed control systems.
- O&M Services:Long-term service agreements preserve manufacturer revenue streams through parts and labor contracts. Contract structures are shifting toward outcome-based availability guarantees.
Multi-shaft configurations dominate utility-scale capacity. Single-shaft designs are expanding most quickly in industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision-cast turbine blade suppliers export nickel-based superalloy components to assembly plants in India, Saudi Arabia, and the United States, anchoring a trade corridor that moves high-value hot-section parts toward markets with active procurement pipelines.
United States
Merchant developers in Texas ERCOT and Florida order hydrogen-ready turbines with 50% blending capability as standard equipment. EPA carbon rules under Section 111 of the Clean Air Act establish emission intensity benchmarks that effectively require carbon capture readiness or hydrogen co-firing for new gas-fired capacity. Houston hosts engineering centers where combustor redesigns for hydrogen blends are accelerating.
India
State power boards in Maharashtra and Gujarat are retiring subcritical coal units in favor of advanced combined cycle blocks above 300 MW. The Central Electricity Authority mandates minimum thermal efficiency thresholds for new thermal installations through CEA technical standards. Tamil Nadu's utility procurement departments specify multi-shaft configurations for grid stabilization against renewable intermittency.
Saudi Arabia
The kingdom's power sector privatization unbundles generation assets, creating openings for independent power producers to develop greenfield combined cycle capacity. Long-term offtake structures under the Saudi Electricity Company reform program anchor project finance. The Eastern Province industrial corridor concentrates petrochemical complexes seeking waste heat capture through single-shaft repowering.
Germany
Precision-cast single-crystal turbine blade manufacturers in Baden-Württemberg and North Rhine-Westphalia supply nickel-based superalloys to global OEM assembly networks. REACH regulations and evolving hydrogen blending mandates in the European Union force combustor material upgrades across manufacturer portfolios. Munich engineering centers concentrate specialized workforce capable of dry low-NOx combustor design.
Japan
Manufacturing scale and localized assembly footprints sustain positions in Asian utility procurement channels. METI standards for hydrogen infrastructure deployment align with turbine specifications requiring future upgrade paths to 100% hydrogen combustion. Nagoya and Yokohama industrial zones host hot-section component fabrication for regional export.
Combined Cycle Gas Turbine Market Vendor Landscape
Player mix skews toward integrated turbine-HRSG-control system bundlers and specialized hot-section component suppliers. The market structure concentrates around three global OEMs with full-plant solution capabilities, supported by a tier of regional assemblers and precision casting specialists. Strategic archetypes include hydrogen-ready technology leaders, industrial cogeneration retrofit specialists, and aftermarket service aggregators. Competitive moves center on combustor engineering talent acquisition and additive manufacturing qualification for spare parts compression.
Within the integrated technology tier, General Electric and Siemens exemplify divergent strategic positioning. General Electric occupies a position anchored to large-scale utility projects through advanced-class turbine platforms. Siemens represents the bundled plant solution approach, combining gas turbines with heat recovery systems and digital controls. Mitsubishi Heavy Industries sits within the Asia-Pacific manufacturing scale archetype, leveraging localized assembly footprints for regional procurement dominance.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| Mitsubishi Heavy Industries |
| Ansaldo Energia |
| Bharat Heavy Electricals Limited |
| Doosan |
| Solar Turbines |
| MAN Energy Solutions |
| Kawasaki Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with Saudi Electricity Company and Indian state power boards lock in multi-year turbine supply commitments while providing price visibility against nickel superalloy volatility. These structures transfer fuel price risk to offtakers but expose OEMs to raw material escalation clauses in precision-cast blade sourcing agreements.
Pricing Analysis
Advanced-class turbines above 400 MW command substantial premiums over prior-generation F-class units and early hydrogen-ready configurations still in validation. Project-based pricing dominates utility procurement, with cost differentiation driven by thermal efficiency guarantees and CEA-mandated emission control tiers. Cost compression in standard-class equipment is intensifying because independent power producers unbundle component sourcing through competitive tender. Merchant developers in Texas ERCOT exhibit highest price sensitivity, while vertically integrated Gulf Coast petrochemical operators prioritize single-source accountability over capital efficiency.
Supply Chain Analysis
Germany and Japan anchor precision-cast single-crystal turbine blade fabrication, exporting nickel-based superalloy components to assembly plants in India, Saudi Arabia, and the United States. The supply chain draws from concentrated rhenium and cobalt sources, with hot-section component lead times tethered to vacuum investment casting capacity at Baden-Württemberg and Nagoya facilities. Single-source vulnerability in specialized alloy supply exposes procurement timelines to geopolitical friction. Distribution runs through OEM-integrated project channels for utility-scale deployments, with aftermarket parts flowing through regional service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA carbon rules and evolving hydrogen blending mandates are disrupting equipment specifications faster than combustor engineering capacity can expand, compressing development cycles for hydrogen-ready turbines. This regulatory inflection creates asymmetric opportunities across incumbent defense, entrant positioning, and acquisition targeting.
For Market Incumbents: Shield installed base revenue through long-term service agreement renewals with outcome-based availability guarantees. Accelerate additive manufacturing qualification for hot-section spare parts to compress lead times from months to weeks against independent aftermarket entrants. Prioritize captive supply of nickel superalloy casting capacity through backward integration into German and Japanese precision foundries.
For New Entrants and Emerging Players: Differentiate on rapid-start flexibility specifications for renewable balancing applications where battery substitution has not yet captured frequency regulation contracts. Target industrial cogeneration retrofit opportunities across United States Gulf Coast petrochemical complexes seeking single-shaft configurations for waste heat capture. Pursue channel partnerships with EPC contractors in Saudi Arabia's privatized power sector to bypass OEM-integrated sales channels.
For Investors and Strategic Acquirers: Specialized combustor engineering boutiques with dry low-NOx hydrogen blend capabilities represent prime acquisition targets as OEM talent scarcity constrains product development velocity. Frame long-term viability around hydrogen readiness upgrade paths and carbon capture compatibility across the analysis window. Monitor FERC interconnection queue clearance rates as the inflection signal for stranded asset risk in completed turbine installations awaiting grid access.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Combustor Retrofit Program | EPA Section 111 benchmarks force 50% blending capability as standard equipment specification. |
| Additive Manufacturing Qualification | Laser powder bed fusion compresses spare parts lead times from months to weeks. |
| Long-term Service Agreement Restructure | Outcome-based availability guarantees preserve manufacturer revenue against independent entrants. |
| Backward Integration into Superalloy Casting | Captive supply of precision-cast blades insulates against German-Japanese supplier concentration. |
| Single-Shaft Configuration Expansion | United States Gulf Coast petrochemical repowering drives waste heat capture demand. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads; and secondary validation against EIA capacity data, IEA power sector reports, FERC interconnection filings, and CEA technical standards documentation. Bottom-up equipment shipment tracking across gas turbine, HRSG, and steam turbine categories was triangulated with top-down power generation capacity expansion forecasts.
Across the projection horizon, the analytical framework modeled segmentation dimensions including technology configuration (multi-shaft versus single-shaft), fuel flexibility tier (natural gas versus hydrogen-ready), and end-user procurement archetype (utility bundled versus IPP unbundled). CAGRs were derived from regression analysis of historical efficiency mandate adoption curves and renewable penetration rates, with forecast inputs incorporating hydrogen blending timeline assumptions and carbon border adjustment mechanism phase-in schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained natural gas price volatility and progressive hydrogen infrastructure deployment; material deviation in regulatory timelines or alloy supply disruption would warrant model refresh. Recalibration cycles align with material shifts in EPA carbon rule implementation and CEA efficiency mandate enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Indonesia Power Market
Power Generation
LAMEA Microturbine Market
Power Generation
United Kingdom Power Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Oman Power Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Algeria Power Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Global Gensets Market
Power Generation
Solar Generator Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Australia Thermal Power Market