
 Commercial Gensets Market | 2026-2036
Commercial Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Gensets Market Analysis
Skilled technician availability is rotating toward hybrid and gas-fired architectures as diesel expertise saturates mature markets. Caterpillar leverages its integrated dealer network to sustain parts availability across North American infrastructure projects. Cummins anchors its position through in-house alternator production and controls engineering. Wärtsilä competes in the above-500 kVA segment with medium-speed gas engines tailored to continuous-duty data center applications.
Commercial gensets are stationary or mobile engine-alternator assemblies rated typically from 10 kVA to 3,000 kVA, designed to deliver emergency, prime, or continuous electrical power when grid supply fails or remains unavailable; core components include the prime mover, synchronous alternator, voltage regulator, and automatic transfer switch, with enclosure design dictating noise attenuation and environmental operating range. Diesel generators still occupy the largest installed base across commercial buildings and construction sites, though gas generators are capturing share in data centers where emissions compliance and fuel cost stability matter. Hybrid generators represent the fastest-growing product type as lithium-ion buffer integration allows runtime extension and peak shaving in prime-power installations. The 151-500 kVA capacity band concentrates margin pools because it balances customization intensity with production scale economics.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe are forcing particulate and NOx after-treatment adoption, raising product cost and favoring suppliers with certified engine platforms across both jurisdictions. India's Central Pollution Control Board enforces construction equipment emission norms that constrain diesel genset deployment in Delhi-NCR and Mumbai metropolitan zones, redirecting procurement toward gas and hybrid alternatives. Stakeholders must monitor how carbon border adjustments and building energy codes redefine total-cost-of-ownership calculations across installation modes.
Market Dynamics
The transition from diesel-only to hybrid and gas-fired architectures is restructuring procurement patterns as emissions deadlines compress upgrade cycles and skilled labor pools rotate toward cleaner technologies.
Growth Catalysts
- Data Center Expansion:Hyperscale operators in the United States and Europe are accelerating backup power contracts ahead of EPA Tier 4 Final and EU Stage V enforcement, pulling forward demand for above-500 kVA continuous-duty units.
- Grid Instability in Manufacturing Clusters:Unreliable electricity supply across Gujarat and Tamil Nadu is forcing automotive and textile producers to install prime-power gensets, concentrating procurement in India's 500+ kVA segment.
- Hybrid Integration:Lithium-ion buffer systems are extending runtime and enabling peak-shaving capabilities, making hybrid generators attractive for installations where fuel logistics constrain pure diesel operation.
Market Restraints
- After-Treatment Cost Burden:Particulate filters and selective catalytic reduction systems required by EPA Tier 4 Final and EU Stage V are raising product cost by fifteen to twenty-five percent, squeezing margins on mid-range units.
- Technician Availability Saturation:Diesel engine expertise has saturated mature markets while hybrid and gas-fired architectures face acute shortages of certified service personnel, lengthening response times for critical failures.
- Metropolitan Deployment Restrictions:India's Central Pollution Control Board construction equipment norms now prohibit diesel genset operation in Delhi-NCR and Mumbai during high-pollution episodes, forcing premature asset retirement.
Strategic Opportunities
- Continuous-Duty Data Center Applications:Medium-speed gas engines tailored to twenty-four-seven operation are capturing share from diesel in European and North American facilities where emissions compliance and fuel cost stability matter.
- Carbon Border Adjustment Positioning:Suppliers with certified engine platforms spanning both EPA and EU jurisdictions can credibly document lifecycle emissions for export-exposed data center operators facing embedded carbon tariffs.
- Service Contract Unbundling:Remote monitoring and predictive maintenance offerings are creating recurring revenue streams independent of equipment sales, with adoption concentrated among financial services and healthcare buyers.
Industry Challenges
- Multi-Platform Certification Complexity:Engine manufacturers must simultaneously validate after-treatment configurations for EPA Tier 4 Final, EU Stage V, and India's evolving CPCB norms, stretching engineering resources and delaying product launches.
- Legacy Control System Integration:Building management system protocols from the 1990s and early 2000s lack standardized communication interfaces with modern genset controllers, requiring costly custom gateway development for retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Gensets Market |
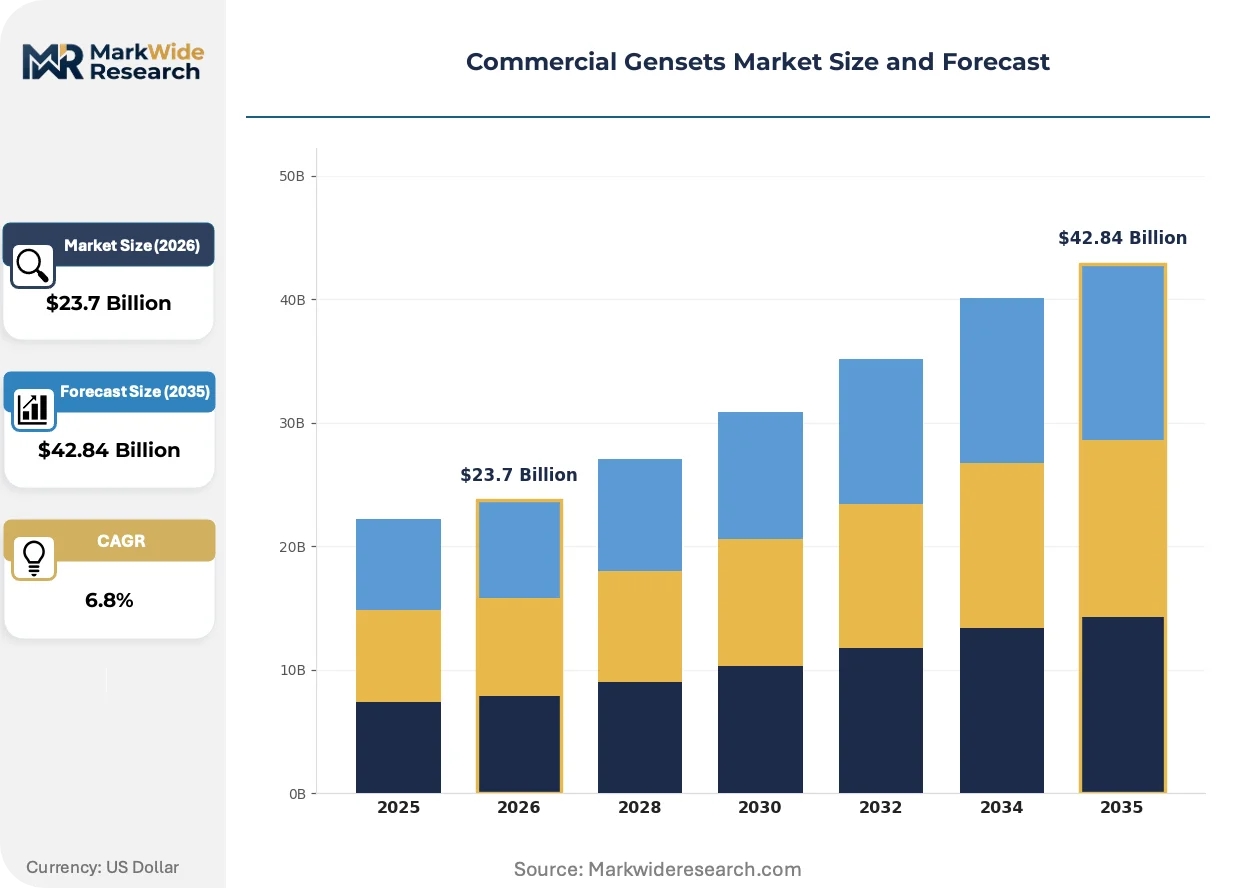
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Hybrid Generators, Portable Generators End User: Commercial Buildings, Data Centers, Manufacturing Facilities, Construction Sites Installation: Standby, Prime, Continuous, Mobile Capacity: Below 50 kVA, 50-150 kVA, 151-500 kVA, Above 500 kVA |
| Companies Covered | Rolls-Royce, Kohler, Caterpillar, GE Power, Wärtsilä, Cummins, Mitsubishi Heavy Industries, MTU Onsite Energy, Generac Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Gensets Market Emerging Trajectories
Product architecture is bifurcating between emissions-compliant diesel with advanced after-treatment and gas-hybrid systems that exploit grid instability and carbon accounting pressures to capture prime-power applications.
Integrated lithium-ion buffer modules are supplanting traditional lead-acid battery banks in prime-power installations. Data center operators in Northern Virginia and Frankfurt are specifying these configurations to extend runtime during fuel delivery interruptions. The technology is compressing the addressable market for oversized diesel-only units by enabling smaller prime movers to handle peak loads.
EU Stage V and EPA Tier 4 Final are forcing synchronous adoption of diesel particulate filters and selective catalytic reduction across the 151-500 kVA band. Engine suppliers with single-platform certification spanning both jurisdictions are capturing specification preference from multinational data center operators. The 10-150 kVA segment faces compressed margins as standardized after-treatment packages eliminate customization differentiation.
Power-purchase agreements with embedded backup guarantees are displacing traditional capital procurement for hyperscale facilities. Colocation providers in Ashburn and Amsterdam are bundling genset capacity into rack-rate contracts rather than requiring tenant-owned infrastructure. This shift concentrates buyer power with a handful of leasing specialists and compresses switching flexibility for end-users.
Commercial Gensets Market Segmentation
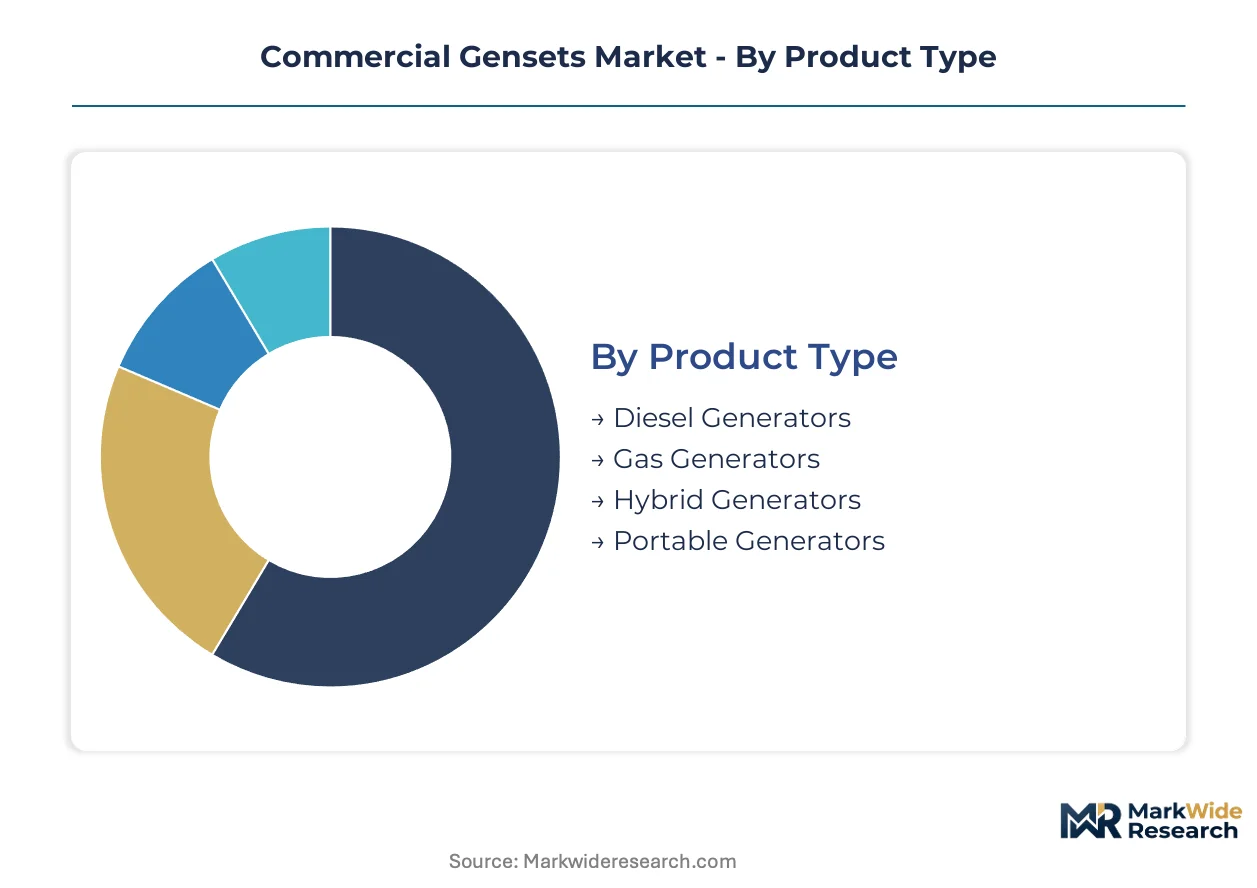
Segmentation reveals how emissions regulations and fuel cost pressures fragment procurement patterns across installation modes and power ratings. Understanding these divides exposes where diesel incumbency holds versus where gas and hybrid alternatives displace legacy architectures.
Product Type:
Hybrid generators face the weakest substitution pressure as lithium-ion integration creates proprietary system boundaries that pure-play diesel or gas suppliers cannot easily replicate.
- Diesel Generators:Compression-ignition prime movers with synchronous alternators remain the default for construction sites and emergency backup in commercial buildings. Demand concentrates in Indian manufacturing clusters where Gujarat and Tamil Nadu textile producers rely on 500+ kVA units during grid failures.
- Hybrid Generators:Diesel or gas prime movers paired with lithium-ion buffer modules enable runtime extension and peak shaving. Data center operators in Northern Virginia and Frankfurt specify these configurations to compress fuel logistics requirements and reduce oversized prime mover specifications.
- Gas Generators:Spark-ignition engines burning pipeline natural gas or biogas, favored where emissions compliance and fuel price stability matter for continuous-duty applications.
- Portable Generators:Trailer-mounted or skid-based units below 150 kVA serving construction and temporary power needs, facing margin compression from standardized after-treatment packages.
Diesel generators anchor the volume base while hybrid generators gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive data center deployments from price-sensitive construction rentals.
- Data Centers:Hyperscale and colocation facilities requiring 24/7 backup with sub-10-second transfer times. Procurement concentrates in Ashburn and Amsterdam where power-purchase agreements bundle genset capacity into rack-rate contracts.
- Manufacturing Facilities:Automotive and textile producers in grid-unstable regions installing prime-power gensets for production continuity. Indian Central Pollution Control Board norms in Delhi-NCR and Mumbai redirect diesel procurement toward gas alternatives.
- Commercial Buildings:Hospitals, hotels, and retail complexes specifying standby units for code-compliant emergency power.
- Construction Sites:Temporary power rentals facing acute price competition and shortened asset lifecycles from mobile deployment wear.
Data centers command the premium pricing tier while manufacturing facilities deliver the highest unit volumes.
Installation:
Application duty cycle determines engineering margins and service contract attach rates.
- Continuous:Prime movers rated for unlimited annual hours at variable load, specified by data centers and remote industrial operations where grid connection is unavailable or unreliable. EPA Tier 4 Final and EU Stage V compliance costs concentrate here.
- Standby:Emergency-only units with limited annual runtime, dominating commercial building specifications where code compliance drives procurement rather than operational economics.
- Prime:Variable load applications where gensets serve as primary power source, common in Indian manufacturing clusters facing distribution utility instability.
- Mobile:Trailer or skid-mounted units for construction and event power, requiring rapid deployment capabilities and simplified fuel logistics.
Standby installations dominate unit shipments while continuous-duty configurations generate the highest revenue per kilowatt.
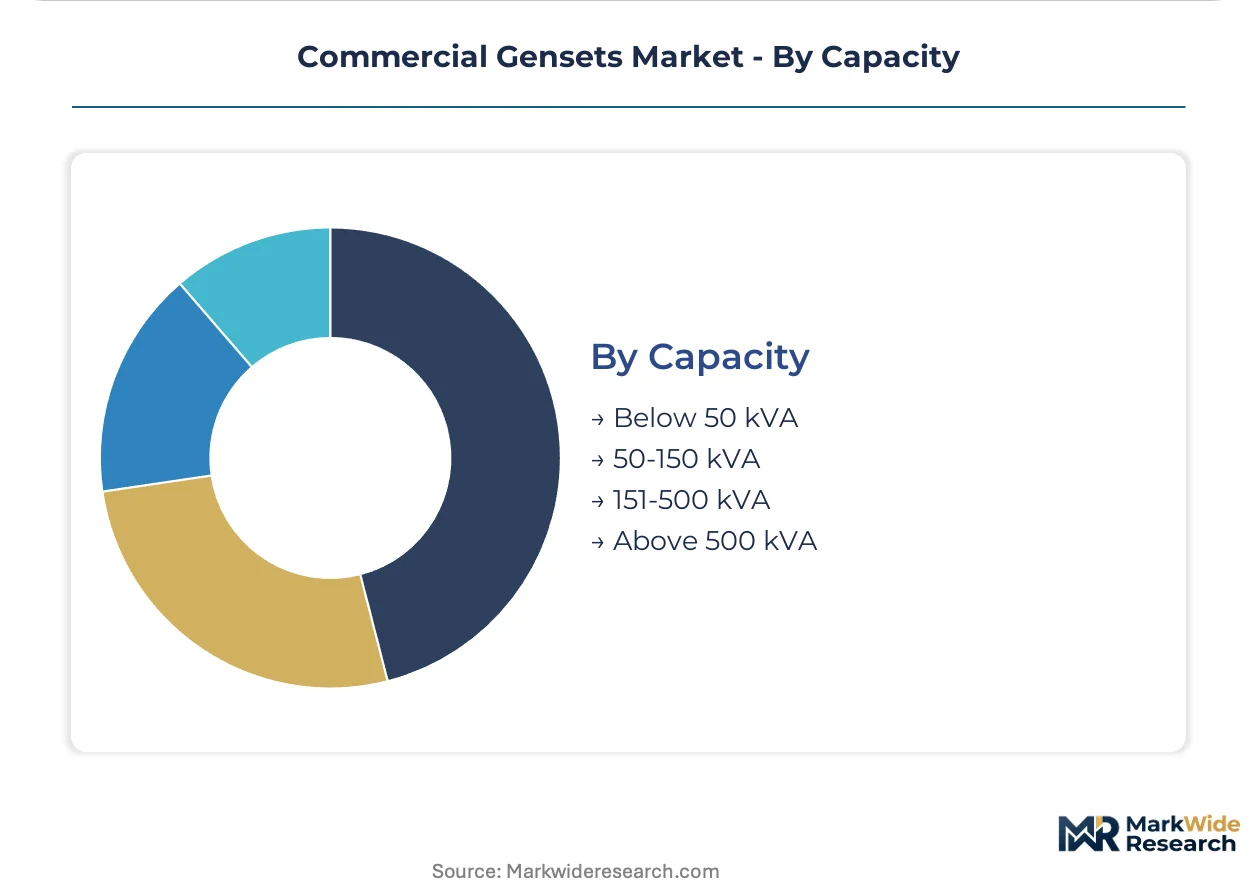
Capacity:
Supply concentration and customization intensity invert across the power spectrum.
- 151-500 kVA:The margin concentration band balancing production scale with engineering customization. After-treatment standardization from EPA Tier 4 Final and EU Stage V squeezes differentiation opportunities here.
- Above 500 kVA:Medium-speed engines and integrated controls architectures serving data center and heavy industrial loads. Wärtsilä and Caterpillar compete here with certified platforms spanning both jurisdictions.
- Below 50 kVA:Compact single-phase or three-phase units for small commercial and residential backup, facing commoditization from Asian manufacturing.
- 50-150 kVA:Mid-range segment where standardized after-treatment packages eliminate vendor differentiation and compress pricing power.
The 151-500 kVA band anchors manufacturer profitability while above-500 kVA units climb the fastest on data center expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand composition varies sharply by geography. The United States and Germany prioritize emissions-compliant continuous-duty units for data center applications, while India procures larger prime-power systems to compensate for grid instability in manufacturing belts.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are accelerating backup power contracts ahead of EPA Tier 4 Final enforcement. The EPA's stringent particulate and NOx limits are forcing after-treatment adoption across the 151-500 kVA band. Ashburn's colocation cluster now specifies medium-speed gas engines for twenty-four-seven operations where fuel cost stability matters.
Germany
Frankfurt's data center corridor drives procurement of above-500 kVA continuous-duty units with EU Stage V certification. The country's Federal Immission Control Act tightens emissions requirements for stationary engines in metropolitan zones. Bavarian automotive suppliers are installing hybrid gensets with lithium-ion buffers to manage peak loads during grid fluctuations.
India
Textile and automotive producers in Gujarat and Tamil Nadu rely on 500+ kVA prime-power gensets during distribution utility failures. The Central Pollution Control Board's construction equipment norms now prohibit diesel genset operation in Delhi-NCR and Mumbai during high-pollution episodes. Manufacturing clusters in Ahmedabad and Coimbatore are redirecting procurement toward gas and hybrid alternatives.
United Kingdom
London's financial services sector specifies standby units with sub-ten-second transfer times for trading floor continuity. The Environment Agency's Medium Combustion Plant Regulations impose emissions limits on generators above 1 MW thermal input. Slough's data center belt is adopting power-purchase agreements that bundle genset capacity into rack-rate contracts.
Japan
Tokyo's commercial building stock drives demand for compact standby units below 150 kVA with seismic certification. METI's energy efficiency standards incentivize hybrid configurations with battery integration. Osaka's manufacturing belt requires prime-power systems with earthquake-resistant enclosures for production continuity.
Commercial Gensets Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in above-500 kVA continuous-duty applications. The upper tier commands specification preference through certified engine platforms spanning EPA and EU jurisdictions. Mid-tier specialists compete on customization intensity in the 151-500 kVA band. Dominant competitive moves include backward integration into alternator production and geographic expansion through dealer network densification.
Among integrated engine-alternator assemblers, Caterpillar, Cummins, and Wärtsilä exemplify distinct archetypes. Caterpillar represents the dealer-network model with integrated parts availability across North American infrastructure. Cummins anchors the in-house component control position through captive alternator manufacturing. Wärtsilä occupies the medium-speed gas engine specialization for continuous-duty data center specifications. These three demonstrate how certification breadth and service infrastructure separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| Rolls-Royce |
| Kohler |
| Caterpillar |
| GE Power |
| Wärtsilä |
| Cummins |
| Mitsubishi Heavy Industries |
| MTU Onsite Energy |
| Generac Power Systems |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for above-500 kVA continuous-duty units lock in supply access for data center operators in Northern Virginia and Frankfurt while anchoring price visibility against volatile steel and copper input markets. These arrangements concentrate buyer power with hyperscale operators and colocation providers, compressing margin flexibility for engine-assemblers facing synchronized EPA Tier 4 Final and EU Stage V compliance costs.
Pricing Analysis
Project-based procurement with embedded service contracts dominates data center deployments, while spot purchasing persists in construction rentals. Price differentiation rests on certification grade spanning EPA and EU jurisdictions plus after-sales service bundling. Cost compression in the 50-150 kVA band is intensifying because standardized after-treatment packages eliminate vendor customization leverage. Construction sites exhibit acute price sensitivity; data center operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
China and India anchor alternator and enclosure fabrication, while Germany and the United States concentrate precision engine component manufacturing. Supply chains draw from rare earth magnets for permanent-magnet alternators, high-grade steel for engine blocks, and lithium-ion cells for hybrid buffer modules. Single-source vulnerability concentrates in semiconductor-based genset controllers sourced from East Asian foundries. Distribution runs through authorized dealer networks for aftermarket parts and direct OEM relationships for hyperscale data center projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling creates recurring revenue layers expanding faster than hardware sales as predictive maintenance and remote monitoring penetrate financial services and healthcare buyer segments.
For Market Incumbents: Shield margin pools in the 151-500 kVA band by deepening captive alternator production and controls engineering capabilities against emerging Asian assemblers. Prioritize EPA-EU dual certification investment to capture specification preference from multinational data center operators facing carbon border adjustment exposure. For New Entrants and Emerging Players: Differentiate on hybrid architecture integration targeting Indian manufacturing clusters in Gujarat and Tamil Nadu where grid instability and CPCB emission restrictions redirect procurement from diesel incumbents. Pursue gas generator specialization with medium-speed engine platforms for continuous-duty prime power applications underserved by established suppliers. For Investors and Strategic Acquirers: Regional service specialists with dense technician networks in North American infrastructure corridors offer acquisition exposure to the maintenance revenue layer. Monitor EPA enforcement timing and EU Stage V implementation rigor as inflection indicators for aftermarket parts demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternator Production | Cummins' captive manufacturing secures supply continuity and margin control against commodity copper volatility. |
| Dual-Jurisdiction Certification Investment | Engine platforms validated for EPA Tier 4 Final and EU Stage V capture specification preference from hyperscale operators. |
| Hybrid Buffer Module Integration | Lithium-ion pairing with diesel or gas prime movers extends runtime and enables peak shaving for data center prime power. |
| Dealer Network Densification | Caterpillar's integrated parts availability sustains aftermarket revenue across North American infrastructure projects. |
| Predictive Maintenance Platform Launch | Remote monitoring offerings create recurring revenue streams independent of equipment sales in healthcare and financial services. |
Methodological Framework
A spread of perspectives from plant engineers at automotive and textile facilities, procurement leads at data center operators, aftermarket service heads at dealer networks, and EPC contractors converged on the working assumptions. Secondary validation drew from EPA certification databases, EU Stage V type-approval records, Central Pollution Control Board construction equipment notifications, and customs trade data for engine-alternator assemblies. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include fuel type architecture, capacity tier, installation duty cycle, end-use vertical, and regional regulatory cluster. CAGRs were derived from slope analysis of historical procurement patterns projected through the forecast period. Industry-specific inputs incorporated data center power density trends, Indian grid reliability indices, and emissions compliance cost curves for after-treatment adoption.
Decision-makers should treat outputs as directional under assumptions of sustained data center construction velocity and incremental EPA-EU regulatory enforcement; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in emissions deadline timing and hyperscale capex commitment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Black Start Generator Market
Power Generation
Cogeneration System Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
India Gas Generator Market
Power Generation
East Africa Power Market
Power Generation
Global Gensets Market
Power Generation
Captive Power Plant Market
Power Generation
Thermal Power Market
Power Generation
Global Power Generation Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
India Gensets Market
Power Generation
Shore Power Market
Power Generation
United Kingdom Power Market
Power Generation
Residential Solar Generator Market
Power Generation
Tunisia Power Market