
 Venezuela Power Market | 2026-2036
Venezuela Power Market Size, Share, and Industry Trends Forecast 2026-2036
Venezuela Power Market Analytics
Preventive maintenance contracts for aging thermoelectric units is broadening revenue streams beyond pure generation sales. CORPOELEC leverages its statutory monopoly over transmission assets to control national grid access. Siemens Energy AG anchors its presence through turbine overhaul capabilities at the Planta Centro complex. General Electric Company competes on gas turbine parts logistics despite import restriction complexities.
Venezuela power encompasses electricity production, bulk transfer, and final delivery through high-voltage lines and distribution networks operating at 60 Hz with nominal voltages of 120/240 V residential and 13.8-230 kV transmission tiers. Hydropower from the Guri complex historically supplied roughly two-thirds of national capacity, though drought cycles and sedimentation now constrain output. Natural gas-fired generation is recovering as associated gas capture improves in eastern oil fields. Industrial end users represent the most tariff-responsive segment, with commercial consumers in Caracas and Maracaibo driving distributed solar pilot adoption amid reliability concerns.
Venezuela's Ministry of Electric Power sets wholesale pricing and grid connection standards, while the national hydrocarbons regulator oversees gas-to-power fuel allocation. The country's central bank exchange controls complicate equipment import financing for international suppliers. Stakeholders must weigh sovereign payment risk against rehabilitation contract structures as the state seeks external technical partnerships without ceding operational control.
Market Dynamics
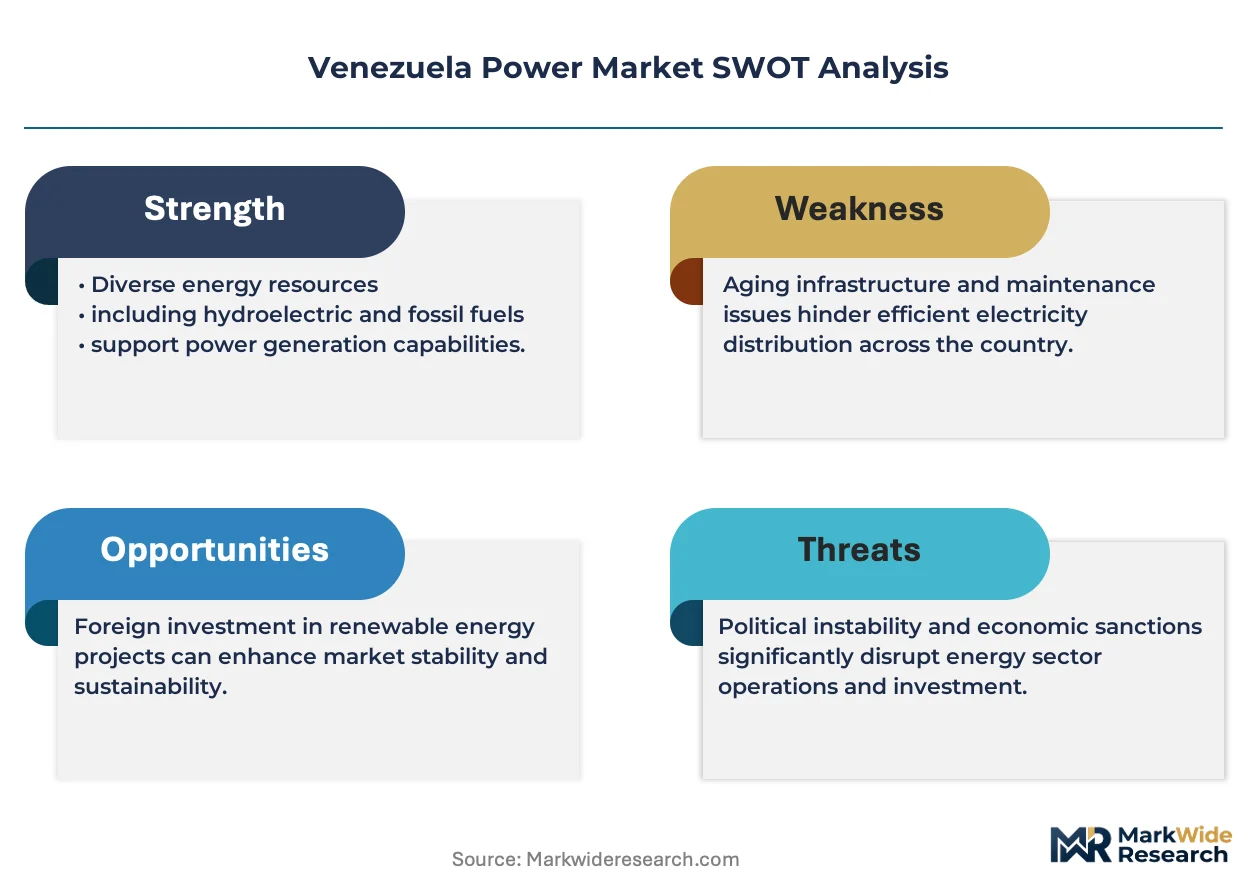
The Venezuela power sector operates under chronic supply-demand imbalance where transmission losses exceed 30 percent and generation capacity utilization remains below 40 percent. CORPOELEC's statutory monopoly over grid infrastructure creates asymmetric market access that shapes competitive positioning for private operators seeking rehabilitation contracts.
Growth Catalysts
- Orinoco Belt industrial expansion:Heavy oil upgrading facilities at Jose and Puerto La Cruz are restarting steam-intensive processes that drive baseload electricity demand from thermoelectric sources.
- Ministry of Electric Power tariff restructuring:The 2024-2025 rate adjustments for industrial consumers above 1 MW are redirecting capital toward grid stabilization investments previously deferred.
- Associated gas capture improvements:PDVSA's eastern field operations are increasing fuel availability for natural gas-fired units at Planta Centro and Termozulia complexes.
Market Restraints
- Central bank exchange control complexity:Equipment import financing requires navigating multiple parallel currency rates that inflate project costs for international turbine suppliers.
- Guri reservoir sedimentation:Accumulated silt has reduced effective storage capacity at the 8,900 MW complex, constraining dispatch flexibility during dry seasons.
- Spare parts supply concentration:Gas turbine rotor and blade sourcing depends on a narrow base of European and US manufacturers subject to sanctions-related payment restrictions.
Strategic Opportunities
- Distributed solar pilots in Caracas commercial zones:Banking and retail clusters are financing rooftop installations to bypass distribution network reliability failures.
- Preventive maintenance contract expansion:Aging thermoelectric units at Tacoa and Ramón Laguna require systematic overhaul programs beyond emergency repair cycles.
- Grid-scale battery feasibility at substations:Frequency regulation services present revenue streams for storage developers under emerging ancillary service frameworks from the national regulator.
Industry Challenges
- Turbine technician skill scarcity:Specialized expertise for Siemens and General Electric heavy-duty gas turbine overhauls has eroded through emigration and training program collapse.
- Legacy SCADA integration complexity:New digital monitoring systems must interface with 1980s-vintage control architectures at major substations without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venezuela Power Market |
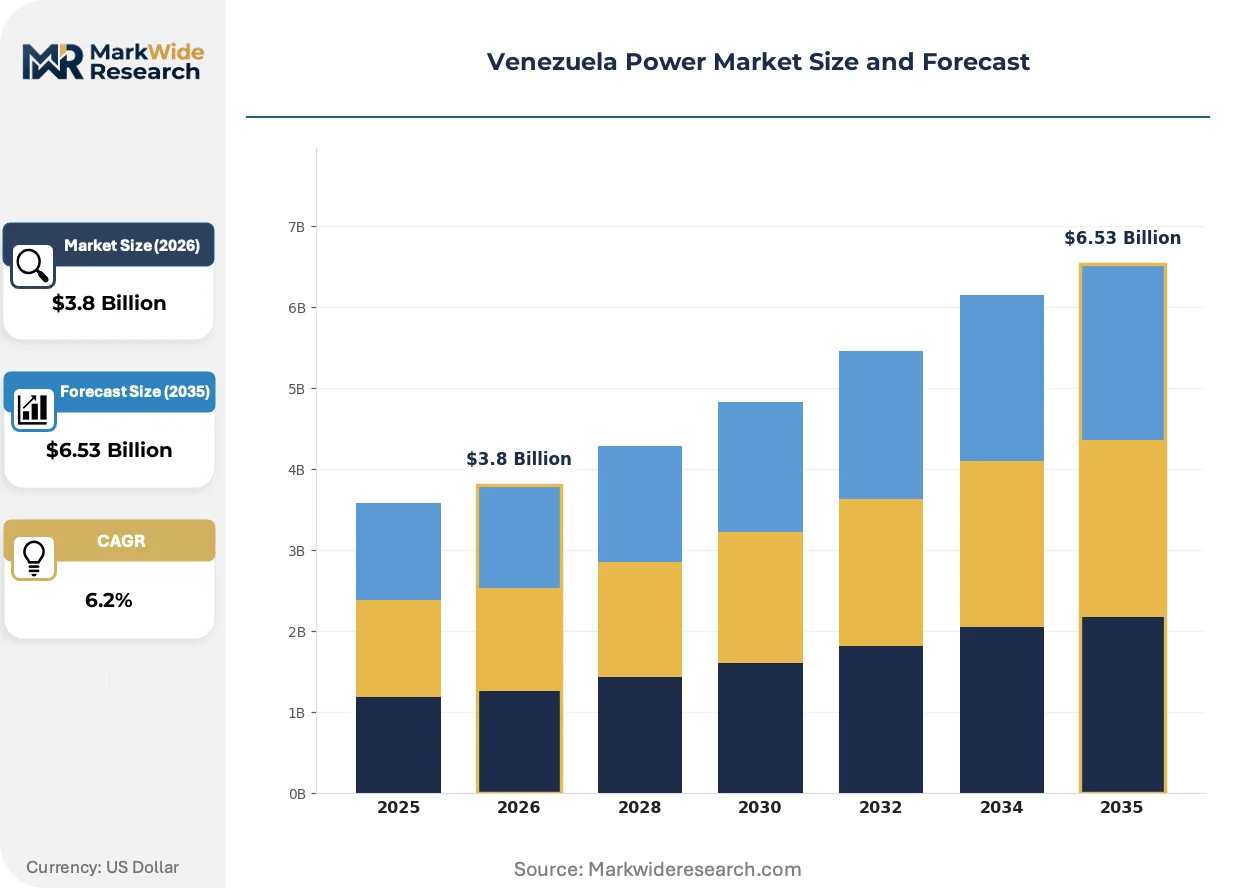
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Generation, Transmission, Distribution, Retail Energy Source: Hydropower, Natural Gas, Oil, Renewable End User: Residential, Industrial, Commercial, Government Installation Type: Onshore, Offshore, Grid-connected, Standalone |
| Companies Covered | CORPOELEC, Petroleos de Venezuela SA, PDVSA Electricidad, Enel Green Power LATAM, Siemens Energy AG, General Electric Company, ABB Ltd, Schneider Electric SE, Vestas Wind Systems A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venezuela Power Market Evolving Landscape
Digital instrumentation and distributed generation architectures are displacing centralized dispatch models across Venezuela's fractured grid. Technology adoption concentrates where commercial consumers possess dollar-denominated revenue streams to bypass sovereign payment risk.
Advanced gas turbine inlet air cooling is electrifying output recovery at thermoelectric plants operating above 35°C ambient temperatures. Industrial consumers at the Guayana mining complex are piloting fogging systems to secure contractual capacity during peak demand periods. This thermal efficiency intervention is compressing fuel consumption per megawatt-hour and extending operational windows for aging combined-cycle units.
Venezuela's Ministry of Electric Power has introduced mandatory grid code compliance deadlines for distributed generators above 500 kW. The regulation requires synchronous inverters and anti-islanding protection that disqualifies legacy solar installations. Commercial developers in Valencia and Maracaibo are accelerating certification timelines to secure interconnection permits before enforcement phases begin.
Self-generation procurement through bilateral power purchase agreements is displacing regulated tariff dependence for large industrial offtakers. Aluminum smelters and steel producers in Bolívar state are negotiating directly with private gas-fired developers to secure firm capacity. This contractual restructuring is most visible in the Ciudad Guayana industrial corridor where state utility reliability failures have exceeded 40 percent annual downtime.
Venezuela Power Market Segmentation
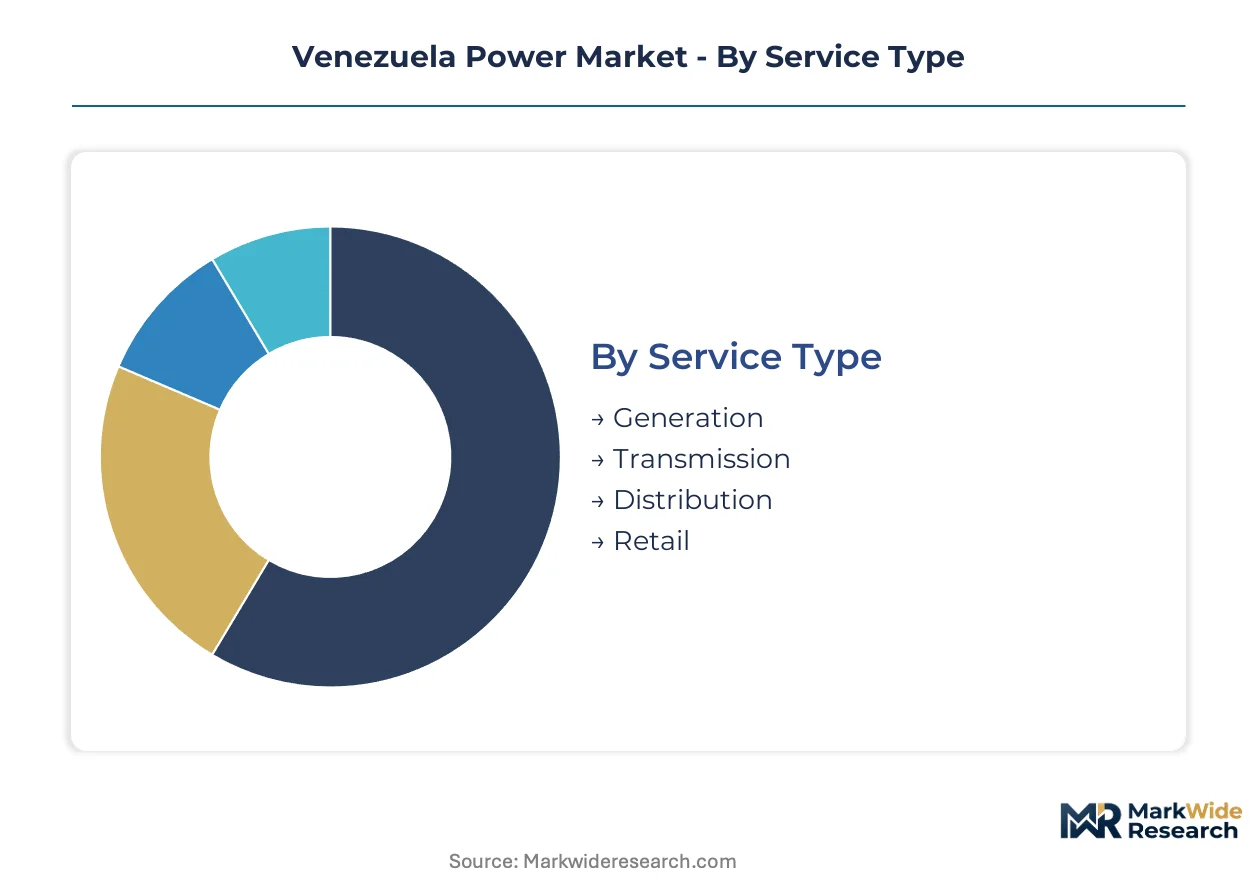
Venezuela's power sector fragmentation reflects divergent infrastructure maturity and payment capacity across service tiers. Segmentation reveals where dollar-indexed revenue pools concentrate versus bolivar-denominated segments dependent on sovereign tariff frameworks.
Service Type:
Contract structures differentiate buyers by capital intensity tolerance and operational control requirements.
- Generation:Thermoelectric and hydroelectric asset operators negotiate fuel supply agreements with PDVSA and water rights with the Guri reservoir authority. Heavy oil upgraders in the Orinoco Belt are expanding captive gas-fired capacity to bypass CORPOELEC grid instability.
- Transmission:High-voltage backbone infrastructure operates under CORPOELEC's statutory monopoly with 13.8-230 kV tiered voltage standards. Private developers seeking interconnection must navigate asymmetric grid access protocols that favor state-affiliated offtakers.
- Distribution:Medium and low-voltage networks serving the Caracas-Valencia corridor are attracting rehabilitation investment under Ministry of Electric Power tariff restructuring.
- Retail:Final supply to metered consumers operates through CORPOELEC subsidiaries with tiered pricing that cross-subsidizes residential users from industrial ratepayers.
Volume sits with Generation; growth tilts toward Distribution rehabilitation contracts.
Energy Source:
Dispatch priority follows fuel availability and reservoir levels rather than marginal cost economics.
- Hydropower:The Guri complex historically anchored national baseload but sedimentation and drought cycles now constrain output flexibility. Seasonal inflow variability forces greater reliance on thermoelectric backup during dry periods.
- Natural Gas:Associated gas capture improvements in eastern oil fields are restoring fuel availability for combined-cycle units at Planta Centro. Gas-fired generation offers faster ramp rates than hydro for industrial load-following.
- Oil:Diesel and fuel oil units provide emergency peaking capacity where gas pipeline infrastructure remains degraded.
- Renewable:Distributed solar pilots in Caracas commercial zones and Maracaibo banking clusters bypass distribution network failures through behind-the-meter installations.
Capacity share concentrates in Hydropower; expansion tilts toward Natural Gas and distributed Renewable projects.
End User:
Payment currency and tariff responsiveness segment buyers into investable versus sovereign-dependent pools.
- Residential:Subsidized tariff structures and collection challenges limit revenue quality for distribution utilities serving urban centers and rural communities.
- Industrial:Aluminum smelters and steel producers in Bolívar state negotiate bilateral power purchase agreements with private gas-fired developers to secure firm capacity beyond CORPOELEC reliability failures.
- Commercial:Banking and retail clusters in Valencia and Maracaibo are financing rooftop solar to mitigate downtime exceeding 40 percent annually on distribution feeders.
- Government:Public sector facilities operate on priority supply schedules that distort dispatch economics and delay maintenance windows for other customer classes.
Revenue quality peaks with Industrial offtakers; Commercial segments are gaining share fastest through distributed generation procurement.
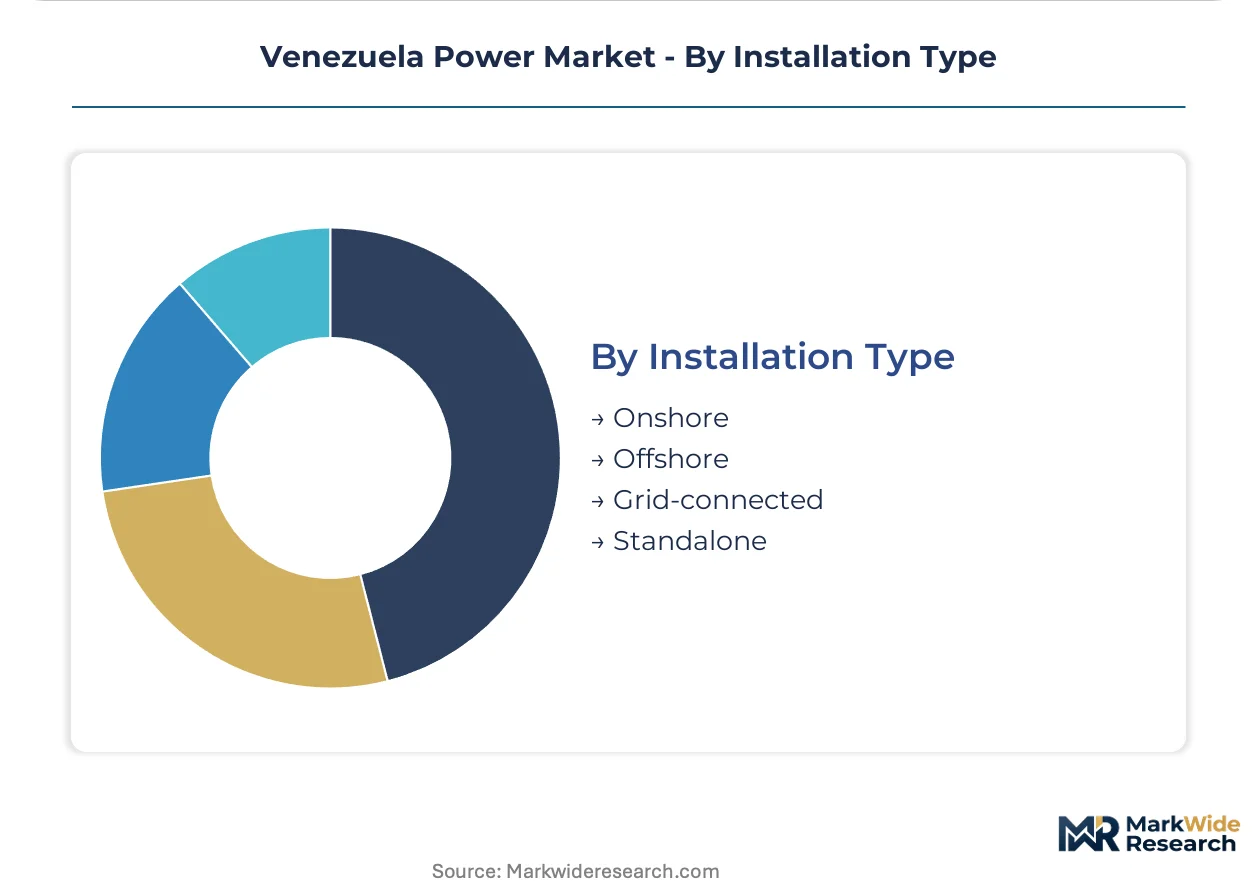
Installation Type:
Grid integration requirements and land access constraints shape project economics across deployment modes.
- Onshore:Thermoelectric and renewable projects concentrate in existing industrial zones with transmission interconnection proximity, particularly around the Ciudad Guayana corridor.
- Offshore:No active development given absence of coastal generation infrastructure and marine logistics capabilities.
- Grid-connected:Projects above 500 kW face mandatory grid code compliance deadlines requiring synchronous inverters and anti-islanding protection under Ministry of Electric Power regulations.
- Standalone:Industrial facilities and commercial clusters deploy captive generation to isolate from CORPOELEC frequency instability and voltage fluctuation events.
Project pipeline concentrates in Grid-connected configurations; Standalone systems are expanding most quickly among commercial users with dollar revenues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Caracas-Valencia corridor anchors Venezuela's electricity demand concentration, hosting the nation's densest industrial load centers and most intensive distribution rehabilitation activity.
Caracas Metropolitan Area
Commercial banking clusters and government facilities drive peak demand exceeding 2,000 MW during business hours. The Ministry of Electric Power prioritizes supply stability here through priority dispatch protocols that divert generation from peripheral regions. Rooftop solar pilots in Chacao and Baruta municipalities bypass CORPOELEC distribution failures through behind-the-meter installations.
Zulia State
Maracaibo's oilfield service sector and agricultural processing plants consume baseload power from thermoelectric units at Termozulia. PDVSA's western operational headquarters negotiates fuel supply agreements directly with generation asset operators. Lake Maracaibo cooling water access supports thermal efficiency at coastal combined-cycle facilities.
Bolívar State
Aluminum smelters and steel producers at Ciudad Guayana negotiate bilateral power purchase agreements with private gas-fired developers. The Guri reservoir authority manages water releases to balance industrial demand against reservoir conservation. Heavy industry here operates captive generation to isolate from grid frequency instability.
Anzoátegui State
Petrochemical complexes at Jose and Puerto La Cruz restart steam-intensive heavy oil upgrading processes. Associated gas capture from eastern oil fields restores fuel availability for Planta Centro thermoelectric units. The Orinoco Belt industrial expansion drives the fastest-growing electricity demand segment nationally.
Falcón State
Wind resource concentration at Paraguaná Peninsula attracts renewable development interest despite transmission interconnection constraints. The national hydrocarbons regulator oversees gas-to-power allocation for thermoelectric backup during wind variability periods. Distribution infrastructure rehabilitation lags behind generation capacity additions here.
Venezuela Power Market Competitive Landscape
Capital-heavy state operators compete with asset-light international service providers across Venezuela's power sector. CORPOELEC's statutory monopoly over transmission and distribution infrastructure creates asymmetric market access that shapes competitive positioning. Two strategic archetypes dominate: integrated state utilities controlling fuel-to-wire value chains, and specialized equipment vendors supplying rehabilitation services under technical partnership frameworks. Competitive moves concentrate on preventive maintenance contract capture and distributed generation interconnection permits.
Among state-affiliated operators, CORPOELEC and PDVSA Electricidad exemplify the integrated utility archetype through their control of generation assets and grid infrastructure. Siemens Energy AG and General Electric Company occupy positions as international equipment specialists, anchoring their presence through turbine overhaul capabilities and parts logistics networks. These named entities represent the bifurcated competitive structure where domestic incumbents control market access while foreign vendors supply critical technical capacity.
| Leading Market Players |
|---|
| CORPOELEC |
| Petroleos de Venezuela SA |
| PDVSA Electricidad |
| Enel Green Power LATAM |
| Siemens Energy AG |
| General Electric Company |
| ABB Ltd |
| Schneider Electric SE |
| Vestas Wind Systems A/S |
| Others |
Value Network & Pricing Analysis
Advanced gas turbine inlet air cooling adoption at Planta Centro and Termozulia complexes simultaneously compresses fuel consumption per megawatt-hour and concentrates procurement leverage among European and US equipment specialists. This thermal efficiency intervention reshapes cost economics for aging combined-cycle units while narrowing the supplier base for rotor and blade sourcing.
Pricing Analysis
Uptime-guaranteed maintenance contracts anchor value-based pricing for thermoelectric rehabilitation services. Three-tier pricing structure across premium, standard, and economy levels differentiates by response time commitments and OEM parts inclusion. Pricing pressure stems from central bank exchange control complexity inflating project costs for international turbine suppliers. Industrial offtakers in the Orinoco Belt exhibit lowest price sensitivity given captive generation alternatives, while residential segments face cross-subsidy burdens.
Supply Chain Analysis
Direct-to-plant technical partnerships handle specialized gas turbine overhaul demand from CORPOELEC and PDVSA Electricidad. Manufacturing concentration rests on Germany, the United States, and Italy for heavy-duty turbine components and digital control systems. Spare parts supply chains draw from precision casting facilities for high-temperature alloys and synchronous inverter electronics for distributed generation compliance. Single-source vulnerability persists for Siemens and General Electric proprietary rotor designs subject to sanctions-related payment restrictions. Distribution runs through bonded warehouse arrangements in Panama and Miami to navigate import financing complexities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Venezuela's power sector operates as a supply-constrained rehabilitation market where turbine technician skill scarcity props pricing for international service providers. Capacity bottlenecks in specialized overhaul expertise sustain margin structures despite sovereign payment risk.
For Market Incumbents: Deepen preventive maintenance contract capture at Tacoa and Ramón Laguna aging thermoelectric units to lock out emerging technical service entrants. Secure exclusive spare parts stocking agreements with European OEMs before grid code compliance deadlines for distributed generators above 500 kW reshape interconnection permitting. Vertical integration into associated gas capture logistics with PDVSA Electricidad defends fuel supply security for Planta Centro output commitments. For New Entrants and Emerging Players: Distributed solar inverter certification services present a technology-first wedge into the Valencia and Maracaibo commercial banking clusters facing mandatory anti-islanding protection requirements. Target rooftop installation partnerships with dollar-denominated revenue streams to bypass bolivar tariff collection risk. Grid-scale battery feasibility studies at 230 kV substations offer the most penetrable entry point under emerging ancillary service frameworks from the national regulator. For Investors and Strategic Acquirers: Re-rating potential sits with specialized turbine overhaul service providers given Orinoco Belt industrial expansion restarting steam-intensive processes. Long-term viability favors asset-light technical partnerships over generation asset ownership given CORPOELEC's statutory monopoly over transmission infrastructure. Acquisition focus should center on firms with Siemens and General Electric authorized service credentials. The signal to watch is Ministry of Electric Power tariff enforcement consistency for industrial consumers above 1 MW.| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Contract Expansion | Systematic overhaul programs at aging Tacoa and Ramón Laguna units secure recurring revenue streams beyond emergency repair cycles. |
| Grid-Scale Battery Feasibility Deployment | Frequency regulation services at 230 kV substations unlock revenue streams under emerging ancillary service frameworks from the national regulator. |
| Distributed Solar Certification Acceleration | Synchronous inverter and anti-islanding protection compliance secures interconnection permits before Ministry of Electric Power enforcement phases begin. |
| Associated Gas Capture Partnership | Fuel supply agreements with PDVSA's eastern field operations restore availability for combined-cycle units at Planta Centro and Termozulia. |
| Bilateral Power Purchase Agreement Structuring | Direct negotiations with aluminum smelters and steel producers in Ciudad Guayana bypass CORPOELEC reliability failures exceeding 40 percent annual downtime. |
Research Methodology
Regulatory filings from the Ministry of Electric Power, PDVSA operational disclosures, and CORPOELEC infrastructure rehabilitation announcements formed the secondary backbone for capacity and demand modeling. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists validated technical assumptions on turbine overhaul lead times and gas capture recovery trajectories. Customs and trade data on generator set imports supplemented bottom-up and top-down triangulation for distributed generation deployment estimates.
Bottom-up capacity modeling across generation, transmission, distribution, and retail service tiers anchored the analytical lens, cross-checked against top-down macroeconomic load growth assumptions. Segmentation dimensions spanned fuel source, end-user payment currency exposure, project scale, and regional grid reliability tier. CAGRs were derived from iterative reconciliation of asset rehabilitation timelines against industrial demand restart schedules in the Orinoco Belt. Forecast inputs incorporated Guri reservoir sedimentation constraints and associated gas capture improvement curves from eastern oil field operations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under drought cycle severity and sanctions regime evolution. Periodic stress-testing of base assumptions is recommended given sovereign payment risk and central bank exchange control policy volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Indonesia Power Market
Power Generation
Wind Power EPC Market
Power Generation
LAMEA Microturbine Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Oman Power Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Stirling Engine Market
Power Generation
Captive Power Plant Market
Power Generation
Power Generation Technologies Market
Power Generation
Global Gas Turbines Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Distributed Generation Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Residential Solar Generator Market
Power Generation
Mobile Power Plant Market
Power Generation
Gas Turbines in Thermal Power Market