
 Stirling Engine Market | 2026-2036
Stirling Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Stirling Engine Market Intelligence
Power generation is decoupling from conventional diesel backup as microgrids and remote installations prioritize low-noise, multi-fuel thermal converters. Sunpower Inc. (AMETEK) leverages its NASA heritage and linear alternator expertise to dominate free-piston designs for space and terrestrial power. Qnergy Ltd. sustains a narrow focus on oil and gas methane mitigation, where its sealed engines convert fugitive emissions into usable electricity without combustion. Azelio anchors thermal energy storage integration, pairing Stirling cycles with molten aluminum heat batteries for dispatchable renewable output.
A Stirling engine operates through cyclic compression and expansion of a working gas at varying temperatures, achieving thermal efficiencies up to 40 percent with external combustion that accepts any heat source. Its primary commercial purpose centers on applications demanding high reliability, low vibration, or fuel flexibility where internal combustion fails. Free piston engines command premium positioning in aerospace and cryogenic cooling due to elimination of crankshaft wear and hermetic sealing capability. Solar driven engines retain niche growth in concentrated solar power installations where dish-Stirling systems convert direct radiation to grid electricity. Traditional Stirling technology remains the volume baseline for residential micro-CHP units across European district heating networks.
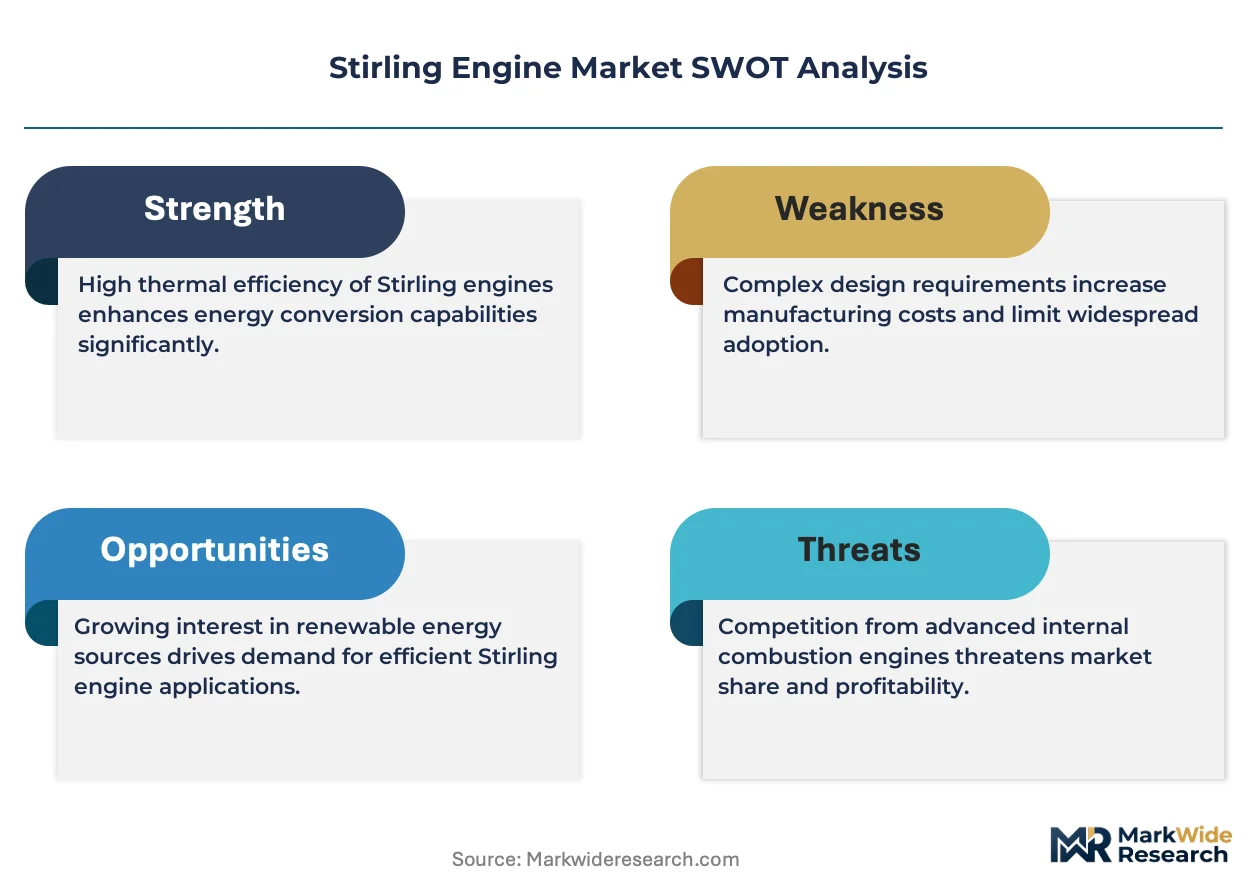
The EPA enforces stationary source emissions limits that disqualify conventional generators in non-attainment zones, redirecting procurement toward external combustion alternatives. REACH and the EU F-Gas Regulation constrain working fluid selections, pressuring manufacturers toward helium and nitrogen systems over hydrogen or organic carriers. China's GB standards and MIIT efficiency mandates for distributed energy equipment create certification barriers that favor established regenerator-type suppliers. Stakeholders must monitor evolving carbon border adjustments and working fluid phase-down schedules to preserve market access and technology roadmaps.
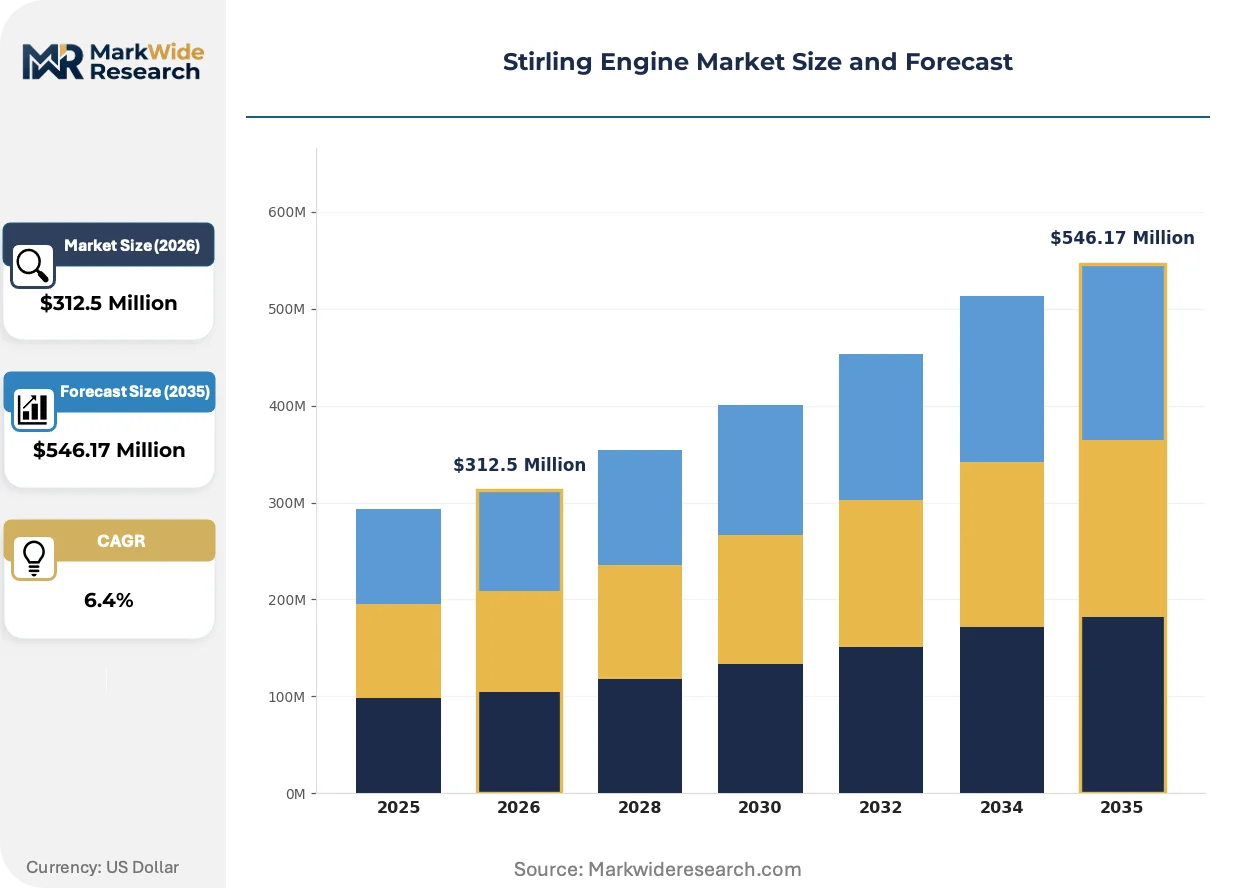
Market Dynamics
Regenerative-type Stirling architectures are displacing conventional kinematic designs as distributed energy policies in China, Germany, and the United States harden emissions thresholds for non-attainment zones and industrial clusters.
Growth Catalysts
- EPA Stationary Source Standards:Non-attainment zone designations disqualify diesel backup generators across California, Texas, and Northeast corridor industrial parks, redirecting procurement toward external combustion alternatives.
- Marine Propulsion Electrification:IMO decarbonization timelines and port authority zero-emission mandates in Hamburg, Rotterdam, and Singapore are accelerating Stirling-electric hybrid installations for auxiliary power.
- Molten Aluminum Thermal Batteries:Azelio's storage-integrated systems pair dispatchable heat discharge with Stirling conversion, creating 24-hour renewable output profiles for off-grid mining and telecom installations.
Market Restraints
- Helium Supply Concentration:Working fluid procurement depends on Qatar, Algeria, and Russia extraction, exposing manufacturers to geopolitical disruption and price volatility in noble gas markets.
- Regenerator Fouling Degradation:Micro-particulate accumulation in mesh-type heat exchangers degrades thermal efficiency below 30 percent within 8,000 operating hours without maintenance protocols.
- Lithium-Ion Substitution:Battery-electric microgrids achieve lower levelized cost of electricity in sub-100kW installations, compressing Stirling addressable market in residential and small commercial segments.
Strategic Opportunities
- India Distributed Solar-CSP Hybrid:Rajasthan and Gujarat concentrated solar parks with 16-hour thermal storage cycles present unserved demand for dish-Stirling prime movers in 25-50kW modular configurations.
- EU F-Gas Phase-Down:Hydrocarbon and HFC working fluid prohibitions under the 2024-2030 schedule create forced replacement cycles in European cryocooler and precision cooling applications.
- Oilfield Methane Monetization:Qnergy's sealed free-piston architecture converts vented and fugitive emissions at wellheads without combustion, qualifying for IRA 45Q credits and EU carbon border adjustment exemptions.
Industry Challenges
- Thermodynamic Simulation Expertise:Computational fluid dynamics modeling for regenerator optimization requires rare cross-training in cryogenics, combustion, and precision manufacturing disciplines.
- Multi-Jurisdictional Certification:CE marking, UL listing, and China's GB standards impose divergent pressure vessel and electrical safety protocols, extending product launch timelines by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stirling Engine Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Temperature Differentials, High Temperature Differentials, Free Piston Engines, Solar Driven Engines Application: Power Generation, Automotive Use, Cryogenic Refrigeration, Marine Propulsion End User: Residential, Commercial, Industrial, Research Institutions Technology: Traditional Stirling, Regenerator Type, Alpha Type, Beta Type |
| Companies Covered | Microgen Engine Corporation, United Sun Systems International Ltd. (TEXEL), Sunpower Inc. (AMETEK), Stirling Energy Systems, Frauscher Motors GmbH, Qnergy Ltd., ADI Thermal Power Corporation, Shanghai Marine Diesel Engine Research Institute, Azelio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stirling Engine Market Strategic Shifts & Innovations
Linear alternator architectures and hermetic sealing protocols are compressing maintenance intervals and expanding addressable applications beyond traditional kinematic engine limitations.
Free-piston Stirling engines with clearance-sealed gas bearings and moving-magnet linear alternators are overtaking crankshaft-driven kinematic designs in aerospace power and cryogenic cooling applications. NASA and ESA satellite programs specify hermetic units for 15-year unattended operation. The elimination of lubricated wear surfaces enables maintenance-free deployment in lunar surface power and deep-space probe missions.
Europe's F-Gas Regulation mandates 79 percent HFC reduction by 2030, forcing working fluid transitions in precision cooling and Stirling cryocooler supply chains. Manufacturers are qualifying helium and nitrogen systems to replace R-23 and R-508B in MRI magnet cooling and infrared sensor applications. German and French medical device suppliers face compressed redesign timelines to maintain CE marking validity.
Utility procurement departments now specify outcome-based thermal service contracts rather than equipment ownership in district heating and industrial cogeneration installations. Copenhagen, Stockholm, and Hamburg municipal utilities contract for guaranteed heat output and availability, transferring operational risk to Stirling system operators. This model accelerates adoption in capital-constrained municipal markets while compressing vendor margins.
Stirling Engine Market Segmentation
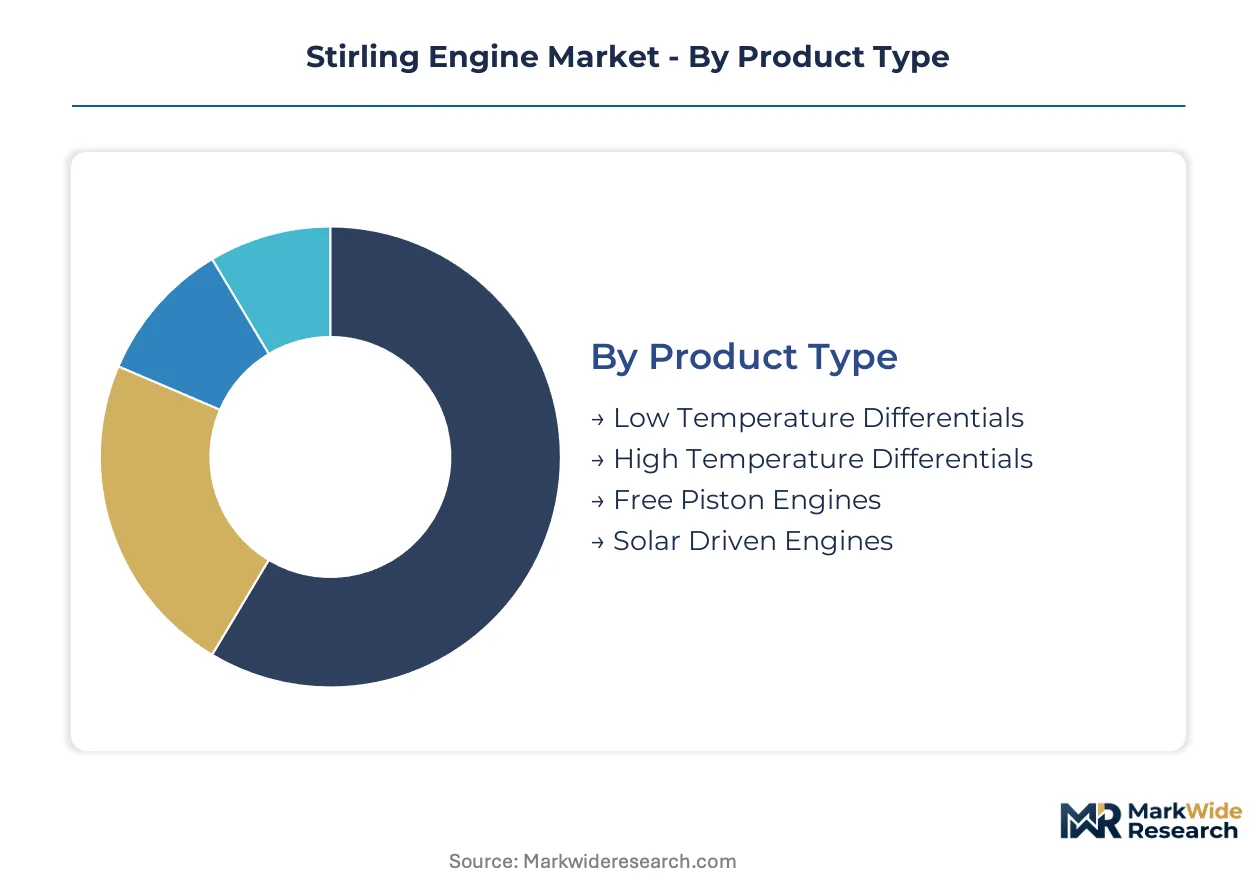
Stirling engine procurement varies sharply by thermal source temperature, mechanical configuration, and duty cycle requirements. Buyers in power generation prioritize fuel flexibility and emissions compliance, while aerospace and medical applications demand hermetic sealing and maintenance-free operation.
Product Type:
Cost tier separates buyers seeking commodity thermal conversion from those requiring precision-engineered, long-life systems.
- Low Temperature Differentials:These engines exploit temperature gaps below 100°C using organic working fluids or pressurized gases. Waste heat recovery installations in German industrial parks and Japanese district heating networks drive procurement, constrained by large heat exchanger surface requirements and extended payback periods.
- High Temperature Differentials:Operating above 500°C with helium or hydrogen working fluids, these systems achieve maximum thermodynamic efficiency. Demand concentrates in Chinese distributed cogeneration plants and US remote power installations where fuel flexibility offsets higher capital costs.
- Free Piston Engines:Linear alternator designs eliminate crankshaft mechanisms for hermetic, lubrication-free operation. NASA satellite programs and ESA deep-space missions specify these for multi-decade unattended service.
- Solar Driven Engines:Dish-Stirling concentrator systems convert direct solar radiation to grid electricity. Rajasthan and Gujarat concentrated solar parks in India present unserved demand for modular 25-50kW configurations with thermal storage integration.
Volume sits with Low Temperature Differentials in European district heating retrofits; growth tilts toward Free Piston Engines as aerospace and cryogenic cooling specifications harden.
Application:
Application selection tracks regulatory pressure intensity and fuel access constraints across end-use environments.
- Power Generation:External combustion architecture enables multi-fuel operation including biogas, landfill methane, and synthetic fuels. EPA non-attainment zone designations in California and Texas redirect procurement from diesel backup toward Stirling microgrids.
- Cryogenic Refrigeration:Reverse-Stirling cycles achieve temperatures below 10K for MRI magnet cooling and infrared sensor applications. EU F-Gas Regulation phase-down of HFC working fluids forces redesign timelines for German and French medical device suppliers.
- Automotive Use:Range-extender applications in hybrid electric vehicles exploit silent operation and fuel flexibility. Development programs at several OEMs remain constrained by power density limitations versus internal combustion alternatives.
- Marine Propulsion:IMO decarbonization timelines and port authority zero-emission mandates in Hamburg, Rotterdam, and Singapore accelerate Stirling-electric hybrid installations for auxiliary power systems.
Power Generation commands current procurement volume; Cryogenic Refrigeration offers the steepest expansion trajectory as F-Gas prohibitions compress redesign cycles.
End User:
Customer type determines financing structure, maintenance capability, and tolerance for operational complexity.
- Industrial:Continuous-duty cogeneration applications in chemical processing and food manufacturing exploit waste heat recovery. Chinese MIIT efficiency mandates for distributed energy equipment favor regenerator-type suppliers with established GB certification.
- Commercial:Hotels, hospitals, and data centers prioritize reliability and low noise over peak efficiency. Outcome-based thermal service contracts in Copenhagen and Stockholm municipal utilities transfer operational risk to vendors.
- Residential:European micro-CHP units integrate with existing district heating infrastructure. Lithium-ion battery cost declines compress addressable market in sub-100kW installations.
- Research Institutions:Specialized applications in materials science and cryogenics demand custom engineering with extended validation protocols.
Industrial segment anchors revenue concentration; Commercial installations are expanding most quickly under performance-contracting procurement models.
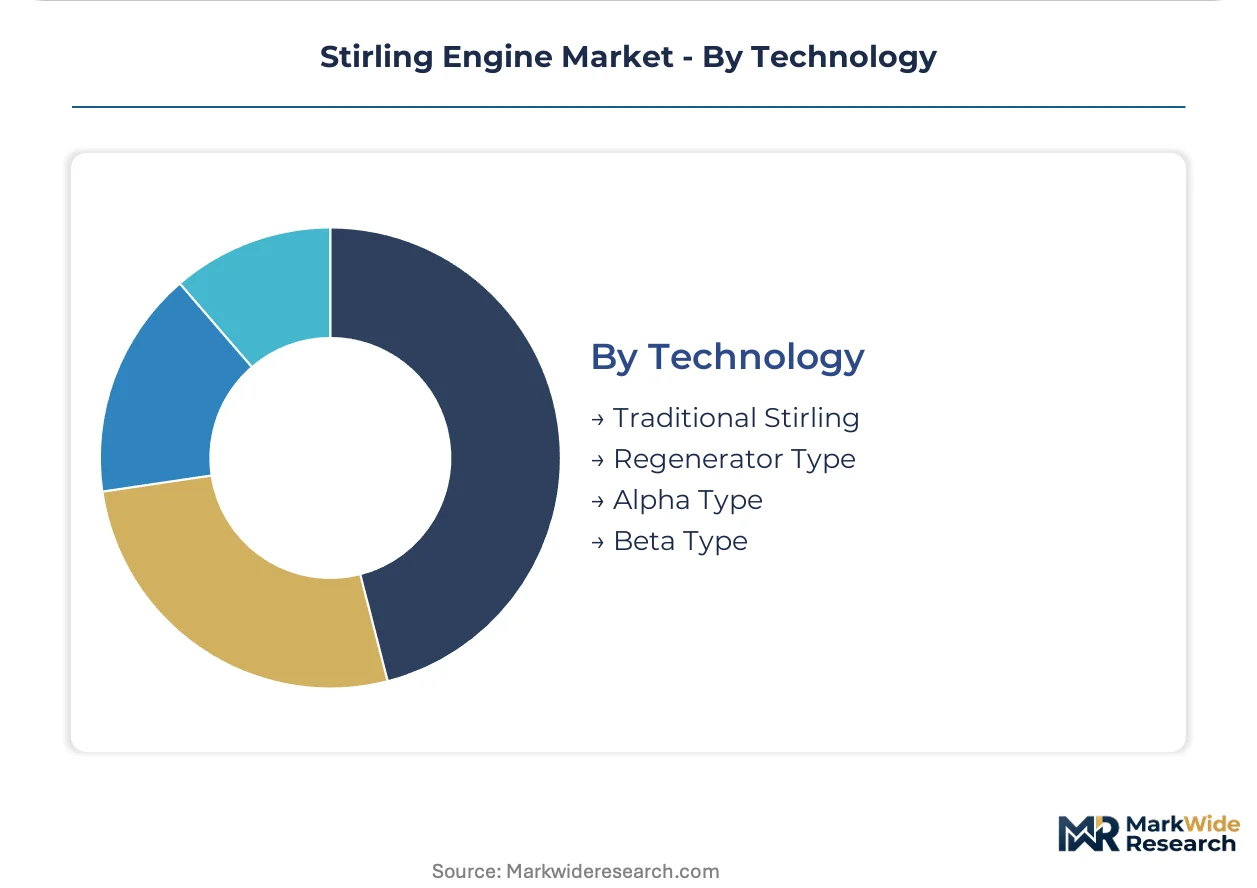
Technology:
Technology choice reflects the trade-off between manufacturing maturity and thermodynamic efficiency optimization.
- Regenerator Type:Porous matrix heat exchangers store and release thermal energy between cycles, achieving efficiencies above 35%. Chinese and German industrial cogeneration specifications increasingly mandate regenerator architectures for emissions compliance.
- Traditional Stirling:Kinematic crankshaft-driven designs dominate residential and small commercial volumes through established supply chains and simplified maintenance protocols.
- Alpha Type:Dual-piston configurations with separate power and displacement cylinders suit high-power applications. Marine and stationary power installations exploit the balanced reciprocating mass for reduced vibration.
- Beta Type:Coaxial piston and displacer arrangements minimize dead volume for compact packaging. Limited adoption outside specialized cryocooler and portable power niches.
Traditional Stirling retains volume leadership in cost-sensitive segments; Regenerator Type gains share fastest as distributed energy policies harden efficiency thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and Germany's Ruhr industrial corridor concentrate regenerator-type manufacturing capacity. India's Rajasthan Solar Park and the UAE's Masdar City cluster anchor concentrated solar power installations. Tax incentives in these zones redirect procurement toward external combustion systems as emissions policies tighten across industrial parks.
United States
EPA non-attainment zone designations in California's Central Valley and Texas Gulf Coast petrochemical corridors disqualify diesel backup generators. The Inflation Reduction Act's 45Q credits monetize methane capture at Permian Basin wellheads. Houston industrial parks deploy sealed free-piston units for auxiliary power in zero-emission port mandates.
Germany
Industrial cogeneration demand concentrates in North Rhine-Westphalia's chemical processing belt and Bavaria's automotive supplier networks. The EU F-Gas Regulation forces working fluid transitions from HFC blends to helium systems by 2030. Hamburg port authority zero-emission mandates accelerate Stirling-electric hybrid installations for auxiliary marine power.
China
MIIT efficiency mandates for distributed energy equipment favor regenerator-type suppliers with established GB certification. Yangtze River Delta special economic zones host concentrated manufacturing of high-temperature differential engines. Shandong Province industrial parks deploy waste heat recovery systems under dual carbon policy targets.
India
Rajasthan and Gujarat concentrated solar parks present unserved demand for dish-Stirling prime movers in 25-50kW modular configurations. The Ministry of New and Renewable Energy's solar-wind hybrid guidelines incentivize thermal storage integration. Gujarat Special Investment Regions attract molten aluminum battery paired installations for off-grid mining operations.
Japan
Precision cooling applications in Osaka-Kobe medical device clusters face compressed redesign timelines under fluorinated gas phase-down schedules. METI's hydrogen society roadmap tests Stirling cycles for ammonia cracking heat recovery. Kyushu region geothermal plants evaluate low-temperature differential engines for binary cycle augmentation.
Stirling Engine Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with hermetic sealing expertise commanding premium positioning in aerospace and cryogenic applications. The vendor base organizes into three functional tiers: NASA heritage linear alternator specialists, oilfield methane monetization pure-plays, and thermal storage integrators. Consolidation pressure concentrates in European cryocooler supply chains as F-Gas prohibitions compress redesign windows. Dominant competitive moves include technology licensing for regenerator optimization protocols and backward integration into noble gas working fluid supply.
Among aerospace and precision cooling specialists, Sunpower Inc. occupies a position exemplifying hermetic sealing and linear alternator heritage. Qnergy Ltd. represents the methane mitigation archetype with sealed architectures for oilfield deployment. Azelio anchors thermal storage integration, pairing Stirling conversion with dispatchable heat discharge systems. These three entities illustrate divergent strategic vectors: space-terrestrial power crossover, emissions compliance service models, and renewable output firming.
| Leading Market Players |
|---|
| Microgen Engine Corporation |
| United Sun Systems International Ltd. (TEXEL) |
| Sunpower Inc. (AMETEK) |
| Stirling Energy Systems |
| Frauscher Motors GmbH |
| Qnergy Ltd. |
| ADI Thermal Power Corporation |
| Shanghai Marine Diesel Engine Research Institute |
| Azelio |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between hermetically sealed free-piston units and conventional kinematic designs manifests in pricing premiums of 40-60 percent for aerospace-qualified systems, while supply chain configurations bifurcate between Qatar-dependent helium sourcing for high-temperature differentials and localized nitrogen system assembly for commercial cogeneration.
Pricing Analysis
Lead-time-driven pricing stratification rewards expedited delivery of regenerator-type engines for EPA non-attainment zone retrofits with 15-25 percent premiums, while spot inventory of traditional kinematic units trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects UL/CE certification grade, helium versus nitrogen working fluid selection, and after-sales service bundling. Cost compression in residential micro-CHP intensifies because lithium-ion substitution erodes addressable market share. Industrial cogeneration buyers exhibit lowest price sensitivity due to outcome-based thermal service contracting, while residential segment procurement faces acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Germany's Ruhr corridor and China's Yangtze River Delta maintain 6-10 week finished goods inventory for European and Asian industrial clusters respectively. Manufacturing concentrates in Germany, China, and the United States for regenerator fabrication and precision machining. Helium procurement draws from Qatar, Algeria, and Russia extraction; rare-earth magnet supply for linear alternators rests on Chinese processing dominance. Single-source vulnerability in noble gas working fluids exposes manufacturers to geopolitical disruption. Distribution runs through authorized service networks for hermetic units and direct OEM relationships for utility-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over helium working fluid supply and regenerator mesh manufacturing determines margin sustainability against lithium-ion substitution pressure.
For Market Incumbents: Anticipate F-Gas Regulation phase-down deadlines by accelerating helium and nitrogen system qualification timelines ahead of 2030 prohibitions. Backward integration into noble gas supply contracts with Qatar and Algeria extraction facilities secures working fluid access against geopolitical disruption. Regenerator fouling degradation below 30 percent efficiency thresholds threatens recurring revenue streams; predictive maintenance protocols preserve service contract renewals. For New Entrants and Emerging Players: Rajasthan and Gujarat concentrated solar park developers represent an underserved buyer archetype lacking indigenous dish-Stirling manufacturing capacity. Modular 25-50kW configurations with molten aluminum thermal storage integration penetrate this white space faster than utility-scale competition. Licensing regenerator optimization protocols from established suppliers accelerates GB certification timelines for Chinese MIIT compliance. For Investors and Strategic Acquirers: Re-rating potential sits with hermetic sealing specialists given NASA and ESA satellite program procurement acceleration for lunar surface power missions. Long-term viability across the analysis window favors vendors with demonstrated 15-year unattended operation records and established CE/UL dual certification. Acquisition target archetype: mid-cap regenerator-type manufacturers with established Chinese GB certification and stranded helium supply contracts. The signal to watch is F-Gas Regulation enforcement intensity in German and French medical device supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Supply Contracting | Captive sourcing from Qatar and Algeria extraction secures working fluid access against geopolitical price volatility. |
| Regenerator Optimization Licensing | Technology transfer agreements compress 14-22 month multi-jurisdictional certification timelines for new market entrants. |
| Thermal Storage Integration | Molten aluminum battery pairing creates 24-hour dispatchable renewable output profiles for off-grid mining installations. |
| Outcome-Based Service Contracting | Copenhagen and Stockholm municipal utilities transfer operational risk to vendors while accelerating capital-constrained procurement. |
| F-Gas Compliance Redesign | German and French medical device suppliers face compressed timelines to maintain CE marking validity under 2030 HFC prohibitions. |
Research Approach
Trade association filings, EIA distributed generation databases, and EU F-Gas Regulation implementation reports formed the secondary backbone, supplemented by customs records tracking helium and rare-earth magnet flows. Primary interviews with Stirling system engineering directors, utility procurement officers, oilfield methane mitigation specialists, and aerospace power systems managers validated technical specifications and pricing benchmarks. Bottom-up unit economics modeling triangulated against top-down sectoral demand projections from MIIT efficiency mandate disclosures and EPA non-attainment zone designations.
Bottom-up segmentation analysis modeled regenerator-type versus traditional kinematic configurations, helium versus nitrogen working fluid selection, and aerospace versus terrestrial application splits across the projection horizon. Top-down validation incorporated distributed energy policy intensity scores and carbon border adjustment exposure indices. CAGRs were derived from installed base growth rates and replacement cycle compression under emissions regulations. Forecast inputs included F-Gas phase-down enforcement schedules and IRA 45Q credit monetization timelines for oilfield methane capture.
Revisions become necessary when F-Gas Regulation enforcement intensity, helium supply disruptions, or lithium-ion cost trajectories materially diverge from baseline assumptions. Forecasts reflect documented parameters around regenerator fouling degradation curves and multi-jurisdictional certification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Commercial Gensets Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Global Power to Gas Market
Power Generation
Peaking Power Plant Market
Power Generation
Thermal Power Market
Power Generation
LAMEA Microturbine Market
Power Generation
Europe Thermal Power Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
Mobile Power Plant Market
Power Generation
Subsea Power Grid System Market
Power Generation
South East Asia Power Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
United Kingdom Power Market
Power Generation
Combined Cycle Power Plant Market