
 Natural Gas Market | 2026-2036
Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Gas Market Intelligence
The unbundling of long-term supply contracts from rigid oil-price indexation is hardening buyer preferences for spot-market pricing and destination flexibility. QatarEnergy specializes in large-scale, long-duration LNG supply agreements. Shell plc leverages its global trading portfolio to capitalize on regional price differentials. ExxonMobil Corporation sustains its position through integrated projects spanning exploration, production, and liquefaction.
Natural gas is a naturally occurring hydrocarbon gas mixture consisting primarily of methane (CH4). Its high energy content and cleaner combustion profile compared to other fossil fuels make it a primary source for power generation, industrial heat, and residential use. The Liquefied Natural Gas (LNG) segment enables long-distance transport, representing the fastest-growing type. Within applications, power generation remains the dominant consumption category, while its use as a chemical feedstock for producing hydrogen and ammonia is expanding.
Regulatory frameworks like the US Federal Energy Regulatory Commission's (FERC) oversight of interstate pipelines and the EU Green Deal's taxonomy for sustainable activities shape investment. In China, the Ministry of Ecology and Environment (MEE) promotes gas usage to meet national air quality and carbon reduction targets. Stakeholder success will depend on navigating the dual pressures of ensuring energy security while aligning with decarbonization commitments.
Market Dynamics
The central dynamic in the natural gas market is the structural tension between sellers seeking long-term supply agreements to underwrite massive capital projects and buyers demanding shorter-duration, spot-indexed contracts with destination flexibility to manage price risk and market uncertainty.
Growth Catalysts
- Power Sector Demand:Continued expansion of gas-fired power generation to support grid stability alongside intermittent renewables and to replace coal provides a foundational source of demand, particularly in developing Asian economies.
- EU Green Taxonomy:The European Union's classification of natural gas power plants as transitional activities under its sustainable finance taxonomy, subject to strict emissions limits, provides a regulatory pathway for investment in new, efficient gas infrastructure.
- Chinese Air Quality Policies:National and provincial policies enforced by China's Ministry of Ecology and Environment (MEE) to reduce coal consumption in industrial and residential sectors continue to drive substantial gas demand growth for air quality improvement.
Market Restraints
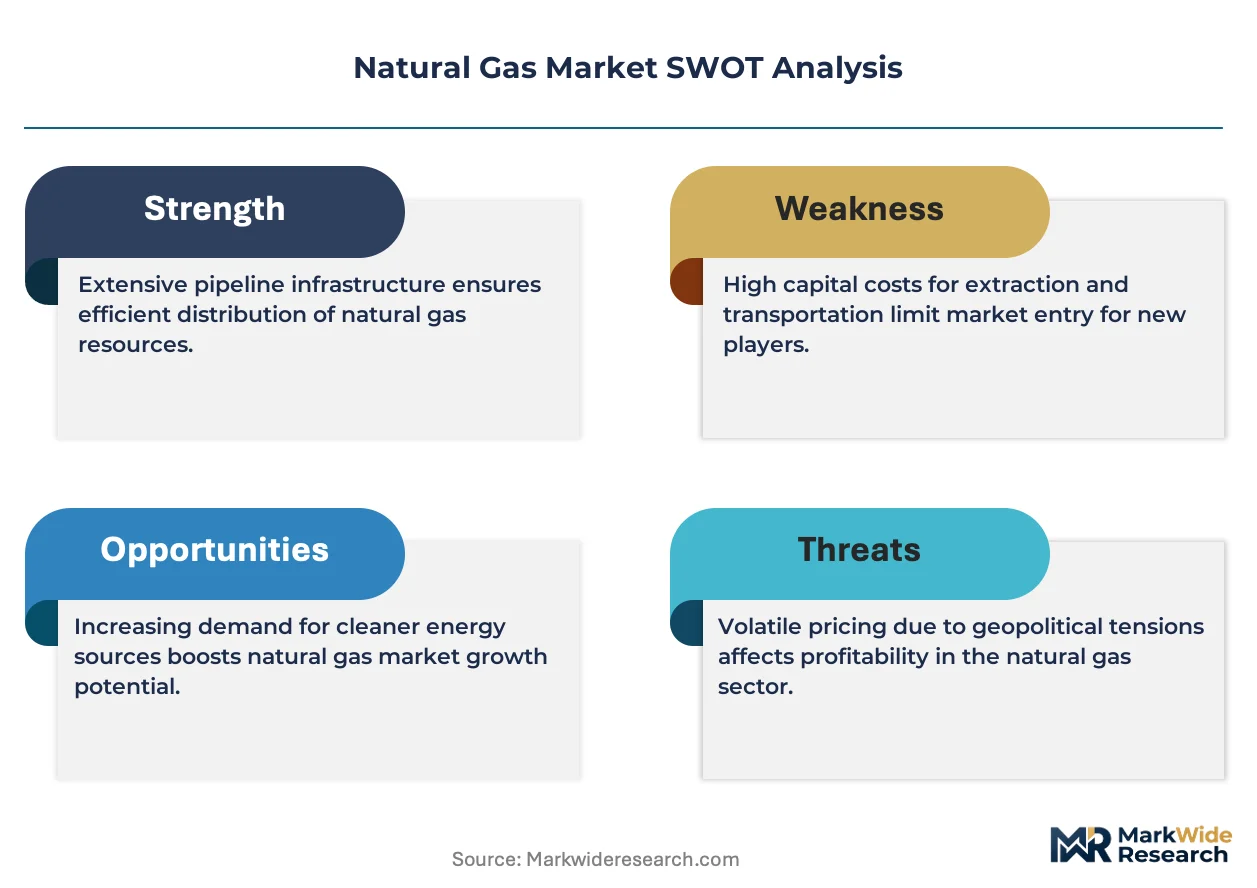
- Renewable Energy Substitution:The falling levelized cost of electricity from solar and wind power, coupled with advances in battery storage, presents a significant long-term substitution threat for natural gas in the power generation sector.
- Methane Emission Regulations:Increasingly stringent regulations on methane leaks and flaring from bodies like the US Environmental Protection Agency (EPA) raise compliance costs and operational complexity across the entire value chain.
- Infrastructure Capex Intensity:The requirement for massive, long-lead-time capital investment for LNG liquefaction plants, regasification terminals, and cross-border pipelines acts as a substantial barrier to new supply projects and market entry.
Strategic Opportunities
- Blue Hydrogen Feedstock:The use of natural gas as a primary feedstock for blue hydrogen production, when paired with carbon capture and storage (CCUS), offers a pathway to participate in the emerging low-carbon hydrogen economy.
- LNG in Marine Bunkering:Stricter international maritime emissions standards create an opportunity for LNG to displace heavy fuel oil as a cleaner marine bunker fuel, driving demand for small-scale LNG infrastructure at major ports.
- Emerging Market Access:Developing LNG import infrastructure in underpenetrated markets across Southeast Asia and sub-Saharan Africa can unlock significant new demand from countries seeking to diversify their energy mix away from oil and coal.
Industry Challenges
- Spot Price Volatility:Extreme price volatility in key regional gas hubs creates significant financial risk and planning uncertainty for producers, traders, and large-scale industrial consumers who rely on spot or short-term procurement.
- Geopolitical Supply Risk:The high concentration of proven gas reserves and export capacity in a few geopolitically sensitive regions exposes importing countries to potential supply disruptions and price shocks.
- Public & Investor Opposition:Securing social license to operate and attracting capital for new fossil fuel infrastructure is complicated by mounting pressure from environmental groups, ESG-focused investors, and a negative public perception.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Gas Market |
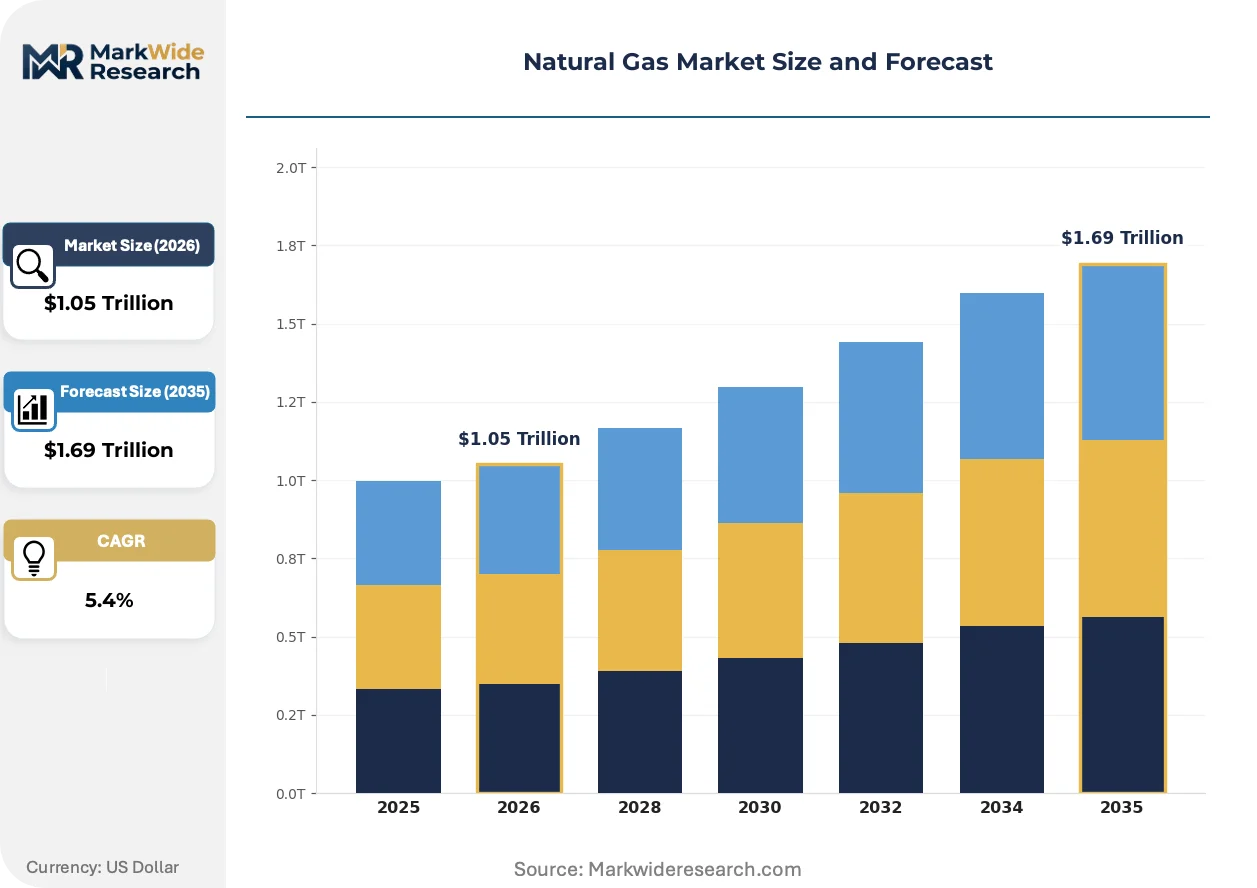
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $1.69 Trillion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquefied Natural Gas, Compressed Natural Gas, Associated Gas, Non-associated Gas, Synthetic Natural Gas Application: Power Generation, Residential Heating, Chemical Feedstock, Transportation Fuel, Electricity Production End User: Electric Utilities, Petrochemical Manufacturers, Residential Consumers, Commercial Establishments, Transportation Sector Distribution Channel: Pipeline Networks, Bottled Gas Delivery, LNG Carriers, Truck Delivery, Virtual Pipeline |
| Companies Covered | ExxonMobil Corporation, Gazprom, QatarEnergy, Shell plc, Chevron Corporation, TotalEnergies SE, PetroChina Company Limited, ConocoPhillips, Equinor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Gas Market Strategic Shifts & Innovations
The market is navigating a complex transition, balancing the immediate need for energy security with long-term decarbonization commitments. This dual pressure is accelerating innovation in both commercial models and the underlying technologies for producing, transporting, and consuming natural gas.
Floating LNG Infrastructure
Floating Liquefied Natural Gas (FLNG) and Floating Storage Regasification Unit (FSRU) systems offer modular, redeployable solutions for liquefaction and regasification. Energy importers and project developers are adopting these systems to accelerate market access and reduce the large upfront capital and footprint of onshore facilities. This flexible, faster-to-deploy offshore infrastructure is overtaking traditional, capital-intensive onshore terminal construction for market-opening projects and capacity expansions.
Transitional Finance Frameworks
The European Union's Green Deal taxonomy classifies certain natural gas activities as transitional, subject to stringent emissions and efficiency criteria. This framework directly influences investment flows by setting sustainability benchmarks that guide capital allocation for financial products marketed as green. Power generation asset owners are most affected, now needing to demonstrate compliance to secure favorable financing and align with institutional investor mandates.
Contract Structure Evolution
Large-scale utility and industrial buyers are systematically moving away from long-term contracts indexed to oil prices. This shift favors pricing mechanisms based on liquid gas hubs, such as the US Henry Hub or the European TTF, alongside a greater reliance on spot market transactions. This trend is most visible among sophisticated buyers in Europe and Asia seeking enhanced pricing transparency and destination flexibility for their LNG cargoes.
Natural Gas Market Segmentation
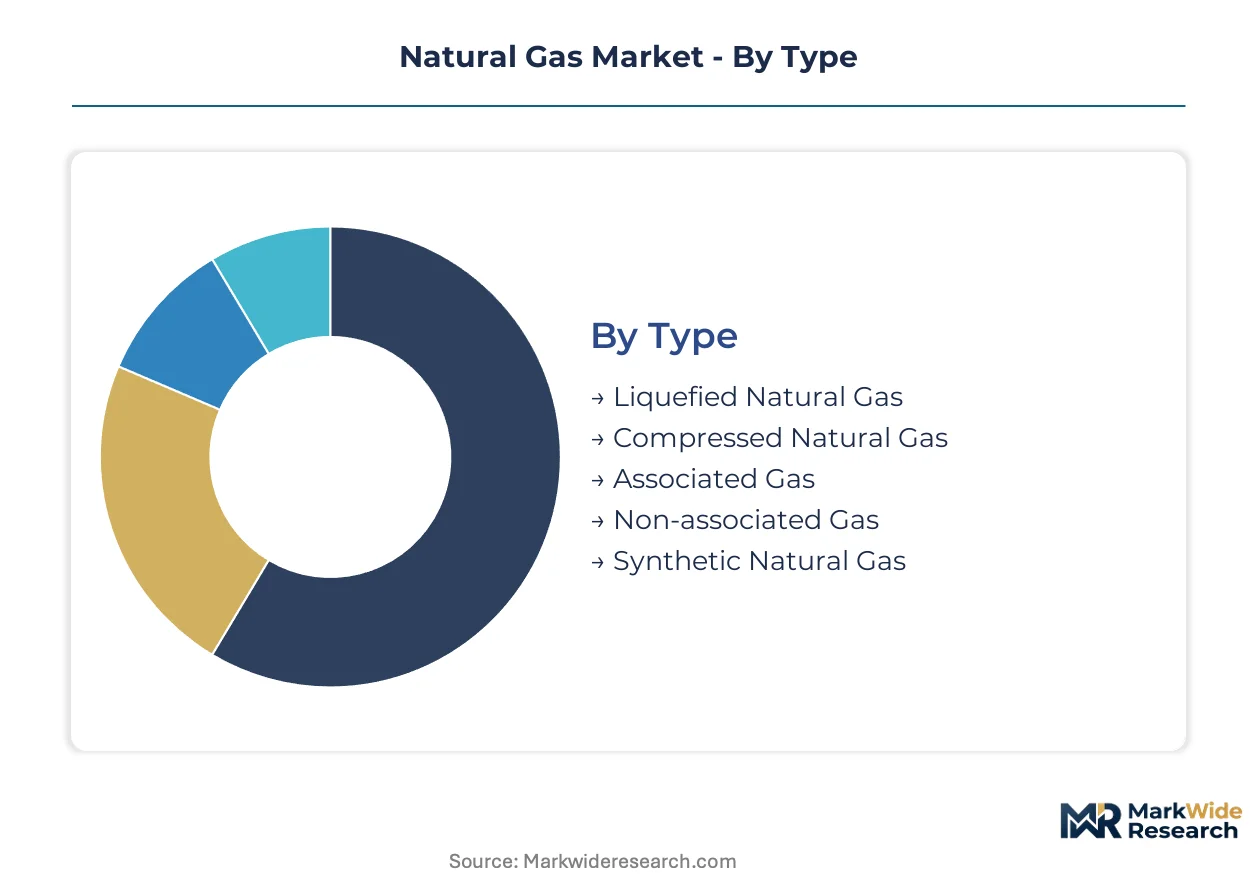
The Natural Gas Market exhibits diverse segmentation across its value chain, reflecting varied production methods, end-use applications, and distribution logistics. Understanding these distinct segments allows stakeholders to identify specific demand drivers, infrastructure requirements, and regulatory impacts across different operational contexts. This granular view is essential for strategic planning and investment decisions within the complex energy landscape.
Type:
The market's type segmentation distinguishes gas sources based on their geological origin and processing state, impacting their handling and integration into energy systems.
- Liquefied Natural Gas:This segment comprises natural gas cooled to approximately -162°C, converting it into a liquid for efficient long-distance transport via specialized vessels. Demand continues to expand in Asia, driven by energy security concerns and the need to diversify energy imports.
- Compressed Natural Gas:CNG consists of natural gas stored at high pressure, typically used as a cleaner alternative fuel for vehicles or in smaller industrial applications. Its demand is concentrating in urban transportation fleets seeking to reduce emissions and operating costs in countries like India.
- Associated Gas:This refers to natural gas found in crude oil reservoirs, often produced as a byproduct of oil extraction. Its utilization depends heavily on infrastructure for capture and processing, otherwise it is flared.
- Non-associated Gas:This gas is found in reservoirs that contain little or no crude oil, making it a primary target for dedicated gas exploration and production. It represents a significant portion of global gas supply.
- Synthetic Natural Gas:SNG is a manufactured fuel gas, produced from sources like coal, biomass, or waste, and designed to be interchangeable with pipeline natural gas. Production is concentrated in regions with abundant coal resources or waste-to-energy initiatives.
Volume placements concentrate in Non-associated Gas; the faster expansion belongs to Liquefied Natural Gas.
Application:
Application segmentation illustrates the primary uses of natural gas, highlighting its versatility across various sectors and its role in decarbonization efforts.
- Power Generation:Natural gas fuels thermal power plants, providing a flexible and lower-emission alternative to coal for electricity production. Demand is foundational across emerging economies like Vietnam, supporting grid stability alongside intermittent renewable sources.
- Chemical Feedstock:Natural gas serves as a crucial raw material for producing essential chemicals, including ammonia for fertilizers and methanol for various industrial processes. Its demand is significant in petrochemical hubs like the US Gulf Coast, driven by competitive feedstock prices.
- Residential Heating:Natural gas provides efficient heating for homes, particularly prevalent in regions with established pipeline infrastructure and cold climates. Consumption patterns are stable in mature markets across Europe and North America.
- Transportation Fuel:Natural gas powers vehicles as CNG or LNG, offering a cleaner-burning alternative to gasoline and diesel for fleets and heavy-duty transport. Adoption is growing in China's public transport and logistics sectors.
- Electricity Production:This application encompasses a broad range of processes where natural gas is converted into electrical energy, often including combined heat and power systems. Its use helps balance energy supply.
Demand for Power Generation remains foundational, while Chemical Feedstock exhibits significant expansion.
End User:
The end-user segmentation categorizes the primary consumers of natural gas, reflecting different consumption patterns, regulatory environments, and procurement strategies.
- Electric Utilities:These large-scale entities consume substantial volumes of natural gas to generate electricity for public distribution grids. Their procurement strategies often involve long-term contracts to ensure supply stability for regional populations.
- Petrochemical Manufacturers:Industrial facilities in this segment utilize natural gas as a feedstock for producing a wide array of chemicals, plastics, and fertilizers. Their demand is highly sensitive to gas prices and global commodity markets, particularly in the Middle East.
- Residential Consumers:Households use natural gas primarily for heating, cooking, and water heating, with consumption varying significantly by climate and seasonal factors. Their supply is typically managed by local distribution companies.
- Commercial Establishments:Businesses such as offices, restaurants, and retail stores consume natural gas for heating, cooling, and industrial processes. Their usage often mirrors residential patterns but with higher average volumes.
- Transportation Sector:This segment includes vehicles, ships, and trains that use natural gas as fuel, driven by emissions regulations and economic incentives. Adoption is concentrated in specific fleet operations and maritime shipping routes.
Large-scale consumption by Electric Utilities stabilizes the market, whereas Petrochemical Manufacturers represent a growth frontier.
Distribution Channel:
Distribution channel segmentation outlines the various methods used to transport natural gas from production sites to end-users, highlighting infrastructure requirements and logistical complexities.
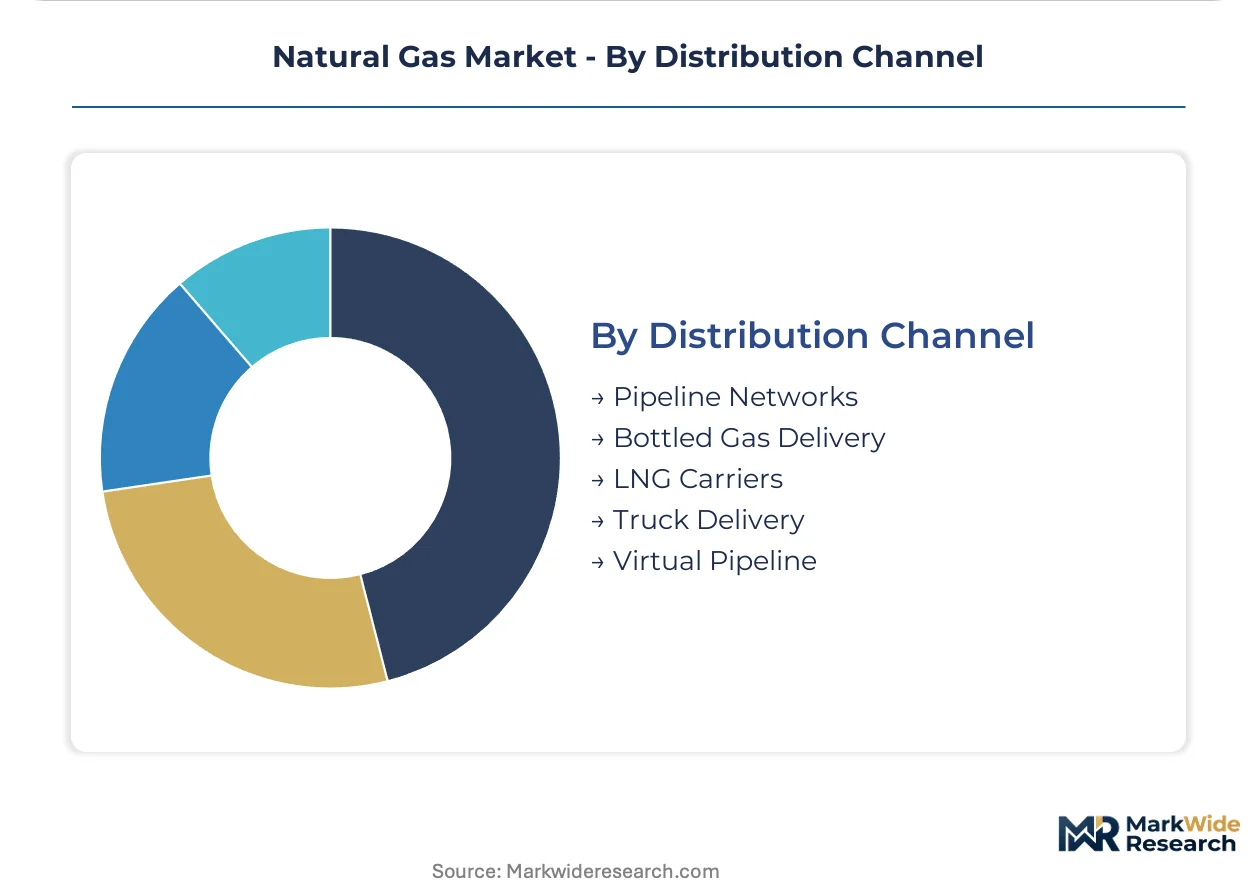
- Pipeline Networks:Extensive systems of interconnected pipelines transport natural gas over long distances from production fields to consumption centers. These networks form the backbone of gas distribution in North America and Europe, ensuring reliable, high-volume delivery.
- LNG Carriers:Specialized ships designed to transport liquefied natural gas across oceans, enabling intercontinental trade and access to diverse supply sources. These vessels are crucial for connecting major gas-producing regions with distant, energy-hungry markets in Asia.
- Bottled Gas Delivery:Natural gas, typically in the form of LPG (liquefied petroleum gas) or sometimes CNG, is delivered in cylinders to residential and commercial users in areas without pipeline access. This method serves remote communities and niche applications.
- Truck Delivery:Compressed or liquefied natural gas is transported by road tankers, often serving industrial sites or power plants not connected to main pipelines. This channel provides flexibility for smaller-scale or temporary supply needs.
- Virtual Pipeline:This concept involves transporting natural gas in compressed or liquefied form via road, rail, or barge, bypassing traditional pipeline infrastructure to reach isolated markets. It offers a solution for expanding gas access to remote regions.
Established infrastructure like Pipeline Networks ensures baseline supply, while innovations in Virtual Pipeline are enhancing market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global natural gas market exhibits a clear division between major producing nations and significant consuming regions. Production centers in North America and the Middle East contrast with high demand in Asia and Europe. This dynamic shapes global trade flows and investment in infrastructure.
United States
United States demand for natural gas remains robust, driven by extensive power generation and its role as a chemical feedstock. The US Federal Energy Regulatory Commission (FERC) regulates interstate pipelines, ensuring efficient transport. The US Gulf Coast region, particularly around Houston, continues to expand its LNG export terminal capacity.
China
China's substantial demand for natural gas stems from national policies to improve air quality and provide industrial heat. The Ministry of Ecology and Environment (MEE) actively promotes gas usage to meet carbon reduction targets. Cities within the Yangtze River Delta are rapidly converting industrial and residential energy systems to natural gas.
Germany
Germany utilizes natural gas extensively for power generation and various industrial processes, balancing energy security with decarbonization goals. The EU Green Deal taxonomy provides a framework for investment in new, efficient gas infrastructure. Industrial centers in the Ruhr Valley are actively exploring natural gas as a feedstock for blue hydrogen production.
Japan
Japan's energy mix heavily relies on natural gas for stable electricity generation and industrial energy needs due to limited domestic resources. The Ministry of Economy, Trade and Industry (METI) plays a central role in guiding the country's long-term LNG procurement strategies. Major urban centers such as Tokyo and Osaka are primary recipients of these imported LNG cargoes.
Qatar
Qatar stands as a major global exporter of liquefied natural gas, capitalizing on its immense reserves and strategic location. QatarEnergy, the national energy company, spearheads investment in large-scale LNG production and export facilities. Ras Laffan Industrial City serves as the primary hub for the nation's extensive liquefaction and export operations.
Natural Gas Market Key Industry Players
The competitive structure tilts toward integrated energy majors and state-owned enterprises, reflecting the substantial capital and long lead times required for natural gas projects. The market exhibits a tiered structure, with a few global players dominating large-scale production, processing, and LNG trade. Key strategic archetypes include upstream specialists, integrated value chain players, and commodity traders. Companies primarily engage in capacity expansion, strategic partnerships, and technology adoption to secure long-term supply agreements and optimize their global portfolios.
Within the integrated energy major archetype, ExxonMobil Corporation exemplifies a strategy focused on large-scale, integrated projects spanning exploration, production, and liquefaction, maintaining a robust global presence. Shell plc, a global energy company, represents a powerful trading and portfolio optimization capability, leveraging its extensive global reach to capitalize on regional price differentials and manage market volatility. QatarEnergy, a state-owned enterprise, anchors the market's supply side through its specialization in large-duration LNG supply agreements, securing long-term export commitments.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Gazprom |
| QatarEnergy |
| Shell plc |
| Chevron Corporation |
| TotalEnergies SE |
| PetroChina Company Limited |
| ConocoPhillips |
| Equinor |
| Others |
Cost & Logistics Intelligence
The divergence between long-term contract pricing and spot market pricing in natural gas shapes both financial risk management and the physical supply chain configuration. This bifurcation influences investment in infrastructure and buyer procurement strategies.
Pricing Analysis
Extreme price volatility in key regional gas hubs creates significant financial risk for producers and large-scale industrial consumers. The market utilizes a hybrid pricing model, blending long-term contract-based offtake agreements with commodity spot pricing for immediate or flexible needs. Price differentiation stems from destination flexibility, contract duration, and the energy content of the gas. Industrial consumers demonstrate high price sensitivity, while electric utilities prioritize supply stability, often accepting higher, fixed costs for reliable delivery.
Supply Chain Analysis
Pipeline networks and LNG carriers form the backbone of natural gas distribution, enabling long-distance transport from production to consumption centers. Supply concentrates in Qatar, the United States, and Russia, creating geopolitical supply risk for importing nations. The supply chain relies on massive investments in gas processing infrastructure, liquefaction plants, and specialized LNG vessels. This concentration exposes importing countries to potential price shocks and disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural gas market represents a vertical-integration race, with key players actively pursuing control over upstream production and downstream liquefaction and regasification capacity. Securing these assets provides strategic advantage in managing global supply and price volatility.
For Market Incumbents: Anticipate continued pressure from renewable energy substitution by strategically investing in carbon capture and storage (CCUS) for blue hydrogen production. Expand existing LNG liquefaction capacity in key export hubs like the US Gulf Coast. Deepen vertical integration into emerging low-carbon energy vectors to diversify revenue streams. Control over infrastructure mitigates long-term demand shifts.
For New Entrants and Emerging Players: A significant price-point gap exists for flexible, smaller-scale LNG supply in underpenetrated markets across Southeast Asia and Sub-Saharan Africa. Target developing LNG import infrastructure using modular solutions like Floating Liquefied Natural Gas (FLNG) and Floating Storage Regasification Units (FSRUs). This approach offers faster market access and reduced upfront capital expenditure. Focus on countries seeking to diversify their energy mix away from coal.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated gas-to-power developers and established LNG terminal operators, offering stable long-term returns over a 5-10 year horizon. Evaluate opportunities in companies with robust project pipelines and strong off-take agreements. The acquisition target archetype favors entities controlling critical infrastructure assets. Monitor regulatory clarity on carbon pricing mechanisms or blue hydrogen production incentives for inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expanding global LNG export facilities strengthens supply position and meets rising Asian demand. |
| Long-term Supply Agreement | Securing multi-decade LNG contracts underwrites capital-intensive projects and provides revenue stability. |
| Green Certification Program | Attaining low-carbon gas certifications aligns with EU Green Deal taxonomy and attracts ESG investment. |
| Joint Venture | Partnering for new regasification terminals de-risks market entry in emerging import regions. |
| Vertical Integration into Storage | Developing underground gas storage enhances supply reliability and manages seasonal demand fluctuations. |
Research Approach
Independent corroboration across industry reports, government energy agencies, and company financial disclosures underwrites qualitative findings and quantitative projections. Primary research involved interviews with energy executives, utility planners, LNG terminal operators, and environmental regulators. Secondary validation drew from IEA reports, EIA data, company filings, and academic literature. Bottom-up and top-down triangulation ensured data consistency.
The rate-of-change decomposition framework projects market evolution across the analysis window, integrating base year volume, growth rates, and market share shifts. Segmentation dimensions modeled include type, application, end-user, distribution channel, and regional regulatory environments. Compound annual growth rates were derived from historical trends and future projections. Energy demand forecasts and infrastructure development pipelines served as key inputs.
Inputs from public data and primary interviews were available; gaps in real-time geopolitical shifts introduce uncertainty. Forecasts reflect assumptions about current market conditions and regulatory stability. Practitioners should monitor major policy announcements and technological breakthroughs in CCUS for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Sand Control Screens Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
Oil Field Drill Bits Market