
 Steam Turbine Market | 2026-2036
Steam Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Turbine Market Analysis
The capability gap between full-service OEMs and component specialists is unwinding as project economics favor integrated lifecycle contracts. Siemens Energy leverages its service footprint across Europe and Asia to sustain long-term service agreements. GE Vernova anchors its position through gas-steam combined cycle integration expertise. Bharat Heavy Electricals Limited competes on domestic Indian content requirements and localized manufacturing scale.
A steam turbine converts thermal energy from pressurized steam into mechanical rotational energy, typically operating at inlet conditions exceeding 540°C and 250 bar in modern ultra-supercritical configurations, primarily to drive electrical generators in power plants and mechanical equipment in industrial processes. Combined cycle turbines capture the dominant share of new order value as utilities prioritize thermal efficiency above 62% in gas-steam configurations. Capacity segments above 500 MW retain the largest installed base though 100-300 MW units represent the fastest-growing procurement class for industrial cogeneration and district heating applications.
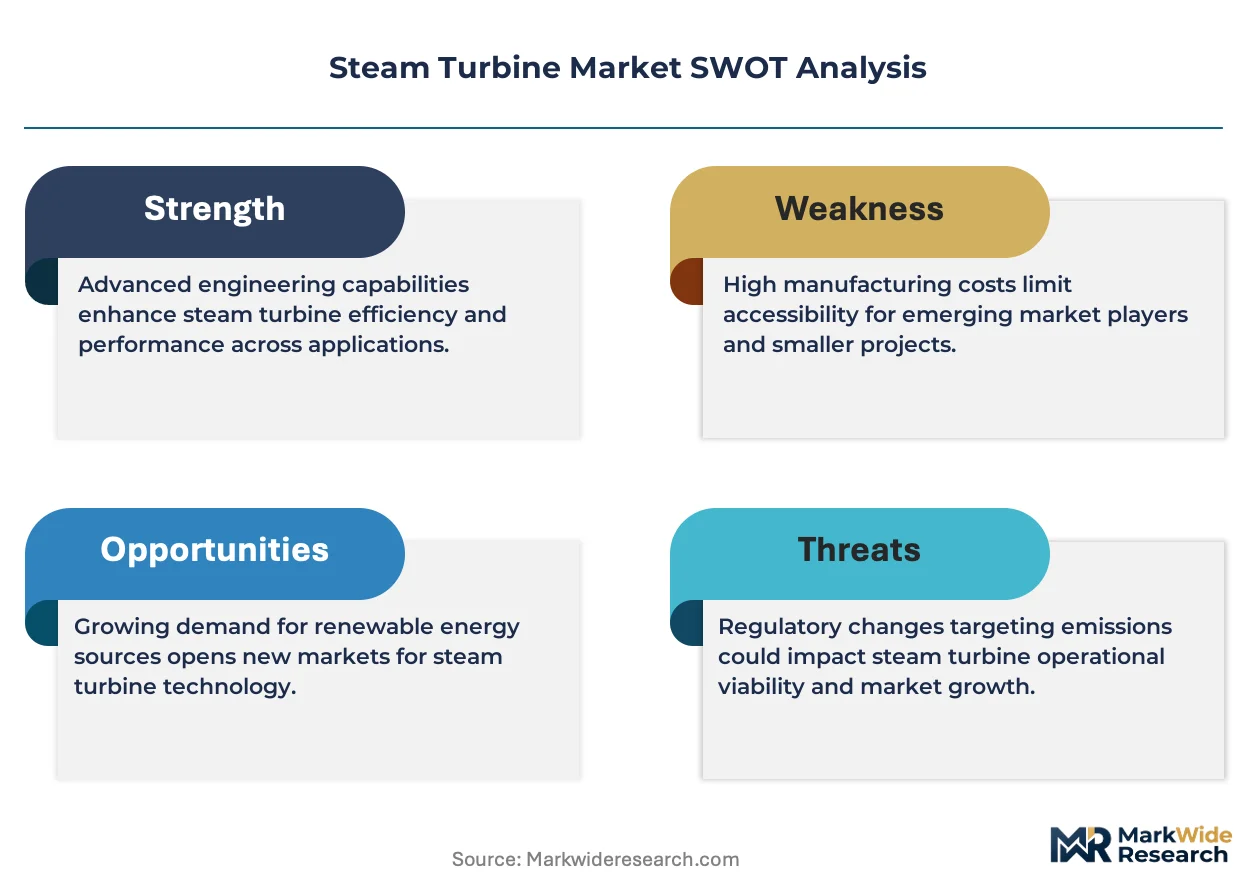
The US EPA enforces emissions limits under the Clean Air Act that compel turbine operators to deploy advanced steam conditions and pollution control retrofits, while the EU F-Gas Regulation and ETS carbon pricing framework accelerate coal plant retirement decisions across member states. India's CEA mandates supercritical technology for new thermal capacity under national power sector planning guidelines. Stakeholders must weigh technology lock-in risks against the operational flexibility required for grid-balancing duty cycles in increasingly renewable-heavy power systems.
Market Dynamics
Ultra-supercritical steam technology is compressing project economics for subcritical fleet operators while tightening emissions protocols in Asia-Pacific force accelerated replacement cycles. This technological displacement creates asymmetric pressure across OEM service portfolios and utility capital planning horizons.
Growth Catalysts
- India's CEA supercritical mandate:New thermal capacity guidelines require supercritical or ultra-supercritical technology, forcing procurement upgrades across state and private generation utilities.
- Coal-to-gas flexibility retrofits:Existing steam turbine infrastructure in Indonesia and Vietnam is being modified for dual-fuel operation to accommodate LNG import growth and grid balancing requirements.
- District heating network expansion:European municipal utilities are deploying 100-300 MW extraction turbines for combined heat and power integration in urban heating zones.
Market Restraints
- Specialized alloy supply concentration:High-temperature turbine blade materials depend on concentrated superalloy production in Germany and Japan, creating input cost volatility and delivery risk.
- Prolonged coal plant retirement timelines:Asset stranding regulations in EU member states under the EU Green Deal accelerate decommissioning, compressing the addressable installed base for retrofits.
- Gas turbine substitution in peaking duty:Aeroderivative gas turbines are capturing frequency response contracts that previously utilized steam turbine synchronous condensers.
Strategic Opportunities
- Industrial cogeneration in Bangladesh:Textile and garment manufacturing clusters lack captive power infrastructure, creating first-mover potential for 50-150 MW extraction turbine deployments.
- Hydrogen-ready turbine development:OEMs integrating high-hydrogen combustion capabilities into gas-steam combined cycle designs can capture early utility pilot programs in the Netherlands and Denmark.
- Lifecycle service contract unbundling:Independent service providers are penetrating long-term maintenance agreements previously held by full-service OEMs through specialized rotor repair and blade coating capabilities.
Industry Challenges
- Welding and rotor balancing specialist scarcity:Precision manufacturing of high-pressure turbine components requires skilled technicians with decades of apprenticeship training, constraining capacity expansion at component suppliers.
- Grid code compliance for renewable integration:Steam turbines must meet fast-ramping and minimum load requirements under revised transmission operator standards, demanding control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Turbine Market |
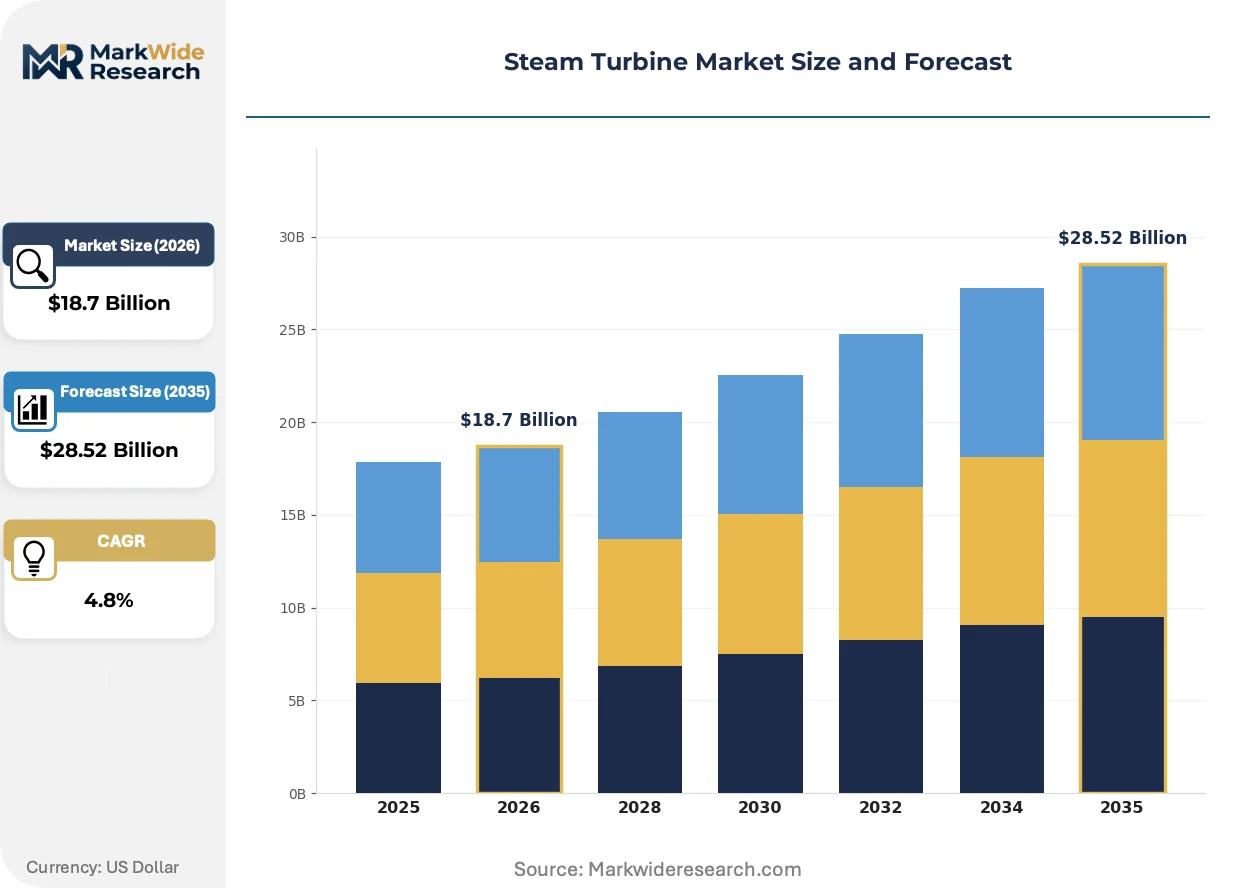
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Steam Turbines, Geothermal Turbines, Marine Steam Turbines, Combined Cycle Turbines End User: Power Generation, Oil & Gas, Marine, Chemical Processing Installation Type: Onshore, Offshore, Fixed, Mobile Capacity: Below 100 MW, 100-300 MW, 300-500 MW, Above 500 MW |
| Companies Covered | Siemens Energy, GE Vernova, Mitsubishi Heavy Industries, Toshiba Energy Systems & Solutions, Doosan Škoda Power, Ansaldo Energia, Bharat Heavy Electricals Limited, General Electric, MAN Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Turbine Market Emerging Trajectories
Digital twin deployment is compressing maintenance intervals and enabling predictive rotor life assessment across utility fleets. Additive manufacturing of blade shrouds and sealing components is reducing lead times for critical spares. These shifts are restructuring competitive advantage toward data-integrated service platforms.
Advanced nickel-based superalloys with ceramic thermal barrier coatings are displacing conventional austenitic steels in final-stage high-pressure turbine blades. Japanese and Korean utilities are adopting these materials for 620°C steam condition upgrades. This materials transition is displacing established European and North American blade suppliers from premium retrofit contracts.
The EU F-Gas Regulation is accelerating turbine seal and coupling replacement schedules to eliminate fluorinated greenhouse gas leakage from auxiliary cooling systems. Industrial operators in Germany and Poland face compliance deadlines that compress procurement cycles for seal upgrade kits. Combined cycle plants with auxiliary cooling loops are absorbing the largest compliance cost burden.
Utility procurement departments are consolidating vendor panels and demanding outcome-based availability guarantees rather than time-and-material service terms. This contract structure shift is compressing margins for component specialists while favoring integrated OEM service platforms with balance-sheet capacity to underwrite performance risk. The transformation is most visible in Indian and Chinese state-owned generation companies restructuring their maintenance procurement frameworks.
Steam Turbine Market Segmentation
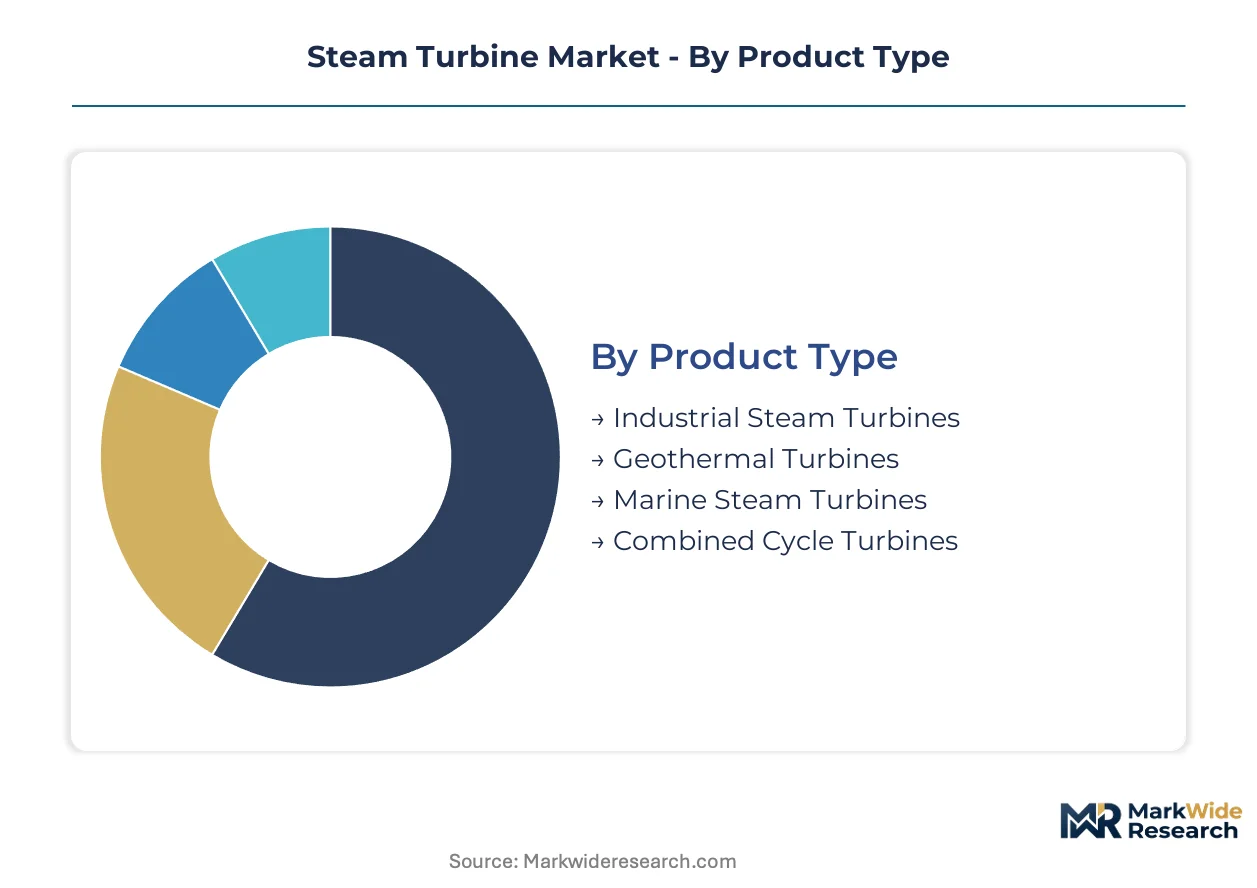
Steam turbine procurement patterns diverge sharply across product architecture and end-use application, with margin capture concentrating in high-efficiency configurations and long-cycle service attachments. Understanding segment-level demand drivers exposes where OEMs and independent service providers can defend pricing power against commoditization pressures.
Product Type:
Margin pools concentrate in combined cycle and industrial turbine categories where efficiency premiums and lifecycle service contracts extend revenue duration beyond initial equipment sales.
- Combined Cycle Turbines:Gas-steam configurations achieve thermal efficiency above 62% through heat recovery steam generator integration. Indian and Chinese utilities prioritize these units for baseload replacement of aging coal capacity under national efficiency mandates.
- Industrial Steam Turbines:Extraction-condensing designs serve cogeneration and mechanical drive applications in petrochemical complexes. District heating network expansions across Poland and Germany are accelerating procurement of 50-150 MW extraction units for urban heat supply.
- Geothermal Turbines:Binary and flash-cycle designs handle corrosive brine conditions in volcanic regions. Indonesia's Pertamina Geothermal Energy dominates fleet expansion across the archipelago's geothermal concessions.
- Marine Steam Turbines:Naval propulsion and LNG carrier applications persist in specialized niches. South Korean shipyards retain limited production for military vessel programs.
Combined cycle turbines hold installed capacity. Industrial steam turbines are rotating up the share rankings.
End User:
Application-specific duty cycles determine maintenance intensity and spare parts consumption, with power generation utilities representing the most service-contract-intensive customer base.
- Power Generation:Central station utilities operate turbines under continuous baseload and intermediate cycling regimes. India's NTPC and Adani Power are expanding ultra-supercritical procurement under CEA technology mandates.
- Oil & Gas:Refinery and petrochemical operators deploy mechanical drive turbines for compressors and pumps. Saudi Aramco's Jazan refinery represents one of the largest recent industrial turbine installations.
- Chemical Processing:Ammonia and methanol plants require extraction turbines for process steam integration. BASF's Ludwigshafen complex maintains one of Europe's largest captive turbine fleets.
- Marine:Commercial shipping has largely abandoned steam propulsion except for nuclear naval vessels. Russia's icebreaker fleet retains steam turbine propulsion for Arctic operations.
Power generation dominates order value. Oil and gas is climbing the fastest in procurement volume.
Installation Type:
Physical deployment constraints segment engineering requirements, with offshore and mobile configurations commanding specialized foundation and packaging premiums.
- Onshore:Ground-mounted installations at power stations and industrial sites constitute the overwhelming majority of turbine deployments. Land-based projects in India and Indonesia benefit from established civil construction supply chains.
- Fixed Offshore:Platform-mounted turbines serve oil and gas production facilities in the North Sea and Gulf of Mexico. Equinor's offshore installations require salt-resistant coatings and compact packaging.
- Mobile:Containerized turbine packages support emergency power and military field operations. Modular designs see limited demand outside defense procurement channels.
- Offshore (Floating):No commercial floating steam turbine installations exist; this category captures conceptual designs for future LNG power barges.
Onshore installations hold installed capacity. Fixed offshore is rotating up the share rankings.
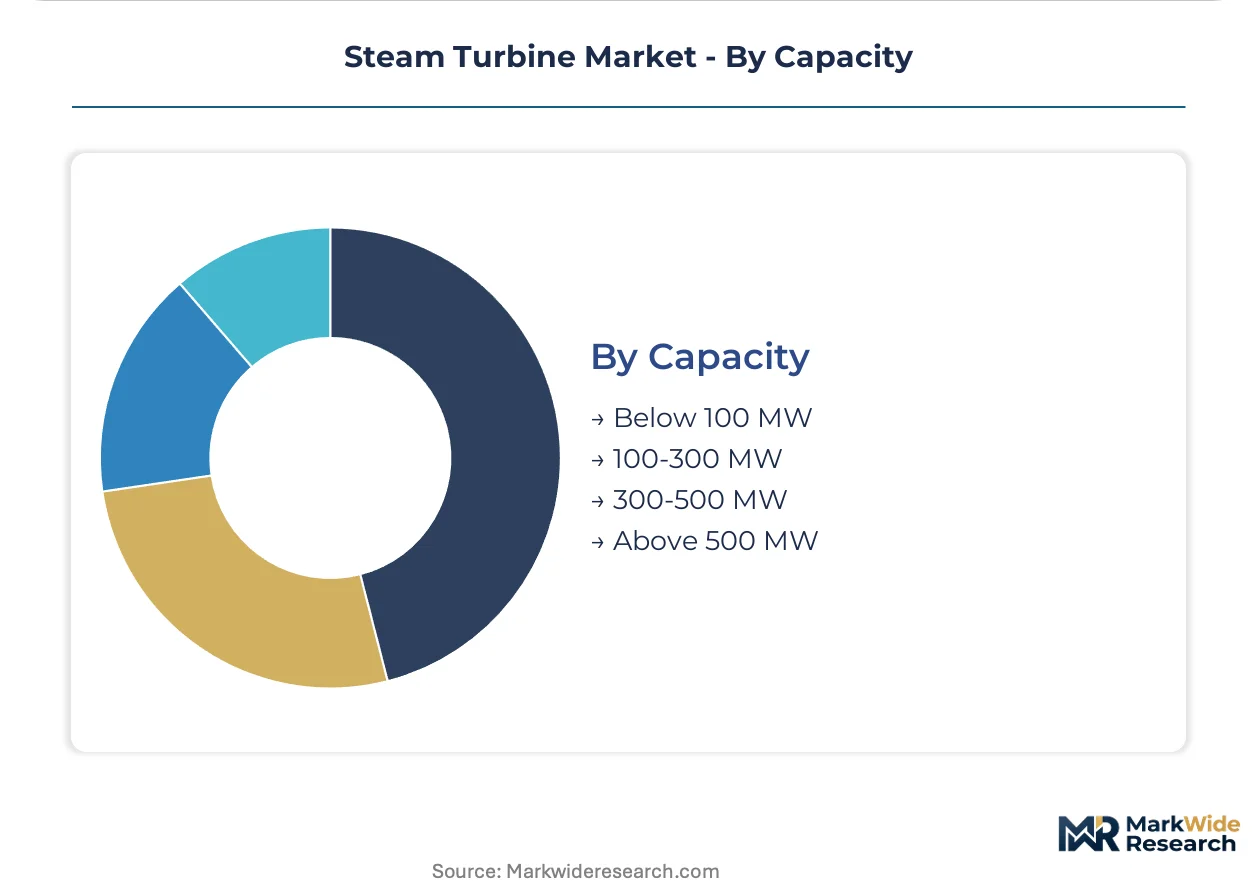
Capacity:
Unit scale determines manufacturing complexity and competitive dynamics, with mid-range segments experiencing the most intense price competition between regional and global OEMs.
- Above 500 MW:Ultra-supercritical reheat turbines serve utility-scale baseload plants. State Power Investment Corporation in China and NTPC in India anchor demand for these largest units.
- 100-300 MW:Industrial cogeneration and district heating applications favor this range for thermal load matching. European municipal utilities in Denmark and Finland are expanding procurement for urban heating integration.
- 300-500 MW:Subcritical and supercritical utility units face replacement pressure from more efficient technologies. This segment is experiencing contracting order volumes as utilities skip to ultra-supercritical configurations.
- Below 100 MW:Small industrial and biomass applications sustain niche manufacturers. Bangladesh's textile sector is emerging as a demand pocket for captive power units in this range.
Above 500 MW holds installed capacity. 100-300 MW is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese manufacturing clusters where superalloy foundries command premium input costs, while Indian and Indonesian project developers extract equipment discounts through localization mandates and fleet-scale procurement.
United States
Combined cycle repowering dominates utility procurement as operators retire subcritical coal units under EPA Clean Air Act enforcement. FERC interconnection queue reforms accelerate gas-steam project approvals in Texas and the PJM corridor. Houston anchors engineering services concentration for North American turbine retrofits.
China
State Power Investment Corporation and China Energy Investment Corporation anchor ultra-supercritical capacity additions under MIIT efficiency mandates. Dual carbon goals compress coal plant construction timelines while preserving steam turbine demand for gas-steam configurations. Yangtze River Delta manufacturing clusters supply domestic alloy casting capacity.
India
NTPC and Adani Power drive supercritical procurement under CEA technology mandates for new thermal capacity. PLI scheme incentives localize turbine component manufacturing in Gujarat and Tamil Nadu industrial corridors. Mundra and Hazira anchor captive power demand for refinery and petrochemical complexes.
Germany
EU ETS carbon pricing and EU Green Deal retirement schedules compress the addressable retrofit base for existing coal turbines. District heating network expansions in Berlin and Munich sustain 100-300 MW extraction turbine demand for municipal utilities. ECHA REACH compliance tightens superalloy supply chain specifications.
Indonesia
PLN procurement prioritizes coal-to-gas flexibility retrofits to accommodate LNG import infrastructure buildout. Pertamina Geothermal Energy expands flash-cycle turbine deployments across Java and Sumatra volcanic fields. Batam and Surabaya anchor industrial cogeneration demand from textile and food processing clusters.
Steam Turbine Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where full-service OEMs capture lifecycle value while regional fabricators compete on localization compliance. European and Japanese manufacturers anchor the premium tier through superalloy metallurgy capabilities. Chinese and Indian state-owned enterprises occupy the scale-driven mid-tier. Strategic moves concentrate on integrated service contract expansion and hydrogen-ready turbine platform development.
Among diversified industrial conglomerates, Siemens Energy and Mitsubishi Heavy Industries exemplify full-service OEM archetypes with integrated power plant capabilities. Bharat Heavy Electricals Limited occupies a distinct position as a state-supported domestic supplier serving Indian content requirements. These three anchors illustrate how competitive positioning splits between global technology platforms and regionally embedded procurement channels.
| Leading Market Players |
|---|
| Siemens Energy |
| GE Vernova |
| Mitsubishi Heavy Industries |
| Toshiba Energy Systems & Solutions |
| Doosan Škoda Power |
| Ansaldo Energia |
| Bharat Heavy Electricals Limited |
| General Electric |
| MAN Energy Solutions |
| Others |
Supply Flow & Price Mechanics
Long-term service agreements lock in both superalloy component access and lifecycle cost visibility for utilities operating ultra-supercritical fleets across India and China. These contracts insulate procurement teams from nickel-based alloy price swings while binding OEMs to availability guarantees under tightening CEA and MIIT efficiency mandates.
Pricing Analysis
The customization-premium spread between configured-to-order ultra-supercritical turbines and standardized industrial extraction units spans wide margin bands. Project-based pricing dominates utility-scale procurement where heat recovery steam generator integration and site-specific civil works drive engineering premiums. Price differentiation rests on steam condition ratings and superalloy metallurgy grades rather than brand positioning alone. Cost compression in subcritical retrofit tiers is intensifying because Indonesian and Vietnamese developers prioritize coal-to-gas flexibility kits over full turbine replacement. State-owned generation companies in India exhibit highest price sensitivity while European municipal utilities purchasing district heating turbines show lowest sensitivity due to EU ETS compliance cost absorption.
Supply Chain Analysis
Inbound logistics costs through Hamburg and Yokohama ports constrain superalloy forging delivery schedules for high-pressure turbine blade castings. Geographic supply concentrates in Germany, Japan, and China where vacuum induction melting facilities anchor nickel-based superalloy production. Raw material dependencies draw from cobalt concentrates in the Democratic Republic of Congo, nickel laterite from Indonesia, and rare earth elements for ceramic thermal barrier coatings. Single-source vulnerability permeates precision forging capacity for 620°C steam condition rotor assemblies. Distribution runs through OEM-integrated service platforms rather than independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. CEA supercritical mandates and EU ETS carbon pricing create structural switching costs that embed incumbent OEMs across decade-long equipment lifecycles.
For Market Incumbents: Consolidate rotor repair and blade coating capabilities through captive supply of high-temperature alloy machining capacity. Siemens Energy and Mitsubishi Heavy Industries should deepen backward integration into precision forging to offset welding specialist scarcity. Aeroderivative gas turbine substitution for synchronous condenser duty represents the most acute technology threat requiring control system upgrade investment. For New Entrants and Emerging Players: Differentiate on hydrogen-ready turbine platform development to capture Dutch and Danish utility pilot procurement. Bangladesh textile clusters and Indonesian food processing zones offer the most penetrable white-space for 50-150 MW extraction turbine deployment. A specialized aftermarket service model unbundling lifecycle contracts from full-service OEMs provides the clearest go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward independent service providers with specialized rotor balancing and ceramic coating capabilities. Long-term viability across the projection horizon favors asset-light service platforms over capital-intensive manufacturing expansion. Watch for EU Green Deal acceleration compressing coal plant retirement timelines as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Forging | Captive supply of high-pressure turbine blade castings reduces delivery risk from German and Japanese foundries. |
| Hydrogen-Ready Turbine Platform Development | Early positioning for Dutch and Danish utility pilot programs captures emerging fuel-flexibility procurement. |
| Lifecycle Service Contract Unbundling | Independent providers penetrate NTPC and Adani Power maintenance frameworks through specialized repair capabilities. |
| District Heating Network Partnership | Municipal utility alliances in Berlin and Munich secure 100-300 MW extraction turbine placement for urban heat zones. |
| Digital Twin Deployment | Predictive rotor life assessment compresses maintenance intervals across State Power Investment Corporation fleets. |
Methodological Framework
Cross-validation between primary interviews with utility planning officers, EPC contractors, and aftermarket service heads anchors the qualitative findings against secondary validation. Bottom-up triangulation incorporates customs data on superalloy imports, FERC interconnection queue filings, and CEA capacity addition notifications. Top-down reconciliation draws from IEA power generation statistics, MIIT equipment efficiency disclosures, and EU ETS carbon price trajectories.
Sensitivity analysis around steam condition upgrade adoption rates and coal plant retirement schedules shapes the analytical framework across the projection horizon. Segmentation dimensions span product architecture, capacity tier, end-use application, and regional regulatory cluster. CAGRs derive from installed base turnover modeling and replacement cycle compression under emissions protocols. Forecast inputs incorporate LNG import infrastructure buildout timelines in Indonesia and PLI scheme localization trajectories in India.
Material uncertainties — policy reversals on coal plant retirement, superalloy supply disruptions, or hydrogen combustion technology breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions on technology transition rates and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
South East Asia Power Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Oman Power Market
Power Generation
Micro CHP Market
Power Generation
Stirling Engine Market
Power Generation
Commercial Gensets Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
Oilfield Power Generation Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Global Gensets Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Distributed Power Generation Market
Power Generation
Iraq Power EPC Market
Power Generation
Variable Speed Generator Market
Power Generation
Residential Solar Generator Market