
 Malaysia Power Market | 2026-2036
Malaysia Power Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Power Market Foresight
Data center demand is hardening as a decisive load driver for Peninsular Malaysia's grid planners. Tenaga Nasional Berhad leverages its transmission monopoly to anchor large-scale interconnection projects serving hyperscale facilities. Malakoff Corporation Berhad competes in the independent power producer segment with natural gas and growing renewable exposure. YTL Power International Berhad specializes in district cooling and embedded generation solutions for commercial precincts.
Malaysia Power encompasses electricity generation, transmission, distribution, and retail across a grid operating at 132 kV, 275 kV, and 500 kV transmission voltages with combined cycle gas turbines providing baseload thermal output. The primary purpose is delivering reliable alternating current to commercial, industrial, and residential consumers across Peninsular Malaysia, Sabah, and Sarawak with growing emphasis on decarbonization. The renewable segment leads capacity additions through utility-scale solar and large hydro, while the distributed generation segment captures the fastest growth as commercial and industrial users deploy behind-the-meter solar and gas engines to manage tariff exposure. Natural gas technology dominates current output but solar is displacing marginal thermal hours during daylight periods.
The Energy Commission (ST) regulates licensing and tariff setting under the Electricity Supply Act, while the Sustainable Energy Development Authority (SEDA) administers feed-in tariff and net energy metering schemes for renewable integration. The Ministry of Natural Resources and Environmental Sustainability shapes carbon intensity targets through the National Energy Transition Roadmap, tightening emissions benchmarks for new thermal entry. Stakeholders must monitor how the proposed single buyer market reform alters dispatch priority and bilateral contracting access for independent producers.
Market Dynamics
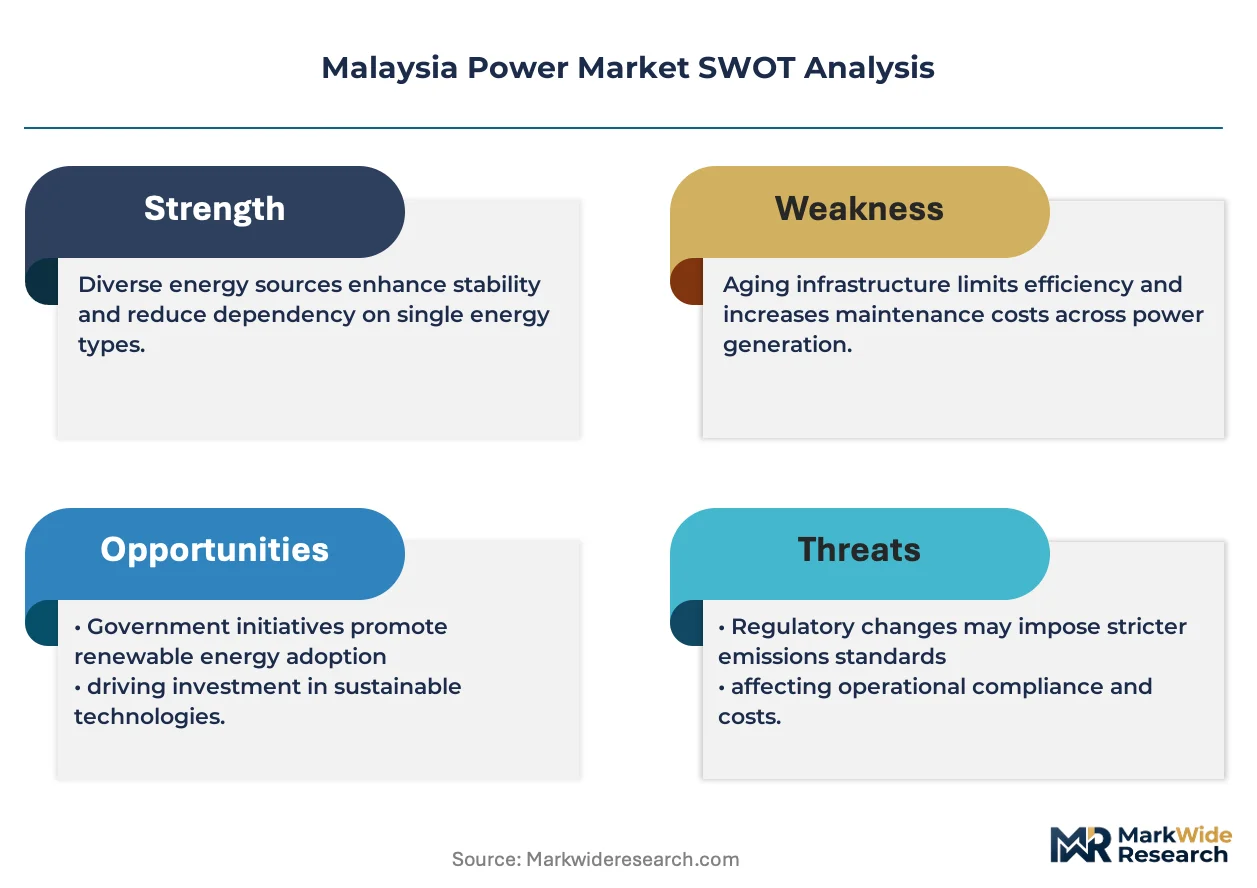
Malaysia's power sector is undergoing a structural reconfiguration driven by the National Energy Transition Roadmap's binding decarbonization targets, which are compressing dispatch windows for thermal assets while accelerating renewable procurement obligations for large consumers.
Growth Catalysts
- Net Energy Metering 3.0:SEDA's revised tariff structure improves commercial payback periods for behind-the-meter solar, unlocking C&I deployment in Selangor and Johor industrial zones.
- Data center load clustering:Hyperscale facility commitments in Iskandar Malaysia are creating anchor demand for 500 MW+ renewable energy certificates and direct power purchase agreements.
- Grid-scale battery storage:Utility procurement mandates under the NETR are absorbing lithium-ion capacity for two-hour evening peak shifting applications.
Market Restraints
- LNG price volatility:Peninsular Malaysia's combined cycle fleet remains exposed to spot LNG cargoes indexed to JKM benchmarks, compressing generator margins during supply shocks.
- Transmission congestion:275 kV interconnection bottlenecks between northern Perak solar zones and central demand centers limit renewable absorption without delayed reinforcement.
- Land acquisition friction:Large-scale solar projects face extended resettlement timelines under state-level native land reserve classifications, particularly in Pahang and Kelantan.
Strategic Opportunities
- Sarawak interconnection:The 500 kV Borneo backbone link enables Peninsular access to Bakun hydro firm capacity, creating cross-border merchant trading structures.
- Green hydrogen offtake:NETR hydrogen economy targets position Port of Tanjung Pelepas as an ammonia bunkering hub, requiring dedicated renewable power purchase.
- Embedded generation deregulation:Proposed amendments to the Electricity Supply Act may permit direct wheeling for commercial precincts in Cyberjaya and KL Eco City.
Industry Challenges
- Grid code compliance timelines:Embedded solar inverters must meet revised fault ride-through standards by Energy Commission deadlines, requiring control system retrofits.
- SCADA-EMS integration:Distribution network operators struggle to reconcile legacy DNP3 protocols with IEC 61850 substation automation for distributed resource visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Power Market |
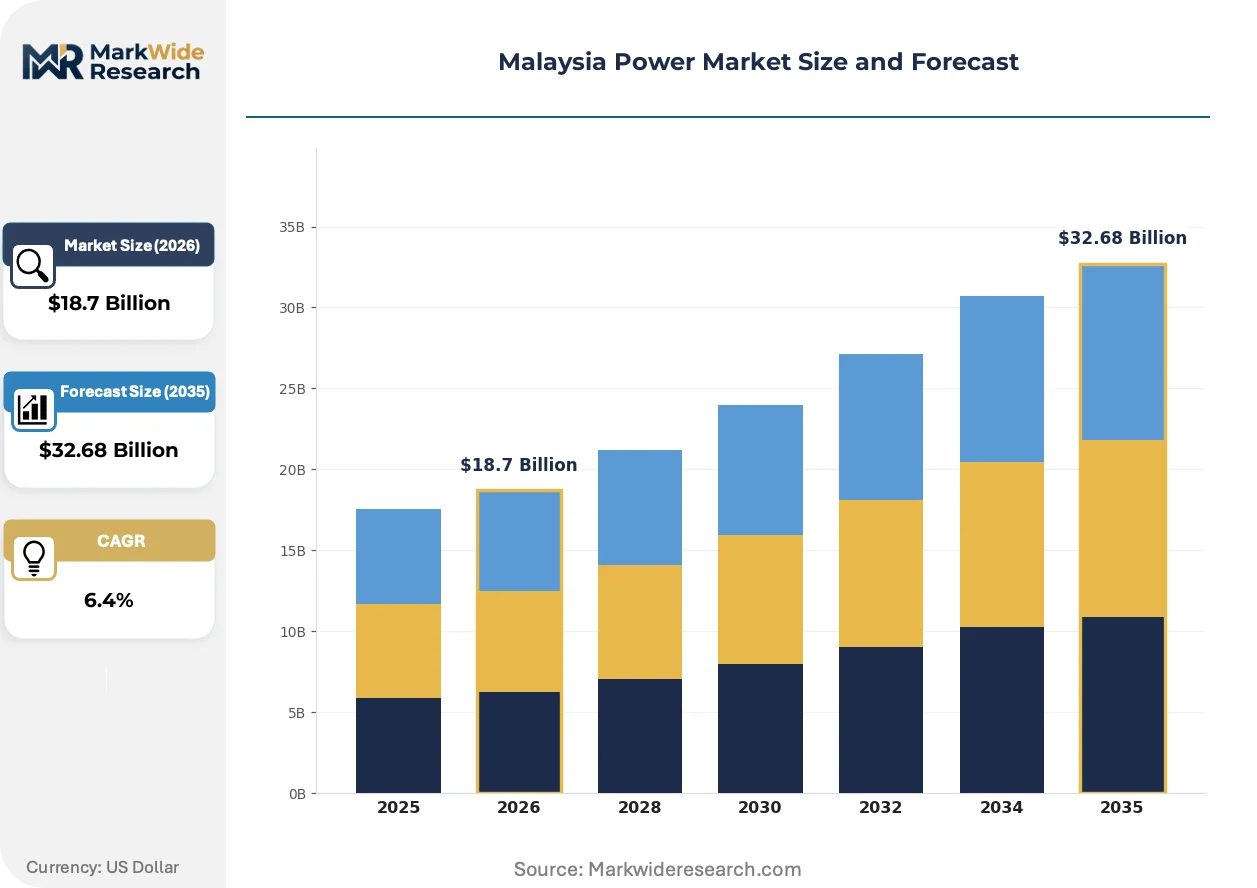
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-Renewable, Hybrid, Distributed Generation Technology: Solar, Wind, Biomass, Natural Gas End User: Commercial, Residential, Industrial, Government Service Type: Generation, Transmission, Distribution, Retail |
| Companies Covered | Malakoff Corporation Berhad, Petronas Gas Berhad, Tenaga Nasional Berhad, Cypark Resources Berhad, Solarvest Holdings Berhad, Sarawak Energy Berhad, YTL Power International Berhad, Genting Sanyen Power, Sabah Electricity Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Power Market Shifts & Advancements
Technology deployment and regulatory architecture are converging to reshape Malaysia's generation mix and network topology, with digitization and decarbonization mandates driving capital allocation across the value chain.
Floating solar photovoltaic arrays on mining lakes and reservoirs are absorbing land-constrained deployment opportunities that ground-mounted projects cannot access. TNB and Malakoff are piloting 50 MWp installations at ex-tin mining pools in Perak, with modular anchoring systems enabling 15% higher yields from evaporative cooling effects. This technology is absorbing project development pipelines that previously stalled on agricultural land-use conflicts.
Malaysia's National Energy Transition Roadmap is tightening emissions intensity benchmarks for new thermal entry, effectively mandating carbon capture readiness for gas-fired capacity. The Ministry of Natural Resources and Environmental Sustainability requires feasibility studies for post-combustion capture on combined cycle turbines above 500 MW, with implementation timelines tied to 2035 net-zero milestones. Independent power producers are responding by front-loading engineering for amine-based systems in greenfield bids.
Corporate renewable energy procurement is fragmenting traditional utility-centric contracting models as data center and semiconductor manufacturers seek direct bilateral agreements. Large energy users in Kulim and Pasir Gudang are bypassing Tenaga Nasional Berhad's single buyer framework through self-generation licenses and virtual power purchase agreements with solar developers. This behavioral shift concentrates in Penang and Johor, where tariff exposure and sustainability commitments intersect most acutely.
Malaysia Power Market Segmentation
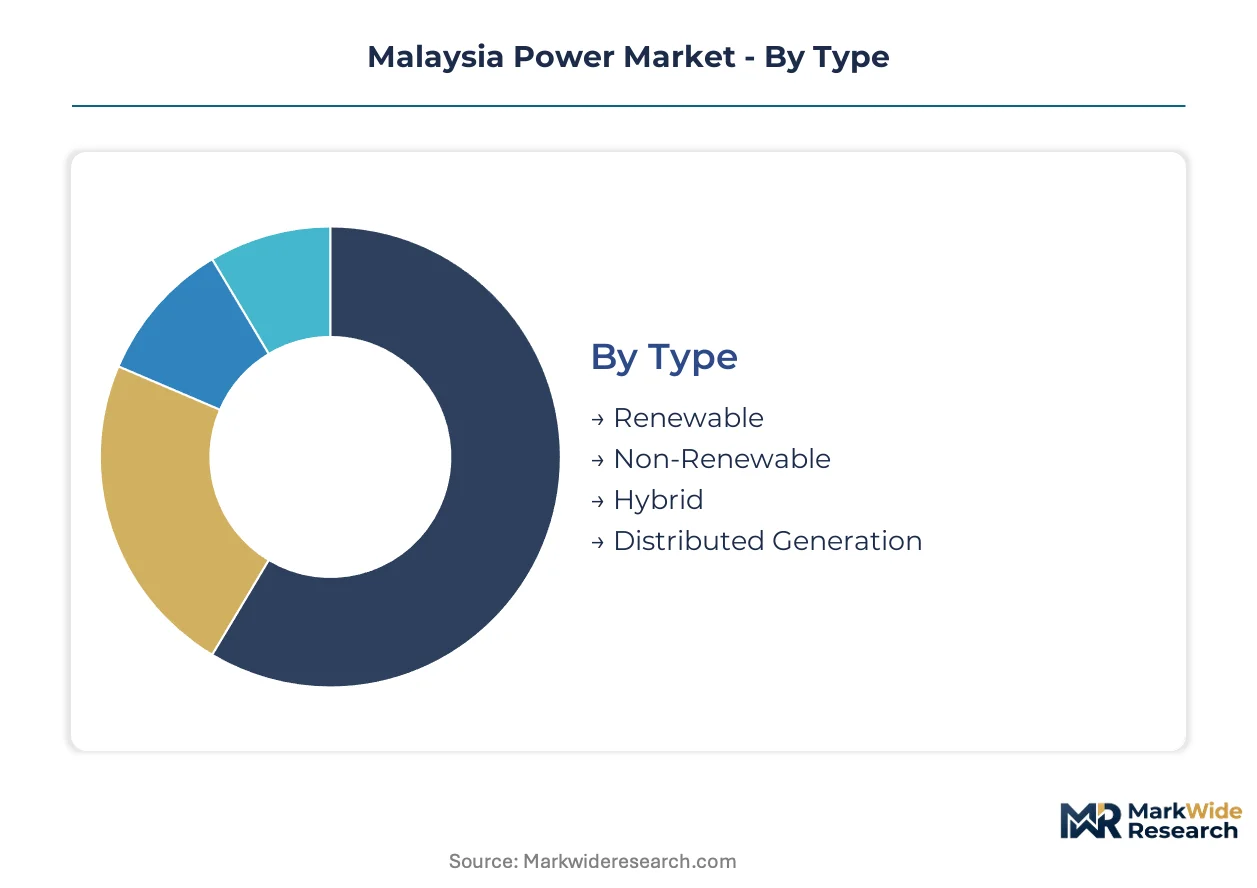
Malaysia's power market segmentation reveals how decarbonization mandates and digital infrastructure expansion are fragmenting traditional utility structures. Each dimension captures distinct buyer priorities, from industrial procurement of renewable certificates to embedded generation solutions for commercial precincts.
Type:
Cost tier differentiation separates buyers seeking grid-scale supply security from those managing tariff exposure through behind-the-meter assets.
- Renewable:Utility-scale solar and large hydro installations deliver firm capacity under the National Energy Transition Roadmap's procurement mandates. Peninsular Malaysia's industrial corridors in Selangor and Johor are absorbing the majority of new capacity as data center operators seek renewable energy certificates for sustainability commitments.
- Non-Renewable:Combined cycle gas turbines provide baseload thermal output at 132 kV, 275 kV, and 500 kV transmission voltages. The Klang Valley's manufacturing clusters depend on this dispatchable supply during evening peak periods when solar output drops.
- Hybrid:Integrated solar-plus-storage configurations address grid stability requirements under revised Energy Commission fault ride-through standards.
- Distributed Generation:Behind-the-meter solar and gas engines enable commercial and industrial users to manage tariff exposure through Net Energy Metering 3.0 schemes.
Non-Renewable leads volumes today; Distributed Generation is gaining share fastest.
Technology:
Application requirements dictate technology selection, with grid-connected and off-grid use cases demanding divergent performance specifications.
- Solar:Photovoltaic arrays dominate capacity additions through utility-scale deployments and floating installations on ex-tin mining pools in Perak. SEDA's revised tariff structure under Net Energy Metering 3.0 is unlocking commercial payback periods for rooftop systems across Iskandar Malaysia.
- Natural Gas:Combined cycle turbines remain the backbone of Peninsular Malaysia's baseload supply, though margins compress during JKM-indexed LNG price spikes. The Ministry of Natural Resources and Environmental Sustainability now mandates carbon capture readiness studies for installations above 500 MW.
- Wind:Limited onshore resource potential restricts deployment to coastal demonstration projects in Sarawak.
- Biomass:Agricultural residue-to-energy plants serve rural electrification needs in Pahang and Kelantan palm oil processing zones.
Natural Gas leads volumes today; Solar is climbing the fastest.
End User:
Volume scale and procurement sophistication separate large energy users capable of bilateral contracting from price-sensitive residential accounts.
- Industrial:Semiconductor manufacturers and data center operators in Kulim and Pasir Gudang are bypassing Tenaga Nasional Berhad's single buyer framework through self-generation licenses and virtual power purchase agreements. This segment concentrates in Penang and Johor where tariff exposure and sustainability commitments intersect.
- Commercial:District cooling requirements in Cyberjaya and KL Eco City are driving embedded generation demand as proposed Electricity Supply Act amendments may permit direct wheeling for commercial precincts.
- Residential:Net Energy Metering 3.0 uptake remains constrained by rooftop ownership patterns and financing access in urban high-rise developments.
- Government:Public building solarization programs under the National Energy Transition Roadmap are absorbing distributed capacity for administrative facilities.
Industrial leads volumes today; Commercial is expanding most quickly.
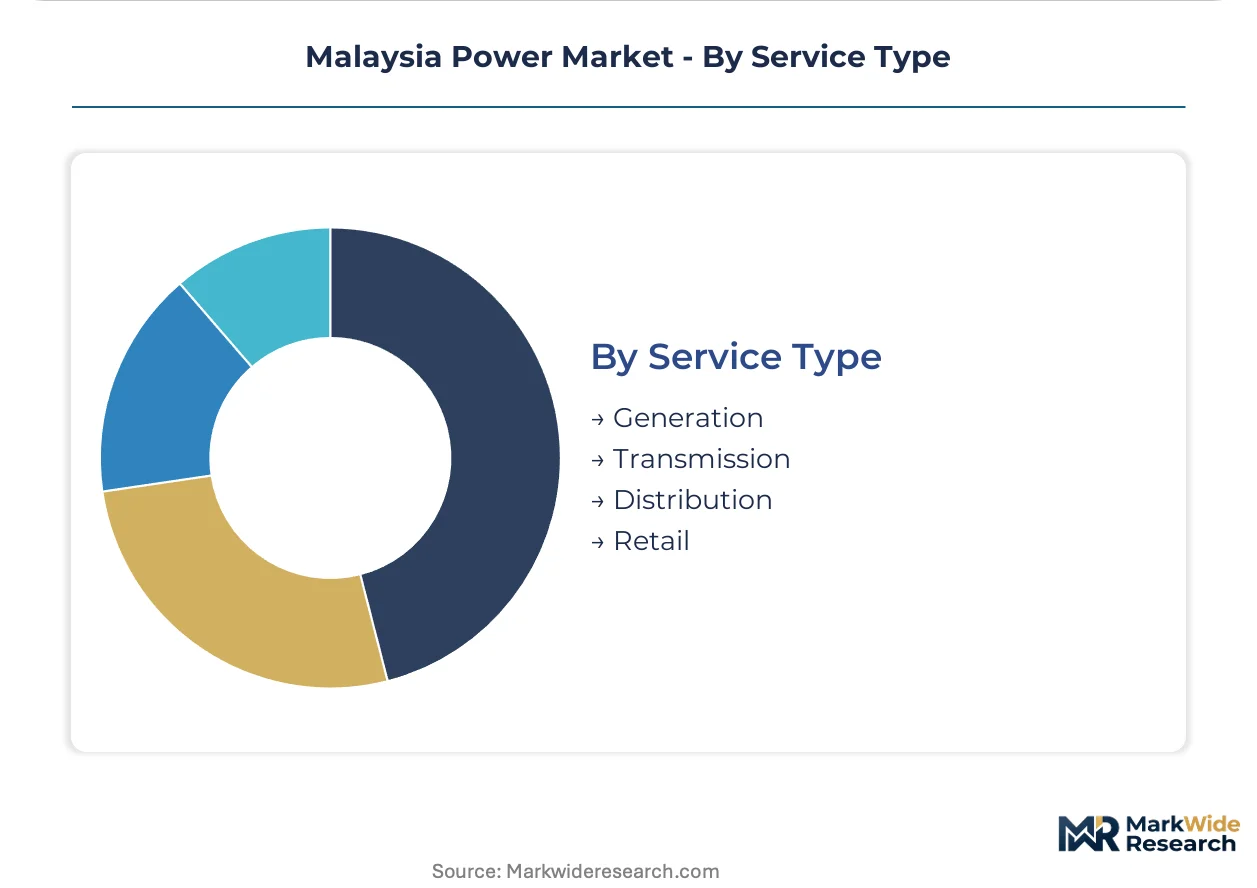
Service Type:
Margin structure and capital intensity separate generation asset owners from network operators with regulated return profiles.
- Generation:Independent power producers compete for capacity payments under the Energy Commission's licensing framework, with Malakoff Corporation Berhad and YTL Power International Berhad anchoring natural gas and renewable exposure respectively. The segment faces tightening emissions benchmarks requiring carbon capture feasibility studies.
- Transmission:Tenaga Nasional Berhad's monopoly over 500 kV and 275 kV interconnection infrastructure enables large-scale renewable absorption from northern Perak solar zones to central demand centers.
- Distribution:Network operators struggle to reconcile legacy DNP3 protocols with IEC 61850 substation automation for distributed resource visibility.
- Retail:Single buyer market reform proposals are altering dispatch priority and bilateral contracting access for independent producers.
Generation leads volumes today; Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Peninsular Malaysia and East Malaysian states is redirecting capital toward jurisdictions with streamlined land-use approvals and lower compliance costs for renewable projects. Developers exploit gaps in native land reserve classifications and feed-in tariff administration to accelerate project timelines.
Selangor and the Klang Valley
Data center load clustering in Cyberjaya and KL Eco City is compressing grid interconnection timelines for hyperscale facilities. The Energy Commission's embedded generation deregulation proposals under Electricity Supply Act amendments would permit direct wheeling for commercial precincts. TNB's 275 kV reinforcement projects target transmission congestion between northern solar zones and central demand centers.
Johor and Iskandar Malaysia
Semiconductor manufacturers and logistics operators in Pasir Gudang are procuring renewable energy certificates through virtual power purchase agreements. SEDA's Net Energy Metering 3.0 scheme is unlocking commercial payback periods for behind-the-meter solar across industrial zones. Malakoff Corporation Berhad and YTL Power International Berhad are competing for embedded generation contracts serving district cooling requirements.
Perak
Ex-tin mining pools are absorbing floating solar photovoltaic deployments that bypass agricultural land-use conflicts. TNB and independent developers are piloting 50 MWp modular anchoring systems with 15% yield premiums from evaporative cooling. The state's northern solar zones face 275 kV interconnection bottlenecks limiting absorption without delayed grid reinforcement.
Sarawak
The 500 kV Borneo backbone link enables Peninsular access to Bakun hydro firm capacity, creating cross-border merchant trading structures. Sarawak Energy Berhad leverages state-level regulatory autonomy to accelerate hydroelectric and marine energy projects. The Port of Tanjung Pelepas ammonia bunkering hub under NETR hydrogen economy targets requires dedicated renewable power purchase structures.
Sabah
Sabah Electricity Sdn Bhd manages distributed generation integration across fragmented grid infrastructure serving palm oil processing clusters. Biomass residue-to-energy plants in Pahang and Kelantan supply rural electrification needs under state-level native land reserve classifications. Land acquisition friction extends resettlement timelines for large-scale solar projects in eastern zones.
Malaysia Power Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with transmission monopolies and independent power producers occupying distinct competitive tiers. The vendor base concentrates around three structural positions: integrated utilities with regulated network assets, gas-fired independent power producers with carbon capture exposure, and renewable specialists capturing corporate procurement flows. Market evolution is forcing portfolio diversification toward solar-plus-storage configurations and hydrogen-ready gas turbines.
Within the integrated utility tier, Tenaga Nasional Berhad occupies a position anchoring transmission infrastructure and single buyer market functions. Among independent power producers, Malakoff Corporation Berhad and YTL Power International Berhad exemplify divergent strategic postures—one emphasizing scale thermal operations with renewable expansion, the other specializing in embedded generation and district cooling solutions for commercial precincts.
| Leading Market Players |
|---|
| Malakoff Corporation Berhad |
| Petronas Gas Berhad |
| Tenaga Nasional Berhad |
| Cypark Resources Berhad |
| Solarvest Holdings Berhad |
| Sarawak Energy Berhad |
| YTL Power International Berhad |
| Genting Sanyen Power |
| Sabah Electricity Sdn Bhd |
| Others |
Supply & Pricing Matrix
The National Energy Transition Roadmap's carbon intensity benchmarks gate qualified supply access for independent power producers while creating premium-tier pricing corridors for renewable energy certificates. Buyers seeking firm renewable capacity face compressed procurement timelines as SEDA's Net Energy Metering 3.0 eligibility criteria filter developer participation.
Pricing Analysis
Direct-to-industrial offtake discounts dominate large-volume contracting as data center operators bypass single buyer markups through virtual power purchase agreements. Price differentiation rests on renewable energy certificate bundling and carbon capture readiness certification for gas-fired assets. Cost compression in baseload thermal supply is intensifying because JKM-indexed LNG volatility erodes generator margins. Industrial buyers in Penang and Johor exhibit lowest price sensitivity due to sustainability commitment premiums, while residential Net Energy Metering participants face highest sensitivity to financing spreads.
Supply Chain Analysis
Single-source vulnerability sits with China for lithium-ion battery modules and South Korea for combined cycle gas turbine components. Malaysia's solar deployment draws from Chinese photovoltaic cell manufacturing, Vietnamese module assembly, and domestic inverter integration. Supply chain risk centers on tariff exposure for imported battery storage systems under evolving ASEAN trade frameworks. Distribution runs through Tenaga Nasional Berhad's transmission monopoly for grid-scale projects, while embedded generation developers self-supply commercial precincts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's power market functions as a geographic-arbitrage play between Peninsular Malaysia's congested grid and Sarawak's surplus hydro capacity, with the 500 kV Borneo backbone link enabling cross-border merchant trading structures that exploit regulatory autonomy differentials.
For Market Incumbents: Cement transmission corridor control by accelerating 275 kV reinforcement projects between northern Perak solar zones and central demand centers before embedded generation deregulation fragments dispatch priority. Deepen backward integration into floating solar anchoring systems to capture 15% yield premiums from evaporative cooling effects at ex-tin mining pools, defending margin position against independent developers. For New Entrants and Emerging Players: Net Energy Metering 3.0 in Selangor and Johor opens a window for commercial rooftop solar deployment as SEDA's revised tariff structure improves payback periods for behind-the-meter assets. Target district cooling contracts in Cyberjaya and KL Eco City where proposed Electricity Supply Act amendments may permit direct wheeling for commercial precincts, penetrating the fastest-expanding end-use segment through embedded generation specialization. For Investors and Strategic Acquirers: Roll-up economics work for hybrid solar-plus-storage developers because grid-scale battery procurement mandates under the NETR are absorbing lithium-ion capacity for two-hour evening peak shifting applications. Focus acquisition screening on independent power producers with carbon capture feasibility studies already filed for gas turbines above 500 MW. Watch for single buyer market reform legislation as the inflection signal altering dispatch priority and bilateral contracting access.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Direct bilateral contracts enable data center operators to bypass Tenaga Nasional Berhad's single buyer framework. |
| Capacity Buildout | Utility-scale solar additions in Perak mining lakes absorb land-constrained deployment opportunities with modular anchoring systems. |
| Vertical Integration into Storage | Integrated solar-plus-storage configurations address revised Energy Commission fault ride-through standards for grid stability. |
| Green Certification Program | Renewable energy certificates satisfy hyperscale facility sustainability commitments in Iskandar Malaysia load clusters. |
| Technology Licensing | Post-combustion carbon capture licensing positions gas-fired independent power producers for 2035 net-zero milestones. |
Research Methodology
Bottom-up industrial load modeling reconciled against top-down generation capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators were combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Triangulation between stakeholder demand signals and supply-side capacity announcements ensures segmentation integrity across fuel source, generation capacity tier, and regional grid type.
Historical trendline analysis of capacity additions and dispatch patterns established baseline growth trajectories across the projection horizon. The forecast framework models segmentation dimensions including fuel source, project scale, regulatory framework, and regional grid type while deriving CAGRs from installed capacity buildout schedules and load factor assumptions. Forecast inputs incorporate solar irradiance data for floating photovoltaic yield projections and LNG price volatility scenarios for thermal generator margin stress testing.
Revisions become necessary when single buyer market reform legislation materializes or when 500 kV interconnection bottlenecks between northern Perak solar zones and central demand centers exceed projected reinforcement timelines. Forecasts reflect documented assumptions regarding SEDA tariff structure continuity and native land reserve classification resolutions in Pahang and Kelantan. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Thermal Power Market
Power Generation
Microturbine Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
South America Thermal Power Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Residential Solar Generator Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Wind Power EPC Market
Power Generation
Hydrogenerators Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Industrial Solar Generator Market