
 Europe Distributed Power Generation Market | 2026-2036
Europe Distributed Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Distributed Power Generation Market Foresight
The Europe distributed power generation sector is recalibrating around a widening split between premium integrated systems and commodity hardware. Engie SA leverages its utility-scale project pipeline to dominate France's commercial segment. Canadian Solar Inc anchors its position through manufacturing scale and module efficiency leadership.
Distributed power generation encompasses small-scale electricity production located near consumption points, typically employing solar PV arrays, wind turbines, biomass combustors, or fuel cells with capacities ranging from kilowatts to tens of megawatts. These systems serve industrial, commercial, and residential loads while reducing transmission losses and grid dependency. Solar PV technology leads installed capacity across Europe, though fuel cells command higher margins in premium industrial applications. The residential application segment shows structural acceleration as rooftop installations expand, while the utilities end-user category remains mature with slower growth but stable procurement volumes.
The EU Green Deal, REPowerEU framework, and national implementations of the F-Gas Regulation shape product standards and interconnection requirements for distributed assets. EMA guidelines on environmental impact assessments and CE marking obligations for electrical equipment create compliance thresholds that filter market participants. Stakeholders must monitor evolving national capacity auctions and grid code revisions that determine project economics.
Market Dynamics
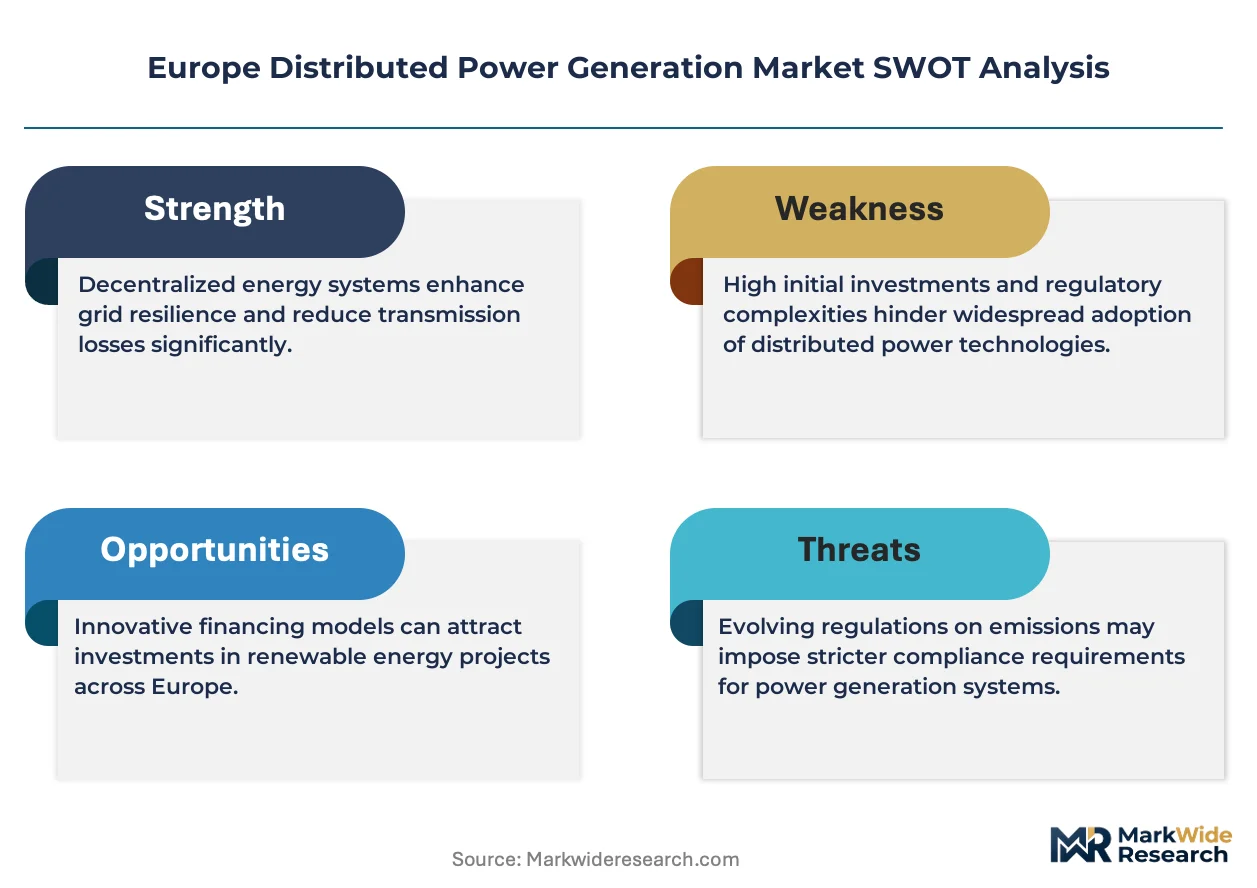
The EU Green Deal and REPowerEU plan are forcing a structural recalibration of European energy security frameworks. Industrial facilities now prioritize on-site generation to reduce grid dependency and exposure to volatile wholesale electricity prices.
Growth Catalysts
- REPowerEU framework:The EU's accelerated renewable targets mandate distributed capacity expansion across member states. National governments are streamlining permitting for commercial and industrial solar installations.
- Industrial load centers:German automotive and chemical plants are deploying multi-megawatt solar arrays with battery storage to secure baseload power and hedge against price spikes.
- Heat pump coupling:Residential sector electrification is driving co-located solar PV and thermal storage systems that optimize self-consumption economics.
Market Restraints
- Grid interconnection queues:Distribution network operators in Italy and Spain face 18-24 month backlogs for new distributed generation connections, delaying project commissioning.
- Polysilicon supply concentration:European module assemblers remain dependent on imported wafers and cells, exposing project economics to input cost volatility and trade policy shifts.
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon quota reductions are constraining heat pump and cooling system availability, limiting hybrid distributed energy configurations.
Strategic Opportunities
- CEE underpenetration:Poland, Romania, and Bulgaria hold substantial untapped rooftop potential as grid parity improves and EU cohesion funds accelerate deployment.
- Agricultural PV integration:Dual-use agrivoltaic systems are gaining regulatory acceptance in France and Germany, opening new land-access models for ground-mounted arrays.
- Power-to-X coupling:Electrolyzer co-location with offshore wind and solar farms is creating integrated hydrogen production hubs in the Netherlands and Denmark.
Industry Challenges
- Electrical engineering talent scarcity:Grid integration specialists and power electronics engineers command premium wages as project pipelines exceed qualified workforce supply.
- CE marking complexity:Module manufacturers face extended certification timelines as EU harmonized standards evolve for bifacial panels and floating PV systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Distributed Power Generation Market |
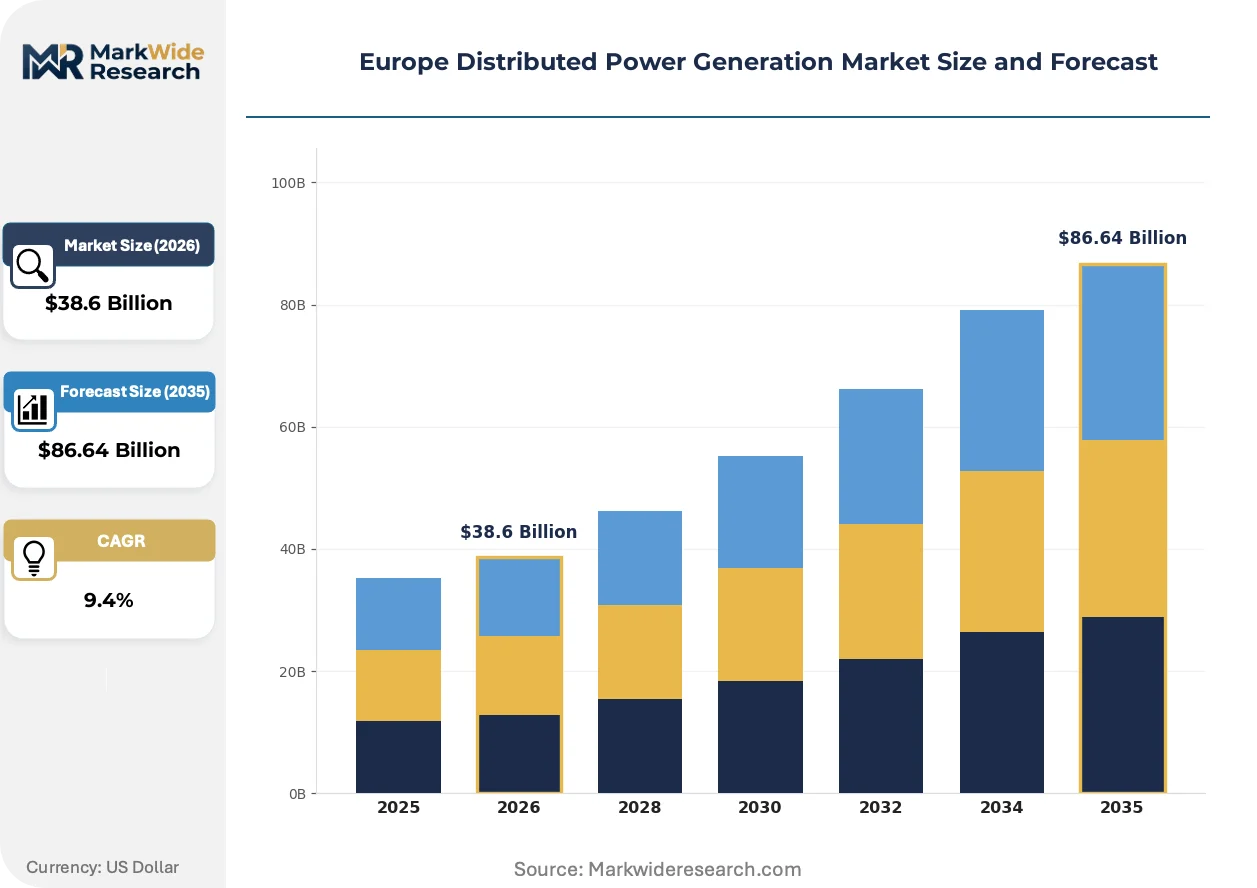
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar PV, Wind Turbines, Biomass, Fuel Cells Application: Residential, Commercial, Industrial, Agricultural End User: Utilities, SMEs, Large Enterprises, Government Installation: On-site, Off-site, Remote, Community |
| Companies Covered | WAGNER SOLAR GMBH, Canadian Solar Inc, Engie SA, Bloom Energy, Compagnie de Saint-Gobain S.A, EDF Renewables, Sunverge Energy, Ansaldo Energia SpA, Maxeon Solar Technologies Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Distributed Power Generation Market Shifts & Advancements
Solid-state inverter architectures and silicon carbide power electronics are compressing balance-of-system costs while enabling higher DC-to-AC ratios. These advances are reshaping competitive positioning between integrated system providers and component specialists.
Silicon carbide MOSFETs are replacing traditional IGBT modules in string inverters, enabling switching frequencies above 50 kHz with reduced thermal losses. Commercial and utility-scale developers in Germany and the Netherlands are specifying SiC-based units for 1500V DC systems. This transition is electrifying the premium inverter segment as manufacturers differentiate through efficiency gains rather than commoditized capacity ratings.
The EU F-Gas Regulation's accelerated phase-down timeline is restricting refrigerant availability for heat pumps and thermal management systems. Equipment manufacturers are redesigning cooling circuits around natural refrigerants and CO2 transcritical cycles. The residential and light commercial segments face the steepest adaptation curves as existing product lines require rapid redesign to maintain CE marking compliance.
Energy-as-a-service contracting is displacing traditional equipment ownership models among European industrial buyers. Third-party developers retain asset ownership and sell electricity through long-term power purchase agreements, transferring performance risk from end-users to specialized financiers. This structure is most prevalent in Spain and Italy where regulatory frameworks for onsite generation leasing have matured.
Europe Distributed Power Generation Market Segmentation
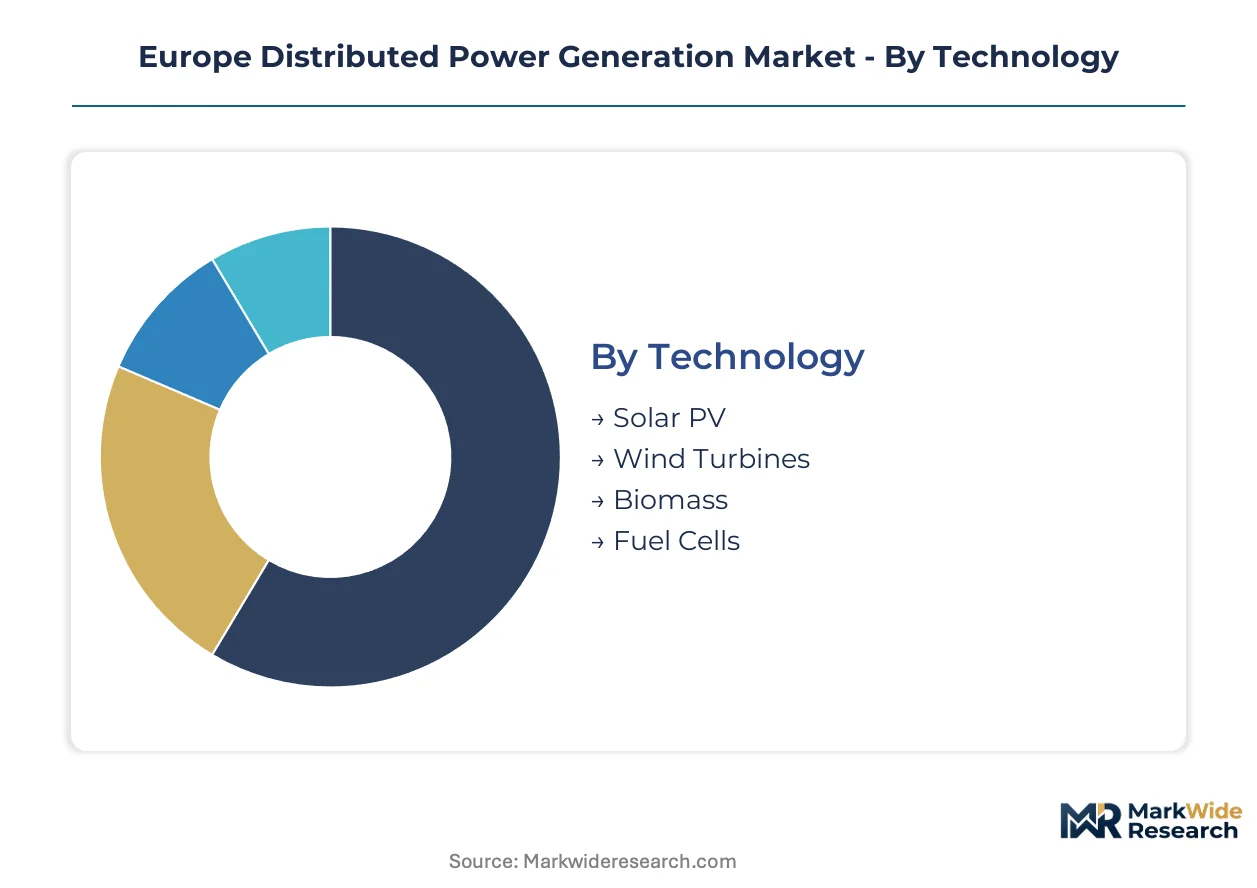
Technology choices in Europe's distributed power generation sector cascade through equipment specifications, financing structures, and regulatory compliance pathways. Application context determines whether buyers prioritize self-consumption economics, grid services revenue, or energy security guarantees.
Technology:
Capital efficiency and levelized cost of electricity drive procurement decisions across the technology stack.
- Solar PV:Crystalline silicon modules dominate installed capacity, with bifacial panels and tracking systems penetrating utility-scale ground-mounted projects. German industrial parks and Dutch agrivoltaic installations absorb the highest volumes as grid parity eliminates subsidy dependence.
- Fuel Cells:Solid oxide and proton exchange membrane systems deliver premium dispatchable power for chemical plants and data centers requiring 99.99% uptime. The Netherlands and Belgium host concentrated deployment where hydrogen infrastructure integration justifies higher capital outlays.
- Wind Turbines:Distributed applications favor sub-100kW vertical axis and small horizontal axis units for commercial rooftops and agricultural settings.
- Biomass:Anaerobic digesters and combined heat and power units serve agricultural and food processing facilities with reliable waste feedstock streams.
Volume sits with Solar PV; growth tilts toward Fuel Cells.
Application:
Load profile characteristics and behind-the-meter economics determine segment attractiveness for developers and financiers.
- Industrial:Multi-megawatt on-site arrays with battery coupling secure baseload power for automotive and semiconductor fabrication facilities. German chemical complexes and Spanish food processors lead procurement as power purchase agreements hedge volatile wholesale prices.
- Residential:Rooftop installations paired with heat pumps and electric vehicle chargers optimize self-consumption under net metering schemes. Italian and Polish households drive deployment as EU cohesion funds reduce upfront capital barriers.
- Commercial:Office buildings and retail chains deploy mid-scale systems to meet corporate sustainability targets and reduce operating expenditures.
- Agricultural:Dual-use agrivoltaic arrays and biogas digesters generate revenue streams while maintaining food production capacity.
Industrial applications command the largest aggregate capacity additions; residential installations are expanding most quickly.
End User:
Counterparty credit quality and offtake contract duration shape project finance availability and developer returns.
- Large Enterprises:Investment-grade corporates sign 15-20 year power purchase agreements with aggregators and independent power producers. French and German automotive manufacturers anchor the premium segment through direct procurement of on-site generation assets.
- SMEs:Small and medium enterprises rely on energy-as-a-service contracts and equipment leasing to avoid capital deployment. Spanish and Italian service providers dominate this fragmented customer base.
- Utilities:Distribution network operators procure distributed capacity for grid stability services and renewable portfolio obligations.
- Government:Public buildings and military installations prioritize energy security and resilience over pure cost optimization.
Large Enterprises absorb the highest absolute capacity; SMEs offer the steepest expansion trajectory through service-based business models.
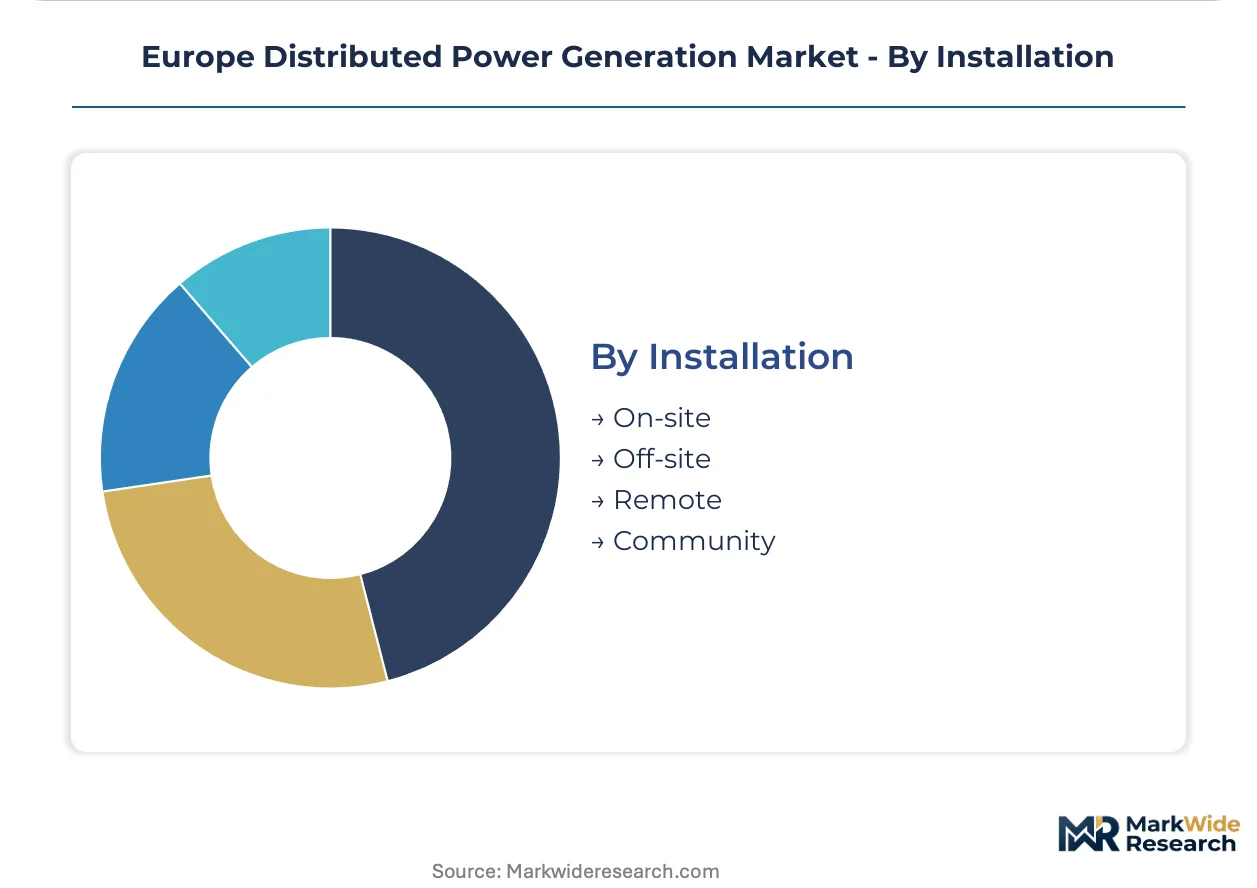
Installation:
Land access, grid connection timelines, and permitting complexity differentiate deployment archetypes.
- On-site:Generation assets sited at consumption points eliminate transmission losses and wheeling charges. German manufacturing campuses and French hospital complexes standardize this configuration for critical load coverage.
- Community:Shared solar and wind installations enable multi-customer participation models where individual rooftops prove unsuitable. Denmark and the Netherlands pioneered regulatory frameworks for collective self-consumption.
- Off-site:Corporate buyers procure renewable energy certificates and physical power from geographically remote distributed assets.
- Remote:Island and mountain installations serve loads disconnected from centralized grid infrastructure, common in Greek archipelagos and Alpine regions.
On-site deployment holds established volume leadership; community models are gaining share fastest where enabling regulation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors distributed power deployment across Germany, where automotive and chemical clusters drive multi-megawatt solar-plus-storage installations.
Germany
Industrial parks in North Rhine-Westphalia and Bavaria deploy solar PV with battery coupling to secure baseload power. The Renewable Energy Sources Act (EEG) streamlines permitting for commercial installations above 750 kW. Stuttgart's automotive manufacturers anchor procurement volumes through direct on-site generation assets.
France
Nuclear-dependent grids create arbitrage opportunities for commercial solar and fuel cell deployments. The REPowerEU national implementation accelerates rooftop permitting through the "Simplification of Renewable Energy Procedures" decree. Lyon and Grenoble host concentrated fuel cell adoption where hydrogen infrastructure integration justifies premium capital outlays.
Italy
Net metering schemes and EU cohesion fund access drive residential rooftop expansion across the Po Valley. The National Integrated Energy and Climate Plan mandates distributed capacity targets through 2030. Milan's commercial real estate sector leads mid-scale system deployment for corporate sustainability compliance.
Netherlands
Agrivoltaic dual-use systems gain regulatory traction in Gelderland and Flevoland provinces. The SDE++ subsidy scheme supports power-to-X coupling with offshore wind and solar farms. Rotterdam port industrial zones anchor electrolyzer co-location projects creating integrated hydrogen production hubs.
Spain
Solar resource abundance and streamlined self-consumption regulation attract energy-as-a-service providers. The National Energy and Climate Plan 2023-2030 establishes distributed generation quotas for commercial buildings. Barcelona and Madrid food processors lead procurement through long-term power purchase agreements hedging wholesale price exposure.
Europe Distributed Power Generation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and service bundling capability. The vendor base stratifies between integrated system providers offering financing and O&M contracts versus component specialists competing on module efficiency and inverter specifications. Three archetypes dominate: utility-backed developers leveraging balance sheet capacity, manufacturing-scale module producers, and energy-as-a-service platforms. Competitive moves concentrate on strategic partnerships for project pipeline access and geographic expansion into underpenetrated Central and Eastern European markets.
Within the integrated developer tier, Engie SA and EDF Renewables occupy positions shaped by utility-scale project execution capabilities. Canadian Solar Inc exemplifies the manufacturing-scale archetype through crystalline silicon module production leadership. Bloom Energy anchors the premium fuel cell segment where solid oxide systems serve industrial uptime requirements.
| Leading Market Players |
|---|
| WAGNER SOLAR GMBH |
| Canadian Solar Inc |
| Engie SA |
| Bloom Energy |
| Compagnie de Saint-Gobain S.A |
| EDF Renewables |
| Sunverge Energy |
| Ansaldo Energia SpA |
| Maxeon Solar Technologies Ltd |
| Others |
Supply & Pricing Matrix
Captive integration into polysilicon refining and wafer slicing anchors both supply security and pricing power for European module assemblers navigating the EU Green Deal's domestic content incentives. German and Dutch project developers leverage this backward control to stabilize input costs against volatile Asian spot markets.
Pricing Analysis
Value-based pricing tied to guaranteed uptime and grid stability services anchors the premium fuel cell segment. Three-tier pricing structure across premium, standard, and economy levels separates solid oxide systems with hydrogen coupling from commodity crystalline silicon modules. Cost compression in the residential solar tier intensifies as Chinese module exports flood European ports. Large enterprises exhibit lowest price sensitivity due to long-term power purchase agreement structures, while SMEs negotiate aggressively on energy-as-a-service contract terms.
Supply Chain Analysis
Dual-sourcing requirements from German automotive and chemical buyers mandate qualified suppliers across at least two of China, Vietnam, and Malaysia for cell and wafer inputs. Module assembly draws from polysilicon, silver paste, and aluminum frame feedstocks. Single-source vulnerability concentrates in metallurgical-grade silicon refining. Distribution runs through EPC contractors and independent power producers with direct utility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play. The 18-24 month grid interconnection backlog in Southern Europe is forcing capital-constrained developers into distressed asset sales.
For Market Incumbents: Deepen backward integration into silicon ingot production to defend margin position against polysilicon price spikes. Acquire distressed project pipelines in Italy and Spain where interconnection delays have weakened smaller developers. The F-Gas Regulation's refrigerant phase-down threatens heat pump coupling revenues without rapid product redesign.
For New Entrants and Emerging Players: Enter via agrivoltaic dual-use installations in France and Germany where regulatory acceptance is outpacing supply. Polish and Romanian residential rooftops offer the most penetrable geography given EU cohesion fund availability and nascent installer networks. Pursue energy-as-a-service contracting models to bypass upfront capital barriers among SME segments.
For Investors and Strategic Acquirers: Exit pathways concentrate in utility-backed buyouts of distributed generation portfolios with contracted offtake. Five-to-ten year viability favors developers with secured grid connection agreements and integrated O&M capabilities. Watch Italian and Spanish permitting queue resolution as the inflection signal for valuation recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Secures supply position against Chinese export quota volatility under EU trade measures. |
| Power Purchase Agreement Expansion | Locks in 15-20 year revenue streams with investment-grade German automotive offtakers. |
| Agrivoltaic Regulatory Certification | Opens dual-use land access models in France's agricultural heartland. |
| Solid Oxide Fuel Cell Scale-Up | Captures premium margins in Dutch chemical corridor hydrogen hub deployments. |
| Energy-as-a-Service Platform Launch | Transfers performance risk from Spanish SME buyers to specialized balance sheet providers. |
Research Methodology
IEA renewable deployment databases, EUROSTAT energy statistics, and FERC interconnection filings formed the secondary backbone. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators validated demand assumptions. Bottom-up and top-down triangulation reconciled project pipeline data with national capacity targets.
Bottom-up modeling of individual project economics preceded top-down reconciliation against REPowerEU aggregate targets. Segmentation across fuel source, generation capacity tier, regulatory framework, and regional grid type structured the analytical framework. CAGRs derived from capacity deployment curves and learning rate cost reductions. Forecast inputs incorporated silicon commodity price trajectories and interconnection queue clearance assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt F-Gas Regulation enforcement or Chinese export restriction scenarios. Deviation in German grid code revision timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Power Grid System Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Stirling Engine Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Distributed Power Generation Market
Power Generation
Micro CHP Market
Power Generation
Power Plant EPC Market
Power Generation
India Thermal Power Plant Market
Power Generation
Peaking Power Plant Market
Power Generation
Indonesia Power Market
Power Generation
Iraq Power EPC Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Asia-Pacific Thermal Power Plant Market