
 Power Plant EPC Market | 2026-2036
Power Plant EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Power Plant EPC Market Analytics
Data center load growth is pivoting EPC contractor priorities toward dispatchable backup and baseload capacity. Bechtel Corporation leverages its nuclear construction pedigree to compete for advanced reactor contracts. Samsung Engineering anchors its backlog with combined-cycle gas turbine projects across Southeast Asian utility buyers. Fluor Corporation differentiates through modular execution methods that compress field construction schedules.
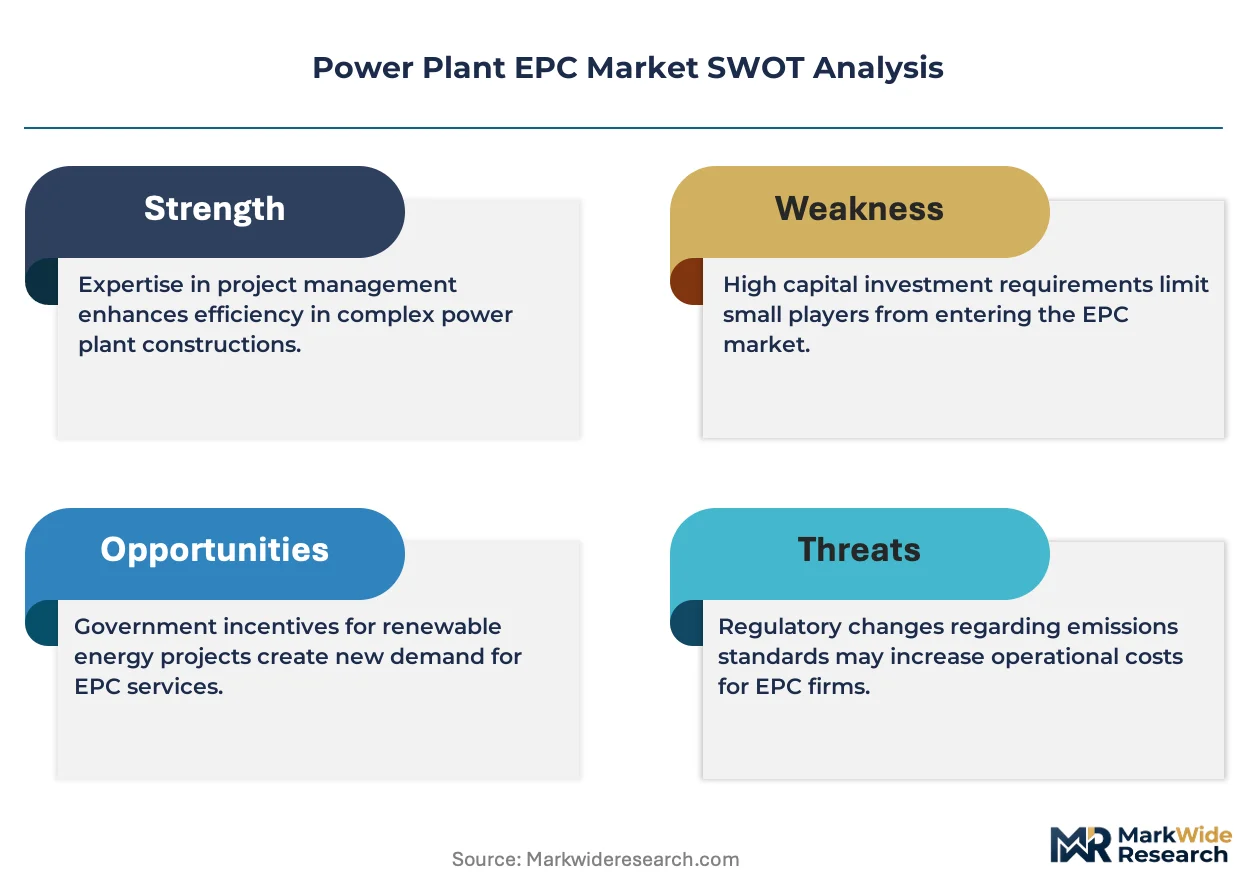
Power plant EPC denotes the integrated engineering, procurement, and construction delivery model for electricity generation facilities, encompassing thermal efficiency specifications above 60 percent for combined-cycle configurations and containment integrity standards for nuclear island work. The primary purpose is transferring full operational risk from asset owners to contractors through lump-sum or cost-reimbursable contracts. Renewable Energy technology is attracting the fastest-growing share of contractor pre-bid investment, while Nuclear Technology commands the highest margin pools due to specialized welding and quality assurance requirements. Engineering Services sustain premium pricing where front-end design work determines total installed cost trajectories.
The US Environmental Protection Agency and the Nuclear Regulatory Commission shape contractor qualification thresholds through emissions compliance and reactor licensing protocols. The EU F-Gas Regulation and CE marking directives constrain equipment sourcing for European projects, filtering supplier pools. India's Central Electricity Authority mandates domestic content floors that redirect procurement toward local fabrication. Stakeholders must monitor how divergent carbon accounting standards across jurisdictions reshape contractor competitiveness in cross-border bidding.
Market Dynamics
The US Inflation Reduction Act is redirecting EPC contractor pipelines toward clean energy portfolios while data center operators expand captive power investments, compressing traditional utility procurement cycles.
Growth Catalysts
- Data Center Load Expansion:Hyperscale operators are tendering dedicated generation assets to secure dispatchable capacity for AI compute clusters. This demand stream bypasses traditional utility interconnection queues.
- India's Ultra-Mega Power Projects:State-run utilities under the Central Electricity Authority are bundling generation, transmission, and fuel supply into single EPC packages exceeding 4,000 MW.
- Modular Nuclear Deployment:Advanced reactor designs from NuScale and GE-Hitachi are unlocking standardized island construction, reducing field welding hours and quality assurance hold points.
Market Restraints
- Specialized Welder Scarcity:Nuclear island work demands ASME Section IX certified welders, with training pipelines constrained by NRC audit requirements and limited apprenticeship slots.
- Steel and Alloy Price Volatility:SA-508 Grade 3 forging steel for reactor pressure vessels concentrates among Japanese and French suppliers, exposing contractors to yen-euro exchange rate swings.
- Domestic Content Mandates:India's CEA domestic content floors redirect procurement toward local fabrication with limited ASME-accredited shops, extending equipment qualification timelines.
Strategic Opportunities
- Southeast Asian CCGT Buildout:Vietnam, Indonesia, and the Philippines are tendering combined-cycle blocks to replace aging coal units, with Samsung Engineering and Mitsubishi Power anchoring early mover positions.
- Green Hydrogen Co-Location:Electrolyzer integration with offshore wind substations creates hybrid EPC scopes spanning electrical, chemical, and marine civil work with limited incumbent expertise.
- EU F-Gas Regulation Arbitrage:Fluorinated gas phase-down schedules are accelerating SF6-free switchgear adoption, rewarding contractors with early supplier partnerships in vacuum interrupter technology.
Industry Challenges
- Reactor Licensing Timeline Compression:NRC Part 52 combined license applications require 42-month review cycles, misaligning with data center operators demanding 24-month energization schedules.
- Cross-Border Carbon Accounting Divergence:Contractors bidding Indian projects face conflicting Scope 3 disclosure requirements under EU CSRD and domestic BRSR mandates, complicating joint venture structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Plant EPC Market |
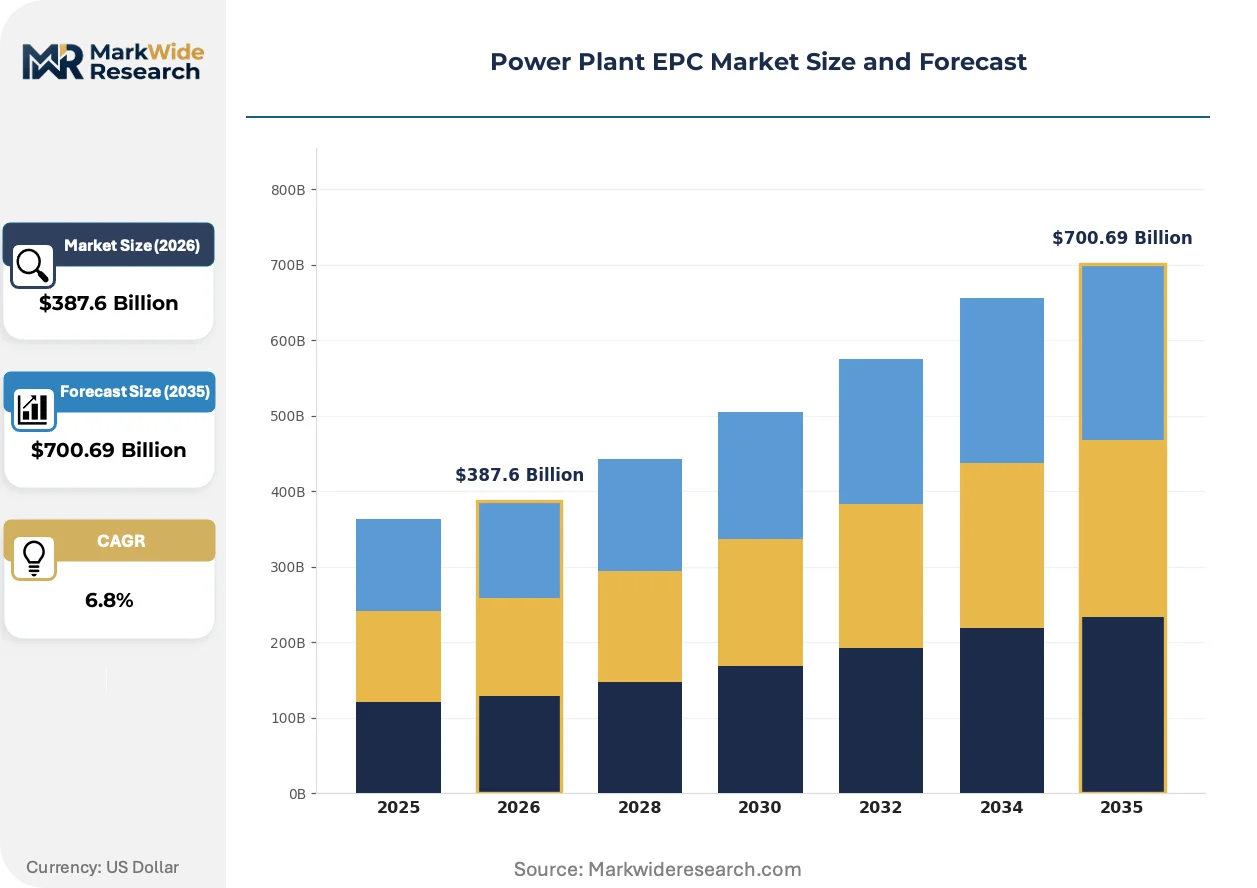
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering Services, Procurement Services, Construction Services, Commissioning Services Technology: Gas Turbine, Steam Turbine, Renewable Energy, Nuclear Technology Installation Type: Onshore, Offshore, Hybrid, Modular Capacity: Small Scale, Medium Scale, Large Scale, Ultra-Large Scale |
| Companies Covered | Worley, Saipem, Fluor Corporation, Samsung Engineering, Hyundai Engineering & Construction, Bechtel Corporation, Jacobs Solutions, SK Engineering and Construction, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Plant EPC Market Evolving Landscape
Digital twin deployment and advanced modular construction are compressing field schedules while regulatory pressure on embodied carbon reshapes equipment sourcing strategies across contractor portfolios.
Solid-state battery buffer systems are electrifying microgrid integration at remote industrial sites. Mining operators in Western Australia and Chilean lithium triangle projects are specifying lithium iron phosphate storage alongside solar-diesel hybrid plants. This convergence is electrifying EPC scope boundaries, forcing electrical contractors to assume controls and energy management system integration previously siloed within separate automation contracts.
The EU F-Gas Regulation mandates 80 percent SF6 emissions reduction by 2030, prohibiting new switchgear installations using the potent greenhouse gas after 2028. European transmission utilities are accelerating procurement of vacuum interrupter alternatives, compressing supplier qualification windows for EPC contractors. German and French grid operators now embed lifecycle carbon thresholds in technical specifications, filtering bidder pools toward contractors with established low-GWP equipment supply chains.
Hyperscale data center operators are unbundling traditional utility relationships, directly tendering generation assets through captive power purchase structures. This procurement fragmentation bypasses incumbent regional utilities in Northern Virginia, Frankfurt, and Singapore, forcing EPC contractors to establish direct commercial relationships with technology firms rather than regulated load-serving entities. Contract terms now emphasize energization guarantees over traditional availability warranties, shifting performance risk allocation toward construction-phase execution certainty.
Power Plant EPC Market Segmentation
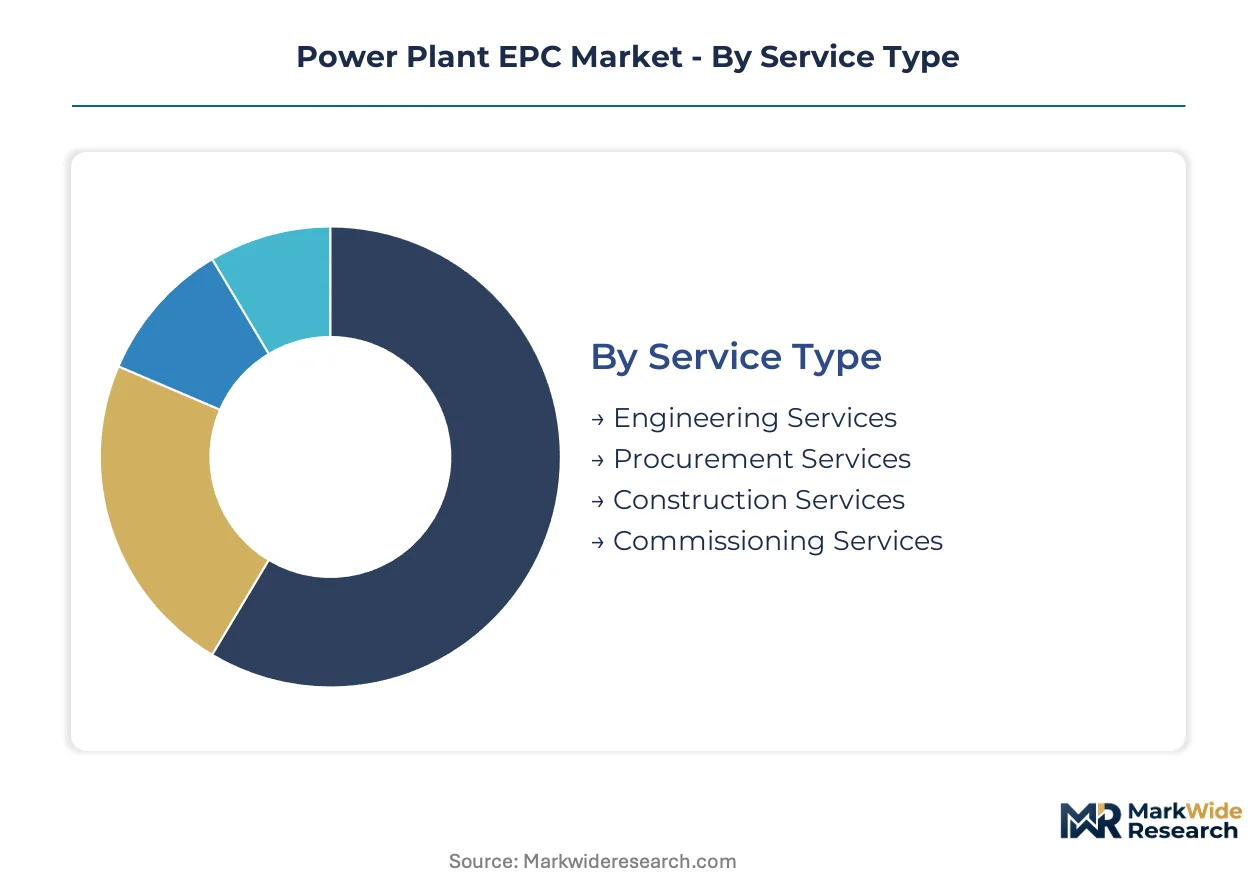
Power plant EPC contractors structure bidding strategies around service scope boundaries and technology risk profiles. Segment differentiation determines whether contractors pursue lump-sum turnkey contracts or cost-plus arrangements with equipment supply carve-outs.
Service Type:
Buyers in this category separate front-end design risk from field execution liability through contract packaging decisions.
- Engineering Services:Front-end engineering design packages establish thermal efficiency baselines and equipment specifications that lock in 70-80 percent of total installed costs. Owner-operators in India and the US increasingly unbundle FEED work to secure financing commitments before awarding construction contracts.
- Construction Services:Field execution scopes concentrate specialized labor risk, with nuclear island work demanding ASME Section IX certified welders and NRC audit-compliant quality assurance protocols. Labor productivity variance between union and non-union jurisdictions drives 15-25 percent cost spreads on identical equipment packages.
- Procurement Services:Equipment sourcing and supplier qualification for long-lead forgings and switchgear assemblies.
- Commissioning Services:Performance testing, grid synchronization, and reliability demonstration protocols.
Construction Services leads volumes today; Engineering Services is gaining share fastest as owners front-load design certainty.
Technology:
Technology selection determines contractor qualification thresholds and margin structures through specialized certification requirements.
- Renewable Energy:Solar PV and wind EPC scopes have modularized into standardized installation packages with compressed learning curves. Indian state-run utilities and European offshore wind developers are tendering hybrid storage-integrated projects that force electrical contractors into battery integration work previously outside traditional boundaries.
- Nuclear Technology:Advanced reactor designs from NuScale and GE-Hitachi are unlocking standardized island construction with reduced field welding hours. The NRC Part 52 licensing framework and specialized containment integrity standards sustain premium pricing pools unavailable in commoditized generation segments.
- Gas Turbine:Combined-cycle configurations achieving thermal efficiency above 60 percent through H-class turbine integration.
- Steam Turbine:Coal and biomass steam cycle retrofits with supercritical pressure specifications.
Gas Turbine leads volumes today; Renewable Energy is climbing the fastest as IRA incentives redirect contractor pipelines.
Installation Type:
Site constraints and grid connection logistics differentiate procurement approaches across installation categories.
- Modular:Factory-fabricated power islands with skid-mounted equipment reduce field construction schedules by 30-40 percent compared to stick-built alternatives. Fluor Corporation and Bechtel Corporation have invested in modular execution capabilities to compress energization timelines for data center operators demanding 24-month delivery cycles.
- Onshore:Traditional greenfield and brownfield construction with established civil works and grid interconnection protocols.
- Offshore:Bottom-fixed and floating platform installations for wind and gas-fired generation with marine logistics complexity.
- Hybrid:Co-located generation and storage assets with integrated control systems spanning electrical and chemical engineering disciplines.
Onshore leads volumes today; Modular is expanding most quickly as schedule certainty commands premium pricing.
Capacity:
Project scale determines contractor consortium structuring and risk allocation mechanisms through financing and execution complexity.
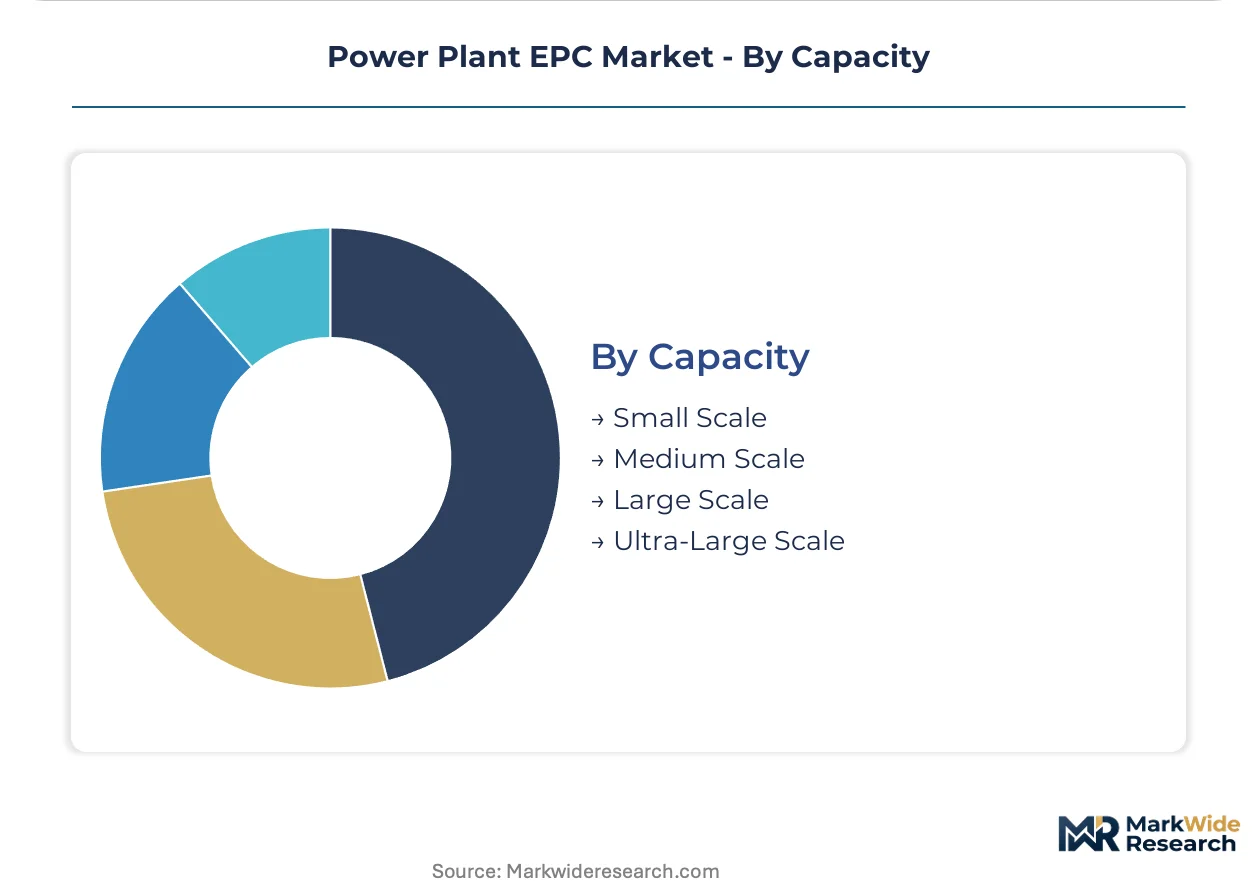
- Large Scale:Utility-scale projects exceeding 500 MW concentrate among integrated EPC firms with balance sheet capacity to absorb lump-sum risk. India's Central Electricity Authority ultra-mega power tenders and Southeast Asian combined-cycle blocks anchor contractor backlogs with multi-year revenue visibility.
- Ultra-Large Scale:Generation complexes exceeding 2,000 MW with bundled transmission and fuel supply infrastructure. State-run utilities in India package generation, transmission, and fuel supply into single EPC scopes exceeding 4,000 MW, filtering bidder pools toward consortia with civil, electrical, and fuel logistics capabilities.
- Medium Scale:Industrial captive power and distributed generation serving single large-load customers.
- Small Scale:Commercial and microgrid installations with standardized equipment packages and compressed development timelines.
Large Scale leads volumes today; Ultra-Large Scale is gaining share fastest as Indian and Middle Eastern utilities consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's ultra-mega power corridor concentrates the largest share of tendering activity, with state-run utilities bundling generation and transmission infrastructure into consolidated procurement packages. The US Inflation Reduction Act redirects contractor investment toward clean energy portfolios. Southeast Asian markets accelerate combined-cycle gas turbine deployment.
United States
Hyperscale data center operators in Northern Virginia and Phoenix directly tender captive generation assets, bypassing traditional utility interconnection queues. The EPA and NRC shape contractor qualification through emissions compliance and reactor licensing protocols. Texas and Arizona industrial clusters anchor demand for dispatchable backup capacity serving AI compute infrastructure.
India
State-run utilities under the Central Electricity Authority tender ultra-mega power projects exceeding 4,000 MW with bundled fuel supply agreements. Domestic content floors mandated by the CEA redirect procurement toward local fabrication shops with limited ASME accreditation. The western states of Gujarat and Maharashtra concentrate fabrication capacity for pressure vessels and turbine components.
China
Dual carbon goals accelerate offshore wind and nuclear expansion, with state-backed developers tendering hybrid storage-integrated projects. The Ministry of Ecology and Environment enforces embodied carbon thresholds in equipment sourcing. The Yangtze River Delta and Pearl River Delta industrial basins host the densest concentration of turbine manufacturing and modular fabrication facilities.
Germany
Transmission utilities accelerate procurement of SF6-free switchgear under the EU F-Gas Regulation phase-down schedule. CE marking directives and lifecycle carbon thresholds filter bidder pools toward contractors with established low-GWP equipment supply chains. The industrial regions of North Rhine-Westphalia and Bavaria concentrate grid infrastructure manufacturing and engineering services.
Saudi Arabia
Vision 2030 drives utility-scale solar and green hydrogen co-location projects with hybrid EPC scopes spanning electrical and chemical engineering. The Saudi Food and Drug Authority and national procurement frameworks shape contractor qualification for industrial power integration. The Eastern Province and NEOM development zone anchor mega-project tendering for integrated generation and desalination complexes.
Power Plant EPC Market Competitive Landscape
Strategic partnerships dominate the current landscape as contractors form consortia to absorb lump-sum risk on ultra-large-scale projects. The vendor base clusters around three tiers: integrated global firms with nuclear construction pedigree, regional specialists anchored in Southeast Asian utility relationships, and modular execution specialists compressing field schedules. Two competitive moves define positioning: technology licensing agreements for advanced reactor designs, and backward integration into ASME-accredited fabrication capacity to secure long-lead forging supply.
Within the integrated global tier, Bechtel Corporation and Fluor Corporation exemplify contrasting execution philosophies—one leveraging nuclear island construction heritage, the other advancing modular fabrication methods. Samsung Engineering anchors the regional specialist archetype through combined-cycle gas turbine relationships across Southeast Asian utility buyers. These three firms represent the dominant competitive vectors: nuclear qualification depth, schedule compression capability, and geographic anchoring in high-growth procurement markets.
| Leading Market Players |
|---|
| Worley |
| Saipem |
| Fluor Corporation |
| Samsung Engineering |
| Hyundai Engineering & Construction |
| Bechtel Corporation |
| Jacobs Solutions |
| SK Engineering and Construction |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
ASME Section IX certified welder pools in the US Gulf Coast and Japanese forging centers concentrate specialized labor costs that widen pricing spreads between premium nuclear-qualified contractors and standard CCGT installers. Labor-cost differentials of 15-25 percent between union and non-union jurisdictions directly map to three-tier pricing stratification across project complexity tiers.
Pricing Analysis
Input-cost pass-through dominates EPC contractor pricing, with SA-508 Grade 3 forging steel and SF6-free switchgear premiums flowing directly to owner-operators. Price differentiation hinges on ASME N-stamp certification depth and modular execution capability, with data center buyers least sensitive due to schedule certainty premiums. Cost compression in standard CCGT segments is intensifying because Samsung Engineering and Mitsubishi Power anchor Southeast Asian markets with scale economies. Utility buyers in India exhibit highest price sensitivity due to domestic content mandates redirecting procurement toward lower-cost local fabrication.
Supply Chain Analysis
Dual-sourcing requirements from India's Central Electricity Authority and US nuclear utilities mandate qualified secondary suppliers for reactor pressure vessels and turbine forgings. Geographic supply concentration centers on Japan, France, and South Korea for SA-508 Grade 3 steel and H-class gas turbine components. Raw material dependencies include nickel-based superalloys, vacuum interrupter assemblies, and long-lead electrical switchgear. Single-source vulnerability persists for ASME-accredited heavy forging capacity. Distribution runs through EPC contractor-led procurement with owner-operator equipment carve-outs on ultra-large-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value where India's domestic content floors create 20-30 percent cost spreads against Japanese and European supply chains for equivalent ASME-grade equipment.
For Market Incumbents: Extend modular fabrication investments to compress field schedules for data center operators demanding 24-month energization cycles. Deepen backward integration into ASME-accredited pressure vessel shops to secure long-lead forging supply against Japanese supplier concentration. Counter emerging modular nuclear specialists by anchoring NuScale and GE-Hitachi technology licensing agreements.
For New Entrants and Emerging Players: Enter via green hydrogen co-location EPC scopes spanning offshore wind substations and electrolyzer integration, where hybrid electrical-chemical engineering boundaries remain undefined. Target Saudi Vision 2030 and NEOM development zones for integrated generation-desalination complexes with limited incumbent expertise. Lead with marine civil capabilities and electrolyzer supplier partnerships rather than traditional power generation pedigree.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional Southeast Asian CCGT specialists lacking nuclear qualification depth but anchoring utility relationships. Long-term viability favors contractors with modular execution IP and ASME N-stamp certification as data center load growth sustains premium pricing pools. Watch NRC Part 52 licensing timeline compression as the inflection signal—contractors demonstrating 30-month reactor construction certainty will command acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into ASME Fabrication | Captive supply of reactor pressure vessel forgings reduces exposure to yen-euro exchange volatility. |
| Modular Execution Capability Investment | Factory-fabricated power islands compress data center energization schedules by 30-40 percent. |
| Advanced Reactor Technology Licensing | NuScale and GE-Hitachi partnerships unlock standardized nuclear island construction with reduced welding hours. |
| Green Hydrogen EPC Scope Expansion | Electrolyzer integration with offshore wind creates hybrid electrical-chemical project boundaries with limited competition. |
| SF6-Free Switchgear Supplier Partnerships | EU F-Gas Regulation compliance filters European transmission utility bidder pools toward early movers. |
Research Methodology
Direct dialogue with utility planning officers, IPP project developers, EPC contract directors, and grid operators grounded qualitative assessment in execution-risk realities. Secondary validation drew from EIA project databases, IEA power sector outlooks, FERC interconnection filings, and Central Electricity Authority tender records. Bottom-up project pipeline aggregation and top-down macro demand drivers were triangulated to cross-check capacity forecasts.
Segmentation outputs across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type were modeled over the projection horizon. CAGRs were derived from installed capacity build-out trajectories and capital cost learning curves. Nuclear licensing timeline assumptions and IRA incentive phase-out schedules served as key forecast inputs.
Inputs from NRC licensing databases and Indian CEA tender portals were available through the study window; gaps in proprietary EPC contract pricing introduce uncertainty bands around margin estimates. Deviation in data center load growth trajectories or NRC Part 52 review cycle compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Residential Solar Generator Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Global Power Grid System Market
Power Generation
Global Gas Turbines Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
North America Distributed Power Generation Market
Power Generation
India Gensets Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Venezuela Power Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Steam Turbine Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Asia-Pacific Distributed Power Generation Market