
 Distributed Generation Market | 2026-2036
Distributed Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Generation Market Intelligence
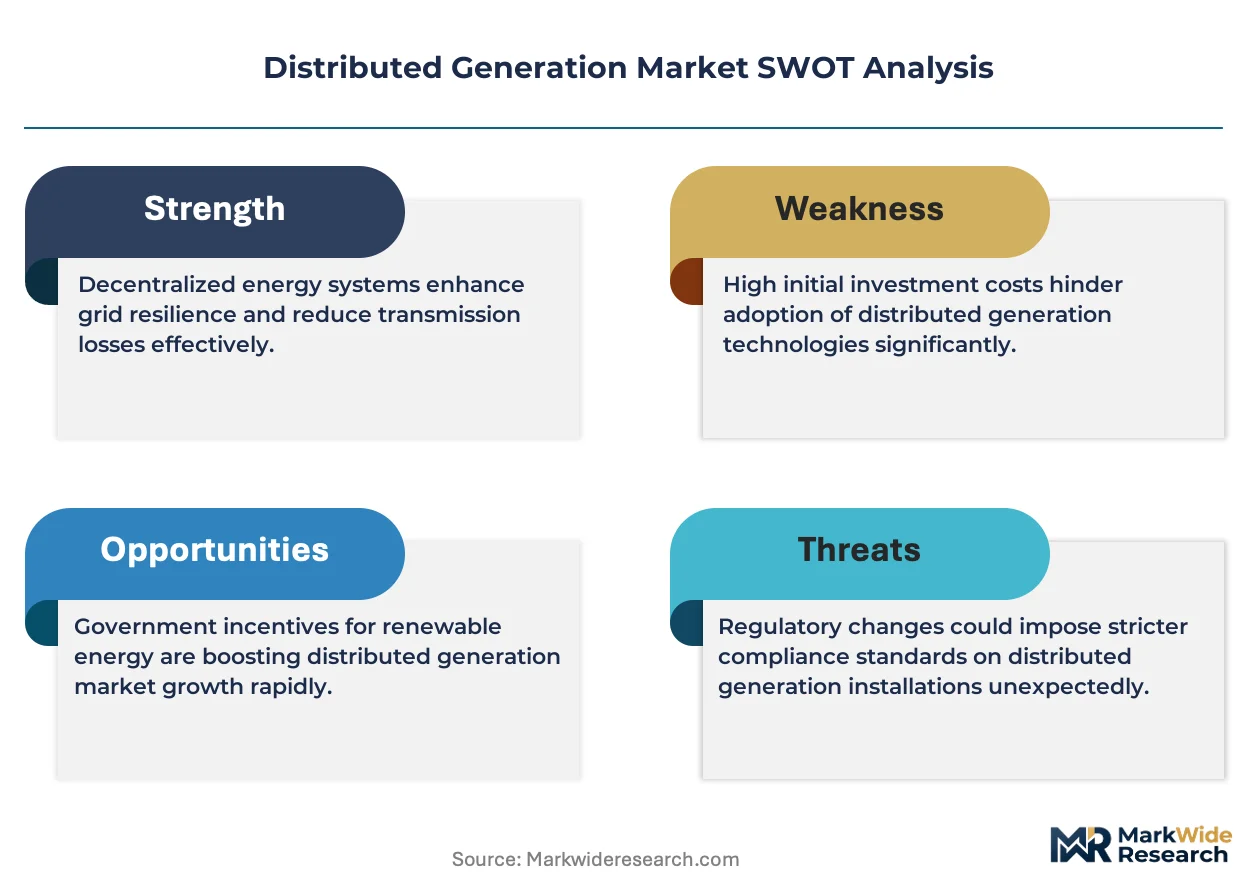
The integration of smart inverters with battery energy storage systems is reshaping the capabilities of distributed generation assets, allowing for enhanced grid stability. General Electric leverages its extensive portfolio in turbines and grid solutions to offer integrated systems. Siemens AG competes with a focus on digitalization for decentralized energy, while Schneider Electric specializes in microgrid solutions for commercial and industrial clients.
Distributed generation refers to the production of electricity from small-scale power sources, typically with capacities under 10 megawatts, located at or near the point of use. These systems provide primary power, backup supply, or grid support services. Within the technology mix, solar photovoltaic systems lead in new installations due to declining costs. Fuel cells are gaining traction for high-reliability applications in commercial facilities and data centers, commanding higher margins.
Regulatory frameworks like the US FERC's Order 2222 and the EU's Renewable Energy Directive create market access for distributed resources. National policies on net metering and interconnection standards, such as those in Australia and Japan, directly influence project economics and deployment speed. The key decision for asset owners now revolves around optimizing dispatch strategies to capture value from both energy and ancillary service markets.
Market Dynamics
The accelerating need for grid resilience against weather and cyber threats is the central force driving distributed generation. This compels utilities and large energy consumers to invest in localized power sources as a hedge against centralized grid failures.
Growth Catalysts
- Supportive Regulatory Frameworks:Policies such as FERC Order 2222 in the US create market access for aggregated distributed resources, improving project viability.
- Declining Technology Costs:Falling prices for solar PV and battery storage systems are lowering the barrier to entry for commercial and residential adopters.
- Data Center Power Demand:The need for uninterruptible power in data centers drives adoption of high-reliability fuel cells and hybrid systems.
Market Restraints
- High Upfront Capital:The significant initial investment for technologies like fuel cells and microturbines remains a barrier for smaller commercial enterprises without financing support.
- Grid Interconnection Hurdles:Inconsistent interconnection standards across different utility territories create project delays and increase development costs for asset owners.
- Intermittent Generation Profile:The variable output of renewable sources like solar requires costly energy storage or backup systems to ensure reliable power supply.
Strategic Opportunities
- Virtual Power Plant Aggregation:Software platforms can aggregate distributed assets to participate in wholesale energy markets, creating new revenue streams from grid services.
- EV Charging Infrastructure Support:Co-locating solar and storage with electric vehicle charging depots helps manage grid load and reduces operating costs for fleet operators.
- Green Hydrogen Production:Dedicated renewable generation can power on-site electrolyzers, creating a new offtake market for green hydrogen in industrial applications.
Industry Challenges
- Skilled Labor Shortages:A deficit of technicians skilled in microgrid design and control systems constrains the pace of complex project deployment.
- Cybersecurity Vulnerabilities:The growing number of connected distributed energy resources expands the attack surface, requiring robust protocols to protect grid infrastructure.
- System Integration Complexity:Ensuring interoperability between multi-vendor components like inverters, batteries, and software remains a significant technical hurdle for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Generation Market |
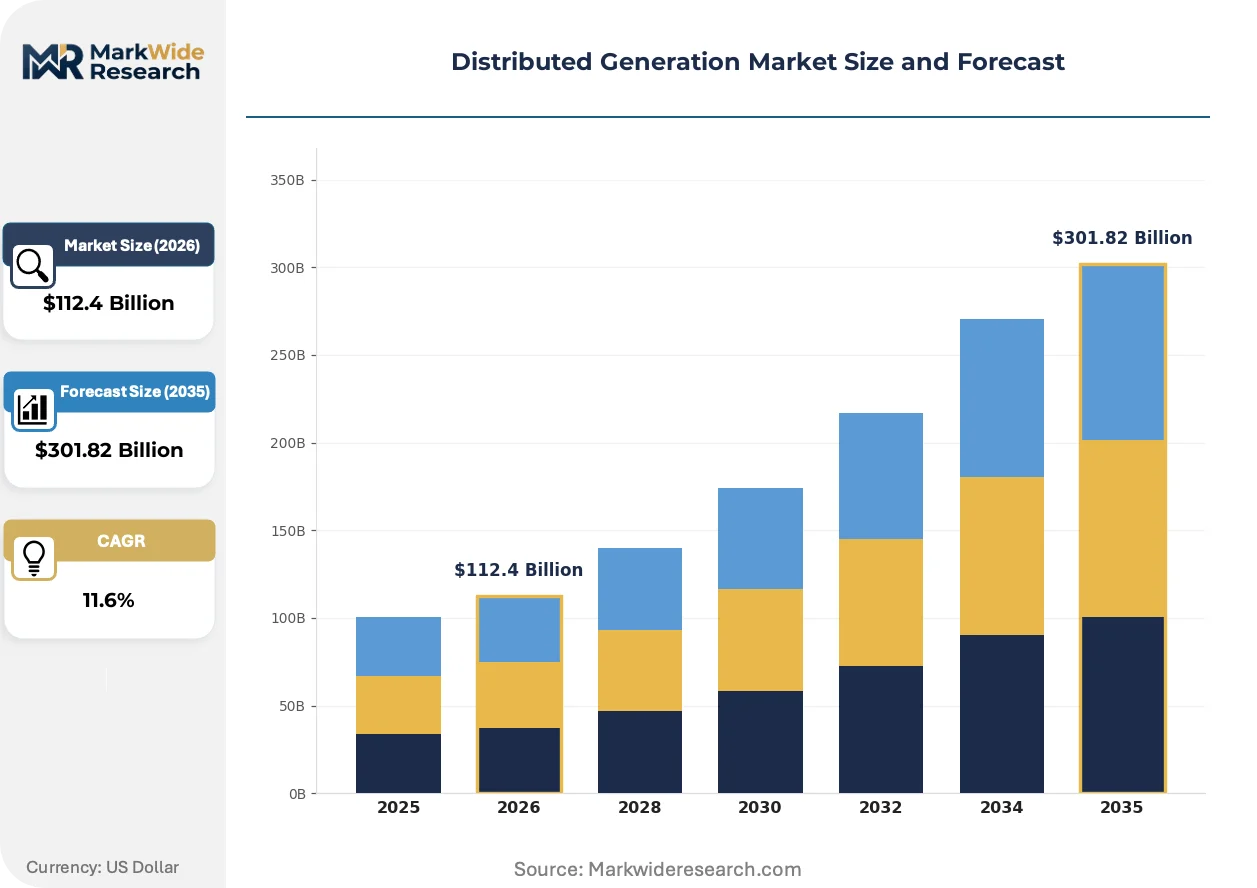
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $301.82 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Photovoltaic, Wind Turbine, Micro Turbine, Fuel Cell, Internal Combustion Engine, Combined Heat & Power Application: Residential Power, Commercial Facilities, Remote Telecom Stations, Data Centers, Agricultural Operations, Backup Power End User: Municipal Utilities, Telecommunications Providers, Data Center Operators, Property Management Firms, Agricultural Enterprises, Backup Power Operators Deployment Type: Grid-Connected, Off-Grid, Hybrid Systems, Islanded Systems |
| Companies Covered | General Electric, Schneider Electric, Siemens AG, Bloom Energy, Caterpillar, Capstone Turbine Corporation, ABB, Mitsubishi Electric, Ballard Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Generation Market Strategic Shifts & Innovations
Digitalization is transforming isolated power systems into interconnected, intelligent networks. This evolution is driven by the need to aggregate and control the collective value of geographically dispersed energy assets for grid stability.
Virtual Power Plant (VPP) software is a key technology that aggregates disparate energy resources. Grid operators and utilities are adopting these platforms to manage congestion and access ancillary services. This software-centric approach is virtualizing thousands of physical assets like batteries and solar arrays into a single, dispatchable utility-scale resource.
The European Union's Renewable Energy Directive (RED II) provides a strong regulatory push for distributed generation. It mandates that member states create frameworks enabling energy communities and prosumers to generate, consume, store, and sell energy. This policy most affects utilities in Germany and Spain, forcing them to adapt business models for local energy markets.
A clear shift is occurring from simple net metering to sophisticated, time-variant electricity rates. This change disrupts the passive solar ownership model, creating demand for integrated systems with smart energy management and storage. The trend is most advanced in markets with high solar penetration, like California and South Australia, where managing midday over-generation is a priority.
Distributed Generation Market Segmentation
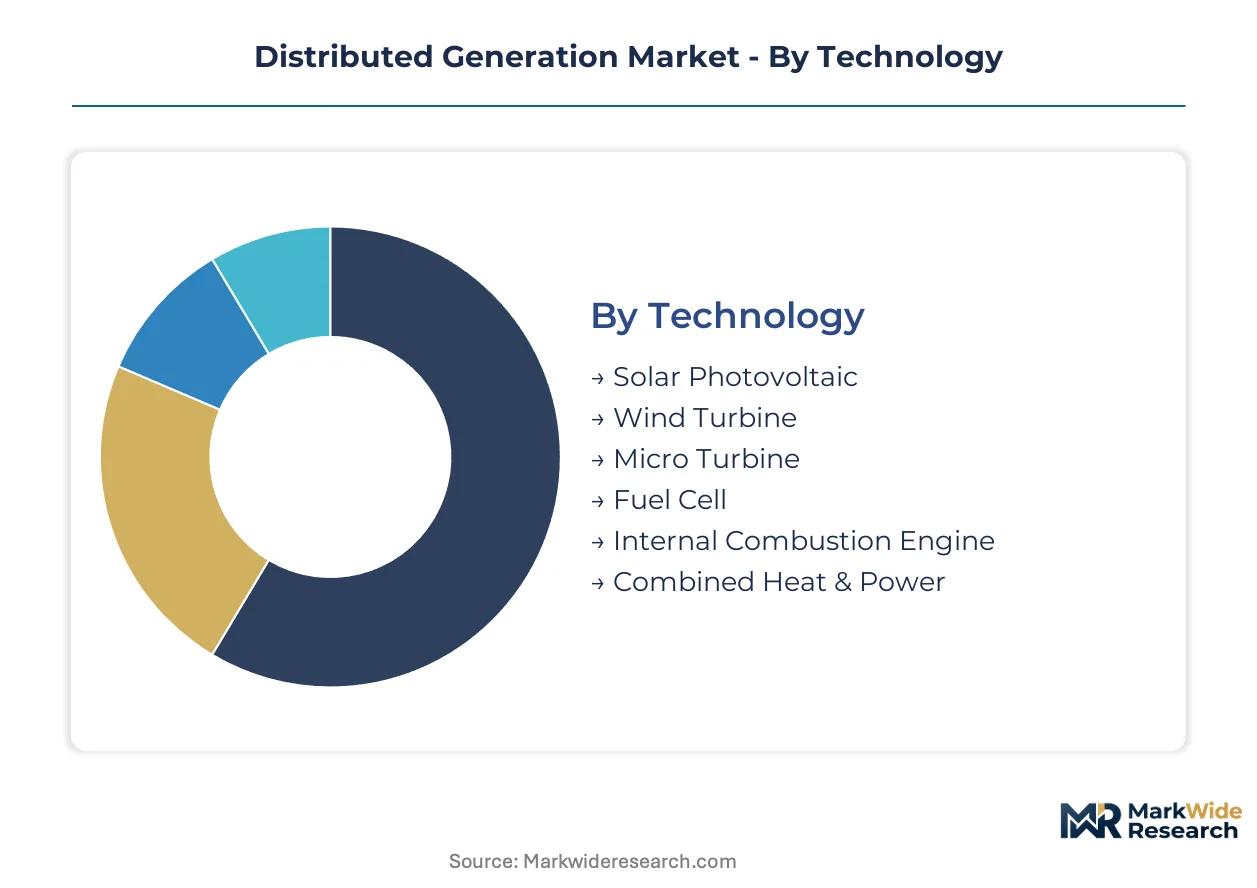
The distributed generation market is segmented to analyze the diverse technologies, applications, and operational models driving localized power production. This detailed classification clarifies where value accrues and identifies specific demand drivers across various end-use cases. Understanding these segments is crucial for strategic planning in this evolving energy landscape.
Technology:
The technology dimension captures the diverse generation methods employed across distributed energy systems.
- Solar Photovoltaic:These systems convert sunlight directly into electricity using semiconductor materials, offering a clean and scalable power source. Declining module costs and supportive net metering policies in regions like Germany drive their widespread adoption in both residential and commercial sectors.
- Fuel Cell:Fuel cells generate electricity through an electrochemical reaction, converting chemical energy from hydrogen or natural gas with high efficiency and low emissions. Data center operators and commercial facilities prioritize fuel cells for their high reliability and uninterruptible power supply needs, especially in the US.
- Wind Turbine:Small-scale wind turbines harness wind energy to produce electricity, often used in remote locations or for agricultural operations.
- Micro Turbine:These compact combustion turbines generate heat and electricity from various fuels, providing efficient combined heat and power solutions for commercial buildings.
- Internal Combustion Engine:Reciprocating engines fueled by natural gas or diesel provide reliable backup and primary power for industrial and commercial applications.
- Combined Heat & Power:CHP systems efficiently produce both electricity and useful thermal energy from a single fuel source, reducing overall energy consumption for industrial users.
Solar Photovoltaic commands the established base. The steepest expansion runs through Fuel Cell.
Application:
Different end-use scenarios dictate the specific distributed generation solutions deployed for various operational needs.
- Data Centers:These facilities require highly reliable and uninterruptible power supplies to maintain continuous operation and protect critical information. Fuel cells and hybrid systems are increasingly deployed to ensure power continuity and reduce reliance on grid power.
- Commercial Facilities:Businesses and institutions utilize distributed generation for primary power, peak shaving, and energy cost management. Microgrids combining solar, storage, and small turbines provide resilience for these clients in markets like California.
- Residential Power:Homeowners install distributed generation, primarily solar PV, to reduce electricity bills and increase energy independence.
- Remote Telecom Stations:Off-grid solutions, often combining solar and battery storage, power critical communication infrastructure in isolated areas.
- Agricultural Operations:Farms employ distributed generation for irrigation, lighting, and processing, often utilizing biogas or solar PV.
- Backup Power:Various sectors deploy distributed generators to ensure power continuity during grid outages, safeguarding essential services.
The demand landscape for distributed generation is primarily shaped by Commercial Facilities, with Data Centers showing significant future potential.
End User:
Customer types define the operational scale and specific requirements for distributed power solutions.
- Data Center Operators:These entities prioritize power reliability and quality above all else, driving investment in robust on-site generation and storage. They often deploy fuel cells and advanced backup systems to prevent downtime, especially in regions with unstable grids.
- Municipal Utilities:Local power providers integrate distributed resources to enhance grid stability, manage peak loads, and comply with renewable energy mandates. They leverage virtual power plant software to aggregate smaller assets for grid services.
- Telecommunications Providers:Companies managing communication networks use distributed generation to ensure continuous service, especially for remote towers and critical infrastructure.
- Property Management Firms:These firms implement distributed energy solutions across commercial and residential portfolios to reduce operating costs and attract tenants.
- Agricultural Enterprises:Large farms and agri-businesses adopt distributed generation for energy independence and operational efficiency, often using biomass or solar.
- Backup Power Operators:Specialised service providers manage and operate distributed generation assets specifically for emergency power supply across various industries.
While Property Management Firms represent a foundational consumer base, Data Center Operators are rapidly integrating distributed resources into their core operations.
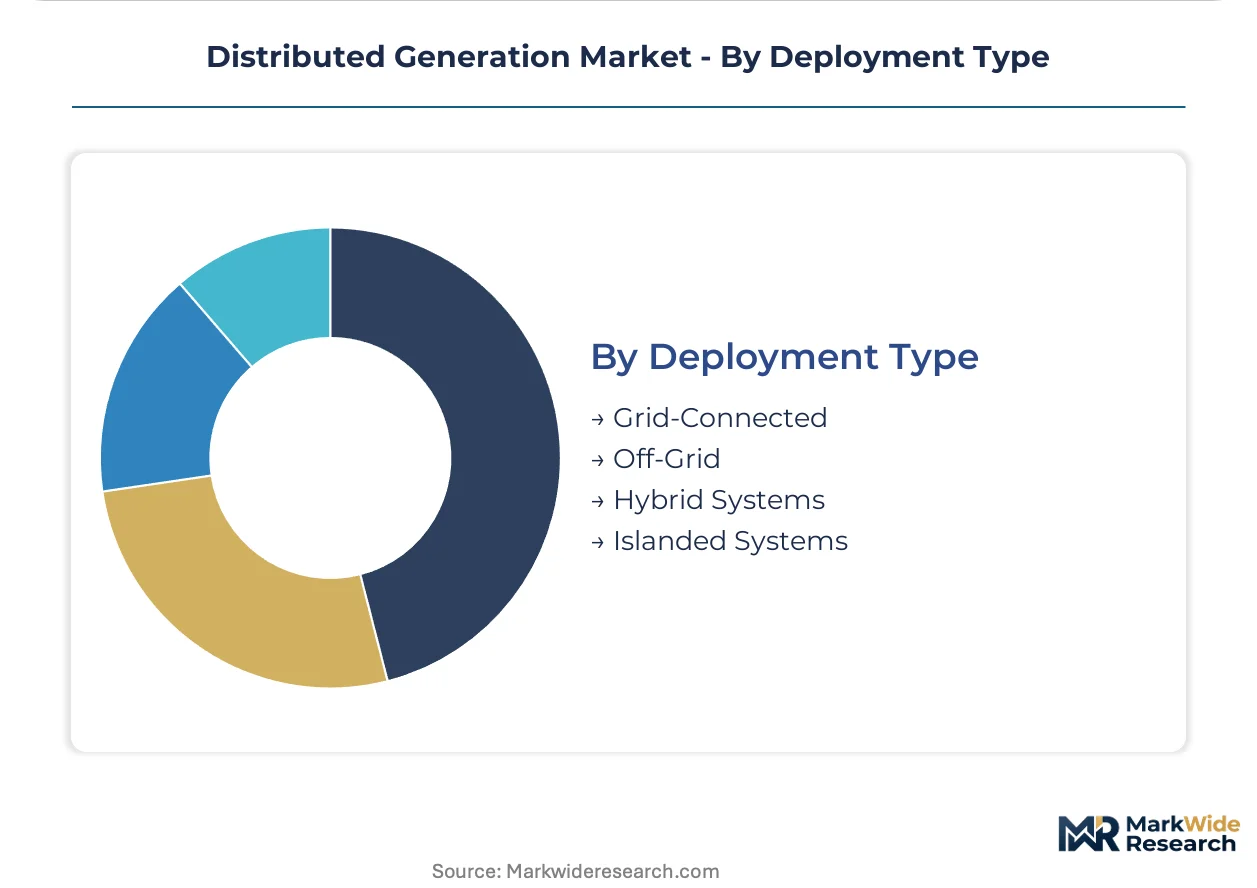
Deployment Type:
The integration model for distributed energy resources varies significantly based on grid connectivity and operational autonomy.
- Grid-Connected:These systems operate in parallel with the main electricity grid, feeding excess power back or drawing from the grid as needed. This type is dominant in developed markets like Australia and Germany, where regulatory frameworks support grid integration.
- Hybrid Systems:Combining multiple generation technologies, often including renewable sources and battery storage, hybrid systems optimize energy supply and reliability. They are increasingly chosen for microgrids and resilience projects in areas prone to outages.
- Off-Grid:Completely independent of the centralized grid, off-grid systems provide power to remote locations without access to utility infrastructure.
- Islanded Systems:These systems can disconnect from the main grid and operate autonomously, providing critical power during outages or for specific industrial processes.
Grid-Connected deployment remains the most prevalent, yet innovative solutions are emerging within Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global distributed generation market sees significant policy influence originating from Europe, impacting adoption rates across diverse national grids. Technology exports from established markets like Germany are shaping deployment strategies in emerging economies. This dynamic interchange fosters localized energy solutions worldwide.
United States
Data center operators drive significant demand for high-reliability fuel cells and hybrid systems. FERC Order 2222 creates market access for aggregated distributed resources, improving project viability for asset owners. California leads in implementing sophisticated time-variant electricity rates, requiring integrated smart energy management and storage solutions.
Germany
Strong renewable incentives and the EU's Renewable Energy Directive (RED II) significantly boost distributed generation deployment. This robust policy framework enables energy communities and prosumers to generate, consume, and sell energy. Berlin's urban energy sector actively focuses on integrating local energy markets and enhancing grid stability.
Australia
High solar penetration and national net metering policies profoundly influence distributed generation project economics. The Clean Energy Regulator supports new installations through various incentive schemes and streamlined approvals. South Australia demonstrates advanced time-variant electricity rates, efficiently managing midday over-generation.
Japan
Grid support services and energy independence drive distributed generation adoption, particularly for commercial facilities and industrial users. National interconnection standards and supportive policies accelerate deployment speed for renewable systems. Tokyo's dense urban infrastructure actively integrates microgrids for enhanced resilience and power continuity.
Distributed Generation Market Key Industry Players
Channel-controlling players compete with product-specialist players across the distributed generation market. The market exhibits a tiered structure, with large industrial conglomerates offering integrated system solutions alongside niche technology providers focusing on specific components. Strategic archetypes include comprehensive energy system integrators, specialized component manufacturers, and advanced software platform developers. Dominant competitive moves involve portfolio diversification into adjacent energy services and strategic partnerships for complex project deployment.
Among diversified industrial conglomerates, General Electric exemplifies a broad portfolio approach, leveraging its extensive turbine and grid solutions to offer integrated distributed generation systems. Siemens AG, a German-based engineering giant, occupies a position focused on digitalization for decentralized energy management and grid optimization. Schneider Electric, a French multinational corporation, represents a specialist archetype in comprehensive microgrid solutions designed for commercial and industrial clients. These entities collectively anchor the market through their extensive global reach, technological breadth, and continuous innovation in energy management.
| Leading Market Players |
|---|
| General Electric |
| Schneider Electric |
| Siemens AG |
| Bloom Energy |
| Caterpillar |
| Capstone Turbine Corporation |
| ABB |
| Mitsubishi Electric |
| Ballard Power Systems |
| Others |
Cost & Logistics Intelligence
Distributed generation overcapacity in Europe's solar sector drives down component costs, influencing global supplier behavior and forcing competitive pricing postures across technology segments.
Pricing Analysis
The technology-generation pricing gap differentiates current-generation solar PV systems from higher-margin fuel cell deployments. Project-based pricing dominates large-scale distributed generation installations, reflecting significant customization requirements for commercial and industrial clients. Price differentiation stems from geographic delivery costs and the level of after-sales service bundled with the system. Pricing softness reflects declining technology costs for solar panels and battery storage, particularly in high-volume markets. Data center operators exhibit the least price sensitivity, prioritizing reliability, while residential adopters remain highly sensitive to upfront capital expenditures.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support component manufacturers and project developers in the distributed generation market. Geographic supply concentration for solar PV components rests heavily in China, while specialized fuel cell components often source from the United States and Japan. Key raw material dependencies include silicon for solar cells and platinum group metals for fuel cell catalysts. Single-source vulnerability for specific inverter components poses a structural risk to project timelines. Distribution runs through a network of EPC contractors and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as grid modernization efforts and utility-scale renewables present a compelling alternative to localized generation for some users.
For Market Incumbents: Entrench market share by deepening vertical integration into battery energy storage manufacturing and advanced inverter controls. Focus on developing integrated hybrid systems that offer superior resilience and energy management capabilities to counter evolving grid infrastructure. Invest in technician training programs to address skilled labor shortages and improve project deployment efficiency.
For New Entrants and Emerging Players: Underpenetration in emerging economies across Southeast Asia and Latin America offers significant white-space opportunities for distributed generation. Target commercial facilities and remote telecom stations seeking energy independence and grid stability. A direct-to-customer sales model combined with flexible financing options represents a viable go-to-market angle for these regions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting in an upward direction across advanced microgrid solutions, driven by complex integration requirements and higher component costs. The long-term viability of distributed generation over a five-to-ten-year window remains strong, supported by resilience and decarbonization mandates. Target acquisition archetypes include specialized software platform developers for Virtual Power Plants. Monitor regulatory shifts in grid interconnection standards as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout for Battery Storage | Secures critical component supply and reduces reliance on external vendors for hybrid systems. |
| Advanced Microgrid Software Development | Enhances system integration and optimizes dispatch strategies for complex distributed assets. |
| Strategic Partnerships with Utilities | Facilitates streamlined grid interconnection and expands market access for aggregated resources. |
| Geographic Expansion into Underserved Markets | Captures new demand from regions with unstable grids or nascent renewable energy policies. |
| Investment in Skilled Workforce Training | Addresses labor shortages and improves the quality and speed of project deployment. |
Research Approach
Cross-validation between primary interviews and secondary market intelligence anchors the qualitative findings within this analysis. The research team engaged with utility planning officers, EPC contractors, data center operators, and component manufacturers to gather firsthand insights. Secondary data sources included government energy reports, regulatory filings, and academic studies, providing a comprehensive view of market dynamics. This approach ensured robust bottom-up and top-down triangulation of market figures.
The calibration approach involved developing an analytical framework that modeled market growth across the projection horizon. Segmentation dimensions included technology type, application, end-user, and deployment model, alongside the specific regulatory frameworks impacting regional adoption. Compound Annual Growth Rates were derived from historical trends and projected future demand, considering inputs like declining technology costs and evolving grid interconnection standards.
Practitioners should monitor shifts in national energy policies and technological breakthroughs for early signals regarding market trajectory. Forecasts reflect assumptions documented through extensive research and analysis. Macroeconomic fluctuations, changes in renewable energy incentives, or significant grid infrastructure upgrades would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Variable Speed Generator Market
Power Generation
Captive Power Generation Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Stirling Engine Market
Power Generation
Power Plant EPC Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
Wind Power EPC Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
East Africa Power Market
Power Generation
Oilfield Power Generation Market
Power Generation
Commercial Gensets Market