
 Battery Swap Station Market | 2026-2036
Battery Swap Station Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Swap Station Market Insights
Lithium iron phosphate is repositioning nickel-cobalt-manganese in swap-compatible battery packs, cutting thermal management costs and extending cycle life. NIO Inc. leverages its proprietary battery-as-a-service architecture to lock in subscriber retention across China's premium EV segment. Gogoro Inc. anchors its dominance in Taiwan through dense urban station networks purpose-built for two-wheeler density. CATL competes by supplying standardized swap cells to multiple OEMs, eroding proprietary lock-in advantages.
A battery swap station is an automated or semi-automated facility that exchanges depleted traction battery packs for fully charged units within three to five minutes, utilizing robotic alignment systems and conductive charging interfaces. The primary commercial purpose is eliminating dwell-time penalties for commercial EV operators who cannot absorb multi-hour plug-in charging intervals. Fleet Services generates the deepest margin pools due to predictable utilization rates and long-term contract structures, while Automated Systems capture disproportionate capital allocation as operators seek labor cost reduction and throughput maximization. Subscription-Based operation models sustain the highest customer lifetime value by bundling battery depreciation risk into predictable monthly fees.
China's MIIT enforces GB/T standards for battery swap interoperability, compelling station operators to adopt uniform mechanical and electrical interfaces. The EU Green Deal and F-Gas Regulation shape European deployment by restricting fluorinated greenhouse gases in thermal management systems and mandating lifecycle carbon accounting for imported batteries. Stakeholders must monitor whether regional standardization bodies harmonize swap protocols or perpetuate fragmented infrastructure investments that strand capital.
Market Dynamics
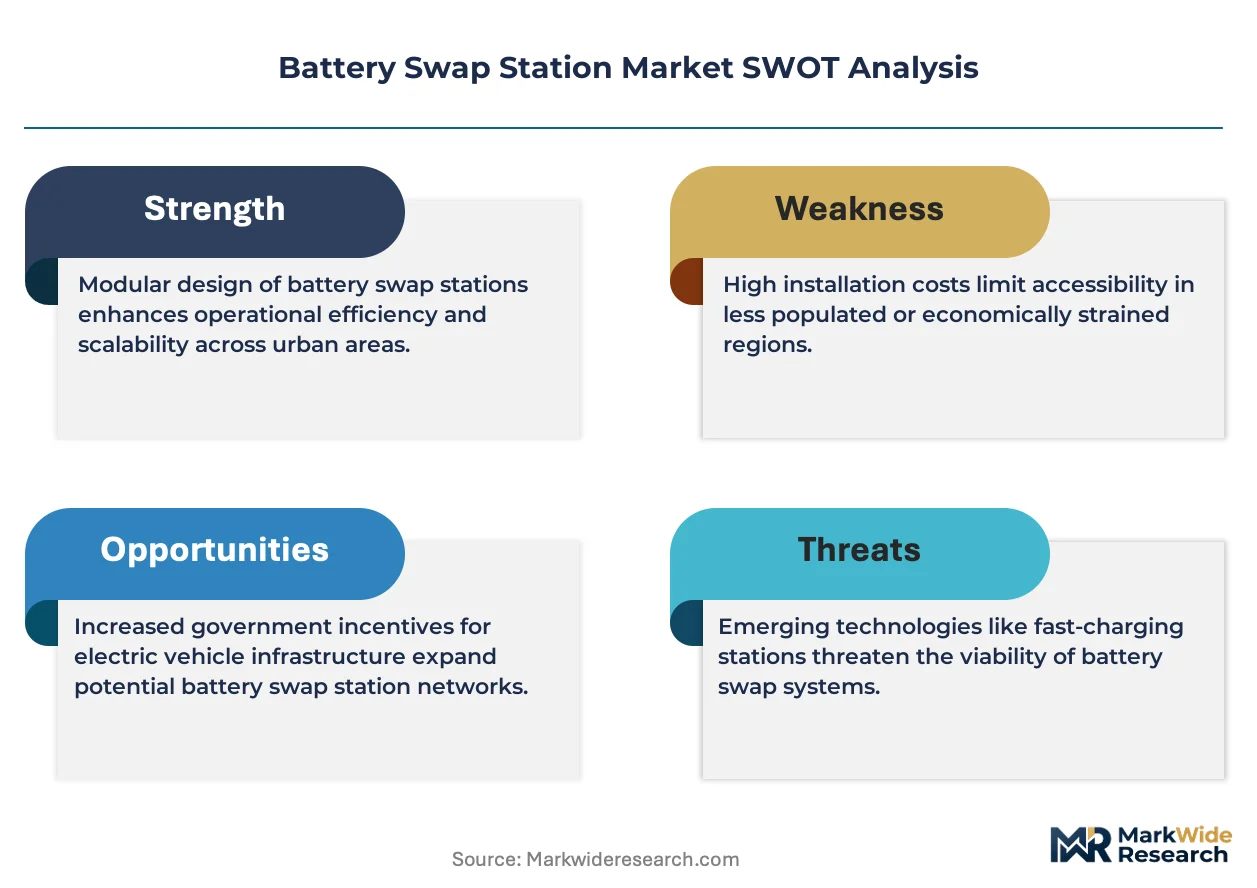
The battery swap station market pivots on the tension between proprietary battery architectures and regulatory pressure for cross-brand interoperability, with China's MIIT mandating GB/T standards that erode first-mover technical moats.
Growth Catalysts
- NEV Mandates:China's dual carbon goals compel municipal governments in tier-one cities to fast-track swap infrastructure permits and subsidize station construction.
- Logistics Fleet Electrification:Last-mile delivery operators face diesel ban deadlines in Shenzhen and Shanghai, driving predictable utilization contracts with swap providers.
- LFP Chemistry Maturation:Lithium iron phosphate cells tolerate higher cycle depths than nickel-cobalt-manganese alternatives, reducing per-swap battery depreciation costs.
Market Restraints
- Lithium Price Volatility:Raw material cost swings compress station operator margins on battery inventory held in float.
- Supply Concentration Risk:Automated robotic alignment systems rely heavily on precision actuator suppliers clustered in Germany's industrial belt.
- Plug-in Charging Substitution:Megawatt-scale fast chargers from ABB and Siemens threaten swap economics for long-haul trucking routes.
Strategic Opportunities
- Southeast Asia Two-Wheeler Density:Jakarta and Bangkok's motorcycle-centric urban mobility patterns replicate Taiwan's proven Gogoro deployment model.
- EU Battery Passport Mandate:The EU Green Deal's lifecycle carbon accounting requirements favor swap systems with centralized battery health tracking over distributed plug-in assets.
- Vehicle-to-Grid Convergence:Swap station battery pools double as grid stabilization assets, capturing frequency regulation revenue streams.
Industry Challenges
- Robotics Integration Talent Scarcity:Station deployment timelines stretch due to shortage of engineers fluent in both battery management systems and precision mechanical alignment.
- Multi-OEM Certification Complexity:Each new vehicle model requires bespoke validation of mechanical lock interfaces and CAN bus handshake protocols.
- Legacy Grid Connection Delays:Distribution utility interconnection queues in dense urban cores extend station commissioning by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Swap Station Market |
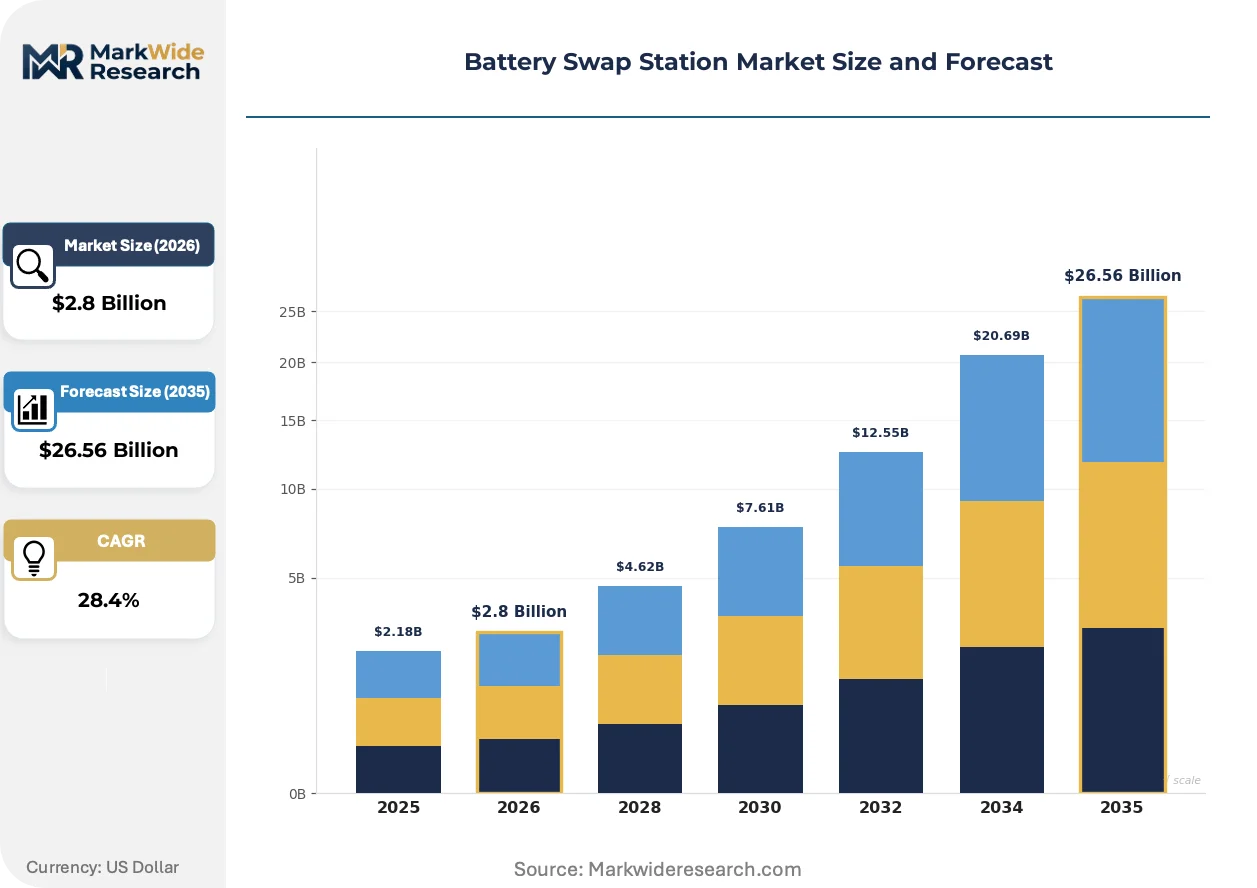
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.56 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Automotive Services, Fleet Services, Consumer Services, Charging Solutions Technology: Automated Systems, Manual Operations, Mobile Platforms, Software Integration End User: EV Owners, Corporate Fleets, Ride-Sharing Services, Delivery Services Operation Model: Subscription-Based, Pay-Per-Swap, Membership Plans, Free Services |
| Companies Covered | NIO Inc., Gogoro Inc., Sun Mobility, Ample, CATL, Aulton New Energy Automotive Technology, BYD Co. Ltd., Kwang Yang Motor Co. Ltd., Amara Raja, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Swap Station Market Trends and Innovations
Standardization pressure and automation investment are compressing swap transaction times while expanding compatible vehicle portfolios beyond premium passenger segments.
Modular battery pack architectures are converging with wireless battery management systems to eliminate physical connector wear points. Fleet operators in cold-chain logistics are adopting these configurations fastest, drawn by reduced maintenance downtime. The structural consequence is converging with open-platform station designs that accommodate multiple OEM form factors without mechanical retrofits.
The EU F-Gas Regulation restricts hydrofluorocarbon-based thermal management fluids in swap station climate control systems. Industrial consequence forces operators toward CO2 or ammonia-based cooling loops with higher capital intensity. Cold-climate Nordic deployments are most affected, with station builders accelerating phase-out timelines ahead of mandated deadlines.
Asset-light subscription contracts are displacing per-swap transaction pricing among commercial fleet buyers. Leasing companies and energy retailers are capturing this channel, bundling battery depreciation risk into fixed monthly fees. This pattern is most visible across China's ride-hailing operator consolidation, where platform companies negotiate enterprise-wide swap access rather than driver-paid transactions.
Battery Swap Station Market Segmentation
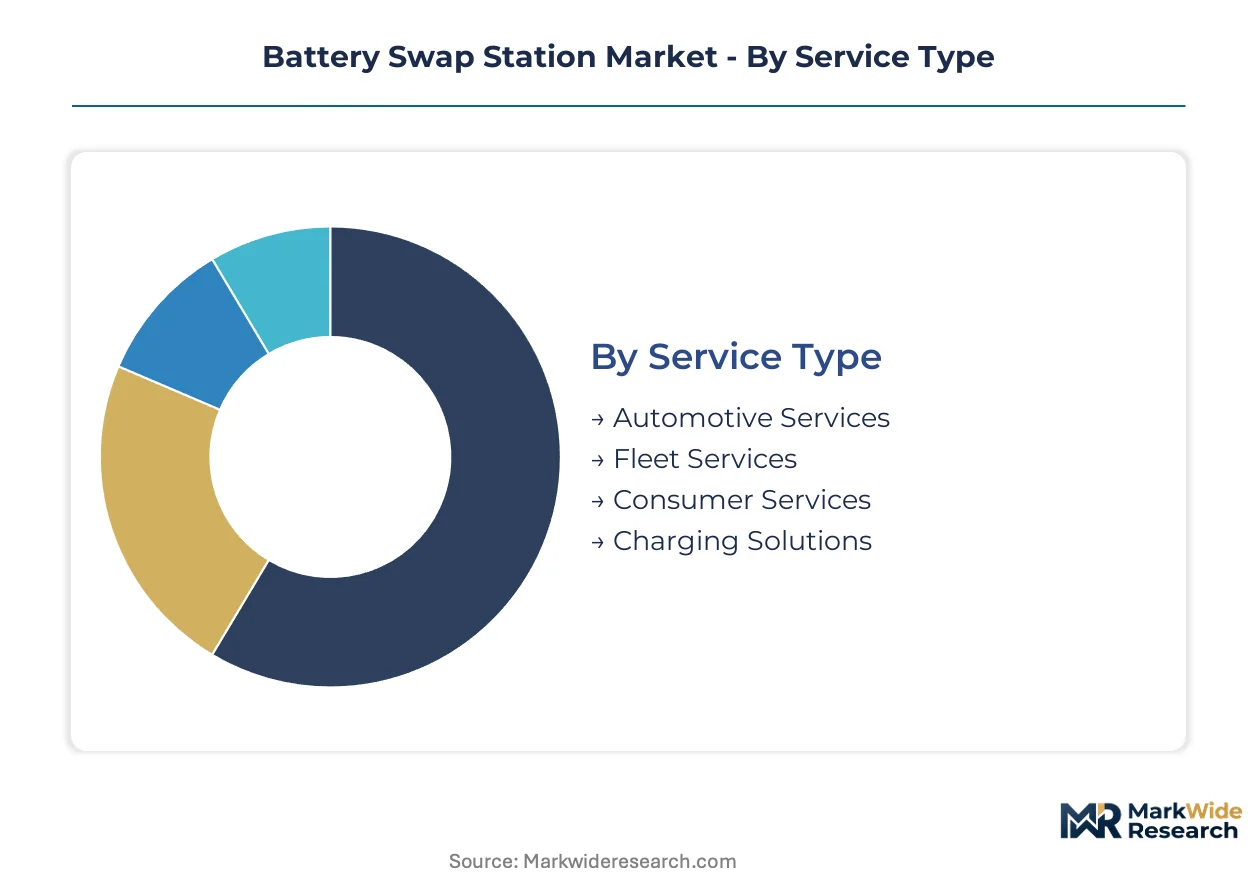
Battery swap station operators configure service portfolios around utilization predictability and capital recovery timelines. Segmentation choices directly determine margin structure, customer acquisition cost, and grid interconnection requirements across deployment geographies.
Service Type:
Fleet operators prioritize guaranteed throughput over consumer convenience, driving divergent infrastructure investments.
- Fleet Services:Long-term contracts with logistics and ride-hailing operators lock in predictable station utilization rates. Shenzhen and Shanghai municipal diesel bans compel last-mile delivery electrification, anchoring demand for dedicated swap bays with priority scheduling protocols.
- Automotive Services:Premium passenger EV owners access swap stations through battery-as-a-service subscriptions. NIO Inc. deploys proprietary architecture across China's tier-one cities, capturing subscriber retention through integrated vehicle-battery-station ecosystems.
- Consumer Services:Individual EV owners without home charging access utilize public swap networks on demand. Taiwan's metropolitan corridors concentrate deployment where residential parking scarcity intersects high two-wheeler density.
- Charging Solutions:Hybrid stations combine swap bays with plug-in fast chargers for mixed-fleet compatibility. European operators favor this configuration under EU Green Deal lifecycle carbon accounting requirements.
Volume sits with Fleet Services; growth tilts toward Consumer Services as residential charging constraints spread beyond China's megacities.
Technology:
Labor cost differentials and throughput requirements shape automation investment decisions across operator portfolios.
- Automated Systems:Robotic alignment systems execute three-to-five-minute battery exchanges using precision actuators and conductive charging interfaces. Germany's industrial belt supplies critical actuator components, creating supply concentration risk for station builders.
- Manual Operations:Semi-automated configurations retain human oversight for battery handling and quality verification. Emerging market deployments favor lower capital intensity where labor costs offset throughput penalties.
- Mobile Platforms:Containerized swap units deploy to temporary locations for event servicing or construction site electrification. Cold-chain logistics operators pilot these for seasonal demand spikes.
- Software Integration:Cloud-based battery health monitoring and predictive maintenance platforms reduce per-swap depreciation costs. EU Battery Passport mandates favor centralized tracking architectures.
Capital deployment concentrates on Automated Systems; expansion is climbing fastest in Software Integration as grid stabilization revenue streams mature.
End User:
Utilization patterns and contract structures vary sharply between individual and institutional buyers.
- Corporate Fleets:Enterprise-wide swap access agreements bundle battery depreciation risk into fixed operational budgets. China's ride-hailing platform consolidation accelerates this segment's expansion.
- Delivery Services:Cold-chain and last-mile operators demand thermal-managed battery pools for cargo integrity. Jakarta and Bangkok replicate Taiwan's two-wheeler density model.
- Ride-Sharing Services:Driver-paid per-swap transactions yield to platform-negotiated subscription models. Asset-light leasing companies capture margin through battery ownership.
- EV Owners:Individual premium segment subscribers accept proprietary lock-in for convenience guarantees. Mass-market penetration awaits cross-brand interoperability standards.
Contract value peaks with Corporate Fleets; customer acquisition velocity favors Delivery Services as Southeast Asian urban density rises.
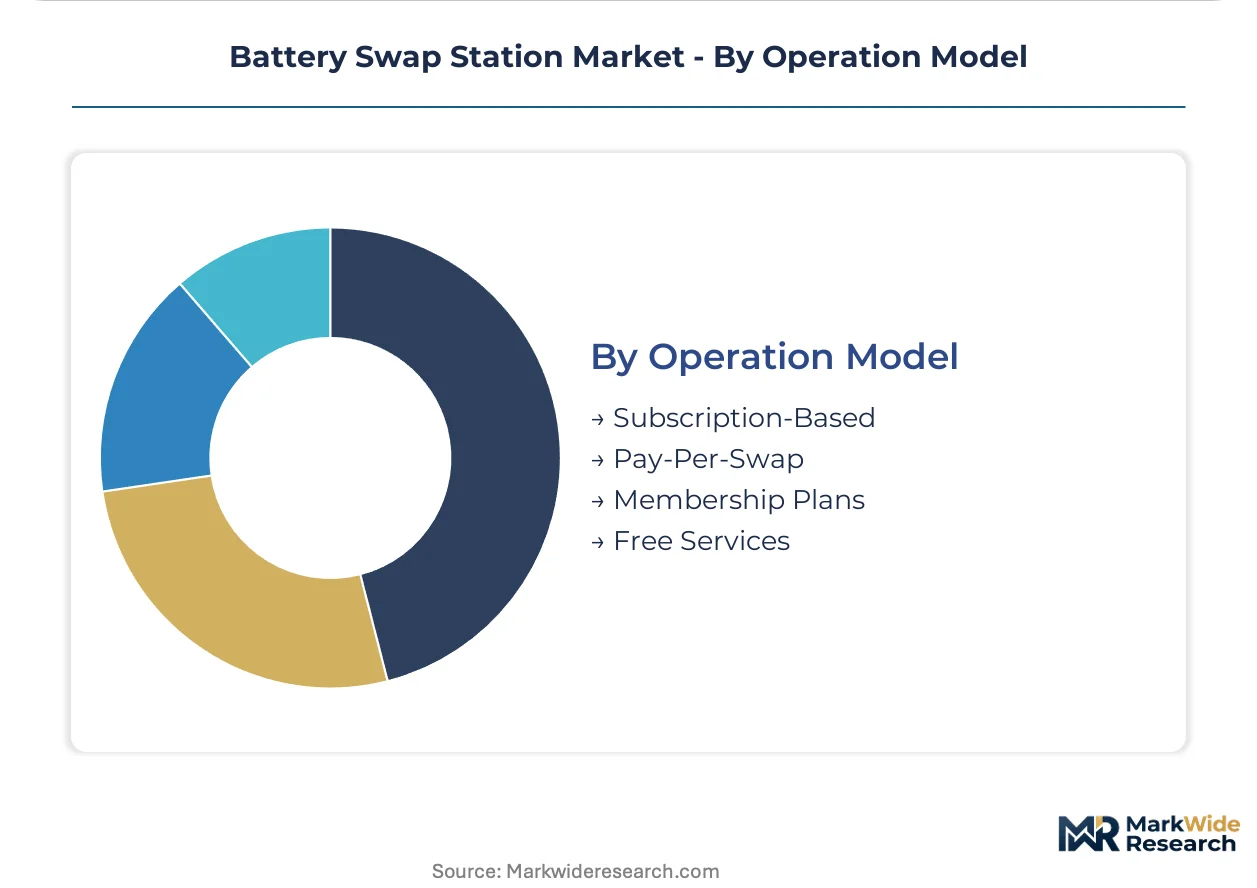
Operation Model:
Pricing architecture determines capital recovery speed and customer lifetime value capture.
- Subscription-Based:Monthly fees bundle unlimited swaps with battery depreciation risk transfer. This model sustains highest customer lifetime value through predictable recurring revenue.
- Pay-Per-Swap:Transaction pricing suits occasional users and trial conversions. Margin compression from lithium price volatility hits this model hardest on battery inventory float.
- Membership Plans:Tiered access packages balance fixed and variable components. Energy retailers favor this hybrid for customer stickiness without full asset ownership.
- Free Services:Promotional swaps drive vehicle sales conversion and platform ecosystem lock-in. OEMs subsidize these through vehicle margin cross-subsidization.
Revenue stability favors Subscription-Based; market share is gaining fastest in Membership Plans as energy retailers enter the channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for battery swap infrastructure concentrates in jurisdictions with aggressive electrification mandates and dense commercial fleet operations. China's tier-one cities anchor deployment volume through municipal diesel bans and dual carbon policy enforcement. Europe and Southeast Asia follow distinct adoption curves shaped by regulatory architecture and urban mobility patterns.
China
Logistics fleet electrification and ride-hailing platform consolidation drive station deployment across Shenzhen, Shanghai, and Beijing. MIIT enforces GB/T interoperability standards that erode proprietary technical advantages while accelerating infrastructure rollout. The Yangtze River Delta hosts the densest station networks, with municipal governments fast-tracking construction permits for swap facilities serving last-mile delivery operators.
Taiwan
Metropolitan corridors exhibit extreme two-wheeler density that sustains purpose-built urban station networks. National regulators align local technical standards with mainland Chinese GB/T protocols to enable cross-strait battery compatibility. Taipei and Kaohsiung concentrate deployment where residential parking scarcity intersects high scooter utilization rates among gig economy workers.
Germany
Premium automotive OEMs pilot swap integration alongside fast-charging corridors for long-haul commercial routes. The EU F-Gas Regulation restricts hydrofluorocarbon thermal management fluids, forcing station builders toward CO2-based cooling systems with higher capital intensity. Bavaria and Baden-Württemberg industrial clusters supply precision actuator components for automated alignment systems.
Indonesia
Jakarta's motorcycle-centric urban mobility patterns replicate proven two-wheeler swap deployment models from neighboring markets. National electric vehicle conversion targets for government fleets create anchor demand for station infrastructure. The Greater Jakarta metropolitan area concentrates pilot programs where ride-hailing platform consolidation enables enterprise-wide battery access agreements.
Netherlands
Last-mile delivery electrification mandates in Amsterdam and Rotterdam drive fleet service contracts with predictable utilization rates. EU Battery Passport lifecycle carbon accounting requirements favor centralized battery health tracking architectures. The Randstad urban corridor hosts hybrid station configurations combining swap bays with plug-in fast chargers for mixed-fleet compatibility.
Battery Swap Station Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary ecosystem builders commanding premium positioning while component suppliers erode technical lock-in through standardization. The vendor base organizes into three tiers: integrated OEM-station operators, independent infrastructure specialists, and battery cell suppliers extending into swap hardware. Consolidation pressure intensifies as GB/T interoperability mandates commoditize mechanical interface differentiation. Dominant competitive moves include strategic partnerships between energy retailers and station operators, plus backward integration by battery manufacturers into swap hardware production.
Within the integrated ecosystem tier, NIO Inc. and Gogoro Inc. exemplify divergent geographic specializations—NIO occupying position across China's premium passenger segment through battery-as-a-service architecture, Gogoro anchoring Taiwan's two-wheeler density with dense urban network deployment. CATL represents the component-supplier archetype, supplying standardized swap cells to multiple OEMs and eroding proprietary advantages through cross-brand compatibility. These three entities illustrate the structural tension between closed-platform retention strategies and open-standard market expansion.
| Leading Market Players |
|---|
| NIO Inc. |
| Gogoro Inc. |
| Sun Mobility |
| Ample |
| CATL |
| Aulton New Energy Automotive Technology |
| BYD Co. Ltd. |
| Kwang Yang Motor Co. Ltd. |
| Amara Raja |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot benchmarks cascade through battery swap station economics, compressing margins on battery inventory float while forcing operators toward subscription pricing that locks in predictable revenue streams against raw material volatility.
Pricing Analysis
Volume concentrates in fleet services contracts with thin per-swap margins, while automotive services subscriptions capture disproportionate value through battery-as-a-service bundling. Price differentiation separates premium proprietary ecosystems from standardized open-platform access, with certification under China's GB/T protocols commanding modest premiums. Cost compression in pay-per-swap tiers is intensifying because lithium price volatility erodes inventory carrying returns. Corporate fleets exhibit lowest price sensitivity due to operational certainty requirements, whereas individual EV owners demonstrate highest elasticity to per-transaction costs.
Supply Chain Analysis
Regional distribution centers in China's Yangtze River Delta and Taiwan's northern industrial corridor feed hub-and-spoke deployment patterns for station hardware. Precision actuators draw from Germany's Bavarian industrial belt, while lithium iron phosphate cells rest on South Korean and Chinese cathode supply. Single-source vulnerability concentrates in robotic alignment systems where German actuator suppliers dominate niche specifications. Distribution runs through OEM-captive logistics for proprietary networks and third-party infrastructure specialists for open-platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as China's GB/T interoperability mandates commoditize mechanical interface differentiation, forcing subscale operators into strategic exits or acquisition.
For Market Incumbents: Hedge proprietary lock-in erosion by securing backward integration into battery cell supply through CATL partnership structures or captive LFP production. Accelerate software integration investments in predictive maintenance platforms that create switching costs independent of hardware standardization. Prioritize fleet service contract renewals in Shenzhen and Shanghai where municipal diesel bans guarantee utilization baselines.
For New Entrants and Emerging Players: Energy retailers represent the most accessible channel partner type for market entry without captive vehicle ecosystems. Target Jakarta and Bangkok's two-wheeler density corridors where Gogoro's model remains unchallenged and local platform consolidation enables enterprise-wide access agreements. Pursue asset-light subscription bundling through existing fuel retail networks rather than greenfield station construction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor automated systems specialists with GB/T certification completion in China's tier-two cities where permit backlogs have stalled independent deployment. Long-term viability hinges on grid stabilization revenue capture through vehicle-to-grid convergence. Monitor EU Battery Passport implementation timelines as the inflection signal for European infrastructure deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | GB/T compliance unlocks multi-OEM station utilization across China's municipal networks. |
| Battery Supply Agreement | CATL's standardized swap cells erode proprietary advantages through cross-brand compatibility. |
| Geographic Manufacturing Footprint | Yangtze River Delta clustering minimizes logistics costs for station hardware deployment. |
| Charging Infrastructure Partnership | Hybrid swap-plug configurations satisfy EU Green Deal lifecycle carbon accounting requirements. |
| Software-Defined Vehicle Investment | Wireless battery management systems eliminate connector wear points in cold-chain logistics fleets. |
Research Methodology
Document review covered MIIT regulatory filings, EU F-Gas Regulation implementation guidance, and customs trade data for precision actuator imports, complemented by interviews with station operations executives, fleet procurement managers at logistics platforms, battery management systems engineers, and municipal transport planning officers. Secondary validation drew from SEC filings of listed swap station operators, IEA electrification scenario databases, and vehicle production registration statistics. Bottom-up station deployment counts triangulated against top-down infrastructure investment forecasts.
Segment-level outputs across service type, automation tier, and end-user category were generated through the projection horizon using elasticity-adjusted adoption curves. CAGRs were derived from logistic diffusion modeling of fleet electrification mandates and consumer charging constraint indices. Key inputs included lithium carbonate price trajectories, GB/T standard implementation timelines, and municipal permit approval velocity across tier-one Chinese cities.
Several conditions sit outside the modeled scope, including abrupt lithium supply disruptions, retroactive regulatory changes to F-Gas phase-out schedules, and breakthrough megawatt charging performance that eliminates swap speed advantages. Forecasts reflect assumptions regarding station utilization rates and battery cycle degradation curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
North America Electric Vehicle Charging Station Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charging System Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market