
 Advanced Energy Storage Systems Market | 2026-2036
Advanced Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Energy Storage Systems Market Intelligence
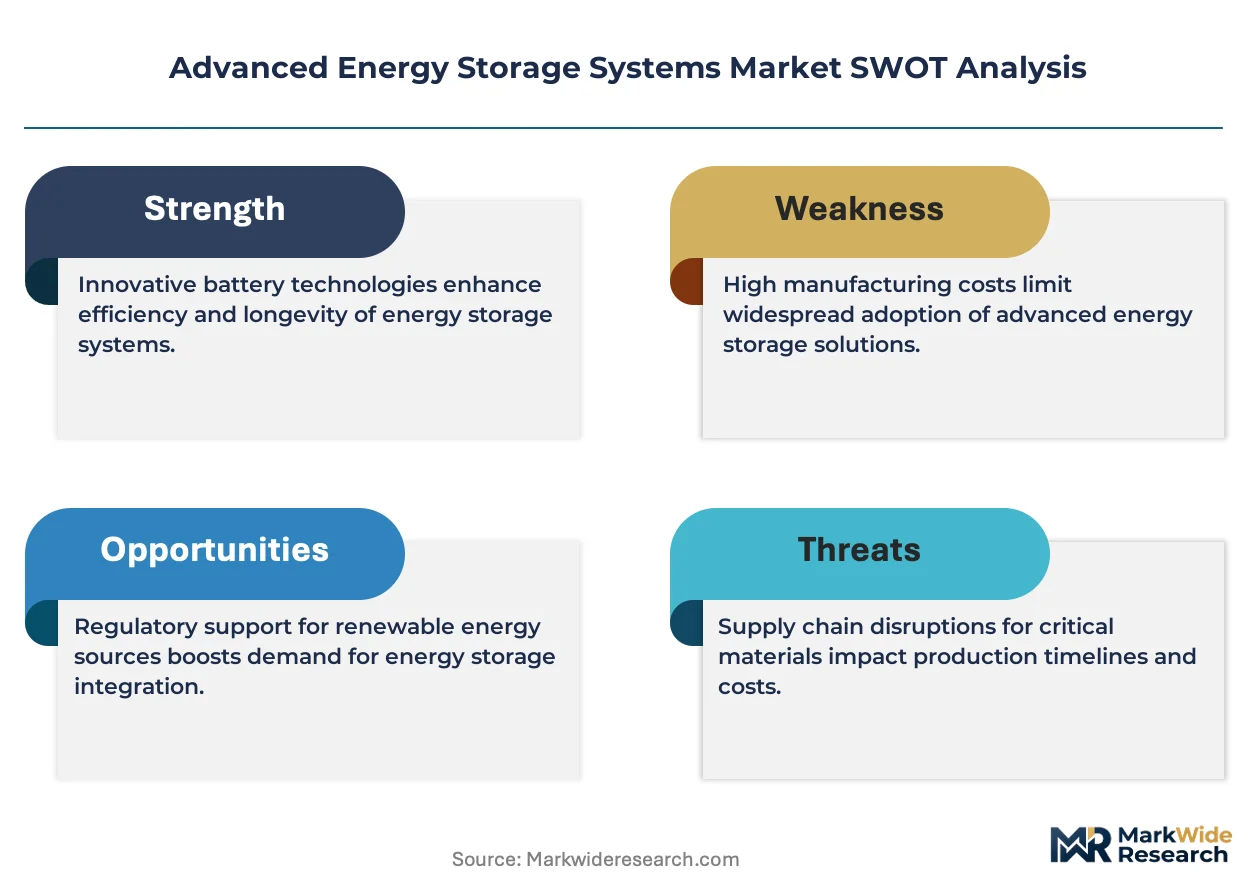
Utility procurement channels is reshaping vendor relationships in advanced energy storage. Tesla leverages its integrated hardware-software stack to control project development timelines from cell production to grid interconnection. LG Energy Solution anchors supply security through captive cathode capacity and long-term offtake agreements with North American developers. Fluence differentiates its digital platform approach, competing on algorithmic dispatch optimization rather than pure hardware cost.
Advanced energy storage systems encompass electrochemical, mechanical, and thermal technologies designed to capture electrical energy for deferred discharge, with lithium-ion cells currently achieving energy densities above 250 Wh/kg and round-trip efficiencies exceeding 90%. These systems enable time-shifting of renewable generation, grid frequency regulation, and backup power continuity for critical loads. Lithium-ion batteries dominate installed capacity due to manufacturing scale and declining cell costs, while flow batteries occupy emerging utility-scale durations beyond four hours where cycling economics favor aqueous chemistries. Solid-state batteries represent the fastest-growing technology segment for aviation and defense applications demanding enhanced safety profiles, though manufacturing maturity remains concentrated in pilot facilities.
The US EPA and FERC jointly influence project economics through environmental permitting timelines and wholesale market participation rules for storage assets. China's MIIT and NMPA enforce GB standards on cell safety and recycling accountability, constraining market access for uncertified suppliers. The EU Green Deal and F-Gas Regulation are redirecting European procurement toward non-fluorinated electrolyte systems. Stakeholders must monitor evolving capacity market remuneration mechanisms and carbon border adjustments that will determine regional manufacturing competitiveness.
Market Dynamics
Utility-scale battery procurement is concentrating manufacturing investment around captive cathode supply and integrated hardware-software stacks, compressing vendor margins for pure cell suppliers while rewarding system integrators with dispatch algorithm control.
Growth Catalysts
- US Inflation Reduction Act production tax credits:Domestic content bonuses redirect gigafactory location decisions toward North American supply chains, accelerating local cell and pack assembly capacity.
- Data center load growth:Hyperscale operators in Virginia and Texas are procuring multi-gigawatt-hour storage portfolios to manage renewable power purchase agreement intermittency and secure dispatchable clean capacity.
- Four-hour plus duration economics:Vanadium and iron-chromium flow batteries achieve favorable levelized cost of storage in daily cycling regimes where lithium-ion degradation accelerates.
Market Restraints
- Lithium carbonate price volatility:Argentine and Chilean brine supply disruptions transmit directly to cell cost structures, destabilizing project finance assumptions for independent power producers.
- Cathode precursor concentration:Chinese refiners control over 80% of nickel-manganese-cobalt hydroxide conversion capacity, creating single-source dependency for Western battery manufacturers.
- Round-trip efficiency ceiling:Lithium-ion systems plateau near 92% efficiency, constraining revenue capture in arbitrage-heavy markets where every percentage point determines merchant viability.
Strategic Opportunities
- India grid-scale tender pipeline:Central Electricity Authority mandates and PLI scheme incentives are aggregating demand for 50 GWh of storage procurement through 2030, opening new manufacturing localization.
- Solid-state aviation certification pathway:Silicon-anode and ceramic electrolyte cells targeting 400 Wh/kg energy density are progressing through FAA testing protocols for electric regional aircraft propulsion.
- Behind-the-meter C&I aggregation:Virtual power plant software platforms are enrolling commercial and industrial battery assets into wholesale capacity markets, monetizing distributed flexibility.
Industry Challenges
- Electrolyte formulator talent scarcity:PhD-level expertise in non-flammable ionic liquid and polymer gel chemistries is concentrated among a handful of Japanese and Korean research institutes.
- Grid interconnection queue congestion:FERC Order 2023 implementation timelines vary by regional transmission organization, extending project energization schedules and carrying cost exposure.
- Second-life valuation uncertainty:Automotive pack repurposing for stationary applications lacks standardized state-of-health testing protocols, complicating residual value accounting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Energy Storage Systems Market |
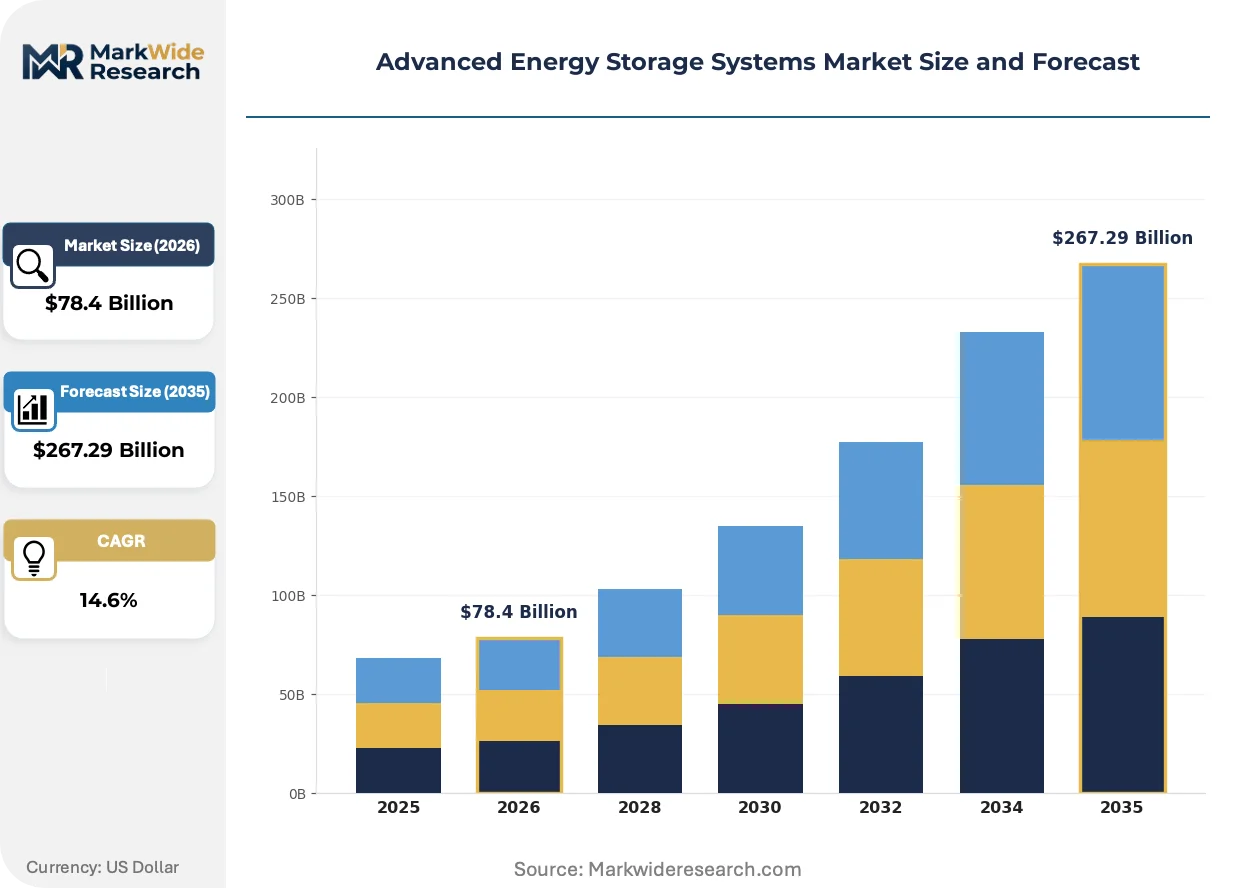
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $267.29 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion Batteries, Flow Batteries, Sodium-Sulfur Batteries, Supercapacitors, Thermal Storage Technology: Pumped Hydro, Compressed Air Energy Storage, Flywheel Storage, Solid-State Batteries, Hydrogen Storage Application: Grid Stabilization, Renewable Integration, Peak Shaving, Backup Power, Frequency Regulation End User: Utility Companies, Microgrid Operators, Telecommunications Providers, Data Centers, Commercial Facilities |
| Companies Covered | BYD, Siemens, Tesla, ABB, Panasonic, LG Energy Solution, General Electric, Fluence, Samsung SDI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Energy Storage Systems Market Strategic Shifts & Innovations
Digital twin architectures and physics-informed machine learning are compressing battery management system development cycles while regulatory pressure on fluorinated electrolytes accelerates alternative chemistry qualification.
Solid-state battery manufacturing is virtualizing conventional cell assembly by eliminating liquid electrolyte filling and formation cycling steps. Automotive OEMs in Germany and Japan are qualifying pilot lines for 2026 production ramps. This process compression is collapsing the capital intensity gap between solid-state and incumbent lithium-ion gigafactories.
China's MIIT and NMPA are enforcing updated GB 38031 cell safety standards with mandatory thermal runaway propagation testing and recycling chain-of-custody documentation. Domestic manufacturers are absorbing compliance costs through captive smelter investments. Export-oriented suppliers face certification timeline extensions as third-party labs in Europe and North America build GB testing capability.
Merchant storage developers are unbundling long-term service agreements from hardware procurement, selecting battery management software and predictive analytics providers separately from cell and pack vendors. Texas ERCOT and California CAISO markets exhibit the most advanced disaggregation. This purchasing fragmentation is forcing hardware OEMs to open application programming interfaces or cede margin to specialized software vendors.
Advanced Energy Storage Systems Market Segmentation
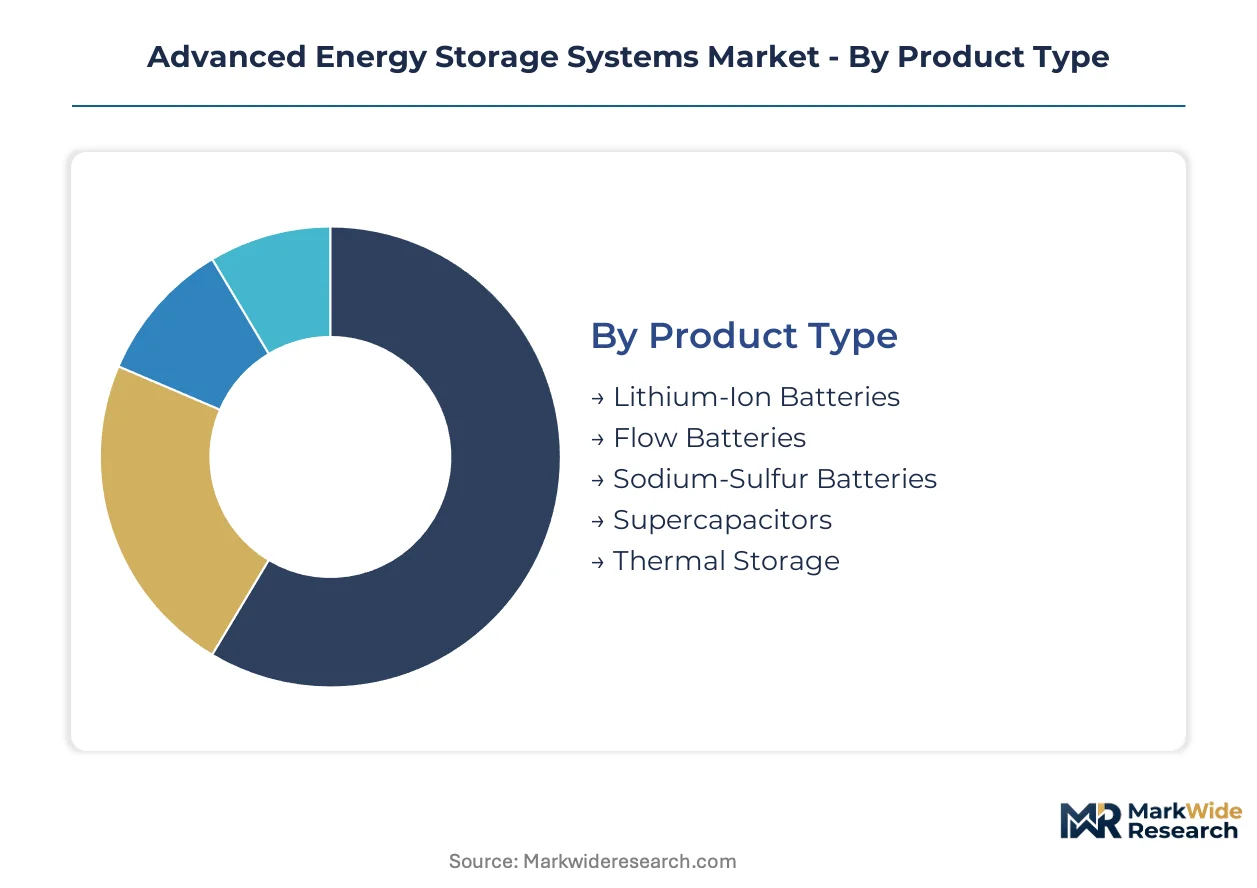
Segmentation in advanced energy storage systems reveals divergent service intensity requirements across electrochemical and mechanical technologies. Product architecture determines maintenance protocols, replacement cycles, and software update dependencies that reshape vendor-customer relationships over asset lifespans.
Product Type:
After-sales-service intensity varies sharply across electrochemical chemistries, with liquid electrolyte systems demanding periodic thermal management calibration and solid-state architectures requiring minimal field intervention.
- Lithium-Ion Batteries:Nickel-cobalt-aluminum and lithium-iron-phosphate cells dominate procurement volumes due to manufacturing scale and declining pack costs. Data center operators in Virginia and Texas are aggregating multi-gigawatt-hour portfolios to manage renewable power purchase agreement intermittency, driving demand for 10-20 year performance warranties with guaranteed degradation curves.
- Flow Batteries:Vanadium and iron-chromium redox systems separate power and energy scaling through external electrolyte tanks, enabling 6-12 hour discharge durations where lithium-ion degradation accelerates. Utility procurement in California and Germany favors these systems for daily cycling regimes requiring 20,000+ cycle lifespans without capacity fade.
- Sodium-Sulfur Batteries:High-temperature ceramic electrolyte cells operate at 300°C, demanding specialized thermal insulation maintenance and limiting deployment to grid-scale applications with dedicated operations teams.
- Supercapacitors:Electric double-layer and pseudocapacitor devices deliver sub-second response times for frequency regulation markets, with minimal degradation but energy density constraints restricting use to power-quality applications.
- Thermal Storage:Molten salt and phase-change materials capture excess renewable generation for dispatchable heat-to-power conversion, requiring periodic heat exchanger inspection and corrosion monitoring.
By volume, Lithium-Ion Batteries leads. By growth pace, Flow Batteries is ahead.
Technology:
Capital intensity and site-specific geology dictate geographic clustering, with gravity-based systems concentrating in mountainous terrain and electrochemical manufacturing scaling near raw material refining hubs.
- Pumped Hydro:Reversible turbine-generator pairs exploit elevation differentials to store 6-20 GWh per installation, with 80-85% round-trip efficiency. Swiss and Austrian alpine reservoirs anchor European long-duration capacity, while Chinese state-owned developers dominate new construction in Yunnan and Sichuan provinces.
- Compressed Air Energy Storage:Adiabatic and diabatic configurations utilize underground salt caverns or depleted gas fields, with German KBA certification protocols governing pressure vessel safety for grid-connected installations.
- Flywheel Storage:Carbon-fiber composite rotors suspended in magnetic bearings deliver 15-minute discharge for frequency regulation, with minimal maintenance but high specific cost limiting deployment to transmission-stabilization applications.
- Solid-State Batteries:Ceramic and sulfide electrolyte cells eliminate flammable liquid components, with FAA testing protocols governing aviation propulsion applications and German automotive OEMs qualifying pilot production lines.
- Hydrogen Storage:Electrolyzer-fuel cell combinations convert electricity to molecular hydrogen for seasonal storage, with EU Green Deal carbon intensity thresholds reshaping electrolyzer procurement toward renewable-powered alkaline and PEM systems.
Pumped Hydro retains the largest installed base. Solid-State Batteries shows the steepest expansion trajectory.
Application:
Revenue model differentiation separates merchant-exposed applications from regulated cost-recovery mechanisms, with arbitrage-heavy segments demanding predictive dispatch algorithms and capacity-market segments prioritizing availability guarantees.
- Grid Stabilization:Inverter-based battery resources provide synthetic inertia and voltage support as synchronous generation retires. ERCOT and CAISO market designs compensate fast frequency response, with Texas developers capturing premium pricing during thermal plant outage events.
- Renewable Integration:Co-located storage smooths photovoltaic and wind output ramps, enabling firm power delivery under long-term purchase agreements. Indian CEA mandates require storage pairing for new solar and wind tenders, aggregating 50 GWh of procurement through 2030.
- Peak Shaving:Behind-the-meter commercial installations reduce demand charges through predictive load forecasting, with virtual power plant platforms enrolling aggregated assets into wholesale capacity markets.
- Backup Power:Uninterruptible supply for critical infrastructure maintains operations during grid disturbances, with telecommunications providers specifying 8-72 hour autonomy for rural cell tower resilience.
- Frequency Regulation:Sub-second response markets reward accurate capacity bidding, with automated generation control signals dispatching battery resources against area control error signals.
Renewable Integration commands the largest share of new capital deployment. Grid Stabilization is climbing the fastest as synchronous generation retirements accelerate.
End User:
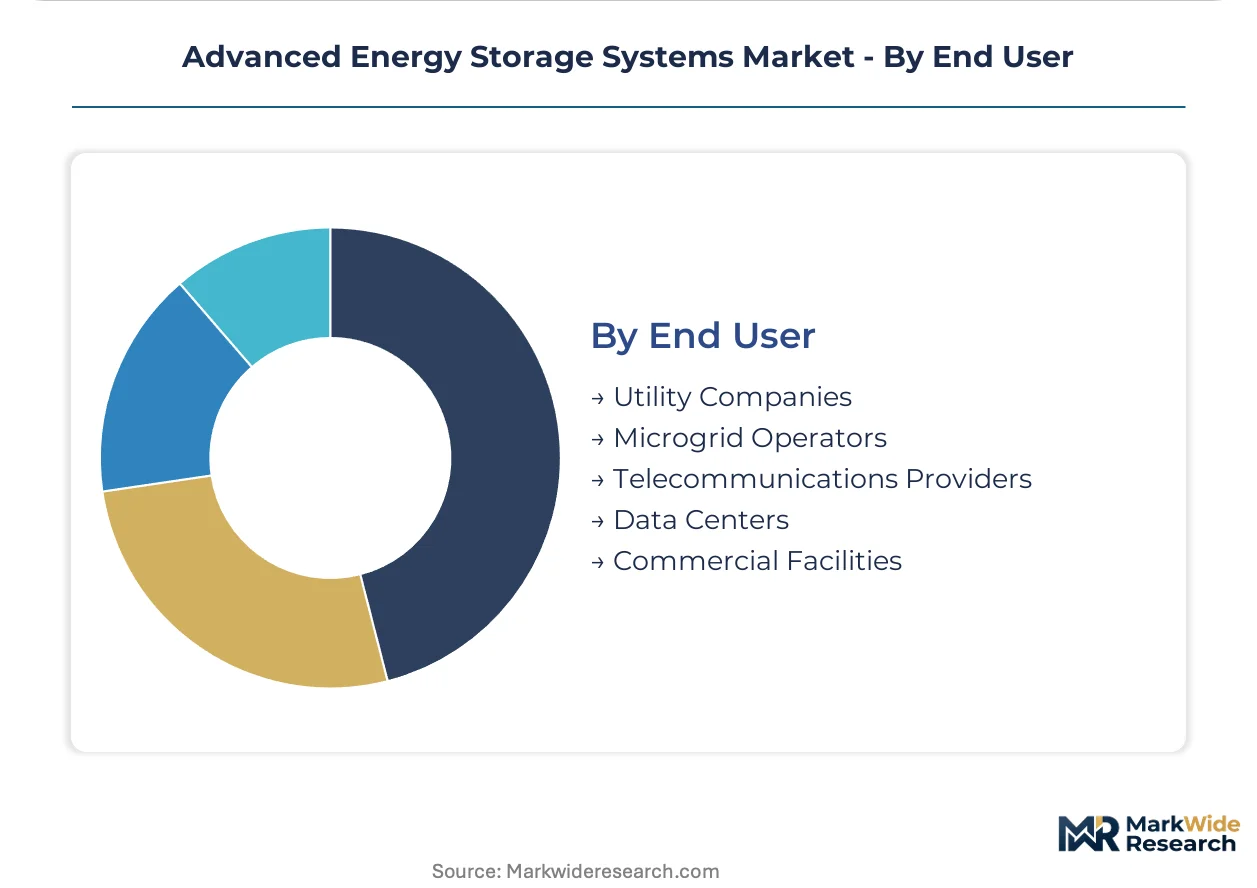
Procurement sophistication spans regulated utilities with integrated resource planning processes to commercial facilities seeking turnkey energy-as-a-service contracts without internal engineering capabilities.
- Utility Companies:Vertically integrated and independent power producers issue multi-gigawatt-hour tenders with 15-25 year contract durations. US IRA production tax credits redirect procurement toward domestic content-compliant vendors, while Chinese state-owned utilities anchor demand through central planning mechanisms.
- Microgrid Operators:Islanded and grid-connected distributed systems prioritize black-start capability and seamless transition between operating modes, with military and campus applications demanding cyber-secure control architectures.
- Telecommunications Providers:Tower operators in India and Southeast Asia specify lithium-ion and sodium-ion systems for diesel displacement, with TRAI mandates accelerating renewable-plus-storage hybridization for rural connectivity.
- Data Centers:Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth aggregate storage portfolios exceeding 10 GWh to meet 24/7 carbon-free energy commitments and manage interconnection queue delays.
- Commercial Facilities:Retail and industrial load centers procure behind-the-meter systems through third-party ownership models, with energy savings performance contracts transferring operational risk to specialized developers.
Utility Companies account for the greatest procurement volume. Data Centers are gaining share fastest as AI training load expansion outpaces transmission infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific DC Interconnector and expanding HVDC corridors across the American Southwest underwrite the United States' central role in grid-scale storage deployment. German pumped hydro reservoirs anchor European long-duration capacity. Chinese ultra-high-voltage transmission networks enable western renewable basins to serve eastern load centers.
United States
Virginia data center clusters and Texas ERCOT merchant markets drive multi-gigawatt-hour procurement. FERC Order 2023 interconnection reforms and IRA production tax credits redirect manufacturing investment toward domestic supply chains. Arizona and Nevada desert solar-plus-storage installations concentrate developer engineering resources.
China
Qinghai and Gansu renewable bases require massive co-located storage for UHVDC transmission stability. MIIT GB 38031 safety standards and dual carbon mandates enforce domestic cell certification and recycling accountability. Yangtze River Delta cathode precursor refiners control conversion capacity for regional battery manufacturers.
Germany
Industrial load centers in North Rhine-Westphalia and Bavaria procure behind-the-meter systems for peak shaving and frequency regulation. KBA pressure vessel certification governs compressed air installations in salt caverns. EU Green Deal carbon border adjustments reshape electrolyzer procurement toward renewable-powered systems.
India
Gujarat and Rajasthan solar parks mandate storage pairing under CEA guidelines aggregating 50 GWh through 2030. PLI scheme incentives attract cell and pack assembly localization. Telangana and Andhra Pradesh grid-scale tenders concentrate developer consortium activity.
Australia
South Australian renewable penetration exceeds 60%, requiring synchronous condenser replacement and grid-forming inverter deployment. AEMO market reforms enable merchant storage participation in frequency control ancillary services. Queensland and New South Wales coal retirement timelines accelerate utility procurement pipelines.
Advanced Energy Storage Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in cell chemistry and power electronics. The vendor base stratifies across three tiers: captive automotive spin-offs with integrated manufacturing, independent system integrators with software-defined dispatch platforms, and pure-play cell manufacturers exposed to commodity margin compression. Dominant competitive moves include backward integration into cathode precursor refining and geographic expansion through joint ventures with regional developers.
Within the automotive-captive tier, BYD and LG Energy Solution exemplify vertical manufacturing control from raw material refining through pack assembly. Tesla occupies a position as a platform integrator competing on algorithmic dispatch optimization rather than pure hardware cost. Among independent system specialists, Fluence represents the software-first archetype unbundling long-term service agreements from hardware procurement.
| Leading Market Players |
|---|
| BYD |
| Siemens |
| Tesla |
| ABB |
| Panasonic |
| LG Energy Solution |
| General Electric |
| Fluence |
| Samsung SDI |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta cathode precursor refiners anchor global lithium-ion cell economics, concentrating conversion capacity for nickel-manganese-cobalt hydroxide within a 200-kilometer radius that feeds pricing power upstream to Chinese material suppliers and compresses margins for Western pack assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with UL-certified utility-scale systems commanding 15-20% premiums over CE-marked commercial equivalents and uncertified economy packs serving price-sensitive behind-the-meter segments. Price differentiation rests on guaranteed degradation curves and 15-year performance warranties versus bare hardware supply. Cost compression in standard-tier lithium-iron-phosphate systems is intensifying because Argentine brine supply disruptions transmit directly to carbonate spot markets. Data center operators exhibit lowest price sensitivity due to 24/7 carbon-free energy commitments, while Indian telecom tower operators face acute budget constraints under diesel displacement mandates.
Supply Chain Analysis
US export controls on semiconductor manufacturing equipment and Chinese dual-use technology restrictions limit flow of precision coating and formation cycling machinery to non-domestic gigafactories. Geographic supply concentrates in China, South Korea, and Japan, with Yangtze River Delta cathode refiners, Gwangju cell assembly clusters, and Osaka electrolyte formulators anchoring capacity. Raw material dependencies span Chilean and Australian spodumene, Indonesian nickel laterite, and DRC cobalt hydroxide. Single-source vulnerability in Chinese NMC precursor conversion creates chokepoint exposure for Western battery manufacturers. Distribution runs through long-term offtake agreements with utility developers and hyperscale data center operators, bypassing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through mandatory GB 38031 thermal runaway testing and IRA domestic content bonuses constructs defensive moats for certified suppliers, as switching costs for utility offtakers escalate with 15-year warranty interdependencies and grid interconnection queue positions.
For Market Incumbents: Pre-empt solid-state aviation certification pathways by securing FAA testing protocol partnerships before ceramic electrolyte manufacturing matures, while accelerating backward integration into Indonesian nickel refining to offset cathode precursor concentration risk. Defensive patent clustering around non-flammable ionic liquid electrolyte formulations blocks emerging Korean and Japanese research institute spinouts from gaining traction in grid-scale safety-critical applications. For New Entrants and Emerging Players: India's Telangana and Andhra Pradesh grid-scale tender pipeline offers the most penetrable white-space target, as PLI scheme incentives lower localization barriers and CEA mandates aggregate 50 GWh of procurement through 2030. Iron-chromium flow battery technology presents a second entry vector, as 6-12 hour duration economics favor aqueous chemistries where lithium-ion degradation accelerates. Go-to-market execution should anchor on joint venture structures with domestic EPC contractors possessing established state utility relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined dispatch platform providers unbundled from hardware procurement, as Texas ERCOT and California CAISO market designs reward algorithmic optimization with multi-year service agreements. Long-term viability across the projection horizon favors acquisition targets with captive cathode capacity and open application programming interfaces enabling third-party battery management integration. The signal to watch is FERC Order 2023 implementation velocity, as regional transmission organization queue processing speed determines project energization schedules and carrying cost exposure for merchant storage developers.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Captive Indonesian nickel refining secures supply against Chinese NMC hydroxide concentration. |
| Software-Defined Dispatch Platform Launch | Unbundled algorithmic optimization captures recurring revenue in ERCOT and CAISO markets. |
| Solid-State Aviation Certification Pathway | FAA testing protocol progression unlocks 400 Wh/kg electric regional aircraft propulsion demand. |
| India Manufacturing Localization Joint Venture | PLI scheme incentives and CEA mandates aggregate 50 GWh of grid-scale procurement. |
| Non-Fluorinated Electrolyte Qualification | EU F-Gas Regulation compliance redirects European procurement away from incumbent formulations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EIA project databases, IEA technology roadmaps, FERC interconnection filings, and MIIT GB standard documentation. Utility planning officers, independent power producer project developers, EPC contractors, and grid operators provided demand-side intelligence. Battery management system engineers, cathode precursor procurement leads, and electrolyte formulation specialists contributed supply-side perspective. Bottom-up project pipeline aggregation triangulates against top-down capacity deployment forecasts.
Forecast inputs span technology cost curves, regulatory incentive phase-out schedules, and raw material supply elasticity across the projection horizon. Segmentation dimensions include electrochemical chemistry, discharge duration tier, application revenue model, and end-user procurement sophistication. CAGRs derive from installed capacity buildout trajectories and average selling price erosion patterns. Industry-specific inputs incorporate lithium carbonate spot volatility, IRA domestic content bonus qualification thresholds, and grid interconnection queue processing rates by regional transmission organization.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, trade policy stringency, or critical mineral export restrictions would shift the trajectory. Forecasts assume continued policy support for utility-scale renewable pairing and sustained data center load expansion. Material shifts in FERC interconnection reform implementation or Chinese GB standard reciprocity recognition would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Energy Storage Market
Battery Management System
Global Power Management System Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Distributed Energy Storage System Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Battery Management Market
Battery Management System
US Energy Storage Market
Battery Management System
North America Energy Storage Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
North America Battery Management System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
Renewable Battery Storage Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
DC Coupled Solar Battery System Market