
 Advanced Energy Market | 2026-2036
Advanced Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Energy Market Analysis
Data center power architecture is broadening as hyperscale operators replace conventional diesel backup with lithium-ion battery systems and on-site solar arrays. Advanced Energy Industries leverages its precision power-conversion portfolio to serve semiconductor fabrication tools. MKS Instruments sustains its position through vacuum and power solutions tied to thin-film deposition equipment. Applied Materials anchors North American supply chains for ion implantation systems requiring stable high-voltage delivery.
Advanced energy encompasses power electronics, energy storage systems, and grid-interactive technologies designed to convert, condition, store, and distribute electricity with efficiency exceeding ninety-five percent across variable loads. These systems integrate wide-bandgap semiconductors, advanced inverters, and intelligent control software to enable bidirectional power flow and frequency regulation in industrial and utility settings. Battery Energy Storage dominates capital allocation as lithium-ion cell costs fall and four-hour duration systems displace peaker plants. Smart Grids compete for utility investment through distribution automation and real-time demand signaling that reduces line losses. Photovoltaics occupies rooftop and floating solar niches where land constraints prevent utility-scale deployment.
The US Environmental Protection Agency and Department of Energy enforce efficiency standards for grid-connected inverters and commercial battery enclosures, while the Federal Energy Regulatory Commission's Order 841 mandates market access for storage resources in wholesale electricity markets. China's Ministry of Ecology and Environment enforces dual carbon targets that compel provincial grids to procure renewable generation paired with storage. Stakeholders must monitor how interconnection queue reforms and inverter-based resource standards reshape project economics and technology selection.
Market Dynamics
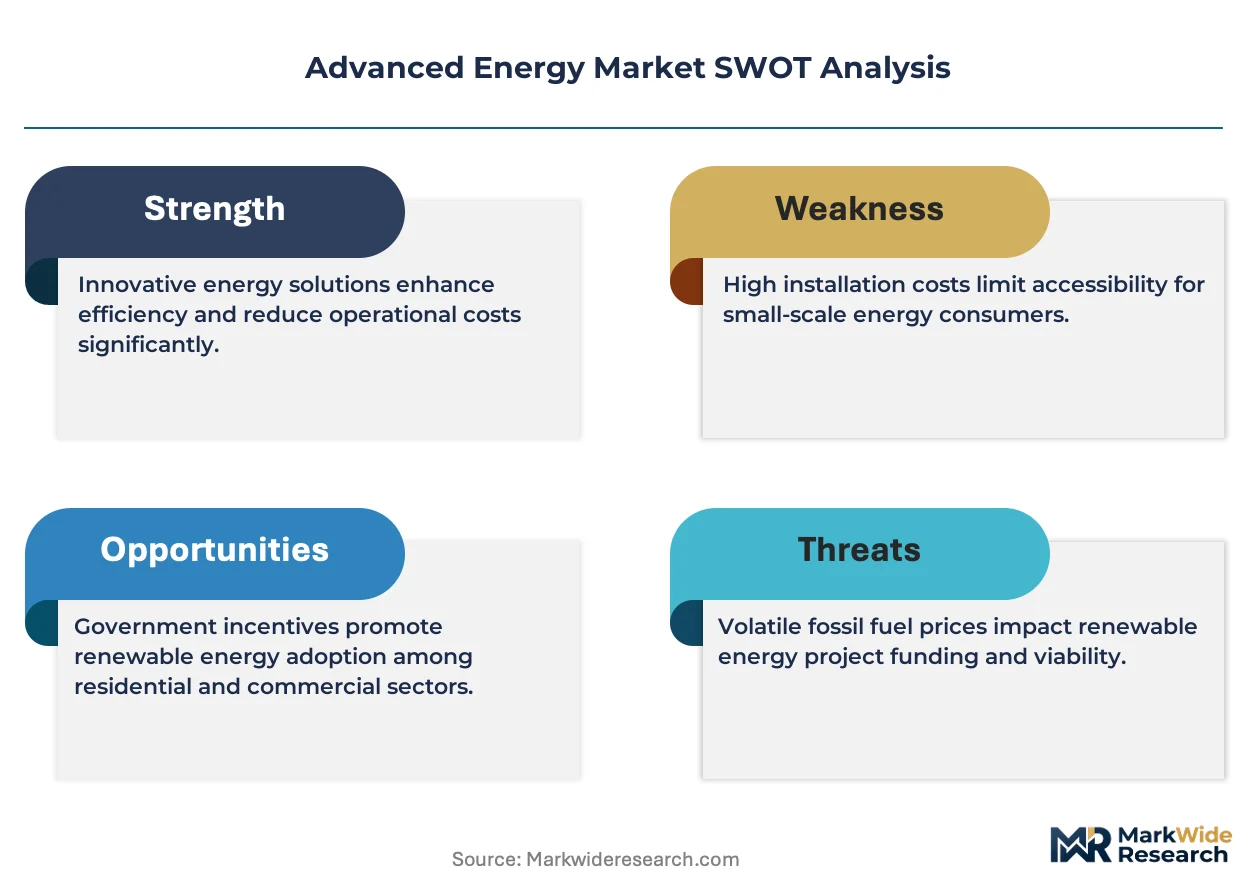
Wide-bandgap semiconductors are compressing switching losses in power electronics, forcing incumbent silicon-based inverter architectures into obsolescence while rewiring supplier qualification timelines across utility-scale procurement.
Growth Catalysts
- US Inflation Reduction Act:Clean energy tax credits accelerate domestic battery manufacturing capacity expansion and on-site renewable deployment at data center campuses.
- China dual carbon mandates:Provincial grid operators in Jiangsu and Guangdong procure gigawatt-scale storage systems to absorb variable wind and solar output.
- Silicon carbide MOSFETs:These devices enable 99% efficient power conversion in electric vehicle fast chargers and grid-tied inverters.
Market Restraints
- Lithium carbonate volatility:Battery cell costs swing with South American brine and Australian spodumene concentrate availability.
- Transformer core steel concentration:Grain-oriented electrical steel production clusters in Japan and South Korea, creating procurement bottlenecks for utility-scale inverters.
- FERC interconnection queues:Grid connection delays in US wholesale markets stretch project timelines beyond developer capital lockup periods.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing attract lithium-ion gigafactory investment.
- Vehicle-to-grid integration:Bidirectional charging hardware converges with residential battery management systems.
- Floating solar pairing:Reservoir-mounted photovoltaic arrays in Japan and South Korea combine with submerged cable conditioning systems.
Industry Challenges
- Power electronics talent scarcity:Engineers with wide-bandgap device characterization expertise command premium compensation.
- UL 9540A certification timelines:Battery energy storage system thermal runaway testing extends product launch schedules.
- Legacy SCADA integration:Grid-interactive inverters must communicate with decades-old utility control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Energy Market |
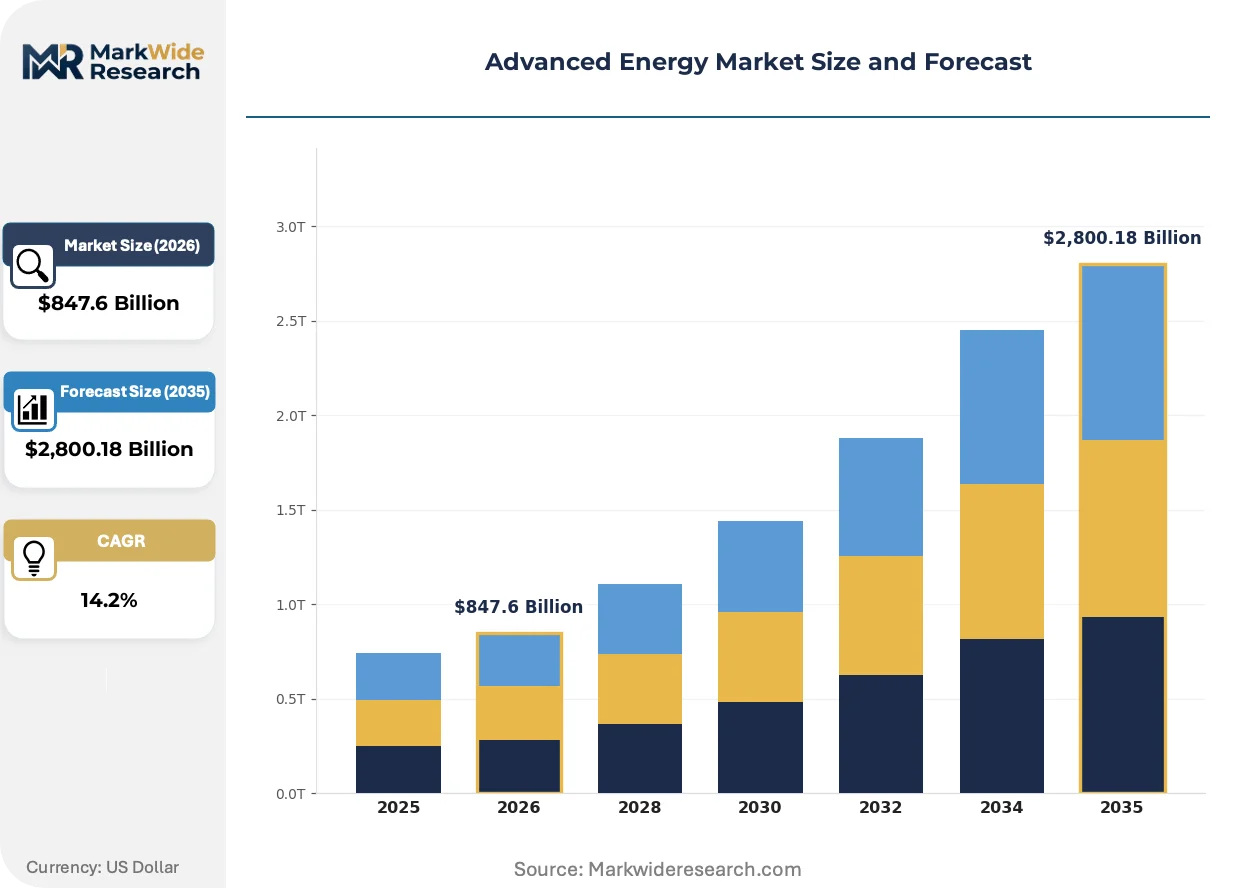
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,800.18 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Energy Storage, Demand Response, Renewable Generation, Grid Management Technology: Battery Energy Storage, Smart Grids, Photovoltaics, Wind Turbines End User: Utilities, Industrial Facilities, Commercial Buildings, Residential Consumers Application: Load Balancing, Ancillary Services, Renewable Integration, Emergency Power Supply |
| Companies Covered | Advanced Energy Industries, MKS Instruments, Applied Materials, ABB Ltd., Delta Electronics, Lam Research, KLA, Ultra Clean Holdings, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Energy Market Emerging Trajectories
Intelligent power conversion is shifting from passive hardware to software-defined architectures that optimize energy flows in real time. This transformation spans semiconductor materials, regulatory frameworks, and procurement behaviors.
Silicon carbide and gallium nitride power devices are automating frequency regulation in grid-forming inverters. Utility-scale developers in Texas and California adopt these systems for 1500-volt DC architectures. The technology is automating the displacement of silicon IGBT modules in string inverter designs.
EU F-Gas Regulation phase-down schedules are accelerating adoption of fluorinated gas-free switchgear in offshore wind substations. Manufacturers redesign medium-voltage ring main units around vacuum interrupter technology. Offshore wind developers in the North Sea and Baltic markets now specify SF6-free equipment in procurement tenders.
Data center operators now contract directly with renewable developers for 24/7 carbon-free energy matching rather than annual renewable energy credit purchases. This behavior fragments traditional utility procurement monopolies. The shift is most visible in Northern Virginia and Frankfurt cloud computing clusters.
Advanced Energy Market Segmentation
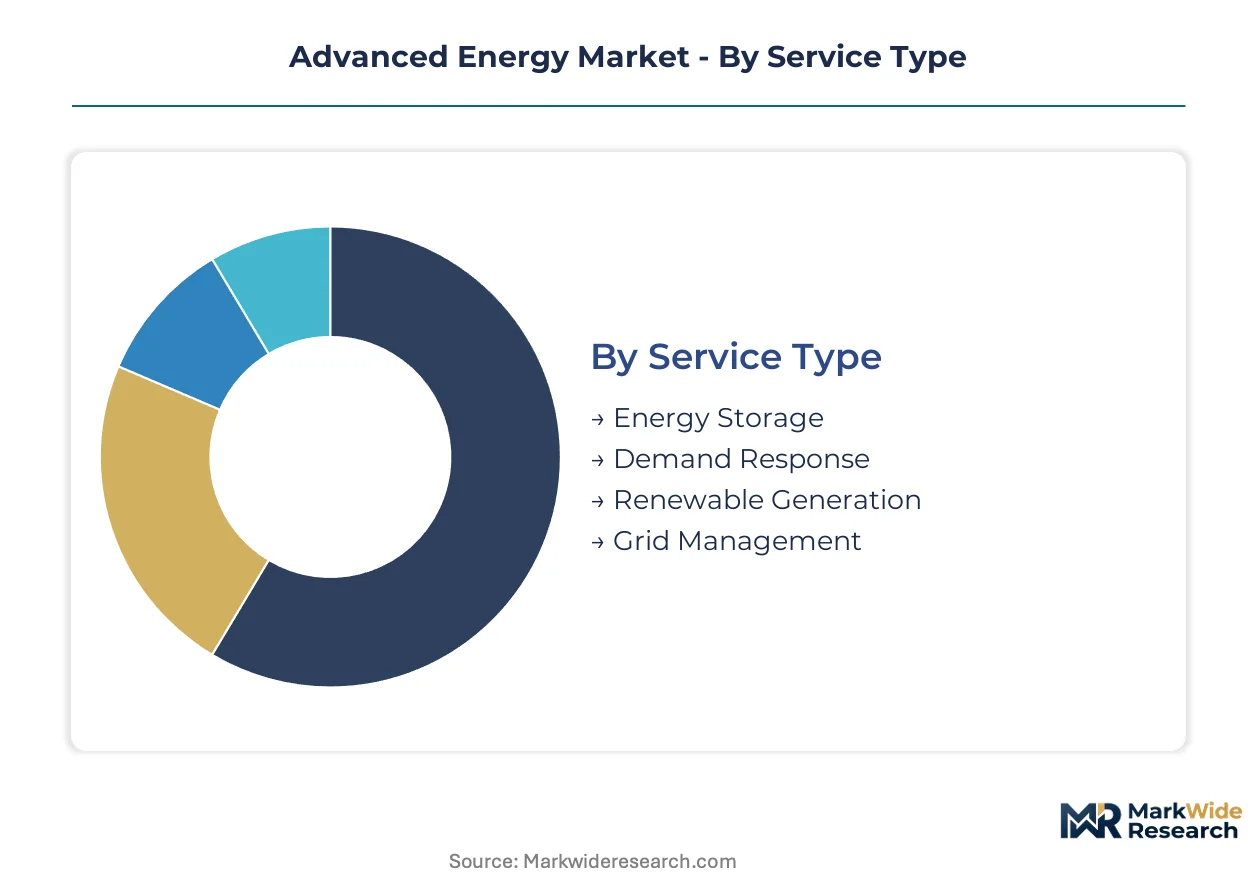
Advanced energy procurement patterns diverge sharply across buyer sophistication, technical requirements, and capital intensity. Segment boundaries determine vendor qualification criteria, contract structures, and technology roadmaps for power conversion equipment.
Service Type:
Capital allocation separates buyers pursuing asset ownership from those contracting for operational outcomes.
- Energy Storage:Four-hour lithium-ion systems displace natural gas peakers in wholesale markets. Procurement concentrates in Texas and California ISOs where FERC Order 841 enables merchant revenue stacking.
- Demand Response:Aggregated load curtailment contracts provide frequency regulation reserves. Industrial facilities in Germany's balancing market capture capacity payments through automated demand-side platforms.
- Renewable Generation:Utility-scale solar and wind paired with storage dominates corporate power purchase agreements.
- Grid Management:Distribution automation software reduces line losses through real-time voltage optimization.
Volume sits with Energy Storage; growth tilts toward Demand Response.
Technology:
Technology selection tracks efficiency thresholds and semiconductor material transitions.
- Battery Energy Storage:Lithium iron phosphate cells dominate four-hour duration systems for grid-scale deployment. Chinese cell manufacturers supply Jiangsu and Guangdong provincial grids under dual carbon procurement mandates.
- Smart Grids:Distribution management systems integrate distributed energy resources through IEC 61850 protocols. European utilities deploy these platforms to manage prosumers under EU Green Deal electrification targets.
- Photovoltaics:Heterojunction modules gain share in rooftop applications where space constraints favor high efficiency.
- Wind Turbines:Direct-drive permanent magnet generators reduce gearbox maintenance in offshore installations.
Deployment volume clusters around Battery Energy Storage; technology substitution accelerates fastest in Smart Grids.
End User:
Buyer scale determines control system complexity and financing structures.
- Utilities:Transmission operators procure gigawatt-scale storage for resource adequacy. Procurement in India targets frequency regulation under CEA technical standards for grid-connected systems.
- Industrial Facilities:C&I buyers contract behind-the-meter solar-plus-storage for peak demand charge management. Heavy manufacturing in South Korea deploys these systems to manage volatile industrial electricity tariffs.
- Commercial Buildings:Property managers install rooftop solar with smart inverters for net metering optimization.
- Residential Consumers:Home battery systems pair with solar for backup power during grid outages.
Capital deployment concentrates with Utilities; adoption expands most quickly among Industrial Facilities.
Application:
Revenue model differentiation shapes hardware specifications and software requirements.
- Load Balancing:Battery systems shift renewable generation across daily demand curves. Texas ERCOT market participants arbitrage real-time price volatility through automated dispatch.
- Ancillary Services:Fast frequency response contracts require sub-second reaction times. Grid-forming inverters with silicon carbide power stages meet these specifications in California ISO markets.
- Renewable Integration:Storage absorbs variable wind and solar output to smooth ramp rates.
- Emergency Power Supply:Diesel replacement drives lithium-ion adoption in critical facility backup.
Contract volume aggregates in Load Balancing; revenue per megawatt-hour climbs fastest in Ancillary Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment tax credit zones in the United States concentrate advanced energy manufacturing, while China's dual carbon procurement zones and India's production-linked incentive corridors reshape regional deployment patterns across power electronics and storage systems.
United States
Data center operators in Northern Virginia and Texas deploy gigawatt-scale battery storage paired with on-site solar under IRA clean energy tax credits. FERC Order 841 mandates wholesale market access for storage resources, accelerating merchant revenue stacking in ERCOT and CAISO territories. Arizona and Nevada host lithium-ion gigafactory clusters serving western grid interconnection queues.
China
Provincial grid operators in Jiangsu and Guangdong procure four-hour duration storage systems to absorb variable wind and solar output. The Ministry of Ecology and Environment enforces dual carbon targets compelling renewable-plus-storage procurement mandates. Yangtze River Delta manufacturing corridors supply silicon carbide power devices for domestic inverter production.
Germany
Industrial facilities in North Rhine-Westphalia contract behind-the-meter solar-plus-storage systems for peak demand charge management under EU Green Deal electrification targets. The F-Gas Regulation phase-down accelerates SF6-free switchgear adoption in offshore wind substations. Bavaria hosts vacuum interrupter manufacturing for medium-voltage ring main units.
India
State transmission utilities in Maharashtra and Gujarat procure grid-connected battery systems for frequency regulation under CEA technical standards. The PLI scheme for advanced chemistry cell manufacturing attracts lithium-ion gigafactory investment. Tamil Nadu solar manufacturing clusters integrate with domestic inverter assembly lines.
Japan
Reservoir-mounted floating solar arrays in Hyogo and Chiba prefectures pair with submerged cable conditioning systems under METI renewable deployment schedules. JIS standards govern grid-interactive inverter certification timelines. Osaka industrial zones manufacture wide-bandgap semiconductor test equipment for power electronics qualification.
Advanced Energy Market Vendor Landscape
Top-tier vendors anchor precision power conversion for semiconductor fabrication, while mid-tier specialists occupy grid-tied inverter and battery management niches. The vendor base stratifies across three archetypes: integrated power electronics conglomerates, vacuum and deposition equipment specialists, and pure-play energy storage system integrators. Dominant competitive moves include backward integration into wide-bandgap semiconductor sourcing and geographic expansion into IRA-eligible manufacturing zones.
Within the precision power conversion tier, Advanced Energy Industries, MKS Instruments, and Applied Materials exemplify equipment suppliers tethered to semiconductor capital expenditure cycles. These firms occupy positions where power conditioning specifications for ion implantation and thin-film deposition tools determine procurement decisions. ABB Ltd., Delta Electronics, and Siemens Energy represent the grid infrastructure archetype, anchoring utility-scale inverter and switchgear markets where FERC interconnection standards and EU F-Gas regulations reshape qualification requirements. Lam Research, KLA, and Ultra Clean Holdings sit within the semiconductor equipment ecosystem, serving fabs where stable high-voltage delivery enables advanced node production.
| Leading Market Players |
|---|
| Advanced Energy Industries |
| MKS Instruments |
| Applied Materials |
| ABB Ltd. |
| Delta Electronics |
| Lam Research |
| KLA |
| Ultra Clean Holdings |
| Siemens Energy |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate futures on the Shanghai Futures Exchange cascade through battery cell procurement contracts into three distinct pricing tiers for utility-scale storage systems. Chinese provincial grid operators absorb premium pricing for expedited delivery under dual carbon mandates, while merchant developers in Texas ERCOT markets negotiate spot-indexed contracts tied to South American brine availability.
Pricing Analysis
Lead-time-driven pricing compresses margins for standard delivery windows while commanding 15-20% premiums for sub-quarter fulfillment. Three-tier pricing structure across premium, standard, and economy levels reflects UL 9540A certification status and silicon carbide power stage integration. Cost compression in economy-tier string inverters is intensifying because Chinese manufacturers are flooding wholesale channels with uncertified equipment. Industrial facilities in South Korea exhibit highest price sensitivity due to volatile electricity tariffs, while semiconductor fabs demonstrate lowest sensitivity given power conditioning specifications dominate procurement decisions.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean producers of grain-oriented electrical steel for transformer cores. Manufacturing concentrates in China for lithium-ion cells, Japan for wide-bandgap semiconductor test equipment, and Germany for vacuum interrupter assemblies. Raw material dependencies span lithium brine from Chilean salars, silicon carbide substrates from US wafer fabs, and rare earth magnets from Chinese separation facilities. Tariff exposure on Chinese battery components threatens project economics for US developers relying on IRA domestic content bonuses. Distribution runs through vertically integrated EPC contractors who bundle hardware procurement with interconnection queue management services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers with captive wide-bandgap semiconductor sourcing as silicon carbide MOSFET shortages force qualified second-tier inverter manufacturers into distressed asset sales.
For Market Incumbents: Extend qualification timelines for new wide-bandgap device suppliers to lock in silicon carbide MOSFET allocation before automotive demand absorbs available wafer capacity. Backward integration into Japanese electrical steel procurement hedges against transformer core bottlenecks threatening utility-scale inverter delivery schedules. For New Entrants and Emerging Players: Begin with vehicle-to-grid bidirectional charging hardware where residential battery management system integration creates lower certification barriers than utility-scale markets. Target India's PLI scheme corridors for advanced chemistry cell manufacturing where domestic content requirements exclude established Chinese suppliers from government procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier inverter assemblers in Arizona and Nevada IRA-eligible zones where interconnection queue delays have frozen project finance draws. Watch FERC Order 841 implementation variance across ISO territories as the signal indicating which regional markets will absorb stranded merchant storage capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wide-Bandgap Sourcing | Captive silicon carbide MOSFET supply secures qualification timelines for grid-forming inverters in California ISO markets. |
| Power Purchase Agreement Structuring | 24/7 carbon-free energy matching contracts with data center operators fragment traditional utility procurement monopolies in Northern Virginia. |
| SF6-Free Switchgear Certification | Vacuum interrupter technology qualification under EU F-Gas Regulation opens North Sea offshore wind substation tenders. |
| Vehicle-to-Grid Hardware Development | Bidirectional charging integration with residential battery management systems converges automotive and stationary storage supply chains. |
| Floating Solar Pairing Systems | Submerged cable conditioning technology for reservoir-mounted photovoltaic arrays accesses land-constrained Japanese and South Korean markets. |
Methodological Framework
Document review covered FERC interconnection queue databases, EIA power plant construction tracking, and IEA grid integration reports, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork validated secondary findings through structured discussions on procurement timelines, inverter qualification protocols, and merchant revenue stacking strategies. Bottom-up project-level capacity aggregation triangulated against top-down manufacturer shipment disclosures.
Segmented outputs reflect technology substitution curves, regulatory framework variations, and regional grid type differences across the projection horizon. The analytical framework models battery energy storage, smart grid deployment, and renewable integration trajectories through capacity-based and revenue-based approaches. CAGRs derive from weighted average of utility procurement pipelines, corporate PPA disclosure trends, and manufacturing capacity expansion announcements. Key inputs include lithium-ion cell cost curves, wide-bandgap semiconductor adoption rates, and interconnection queue clearance velocities.
Commodity price volatility, interconnection reform implementation delays, and inverter-based resource standard revisions are the dominant revision risks to modeled forecasts. Deviation in FERC Order 841 compliance timelines across ISO territories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Nanotechnology in Energy Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Global Microreactor Technology Market