
 Hydrogen Composite Tanks Market | 2026-2036
Hydrogen Composite Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Composite Tanks Market Insights
Buyer concentration among heavy-duty fleet operators is hardening as logistics providers and OEMs consolidate procurement around qualified tank suppliers. Hexagon Purus leverages its Scandinavian manufacturing base to dominate European fuel cell vehicle programs. Worthington Industries anchors North American supply through its steel-composite hybrid expertise and industrial gas relationships. Luxfer Group differentiates via its aluminum-lined Type 3 designs that serve aerospace and defense contractors requiring traceable fatigue-life certification.
Hydrogen composite tanks are pressure vessels constructed from filament-wound carbon fiber over metallic or polymer liners, designed to store hydrogen at 350-700 bar for fuel cell and combustion applications. Type 4 polymer-lined composite tanks lead in lightweighting for automotive fuel cell vehicles, while Type 3 metal-lined variants retain share in aerospace and defense where permeation standards are strictest. Carbon fiber compositions command premium positioning due to raw material constraints and qualification timelines, whereas glass fiber alternatives occupy cost-sensitive portable and stationary storage segments.
Europe's F-Gas Regulation and CE marking under the EU AI Act-adjacent machinery directives shape tank certification pathways, while the EU Green Deal subsidies accelerate hydrogen refueling infrastructure deployment. The US DOT and NHTSA govern transportable tank standards, with OSHA workplace rules influencing stationary installation specifications. Stakeholders must monitor evolving ISO 19881 and IEC 62282 harmonization efforts that will determine cross-border market access and testing reciprocity.
Market Dynamics
Fleet operators in heavy-duty trucking are consolidating procurement around qualified tank suppliers, compressing qualification timelines and reshaping supplier relationships across the hydrogen storage value chain.
Growth Catalysts
- EU Green Deal subsidies:Hydrogen refueling infrastructure deployment receives direct capital support across member states, accelerating corridor buildout along major freight routes.
- Type 4 polymer-lined designs:Carbon fiber winding automation reduces unit weight for automotive fuel cell vehicles, enabling extended range without payload sacrifice.
- Germany's hydrogen mobility corridors:Automotive OEMs and energy utilities co-invest in high-pressure storage networks connecting industrial clusters to transport nodes.
Market Restraints
- Carbon fiber supply concentration:Precursor production clusters in Japan and the United States create input bottlenecks for tank manufacturers outside these geographies.
- CE marking complexity:Machinery directives adjacent to the EU AI Act extend certification timelines for novel tank designs entering European markets.
- Compressed natural gas substitution:Mature CNG infrastructure and lower conversion costs divert fleet investment from hydrogen systems in cost-sensitive operator segments.
Strategic Opportunities
- India's PLI scheme for clean hydrogen:Production-linked incentives for electrolyzer and storage manufacturing attract tank suppliers to establish local assembly.
- Aerospace fatigue-life certification:Aluminum-lined Type 3 designs with traceable cycle data open defense and satellite propulsion applications.
- ISO 19881 harmonization:Reciprocal testing standards across jurisdictions reduce redundant qualification costs for multi-market tank suppliers.
Industry Challenges
- Filament winding technician scarcity:Specialized composite manufacturing skills outpace vocational training output in established production regions.
- 700-bar validation protocols:Extended pressure cycle testing for automotive certification compresses product launch timelines and ties up capital equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Composite Tanks Market |
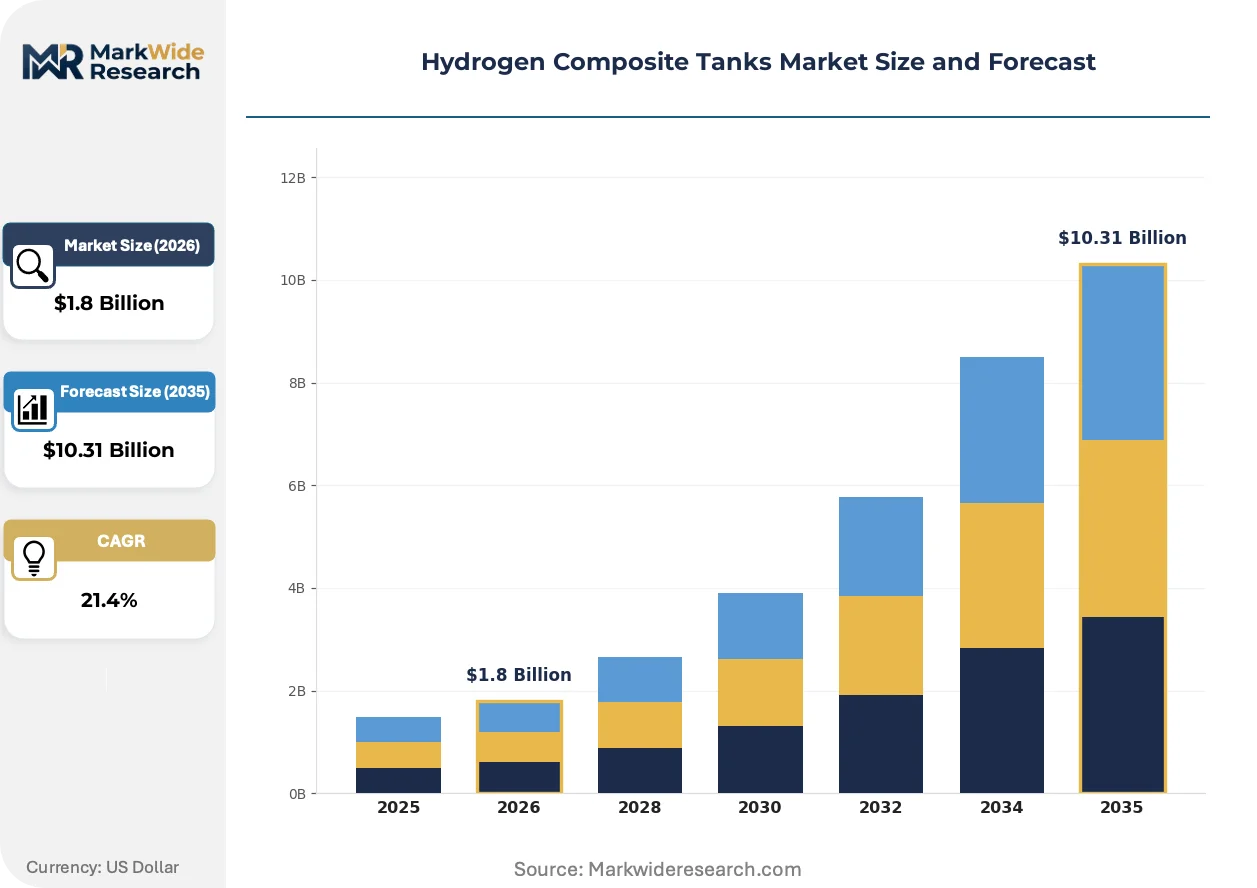
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $10.31 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tank Type: Type 1 All-Metal Tanks, Type 2 Hoop-Wrapped Tanks, Type 3 Metal-Lined Composite Tanks, Type 4 Polymer-Lined Composite Tanks, Type 5 Linerless Composite Tanks Application: Fuel Cell Vehicles, Aerospace, Portable Storage, Stationary Storage, Industrial Gas Storage Material Composition: Carbon Fiber, Glass Fiber, Aramid Fiber, Metallic Liner, Polymer Liner End User: OEMs, Research Institutions, Energy & Power Enterprises, Logistics Providers, Defense Contractors |
| Companies Covered | Hexagon Purus, Worthington Industries, Luxfer Group, Quantum Fuel Systems LLC, Faber Industrie S.p.A., NPROXX, Composite Advanced Technologies, LLC, Everest Kanto Cylinder Ltd., Steelhead Composites, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Composite Tanks Market Trends and Innovations
Automation in carbon fiber placement and real-time quality monitoring is compressing production cycles while tightening performance tolerances for high-pressure hydrogen containment systems.
Robotic fiber placement systems are automating the precision winding of carbon layers over polymer liners, replacing manual layup in tank manufacturing cells. Tier 1 automotive suppliers are adopting these systems at pilot scale in Germany and South Korea. The technology is automating throughput scaling without proportional labor expansion, reducing unit cost curves for Type 4 tank production.
Europe's F-Gas Regulation tightens fluorinated gas containment standards that indirectly elevate hydrogen system integrity requirements for shared infrastructure. Industrial gas distributors must retrofit monitoring and leak-detection protocols across shared storage facilities. The regulation most affects multi-gas terminal operators in the Netherlands and Belgium, who are accelerating tank recertification schedules.
Long-term leasing structures for tank assets are displacing outright purchase in heavy-duty fleet procurement, transferring residual value risk to manufacturers. Logistics providers in California and Germany now contract for tank availability per kilometer rather than capital expenditure. This shift concentrates most visibly among zero-emission fleet operators facing technology obsolescence uncertainty.
Hydrogen Composite Tanks Market Segmentation
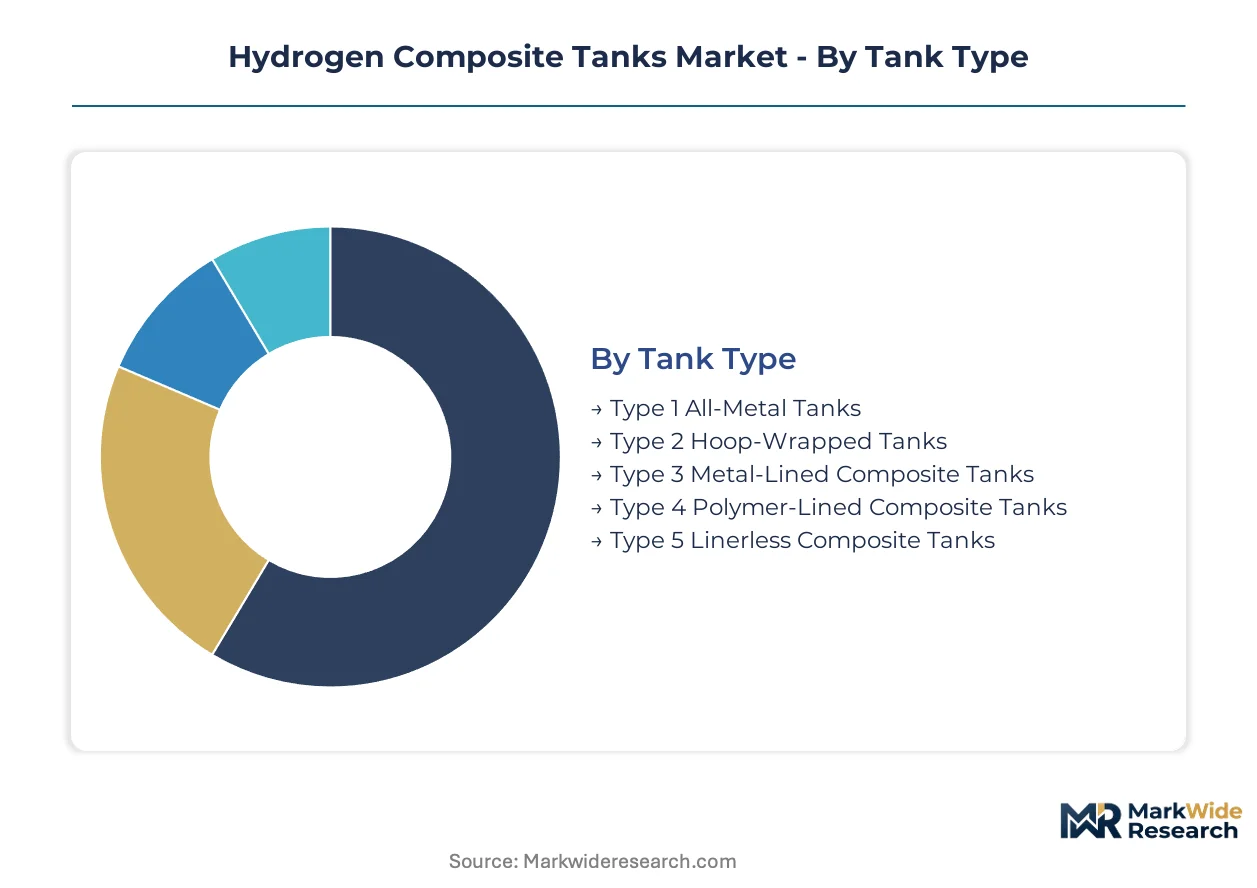
Hydrogen composite tanks serve divergent performance requirements across mobility, stationary, and aerospace applications. Segmentation reveals how pressure ratings, weight constraints, and certification standards partition demand across tank architectures and material systems.
Tank Type:
Standardization dominates low-pressure industrial storage, while customization intensity rises with pressure ratings and weight-critical applications.
- Type 4 Polymer-Lined Composite Tanks:Full carbon fiber winding over thermoplastic liners achieves 700-bar storage at 40% weight reduction versus metal alternatives. Automotive OEMs in Germany and South Korea specify Type 4 designs for fuel cell vehicle programs where range extension without payload sacrifice drives procurement. Filament winding automation is compressing production cycles for this architecture.
- Type 3 Metal-Lined Composite Tanks:Aluminum or steel liners wrapped with carbon fiber provide permeation resistance for aerospace and defense applications. Defense contractors require traceable fatigue-life certification that Type 3 architectures deliver through metallic barrier layers. KBA approval protocols in Germany favor these designs for heavy-duty trucking corridors.
- Type 1 All-Metal Tanks:Seamless steel or aluminum construction serves industrial gas bulk storage where weight is secondary to cost.
- Type 2 Hoop-Wrapped Tanks:Metal cylinders with circumferential composite reinforcement occupy mid-pressure stationary applications.
- Type 5 Linerless Composite Tanks:All-composite construction eliminates liner interfaces for extreme lightweighting in satellite propulsion systems.
Most installed capacity flows through Type 3 designs given aerospace and defense procurement longevity. Expansion is steepest in Type 4 as automotive fuel cell vehicle production scales.
Application:
Volume concentration sits with fleet operators facing regulatory deadlines, while margin concentration follows aerospace certification complexity.
- Fuel Cell Vehicles:Heavy-duty trucking fleets in California and Germany are consolidating procurement around qualified tank suppliers. EU Green Deal subsidies for hydrogen refueling infrastructure accelerate corridor deployment along major freight routes. Type 4 tanks dominate this segment due to weight-critical range requirements.
- Aerospace:Satellite propulsion and unmanned aerial systems demand traceable cycle data and fatigue-life documentation. Defense contractors specify aluminum-lined Type 3 designs with qualification timelines extending across multiple years. FAA and EASA certification reciprocity remains incomplete, fragmenting supplier access.
- Portable Storage:Glass fiber composites serve cost-sensitive mobile refueling and backup power applications.
- Stationary Storage:Industrial gas terminals in the Netherlands and Belgium retrofit shared facilities under tightened F-Gas Regulation protocols.
- Industrial Gas Storage:Mature CNG infrastructure competes for fleet investment in cost-sensitive operator segments.
Revenue gravity centers on fuel cell vehicles given fleet scale. Aerospace commands premium positioning through certification barriers.
Material Composition:
Raw material access and qualification timelines stratify supplier positioning across fiber and liner categories.
- Carbon Fiber:Toray and Hexcel precursor supply concentrates in Japan and the United States, creating input bottlenecks for tank manufacturers outside these geographies. Precursor production constraints elevate pricing and extend lead times for automotive qualification programs. PAN-based standard modulus grades dominate pressure vessel applications.
- Polymer Liner:High-density polyethylene and nylon barriers enable Type 4 weight advantages while requiring permeation testing under ISO 19881 protocols. Automotive OEMs specify liner materials compatible with 700-bar cycling and temperature extremes.
- Glass Fiber:E-glass and S-glass alternatives occupy portable and stationary storage segments where cost sensitivity outweighs weight optimization.
- Metallic Liner:Aluminum 6061-T6 and stainless steel 316L serve Type 3 architectures requiring zero permeation.
- Aramid Fiber:Kevlar and Twaron reinforcement provides impact resistance for aerospace and defense containment systems.
Carbon fiber commands the dominant share of material value. Polymer liner demand is climbing fastest as Type 4 production automates.
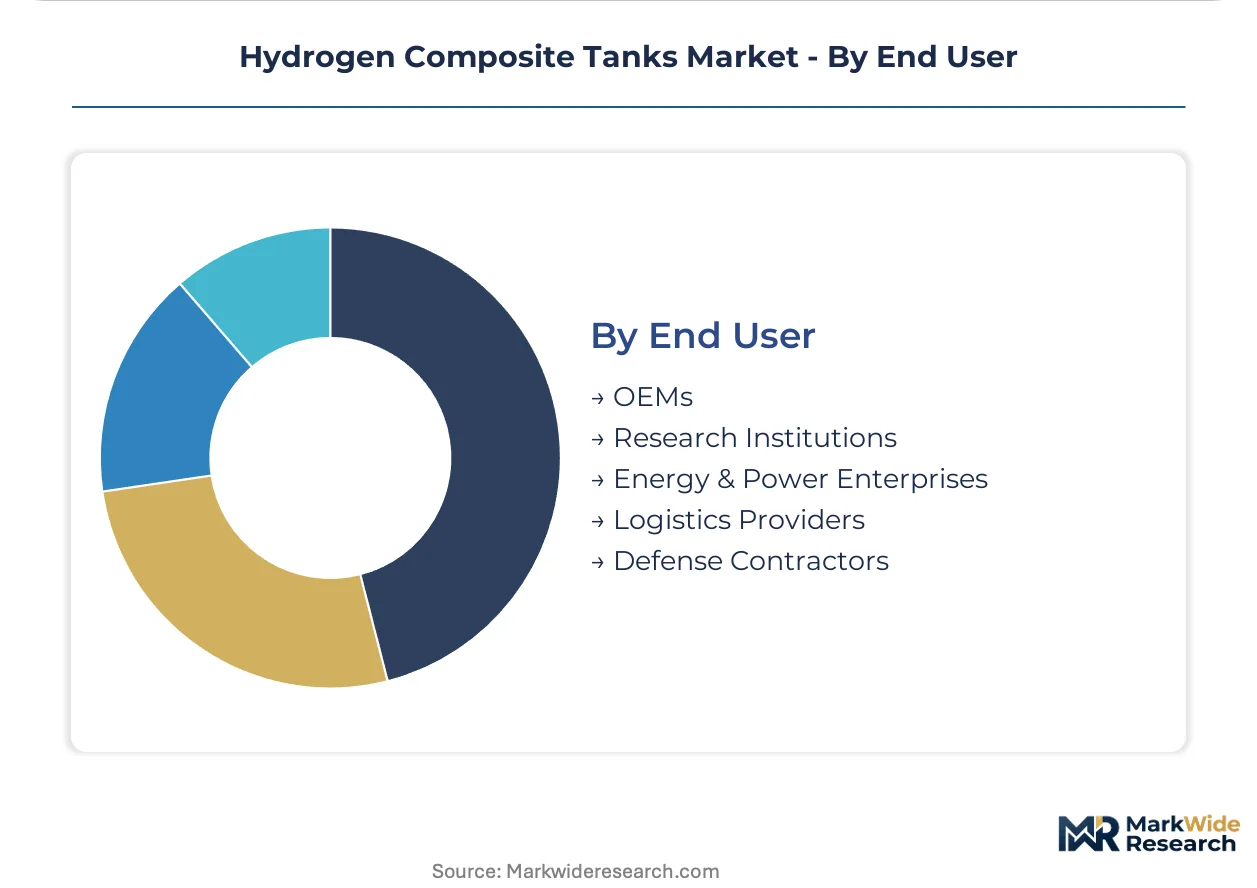
End User:
Procurement authority concentrates with OEMs integrating tanks into vehicle platforms, while research institutions shape early technology validation.
- OEMs:Automotive manufacturers in Germany co-invest with energy utilities in hydrogen mobility corridors. Tank qualification timelines compress as OEMs consolidate supplier bases around proven filament winding operations. Long-term leasing structures displace outright purchase, transferring residual value risk to manufacturers.
- Logistics Providers:Fleet operators in heavy-duty trucking scale orders for composite tank systems under California CARB and EU CO2 fleet standards. Zero-emission fleet operators contract for tank availability per kilometer rather than capital expenditure.
- Energy & Power Enterprises:Industrial gas distributors retrofit monitoring protocols under F-Gas Regulation requirements.
- Defense Contractors:Aerospace and satellite programs require traceable fatigue-life certification that extends procurement cycles.
- Research Institutions:National laboratories and university programs validate novel liner materials and winding architectures.
OEM procurement represents the largest revenue pool. Logistics provider demand is expanding most quickly as fleet conversion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hydrogen mobility corridors attract co-investment from automotive OEMs and energy utilities, while the United States anchors North American demand through California's zero-emission fleet mandates and federal hydrogen hub funding.
United States
Heavy-duty trucking fleets in California consolidate procurement around qualified tank suppliers under CARB regulations. The Department of Energy's Regional Clean Hydrogen Hubs program directs capital toward Gulf Coast and Midwest production clusters. Houston and Los Angeles emerge as primary nodes for hydrogen refueling infrastructure deployment.
Germany
Automotive OEMs and energy utilities co-invest in hydrogen mobility corridors connecting industrial clusters to transport nodes. The EU Green Deal and F-Gas Regulation tighten emissions standards while KBA approval protocols favor Type 3 tank designs for freight applications. Bavaria and North Rhine-Westphalia concentrate manufacturing capacity for high-pressure storage systems.
China
Fuel cell vehicle production scales in the Yangtze River Delta and Pearl River Delta regions under national dual carbon goals. MIIT standards govern pressure vessel certification while provincial governments subsidize hydrogen refueling station buildout. Shanghai and Guangzhou lead fleet conversion programs for municipal logistics.
Japan
Toray's precursor production clusters create carbon fiber supply advantages for domestic tank manufacturers. METI's hydrogen roadmap targets industrial and transport applications with JIS standards governing containment system safety. Nagoya and Tokyo host integrated fuel cell vehicle development programs.
South Korea
Automotive OEMs specify Type 4 tanks for fuel cell vehicle platforms targeting export markets. MFDS and KGS certification requirements shape qualification timelines for high-pressure storage systems. Ulsan and Gwangju concentrate filament winding automation and composite manufacturing capacity.
Hydrogen Composite Tanks Market Competitive Landscape
European producers anchor one tier through Scandinavian and German manufacturing bases; North American specialists hold supply relationships with industrial gas distributors and heavy-duty fleet operators. The vendor base stratifies across three tiers: integrated composite manufacturers with captive fiber supply, mid-scale specialists focused on automotive qualification, and regional fabricators serving stationary storage applications. Consolidation pressure intensifies as OEM procurement consolidates around proven filament winding operations. Capacity expansion and strategic partnerships dominate competitive moves as suppliers race to secure carbon fiber allocation and automate production cells.
Within the integrated manufacturing tier, Hexagon Purus and Worthington Industries occupy positions that exemplify geographic specialization—Scandinavian and North American respectively—while Luxfer Group represents the aerospace-defense certification archetype through its aluminum-lined Type 3 focus. These three anchors demonstrate how raw material access and qualification timelines stratify competitive positioning across mobility and defense applications.
| Leading Market Players |
|---|
| Hexagon Purus |
| Worthington Industries |
| Luxfer Group |
| Quantum Fuel Systems LLC |
| Faber Industrie S.p.A. |
| NPROXX |
| Composite Advanced Technologies, LLC |
| Everest Kanto Cylinder Ltd. |
| Steelhead Composites, Inc. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal compliance mandates gate qualified supply access and premium-tier pricing power, compressing procurement timelines for certified tank manufacturers while elevating entry barriers for uncertified competitors. Fleet operators now consolidate procurement around suppliers with proven KBA and DOT qualification records, transferring residual value risk through long-term leasing structures that favor established filament winding operations.
Pricing Analysis
Capacity additions in Germany and South Korea are reshaping price floors for Type 4 polymer-lined tanks as automated winding cells compress unit cost curves without proportional labor expansion. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified Type 3 designs from automotive Type 4 variants and glass-fiber portable storage units. Price differentiation hinges on carbon fiber grade and ISO 19881 certification tier. Pricing pressure stems from CNG infrastructure substitution in cost-sensitive fleet segments. Logistics providers in California exhibit highest price sensitivity due to technology obsolescence uncertainty, while defense contractors demonstrate lowest sensitivity given multi-year qualification timelines.
Supply Chain Analysis
Carbon fiber precursor supply rests on Japanese and United States specialty chemical producers, creating input bottlenecks for tank manufacturers outside these geographies. Raw material dependencies include PAN-based standard modulus fiber, high-density polyethylene liners, and aluminum 6061-T6 barrier materials. Single-source vulnerability concentrates in Toray and Hexcel precursor networks. Distribution runs through Tier 1 automotive supplier channels in Germany and direct industrial gas distributor relationships in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as heavy-duty fleet procurement shifts toward 700-bar Type 4 specifications with traceable fatigue-life documentation, elevating supplier qualification requirements beyond reach of regional fabricators.
For Market Incumbents: To counter filament winding technician scarcity compressing production scaling, Hexagon Purus and Worthington Industries should deepen backward integration into carbon fiber precursor supply through captive offtake agreements with Japanese producers. Certification investment in emerging hydrogen mobility corridors across India and the Middle East anchors channel control against emerging Asian competitors. For New Entrants and Emerging Players: Glass fiber composite automation for portable and stationary storage segments offers the most penetrable entry point, as aerospace and automotive certification timelines extend across multiple years. Target India's PLI scheme for clean hydrogen manufacturing through local assembly partnerships with domestic industrial gas distributors, leveraging cost advantages in labor-intensive winding operations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialists with automotive qualification progress but incomplete OEM supplier status. Long-term viability across the projection horizon favors targets with demonstrated 700-bar validation protocols and established energy utility co-investment relationships. The signal to watch is KBA approval acceleration for Type 4 designs in German freight corridors, indicating inflection toward mass fleet procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Filament Winding Automation Scale-Up | Robotic fiber placement compresses Type 4 production cycles for German automotive OEMs. |
| Carbon Fiber Precursor Backward Integration | Captive supply from Toray and Hexcel networks reduces input bottlenecks for tank manufacturers. |
| 700-Bar Validation Protocol Investment | Extended pressure cycle testing secures automotive certification under ISO 19881 harmonization. |
| Hydrogen Mobility Corridor Joint Venture | Energy utility co-investment accelerates refueling infrastructure deployment along EU freight routes. |
| Aerospace Fatigue-Life Certification Program | Traceable cycle data opens defense and satellite propulsion applications for aluminum-lined Type 3 designs. |
Research Methodology
Bottom-up fuel cell vehicle fleet modeling reconciled against top-down carbon fiber supply tracking forms the analytical core of this study. Primary interviews with Tier 1 automotive procurement directors, industrial gas distribution executives, filament winding operations managers, and defense contractor engineering leads combined with secondary validation from DOT transportable tank filings, EU Green Deal subsidy disbursement records, KBA approval registries, and SEC 10-K disclosures from composite manufacturers. Triangulation across stakeholder inputs and regulatory databases ensures segmentation integrity.
Input-output matrices map carbon fiber precursor availability through tank manufacturing capacity to end-use demand across mobility, stationary, and aerospace applications. Segmentation dimensions include tank architecture type, pressure rating tier, liner material system, and regional regulatory cluster. CAGRs derive from pressure vessel installation run-rates correlated with hydrogen refueling station deployment trajectories and fleet conversion timelines under California CARB and EU CO2 standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ISO 19881 and IEC 62282 harmonization delays, carbon fiber supply allocation shifts, and CNG infrastructure substitution rates in cost-sensitive operator segments. A small set of triggers—including KBA Type 4 approval acceleration and India's PLI scheme implementation velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
India Hydrogen Market