
 Automotive Battery Management System Market | 2026-2036
Automotive Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Management System Market Analysis
South Korean semiconductor foundries is realigning BMS chip output toward automotive-grade silicon. Panasonic Corporation leverages its vertical integration into cylindrical cell production to sustain module-level BMS dominance. Robert Bosch GmbH anchors European supply through its manufacturing footprint in Germany and Hungary. Infineon Technologies AG differentiates via silicon-carbide gate drivers integrated into high-voltage battery controllers.
An automotive battery management system comprises embedded electronics, sensing networks, and software algorithms that monitor cell voltage, temperature, and state of charge across electrochemical storage packs. The architecture executes cell balancing, thermal regulation, and fault isolation to preserve battery longevity and operational safety in electrified drivetrains. Lithium-ion systems occupy the dominant product position due to energy density requirements in passenger electric vehicles, while solid-state configurations represent the emerging frontier where cell chemistry shifts demand new estimation algorithms. Electric vehicle manufacturers command the primary end-user channel, though aftermarket providers are building diagnostic tool ecosystems as vehicle fleets age.
China's NMPA enforces GB/T battery safety standards that mandate thermal runaway propagation resistance in passenger vehicle packs. The EU Green Deal and F-Gas Regulation are accelerating refrigerant transitions that reshape thermal management circuit designs within BMS architectures. ISO 26262 functional safety certification is becoming a non-negotiable market access filter for tier-one suppliers. Stakeholders must monitor how solid-state chemistry maturation alters cell modeling requirements and whether semiconductor supply resilience in East Asia reshapes geographic sourcing strategies.
Market Dynamics
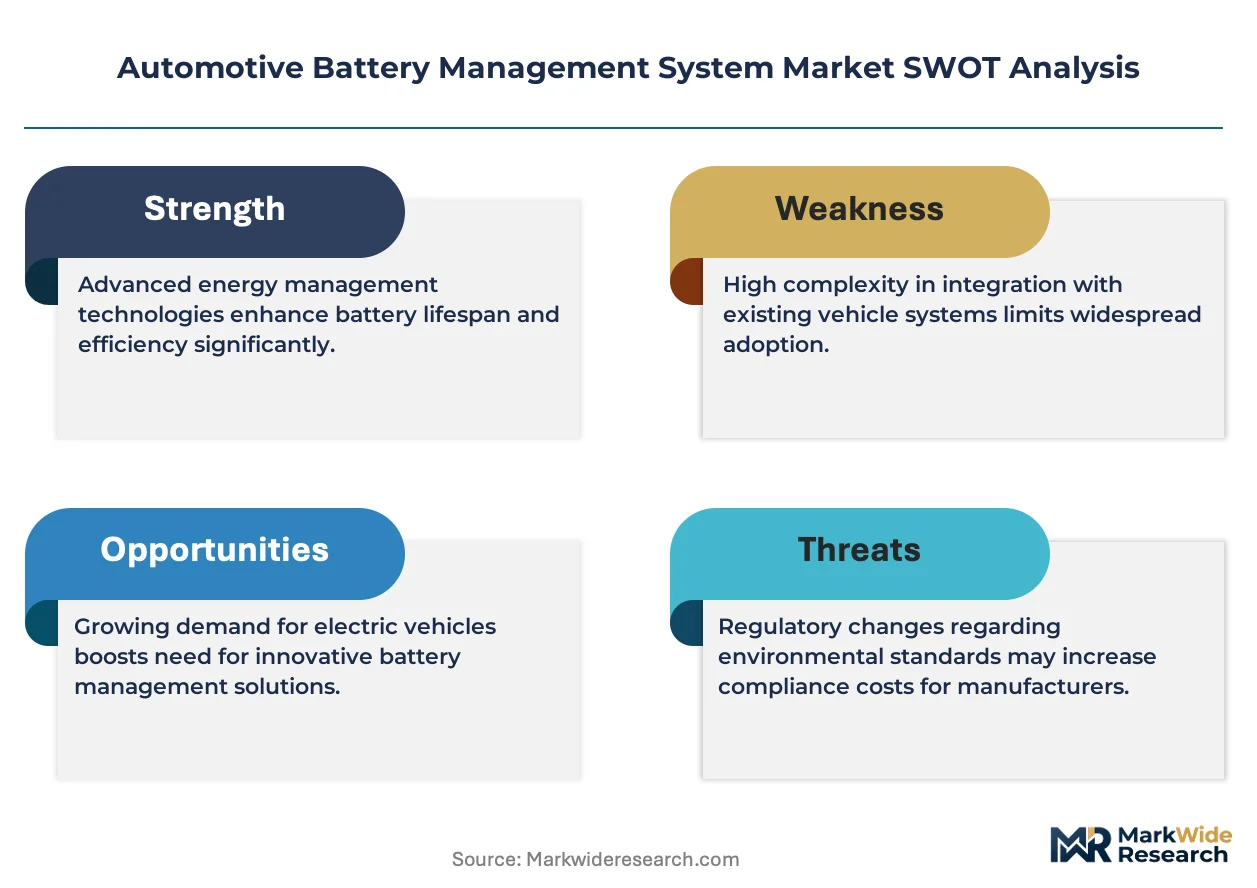
Semiconductor supply concentration in East Asia is forcing automotive OEMs to redesign BMS sourcing strategies around captive silicon capacity and geographic diversification mandates.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating thermal management circuit redesigns in European BMS architectures. This creates pull-through demand for integrated cooling-control electronics.
- Cell chemistry evolution:Solid-state battery pilots are requiring new state-of-estimation algorithms that fuse electrochemical impedance spectroscopy with real-time thermal data.
- South Korean foundry corridor:Concentrated automotive-grade silicon output near Seoul is reducing lead times for high-voltage isolation ICs and gate drivers.
Market Restraints
- Silicon carbide substrate costs:Wafer price volatility constrains margin expansion for high-voltage BMS controller suppliers.
- East Asian semiconductor concentration:Single-source dependency for automotive-grade MCUs creates geopolitical exposure in tier-one supply chains.
- ISO 26262 certification timelines:Functional safety validation cycles extend product launch windows by 18-24 months for new entrants.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are drawing BMS pack integrators to Gujarat and Tamil Nadu.
- Second-life battery diagnostics:Stationary storage repurposing is opening aftermarket software licensing channels for state-of-health prediction algorithms.
- Wireless BMS architectures:Elimination of high-voltage wiring harnesses converges with 5G industrial connectivity standards to reduce pack assembly labor.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262-certified firmware architects command premium compensation that strains R&D budgets at mid-tier suppliers.
- Legacy vehicle integration:Retrofit BMS compatibility with 400V architectures from prior EV generations complicates platform standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Management System Market |
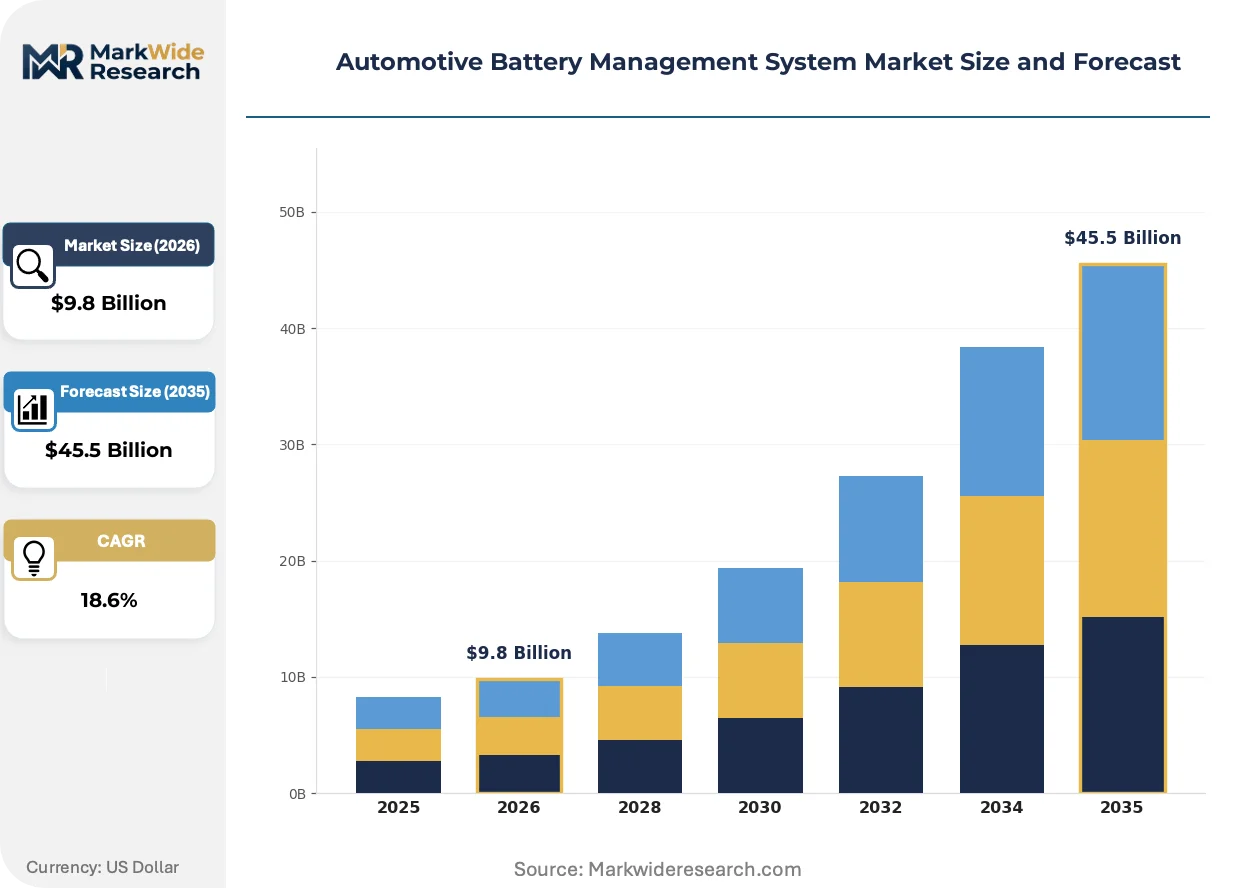
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $45.5 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State End User: OEMs, Aftermarket Providers, Electric Vehicle Manufacturers, Battery Suppliers Application: Energy Storage Systems, Electric Vehicles, Hybrid Vehicles, Renewable Energy Technology: Cell Balancing, State of Charge Estimation, Thermal Management, Communication Protocols |
| Companies Covered | Panasonic Corporation, Contemporary Amperex Technology Co. Limited (CATL), Robert Bosch GmbH, Infineon Technologies AG, Texas Instruments Incorporated, Continental AG, BYD Company Limited, Samsung SDI Co. Ltd., LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Management System Market Emerging Trajectories
Electrification platform consolidation is compressing BMS vendor margins while elevating the strategic value of software-defined battery control. Three forces are actively reshaping competitive positioning.
Silicon-carbide gate drivers are consolidating high-voltage switching functions previously distributed across discrete components. Tier-one suppliers are adopting these integrated modules for 800V architectures at accelerated qualification paces. This consolidation is compressing the addressable market for standalone driver IC suppliers while expanding margin pools for vertically integrated controller vendors.
China's NMPA is tightening GB/T thermal runaway propagation standards that mandate five-minute warning intervals before cell venting. Passenger vehicle OEMs are redesigning pack architectures to embed distributed temperature sensors at cell-tab junctions. European and South Korean battery producers are responding by pre-certifying modules against the Chinese protocol to maintain export eligibility.
Fleet operators are unbundling battery health monitoring from OEM service contracts and procuring predictive analytics directly from specialized software vendors. This disintermediation is visible most acutely in German commercial vehicle leasing markets where total-cost-of-ownership guarantees drive demand for independent state-of-charge verification. Third-party diagnostic platforms are capturing recurring revenue streams that previously accrued to vehicle manufacturers.
Automotive Battery Management System Market Segmentation
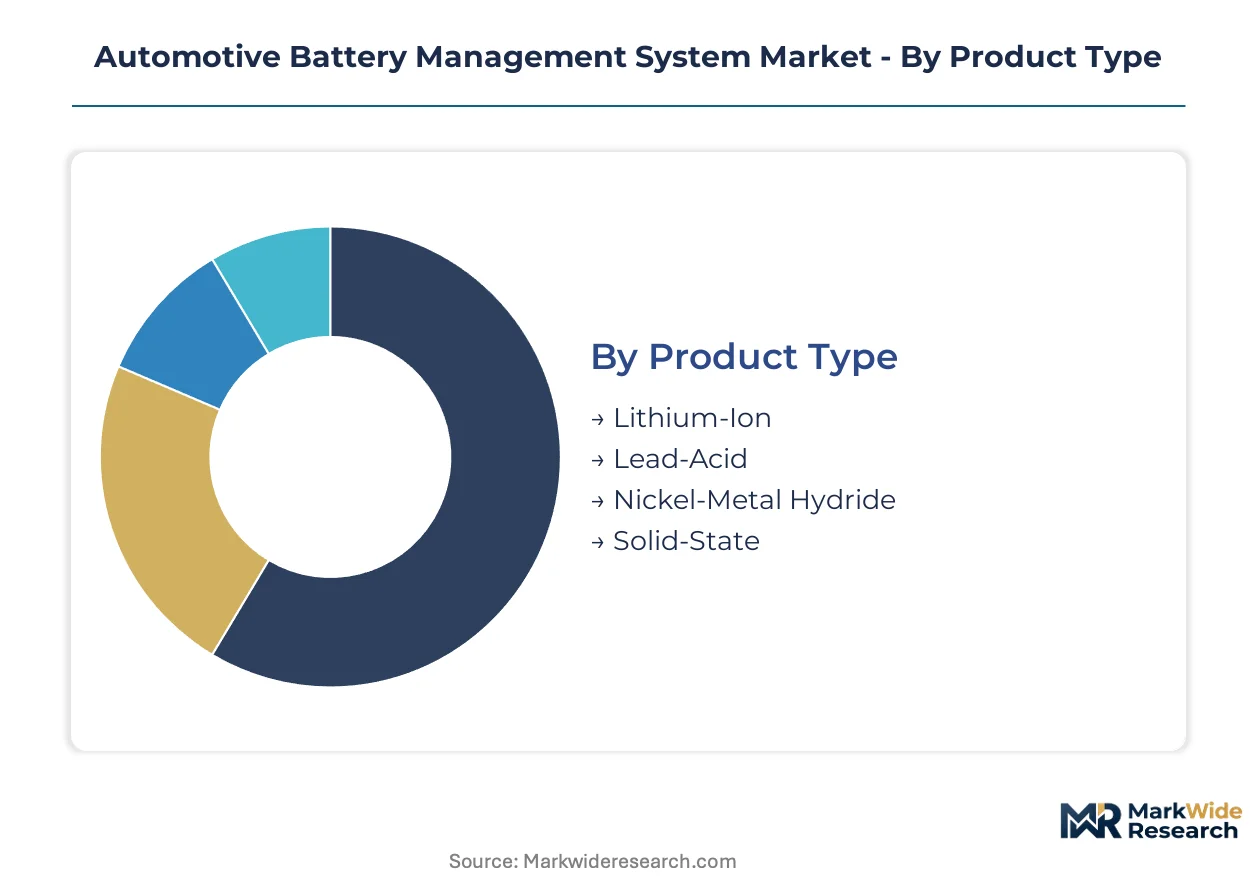
Automotive BMS architectures diverge sharply across electrochemical chemistries and voltage platforms. Cell monitoring algorithms must recalibrate for each chemistry's thermal signature, while end-user procurement patterns split between captive OEM supply and independent aftermarket channels.
Product Type:
Standardization dominates at the cell chemistry level, yet pack-level BMS firmware requires heavy customization per chemistry's electrochemical model.
- Lithium-Ion:Nickel-cobalt-manganese and lithium-iron-phosphate cathodes demand distinct state-of-charge estimation curves. Demand concentrates in passenger electric vehicle packs from Chinese and German OEMs, driven by energy density requirements for 400V and 800V platforms.
- Solid-State:Sulfide and oxide electrolyte chemistries eliminate thermal runaway risks but introduce impedance spectroscopy challenges for state estimation. Pilot deployments in South Korean and Japanese luxury EVs are accelerating algorithm development for dendrite detection.
- Lead-Acid:Flooded and absorbed glass mat variants serve 12V auxiliary systems in mild-hybrid architectures.
- Nickel-Metal Hydride:Toyota's hybrid-dedicated production line in Japan sustains niche demand for legacy power-split drivetrains.
Leading the category by volume: Lithium-Ion. Growing fastest: Solid-State.
End User:
Procurement authority shifts downstream as fleet operators seek direct control over battery health data.
- OEMs:Volkswagen Group and Hyundai Motor Company maintain captive BMS engineering teams that specify chipsets from Infineon and NXP. Their vertical control over firmware intellectual property blocks tier-one suppliers from accessing full vehicle diagnostic bus architectures.
- Electric Vehicle Manufacturers:BYD and Tesla integrate BMS design with cell manufacturing, compressing supplier margins. Their in-house production of battery controllers is displacing traditional tier-one module suppliers in China and the United States.
- Aftermarket Providers:German commercial vehicle leasing specialists are licensing predictive analytics for second-life battery valuation.
- Battery Suppliers:CATL and LG Energy Solution are pushing module-integrated BMS to capture value upstream of vehicle assembly.
Volume leadership sits with OEMs. Aftermarket Providers are expanding most quickly as aging EV fleets create diagnostic service demand.
Application:
Voltage and duty cycle requirements fragment BMS design specifications across mobility and stationary use cases.
- Electric Vehicles:Passenger car packs operate at 400V-800V with cell-level temperature monitoring at 1-second intervals. Chinese NMPA thermal runaway mandates are forcing redesigns of sensor placement at cell-tab junctions.
- Energy Storage Systems:Grid-scale installations prioritize cycle-life optimization over fast-charge capability. South Korean project developers are procuring BMS with 15-year warranty algorithms for lithium-phosphate installations.
- Hybrid Vehicles:Power-split architectures require rapid state-of-charge swings that stress estimation accuracy.
- Renewable Energy:Solar-plus-storage configurations in India and Australia demand wide-temperature-range operation for desert installations.
Electric Vehicles command the steepest expansion trajectory. Energy Storage Systems are gaining share fastest as grid interconnection queues lengthen.
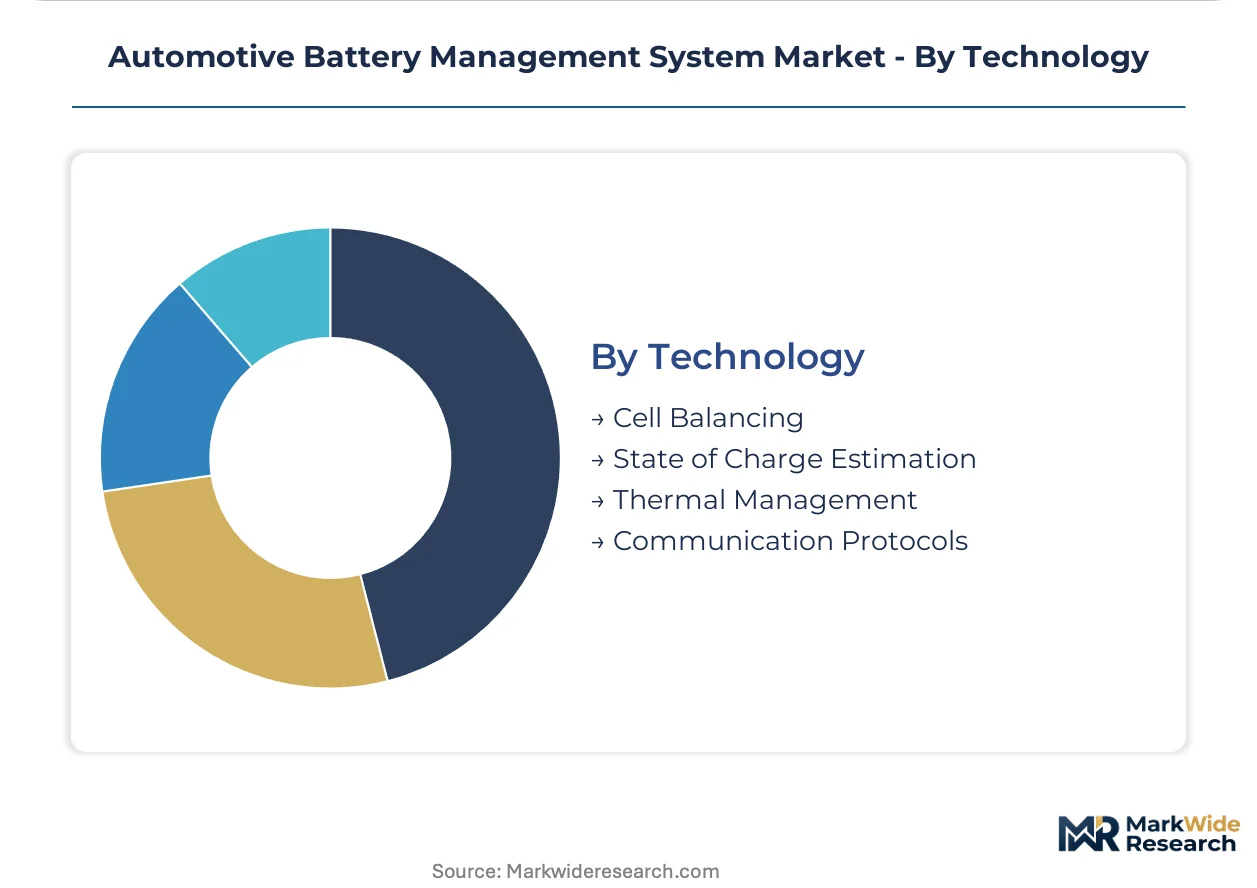
Technology:
Software-defined functionality is displacing hardware-centric architectures as semiconductor integration advances.
- State of Charge Estimation:Kalman filter and neural network implementations fuse voltage, current, and temperature inputs. German OEMs are requiring ASIL-D certification for estimation algorithms in premium EV platforms.
- Thermal Management:EU F-Gas Regulation refrigerant phase-downs are forcing redesigns of cooling circuit control logic. Integrated gate drivers from Infineon now combine switching functions with temperature feedback loops.
- Cell Balancing:Active balancing circuits recover energy during charge equalization, improving pack efficiency by 3-5 percentage points.
- Communication Protocols:CAN FD and automotive Ethernet are displacing legacy CAN for 800V architectures requiring faster fault propagation signaling.
State of Charge Estimation leads by installed base. Thermal Management is climbing the fastest as high-voltage platforms multiply cooling complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate deposits in Chile's Atacama Desert and cobalt refining capacity in the Democratic Republic of Congo anchor raw-material flows toward battery manufacturing hubs. Cell production concentrates in East Asian industrial corridors and German automotive clusters, with BMS design engineering following pack assembly location.
China
CATL and BYD dominate cell production in Fujian and Guangdong provinces, consuming over half of global lithium chemical supply. The NMPA enforces GB/T thermal runaway standards that mandate five-minute warning intervals before cell venting. Shenzhen and Ningbo host concentrated BMS firmware development centers serving domestic EV manufacturers.
Germany
Volkswagen Group and BMW specify BMS architectures for 800V platforms launching from 2024-2026. The EU F-Gas Regulation accelerates refrigerant transitions that reshape thermal management circuit designs. Stuttgart and Munich anchor development corridors where Infineon and Bosch maintain captive engineering centers.
United States
Tesla's Nevada Gigafactory and emerging Michigan battery plants drive demand for high-voltage isolation ICs. The Inflation Reduction Act domestic content requirements are reshoring pack assembly from Mexican maquiladoras. Austin and Detroit metropolitan areas concentrate BMS software talent pools for autonomous vehicle integration.
South Korea
LG Energy Solution and Samsung SDI supply cylindrical and prismatic cells to German and US OEMs under long-term contracts. The MFDS maintains medical-grade quality standards that semiconductor foundries adapt for automotive reliability certification. Seoul's Pangyo Techno Valley hosts fabless BMS chip design houses reducing NRE costs for tier-one suppliers.
Japan
Toyota's solid-state battery pilot lines in Aichi Prefecture are accelerating algorithm development for sulfide electrolyte impedance spectroscopy. METI funding programs support domestic semiconductor production to reduce MCU import dependency. Nagoya and Kyoto maintain precision manufacturing clusters for high-voltage sensor modules.
Automotive Battery Management System Market Vendor Landscape
Global majors compete with regional champions across silicon supply and firmware intellectual property. The vendor base separates into three tiers: captive OEM engineering divisions, tier-one module integrators, and fabless semiconductor specialists. Two strategic archetypes dominate: vertically integrated battery producers controlling cell-to-system design, and semiconductor vendors supplying standardized controller platforms. Competitive moves concentrate on backward integration into silicon carbide substrate sourcing and geographic diversification of foundry relationships.
Among Japanese diversified electronics conglomerates, Panasonic Corporation exemplifies the cell-manufacturing-integrated archetype through its cylindrical battery production. German automotive suppliers Robert Bosch GmbH and Infineon Technologies AG occupy positions spanning tier-one module supply and semiconductor component provision respectively. These three entities represent distinct competitive vectors: captive cell-BMS integration, European manufacturing footprint anchoring, and silicon-carbide power electronics specialization.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Contemporary Amperex Technology Co. Limited (CATL) |
| Robert Bosch GmbH |
| Infineon Technologies AG |
| Texas Instruments Incorporated |
| Continental AG |
| BYD Company Limited |
| Samsung SDI Co. Ltd. |
| LG Chem Ltd. |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate price indices cascading from Chilean extraction through Chinese refining establish tiered cost baselines that stratify BMS module pricing across automotive-grade silicon, thermal management subsystems, and firmware licensing bundles. OEMs with captive cell production capture margin compression relief unavailable to tier-one suppliers dependent on spot-market cathode materials.
Pricing Analysis
Warranty and predictive-maintenance bundling separates premium BMS offerings from transactional hardware sales. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and uncertified controller levels reflects ISO 26262 validation investment recovery. Cost compression in entry-level lithium-ion BMS modules is intensifying because Chinese EV manufacturers are bringing controller design in-house. Fleet operators leasing German commercial vehicles exhibit highest price sensitivity due to total-cost-of-ownership guarantees, while luxury OEMs in Japan and South Korea absorb premium pricing for solid-state-compatible firmware.
Supply Chain Analysis
Domestic content requirements in the US Inflation Reduction Act and India's PLI scheme for advanced chemistry cells are reshoring pack assembly from Mexican maquiladoras and drawing integrators to Gujarat. Semiconductor fabrication concentrates in South Korea, Taiwan, and Japan for automotive-grade MCUs and isolation ICs. Silicon carbide substrates and lithium hexafluorophosphate electrolytes constitute critical input dependencies. Single-source vulnerability for high-voltage gate drivers creates geopolitical exposure. Distribution runs through tier-one module integrators supplying OEM final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive BMS sector is becoming a vertical-integration race where control over silicon carbide substrate sourcing and captive foundry relationships determines margin sustainability. Players are pursuing upstream semiconductor capacity as the decisive competitive lever.
For Market Incumbents: Deploy captive silicon carbide wafer sourcing to offset price volatility eroding high-voltage controller margins. Secure ASIL-D certification for state-estimation algorithms before Chinese NMPA mandates tighten further. Consolidate module supply agreements with Volkswagen Group and Hyundai Motor Company to block tier-two entrants from accessing 800V platform specifications.
For New Entrants and Emerging Players: The EU F-Gas Regulation in Europe opens a window for thermal management circuit specialists to capture redesign demand from refrigerant phase-down mandates. Target aftermarket predictive analytics for second-life battery valuation in German commercial vehicle leasing. License state-of-health algorithms to stationary storage project developers as a software-first entry path avoiding capital-intensive hardware manufacturing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless BMS chip design houses in South Korea's Pangyo Techno Valley facing working capital constraints from semiconductor inventory corrections. Long-term viability hinges on algorithm intellectual property transferable across solid-state and lithium-ion chemistry transitions. Watch for NMPA thermal runaway standard harmonization with EU protocols as inflection signal for export-oriented module suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | Captive wafer supply from Japanese and US sources insulates Infineon from price volatility. |
| ASIL-D Algorithm Certification Investment | German OEM requirements for functional safety create non-negotiable market access filters. |
| Wireless BMS Architecture Development | Elimination of high-voltage harnesses aligns with 5G industrial connectivity standards. |
| India PLI Scheme Manufacturing Footprint | Gujarat and Tamil Nadu incentives attract pack integrators serving domestic EV demand. |
| Second-Life Battery Diagnostic Platform Launch | Stationary storage repurposing opens recurring software licensing revenue streams. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, tier-one supplier procurement leads, semiconductor foundry operations managers, and aftermarket diagnostic software vendors underwrites the qualitative findings. Primary interviews with BMS firmware architects and thermal management circuit designers combined with secondary validation from vehicle production databases, NMPA GB/T standard filings, and SEC disclosures from battery and semiconductor suppliers. Bottom-up cell chemistry demand modeling and top-down automotive electrification penetration rates triangulate volume estimates.
Comparable historical periods anchoring battery controller adoption curves and silicon carbide power electronics qualification timelines informed the projection framework. Segmentation dimensions span cell chemistry, voltage platform, end-user procurement authority, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to OEM platform launch schedules and foundry capacity expansion announcements. Solid-state battery pilot deployment timelines and thermal runaway testing protocol evolution constitute industry-specific forecast inputs.
Caveats apply where NMPA mandate acceleration or East Asian semiconductor export restrictions could materially shift the outlook. Forecasts reflect assumptions regarding chemistry transition pace and functional safety certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Distributed Energy Storage System Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
North America Battery Management System Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Battery Management Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
US Energy Storage Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
Smart Battery Maintainer Market