
 Battery Monitoring Unit Market | 2026-2036
Battery Monitoring Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Monitoring Unit Market Outlook
Aftermarket service revenue is tilting toward predictive analytics and remote diagnostics as battery operators seek to minimize unplanned downtime. Schneider Electric leverages its energy management software stack to anchor recurring service contracts across data center fleets. Texas Instruments specializes in precision voltage sensing ICs that sustain design wins with tier-one automotive battery pack integrators. ABB competes through integrated power-electronics platforms that extend from cell monitoring up to grid-tied inverter control.
A battery monitoring unit is an embedded electronics assembly that measures cell voltage, temperature, and impedance with millivolt accuracy to prevent thermal runaway and capacity fade. Its primary commercial purpose is to extend battery cycle life and certify operational safety in high-value energy storage installations. Wired technology still dominates installed base economics, though IoT-based architectures are capturing the fastest expansion as edge computing costs fall and cloud-integrated platforms aggregate fleet-level degradation models across dispersed assets. Lithium-ion product types command the deepest margin pools because their monitoring complexity justifies premium hardware and software stacks.
FDA device-grade reliability standards, ECHA battery passport traceability rules under REACH, and MIIT's GB/T cell testing protocols are all tightening data logging and fault-response requirements for monitoring hardware. These frameworks elevate compliance costs for new entrants while locking in incumbent suppliers with certified testing laboratories and regulatory dossiers. Stakeholders must weigh whether to build cloud-native monitoring stacks in-house or partner with platform vendors as OEMs consolidate supplier lists around vertically integrated safety systems.
Market Dynamics
The Battery Monitoring Unit Market pivots on the collision between stricter cell-level safety mandates and the operational economics of multi-gigawatt-hour storage fleets. ECHA battery passport requirements and MIIT GB/T testing protocols are forcing hardware redesigns that prioritize traceability over legacy voltage-only monitoring.
Growth Catalysts
- Grid-scale storage deployment:Utility-scale lithium-ion installations across the United States, China, and South Korea require centralized monitoring architectures that aggregate thousands of cell-level data streams into predictive maintenance dashboards.
- REACH traceability mandates:ECHA battery passport rules under the EU regulatory framework compel pack integrators to retrofit existing assets with enhanced data logging hardware, creating replacement demand across European industrial fleets.
- Edge computing cost compression:Falling semiconductor prices for ARM-based microcontrollers enable distributed processing architectures that reduce cloud transmission latency for thermal runaway detection algorithms.
Market Restraints
- Precision sensor supply concentration:Millivolt-accurate voltage sensing ICs depend on a narrow supplier base concentrated in East Asian foundries, exposing integrators to allocation risk during automotive demand surges.
- Certification timeline friction:FDA device-grade reliability standards and automotive ISO 26262 functional safety certifications impose 18-24 month validation cycles that delay revenue recognition for new hardware entrants.
- Passive balancing cost floor:Resistive cell balancing remains the dominant architecture in cost-sensitive applications, limiting attach rates for higher-margin active balancing monitoring systems.
Strategic Opportunities
- Second-life battery monitoring:Decommissioned electric vehicle packs entering stationary storage in Germany and China require adaptive monitoring hardware that recalibrates degradation models for reduced-capacity cells.
- IoT architecture penetration:Wireless mesh protocols combined with cloud-integrated platforms enable fleet-level analytics across dispersed renewable-plus-storage installations without trenching costs.
- India CEA storage mandates:Central Electricity Authority regulations requiring frequency regulation reserves create demand for monitoring systems in grid-connected battery installations across Maharashtra, Gujarat, and Tamil Nadu.
Industry Challenges
- Embedded firmware talent scarcity:Battery management algorithm development requires specialized expertise in electrochemical impedance spectroscopy and Kalman filter state estimation that concentrates in automotive hubs.
- Legacy SCADA integration complexity:Industrial battery operators in data center and telecom verticals maintain decades-old control architectures that resist API-based connectivity with modern monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Monitoring Unit Market |
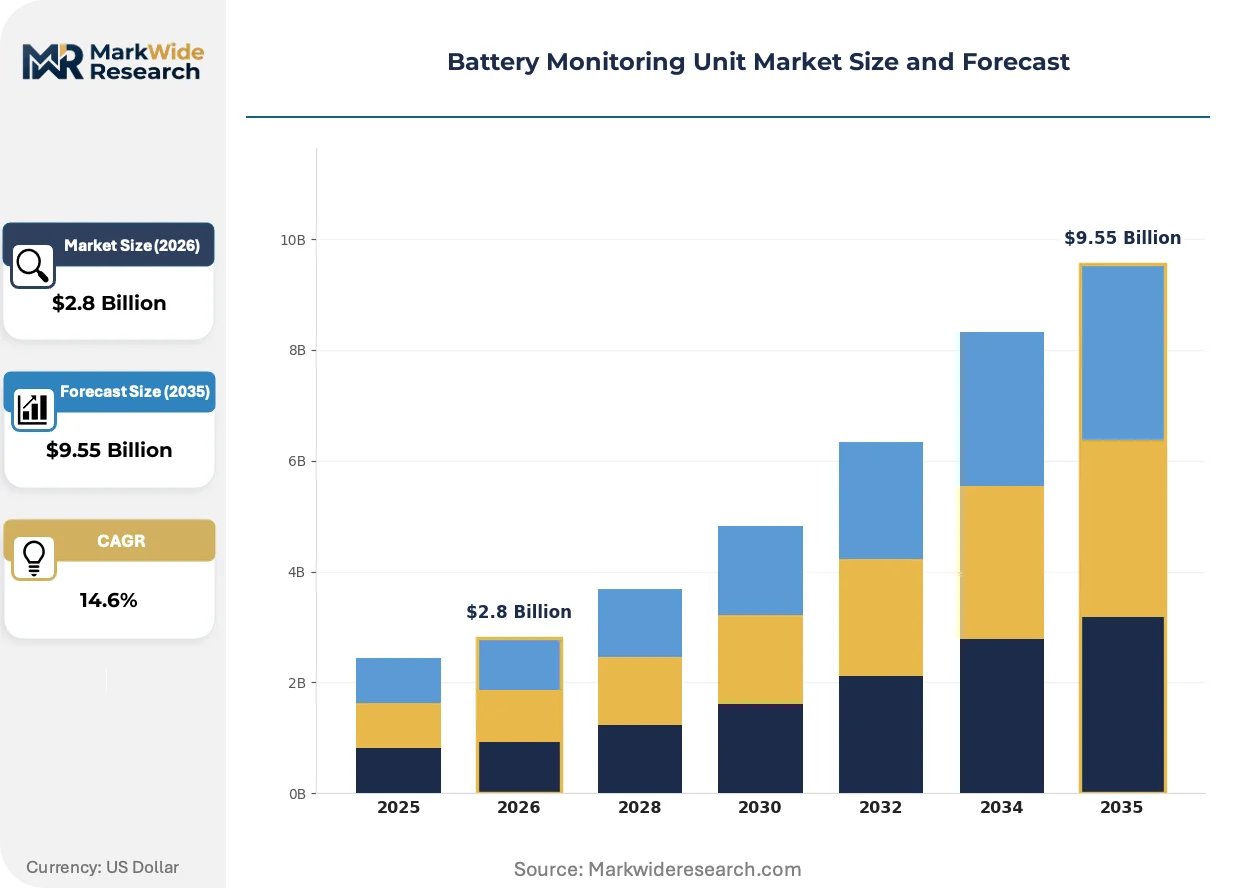
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Others End User: Automotive, Renewable Energy, Industrial, Consumer Electronics Technology: Wired, Wireless, IoT-Based, Cloud-Integrated Application: Telecom, Data Centers, Electric Vehicles, Backup Power |
| Companies Covered | Schneider Electric, ABB, Texas Instruments, NDSL Group Limited, General Electric, Hitachi Energy, Eagle Eye Power Solutions, HBL Power Systems, Benchmark Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Monitoring Unit Market Strategic Shifts
Electrochemical sensing modalities and connectivity architectures are converging to compress hardware BOM costs while expanding diagnostic depth. These shifts are reconfiguring supplier value capture toward software-defined monitoring stacks.
Silicon-carbide-based isolated ADC architectures are rendering obsolete optocoupler-based voltage sensing chains that dominated prior-generation battery management systems. Tier-one automotive pack integrators in Germany and South Korea have accelerated qualification timelines for these devices by eight quarters. The transition compresses bill-of-materials costs for high-channel-count systems while enabling sub-millivolt accuracy across wider temperature ranges.
MIIT's GB/T 36276 cell testing protocols and ECHA battery passport traceability rules are tightening data retention and fault-response latency requirements for monitoring hardware deployed in Chinese and European markets. Pack manufacturers must now implement redundant storage of decade-long operational logs with cryptographic integrity verification. Industrial storage integrators are responding by consolidating supplier relationships around vertically certified safety system vendors with in-house testing laboratories.
Aftermarket service unbundling is disrupting traditional hardware-plus-warranty contracting across data center and utility fleets. Battery operators in the United States are separating predictive analytics subscriptions from initial capital purchases, forcing hardware OEMs to develop recurring revenue capabilities or cede margin to independent software vendors. This bifurcation concentrates procurement decision-making with fleet engineering teams rather than capital project managers.
Battery Monitoring Unit Market Segmentation
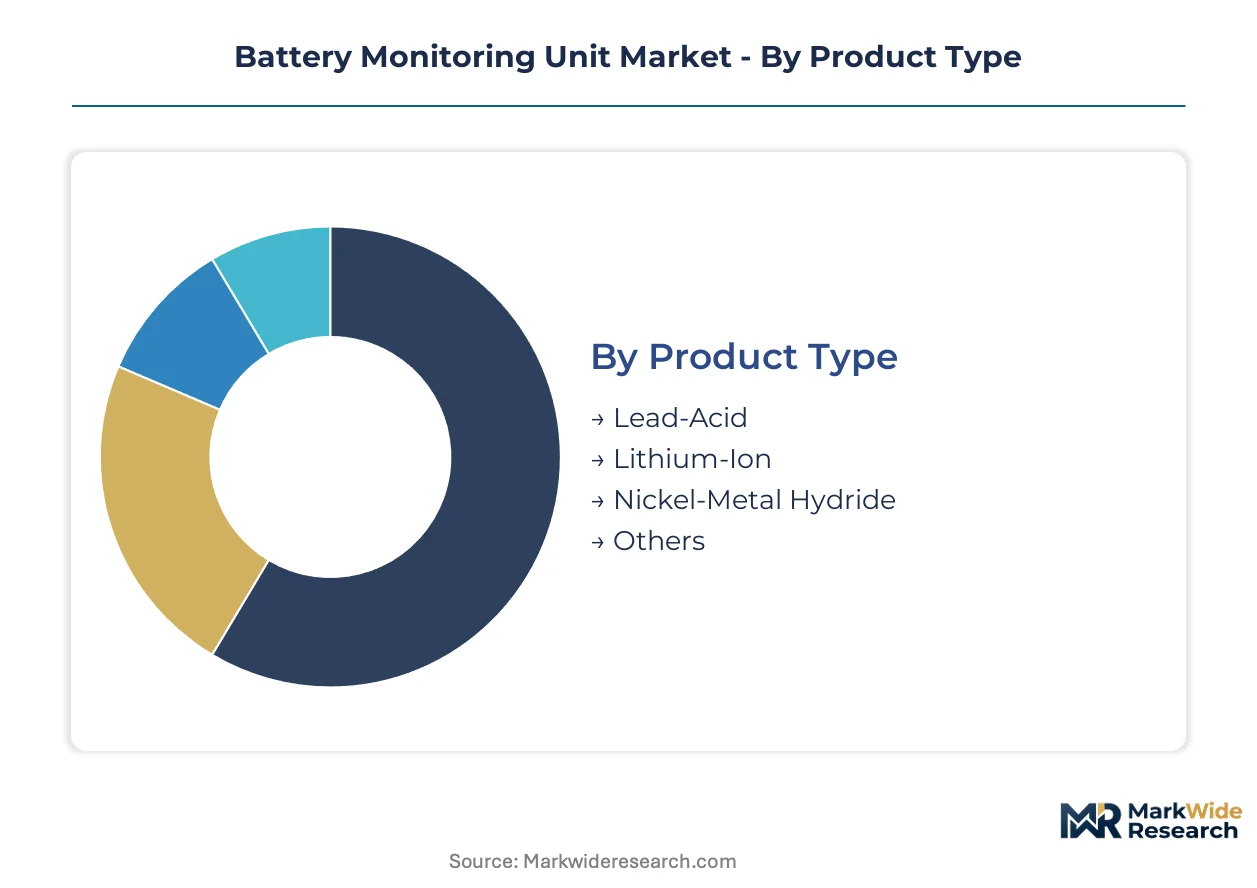
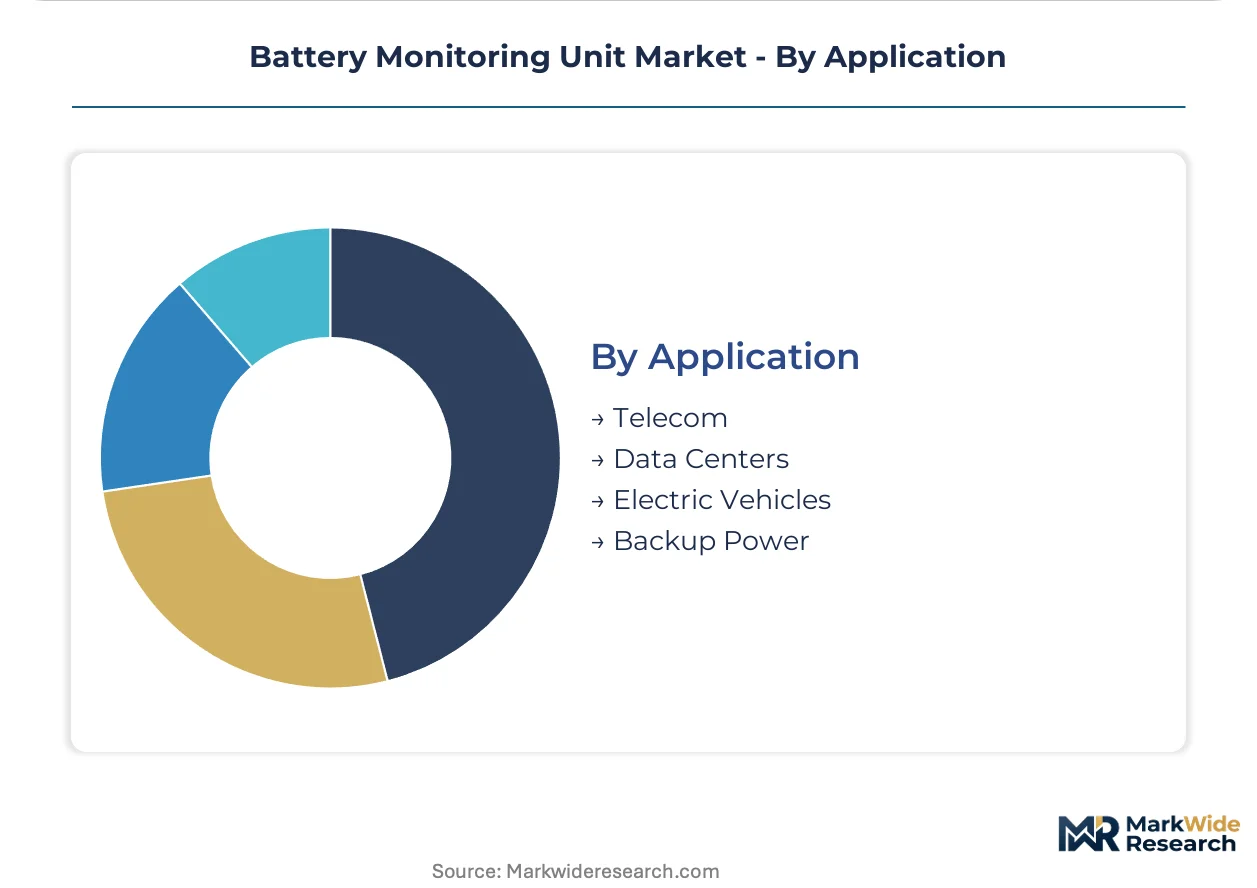
Battery monitoring unit segmentation reflects divergent technical requirements across electrochemical chemistries and deployment architectures. Product type and technology choices determine hardware BOM composition, while end-user verticals dictate certification tiers and service revenue models.
Product Type:
Mature lead-acid monitoring systems anchor installed base economics, while lithium-ion architectures command premium positioning through complex cell balancing demands.
- Lithium-Ion:Multi-channel voltage sensing with millivolt precision addresses thermal runaway risks in high-density pack configurations. Grid-scale storage installations across the United States, China, and South Korea drive concentrated demand for predictive analytics integration.
- Lead-Acid:Simpler float voltage monitoring dominates telecom backup and industrial forklift fleets where cost sensitivity overrides diagnostic depth. Resistive balancing circuits sustain multi-decade replacement cycles in mature infrastructure.
- Nickel-Metal Hydride:Legacy hybrid vehicle programs in Japan retain specialized monitoring demand for state-of-charge estimation algorithms.
- Others:Sodium-ion and solid-state pilot deployments require adaptive firmware architectures not yet standardized.
Lithium-ion retains volume leadership; emerging solid-state chemistries hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive utility procurement from price-sensitive consumer electronics integration.
- Automotive:ISO 26262 functional safety certification mandates redundant sensing chains for electric vehicle battery packs. German and Chinese OEMs consolidate supplier lists around vertically integrated safety system vendors with in-house testing laboratories.
- Renewable Energy:Utility-scale solar-plus-storage installations require centralized monitoring architectures aggregating thousands of cell-level data streams. ECHA battery passport traceability rules under REACH compel enhanced data logging hardware retrofits across European industrial fleets.
- Industrial:Data center uninterruptible power systems prioritize FDA device-grade reliability standards for mission-critical uptime guarantees.
- Consumer Electronics:Smartphone and laptop manufacturers absorb monitoring functions into power management ICs, collapsing standalone unit attach rates.
Automotive commands the deepest margin pools; renewable energy gains share fastest through gigawatt-hour deployment acceleration.
Technology:
Supply concentration in precision analog semiconductors shapes integration economics across connectivity architectures.
- Wired:CAN bus and isolated SPI interfaces dominate automotive pack architectures where electromagnetic immunity is non-negotiable. Tier-one integrators in Germany and South Korea maintain eight-quarter qualification timelines for silicon-carbide-based isolated ADC devices.
- IoT-Based:Wireless mesh protocols combined with edge computing enable fleet-level analytics across dispersed renewable-plus-storage installations without trenching costs. Falling ARM-based microcontroller prices compress hardware BOM for distributed processing architectures.
- Wireless:Bluetooth Low Energy and proprietary sub-GHz radios penetrate second-life battery monitoring where retrofit wiring is impractical.
- Cloud-Integrated:API-based platforms aggregate degradation models across dispersed assets, shifting value capture toward software-defined monitoring stacks.
Wired technology sustains installed base dominance; IoT-based architectures climb the fastest as edge computing costs compress.
Application:
Customer type segmentation separates procurement decision-making between fleet engineering teams and capital project managers.
- Electric Vehicles:Cell-level monitoring with sub-millivolt accuracy across wide temperature ranges sustains battery cycle life certification. MIIT GB/T testing protocols and ECHA battery passport rules tighten data retention requirements with cryptographic integrity verification.
- Data Centers:Schneider Electric anchors recurring service contracts through energy management software stacks that minimize unplanned downtime. Aftermarket service unbundling separates predictive analytics subscriptions from initial capital purchases.
- Telecom:Legacy SCADA integration complexity resists API-based connectivity with modern monitoring platforms in decades-old control architectures.
- Backup Power:Passive balancing cost floors limit attach rates for higher-margin active balancing systems in price-sensitive commercial installations.
Electric vehicles retain technology leadership; data centers drive service revenue transformation fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb premium pricing for certified safety systems, while operators in India and Southeast Asia prioritize cost-optimized hardware that meets baseline functional requirements.
United States
Utility-scale lithium-ion storage deployments across Texas and California require centralized monitoring architectures aggregating thousands of cell-level data streams. FERC Order 841 enables battery storage participation in wholesale markets, accelerating procurement of predictive maintenance platforms. Data center clusters in Northern Virginia and Phoenix anchor recurring service contracts through energy management software stacks.
Germany
Electric vehicle manufacturers in Bavaria and Baden-Württemberg scale battery monitoring deployments to comply with ECHA battery passport traceability rules under REACH. The country's national automotive regulator KBA enforces stringent documentation requirements for cell-level safety systems. Industrial storage installations in North Rhine-Westphalia retrofit existing assets with enhanced data logging hardware.
China
Grid-scale storage installations across Jiangsu and Guangdong provinces drive concentrated demand for lithium-ion monitoring systems. MIIT's GB/T 36276 cell testing protocols tighten data retention and fault-response latency requirements for monitoring hardware. Battery pack integrators in the Yangtze River Delta consolidate supplier relationships around vertically certified safety system vendors.
South Korea
Automotive battery pack manufacturers in Seoul and Ulsan accelerate qualification timelines for silicon-carbide-based isolated ADC devices. The country's national pharmaceutical and medical device regulator MFDS maintains overlapping jurisdiction for device-grade reliability standards in medical energy storage. Renewable-plus-storage installations in Jeolla Province adopt wireless mesh protocols for fleet-level analytics.
India
Central Electricity Authority regulations requiring frequency regulation reserves create demand for monitoring systems in Maharashtra, Gujarat, and Tamil Nadu. The Bureau of Indian Standards implements testing protocols for battery management systems in grid-connected installations. Industrial operators in the Delhi-Mumbai Industrial Corridor prioritize cost-optimized hardware configurations.
Battery Monitoring Unit Market Competitive Environment
Capability concentration sits with precision analog semiconductor specialists; scale advantage sits with diversified industrial conglomerates. The vendor base organizes around three strategic archetypes: energy management software integrators, precision sensing IC designers, and integrated power-electronics platform builders. Consolidation pressure favors backward integration into captive testing laboratories and in-house certification capabilities. Geographic expansion and strategic partnerships represent the dominant competitive moves as OEMs reduce supplier lists.
Within the diversified industrial tier, Schneider Electric and ABB occupy positions anchoring recurring service contracts through software-defined monitoring stacks. Texas Instruments exemplifies the precision analog specialist archetype, sustaining design relationships with automotive pack integrators through voltage sensing integrated circuits. These three entities represent distinct capability vectors: software integration, semiconductor precision, and power-electronics platforms.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Texas Instruments |
| NDSL Group Limited |
| General Electric |
| Hitachi Energy |
| Eagle Eye Power Solutions |
| HBL Power Systems |
| Benchmark Electronics |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on East Asian precision voltage sensing ICs compresses margin structures across hardware tiers while forcing buyers into long-term offtake commitments to secure allocation. This concentration simultaneously widens pricing spreads between certified automotive-grade systems and cost-optimized commercial installations.
Pricing Analysis
Aftermarket predictive analytics subscriptions now capture the dominant share of lifetime customer value, displacing upfront hardware margins as the primary revenue anchor. Three-tier pricing structure across premium, standard, and economy levels separates FDA device-grade certified systems from industrial-grade monitoring units and cost-sensitive telecom backup configurations. Cost compression in the standard tier is intensifying because automotive demand surges are absorbing precision semiconductor capacity. Data center operators exhibit the lowest price sensitivity due to mission-critical uptime requirements, while commercial backup power installers remain most responsive to unit economics.
Supply Chain Analysis
Extended payment terms from tier-one automotive pack integrators in Germany and South Korea are forcing precision analog semiconductor suppliers to absorb working capital strain through supply-chain finance facilities. Manufacturing concentration centers on Taiwan for isolated ADC fabrication, South Korea for silicon-carbide substrate production, and China for lithium-ion cell assembly integration. Millivolt-accurate voltage sensing ICs, ARM-based microcontroller modules, and cryptographic secure elements constitute critical component dependencies. Single-source vulnerability in East Asian foundry capacity exposes integrators to allocation risk during automotive demand cycles. Distribution runs through authorized distributor networks serving industrial automation and energy verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Battery Monitoring Unit Market is entering a cyclical recovery phase as grid-scale storage deployment accelerates through utility procurement cycles. This rebound draws from FERC Order 841 enabling wholesale market participation and ECHA battery passport retrofit mandates across European industrial fleets.
For Market Incumbents: Pre-empt margin erosion in hardware-only contracting by bundling predictive analytics subscriptions into multi-year service agreements. Consolidate supplier relationships around vertically certified safety system vendors with captive testing laboratories to defend against emerging IoT-native platform competitors. Accelerate qualification timelines for silicon-carbide-based isolated ADC architectures to capture design wins with tier-one automotive pack integrators. For New Entrants and Emerging Players: Second-life battery monitoring for decommissioned electric vehicle packs entering stationary storage in Germany and China represents the most penetrable entry point for adaptive hardware architectures. Wireless mesh protocol deployments across dispersed renewable-plus-storage installations in India offer a software-first go-to-market angle that bypasses legacy SCADA integration complexity. Target CEA-mandated frequency regulation reserve installations in Maharashtra and Gujarat with cost-optimized hardware configurations. For Investors and Strategic Acquirers: ECHA battery passport traceability rules under REACH reshape the acquisition landscape by elevating compliance costs for uncertified hardware vendors. Long-term viability over the projection horizon favors precision analog semiconductor specialists with established automotive design relationships and in-house testing capabilities. The signal to monitor is qualification timeline compression for silicon-carbide-based isolated ADC devices, which indicates accelerating technology transition and vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Sensing ICs | Captive voltage sensing fabrication reduces allocation risk from East Asian foundry concentration. |
| Cloud-Native Monitoring Platform Launch | API-based degradation analytics shift value capture toward recurring software revenue from hardware sales. |
| Certification Laboratory Acquisition | In-house ECHA battery passport and MIIT GB/T testing capabilities accelerate OEM supplier list consolidation. |
| Wireless Mesh Protocol Partnership | IoT architecture penetration enables fleet-level analytics without trenching costs across dispersed assets. |
| Second-Life Battery Monitoring Product Line | Adaptive firmware for reduced-capacity cells addresses emerging demand from decommissioned EV pack repurposing. |
Study Parameters
The analysis maps lithium-ion monitoring systems, lead-acid legacy architectures, and emerging solid-state chemistries, each validated through battery pack integrators, utility procurement officers, data center engineering directors, and precision analog semiconductor suppliers. Primary interviews with these stakeholders combined with secondary validation from MIIT GB/T regulatory filings, ECHA battery passport documentation, FERC Order 841 implementation records, and automotive OEM supplier qualification databases. Bottom-up unit economics and top-down grid-scale deployment targets were triangulated to constrain estimate variance.
Assumptions held fixed include ECHA battery passport traceability enforcement timelines, MIIT GB/T 36276 testing protocol adherence, and silicon-carbide-based isolated ADC cost compression curves; varied assumptions encompass grid-scale storage deployment acceleration rates and second-life battery pack commercialization timing. The analytical framework models product type, end-user vertical, connectivity technology, and application segments across the projection horizon. CAGRs were derived from segment-level unit shipment trajectories and average selling price evolution. Electrochemical impedance spectroscopy algorithm development timelines and ARM-based microcontroller cost curves served as industry-specific forecast inputs.
Stress conditions across precision semiconductor allocation cycles, regulatory certification timeline friction, and automotive demand surge magnitude were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology transition pacing and compliance cost trajectories. Macroeconomic contraction, regulatory enforcement delay, or solid-state chemistry breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Battery Management Market
Battery Management System
Global Power Management System Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
North America Energy Storage Market