
 Wind Turbine Inspection Drones Market | 2026-2036
Wind Turbine Inspection Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Inspection Drones Market Outlook
The wind turbine inspection drones sector is restructuring around a sharp split between premium autonomous platforms with AI-powered defect classification and commodity remote-operated units sold on hardware margins. Cyberhawk Innovations Limited leverages its offshore certification depth to anchor premium contracts in North Sea markets. SZ DJI Technology Co., Ltd. sustains volume dominance through modular hardware ecosystems that service providers customize for regional wind farm conditions. Percepto Ltd. differentiates through fully autonomous docking stations that eliminate pilot dependency for routine blade surveys.
Wind turbine inspection drones are unmanned aerial systems engineered with sub-millimeter optical resolution and integrated thermal payloads to detect leading-edge erosion, lightning receptor damage, and adhesive joint delamination on rotor blades. Multirotor configurations dominate near-turbine maneuverability requirements, while fixed-wing platforms extend range for linear array inspections across sprawling onshore complexes. LiDAR-enabled systems are capturing the fastest expansion as operators demand three-dimensional blade geometry mapping to predict structural fatigue. Service providers represent the most contested end-user segment, with inspection firms consolidating vendor relationships to secure fleet-wide maintenance contracts from utility companies.
FAA Part 107 waivers and EASA-specific drone operational certificates shape product design requirements for beyond-visual-line-of-sight flights over critical infrastructure. OSHA fall-protection mandates and the EU Green Deal's embedded lifecycle monitoring provisions are hardening inspection frequency standards across regulated markets. Stakeholders must weigh autonomous technology readiness against evolving airspace integration rules that will determine which platform architectures achieve scalable deployment.
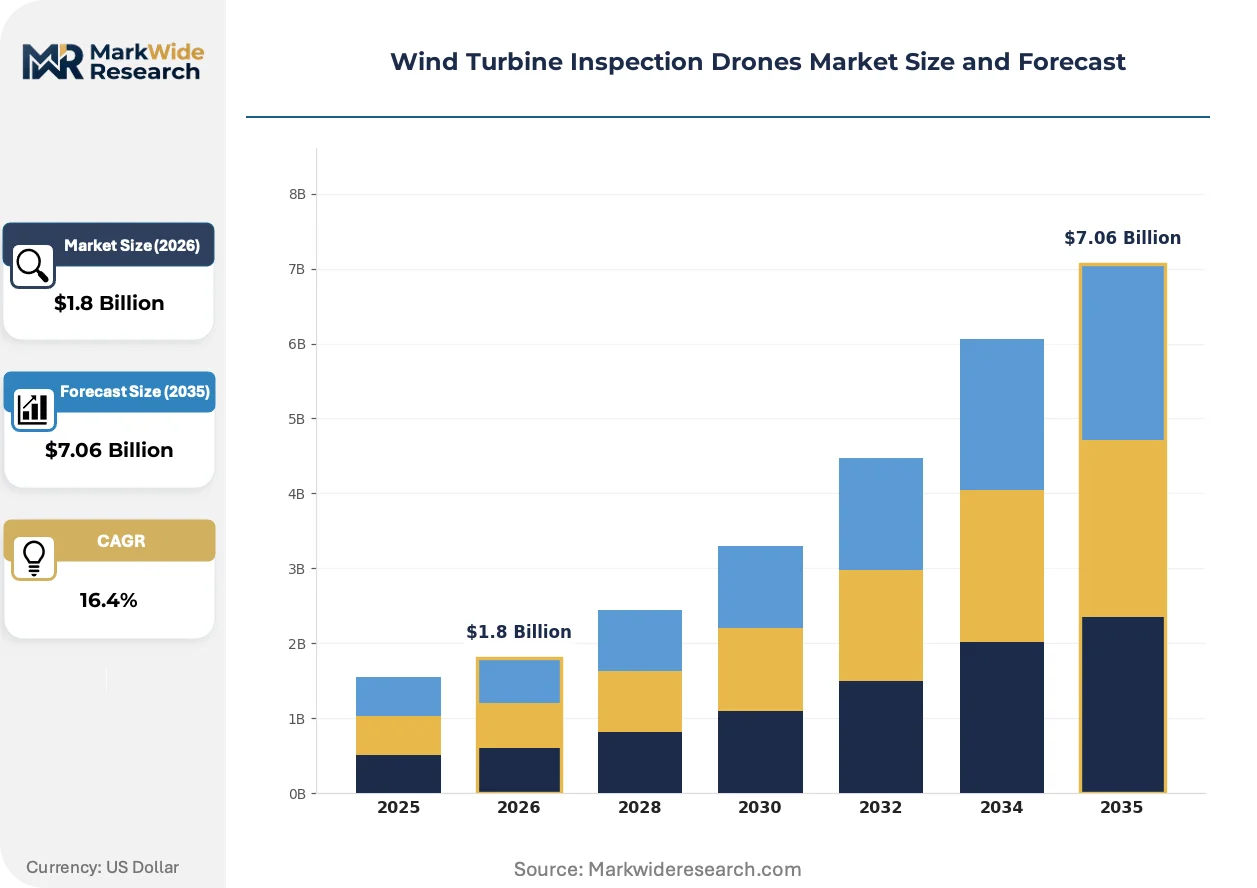
Market Dynamics
Autonomous navigation systems are compressing inspection timelines from days to hours, forcing operators to choose between pilot-dependent service contracts and capital-intensive in-house drone fleets with docking stations.
Growth Catalysts
- EU Green Deal lifecycle monitoring mandates:Embedded carbon accounting rules require documented blade condition assessments at prescribed intervals, creating recurring revenue streams for inspection service providers.
- Offshore wind capacity expansion:Floating turbine installations in deeper waters exceed human rope-access safety limits, mandating robotic alternatives for structural integrity verification.
- Sub-millimeter photogrammetry:Advances in optical resolution enable early-stage leading-edge erosion detection that prevents catastrophic blade failure and extends operational life.
Market Restraints
- LiDAR sensor cost volatility:Semiconductor supply constraints and rare-earth magnet dependencies inflate payload costs for precision mapping systems.
- Beyond-visual-line-of-sight certification friction:FAA Part 107 waiver processing delays and EASA-type certificate complexity extend deployment timelines for autonomous platforms.
- Fixed-wing range limitations:Battery energy density constraints restrict flight duration for linear array inspections across sprawling onshore complexes.
Strategic Opportunities
- India's renewable capacity auctions:State-level wind park tenders with bundled O&M provisions create entry points for drone-as-a-service operators in emerging markets.
- Digital twin convergence:Integration of inspection data with structural simulation platforms enables predictive maintenance contracts that command premium pricing.
- Utility direct procurement channels:Bypassing traditional inspection intermediaries allows manufacturers to capture full hardware margins and recurring software licensing revenue.
Industry Challenges
- Autonomous systems engineering talent scarcity:Shortages in computer vision specialists and flight control firmware developers constrain R&D velocity for platform developers.
- Airspace integration complexity:Multi-jurisdictional UTM system fragmentation forces redundant compliance investments for cross-border service operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Inspection Drones Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Fixed-wing, Hybrid, Gas-powered Technology: GPS, LiDAR, Thermal Imaging, Optical Sensors End User: Utility Companies, Project Developers, Service Providers, Inspection Firms Deployment Model: Onshore, Offshore, Autonomous, Remote-operated |
| Companies Covered | Cyberhawk Innovations Limited, Percepto Ltd., SZ DJI Technology Co., Ltd., Sharper Shape Oy, PrecisionHawk, Inc., AeroVironment, Inc., Delair SAS, senseFly, SkySpecs, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Inspection Drones Market Strategic Shifts
Inspection workflows are digitizing around continuous data streams rather than episodic manual surveys, redefining asset management from reactive repair to predictive intervention.
LiDAR-enabled blade geometry mapping is expanding into standard maintenance protocols across German and Danish offshore operators. Utility engineering departments now specify three-dimensional structural fatigue modeling as a contract deliverable, compressing the sales cycle for integrated sensor-platform bundles. This capability displacement is marginalizing photogrammetry-only vendors in premium contract competitions.
REACH chemical compliance and the EU AI Act's high-risk system classification are reshaping hardware material selection and algorithmic transparency requirements. Manufacturers must document sensor coating composition and defect detection model training data provenance. Offshore certification bodies in the North Sea region are embedding these standards into type approval processes ahead of formal enforcement dates.
Buyer consolidation among European utility majors is compressing vendor qualification cycles and favoring multi-year fleet management agreements over transactional inspection orders. Procurement teams now mandate API-accessible data formats and centralized dashboard integration. This behavioral shift is most visible in Germany's aging onshore wind belt, where RWE and EnBW have standardized on single-vendor drone ecosystems across their combined portfolios.
Wind Turbine Inspection Drones Market Segmentation
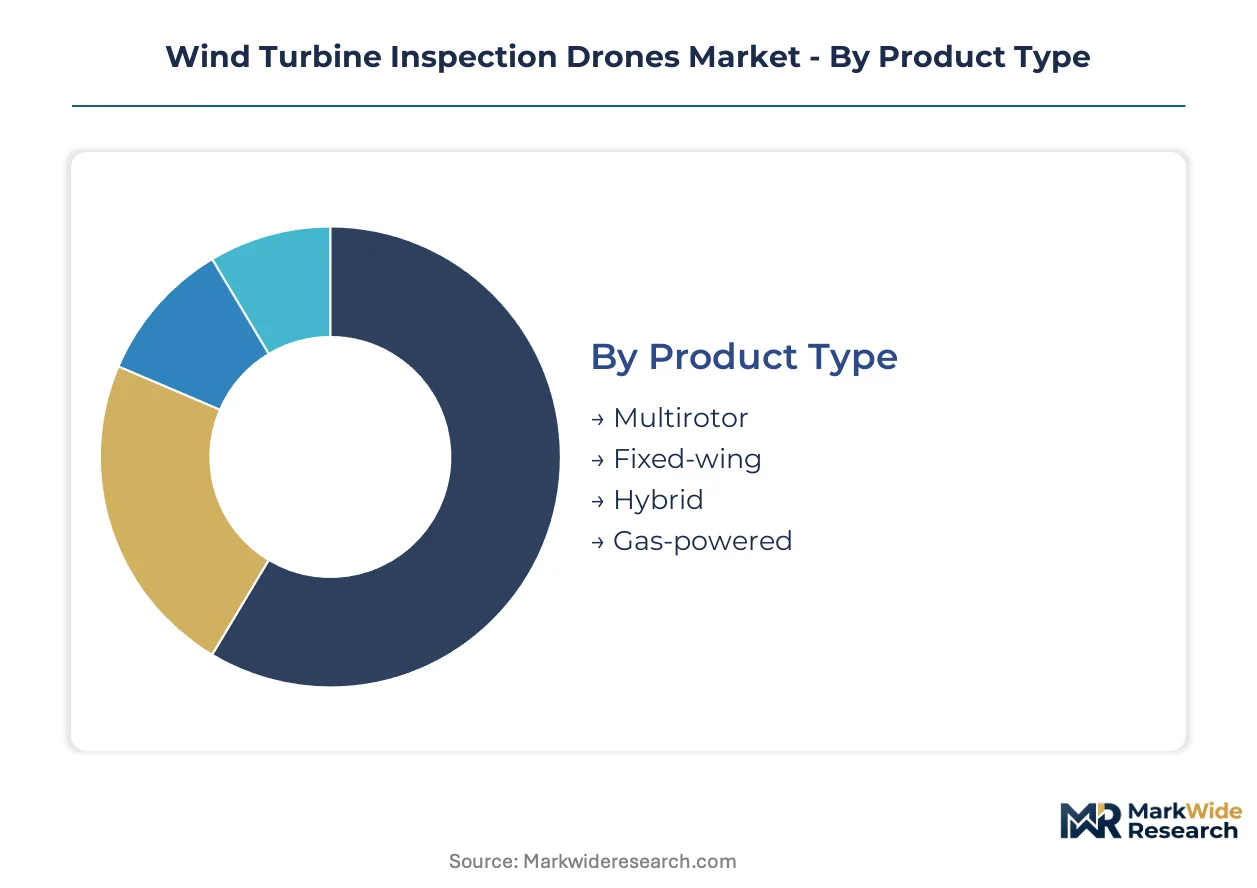
Platform architecture choices determine inspection economics across wind farm scale and complexity. Payload integration and operational modality decisions cascade through procurement budgets, regulatory compliance pathways, and maintenance contract structures.
Product Type:
Buyer procurement teams weight maneuverability precision against flight endurance when selecting airframe configurations for specific turbine array layouts.
- Multirotor:Vertical takeoff and landing capability with six or eight rotor configurations enables centimeter-scale positioning near blade surfaces in turbulent offshore conditions. German North Sea operators specify these platforms for lightning receptor and leading-edge erosion surveys where hovering stability outweighs range constraints.
- Fixed-wing:Extended linear range suits sprawling onshore complexes in Texas and Iowa where turbines sit kilometers apart across agricultural terrain. Battery energy density limitations restrict mission duration, forcing operators to stage multiple units or accept segmented inspection schedules.
- Hybrid:Tilt-rotor designs combine VTOL convenience with fixed-wing cruise efficiency for transitional wind farm topologies.
- Gas-powered:Internal combustion endurance extends range for remote installations beyond reliable battery swap infrastructure.
Volume sits with Multirotor platforms; growth tilts toward Hybrid configurations as operators seek unified fleets for mixed onshore-offshore portfolios.
Technology:
Sensor payload selection now precedes airframe procurement in utility engineering specifications, with data deliverable requirements driving hardware configurations.
- LiDAR:Pulsed laser systems generate three-dimensional blade geometry maps that feed structural fatigue models. Danish offshore operators mandate this capability for predictive maintenance contracts, displacing photogrammetry-only vendors in premium competitions.
- Thermal Imaging:Infrared detectors identify adhesive joint delamination and internal blade defects through surface temperature differentials. Demand concentrates in aging onshore fleets where subsurface damage exceeds visible erosion thresholds.
- Optical Sensors:Sub-millimeter resolution cameras remain standard for routine leading-edge condition documentation.
- GPS:Differential positioning systems enable centimeter-accurate defect georeferencing for maintenance crew dispatch.
LiDAR commands premium pricing tiers; Thermal Imaging expands most quickly as aging European fleets accelerate replacement cycles.
End User:
Procurement centralization among utility majors is compressing vendor qualification cycles and favoring multi-year fleet management agreements over transactional orders.
- Service Providers:Independent inspection firms consolidate vendor relationships to secure utility maintenance contracts, driving volume demand for modular hardware ecosystems that accommodate regional wind farm conditions.
- Utility Companies:Direct procurement channels allow RWE and EnBW to standardize on single-vendor drone ecosystems across combined portfolios, capturing full hardware margins and recurring software licensing revenue.
- Inspection Firms:Specialized operators seek API-accessible data formats and centralized dashboard integration for multi-client reporting.
- Project Developers:Construction-phase commissioning inspections create episodic demand for certified platforms with EASA-type approval documentation.
Service Providers anchor current procurement volume; Utility Companies represent the steepest expansion trajectory as direct channel strategies displace intermediaries.
Deployment Model:
Operational modality selection determines regulatory compliance burden and pilot dependency economics across inspection programs.
- Autonomous:Docking station systems with AI-powered defect classification eliminate pilot dependency for routine blade surveys. FAA Part 107 waiver processing delays and EASA-type certificate complexity currently constrain scalable deployment despite technical readiness.
- Offshore:Floating turbine installations in deeper waters exceed human rope-access safety limits, mandating robotic alternatives where BVLOS certification depth anchors vendor selection criteria.
- Onshore:Visual-line-of-sight operations dominate aging fleet monitoring in Germany's wind belt where regulatory familiarity reduces deployment friction.
- Remote-operated:Pilot-dependent service contracts persist where capital constraints prevent docking station investment or where inspection frequency remains too low to amortize autonomous infrastructure.
Remote-operated deployments retain volume dominance; Autonomous systems gain share fastest as airspace integration rules mature and docking station costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European drone certification activity through its cluster of offshore wind engineering consultancies and EASA-approved testing facilities. The concentration of blade inspection service providers along the Elbe corridor shapes procurement patterns for North Sea operators.
Germany
Aging onshore wind fleets in Lower Saxony and Schleswig-Holstein drive accelerated monitoring cycles for blade erosion and adhesive joint fatigue. The EU Green Deal's embedded lifecycle monitoring provisions mandate documented condition assessments at prescribed intervals. Hamburg-based service providers consolidate vendor relationships to capture multi-year fleet management contracts from RWE and EnBW.
United States
Sprawling onshore complexes across Texas and Iowa create demand for extended-range fixed-wing platforms that traverse agricultural terrain between turbine arrays. FAA Part 107 waiver processing delays constrain beyond-visual-line-of-sight deployment timelines despite technical readiness. Oklahoma's wind corridor clusters inspection firms that customize modular hardware ecosystems for regional climate conditions.
Denmark
Danish offshore operators mandate LiDAR-enabled blade geometry mapping as a standard contract deliverable for predictive maintenance agreements. The country's national energy regulator enforces structural integrity verification protocols that exceed human rope-access safety limits. Copenhagen-area engineering departments specify three-dimensional fatigue modeling capabilities that displace photogrammetry-only vendors in premium competitions.
China
Dual carbon goals accelerate wind capacity auctions across coastal provinces, creating procurement volume for drone-as-a-service operators in emerging maintenance markets. The Ministry of Industry and Information Technology drafts unmanned aerial system standards that shape platform certification pathways. Yangtze River Delta manufacturing clusters produce modular payload components for both domestic deployment and export assembly.
United Kingdom
Floating turbine installations in Scottish waters exceed conventional access limits, mandating robotic inspection alternatives for structural verification. The country's aviation regulator coordinates with offshore certification bodies to embed REACH chemical compliance into type approval processes. Aberdeen's energy transition corridor attracts autonomous docking station deployments that eliminate pilot dependency for routine blade surveys.
Wind Turbine Inspection Drones Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and sensor integration sophistication. The sector organizes around three strategic archetypes: offshore-certified specialists with EASA-type approval documentation, modular hardware ecosystem providers that accommodate regional customization, and fully autonomous platform developers with docking station infrastructure. Consolidation pressures favor multi-year fleet management agreements over transactional inspection orders. Strategic moves concentrate on vendor qualification compression and API-accessible data format standardization.
Within the offshore-certified tier, Cyberhawk Innovations Limited and Percepto Ltd. occupy positions that exemplify divergent automation philosophies. SZ DJI Technology Co., Ltd. anchors the volume-driven modular hardware segment through its Shenzhen-based manufacturing scale. These three entities represent the spectrum from pilot-dependent service architectures to fully autonomous systems with eliminated human-in-the-loop requirements.
| Leading Market Players |
|---|
| Cyberhawk Innovations Limited |
| Percepto Ltd. |
| SZ DJI Technology Co., Ltd. |
| Sharper Shape Oy |
| PrecisionHawk, Inc. |
| AeroVironment, Inc. |
| Delair SAS |
| senseFly |
| SkySpecs, Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up inspection service specialists anchor supply discipline through multi-year fleet standardization mandates that compress vendor pricing power across European utility portfolios. Their consolidated procurement volume forces hardware manufacturers into software-bundled subscription structures that lock in recurring revenue against commodity margin erosion.
Pricing Analysis
Outcome-based pricing tied to turbine uptime guarantees anchors premium tiers for autonomous docking station deployments with AI-powered defect classification. Three-tier pricing structure across premium, standard, and economy levels separates EASA-type-certified offshore platforms from modular remote-operated units and bare-hardware commodity configurations. Cost compression in the standard tier intensifies because SZ DJI Technology Co., Ltd.'s manufacturing scale floods service provider channels with interchangeable payload modules. Service providers exhibit acute price sensitivity due to thin inspection contract margins, while utility direct procurement teams prioritize total-cost-of-ownership over unit hardware costs.
Supply Chain Analysis
Freight costs for LiDAR sensor modules from Germany and thermal imaging cores from the United States inflate landed costs for Asian platform assemblers serving European offshore markets. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan; rare-earth magnet processing for precision gimbal motors draws from China and Vietnam. Single-source vulnerability in pulsed laser emitter components threatens delivery timelines for Danish and German operators mandating three-dimensional blade geometry mapping. Distribution runs through Hamburg-based engineering consultancies that bundle hardware procurement with EASA certification consulting for North Sea wind farm developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous navigation systems with eliminated pilot dependency are displacing legacy remote-operated service contracts, compressing deployment timelines from days to hours and restructuring competitive advantage around docking station infrastructure ownership.
For Market Incumbents: Extend EASA-type certification depth into emerging floating turbine markets through Aberdeen and Copenhagen engineering partnerships that preempt regulatory fragmentation. Anchor vendor lock-in through API-accessible data format standardization that complicates multi-platform procurement for utility majors. Vertical integration into predictive maintenance software licensing captures recurring revenue streams as hardware margins commoditize. For New Entrants and Emerging Players: EU Green Deal lifecycle monitoring mandates in Germany open a window for drone-as-a-service operators targeting aging onshore fleets in Lower Saxony and Schleswig-Holstein where inspection frequency standards harden. India's state-level wind park tenders with bundled O&M provisions present the most penetrable geography for capital-light service models. A direct utility sales channel bypassing Hamburg-based inspection intermediaries accelerates vendor qualification compression. For Investors and Strategic Acquirers: Distressed-cycle entries favor autonomous platform developers with deployed docking station networks in Scottish floating wind corridors where BVLOS certification friction has constrained scalable deployment despite technical readiness. Long-term viability hinges on airspace integration rule maturation rather than hardware differentiation alone. Watch FAA Part 107 waiver processing velocity as the inflection signal for North American autonomous system penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Docking Station Deployment | Eliminates pilot dependency for routine blade surveys across RWE and EnBW portfolios. |
| LiDAR Sensor Integration Partnership | Feeds three-dimensional fatigue models that Danish operators mandate for predictive contracts. |
| EASA-Type Certification Acceleration | Compresses vendor qualification cycles for North Sea floating turbine installations. |
| Digital Twin Platform Convergence | Enables predictive maintenance contracts commanding premium pricing from utility engineering departments. |
| Direct Utility Procurement Channel | Captures full hardware margins and recurring software licensing revenue from bypassed intermediaries. |
Study Parameters
Independent corroboration across primary interviews with wind farm operations directors, EASA certification consultants, and utility procurement managers, combined with secondary validation through FAA waiver processing databases, EU Green Deal implementation trackers, and offshore wind project development registries, underwrites the qualitative findings. Bottom-up triangulation against manufacturer shipment disclosures and top-down reconciliation with utility capital expenditure filings anchor volume estimates. Stakeholder conversations spanned Hamburg-based service providers, Copenhagen engineering departments, and Oklahoma inspection firm clusters.
Comparable-period anchoring to historical inspection frequency standards and platform deployment timelines across the analysis window structures the forecast framework. Segmentation dimensions modeled include platform architecture, sensor payload technology, operational modality, and end-user procurement channel. CAGRs derive from utility fleet expansion trajectories, regulatory mandate phase-in schedules, and autonomous technology readiness curves. Forecast inputs incorporate battery energy density improvement assumptions and semiconductor supply constraint persistence.
The model assumes a particular technology adoption path; alternative pathways for beyond-visual-line-of-sight airspace integration would alter the outlook. Forecasts reflect assumptions about EASA-type certificate processing efficiency and FAA waiver approval velocity that regulatory backlog could revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Solar EPC Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Solar Showers Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Hybrid Solar Wind System Market