
 DC Coupled Solar Battery System Market | 2026-2036
DC Coupled Solar Battery System Market Size, Share, and Industry Trends Forecast 2026-2036
DC Coupled Solar Battery System Market Insights
The gap between premium high-voltage architectures and commodity low-voltage entry systems is broadening as installation complexity and inverter compatibility requirements diverge. LG Energy Solution leverages its cell-to-pack expertise to anchor the premium residential segment across North American and European markets. BYD competes through integrated module-battery combinations that reduce balance-of-system costs for commercial installers. Pylontech specializes in stackable low-voltage racks that dominate price-sensitive residential retrofits in emerging solar markets.
A DC coupled solar battery system connects battery storage directly to the photovoltaic array on the direct current side, eliminating the efficiency losses of alternating current conversion stages and typically achieving round-trip efficiencies above ninety percent. The primary purpose centers on maximizing self-consumption of generated solar power while providing backup resilience during grid outages. Lithium-ion chemistries occupy the dominant product type position due to declining cell costs and established recycling infrastructure. The 5-10 kWh capacity band leads residential attachment rates where average household daily consumption patterns align with overnight discharge cycles. Utility end users represent the fastest-growing installation type segment as grid operators procure front-of-meter storage for frequency regulation and peak shaving services.
The EU Green Deal and F-Gas Regulation shape European product standards by restricting fluorinated greenhouse gases in thermal management systems, while the Inflation Reduction Act's standalone storage investment tax credit drives United States demand independent of solar co-location requirements. China's GB standards and MIIT circulars enforce domestic cell safety testing protocols that constrain import eligibility for non-certified manufacturers. Stakeholders must monitor how divergent certification timelines across EPA, ECHA, and SAMR jurisdictions affect product launch sequencing and regional inventory positioning.
Market Dynamics
Installer certification bottlenecks and inverter interoperability standards are fragmenting competitive positioning between integrated system providers and modular component suppliers across residential and utility-scale deployment channels.
Growth Catalysts
- EU Green Deal storage mandates:Germany's national building efficiency codes now require battery-ready solar inverters for all new residential retrofits, creating immediate pull-through for DC coupled architectures.
- Lithium-ion cell cost curves:Pack-level economics below residential payback thresholds are electrifying attachment rates in Australia and the southwestern United States where time-of-use arbitrage values peak.
- Utility frequency regulation procurement:Grid operators in Texas and California are contracting front-of-meter DC coupled systems for synthetic inertia services, bypassing AC conversion losses in stacked solar-plus-storage plants.
Market Restraints
- Fluorinated gas thermal management constraints:The EU F-Gas Regulation restricts hydrofluorocarbon-based cooling systems, forcing redesign cycles for high-voltage battery enclosures targeting European certification.
- Cell supply concentration:Cathode precursor refining capacity clusters in China's Jiangxi and Hunan provinces, exposing non-integrated system assemblers to export license volatility under MIIT circular enforcement.
- AC microgrid legacy lock-in:Existing commercial and industrial sites with installed hybrid inverters face stranded asset risk when upgrading to native DC coupled topologies, depressing retrofit velocity.
Strategic Opportunities
- India's CEA distribution network codes:Mandatory storage procurement obligations for renewable energy generators create first-mover positioning for DC coupled systems in Gujarat and Rajasthan solar parks.
- Vehicle-to-home convergence:Bidirectional EV charging standards (CHAdeMO, CCS) are enabling DC coupled home energy hubs that arbitrage between stationary batteries and automotive packs.
- Direct-installer channel bypass:Module-level power electronics manufacturers are building certified installer networks that disintermediate traditional electrical distributors in price-sensitive retrofit markets.
Industry Challenges
- Multi-jurisdiction certification sequencing:UL 9540A fire safety testing, IEC 62619 cell safety validation, and GB/T 36276 China grid compliance create 14-18 month product launch timelines that compress working capital cycles.
- Legacy SCADA integration complexity:Utility-scale DC coupled deployments must bridge proprietary battery management system protocols with existing DMS/OMS infrastructure, requiring custom middleware development.
- Electrochemical technician scarcity:Safe handling of lithium-ion thermal runaway events demands specialized training that outpaces vocational program output in Germany, Australia, and the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC Coupled Solar Battery System Market |
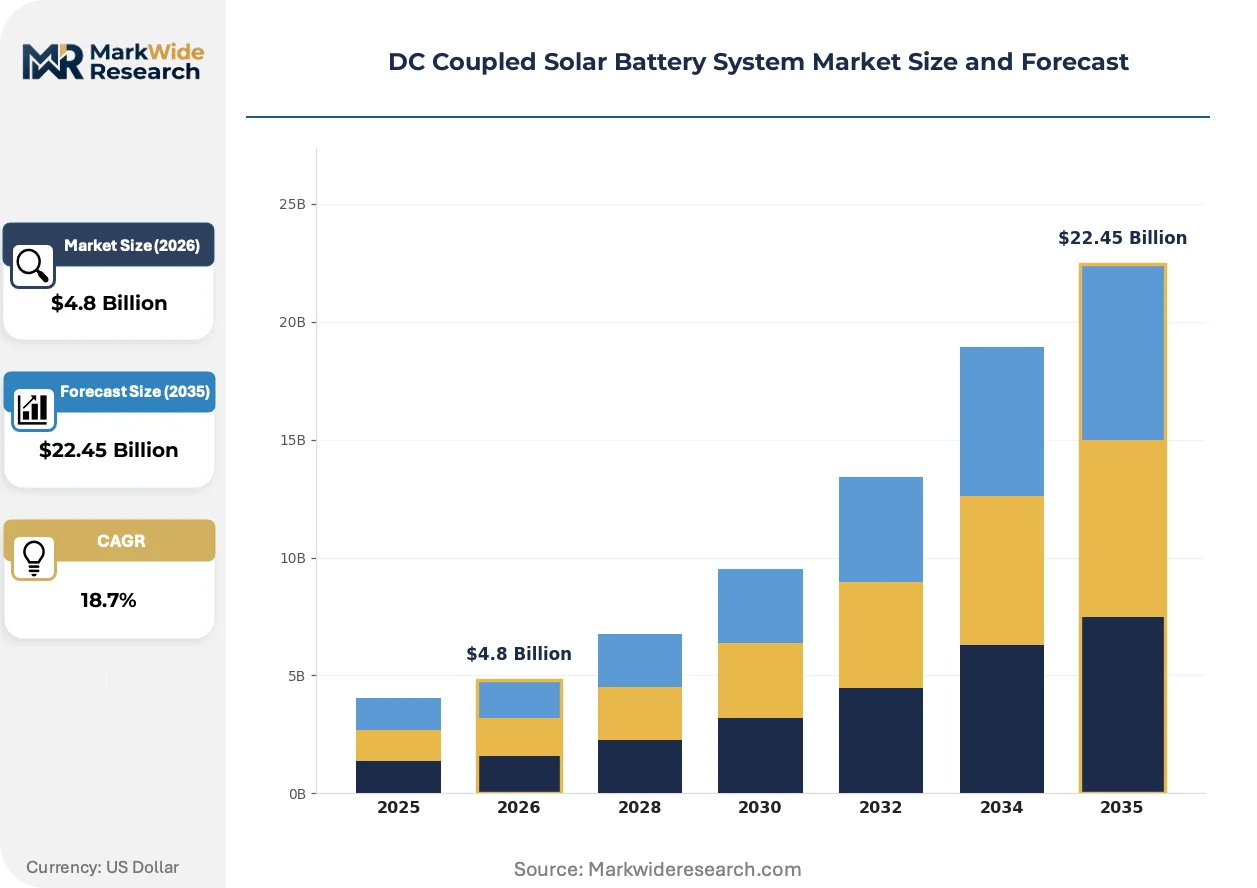
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Flow battery, Saltwater battery Installation Type: On-grid, Off-grid, Hybrid, Portable End User: Residential, Commercial, Industrial, Utilities Capacity: Below 5 kWh, 5-10 kWh, 10-20 kWh, Above 20 kWh |
| Companies Covered | LG Energy Solution, BYD, Huawei, Panasonic, Generac, Pylontech, SimpliPhi Power, SolarEdge, CATL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC Coupled Solar Battery System Market Trends and Innovations
Solid-state cell architectures and silicon carbide power electronics are compressing system footprint while elevating round-trip efficiency benchmarks above incumbent lithium-ion and IGBT baselines.
Solid-state lithium-metal cells with ceramic electrolytes are electrifying premium residential system design by eliminating thermal propagation risks that constrain pack density in conventional NMC configurations. High-net-worth homeowners in California and Bavaria are specifying these systems for indoor garage installations where fire code restrictions previously excluded battery storage. The technology is electrifying margin structures at the top of the product pyramid while forcing commodity lithium-ion suppliers toward aggressive cost positioning in the mid-market.
The United States Inflation Reduction Act's standalone storage investment tax credit is decoupling battery procurement from solar co-location requirements, enabling pure-play DC coupled retrofits on existing PV arrays. This policy architecture is accelerating third-party ownership models where financiers capture tax equity while homeowners retain operational benefits. Commercial installers in Texas and Florida are restructuring product offerings around this incentive geometry, prioritizing DC coupled compatibility in new vendor qualification protocols.
Aggregator-led virtual power plant enrollment is displacing direct utility interconnection as the dominant procurement pathway for residential battery owners. Homeowners in South Australia and Germany are prioritizing systems with pre-certified VPP software stacks over raw hardware specifications, compressing vendor selection criteria toward platform interoperability. This behavioral shift is most visible in markets where distribution network operators actively procure aggregated capacity for peak shaving and voltage support services.
DC Coupled Solar Battery System Market Segmentation
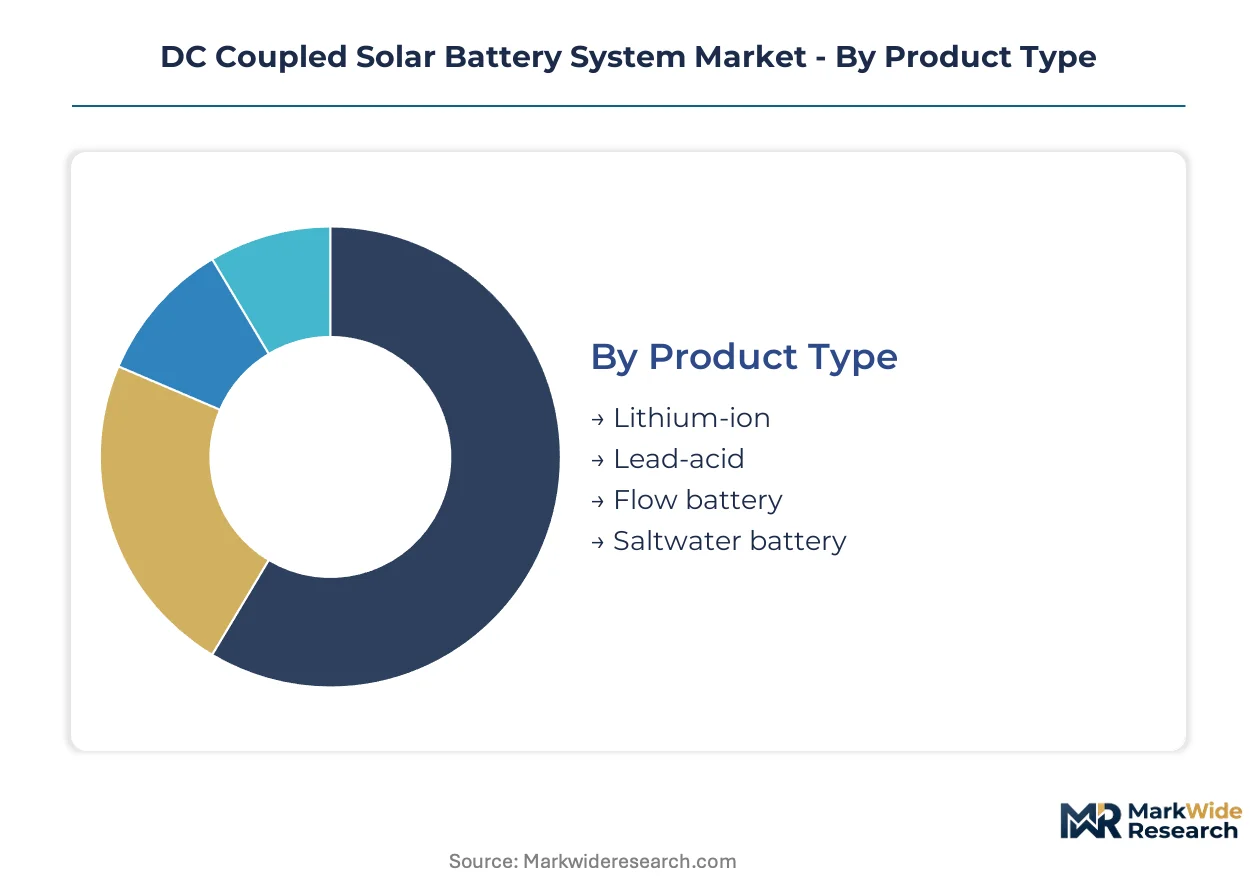
DC coupled solar battery systems fragment across chemistry, scale, and grid-interaction modes, each configuration demanding distinct inverter protocols and installation workflows. Upgrade cycles for existing solar arrays create natural replacement windows where chemistry shifts and capacity expansions reshape vendor positioning.
Product Type:
Replacement timelines for first-generation solar-plus-storage installations are compressing as cell degradation curves and warranty expirations trigger chemistry reconsideration.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cells dominate new installations with energy densities above 150 Wh/kg and established recycling pathways through Redwood Materials and Li-Cycle networks. Residential retrofits in Germany and Australia concentrate pull for NMC configurations where space constraints matter; LFP variants capture utility-scale procurement in Texas and California where cycle life economics override footprint concerns.
- Lead-acid:Flooded and valve-regulated designs persist in off-grid rural electrification projects across India and sub-Saharan Africa where capital constraints outweigh efficiency penalties. The chemistry's tolerance for partial state-of-charge operation suits intermittent solar resource profiles in Rajasthan and Gujarat solar parks where maintenance access remains limited.
- Flow battery:Vanadium redox configurations from Invinity Energy Systems and CellCube address multi-hour discharge requirements at commercial and utility scale.
- Saltwater battery:Aquion and Blue Planet Energy designs serve environmentally sensitive coastal installations where thermal runaway risks are unacceptable.
Volume placements concentrate in lithium-ion configurations; the faster expansion belongs to flow battery architectures in front-of-meter frequency regulation contracts.
Installation Type:
Cost tier stratification separates hardware-light portable units from capital-intensive hybrid systems requiring dual-mode inverters and grid-forming capabilities.
- On-grid:Systems without islanding capability prioritize export limitation and self-consumption maximization through DC coupling to existing string inverters. German and Australian installers favor this architecture for retrofit economics where backup resilience is not valued; California's NEM 3.0 export compensation structures are accelerating attachment rates as homeowners seek to arbitrage time-of-use rate differentials.
- Off-grid:Standalone configurations with dedicated charge controllers and battery management systems serve remote mining camps and telecommunications infrastructure across Western Australia and the Canadian Arctic. The segment demands oversized solar arrays and battery banks to cover multiple days of autonomy, compressing lithium-ion cost curves toward viability thresholds previously occupied by diesel generation.
- Hybrid:Grid-tied systems with seamless islanding capability command premium pricing for transfer switch integration and UL 1741 compliance.
- Portable:Briefcase-scale lithium-ion packs with MC4 solar input connectors target recreational vehicle and emergency preparedness markets.
Cost tier concentration favors on-grid installations; the steepest expansion trajectory belongs to hybrid systems in hurricane-prone Florida and Texas markets.
End User:
Customer type determines procurement channel structure, with utilities negotiating multi-year framework agreements while residential buyers navigate certified installer networks.
- Residential:Single-family and multi-family installations concentrate in 5-10 kWh capacity bands matching overnight consumption patterns. German building efficiency codes and South Australian VPP enrollment incentives are accelerating attachment rates; California's SGIP rebate program structures favor DC coupled architectures over AC battery alternatives for existing PV host customers.
- Commercial:Retail, hospitality, and light manufacturing facilities deploy 50-200 kWh systems for demand charge management and backup power. The segment favors modular rack configurations from BYD and Pylontech that scale with facility expansion; Texas and Arizona time-of-use structures create compelling payback periods for behind-the-meter storage.
- Industrial:Heavy manufacturing and cold storage facilities specify megawatt-hour scale systems for process continuity and grid services participation.
- Utilities:Front-of-meter deployments for synthetic inertia and frequency regulation concentrate in ERCOT and CAISO territories.
Customer type volume concentrates in residential retrofits; utility-scale procurement is climbing the fastest as grid operators contract stacked solar-plus-storage plants.
Capacity:
Application maturity separates established below-5 kWh segments from emerging above-20 kWh utility-scale configurations where supply chains and installation protocols remain unsettled.
- Below 5 kWh:Compact lithium-ion packs suit apartment balconies and small off-grid cabins where space constraints and load profiles limit storage requirements. The segment competes with portable power stations and sees strongest demand in Japanese urban markets where rooftop solar penetration meets strict building code limitations.
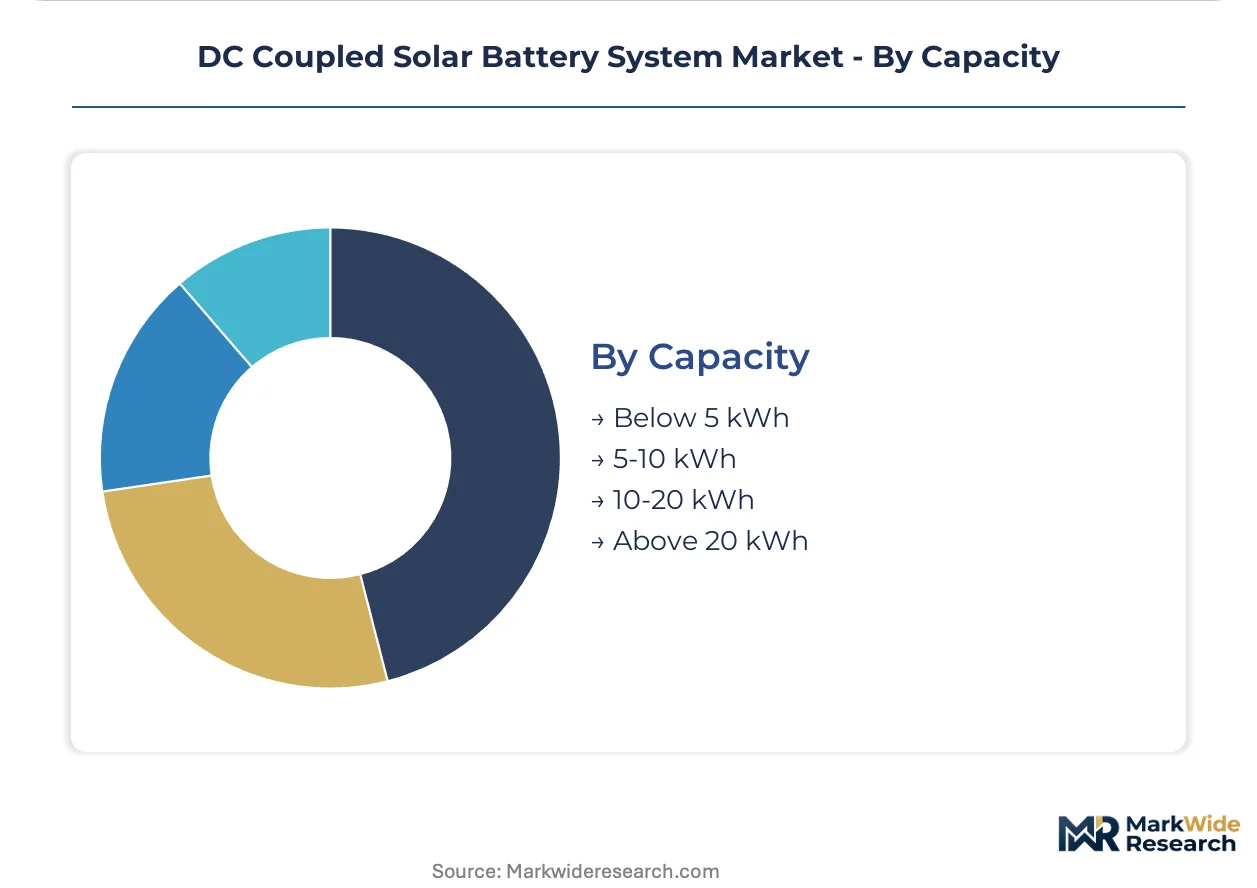
- 5-10 kWh:Single-phase residential systems align with average household daily consumption and overnight discharge cycles. This band captures the highest attachment rates in German and Australian markets where solar self-consumption economics drive purchase decisions; stackable rack designs from Pylontech and BYD dominate price-sensitive procurement.
- 10-20 kWh:Large residential and small commercial installations address extended backup requirements and electric vehicle pre-wiring.
- Above 20 kWh:Three-phase commercial and utility-scale configurations require containerized enclosures and sophisticated thermal management.
Application maturity favors the 5-10 kWh band; above-20 kWh systems are gaining share fastest as Texas and California utilities procure front-of-meter capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors manufacturing gravity for DC coupled battery systems, with the Pearl River Delta cluster supplying cell-to-pack assemblies that flow through Port of Shenzhen to Australian and German distribution channels.
United States
Texas ERCOT grid operators procure front-of-meter DC coupled capacity for synthetic inertia services while California's NEM 3.0 export structures accelerate residential retrofit attachment rates. The Inflation Reduction Act's standalone storage investment tax credit decouples battery procurement from solar co-location requirements. Installers in Houston and Dallas-Fort Worth metroplexes restructure product offerings around this incentive geometry.
Germany
Residential retrofit installations accelerate across Bavaria and North Rhine-Westphalia driven by national building efficiency codes mandating battery-ready solar inverters. The EU Green Deal's storage mandates and F-Gas Regulation restrictions on fluorinated thermal management systems reshape product certification requirements. Munich-based engineering consultancies specialize in high-voltage enclosure redesign cycles for European market entry.
Australia
South Australian virtual power plant enrollment displaces direct utility interconnection as the dominant procurement pathway for residential battery owners. Time-of-use arbitrage values in Queensland and New South Wales peak during summer evening demand periods. Brisbane installers prioritize systems with pre-certified VPP software stacks over raw hardware specifications.
China
Domestic GB standards and MIIT circulars enforce cell safety testing protocols that constrain import eligibility for non-certified manufacturers. Cathode precursor refining capacity clusters in Jiangxi and Hunan provinces expose assemblers to export license volatility. Shanghai and Shenzhen technology zones concentrate battery management system firmware development for stacked solar-plus-storage plants.
DC Coupled Solar Battery System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across voltage architecture and installation complexity dimensions. The vendor base stratifies between integrated system providers and modular component suppliers, with inverter interoperability standards fragmenting competitive positioning across deployment channels. Three archetypes dominate: cell-to-pack specialists, integrated module-battery combiners, and stackable low-voltage rack fabricators. Capacity expansion and certified installer network development represent the dominant competitive moves.
Among Asia-Pacific-based manufacturers, LG Energy Solution, BYD, and CATL occupy distinct tier positions. LG Energy Solution exemplifies the premium residential archetype through cell-to-pack expertise. BYD represents integrated module-battery combination strategies that reduce balance-of-system costs. CATL anchors utility-scale procurement channels with containerized enclosure capabilities. Pylontech sits within the stackable low-voltage rack segment targeting price-sensitive residential retrofits.
| Leading Market Players |
|---|
| LG Energy Solution |
| BYD |
| Huawei |
| Panasonic |
| Generac |
| Pylontech |
| SimpliPhi Power |
| SolarEdge |
| CATL |
| Others |
Pricing and Supply Chain Analysis
The high-voltage-to-low-voltage certification ladder splits DC coupled battery procurement into parallel supply channels, with UL 9540A-tested premium systems commanding installer loyalty through warranty-backed performance guarantees while commodity low-voltage racks compete on balance-of-system cost reduction. This bifurcation concentrates margin capture among cell-to-pack specialists in South Korea and integrated module-battery assemblers in China, leaving price-sensitive residential retrofits to stackable rack fabricators sourcing from Shenzhen component markets.
Pricing Analysis
Value-based pricing anchored on round-trip efficiency guarantees and backup uptime commitments dominates premium residential segments, with price differentiation driven by IEC 62619 certification tier and after-sales service bundling. Cost compression in the low-voltage retrofit tier is intensifying because Pylontech and BYD are expanding certified installer networks that disintermediate traditional electrical distributors. Commercial buyers in Texas and California exhibit lowest price sensitivity due to time-of-use arbitrage payback calculations, while emerging market residential adopters in India prioritize per-kWh capital cost above performance metrics.
Supply Chain Analysis
Cathode precursor supply rests on Jiangxi and Hunan province refining capacity in China, with lithium carbonate feedstock drawing from Chile and Australia. NMC and LFP cell production clusters in South Korea and Japan, exposing non-integrated system assemblers to MIIT circular export license volatility. Single-source vulnerability concentrates in high-nickel cathode chemistries where Indonesian nickel processing expansion remains below battery-grade purity thresholds. Distribution runs through Port of Shenzhen to Australian and German distribution channels, with regional warehousing in Rotterdam and Los Angeles buffering certification timeline delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DC coupled solar battery market sits in a technology-transition phase where silicon carbide power electronics and solid-state lithium-metal architectures are displacing incumbent IGBT and conventional NMC configurations. Stakeholders must position around this chemistry and semiconductor substitution curve.
For Market Incumbents: To counter solid-state cell disruption from emerging Korean and Japanese suppliers, LG Energy Solution and CATL should deepen backward integration into cathode precursor refining and accelerate GB/T 36276 China grid compliance certification for utility-scale containerized systems. Captive supply of lithium carbonate and nickel sulfate reduces Jiangxi export license exposure. For New Entrants and Emerging Players: Direct-installer channel partnerships offer the most penetrable route into price-sensitive residential retrofit markets in India and Southeast Asia, bypassing established electrical distributor relationships. New entrants should target CEA-mandated storage procurement obligations in Gujarat and Rajasthan solar parks with modular low-voltage rack configurations certified for tropical climate operation. For Investors and Strategic Acquirers: Re-rating potential sits with vehicle-to-home convergence specialists given bidirectional EV charging standardization under CHAdeMO and CCS protocols. Long-term viability across the next decade favors platform-agnostic software stacks enabling virtual power plant aggregation, with pre-certified VPP enrollment rates in South Australia and Germany serving as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Refining | Captive supply of nickel sulfate and lithium carbonate reduces exposure to MIIT export license volatility in Jiangxi province. |
| Silicon Carbide Inverter Platform Development | Power electronics substitution above 650V elevates round-trip efficiency benchmarks and compresses thermal management footprint. |
| Virtual Power Plant Software Stack Certification | Pre-certified aggregation platforms unlock South Australian and German distribution network operator procurement contracts. |
| GB/T 36276 China Grid Compliance Investment | Mandatory domestic safety testing protocols constrain import eligibility and create first-mover positioning in utility-scale tenders. |
| Certified Installer Network Expansion | Direct channel bypass of electrical distributors captures margin in price-sensitive residential retrofit markets across emerging solar economies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility planning officers, EPC contractors, battery management system firmware developers, and certified installation network managers. EIA storage deployment databases, IEA renewable integration reports, FERC interconnection queue filings, and MIIT circular enforcement records provided demand-side validation. Bottom-up project pipeline aggregation across ERCOT and CAISO territories reconciled with top-down manufacturer shipment disclosures.
Data-stream reconciliation across the analysis window applied capacity-weighted averaging to utility-scale procurement announcements and residential attachment rate surveys. Segmentation dimensions modeled include chemistry configuration, voltage architecture tier, installation type, and regional regulatory framework cluster. CAGRs were derived from logistic diffusion curves fitted to historical deployment trajectories, with inverter interoperability standards and certification timeline lags incorporated as adoption friction parameters.
The model holds under stable lithium-ion cell cost curves and consistent ITC policy treatment; deviation in F-Gas Regulation enforcement stringency or MIIT export license suspension would shift regional deployment trajectories. A small set of named triggers—solid-state cell manufacturing scale-up, bidirectional EV charging mandate adoption, and virtual power plant platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Energy Storage Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
North America Battery Management System Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market