
 Battery Management Market | 2026-2036
Battery Management Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Management Market Outlook
The EU Battery Regulation is consolidating demand around traceable, repairable battery architectures across European automotive supply chains. Panasonic Corporation leverages its cylindrical cell expertise to sustain dominance in EV module integration. Robert Bosch GmbH anchors its position through embedded control software bundled with powertrain systems. Infineon Technologies AG differentiates via silicon carbide gate drivers paired with battery control ICs.
A battery management system orchestrates electrochemical cell monitoring, state-of-charge estimation, and thermal regulation through voltage sensing circuits typically resolving to within one millivolt, protecting lithium-ion packs from thermal runaway in high-density installations. Battery Monitoring Systems capture the largest installed base as fleet operators retrofit legacy energy storage assets with predictive maintenance capabilities. Solid-state technology segments attract premium engineering investment despite manufacturing immaturity, while Electric Vehicles application demand outpaces portable devices by order of cell count per system.
The EPA enforces lithium-ion recycling standards affecting end-of-life management system design in the United States, while China's MIIT mandates GB standard compliance for domestic battery passport data architecture. The EU Green Deal and REACH chemical restrictions further constrain electrolyte formulations and thermal interface materials eligible for CE-marked systems. Stakeholders must weigh regulatory divergence against platform standardization economics when selecting geographic deployment sequences.
Market Dynamics
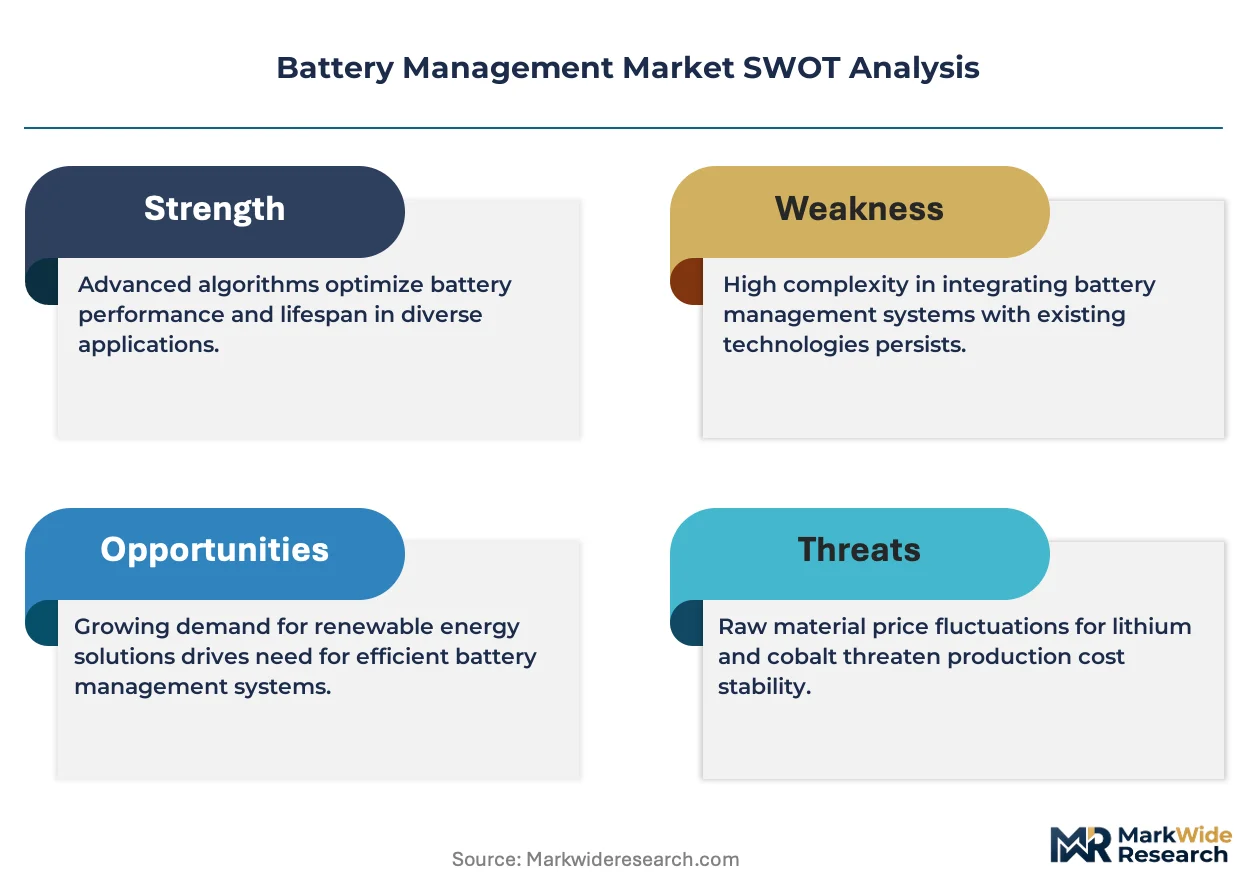
Cell-level safety mandates across automotive supply chains are forcing OEMs to embed predictive diagnostics deeper into battery architectures, redirecting R&D budgets from hardware miniaturization toward software-defined thermal management platforms.
Growth Catalysts
- EU Battery Passport:The EU Battery Regulation mandates traceable cell-level data architecture across European automotive supply chains, consolidating demand for integrated monitoring systems that can log electrochemical performance across full lifecycle.
- Solid-state prototyping:Engineering investment in solid-state battery formats requires redesigned management electronics capable of handling different thermal profiles and voltage characteristics than conventional lithium-ion architectures.
- Fleet retrofitting:Commercial vehicle operators in Germany, Japan, and South Korea are scaling battery monitoring deployments to extend asset life and meet insurer requirements for thermal runaway prevention documentation.
Market Restraints
- Silicon carbide supply concentration:Gate driver ICs using silicon carbide substrates face sourcing constraints from limited wafer fabrication capacity, creating bottlenecks for high-performance battery control modules.
- GB standard compliance costs:China's MIIT mandates domestic battery passport data architecture that diverges from EU formats, forcing parallel engineering tracks for multinational suppliers.
- Solid-state manufacturing immaturity:Low yields in ceramic electrolyte processing keep unit economics unfavorable, delaying volume deployment of next-generation cells that would drive management system refresh cycles.
Strategic Opportunities
- Second-life stationary storage:Retired EV batteries from early-generation Nissan and BMW fleets create demand for refurbished management systems that can recalibrate state-of-health algorithms for grid-tied applications.
- Silicon carbide and gallium nitride convergence:Pairing wide-bandgap semiconductors with advanced sensing circuits enables faster switching frequencies and tighter thermal loops in high-density pack configurations.
- India PLI scheme:Production-linked incentives for domestic cell manufacturing in Gujarat and Tamil Nadu are attracting control module suppliers to co-locate with emerging electrode and electrolyte facilities.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering for ASIL-D rated battery systems requires specialized expertise in ISO 26262 compliance that outpaces available training pipeline output.
- Legacy fleet integration friction:Retrofitting predictive maintenance capabilities into first-generation EV architectures with proprietary CAN bus protocols demands costly reverse-engineering of OEM communication stacks.
- Dual certification timelines:Simultaneous UL 1973 and UN 38.3 testing for energy storage and transportation applications extends product launch schedules by 8-14 months for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Management Market |
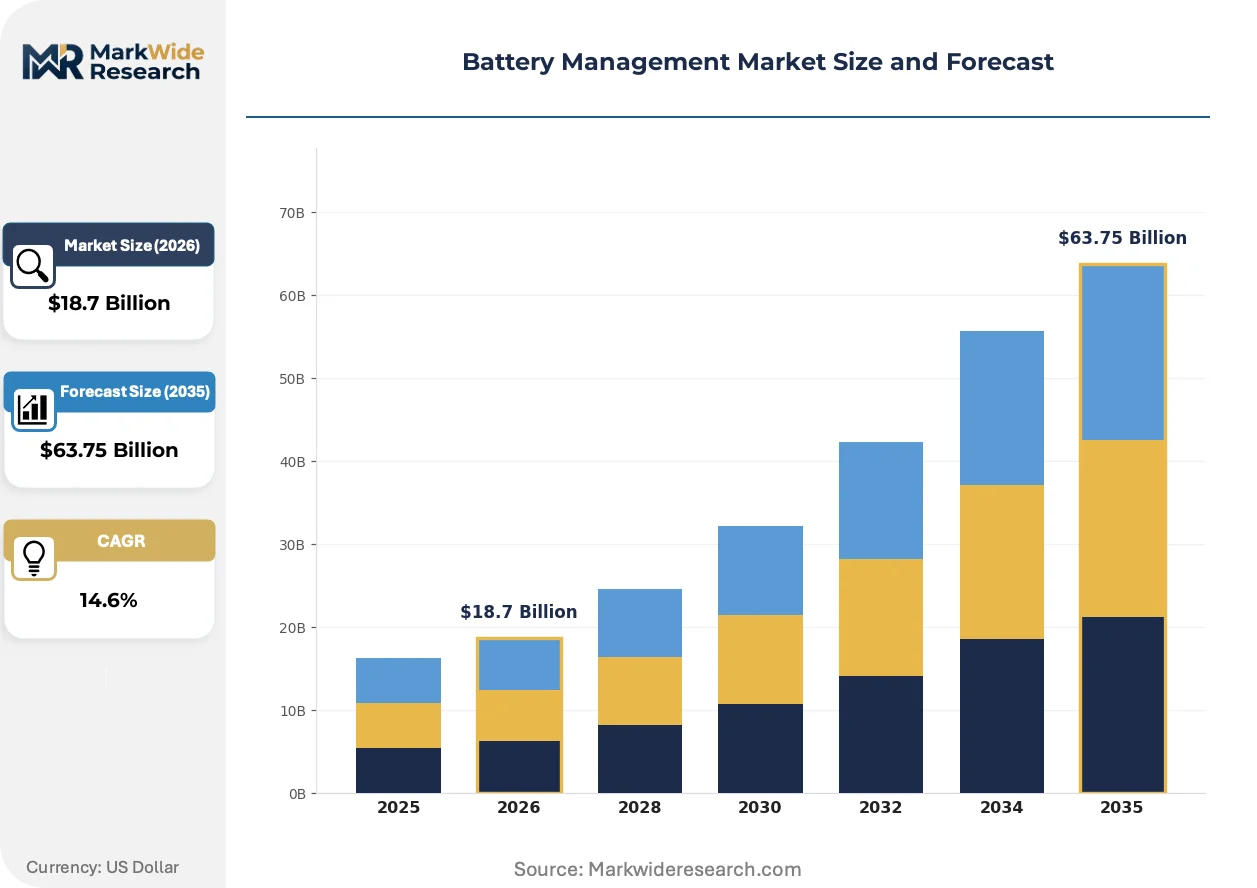
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Monitoring Systems, Battery Control Modules, Battery Balancing Systems, Battery Testing Equipment End User: Automotive, Renewable Energy, Consumer Electronics, Industrial Equipment Technology: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state Application: Electric Vehicles, Energy Storage Systems, Uninterruptible Power Supplies, Portable Devices |
| Companies Covered | LG Energy Solution, Contemporary Amperex Technology Co., Limited (CATL), Panasonic Corporation, Texas Instruments, Eberspächer, Sensata Technologies, Inc., Robert Bosch GmbH, Infineon Technologies AG, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Management Market Strategic Shifts
Predictive algorithms and wide-bandgap semiconductors are compressing the functional boundary between battery monitoring and active control, enabling real-time intervention that was previously limited to passive alarm states.
AI-driven state-of-health estimation is automating degradation pattern recognition across heterogeneous cell populations. Fleet operators with mixed-age battery assets are deploying these platforms to optimize charge scheduling and thermal conditioning. The technology is automating maintenance dispatch decisions that previously required manual technician review of voltage histograms.
REACH chemical restrictions and the EU Green Deal are constraining electrolyte formulations and thermal interface materials eligible for CE-marked systems. Manufacturers must reformulate flame-retardant encapsulants and phase-change materials to eliminate restricted substances. High-voltage automotive modules face the tightest substitution timelines as OEMs prepare for 2027 compliance checkpoints.
After-sales service unbundling is fragmenting the traditional bundled hardware-software procurement model. Independent service providers in China's Jiangsu province now source control modules separately from diagnostic software licenses, enabling customized algorithm stacks for specific cell chemistries. This pattern is compressing margin structures for integrated system suppliers while opening niche configuration opportunities for specialized software vendors.
Battery Management Market Segmentation
Battery management architectures fragment across electrochemical chemistries, powertrain integration depths, and lifecycle monitoring requirements. Each segment carries distinct certification burdens that reshape supplier qualification timelines and geographic deployment priorities.
Product Type:
UL 1973 and UN 38.3 certifications dominate high-voltage modules, while portable monitoring systems face lighter IEC 62619 requirements. Automotive-grade control electronics must additionally satisfy ISO 26262 ASIL-D functional safety mandates.
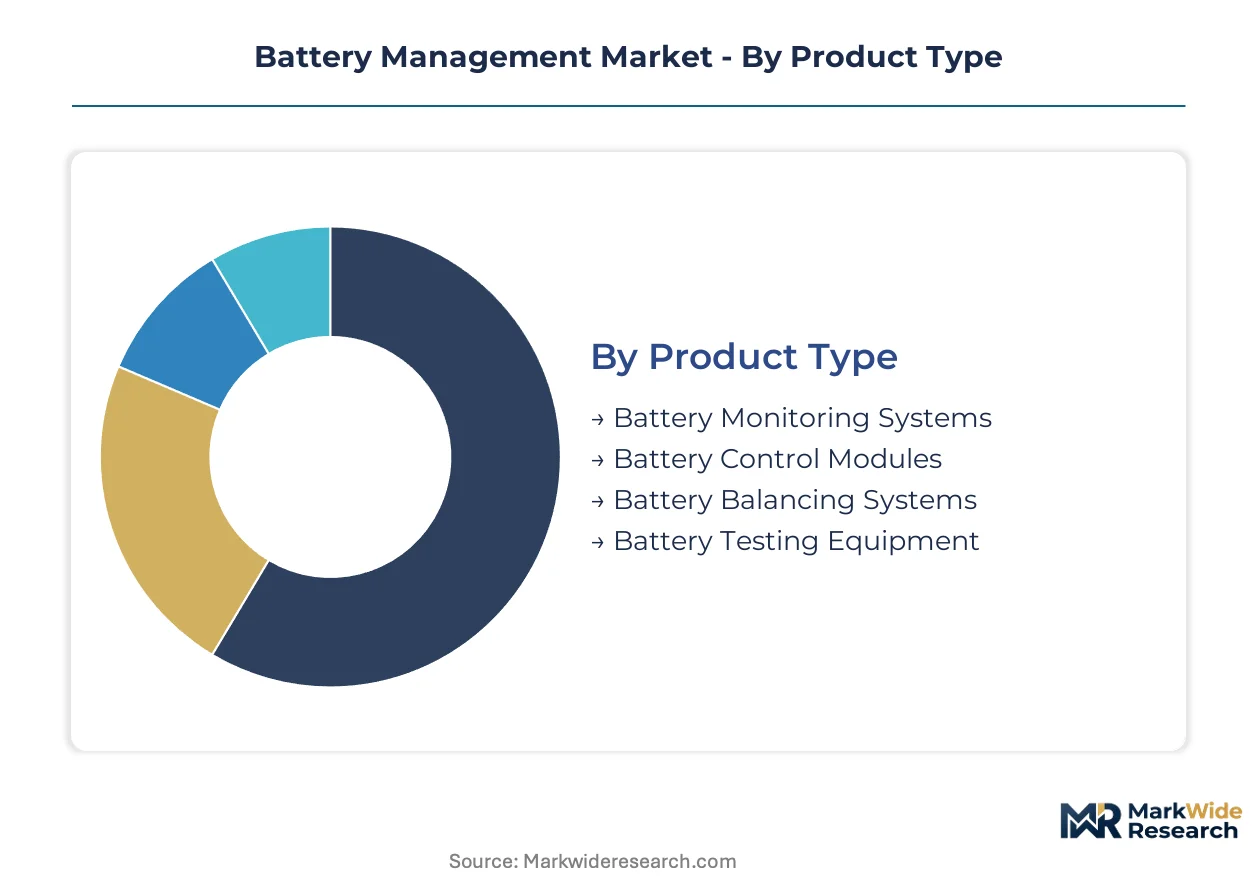
- Battery Monitoring Systems:Voltage sensing circuits resolving to one millivolt capture the largest installed base as fleet operators retrofit legacy energy storage assets. Demand concentrates in Germany and Japan where commercial vehicle operators scale predictive maintenance deployments to meet insurer thermal runaway documentation requirements.
- Battery Control Modules:Embedded software orchestrates electrochemical cell monitoring, state-of-charge estimation, and thermal regulation through silicon carbide gate drivers. China's Jiangsu and Guangdong provinces concentrate manufacturing as cell fabrication clusters integrate control module production.
- Battery Balancing Systems:Active cell equalization circuits prevent capacity drift in high-series-count automotive packs.
- Battery Testing Equipment:Laboratory-grade cyclers and impedance analyzers support solid-state prototyping programs.
Leading the category by volume: Battery Monitoring Systems. Growing fastest: Battery Control Modules.
End User:
Automotive applications command the steepest certification stack, while industrial equipment tolerates broader component sourcing flexibility. Cost tiers separate safety-critical traction systems from stationary storage monitoring hardware.
- Automotive:OEMs embed predictive diagnostics deeper into battery architectures as cell-level safety mandates tighten across European supply chains. Robert Bosch GmbH anchors position through embedded control software bundled with powertrain systems.
- Renewable Energy:Grid-tied installations require refurbished management systems recalibrating state-of-health algorithms for second-life stationary storage applications from retired Nissan and BMW EV fleets.
- Consumer Electronics:Portable device manufacturers prioritize miniaturized monitoring ICs over active thermal management.
- Industrial Equipment:Forklift and material handling fleets drive demand for lead-acid replacement monitoring in warehouse automation.
Automotive commands premium pricing tiers. Renewable Energy shows steepest expansion trajectory as grid-scale deployments accelerate.
Technology:
Manufacturing maturity separates volume production chemistries from prototype-stage architectures. Solid-state formats require redesigned management electronics handling distinct thermal profiles and voltage characteristics.
- Lithium-ion:Dominant chemistry across EV and stationary storage applications with established BMS algorithm libraries and temperature-dependent degradation models. Panasonic Corporation leverages cylindrical cell expertise to sustain module integration dominance.
- Solid-state:Ceramic electrolyte processing yields remain unfavorable, delaying volume deployment of next-generation cells that would drive management system refresh cycles. Engineering investment concentrates despite manufacturing immaturity.
- Lead-acid:Mature monitoring solutions serve industrial forklift and backup power segments with minimal semiconductor content.
- Nickel-metal Hydride:Hybrid vehicle legacy systems sustain replacement part demand in Japan and South Korea.
Lithium-ion dominates revenue concentration. Solid-state gains share fastest among emerging technology investments.
Application:
Cell count per system creates order-of-magnitude demand differentiation between traction and portable applications. Electric vehicle architectures require ASIL-D rated functional safety engineering that outpaces available training pipeline output.
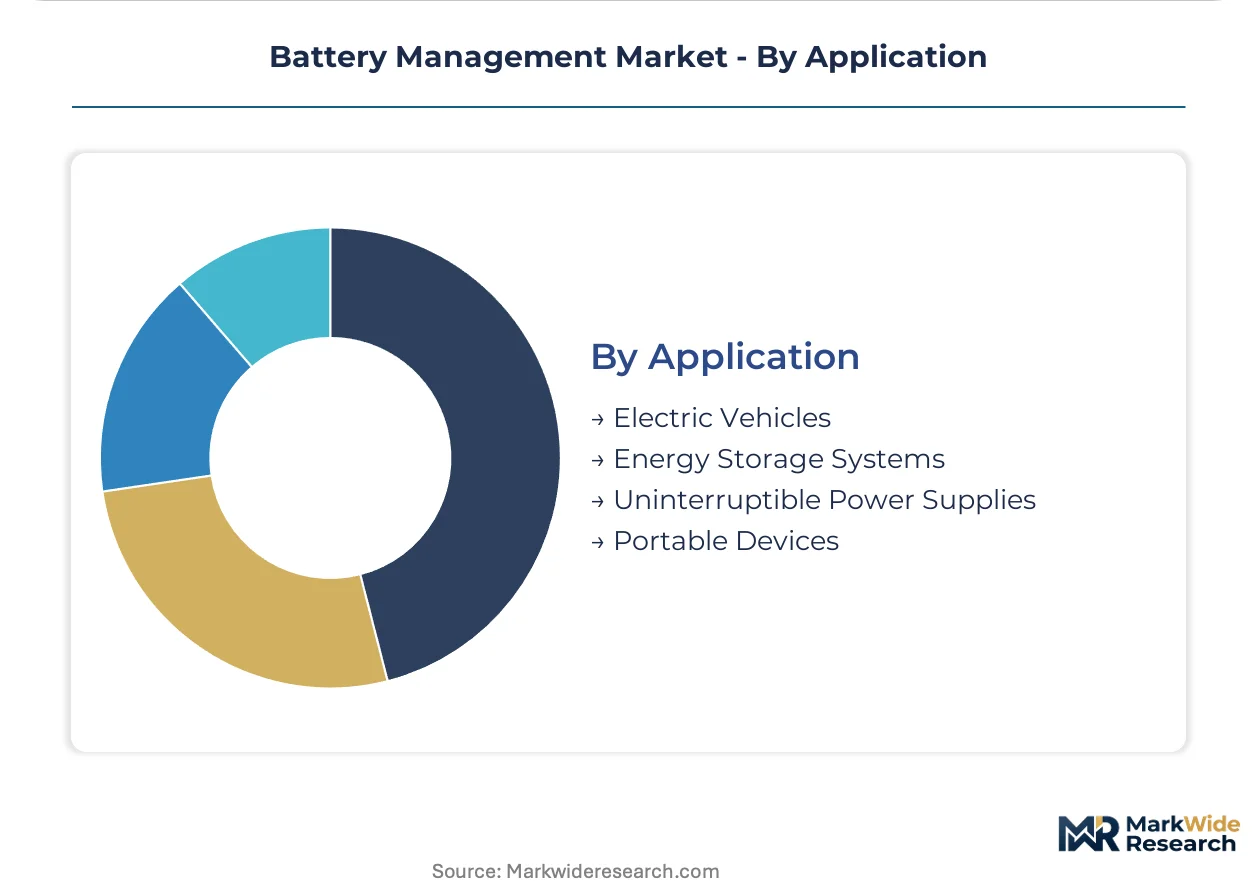
- Electric Vehicles:High-density lithium-ion installations demand thermal runaway protection through millivolt-resolution sensing and predictive algorithm intervention. EU Battery Passport mandates consolidate demand for traceable cell-level data architecture.
- Energy Storage Systems:Grid-tied and behind-meter installations source control modules separately from diagnostic software licenses in China's Jiangsu province, fragmenting traditional bundled procurement models.
- Uninterruptible Power Supplies:Data center operators specify battery monitoring for warranty compliance and downtime prevention.
- Portable Devices:Single-cell or small-series packs utilize simplified protection circuits with minimal software overhead.
Electric Vehicles leads by unit value. Energy Storage Systems climbs fastest as stationary deployments scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Guangdong provinces anchor manufacturing concentration as cell fabrication clusters integrate control module production into existing supply chains. OEMs face divergent certification requirements across major automotive markets. Regional deployment sequences reflect regulatory fragmentation rather than pure cost optimization.
China
MIIT mandates GB standard compliance for domestic battery passport data architecture, forcing parallel engineering tracks for multinational suppliers. The dual carbon goals accelerate demand for predictive diagnostics in grid-tied energy storage installations. Jiangsu province concentrates manufacturing as independent service providers unbundle after-sales service procurement models.
Germany
Commercial vehicle operators scale battery monitoring deployments to meet insurer documentation requirements for thermal runaway prevention. KBA enforces cell-level safety mandates that redirect OEM R&D budgets toward software-defined thermal management platforms. Bavaria anchors automotive supply chain integration as Robert Bosch GmbH bundles embedded control software with powertrain systems.
United States
EPA recycling standards affect end-of-life management system design for lithium-ion pack disposal and second-life applications. Texas and California concentrate grid-scale energy storage deployments requiring refurbished management systems for retired EV battery assets. Data center operators in Northern Virginia specify monitoring hardware for warranty compliance.
Japan
METI standards and commercial fleet operators drive predictive maintenance retrofits for legacy energy storage assets. Toyota and Nissan early-generation EV fleets create demand for recalibrated state-of-health algorithms in stationary storage applications. Kansai region maintains concentration in hybrid vehicle legacy systems and nickel-metal hydride replacement parts.
South Korea
MFDS and METI-aligned safety protocols shape automotive-grade certification requirements for ASIL-D rated functional safety engineering. Seoul Capital Area concentrates R&D investment in solid-state battery prototyping despite ceramic electrolyte processing yield challenges. Busan-Ulsan corridor integrates silicon carbide gate driver sourcing with battery control module fabrication.
Battery Management Market Competitive Environment
The competitive structure tilts toward integrated system suppliers with captive semiconductor capabilities. Tiered specialization separates automotive-grade ASIL-D certifiers from industrial monitoring hardware vendors. Three archetypes dominate: diversified electronics conglomerates with powertrain integration depth, pure-play semiconductor specialists in wide-bandgap devices, and emerging software-defined thermal management platforms. M&A activity concentrates on predictive algorithm assets, while capacity expansion targets co-location with cell manufacturing clusters in China and India.
Among diversified electronics conglomerates, Panasonic Corporation and Robert Bosch GmbH exemplify archetype positioning through embedded control software bundling and cylindrical cell integration expertise. Texas Instruments and Infineon Technologies AG occupy positions within the semiconductor specialist tier, leveraging silicon carbide and sensing circuit capabilities. Contemporary Amperex Technology Co., Limited anchors the cell manufacturer-integrated control module segment as production gravity shifts toward captive supply arrangements in Jiangsu and Guangdong.
| Leading Market Players |
|---|
| LG Energy Solution |
| Contemporary Amperex Technology Co., Limited (CATL) |
| Panasonic Corporation |
| Texas Instruments |
| Eberspächer |
| Sensata Technologies, Inc. |
| Robert Bosch GmbH |
| Infineon Technologies AG |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide wafer fabrication costs cascade through battery control module pricing tiers, with substrate scarcity concentrating margin pressure on automotive-grade ASIL-D certified systems while industrial monitoring hardware absorbs less volatile semiconductor input exposure.
Pricing Analysis
Outcome-based pricing anchored to fleet uptime guarantees dominates automotive contracts, with predictive maintenance subscriptions commanding premium positioning over transactional hardware sales. Certification tier separates ASIL-D automotive modules from IEC 62619 industrial systems, while after-sales service unbundling in China's Jiangsu province compresses integrated supplier margins. Pricing pressure stems from silicon carbide gate driver sourcing constraints, with commercial vehicle operators in Germany showing highest price sensitivity due to insurer documentation mandates.
Supply Chain Analysis
Certification gating through UL 1973, UN 38.3, and ISO 26262 ASIL-D tiers fragments supplier qualification timelines and concentrates procurement decisions around pre-qualified component vendors. Manufacturing gravity centers on China's Jiangsu and Guangdong provinces, South Korea's Seoul Capital Area, and Germany's Bavaria region. Raw material dependencies span silicon carbide substrates, lithium-ion cell electrodes, and ceramic electrolyte precursors. Single-source vulnerability in wide-bandgap semiconductor wafer fabrication creates structural risk. Distribution runs through captive supply arrangements with cell manufacturing clusters and Tier 1 automotive module integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's traceable cell-level data architecture creates a cost-of-compliance moat that favors incumbents with embedded software capabilities and certified manufacturing footprints over undifferentiated hardware assemblers.
For Market Incumbents: Extend predictive algorithm portfolios through acquisition of specialized state-of-health estimation software assets, while deepening silicon carbide gate driver sourcing relationships to defend against emerging wide-bandgap semiconductor specialists. Certification investment in parallel GB standard and EU Battery Passport compliance tracks anchors position against regulatory divergence threats. For New Entrants and Emerging Players: Launch via unbundled diagnostic software licensing models targeting China's independent service provider ecosystem in Jiangsu province, where aftermarket procurement fragmentation creates white-space outside integrated supplier strongholds. Second-life stationary storage recalibration services for retired Nissan and BMW fleets offer the most penetrable entry vector. For Investors and Strategic Acquirers: Solid-state battery prototyping program announcements from major cell manufacturers are the leading indicator that management system refresh cycles will accelerate demand for redesigned thermal profile electronics. Acquisition targets should focus on software-defined thermal management platforms with functional safety engineering depth, as ASIL-D compliance scarcity underwrites long-term viability across the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Algorithm Acquisition | Embedded software capabilities differentiate ASIL-D certified suppliers from hardware assemblers in automotive procurement. |
| Silicon Carbide Supply Partnership | Wide-bandgap semiconductor sourcing relationships gate access to high-performance battery control module tiers. |
| Dual Certification Investment | Parallel GB standard and EU Battery Passport compliance enables geographic optionality for multinational deployments. |
| Second-Life Storage Refurbishment | Retired EV battery assets from early-generation fleets create aftermarket service revenue streams. |
| India PLI Co-Location | Gujarat and Tamil Nadu manufacturing presence captures production-linked incentive benefits for domestic cell integration. |
Study Parameters
Independent corroboration across battery control module procurement leads at Tier 1 automotive suppliers, functional safety engineering directors at ASIL-D certifiers, and fleet operations managers at commercial vehicle operators underwrites the qualitative findings. Secondary validation draws from MIIT GB standard filings, EU Battery Regulation implementation guidance, EPA lithium-ion recycling enforcement records, and customs data tracking silicon carbide substrate trade flows. Bottom-up segment sizing triangulates against top-down OEM platform deployment projections.
Rate-of-change decomposition separates volume growth from value mix shifts across the projection horizon. The analytical framework models electrochemical chemistry tier, powertrain integration depth, application cell count, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from installed base expansion rates, replacement cycle compression, and average content per vehicle trajectories informed by solid-state prototyping investment levels and fleet retrofitting penetration curves.
Ceramic electrolyte processing yield breakthroughs, silicon carbide wafer fabrication capacity additions, and EU Battery Passport enforcement timeline adjustments are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in solid-state battery manufacturing readiness indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Battery Management System (BMS) Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
US Energy Storage Market
Battery Management System
Renewable Battery Storage Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market