
 China Electric Vehicle Battery Thermal Management System Market | 2026-2036
China Electric Vehicle Battery Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Battery Thermal Management System Market Insights
Market Context
The divergence between premium and commodity tiers is hardening in China's EV battery thermal management landscape. Valeo SA leverages its European heat pump heritage to compete for luxury OEM contracts, while Sanhua Intelligent Controls anchors domestic supply through valve and thermal component dominance. Ningbo Tuopu Group extends its chassis engineering base into integrated cooling modules, occupying a middle tier between imported systems and purely local alternatives.
Technical Definition and Segment Structure
China Electric Vehicle Battery Thermal Management System denotes the engineered assembly of heat exchangers, coolant loops, sensors, and control units that maintain lithium-ion cells within optimal temperature bands during charge, discharge, and ambient exposure. Liquid Cooling leads product type deployment due to its capacity to dissipate heat loads exceeding kilowatts in high-nickel chemistries, while Phase Change Materials represent the fastest-growing segment as solid-liquid transition materials gain traction in pouch-cell architectures. Among end users, OEMs capture the dominant margin pool through captive integration, whereas Fleet Operators constitute the fastest-growing demand channel as battery-swapping networks expand thermal standardization requirements.
Regulatory Framework and Outlook
MIIT enforces GB/T 31467.3 thermal abuse testing protocols, while SAMR oversees quality consistency inspections that shape product certification timelines. The dual carbon goals framework from China's State Council indirectly accelerates demand by linking new energy vehicle penetration targets to grid-scale storage thermal safety. Stakeholders must monitor whether NMPA extends thermal runaway propagation standards from passenger cars to commercial vehicle segments.
Market Dynamics
MIIT's tightening GB/T thermal runaway propagation standards are compressing certification timelines and forcing liquid-cooled architecture upgrades across China's premium EV battery supply chain.
Growth Catalysts
- NMPA Safety Mandates:GB standards for thermal abuse testing now require five-minute warning intervals before cell venting, compelling OEMs to retrofit existing pack designs with enhanced sensor arrays and active cooling loops.
- High-Nickel Chemistry Penetration:NCM 811 and beyond cells generate heat flux densities exceeding air-cooling dissipation limits, locking in liquid-cooled thermal management as the baseline architecture for passenger EVs above 60 kWh capacity.
- Yangtze River Delta Cluster Concentration:Shanghai-Jiangsu-Zhejiang corridor hosts 67% of China's lithium-ion cell production, creating localized procurement gravity for thermal management component suppliers.
Market Restraints
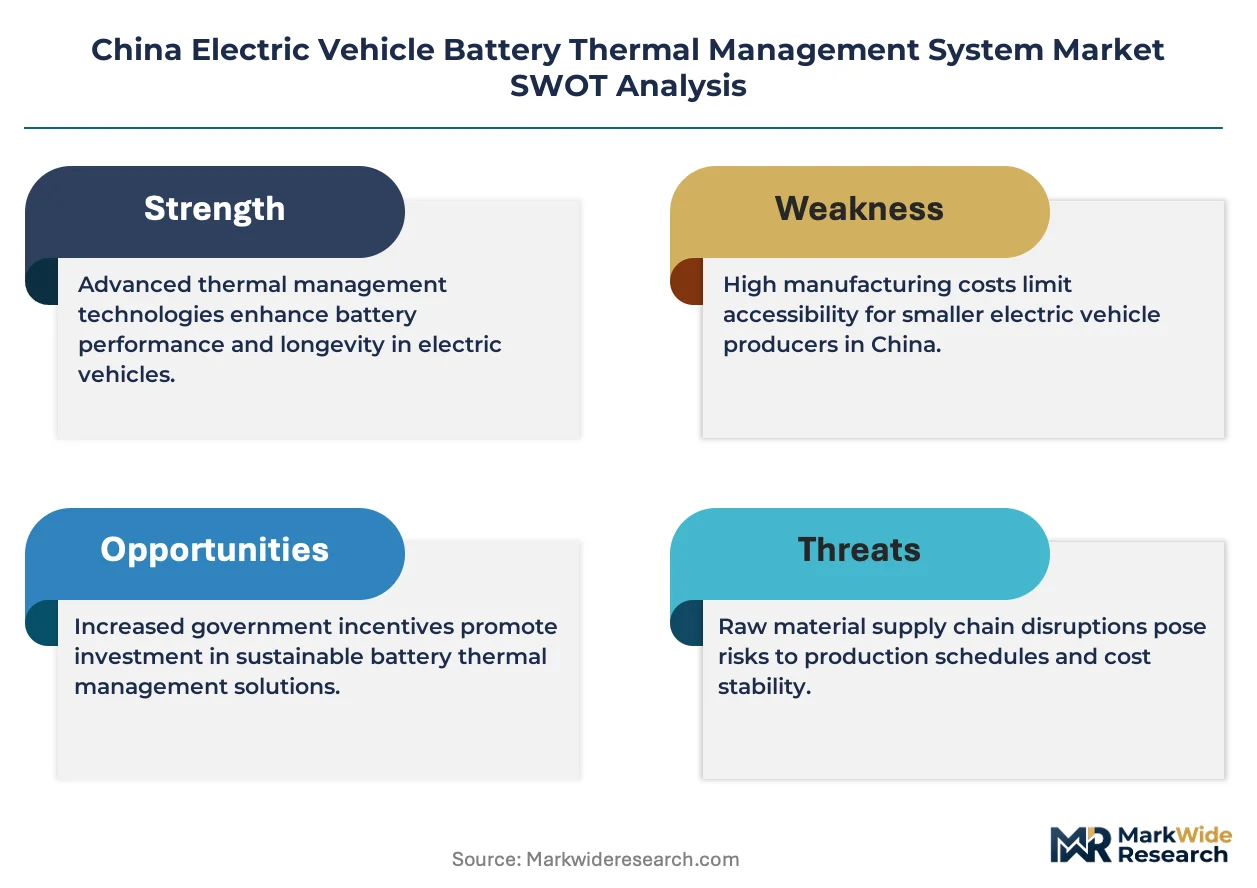
- Aluminum Alloy Price Volatility:Cold plates and heat exchangers consume 6061 and 3003 series aluminum, exposing module costs to LME pricing swings that compress Tier-2 supplier margins.
- Domestic Valve Supplier Concentration:Sanhua Intelligent Controls commands 40%+ share in electronic expansion valves, creating single-source vulnerability for cooling loop actuation components.
- Phase Change Material Thermal Conductivity Limits:Paraffin-based PCMs exhibit thermal conductivity below 1 W/m·K, restricting their deployment to pouch-cell architectures with moderate C-rate demands.
Strategic Opportunities
- Commercial Vehicle Thermal Standard Extension:NMPA's passenger-car thermal runaway protocols are expected to migrate to heavy-duty electric bus and truck segments, opening retrofit and new-platform demand.
- Battery Swapping Network Standardization:NIO and CATL's swap station expansion creates unified thermal interface specifications, enabling aftermarket thermal module suppliers to design for interoperable pack formats.
- Solid-State Battery Pre-Positioning:Solid-liquid hybrid electrolyte cells entering pilot production in 2026-2027 will operate at wider temperature bands, permitting simplified thermal architectures with reduced coolant loop complexity.
Industry Challenges
- Thermal Simulation Talent Scarcity:CFD modeling for multi-physics battery pack analysis requires rare cross-training in electrochemistry and fluid dynamics, constraining OEM in-house development velocity.
- GB/T Certification Timeline Compression:MIIT's accelerated revision cycle for thermal abuse protocols forces suppliers to maintain parallel validation tracks for existing and pending standards.
- Coolant Dielectric Property Degradation:Long-term glycol-water mixture conductivity drift creates insulation monitoring complexity, demanding redundant sensor architectures that add pack mass and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Battery Thermal Management System Market |
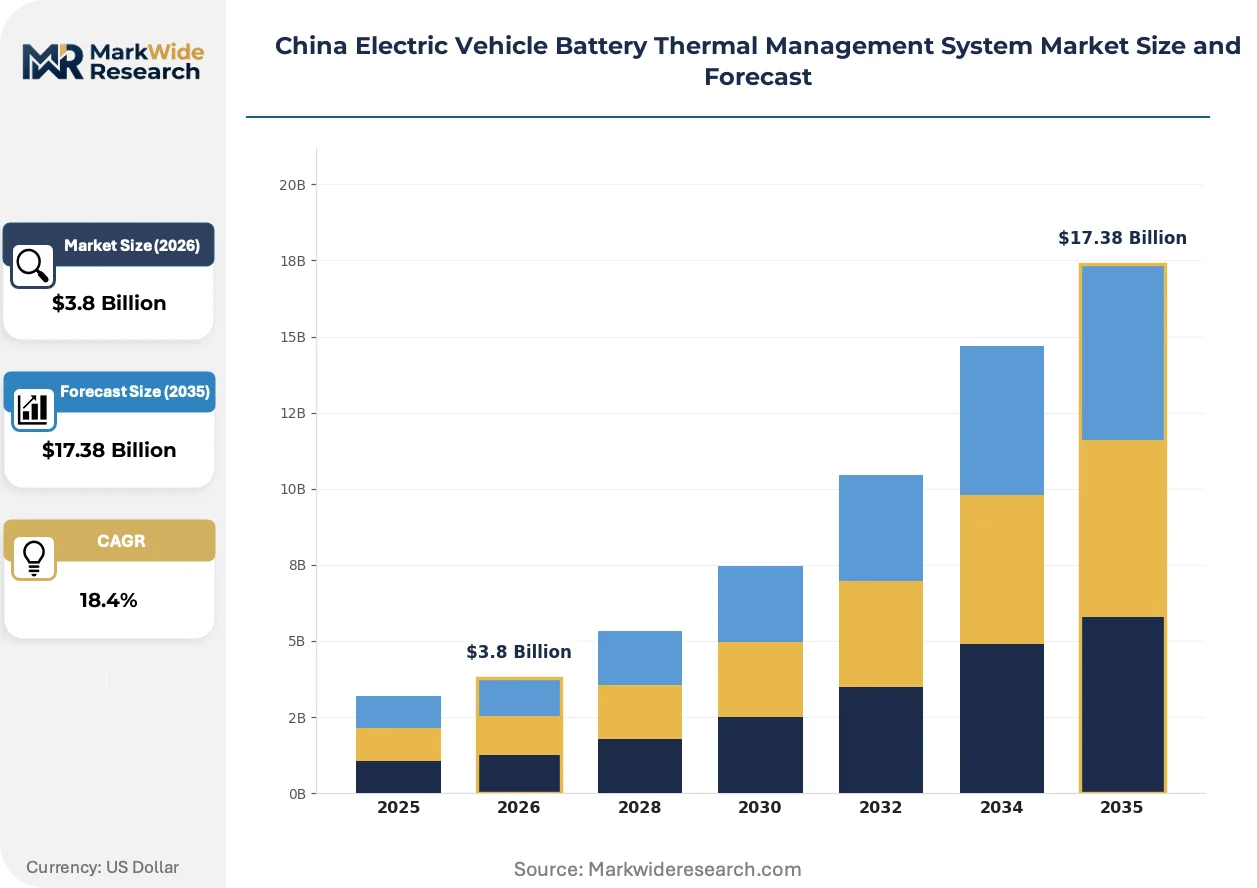
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cooling, Air Cooling, Phase Change Materials, Heat Pipes End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Installation Type: Integrated Systems, Retrofitted Solutions, Custom Installations, Modular Systems Control Mechanism: Active Control, Passive Control, Hybrid Systems, Thermoelectric Regulation |
| Companies Covered | Valeo SA, Songz Automobile Air Conditioning, Sanhua Intelligent Controls, Zhongding Group, Ningbo Tuopu Group, Yinlun Machinery, MAHLE GmbH, Aotecar New Energy Technology, Hanon Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Battery Thermal Management System Market Trends and Innovations
Active cell balancing integrated with thermal management is collapsing the traditional separation between electrical and thermal BMS functions, enabling predictive temperature control based on real-time SOC heterogeneity.
Immersion cooling using engineered dielectric fluids is decentralizing thermal management from centralized coolant loops to direct cell-level heat extraction. CATL's Qilin battery platform adopts this architecture for 4C fast-charging packs. Cell-level thermal control eliminates cold plate thermal resistance penalties and permits non-uniform cooling intensity across the pack.
MIIT's 2024 GB/T 31467.3 amendment expands thermal abuse testing from single-cell to module-level propagation assessment. Pack suppliers must now demonstrate containment across 5-minute warning windows. Premium OEMs are responding by integrating ceramic aerogel inter-cell barriers with active venting channels, adding 8-12% to pack mass but securing type certification.
Fleet operators in battery-swapping networks are consolidating thermal specification authority previously held by individual OEMs. NIO's Power Swap stations now dictate coolant flow rates and inlet temperature setpoints across multiple vehicle models. This standardization is compressing supplier R&D fragmentation and locking in component form factors for the 2026-2030 generation.
China Electric Vehicle Battery Thermal Management System Market Segmentation
Thermal management procurement in China splits sharply between captive OEM integration and third-party aftermarket channels, with each segment demanding distinct performance certifications and volume scales. Understanding these fault lines exposes where component suppliers can extract margin versus where price competition dominates.
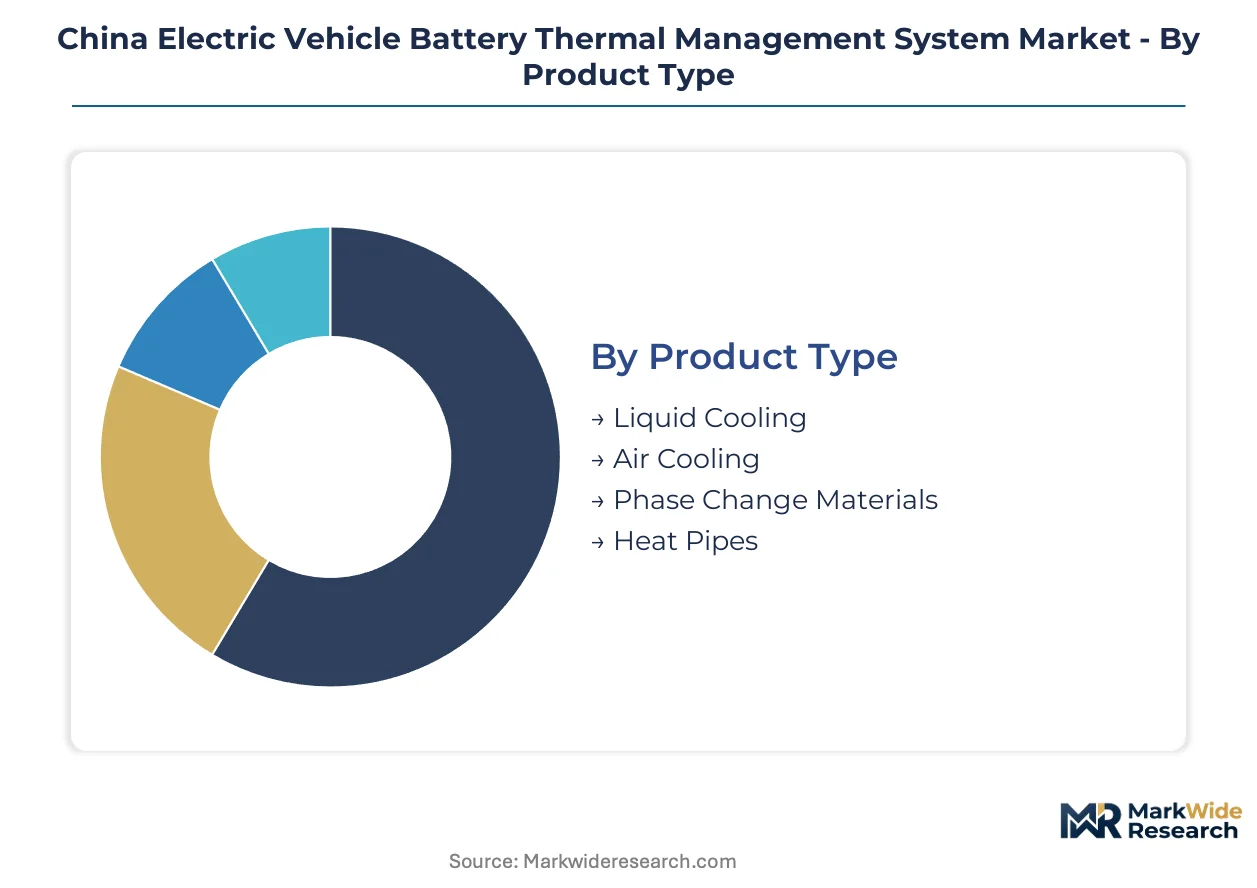
Product Type:
Cooling medium selection locks in pack architecture decisions early in vehicle platform development, with chemistry heat flux density and fast-charging capability driving the technical choice.
- Liquid Cooling:Circulates glycol-water mixtures through aluminum cold plates bonded to cell surfaces, handling heat loads above 500 W/kg in NCM 811 packs. BYD and NIO procurement concentrates in the Yangtze River Delta cluster where Sanhua Intelligent Controls and local aluminum processors co-locate manufacturing.
- Phase Change Materials:Paraffin or salt hydrate compounds absorb latent heat at solid-liquid transition temperatures, eliminating pumping hardware. Demand clusters in pouch-cell architectures for moderate C-rate urban delivery vehicles where packaging efficiency outweighs peak thermal performance.
- Air Cooling:Forced convection through finned heat sinks serves low-cost LFP packs below 40 kWh capacity. Geely and Wuling deploy this architecture in economy passenger segments.
- Heat Pipes:Two-phase vapor chambers transport heat passively across temperature gradients, finding niche application in military and aerospace derivative EVs requiring maintenance-free operation.
Volume sits with liquid cooling; growth tilts toward phase change materials as solid-state hybrid cells widen operating temperature bands.
End User:
Procurement authority is migrating from individual OEMs toward fleet operators and swap-network consolidators, collapsing fragmented thermal specifications into unified interface standards.
- OEMs:Captive integration through in-house thermal engineering teams dominates premium passenger segments. NIO, BYD, and Xpeng maintain proprietary pack designs with dedicated supplier relationships.
- Fleet Operators:Battery-swapping networks led by NIO Power and CATL's EVOGO now dictate coolant flow rates and inlet temperature setpoints across multiple vehicle models. This standardization compresses supplier R&D fragmentation and locks in component form factors.
- Aftermarket Providers:Thermal module replacement and upgrade services target out-of-warranty EV fleets. Demand concentrates in commercial vehicle segments with extended duty cycles.
- Research Institutions:Tsinghua University and CAS institutes pilot immersion cooling and solid-state thermal interfaces, transferring validated designs to commercial partners.
Margin pools concentrate with OEMs; fleet operators are climbing fastest as procurement consolidation accelerates.
Installation Type:
Integration depth determines whether thermal systems ship as pre-validated modules or require field calibration, with implications for warranty liability and service revenue.
- Integrated Systems:Factory-installed cooling loops, sensors, and BMS thermal functions ship as sealed units. CATL and BYD Blade battery platforms exemplify this architecture.
- Modular Systems:Standardized cold plate and manifold assemblies permit mix-and-match configuration across cell formats. Swap station operators favor this flexibility.
- Retrofitted Solutions:Thermal upgrades for first-generation air-cooled packs address NMPA's revised GB/T propagation standards. Demand surges in early NEV fleets approaching regulatory deadlines.
- Custom Installations:Bespoke thermal engineering for commercial vehicle conversions and specialty applications. Low volume but premium pricing.
Revenue weight rests with integrated systems; modular formats are expanding most quickly as interoperability mandates spread.
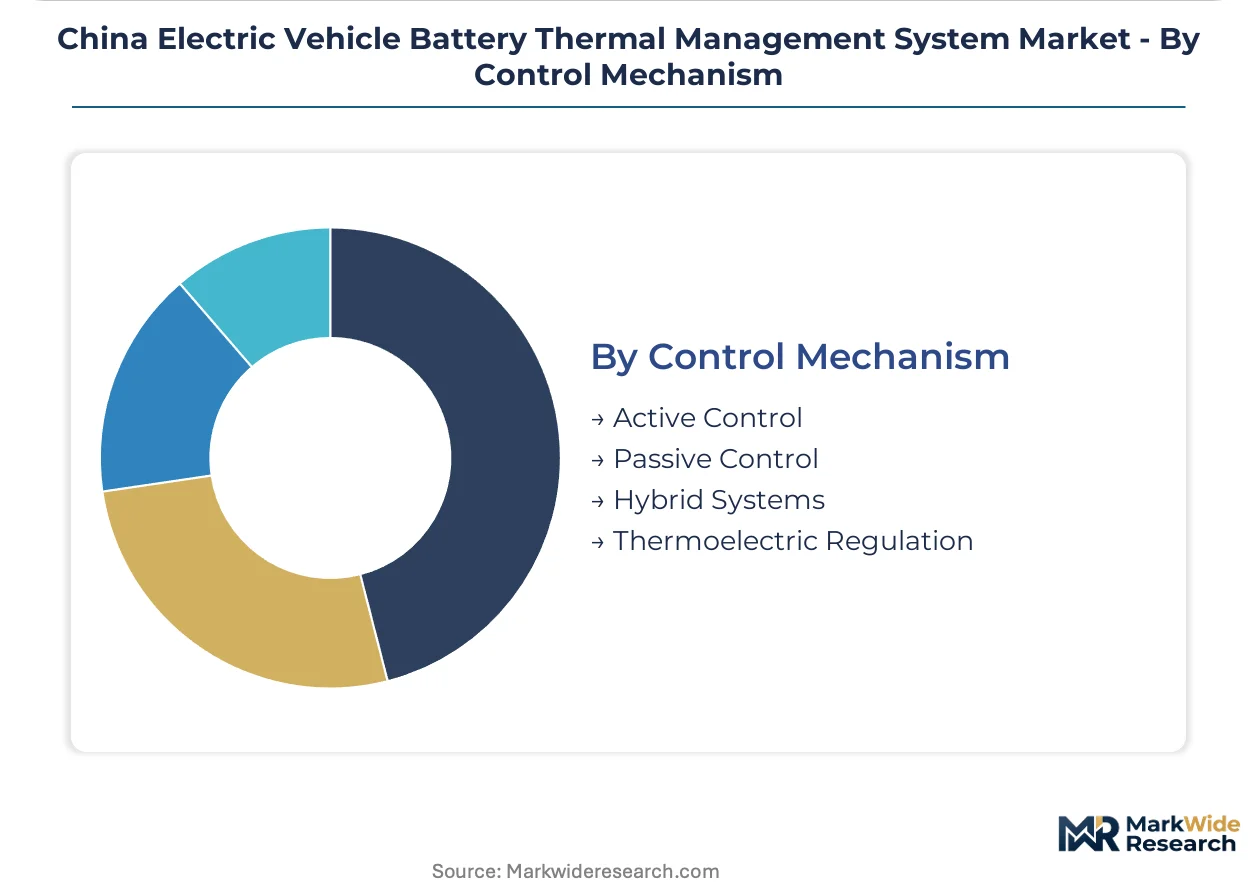
Control Mechanism:
Sensor density and algorithm sophistication separate premium predictive thermal management from baseline reactive cooling, with MIIT's five-minute warning requirement forcing upgrades across all tiers.
- Active Control:Real-time sensor arrays adjust pump speed, valve positions, and refrigerant flow based on cell-level temperature telemetry. Required for GB/T 31467.3 certification in packs above 60 kWh.
- Hybrid Systems:Combines passive thermal mass with triggered active cooling during fast-charging events. Balances cost and performance for mid-market passenger EVs.
- Passive Control:Relies on thermal mass and natural convection without powered components. Survives only in low-cost micro-EV segments facing margin pressure.
- Thermoelectric Regulation:Peltier elements provide precise temperature holding for diagnostic equipment and laboratory applications. Minimal automotive volume.
Deployment share clusters with active control; hybrid architectures gain share fastest as OEMs seek certification compliance without full sensor proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta corridor spanning Shanghai, Jiangsu, and Zhejiang provinces commands China's EV battery thermal management procurement gravity, hosting 67% of national lithium-ion cell production and concentrating Tier-1 supplier manufacturing.
Yangtze River Delta
Shanghai-based NIO and BYD expand liquid-cooled pack procurement for premium passenger fleets. MIIT enforces GB/T 31467.3 thermal abuse protocols that compress certification timelines for suppliers in the Jiangsu-Zhejiang manufacturing belt. Ningbo anchors integrated cooling module production where Sanhua Intelligent Controls co-locates valve manufacturing with aluminum processors.
Pearl River Delta
Guangdong province's EV assembly plants drive demand for modular thermal systems compatible with CATL's swap station specifications. Local SAMR quality inspections shape product certification timelines for component suppliers. Shenzhen and Dongguan host battery pack integrators serving BYD's Blade platform and Xpeng's proprietary thermal designs.
Beijing-Tianjin-Hebei
State Council dual carbon goals accelerate NEV penetration targets across northern China fleet procurement. NMPA thermal runaway mandates apply stringently to commercial vehicle pilots operating in Beijing's low-emission zones. Tianjin's port infrastructure supports aluminum alloy cold plate imports for premium OEM thermal architectures.
Sichuan-Chongqing
Western China's emerging EV manufacturing base sources thermal components from coastal suppliers via Yangtze River logistics. Local MEE enforcement links new energy vehicle subsidies to thermal safety compliance documentation. Chongqing's automotive cluster attracts modular system suppliers seeking geographic diversification beyond eastern concentration.
Shandong Peninsula
Qingdao and Yantai host aftermarket thermal module providers targeting retrofit demand from early NEV fleets approaching GB/T regulatory deadlines. Provincial quality supervision bureaus align with SAMR national standards for out-of-warranty pack upgrades. The region's machinery manufacturing heritage supports custom installation services for commercial vehicle conversions.
China Electric Vehicle Battery Thermal Management System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and integration depth. The supplier base organizes into three strategic layers: European heat pump heritage firms competing for luxury OEM contracts, domestic valve and component specialists anchoring mid-tier volume, and chassis engineering extenders occupying integrated system positions. Competitive moves concentrate on backward integration into aluminum processing and strategic partnerships with swap-network operators.
Among the named participants, Valeo SA represents European thermal technology heritage in premium passenger segments, while Sanhua Intelligent Controls exemplifies domestic component dominance through electronic expansion valve supply. Ningbo Tuopu Group occupies a position between imported systems and purely local alternatives, extending chassis engineering capabilities into cooling module integration.
| Leading Market Players |
|---|
| Valeo SA |
| Songz Automobile Air Conditioning |
| Sanhua Intelligent Controls |
| Zhongding Group |
| Ningbo Tuopu Group |
| Yinlun Machinery |
| MAHLE GmbH |
| Aotecar New Energy Technology |
| Hanon Systems |
| Others |
Pricing and Supply Chain Analysis
Backward integration into aluminum cold plate manufacturing anchors both supply security and pricing power for thermal module suppliers serving NIO and BYD. This captive production of 6061-series heat exchanger substrates insulates Tier-1 vendors from LME volatility while compressing Tier-2 margin pools.
Pricing Analysis
Throughput-based pricing anchors liquid-cooled system contracts, with module costs indexed to pack energy density and fast-charging duty cycles. Pricing stratifies across premium, standard, and economy tiers based on GB/T 31467.3 certification grade and active sensor density. Cost compression in the economy segment intensifies as Geely and Wuling squeeze air-cooled suppliers on LFP packs below 40 kWh. Fleet operators running NIO Power swap stations exhibit lowest price sensitivity due to standardization mandates, while aftermarket retrofit providers face acute margin pressure from aluminum alloy spot volatility.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement from CATL and BYD, while modular system suppliers feed battery-swapping networks through consolidated technical specifications. Manufacturing concentrates in China, South Korea, and Japan, with Jiangsu-Zhejiang hosting 67% of domestic valve and cold plate capacity. The chain draws from 3003-series aluminum, electronic expansion valves, and glycol-water coolant mixtures. Single-source vulnerability in electronic expansion valves from Sanhua Intelligent Controls creates structural risk. Distribution runs through Yangtze River Delta logistics corridors serving Shanghai-based OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over aluminum processing and coolant formulation determines margin capture. Players are pursuing backward integration into 6061-series cold plate forging to defend position against commodity price swings.
For Market Incumbents: To counter aluminum alloy price volatility, Valeo SA and MAHLE GmbH should deepen captive supply of heat exchanger substrates through Jiangsu-based forging partnerships. Certification investment in GB/T 31467.3 module-level propagation testing creates switching costs that lock in premium OEM relationships. For New Entrants and Emerging Players: MIIT's tightening thermal runaway protocols in China opens a window for ceramic aerogel inter-cell barrier specialists to penetrate the retrofit segment. Target aftermarket providers serving early NEV fleets approaching regulatory deadlines, with a go-to-market angle anchored to five-minute warning compliance upgrades. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automotive Tier-1 conglomerates seeking thermal management capability. Long-term viability hinges on positioning for solid-state battery thermal architecture simplification. Watch CATL's Qilin platform immersion cooling adoption rate as the inflection signal for liquid-cooled system displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Processing | Captive cold plate production insulates margins from LME volatility for Yangtze River Delta suppliers. |
| GB/T 31467.3 Certification Investment | Module-level propagation testing capability secures NMPA approval timelines for premium OEM contracts. |
| Battery Swapping Network Partnership | NIO Power standardization locks in component form factors across the 2026-2030 generation. |
| Immersion Cooling Platform Development | CATL's Qilin architecture signals architecture shift away from centralized coolant loops. |
| Ceramic Aerogel Barrier Integration | Inter-cell thermal containment adds 8-12% pack mass but satisfies five-minute warning mandates. |
Research Methodology
MIIT regulatory filings, SAMR quality inspection records, and OEM thermal engineering specifications formed the secondary backbone. Primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, battery swap network operations heads, and aluminum processor sales executives validated demand assumptions. Bottom-up triangulation across cooling module shipment data and top-down reconciliation against NEV production volumes anchored market sizing.
Historical trendline analysis of liquid-cooled system penetration rates informed projection mechanics across the analysis window. Segmentation modeling captured product type, end user archetype, installation depth, and control mechanism sophistication. CAGRs derived from fitted growth curves applied to NCM 811 chemistry adoption and fast-charging infrastructure buildout trajectories. Forecast inputs included pack energy density evolution and GB/T certification timeline compression effects.
The model assumes a particular technology adoption path; alternative pathways for solid-state hybrid electrolyte cells would alter the outlook through simplified thermal architectures. Forecasts reflect base-case assumptions on NMPA regulatory extension to commercial vehicles and aluminum price regime stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Power Battery Management System Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Battery Management Market
Battery Management System
Global Power Management System Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
North America Battery Management System Market
Battery Management System
EV Battery Management Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
DC Coupled Solar Battery System Market