
 Automotive Lithium-Ion Battery Management System Market | 2026-2036
Automotive Lithium-Ion Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lithium-Ion Battery Management System Market Analysis
Platform licensing revenue is tilting from discrete hardware sales toward embedded software stacks in automotive BMS architectures. Texas Instruments leverages its analog semiconductor heritage to anchor high-voltage sensing front-ends for Tier-1 battery pack integrators. Robert Bosch GmbH competes through vertically integrated control firmware that spans cell monitoring to vehicle-level energy optimization. Analog Devices specializes in precision battery monitoring integrated circuits that sustain margin pools in premium EV segments.
An automotive lithium-ion battery management system is an electrochemical control architecture comprising voltage, current, and temperature sensing arrays coupled with state-estimation algorithms and contactor actuation circuits, typically operating across cell voltages from 2.5V to 4.35V and pack voltages exceeding 800V in next-generation platforms; its primary purpose is to maximize cycle life, prevent thermal runaway propagation, and enable accurate range prediction in electrified drivetrains. Thermal management commands the highest engineering investment intensity as OEMs push fast-charging protocols above 350kW. Wireless BMS architectures represent the fastest-expanding technology category by eliminating harness weight and isolation barriers in modular pack designs. Safety management retains durable margins from functional safety ISO 26262 certification requirements that limit supplier interchangeability.
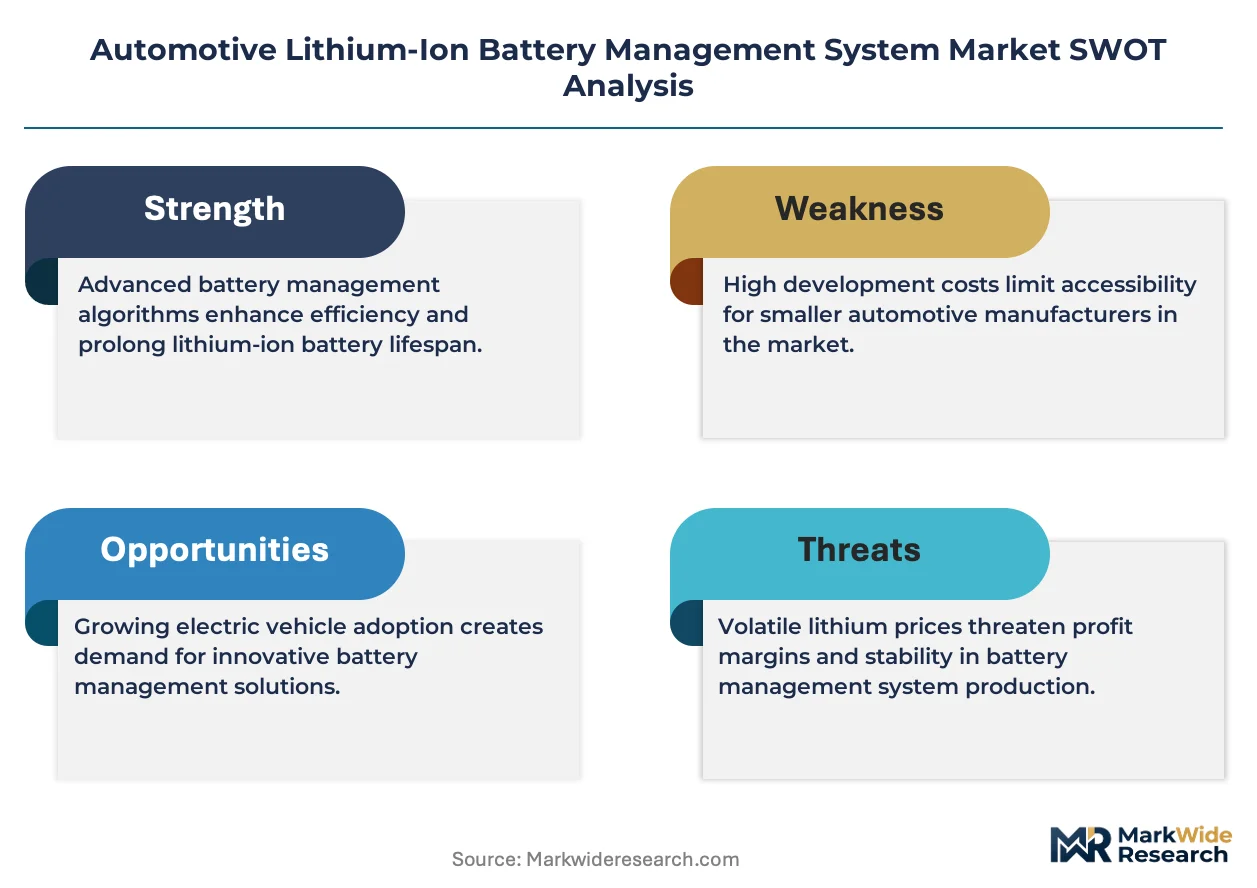
FDA-equivalent automotive safety oversight in the United States flows through NHTSA defect investigations and FMVSS electrical safety standards, while Europe's REACH and EU Battery Regulation impose full supply chain substance disclosure and end-of-life recycling accountability on BMS manufacturers. China's GB/T standards and MIIT new energy vehicle directory listing requirements create parallel certification pathways that shape product architecture decisions for multinational suppliers. Stakeholders must monitor how divergent cybersecurity mandates across these jurisdictions fragment firmware development roadmaps and qualification budgets.
Market Dynamics
Wireless BMS architectures are compressing pack assembly timelines while forcing Tier-1 integrators to requalify entire firmware stacks around electromagnetic compatibility protocols.
Growth Catalysts
- EU Battery Regulation digital passport mandates:Cell-level traceability requirements are expanding software licensing attach rates for BMS middleware providers serving European OEM assembly lines.
- 350kW fast-charging protocols:Thermal management algorithm sophistication is becoming a procurement differentiator as charging infrastructure operators demand guaranteed cycle-life performance.
- South Korea's battery manufacturing cluster:Concentrated cell production in Gyeonggi and Chungnam provinces is pulling dedicated BMS engineering centers into regional captive supply arrangements.
Market Restraints
- Silicon carbide power semiconductor shortages:High-voltage isolation components face allocation constraints from foundry capacity limitations in Taiwan and Germany.
- Functional safety certification costs:ISO 26262 ASIL-D qualification timelines extend 18-24 months, freezing supplier interchangeability and inflating qualification budgets for new entrants.
- Lithium iron phosphate cell chemistries:Lower voltage precision requirements in LFP packs compress margins for premium sensing ICs optimized to NMC tolerances.
Strategic Opportunities
- Second-life stationary storage:Retired automotive packs require refurbished BMS firmware for grid-scale deployment, opening aftermarket software licensing channels.
- India's PLI scheme for ACC manufacturing:Localized cell production incentives are creating demand for BMS suppliers willing to establish domestic engineering subsidiaries.
- Vehicle-to-grid integration:Bidirectional power flow protocols are converging BMS architectures with home energy management systems, expanding addressable market scope.
Industry Challenges
- Embedded cybersecurity engineering:UN R155 and ISO/SAE 21434 mandates require dedicated firmware security architects, a skill set scarce in traditional automotive electronics teams.
- Pack-level integration complexity:Modular cell-to-pack designs demand BMS suppliers coordinate thermal, electrical, and mechanical interfaces across multiple subsystem owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lithium-Ion Battery Management System Market |
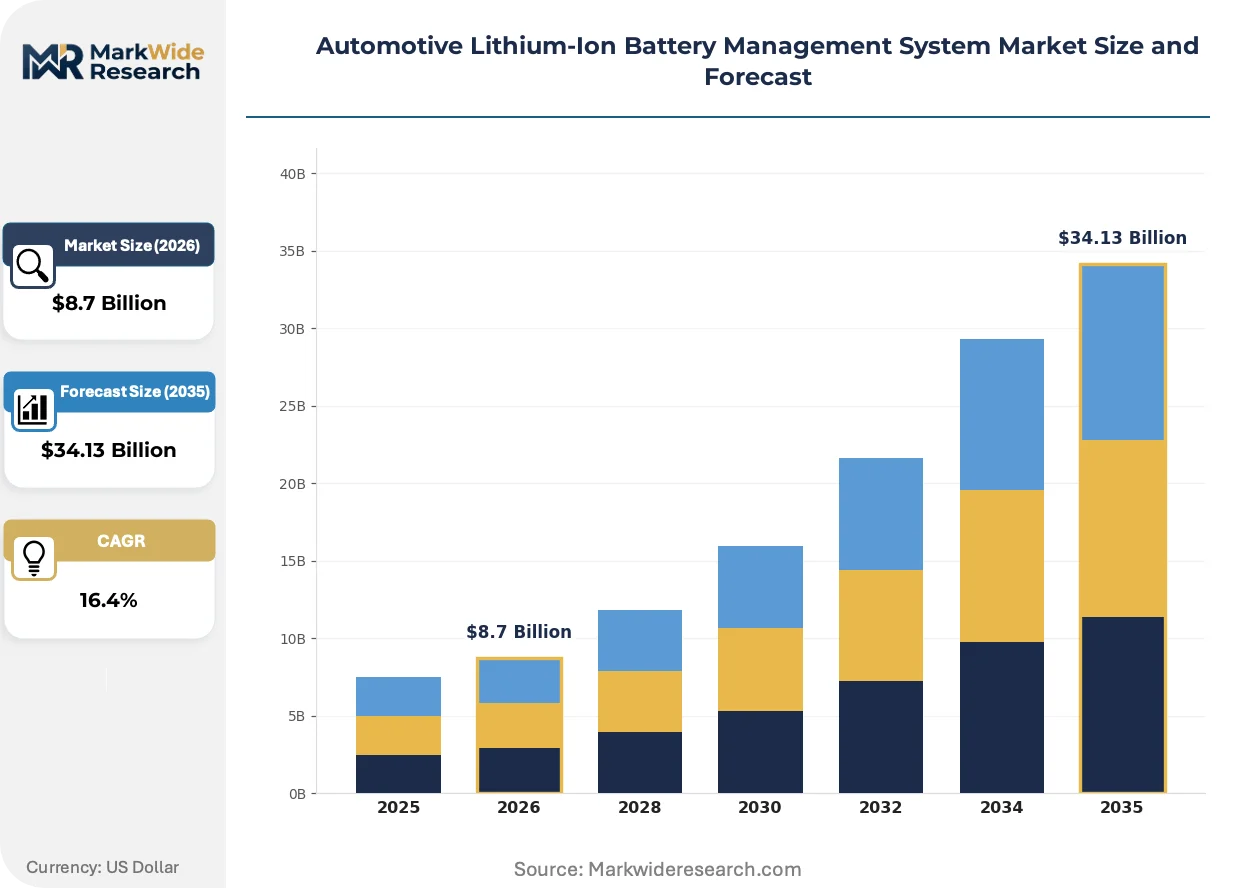
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Monitoring, Charging Management, Thermal Management, Safety Management End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Analog, Digital, Hybrid, Wireless Application: Electric Vehicles, Hybrid Vehicles, Energy Storage, Marine Applications |
| Companies Covered | LG Energy Solution, Panasonic Holdings Corp., CATL, Robert Bosch GmbH, Continental AG, Sensata Technologies, Ficosa Internacional, Texas Instruments, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lithium-Ion Battery Management System Market Emerging Trajectories
Electrification roadmaps are forcing BMS architectures to absorb functions previously distributed across vehicle domain controllers, compressing supplier margins while expanding technical scope.
Cell monitoring integrated circuits are migrating from centralized master-slave topologies toward distributed edge-computing nodes. Premium EV platforms in Germany and South Korea are adopting this architecture to reduce harness weight and improve fault isolation. The shift is enabling cell-level predictive maintenance contracts that extend software revenue streams beyond hardware shipment.
REACH substance disclosure requirements are forcing BMS manufacturers to map conflict mineral content through four-tier supply chains. European pack integrators now require full material composition databases as a condition of RFQ participation. This regulatory friction is favoring incumbent suppliers with established compliance infrastructure over Asian challengers.
Fleet operators are consolidating BMS procurement decisions at the holding-company level rather than delegating to individual OEM brand teams. Rental and logistics fleets in California and the Netherlands are driving this concentration, demanding standardized telemetry formats across multi-brand vehicle pools. The pattern is compressing supplier negotiation leverage and accelerating API standardization efforts.
Automotive Lithium-Ion Battery Management System Market Segmentation
BMS procurement patterns diverge sharply across customer tiers and technology generations. Product architecture decisions cascade differently for fast-charging passenger platforms versus second-life stationary deployments. Understanding these fault lines clarifies where margin pools concentrate and which segments absorb qualification cost burdens.
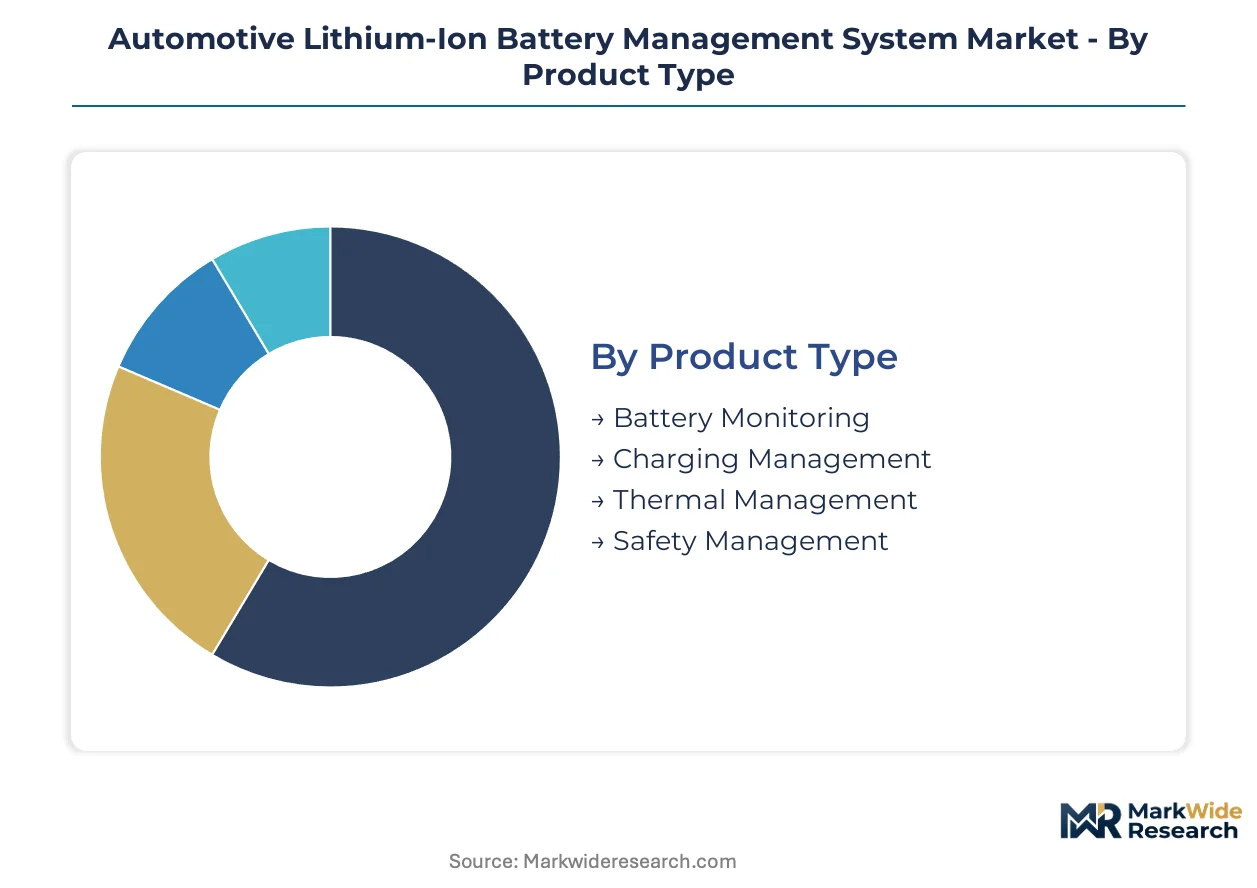
Product Type:
Cost tier stratification separates commodity monitoring hardware from algorithm-intensive thermal and safety systems that command recurring software revenue.
- Thermal Management:Fast-charging protocols above 350kW demand predictive thermal models that adjust cooling rates cell-by-cell. German OEM assembly lines concentrate procurement for 800V platforms, with charging infrastructure operators demanding guaranteed cycle-life performance as a contractual condition.
- Safety Management:ISO 26262 ASIL-D certification creates durable margin pools by freezing supplier interchangeability. European pack integrators require full functional safety documentation as a gate to RFQ participation, extending qualification timelines 18-24 months.
- Battery Monitoring:Voltage, current, and temperature sensing arrays form the hardware base layer.
- Charging Management:Bidirectional power flow protocols are converging with home energy management architectures.
Thermal Management commands the established base. The steepest expansion runs through Safety Management.
End User:
Customer type determines who bears firmware qualification costs and who controls telemetry data rights.
- OEMs:Direct procurement concentrates in Germany's automotive engineering corridor and South Korea's battery manufacturing cluster. California and Netherlands fleet operators are consolidating BMS decisions at holding-company level, demanding standardized APIs across multi-brand vehicle pools.
- Tier-1 Suppliers:Pack integrators face requalification pressure as wireless BMS architectures force firmware stack revisions around electromagnetic compatibility protocols. REACH substance disclosure requirements now mandate four-tier supply chain mapping.
- Aftermarket Providers:Second-life stationary storage opens refurbished firmware licensing channels.
- Vehicle Assemblers:Contract manufacturers absorb integration complexity across modular cell-to-pack designs.
OEMs anchor volume commitments. Tier-1 Suppliers face the steepest margin compression from integration complexity.
Technology:
Architecture maturity spans legacy analog front-ends through distributed edge-computing nodes.
- Wireless:Eliminating harness weight and isolation barriers compresses pack assembly timelines. Premium EV platforms in Germany and South Korea adopt distributed architectures to improve fault isolation, enabling cell-level predictive maintenance contracts.
- Hybrid:Combines analog sensing precision with digital state-estimation flexibility.
- Analog:Precision battery monitoring ICs sustain margins in premium NMC-optimized segments.
- Digital:Embedded software stacks are displacing discrete hardware sales in licensing revenue models.
Analog retains the installed base. Wireless gains share fastest as pack designs modularize.
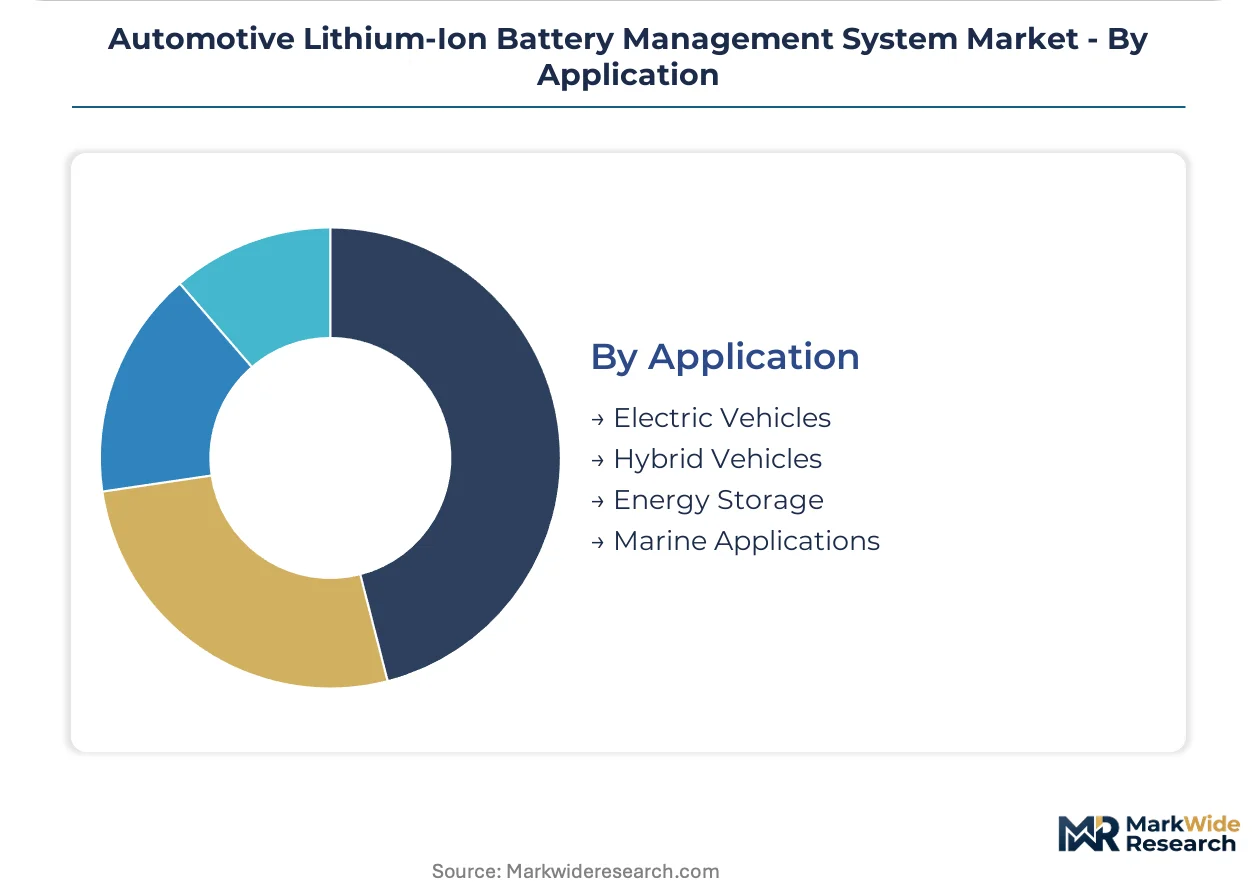
Application:
Volume concentration versus technology premium splits procurement specifications across mobility and stationary segments.
- Electric Vehicles:Passenger fleets scaling across North American and European OEM lines drive BMS procurement volume. China's NMPA cell-grade certification and EU Battery Regulation digital passport mandates tighten software traceability standards.
- Energy Storage:Grid-scale deployment of retired automotive packs requires refurbished BMS firmware, creating aftermarket software licensing channels distinct from hardware shipment revenue.
- Hybrid Vehicles:Dual powertrain architectures demand BMS coordination with engine management systems.
- Marine Applications:Specialized thermal runaway containment requirements apply in vessel installations.
Electric Vehicles command the established base. Energy Storage climbs the fastest as second-life protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing concentration in Gyeonggi and Chungnam provinces pulls dedicated BMS engineering centers into regional captive supply arrangements across East Asia. Germany's automotive engineering corridor anchors European procurement for 800V platforms. China's NMPA certification requirements and the EU Battery Regulation's digital passport mandates reshape firmware development roadmaps for multinational suppliers.
China
CATL and BYD scale cell-to-pack architectures that demand sophisticated thermal management algorithms. NMPA cell-grade certification and MIIT new energy vehicle directory listings create parallel qualification pathways. The Yangtze River Delta and Pearl River Delta clusters host captive BMS engineering subsidiaries serving domestic OEM assembly lines.
Germany
Premium EV platforms from BMW and Mercedes-Benz drive procurement for precision battery monitoring integrated circuits. EU Battery Regulation digital passport mandates expand software licensing attach rates for BMS middleware providers. The Baden-Württemberg engineering corridor concentrates Tier-1 pack integrator headquarters.
South Korea
LG Energy Solution and Samsung SDI cell production in Gyeonggi and Chungnam provinces pulls dedicated BMS engineering centers into regional supply arrangements. MFDS-equivalent automotive safety oversight flows through KBA-type defect investigations. Seoul Capital Area anchors firmware development for wireless BMS architectures.
United States
Tesla and Rivian scale 800V platforms across California and Texas assembly lines. NHTSA defect investigations and FMVSS electrical safety standards govern functional safety certification. The Pacific Northwest and Greater Boston clusters host analog semiconductor design centers for high-voltage sensing front-ends.
India
PLI scheme incentives for ACC manufacturing create demand for BMS suppliers establishing domestic engineering subsidiaries. BIS standards and CEA grid integration requirements shape product architecture decisions. Maharashtra and Gujarat automotive corridors concentrate contract manufacturer integration activity.
Automotive Lithium-Ion Battery Management System Market Vendor Landscape
Semiconductor heritage specialists and vertically integrated automotive suppliers split the market into distinct capability tiers. The vendor base concentrates around analog front-end precision and embedded software stack control. Three archetypes dominate: analog semiconductor designers with high-voltage sensing expertise, Tier-1 automotive suppliers with vehicle-level energy optimization platforms, and battery cell manufacturers with captive BMS development. Competitive moves center on electromagnetic compatibility requalification for wireless architectures and REACH substance disclosure infrastructure buildout.
Among semiconductor-focused suppliers, Texas Instruments and Analog Devices occupy positions defined by precision measurement heritage. Robert Bosch GmbH exemplifies the vertically integrated automotive supplier archetype spanning cell monitoring to vehicle-level systems. These three anchors represent how competitive positioning tilts from discrete hardware sales toward embedded software licensing revenue models in next-generation pack architectures.
| Leading Market Players |
|---|
| LG Energy Solution |
| Panasonic Holdings Corp. |
| CATL |
| Robert Bosch GmbH |
| Continental AG |
| Sensata Technologies |
| Ficosa Internacional |
| Texas Instruments |
| Analog Devices |
| Others |
Supply Flow & Price Mechanics
Gyeonggi Province's concentrated cell manufacturing capacity creates asymmetric pricing power for Korean battery producers sourcing BMS modules from captive engineering subsidiaries. This geographic concentration compresses procurement leverage for European OEMs while amplifying margin capture for integrated pack suppliers serving premium 800V platforms.
Pricing Analysis
EU Battery Regulation digital passport mandates dictate the pricing tier structure across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified firmware stacks from uncertified hardware monitoring modules. Cost compression in commodity sensing ICs is intensifying because lithium iron phosphate cell chemistries reduce voltage precision requirements. Fleet operators in California and the Netherlands demonstrate highest price sensitivity through consolidated holding-company procurement decisions, while German premium OEMs absorb certification premiums with minimal negotiation leverage.
Supply Chain Analysis
Export-control restrictions on silicon carbide power semiconductors limit foundry capacity flows from Taiwan and Germany to BMS integrators. Component sourcing draws from South Korea's analog semiconductor design centers, China's Yangtze River Delta cell production clusters, and Japan's precision sensing IC manufacturers. Single-source vulnerability concentrates in high-voltage isolation components facing allocation constraints. Distribution runs through Tier-1 pack integrator headquarters in Baden-Württemberg and captive supply arrangements anchored in Seoul Capital Area engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless BMS architectures are disrupting established supplier relationships as electromagnetic compatibility requalification demands reshape procurement criteria across automotive electronics. UN R155 cybersecurity mandates create immediate capability gaps for firmware security architecture teams.
For Market Incumbents: Entrench functional safety certification moats by accelerating ISO 26262 ASIL-D qualification investments before regulatory timelines tighten. Deepen backward integration into high-voltage sensing front-end semiconductor design to offset silicon carbide allocation risks from Taiwanese foundries. Anchor capacity in Gyeonggi Province engineering centers to secure Korean cell manufacturer procurement relationships against Chinese challengers. For New Entrants and Emerging Players: India's PLI scheme for ACC manufacturing creates underpenetrated demand for BMS suppliers establishing domestic engineering subsidiaries outside established Korean and German supply orbits. Target second-life stationary storage refurbishment channels where aftermarket firmware licensing bypasses hardware shipment barriers. Pursue vehicle-to-grid integration partnerships with home energy management system providers as bidirectional power protocols converge BMS architectures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors embedded software stack specialists with electromagnetic compatibility requalification capabilities over discrete hardware vendors. Five-to-ten year viability hinges on cybersecurity firmware architecture teams capable of UN R155 and ISO/SAE 21434 compliance. Watch for fleet operator API standardization announcements as signals of procurement consolidation accelerating supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless BMS Architecture Migration | Eliminates harness weight and isolation barriers for German premium EV platforms. |
| ISO 26262 ASIL-D Certification Investment | Freezes supplier interchangeability and extends qualification timelines for European integrators. |
| Second-Life Firmware Refurbishment | Opens aftermarket software licensing channels for retired automotive pack grid deployment. |
| Silicon Carbide Supply Agreement | Secures allocation priority for high-voltage isolation components from Taiwanese foundries. |
| EU Battery Regulation Compliance Buildout | Enables RFQ participation through REACH substance disclosure infrastructure for cell-level traceability. |
Methodological Framework
Desk research of automotive production databases, SEC filings from semiconductor suppliers, and EU regulatory filings preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and firmware security architects. Primary fieldwork combined with secondary validation from IHS Markit vehicle registration data and customs trade records. Bottom-up segment sizing triangulated against top-down market value estimates across thermal management, safety management, and battery monitoring product categories.
Assumptions held fast-charging protocol adoption curves and cell chemistry mix shares within observed ranges while varying wireless BMS penetration rates and cybersecurity mandate implementation timelines. The analytical framework segmented by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derived from modeled unit shipments and average selling price trajectories incorporating silicon carbide component cost curves and functional safety certification premium persistence.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese cell manufacturers or accelerated EU digital passport enforcement would shift outcomes. Material shifts in semiconductor foundry allocation priorities or LFP chemistry share gains beyond baseline assumptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
US Energy Storage Market
Battery Management System
Battery Management Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
Battery Management System (BMS) Market
Battery Management System
EV Battery Management Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
Energy Storage Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
Power Battery Management System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
United States Rechargeable Battery Market