
 Distributed Energy Storage System Market | 2026-2036
Distributed Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Energy Storage System Market Analysis
Grid-scale lithium-ion certification is rotating toward utility-grade safety and cycle-life standards. Tesla Energy leverages its automotive cell architecture to sustain cost advantages in megapack deployments. Fluence anchors its position through software-integrated power electronics that optimize dispatch across multiple revenue streams. BYD Energy Storage dominates manufacturing scale with captive vertical integration from cathode powder to container assembly.
A distributed energy storage system comprises modular electrochemical, mechanical, or thermal units sited near consumption points, typically rated from kilowatts to hundreds of megawatts with round-trip efficiencies between 80% and 95% depending on chemistry. These systems buffer supply-demand mismatches, defer transmission upgrades, and monetize ancillary services in deregulated power markets. Battery storage leads installed capacity due to lithium-ion cost declines and manufacturing scale, while flow battery technology captures growing interest for multi-hour duration applications where daily cycling economics favor aqueous chemistries. Thermal energy storage occupies niche but defensible positions in district heating networks and industrial process heat recovery where electrochemical alternatives face temperature limitations.
The US Federal Energy Regulatory Commission Order 2222 enables aggregated distributed resources to participate in wholesale markets, directly expanding addressable revenue for behind-the-meter systems. China's National Energy Administration enforces mandatory storage ratios for renewable project approvals, creating policy-backed procurement floors that other jurisdictions observe. The EU Battery Regulation establishes carbon footprint disclosure and recycled content mandates that will filter supplier eligibility by the mid-2030s. Stakeholders must monitor how jurisdictional certification divergence affects product platform standardization and service model portability.
Market Dynamics
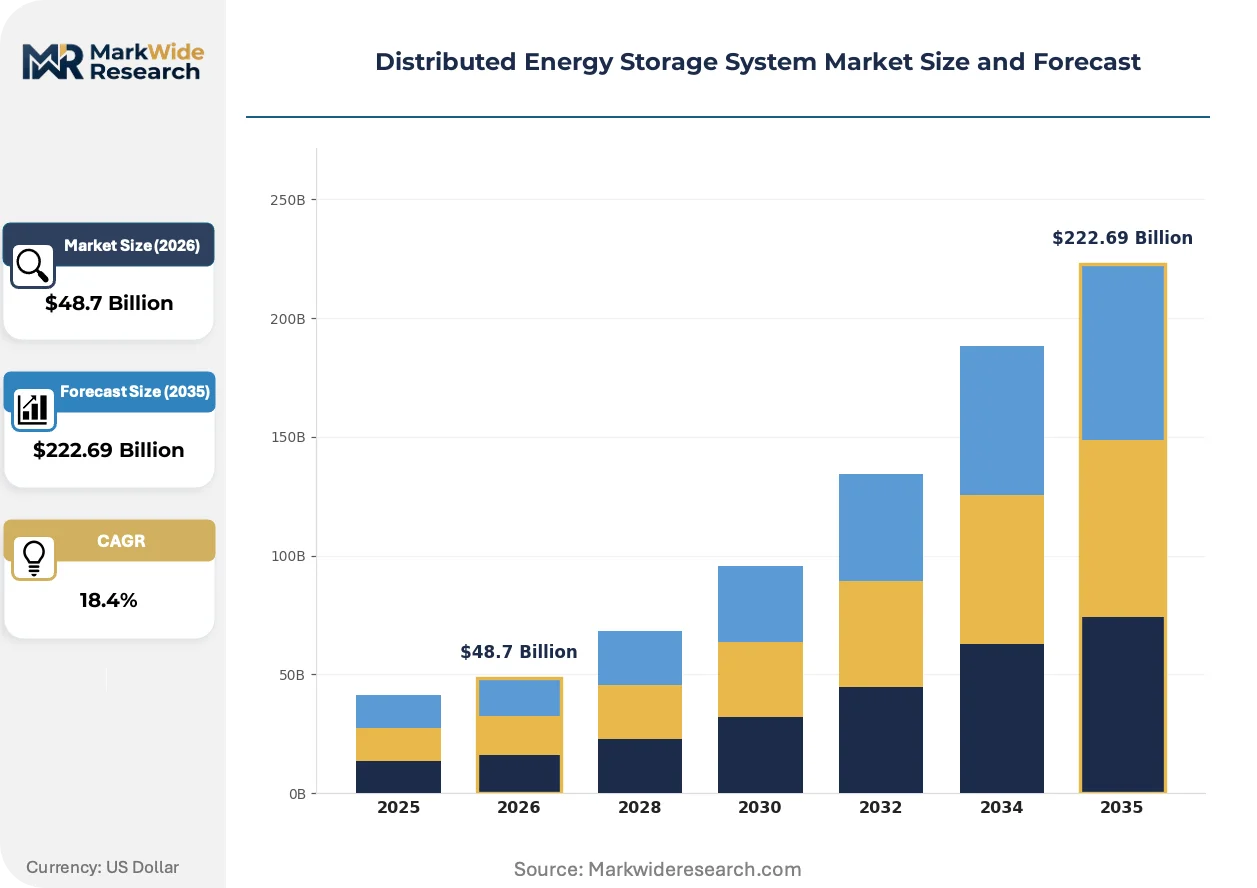
The distributed energy storage system market is restructuring around lithium-ion cost compression and utility-scale procurement mandates that favor multi-hour duration assets over shorter cycling systems. Grid operators now require storage co-location with renewable generation, forcing developers to recalibrate project economics around energy arbitrage and ancillary service stacking rather than simple peak shaving.
Growth Catalysts
- US Inflation Reduction Act tax credits:The standalone storage investment tax credit accelerates project development timelines for battery developers, reducing payback periods for utility-scale deployments.
- China's mandatory storage ratios:Provincial grid codes from the National Energy Administration require renewable developers to install co-located storage, creating policy-backed procurement floors.
- Flow battery aqueous chemistries:Multi-hour duration applications favor vanadium and iron-chromium systems where daily cycling economics exceed lithium-ion degradation costs.
Market Restraints
- Lithium carbonate price volatility:Cathode active material costs swing with South American brine and Australian spodumene concentrate supply disruptions.
- Cell manufacturing concentration:Cylindrical and prismatic cell supply clusters in East Asian production hubs expose developers to single-source risk.
- Interconnection queue delays:Regional transmission organization study backlogs stretch project commercialization timelines by months.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Production-linked incentives for advanced chemistry cell manufacturing attract gigafactory investment outside incumbent supply geographies.
- Behind-the-meter commercial-industrial aggregation:Virtual power plant software platforms unlock wholesale market participation for distributed assets.
- Long-duration iron-air systems:Multi-day storage technology converges with renewable overbuild economics to replace peaker plant capacity.
Industry Challenges
- Power electronics firmware integration:Battery management system and inverter control software interoperability demands specialized embedded systems engineering talent.
- UL 9540A fire safety certification:Large-scale thermal runaway testing protocols extend product validation timelines for containerized systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Energy Storage System Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Storage, Flywheel Storage, Pumped Hydro Storage, Thermal Energy Storage End User: Residential, Commercial, Industrial, Utility Technology: Lithium-ion, Lead Acid, Flow Battery, Compressed Air Application: Load Shifting, Frequency Regulation, Renewable Integration, Backup Power |
| Companies Covered | Hitachi Energy, Tesla Energy, General Electric, Sungrow, ABB, Siemens Energy AG, Delta Electronics, Fluence, BYD Energy Storage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Energy Storage System Market Emerging Trajectories
Solid-state and sodium-ion chemistries are advancing through pilot manufacturing lines, threatening incumbent lithium-ion dominance in stationary applications. Software-defined dispatch and predictive analytics now determine project returns more than hardware specifications alone.
Lithium iron phosphate cathode formulations are displacing nickel-manganese-cobalt alternatives in utility-scale tenders. Developers favor the chemistry's thermal stability and supply chain transparency. The shift compresses nickel and cobalt offtake demand while expanding phosphate rock and iron precursor markets.
The EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds that filter supplier eligibility by the mid-2030s. Cell manufacturers must document lifecycle emissions and establish European recycling partnerships. The requirements accelerate supply chain localization decisions for market access.
Commercial and industrial buyers now procure storage through energy-as-a-service contracts rather than direct asset ownership. Third-party financiers assume technology performance risk and capture wholesale market revenues. This model concentrates in deregulated US states with mature demand response programs and transparent nodal pricing.
Distributed Energy Storage System Market Segmentation
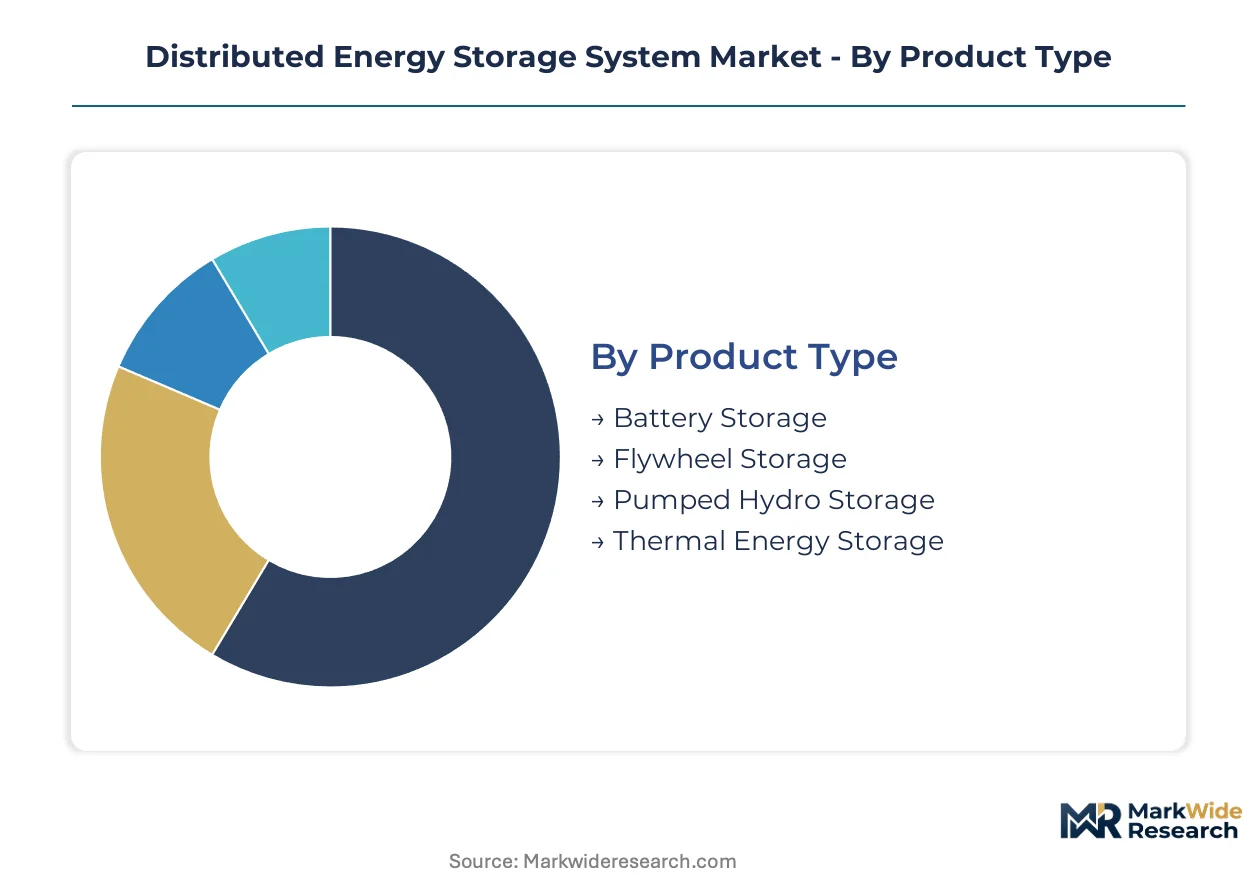
Segmentation in distributed energy storage reveals how regulatory mandates and revenue stacking strategies reshape procurement patterns. Each dimension captures distinct technical requirements and certification pathways that determine project bankability.
Product Type:
FERC Order 2222 in the US and China's NEA storage mandates create divergent certification requirements across electrochemical and mechanical systems.
- Battery Storage:Lithium-ion and flow battery systems dominate new capacity additions with modular containerized designs rated 10-100 MWh. Utility-scale procurement in Texas and California favors 4-hour duration configurations for energy arbitrage and ancillary service stacking. FERC Order 2222 compliance costs favor standardized battery management system architectures.
- Thermal Energy Storage:Molten salt and phase-change materials store process heat and cooling loads with 90%+ round-trip efficiency in temperature-specific applications. District heating networks in Denmark and industrial facilities in Germany deploy these systems where electrochemical alternatives face thermal limitations. EU ETS carbon pricing improves project economics against gas-fired alternatives.
- Flywheel Storage:Carbon fiber composite rotors deliver sub-second frequency response with 100,000+ cycle lifespans. Grid operators in New York and Texas deploy these for primary frequency regulation where rapid response outweighs energy density requirements.
- Pumped Hydro Storage:Reversible turbine-generator sets provide multi-gigawatt bulk storage with 80-85% round-trip efficiency. Topographical constraints limit deployment to mountainous regions in Switzerland, Austria, and Norway where existing reservoirs enable retrofit configurations.
Battery Storage handles the majority of throughput; Thermal Energy Storage is expanding most quickly in industrial decarbonization applications.
End User:
Customer type determines financing structures and revenue stream access, with utility-scale assets capturing wholesale market participation unavailable to smaller systems.
- Utility:Transmission-connected assets rated 100+ MWh participate in wholesale energy, capacity, and ancillary service markets through independent system operator frameworks. Developers in PJM and ERCOT optimize dispatch algorithms across multiple revenue streams. Interconnection queue delays in California ISO and SPP stretch commercialization timelines.
- Commercial:Behind-the-meter systems from 100 kWh to 10 MWh reduce demand charges and enable peak shaving for retail, healthcare, and data center loads. Virtual power plant aggregation platforms in California and New York unlock wholesale market revenues previously restricted to utility-scale assets.
- Industrial:Process-integrated storage buffers manufacturing loads against power quality events and time-of-use rate structures. Chemical plants and semiconductor fabs in Germany and South Korea deploy these systems where voltage sags cause million-dollar production losses.
- Residential:Single-family and multi-unit battery systems from 5-20 kWh pair with rooftop solar for self-consumption optimization. Germany's EEG feed-in tariff reductions and California's NEM 3.0 export rate cuts accelerate battery attachment rates.
Utility captures the dominant share of installed capacity; Commercial is gaining share fastest through virtual power plant aggregation.
Technology:
Cell chemistry selection trades energy density against cycle life, with aqueous systems capturing multi-hour applications where lithium-ion degradation costs accumulate.
- Lithium-ion:Lithium iron phosphate cathodes displace nickel-manganese-cobalt in utility tenders due to thermal stability and supply chain transparency. Manufacturing scale in China and South Korea compresses system costs below $150/kWh at the pack level. EU Battery Regulation carbon footprint disclosure requirements filter supplier eligibility by the mid-2030s.
- Flow Battery:Vanadium and iron-chromium chemistries enable 6-12 hour duration with unlimited cycle life and no capacity fade. Daily cycling economics favor these systems for solar shifting applications in Australia and South Africa where lithium-ion replacement costs dominate lifecycle analysis.
- Lead Acid:Mature recycling infrastructure and low capital cost sustain deployment in backup power and rural electrification. Telecom towers and off-grid installations in India and Southeast Asia continue procurement despite energy density limitations.
- Compressed Air:Underground cavern storage with thermal recovery achieves 70% round-trip efficiency in geologically suitable locations. Projects in Germany and China leverage salt dome formations for seasonal storage applications.
Lithium-ion holds the dominant technology position; Flow Battery is climbing the fastest in multi-hour duration procurement.
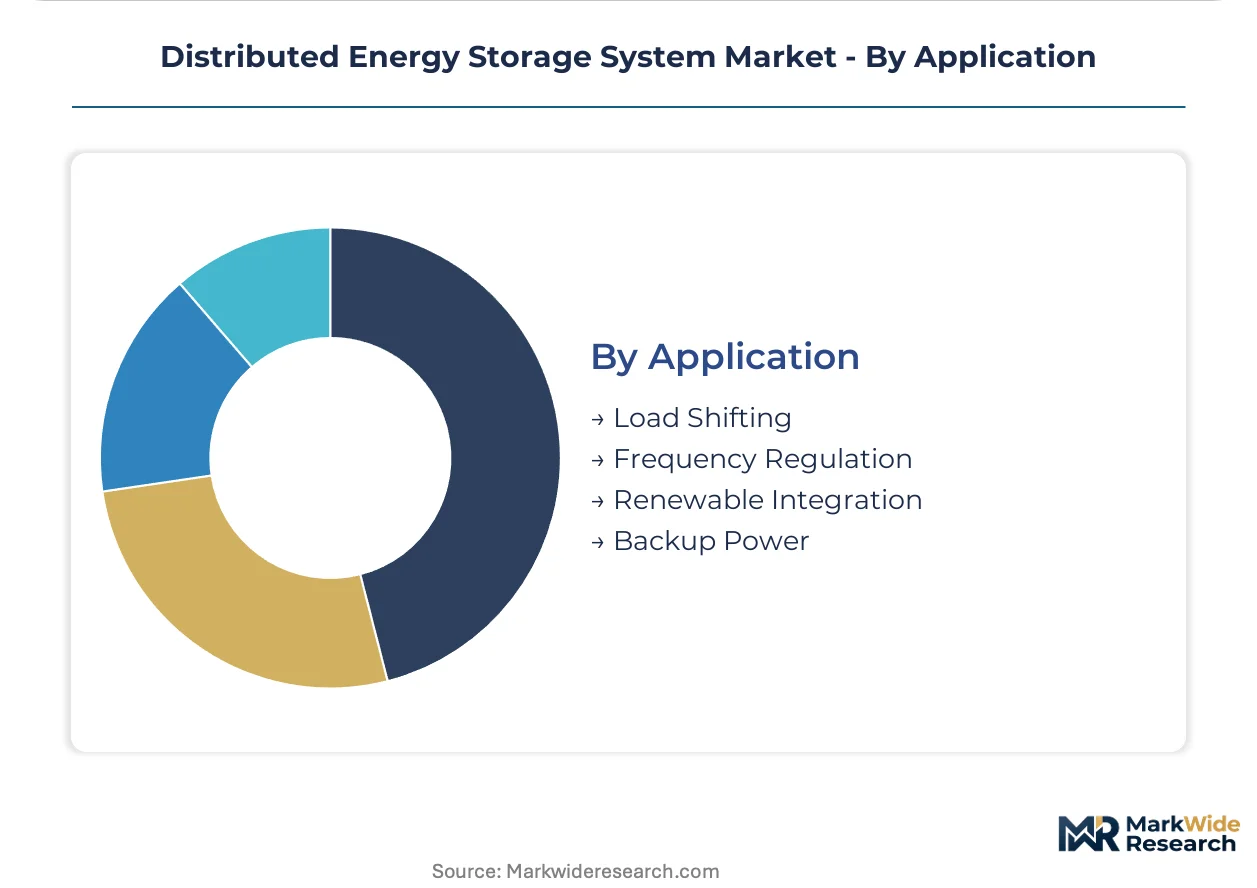
Application:
Revenue stacking complexity varies by application, with frequency regulation commanding premium pricing in deregulated markets and renewable integration driven by procurement mandates.
- Renewable Integration:Co-located storage smooths solar and wind output variability to meet grid code compliance and capture peak pricing spreads. China's NEA mandates 10-20% storage ratios for project approvals, creating policy-backed procurement floors. California's CPUC resource adequacy requirements force similar co-location economics.
- Frequency Regulation:Fast-responding assets maintain grid frequency within 60 Hz ±0.036 Hz through automatic generation control signals. PJM's RegD market and ERCOT's fast frequency response program compensate rapid ramp capability with mileage payments.
- Load Shifting:Time-of-use arbitrage moves energy consumption from peak to off-peak rate periods. Commercial and industrial facilities in deregulated US states with transparent nodal pricing optimize dispatch against day-ahead and real-time market spreads.
- Backup Power:Uninterruptible supply for critical loads during grid outages commands premium pricing in reliability-constrained regions. Data centers, hospitals, and semiconductor fabs in Taiwan and Singapore prioritize power quality over energy arbitrage returns.
Renewable Integration carries the largest project pipeline; Frequency Regulation is expanding most quickly in ancillary service market redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese cell manufacturers dominate global supply chains, while import dependency shapes procurement strategies in markets lacking domestic gigafactory capacity. The United States and European Union are accelerating reshoring incentives to reduce reliance on East Asian production hubs. Regional regulatory divergence is fragmenting certification requirements and complicating product platform standardization.
United States
Standalone storage investment tax credits from the Inflation Reduction Act compress project payback periods for utility-scale developers. FERC Order 2222 enables aggregated distributed resources to access wholesale markets, expanding revenue streams for behind-the-meter systems. Texas and California host the densest project pipelines, with ERCOT and CAISO interconnection queues stretching commercialization timelines.
China
Provincial grid codes from the National Energy Administration mandate 10-20% storage ratios for renewable project approvals, creating policy-backed procurement floors. The dual carbon goals framework accelerates co-location requirements for solar and wind developers. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta dominate cathode powder through container assembly vertical integration.
Germany
EU ETS carbon pricing improves thermal energy storage economics against gas-fired alternatives in district heating networks. The EU Battery Regulation establishes carbon footprint disclosure mandates that filter supplier eligibility by the mid-2030s. Industrial facilities in Bavaria and North Rhine-Westphalia deploy process-integrated storage where voltage sags cause million-euro production losses.
India
Production-linked incentives for advanced chemistry cell manufacturing attract gigafactory investment outside incumbent East Asian supply geographies. The Central Electricity Authority mandates storage obligations for interstate transmission-connected solar and wind projects. Telangana and Gujarat host emerging cell and pack assembly clusters serving domestic renewable integration demand.
Australia
Multi-hour duration procurement favors vanadium flow battery economics where daily cycling costs exceed lithium-ion degradation penalties. The country's national energy regulator redesigns ancillary service markets to compensate fast frequency response capability. South Australia and Queensland lead utility-scale deployment, with grid operators requiring storage co-location to manage renewable intermittency.
Distributed Energy Storage System Market Vendor Landscape
Concentration sits with integrated automotive-cell manufacturers and software-defined power electronics specialists. The vendor base stratifies across three tiers: captive vertical integrators with cathode-to-container control, modular hardware-software platform providers, and regional system integrators serving procurement-mandated markets. Automotive spin-offs leverage cell cost advantages from passenger vehicle scale. Independent power electronics firms anchor positions through dispatch optimization algorithms. Consolidation pressure intensifies as utility-scale tenders favor multi-hundred-megawatt project experience.
Within the integrated manufacturing tier, BYD Energy Storage and Tesla Energy exemplify archetypes of captive supply chain control. Fluence occupies a position among software-anchored platform providers. These three entities represent divergent strategic bets: backward integration into raw materials versus algorithmic dispatch optimization versus automotive cell architecture adaptation for stationary applications.
| Leading Market Players |
|---|
| Hitachi Energy |
| Tesla Energy |
| General Electric |
| Sungrow |
| ABB |
| Siemens Energy AG |
| Delta Electronics |
| Fluence |
| BYD Energy Storage |
| Others |
Supply Flow & Price Mechanics
Lithium iron phosphate cathode chemistry substitution for nickel-manganese-cobalt formulations simultaneously shifts procurement geography toward Chinese phosphate rock deposits and compresses pack-level pricing through manufacturing scale advantages in the Yangtze River Delta.
Pricing Analysis
Industrial OEM buyers anchor project-based contract structures with long-term offtake agreements dominating utility-scale procurement. Price differentiation rests on UL 9540A certification tier and cathode chemistry transparency rather than brand premium alone. Cost compression in containerized lithium-ion systems is intensifying because automotive cell manufacturers transfer passenger vehicle scale economies into stationary applications. Commercial and industrial behind-the-meter segments exhibit highest price sensitivity, while utility-scale developers prioritize cycle-life guarantees over upfront capital expenditure.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane expose inbound logistics vulnerabilities for European developers sourcing from East Asian production hubs. Cathode active material supply concentrates in China, South Korea, and Japan, with cylindrical and prismatic cell manufacturing drawing from concentrated East Asian production clusters. Raw material dependencies span lithium carbonate from South American brine operations, phosphate rock from Moroccan and Chinese mines, and electrolyte salts from Japanese chemical producers. Single-source vulnerability in cell supply exposes developers to disruption risk. Distribution runs through EPC contractors and direct utility procurement channels with limited aftermarket service integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry opportunities as FERC Order 2222 and China's NEA mandates spawn divergent certification requirements that favor specialized regional players over standardized global platforms.
For Market Incumbents: Secure backward integration into cathode powder production to defend margins against lithium carbonate volatility and emerging sodium-ion substitutes. Fluence-style software-anchored positions require continuous firmware investment to maintain dispatch optimization advantages as power electronics commoditize. BYD and Tesla Energy demonstrate how captive cell supply insulates against East Asian single-source concentration risk. For New Entrants and Emerging Players: Lead with iron-chromium flow battery technology in Australian and South African multi-hour duration tenders where daily cycling economics exceed lithium-ion degradation costs. India's PLI scheme for ACC batteries offers the most penetrable geography for manufacturing footprint establishment outside incumbent supply clusters. Target virtual power plant software platforms as the go-to-market angle for behind-the-meter commercial aggregation in deregulated US states with transparent nodal pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed power electronics specialists lacking cell supply control and software-defined dispatch capabilities. Long-term viability across the analysis window hinges on technology performance validation through multi-hundred-megawatt project experience rather than pilot deployment claims. Watch FERC interconnection queue clearance rates as the inflection signal indicating utility-scale revenue realization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Production | Captive phosphate rock supply from Moroccan deposits insulates BYD against lithium carbonate volatility. |
| Software-Defined Dispatch Platform Development | Fluence's algorithmic optimization across multiple revenue streams commands premium pricing in ERCOT and PJM markets. |
| Multi-Hour Duration Flow Battery Deployment | Vanadium systems in South Australia capture solar shifting economics where lithium-ion replacement costs dominate. |
| Virtual Power Plant Aggregation Scale-Up | California's NEM 3.0 export rate cuts accelerate commercial battery attachment rates for wholesale market participation. |
| EU Battery Regulation Compliance Certification | Carbon footprint disclosure mandates filter supplier eligibility by requiring European recycling partnerships. |
Methodological Framework
The analysis maps battery storage, thermal energy storage, flywheel systems, and pumped hydro configurations, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators across primary interviews combined with EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity installation tracking triangulates against top-down regulatory mandate analysis to verify market sizing.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation by product type, end user, technology chemistry, and application with regional grid type as an additional dimension. CAGRs derive from policy-backed procurement floor trajectories and technology cost curves. Key inputs include interconnection queue progression rates, lithium carbonate price indices, and flow battery deployment pipelines.
The analysis sits within stated boundaries; outcomes outside IRA tax credit continuity, Chinese dual carbon goal enforcement, or EU Battery Regulation implementation timelines would require recalibration. Forecasts reflect assumptions on cathode chemistry transition speeds and manufacturing scale expansion rates. Regulatory divergence across FERC Order 2222, China's NEA mandates, and EU carbon disclosure requirements present revision risks to standardization and service model portability assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
North America Battery Management System Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
EV Battery Management Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Energy Storage Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market