
 Automotive Energy Storage System Market | 2026-2036
Automotive Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Energy Storage System Market Outlook
Solid-state electrolyte research is tilting the technology stack away from conventional liquid-electrolyte architectures toward higher energy-density platforms. CATL sustains manufacturing scale across giga-factory deployments in multiple continents. Tesla leverages vertical control over cell-to-pack integration. LG Energy Solution anchors premium supply relationships with European OEM platforms.
An automotive energy storage system integrates electrochemical cells, thermal management hardware, and power electronics into a deployable unit rated typically between 50 kWh and 150 kWh for passenger applications, designed to store and discharge electrical energy for vehicle propulsion. Lithium-ion batteries dominate current production volumes while solid-state batteries attract the steepest R&D allocation due to their potential for energy density above 400 Wh per kilogram. Ultra-capacitors occupy niche regenerative braking applications where rapid charge acceptance outweighs total energy capacity. Fuel cells compete in heavy-duty segments requiring continuous power output beyond battery-economical thresholds.
The EU Battery Regulation mandates carbon footprint declarations and recycled content minimums for cells sold in member states, while China's MIIT enforces NEV credit quotas that directly determine OEM storage procurement volumes. The US EPA tailpipe standards and IRA domestic content rules are reshaping where battery assembly occurs. Stakeholders must monitor how regulatory divergence between Brussels, Beijing, and Washington affects cell chemistry roadmaps and localization timelines.
Market Dynamics
Solid-state electrolyte maturation is collapsing the traditional liquid-electrolyte value chain, compressing pack architectures and forcing thermal management redesigns across passenger and commercial vehicle platforms.
Growth Catalysts
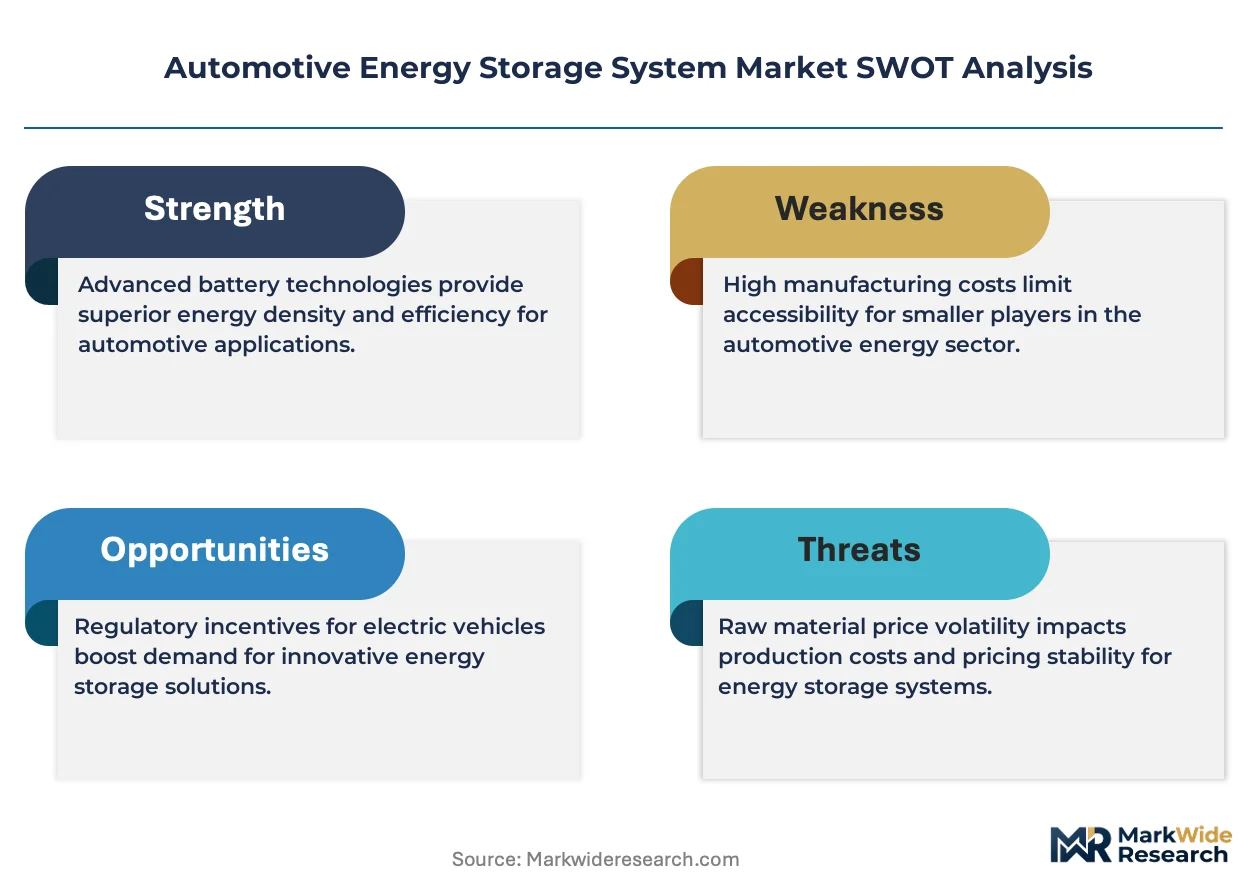
- EU Battery Regulation carbon mandates:Recycled content minimums for cells sold in member states are accelerating closed-loop material recovery investments and pack redesigns toward disassembly.
- China MIIT NEV credit quotas:OEM procurement volumes now tie directly to government-mandated new energy vehicle production targets, pulling lithium-ion capacity expansion.
- Cell-to-pack integration:Structural battery architectures are eliminating module housings, reducing pack mass and assembly steps for electric vehicle platforms.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress cell manufacturer margins and destabilize long-term OEM supply contracts.
- Electrolyte supply concentration:Liquid electrolyte production clusters in East Asian chemical corridors create single-source vulnerability for European and North American cell plants.
- Solid-state manufacturing yield gaps:Ceramic electrolyte sintering defects and dendrite suppression failures limit production scale-up below commercial thresholds.
Strategic Opportunities
- India PLI scheme for ACC storage:Production-linked incentives for advanced chemistry cell manufacturing are attracting giga-factory commitments outside traditional Asian supply hubs.
- Heavy-duty fuel cell hybridization:Long-haul trucking applications combining batteries with hydrogen fuel cells address range and payload requirements beyond pure battery economics.
- Second-life stationary storage:Retired automotive packs are repurposing for grid stabilization, creating circular revenue streams from degradation-tolerant applications.
Industry Challenges
- Solid-state process engineering talent scarcity:Thin-film deposition and ceramic processing expertise concentrates in semiconductor and aerospace sectors, not automotive battery manufacturing.
- UN 38.3 lithium transport certification:Air and maritime shipping approvals for prototype cells create timeline friction for R&D programs spanning multiple geographies.
- Legacy thermal management integration:Existing vehicle platform cooling architectures resist adaptation to cell-to-pack designs without structural floor pan redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Energy Storage System Market |
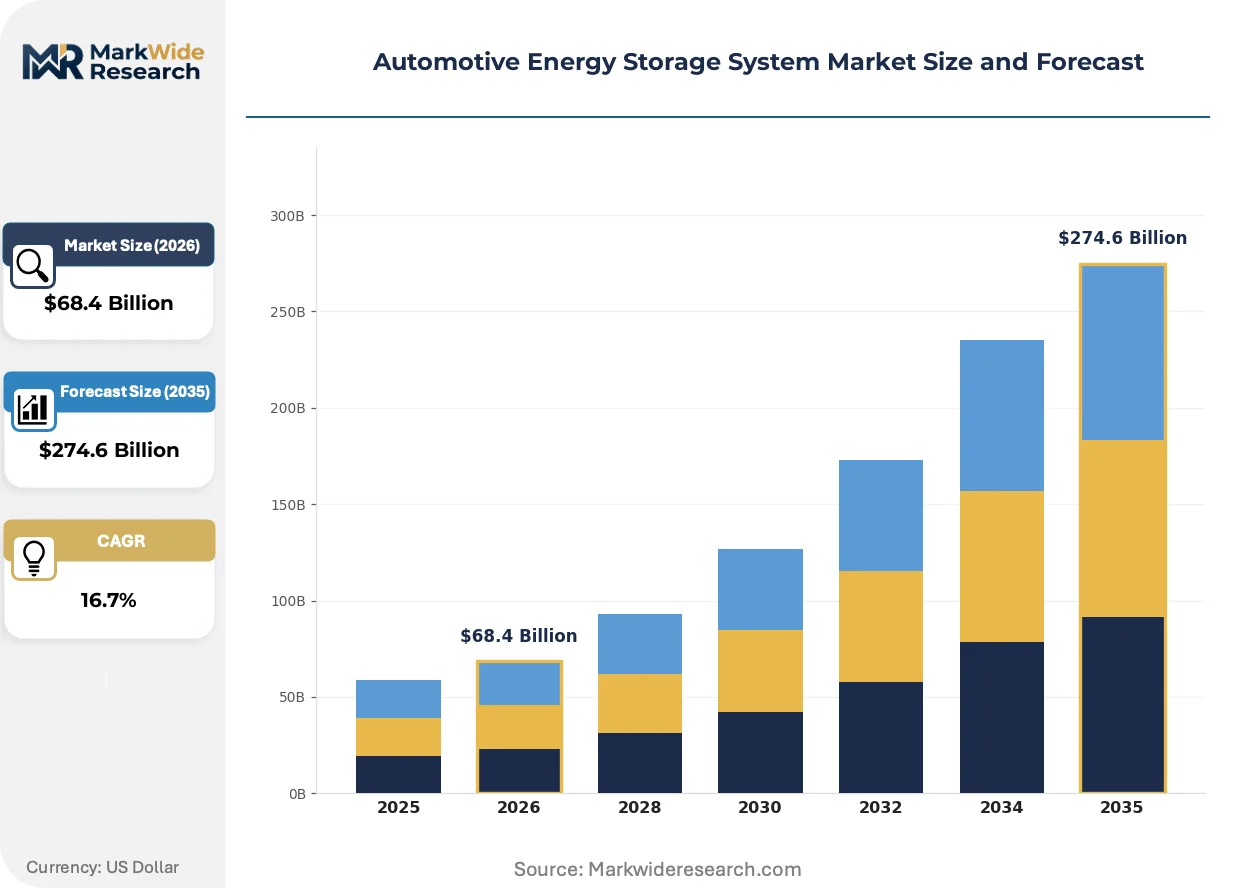
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $274.6 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion Batteries, Lead-acid Batteries, Nickel-metal Hydride, Solid-state Batteries Technology: Ultra-capacitors, Fuel Cells, Thermal Energy Storage, Flywheel Energy Storage Application: Electric Vehicles, Hybrid Vehicles, Public Transport, Energy Management Systems End User: OEMs, Aftermarket Providers, Fleet Operators, Utility Companies |
| Companies Covered | Tesla, LG Energy Solution, Samsung SDI, Panasonic Holdings Corporation, BYD Company Limited, Contemporary Amperex Technology Co. Limited (CATL), Siemens Energy, ABB Ltd., General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Energy Storage System Market Strategic Shifts
Electrochemical architecture convergence with structural vehicle engineering is eliminating discrete battery enclosures, merging energy storage with chassis load-bearing functions.
Solid-state lithium-metal anodes are collapsing the energy density ceiling that constrained liquid-electrolyte systems. Automotive OEMs are qualifying sulfide and oxide electrolyte formulations for 2027-2028 platform launches. This chemistry transition is compressing incumbent cathode-active-material supply commitments and redirecting capital toward dry-electrode coating equipment.
REACH substance restrictions on nickel and cobalt compounds are forcing cathode chemistry pivots toward lithium-iron-phosphate and manganese-rich alternatives. Cell manufacturers are reformulating active materials to maintain energy density while satisfying substance authorization timelines. European OEM procurement specifications now embed compliance documentation requirements that Asian suppliers are racing to meet.
Fleet operators are consolidating storage procurement through direct cell-of-origin contracts, bypassing traditional tiered supplier hierarchies. Commercial vehicle buyers in Germany and California are negotiating giga-factory offtake agreements that lock capacity years ahead of delivery. This disintermediation is compressing margins for pack integrators who lack captive cell supply or vertical control over thermal management hardware.
Automotive Energy Storage System Market Segmentation
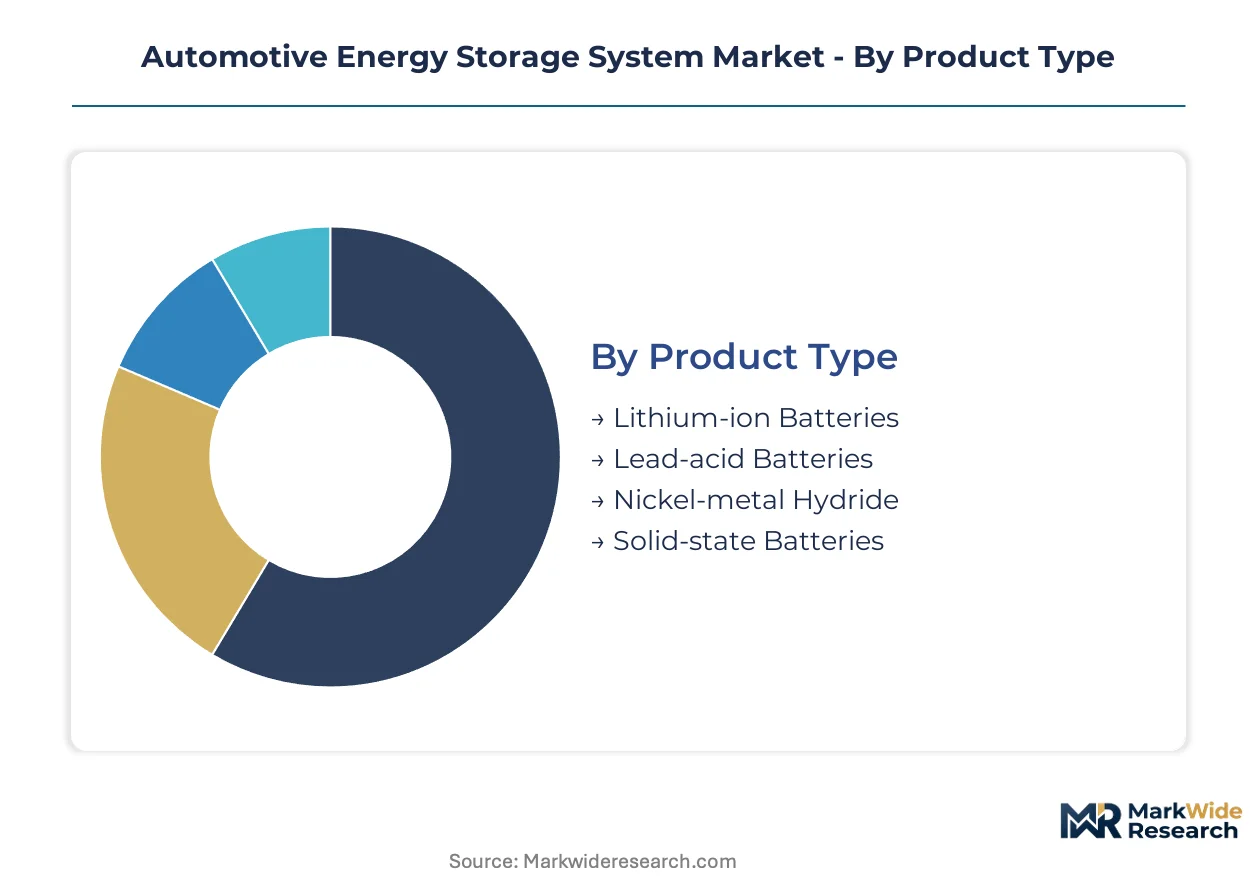
Automotive energy storage segmentation reveals divergent replacement cycles across chemistries and architectures. Product type distinctions drive procurement timing, while application segments determine thermal management specifications and pack sizing requirements.
Product Type:
Lithium-ion platforms turn over fastest as cathode formulations iterate, while lead-acid architectures persist longest in auxiliary roles. Solid-state development cycles compress as OEMs accelerate qualification timelines.
- Lithium-ion Batteries:Layered oxide cathodes paired with graphite or silicon-blend anodes deliver 250-300 Wh/kg energy density for mainstream passenger platforms. CATL and LG Energy Solution are expanding NCM and LFP cell output across Germany, South Korea, and US manufacturing corridors to serve Tesla, Volkswagen, and Hyundai-Kia platform launches. Demand concentrates where IRA domestic content rules and EU Battery Regulation carbon mandates reshape procurement geography.
- Solid-state Batteries:Ceramic electrolyte architectures employing sulfide or oxide formulations target 400+ Wh/kg density with lithium-metal anodes. Toyota and QuantumScape are pushing sulfide-based designs toward production scale, though ceramic sintering defects and dendrite suppression failures constrain manufacturing yields below commercial thresholds. Expansion concentrates in premium passenger segments where energy density premiums offset unit costs.
- Lead-acid Batteries:Mature flooded and absorbed glass mat designs retain 12V auxiliary power roles in internal combustion and hybrid architectures. Johnson Controls and Clarios supply engine starting and cabin electronics backup across legacy vehicle parcs.
- Nickel-metal Hydride:Toyota sustains production for hybrid electric vehicle applications where proven thermal stability outweighs lithium-ion energy density advantages. Panasonic remains the primary cell supplier for Prius and Camry hybrid platforms.
Lithium-ion batteries dominate installed base. Solid-state batteries are where expansion concentrates.
Technology:
Cost tiers separate mass-market electrochemical storage from premium power-dense alternatives. Ultra-capacitors command highest per-kWh pricing but deliver unmatched cycle life for specific duty cycles.
- Ultra-capacitors:Electric double-layer capacitors using activated carbon electrodes achieve 100,000+ charge cycles with 95% round-trip efficiency. Skeleton Technologies supplies banks for Kinetic TAF urban buses in Estonia and Poland where regenerative braking frequency exceeds battery economical thresholds.
- Fuel Cells:Proton-exchange membrane stacks converting hydrogen to electricity serve long-haul trucking above 500-mile daily ranges. Hyundai Motor Group and Daimler Truck are deploying XCIENT and GenH2 platforms across Germany and California freight corridors where battery weight penalties erode payload capacity.
- Thermal Energy Storage:Phase-change materials and heated coolant reservoirs capture waste heat for cabin conditioning. BMW and Volkswagen integrate these systems to reduce winter range penalties in Nordic markets.
- Flywheel Energy Storage:Composite rotor systems storing kinetic energy occupy motorsport and grid stabilization niches. Williams Advanced Engineering supplies flywheel hybrids for Formula E regenerative braking recovery.
Fuel cells anchor heavy-duty installed base. Ultra-capacitors are climbing the fastest in urban transit applications.
Application:
Volume concentration varies dramatically across mobility modes, with passenger platforms consuming multiple orders of magnitude more cell capacity per unit than stationary derivatives.
- Electric Vehicles:Battery electric platforms integrate 60-100 kWh packs with cell-to-pack architectures eliminating module housings. Tesla's structural battery designs and BYD's blade cell configurations are compressing pack mass and assembly steps across sedan and SUV form factors.
- Hybrid Vehicles:Power-split and PHEV architectures employ 1-15 kWh batteries for electric-only urban segments and torque supplementation. Toyota and Honda dominate this segment where smaller pack sizes reduce lithium exposure and thermal management complexity.
- Public Transport:Electric buses and rail systems deploy 200-400 kWh depot-charged or opportunity-charged configurations. BYD and Yutong supply battery-electric bus fleets to Shenzhen, Santiago, and European municipal operators under EU Clean Vehicle Directive procurement rules.
- Energy Management Systems:Vehicle-to-grid and second-life stationary applications repurpose degraded automotive packs for grid stabilization. Renault and Nissan are deploying retired LEAF batteries across French and Japanese utility partnerships.
Electric vehicles dominate installed base. Energy management systems are gaining share fastest as circular economy mandates mature.
End User:
Customer type determines contract structure, with OEMs locking multi-year supply agreements while fleet operators negotiate direct cell-of-origin arrangements.
- OEMs:Volkswagen, General Motors, and Stellantis negotiate giga-factory offtake agreements covering 5-10 year horizons. These contracts embed chemistry roadmaps, pricing escalators, and localization requirements responsive to IRA and EU Battery Regulation compliance timelines.
- Fleet Operators:DHL, Amazon, and Deutsche Post are consolidating procurement through direct CATL and BYD cell contracts, bypassing traditional tiered supplier hierarchies. German and California commercial vehicle buyers lock capacity years ahead of delivery.
- Aftermarket Providers:Independent service facilities and remanufacturers address warranty replacements and performance upgrades outside OEM channel control. These operators face UN 38.3 lithium transport certification friction for prototype and refurbished cell movements.
- Utility Companies:Grid operators and renewable developers source second-life automotive packs and dedicated stationary systems for frequency regulation and peak shaving. EDF and Enel are deploying vehicle-to-grid pilots across French and Italian distribution networks.
OEMs dominate installed base. Fleet operators are where procurement pattern disruption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports lithium-ion cells to German automotive OEMs along the busiest trade corridor in automotive energy storage, with containerized cell shipments routing through Hamburg and Bremerhaven for final pack assembly.
Germany
Volkswagen and BMW procurement teams are locking decade-long offtake agreements with Korean suppliers. The EU Battery Regulation carbon footprint declarations are forcing pack redesigns toward disassembly-friendly architectures. The Stuttgart automotive corridor hosts cell-to-pack integration facilities serving premium sedan platforms.
China
CATL and BYD are expanding giga-factory capacity across multiple provinces to meet MIIT NEV credit quota obligations. Domestic content rules under the dual carbon goals framework are redirecting cathode active material sourcing. The Yangtze River Delta battery manufacturing cluster anchors global lithium-ion output volume.
United States
Tesla and General Motors are qualifying cell suppliers against IRA domestic content thresholds for consumer tax credit eligibility. The EPA tailpipe standards are compressing internal combustion platform timelines. Michigan and Texas manufacturing corridors are attracting Korean and Japanese cell plant investments.
South Korea
LG Energy Solution and Samsung SDI are shipping NCM cells to European OEMs under long-term supply contracts. The MFDS chemical substance tracking requirements are aligning with REACH substance restrictions. The Ulsan-Gwangju battery belt concentrates electrolyte formulation and electrode coating capacity.
India
Reliance Industries and Ola Electric are bidding for PLI scheme ACC storage manufacturing licenses. The BIS certification requirements for lithium-ion cells are tightening import quality gates. The Gujarat and Tamil Nadu industrial corridors are attracting giga-factory commitments outside traditional Asian supply hubs.
Automotive Energy Storage System Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers. Tier-one players control captive cathode active material supply and cell-to-pack integration. Tier-two specialists concentrate on thermal management hardware and power electronics. Tier-three assemblers lack upstream chemical processing and depend on spot market cell procurement. Dominant competitive moves include backward integration into lithium refining and geographic relocation of electrode coating capacity to satisfy IRA and EU Battery Regulation localization mandates.
Within the integrated manufacturing tier, Tesla and Contemporary Amperex Technology Co. Limited exemplify divergent scale strategies. Tesla represents North American vertical control over structural battery architectures. CATL occupies a position as the dominant Chinese cell supplier with multi-continent giga-factory deployment. LG Energy Solution anchors the Korean premium supply archetype serving European OEM platform launches.
| Leading Market Players |
|---|
| Tesla |
| LG Energy Solution |
| Samsung SDI |
| Panasonic Holdings Corporation |
| BYD Company Limited |
| Contemporary Amperex Technology Co. Limited (CATL) |
| Siemens Energy |
| ABB Ltd. |
| General Electric |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Bremerhaven container corridor routes Korean lithium-ion cells to German OEM pack assembly facilities, with freight cost volatility amplifying price spreads between captive-giga-factory supply and spot-market procurement. This logistics artery concentrates pricing power among cell manufacturers with multi-continent manufacturing footprints, while downstream buyers face divergent landed costs depending on IRA domestic content qualification and EU Battery Regulation carbon compliance tiers.
Pricing Analysis
Next-generation solid-state cell pricing commands multiples over current-generation lithium-ion platforms, while prior-generation nickel-metal hydride architectures occupy residual value tiers in hybrid applications. Contract-based long-term offtake agreements dominate OEM procurement, embedding volume scale and certification grade (UL 2580, UN 38.3) as primary price differentiation drivers. Pricing pressure stems from lithium carbonate spot market swings compressing cell manufacturer margins. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while premium passenger OEMs absorb energy density premiums for platform differentiation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Korean trading houses enable electrode coating equipment imports for Indian PLI scheme participants. Raw material flows concentrate in China, South Korea, and Australia for lithium spodumene and cathode active materials. The supply chain draws from Indonesian nickel processing and Chilean lithium brine operations. Single-source vulnerability in sulfide electrolyte precursor chemicals creates concentration risk. Distribution runs through tiered supplier hierarchies with cell-to-pack integrators serving OEM final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to NEV credit quota resets and subsidy regime transitions across major automotive production regions. OEM procurement cycles and raw material inventory destocking amplify demand volatility through the recovery phase.
For Market Incumbents: Harden cathode active material supply through backward integration into lithium refining or captive offtake from Australian and Chilean producers. Secure electrode coating capacity in Michigan and Texas manufacturing corridors to satisfy IRA domestic content thresholds. Defend against solid-state entrants by accelerating dry-electrode process qualification and locking European OEM platform engineering commitments.
For New Entrants and Emerging Players: Pursue second-life stationary storage applications where degradation-tolerant revenue streams bypass automotive qualification barriers. Target Indian PLI scheme manufacturing licenses as the most penetrable geography given nascent local capacity and government incentive coverage. Establish direct utility partnerships for grid stabilization deployments rather than competing through OEM tiered supply chains.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded thermal management hardware divisions lacking cell chemistry integration. Long-term viability centers on solid-state process engineering capabilities and ceramic sintering yield improvement. Watch sulfide electrolyte defect rates as the inflection signal for manufacturing scale readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Deployment | Tesla and BYD structural battery designs eliminate module housings, reducing pack mass and assembly steps. |
| Solid-State Electrolyte Qualification | Toyota and QuantumScape sulfide formulations target premium passenger segments with 400+ Wh/kg density. |
| Giga-Factory Geographic Expansion | CATL multi-continent deployments satisfy EU Battery Regulation carbon mandates and IRA domestic content rules. |
| Second-Life Stationary Repurposing | Renault and Nissan retired LEAF batteries deploy across French and Japanese utility grid stabilization partnerships. |
| Direct Fleet Procurement Contracts | DHL and Amazon bypass tiered suppliers through direct CATL and BYD cell-of-origin agreements. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, and aftermarket distributors; and secondary validation against SEC 10-K filings, vehicle production databases, and IHS Markit registration data. Bottom-up cell capacity buildouts and top-down OEM procurement commitments were triangulated to reconcile supply and demand estimates across the analysis window.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation. CAGRs were derived from modeled cell demand trajectories against qualified manufacturing capacity expansion timelines. Analytical outputs incorporate lithium carbonate price elasticity, NEV credit quota compliance schedules, and solid-state yield improvement curves without specifying intervention points.
Macroeconomic conditions sit as an overlay; deviation in interest rate regimes and industrial commodity indices would shift the trajectory of giga-factory financing and cathode active material sourcing economics. Forecasts reflect assumptions regarding regulatory stability in subsidy and carbon accounting frameworks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Renewable Battery Storage Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
Power Battery Management System Market
Battery Management System
EV Battery Management Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
North America Battery Management System Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Energy Storage Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Battery Management Market
Battery Management System
Global Power Management System Market
Battery Management System
South America Battery Energy Storage System Market