
 Global Power Management System Market | 2026-2036
Global Power Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Management System Market Foresight
East Asian semiconductor foundries is restructuring power procurement strategies as wafer fabrication scales to 3nm nodes and below. Siemens leverages deep domain expertise in grid automation software to anchor European utility contracts. ABB sustains technology leadership through high-voltage direct current integration with digital twin architectures. Schneider Electric differentiates via end-to-end microgrid solutions spanning generation controls to load balancing algorithms.
A power management system coordinates generation, distribution, and consumption of electrical energy through real-time monitoring, automated switching, and demand-side load optimization, typically operating across voltage classes from 480V industrial feeders to 345kV transmission interfaces. The primary purpose centers on minimizing energy waste, preventing equipment damage from sags or harmonics, and enabling seamless renewable intermittency absorption. Energy Storage Systems command the deepest margin pools as lithium-ion and emerging solid-state chemistries require sophisticated charge-discharge orchestration. IoT-enabled Controls represent the fastest-expanding technology segment as edge computing architectures reduce latency for protective relay decisions. Cloud-based Management retains mature growth profiles in utility-scale deployments where cybersecurity latency tolerances remain permissive.
EU Green Deal efficiency mandates, FERC Order 2222 aggregation standards in the United States, and Japan's METI carbon neutrality roadmap collectively reshape product certification requirements and market access conditions for power management vendors. EMA energy performance directives and REACH substance restrictions further constrain component sourcing for equipment destined for European grid interconnection. Stakeholders must monitor evolving interoperability standards between proprietary SCADA protocols and open-source IoT frameworks as procurement specifications shift toward vendor-agnostic system architectures.
Market Dynamics
Data center operators are forcing a fundamental recalibration of power management architectures as AI training clusters push rack densities past 50kW, requiring real-time orchestration between on-site generation, battery storage, and grid interconnection that legacy SCADA systems cannot deliver.
Growth Catalysts
- FERC Order 2222:The US aggregation standard enables distributed energy resource participation in wholesale markets, compelling utilities to deploy advanced management platforms for bidirectional grid coordination.
- Wafer fabrication scaling:East Asian semiconductor foundries now require sub-15ms power quality response at 3nm nodes, driving procurement of solid-state transfer switches and dynamic voltage restorers.
- EU Green Deal efficiency mandates:Germany's national implementation tightens minimum performance standards for grid-connected industrial equipment, accelerating replacement cycles across manufacturing bases.
Market Restraints
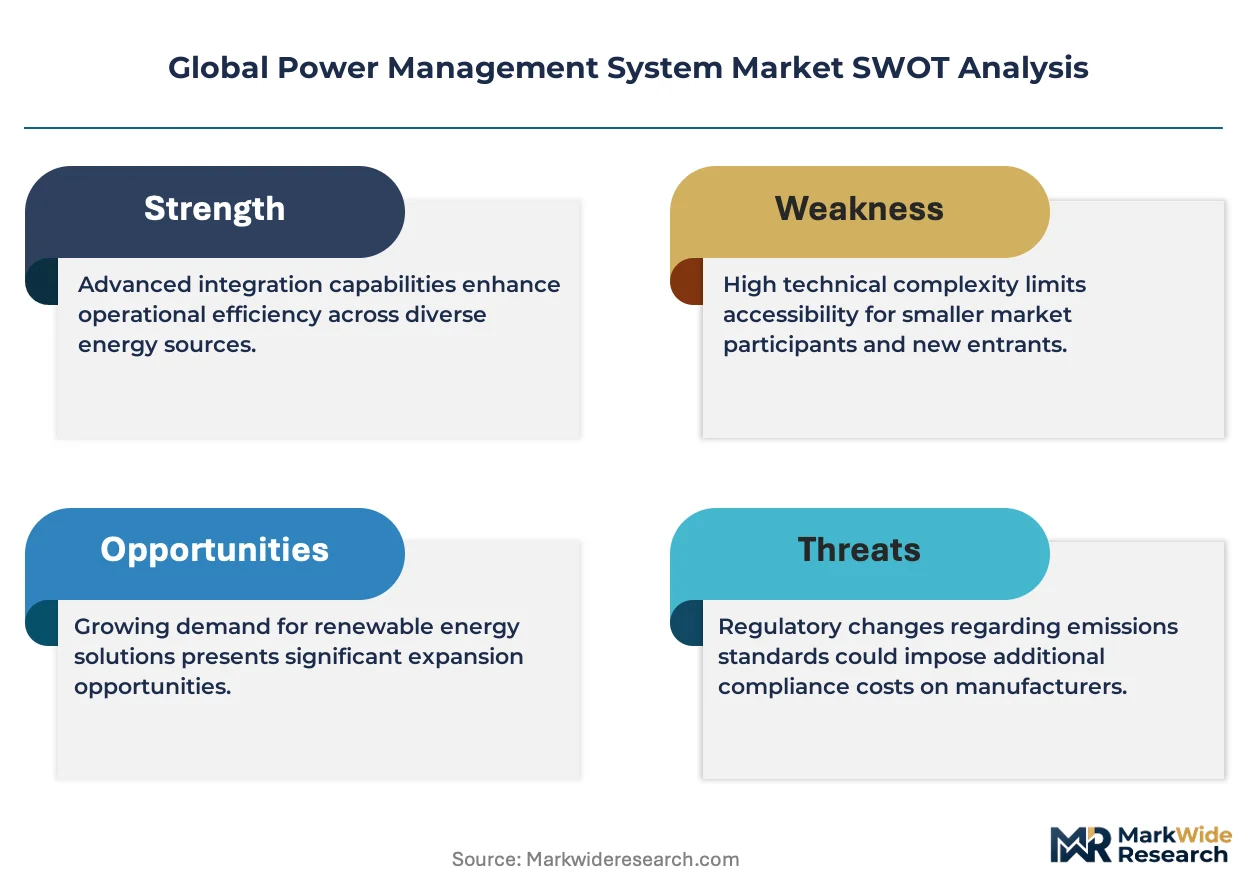
- Silicon carbide substrate shortages:Power electronics manufacturers face 40-week lead times for high-purity SiC wafers, constraining inverter and converter output capacity.
- Technical interoperability gaps:Proprietary Modbus and DNP3 protocols resist seamless integration with open-source MQTT frameworks, forcing costly middleware development.
- Substitution pressure from passive power quality devices:Static VAR compensators and harmonic filters capture budget-constrained industrial segments that cannot justify full digital management platforms.
Strategic Opportunities
- India's renewable integration imperative:The country's central electricity authority mandates renewable purchase obligations that distribution companies cannot meet without distributed management systems for solar-wind hybrid parks.
- Maritime electrification:Port authorities in Rotterdam and Singapore now require shore power connections for container vessels, creating demand for vessel-to-grid synchronization controllers.
- Edge computing convergence with protective relaying:Microsecond fault detection at substation perimeters enables new service models for grid operators seeking to defer transmission upgrades.
Industry Challenges
- Cyber-physical systems engineering talent scarcity:Vendors struggle to recruit professionals fluent in both IEC 61850 substation automation and NIST cybersecurity frameworks.
- Multi-vendor integration complexity:End-users face 18-month commissioning timelines when marrying ABB switchgear with Schneider Electric control layers and third-party battery management systems.
- Certification timeline compression:UL 1741-SA grid support utility interactive inverters now require updated test sequences for voltage ride-through that delay product launches by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Management System Market |
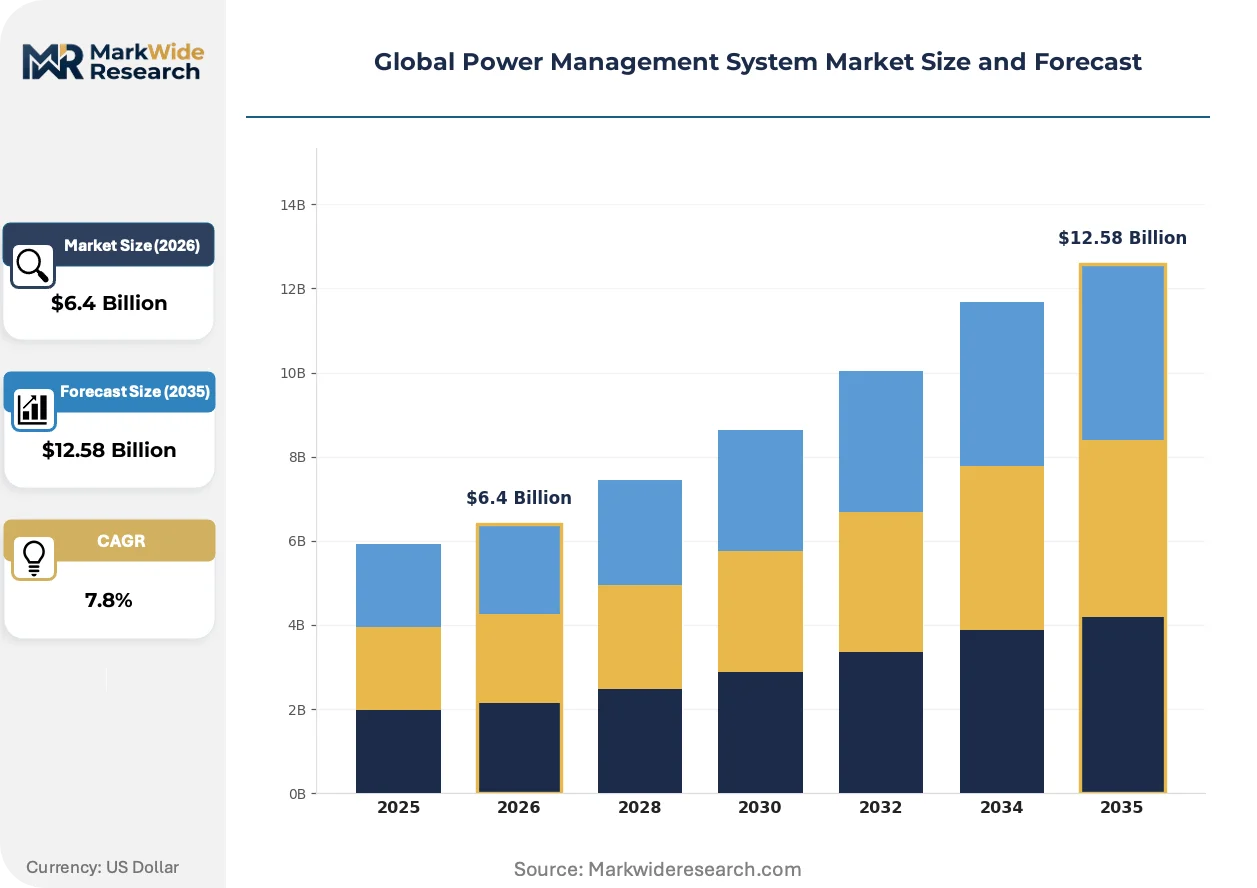
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
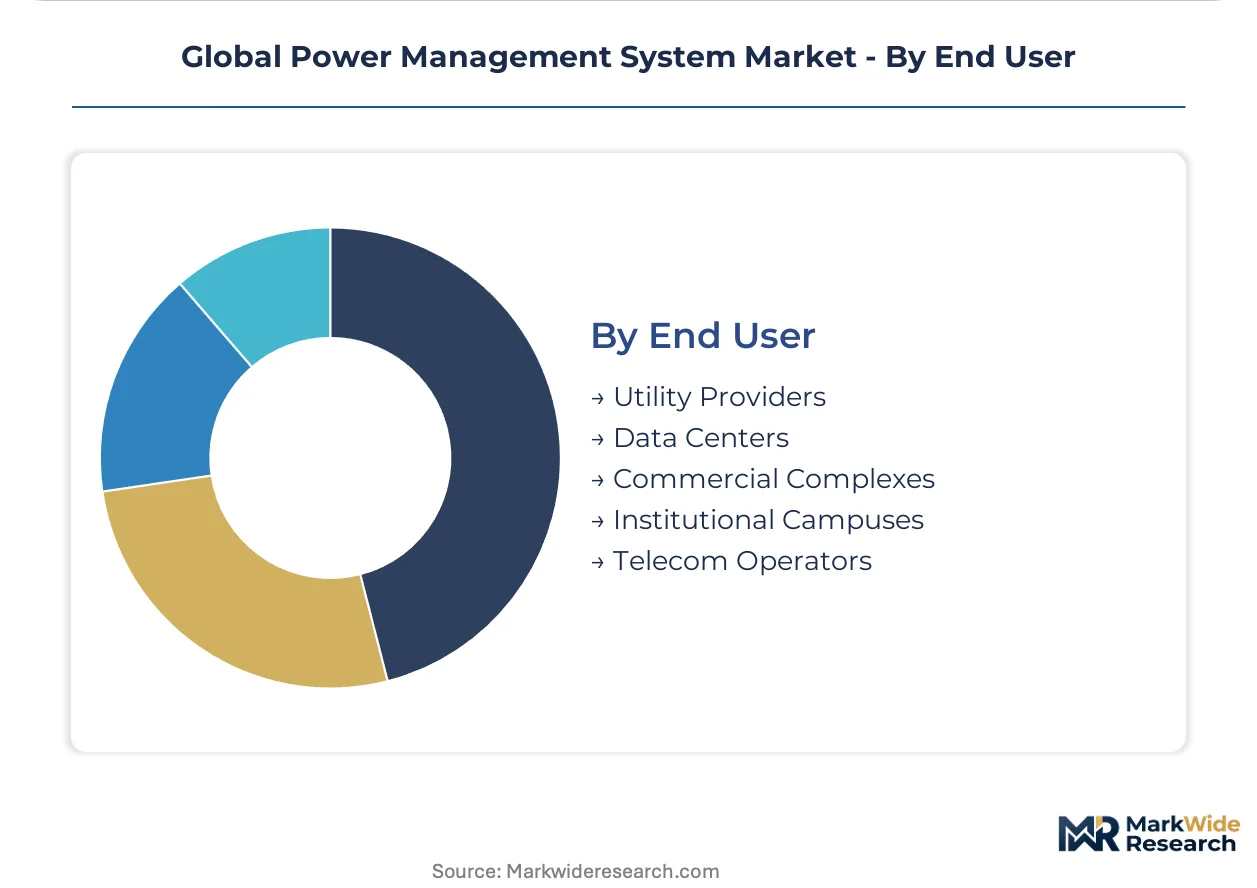
| Segmentation | Product Type: Smart Meters, Energy Storage Systems, Voltage Regulators, Load Management Units, Power Conditioners Technology: SCADA, IoT-enabled Controls, Wireless Sensor Networks, Cloud-based Management, Predictive Analytics Application: Renewable Energy Integration, Grid Automation, Demand Response, Microgrid Solutions, Electric Fleet Management End User: Utility Providers, Data Centers, Commercial Complexes, Institutional Campuses, Telecom Operators |
| Companies Covered | General Electric, Emerson Electric Co., ABB, Rockwell Automation, Honeywell International Inc., Schneider Electric, Eaton, ETAP, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Management System Market Shifts & Advancements
Digital twin architectures are collapsing the boundary between physical power infrastructure and software-defined control, enabling predictive maintenance and scenario simulation that reduces unplanned outages. This convergence is accelerating procurement cycles for integrated hardware-software platforms.
Silicon carbide power semiconductors are rewriting thermal and efficiency constraints for medium-voltage converters. Data center operators in Ashburn and Frankfurt now specify SiC-based uninterruptible power supplies for 3% efficiency gains that compound across 100MW deployments. The technology is compressing payback periods for premium equipment tiers from seven years to under four.
Japan's METI carbon neutrality roadmap mandates grid-forming inverter capabilities for all new solar installations above 50kW from fiscal year 2025. Equipment manufacturers must redesign control algorithms to provide synthetic inertia and frequency response previously delivered by rotating machinery. Domestic suppliers are accelerating certification timelines to capture replacement demand from 12GW of existing solar capacity.
Hyperscale cloud providers are consolidating procurement authority for power infrastructure previously managed by individual facility operators. Amazon Web Services and Microsoft Azure now negotiate enterprise-wide frameworks with ABB, Siemens, and Schneider Electric, displacing the fragmented site-by-site purchasing that characterized data center construction through 2020. This concentration is most visible in Northern Virginia's Data Center Alley, where three buyers now account for majority capacity additions.
Global Power Management System Market Segmentation
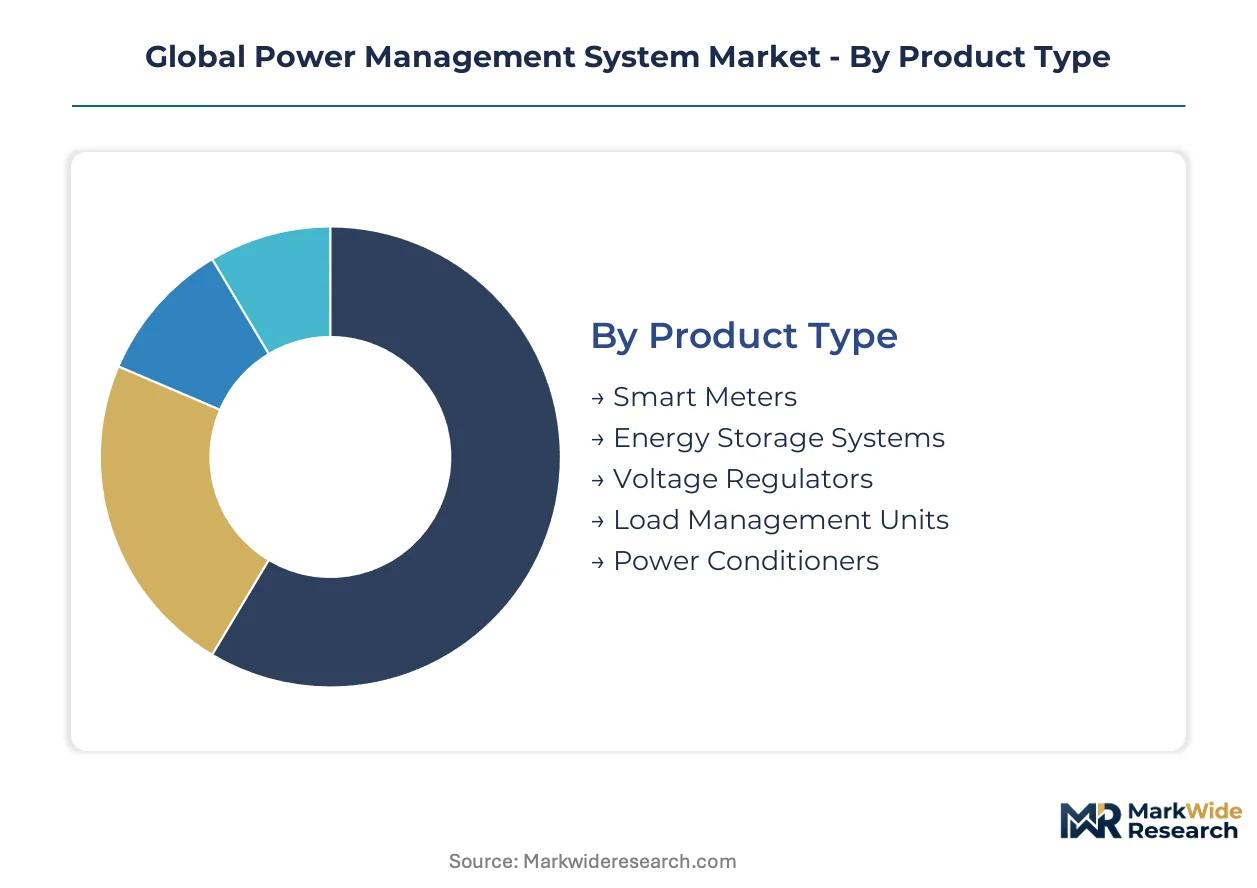
Power management system procurement specifications diverge sharply across deployment contexts, with certification requirements for grid-interactive equipment creating natural segment boundaries. Vendors must align product architectures with distinct regulatory pathways that govern everything from residential smart metering to utility-scale storage integration.
Product Type:
UL 1741-SA certification for grid support interactive inverters applies selectively across this category, with Energy Storage Systems and Smart Meters facing the most stringent test sequence updates from NERC and regional transmission organizations.
- Smart Meters:Advanced metering infrastructure devices incorporate bidirectional communication modules for real-time consumption feedback and remote disconnect capabilities. North American utilities dominate procurement as FERC Order 2222 aggregation standards compel distribution operators to deploy interval metering for distributed resource participation.
- Energy Storage Systems:Lithium-ion and emerging solid-state battery configurations require sophisticated battery management systems with thermal runaway prevention and charge-discharge orchestration. Data center operators in Ashburn and Frankfurt now specify these systems for 50kW+ rack density support, driving premium tier demand.
- Voltage Regulators:Tap-changing transformers and static VAR compensators maintain feeder voltage within ANSI C84.1 bounds.
- Load Management Units:Demand response controllers enable automated curtailment signals from grid operators to industrial facilities.
- Power Conditioners:Active harmonic filters and dynamic voltage restorers protect sensitive semiconductor fabrication loads.
Smart Meters sits at the top of the volume ranking, with Energy Storage Systems climbing the fastest.
Technology:
Cost stratification separates legacy SCADA deployments from premium IoT-enabled architectures, with wireless sensor networks occupying a mid-tier position for retrofit applications where full infrastructure replacement is uneconomical.
- SCADA:Supervisory control and data acquisition platforms remain entrenched in utility transmission operations where proprietary Modbus and DNP3 protocols resist migration. European grid operators maintain these systems under EU Green Deal efficiency mandates that prioritize operational continuity over architectural modernization.
- IoT-enabled Controls:Edge computing architectures reduce protective relay decision latency to sub-15ms thresholds required by East Asian semiconductor foundries. South Korea's smart grid investments concentrate procurement for these systems in the Incheon and Yongin manufacturing corridors.
- Wireless Sensor Networks:LoRaWAN and 5G private network deployments enable retrofit monitoring without fiber trenching.
- Cloud-based Management:Centralized analytics platforms serve utility-scale deployments where cybersecurity latency tolerances remain permissive.
- Predictive Analytics:Machine learning models forecast transformer failure and optimize maintenance scheduling.
SCADA retains the largest installed base, though IoT-enabled Controls is expanding most quickly as foundry power quality requirements tighten.
Application:
Application selection correlates directly with customer technical maturity, with Microgrid Solutions commanding the longest sales cycles and Electric Fleet Management representing the newest procurement category with evolving standards.
- Renewable Energy Integration:Grid-forming inverter capabilities and synthetic inertia provision address solar and wind intermittency challenges. Japan's METI carbon neutrality roadmap mandates these functions for all new solar installations above 50kW, compelling algorithm redesigns from domestic suppliers.
- Grid Automation:Substation automation and feeder reconfiguration reduce outage duration through self-healing network topologies. Germany's national implementation of EU Green Deal efficiency standards accelerates replacement cycles across manufacturing bases for these systems.
- Demand Response:Automated load curtailment programs align industrial consumption with wholesale price signals.
- Microgrid Solutions:Islanding capabilities and seamless grid reconnection serve institutional campuses and remote installations.
- Electric Fleet Management:Vehicle-to-grid synchronization and depot charging optimization support port electrification requirements in Rotterdam and Singapore.
Grid Automation leads current deployment value, while Electric Fleet Management shows the steepest expansion trajectory as maritime and logistics electrification accelerates.
End User:
Customer concentration patterns reveal hyperscale consolidation in data center procurement, with three buyers now accounting for majority capacity additions in Northern Virginia's Data Center Alley, while utility procurement remains fragmented across regional transmission organizations.
- Utility Providers:Transmission and distribution operators deploy wide-area management systems for voltage regulation and fault isolation. India's Central Electricity Authority renewable purchase obligations compel distribution companies to procure distributed management systems for solar-wind hybrid parks.
- Data Centers:Hyperscale cloud providers now negotiate enterprise-wide frameworks with major equipment vendors, displacing fragmented site-by-site purchasing. AI training clusters pushing past 50kW rack densities force real-time orchestration between generation, storage, and grid interconnection.
- Commercial Complexes:Retail and office building operators pursue peak demand charge reduction through automated load shifting.
- Institutional Campuses:Universities and medical centers deploy microgrids for resilience and sustainability targets.
- Telecom Operators:Base station power systems require battery backup and diesel generator coordination for grid reliability.
Utility Providers maintain the deepest historical penetration, though Data Centers is gaining share fastest as AI infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting power management system procurement toward jurisdictions where carbon compliance costs remain below EU levels. Manufacturers now site advanced converter production in Southeast Asia to serve European demand without incurring full EU Green Deal certification overhead.
United States
FERC Order 2222 aggregation standards compel utilities to deploy distributed energy resource management platforms for wholesale market participation. Independent system operators in Texas and California now require grid-forming inverter capabilities for new solar interconnections above 5MW. Northern Virginia's Data Center Alley concentrates hyperscale procurement, with three buyers commanding majority capacity additions.
Germany
The national implementation of EU Green Deal efficiency mandates tightens minimum performance standards for grid-connected industrial equipment. Manufacturing bases across Bavaria and North Rhine-Westphalia face accelerated replacement cycles for legacy switchgear and substation automation. Siemens anchors European utility contracts through deep domain expertise in grid automation software.
Japan
METI's carbon neutrality roadmap mandates grid-forming inverter capabilities for all new solar installations above 50kW from fiscal year 2025. Domestic suppliers accelerate certification timelines to capture replacement demand from 12GW of existing solar capacity. The Kanto region around Tokyo concentrates microgrid deployments serving institutional resilience requirements.
South Korea
Smart grid investments by Korea Electric Power Corporation create concentrated procurement pull in the Incheon and Yongin manufacturing corridors. Semiconductor foundries now require sub-15ms power quality response at 3nm nodes, driving solid-state transfer switch deployments. Government-backed green hydrogen initiatives extend demand to electrolyzer power conditioning systems.
India
The Central Electricity Authority mandates renewable purchase obligations that distribution companies cannot meet without distributed management systems for solar-wind hybrid parks. Gujarat and Rajasthan host the largest procurement volumes for grid-tied inverters and battery energy storage integration. Port authorities in Mumbai and Chennai now require shore power connections for vessel electrification.
Global Power Management System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-computing convergence and solid-state power electronics. The vendor base stratifies across three maturity levels: diversified industrial conglomerates with century-long grid automation heritage, mid-scale specialists in semiconductor power devices, and software-native entrants from cloud infrastructure backgrounds. Competitive positioning depends on certification velocity for evolving grid-interconnection standards and the ability to compress multi-vendor integration timelines.
Within the diversified industrial tier, General Electric, ABB, and Siemens represent distinct geographic anchors for regional procurement frameworks. General Electric exemplifies North American utility relationships built through transmission infrastructure legacy. ABB occupies a position at the intersection of high-voltage direct current and digital twin architectures. Siemens anchors European market access through deep integration with German industrial automation ecosystems.
| Leading Market Players |
|---|
| General Electric |
| Emerson Electric Co. |
| ABB |
| Rockwell Automation |
| Honeywell International Inc. |
| Schneider Electric |
| Eaton |
| ETAP |
| Siemens |
| Others |
Supply & Pricing Matrix
EU Green Deal efficiency mandates gate qualified supply for grid-interactive equipment, restricting premium-tier pricing access to vendors with certified architectures while forcing uncertified competitors toward commodity segments with compressed margins.
Pricing Analysis
Distributor margins for power management hardware compress as hyperscale data center buyers negotiate direct-to-OEM frameworks with ABB, Siemens, and Schneider Electric. Pricing stratifies across UL 1741-SA certified premium tiers, standard utility-grade equipment, and economy retrofit controllers lacking grid-forming capabilities. Cost compression in the economy tier intensifies because static VAR compensators substitute for full digital platforms in budget-constrained industrial segments. Data center operators show least price sensitivity due to 50kW+ rack density requirements, while commercial building operators exhibit highest sensitivity to peak demand charge reduction payback periods.
Supply Chain Analysis
Single-source vulnerability sits with high-purity silicon carbide wafer supply concentrated in Japan, Germany, and the United States. Power electronics manufacturing draws from SiC substrates, lithium-ion battery cells, and rare earth magnetic materials for converter assemblies. Tariff exposure on Chinese rare earth processing creates margin volatility for inverter producers. Distribution runs through authorized industrial distributors serving utility procurement departments and direct enterprise sales teams for hyperscale data center accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage favors Southeast Asian converter production for European demand, exploiting the cost differential between EU Green Deal certification overhead and regional manufacturing bases outside the regulatory perimeter.
For Market Incumbents: Lock in grid-forming inverter certification velocity ahead of Japan's METI fiscal year 2025 mandate to capture replacement demand from existing solar capacity. Anchor European utility contracts through backward integration into grid automation software stacks that resist disintermediation by open-source IoT frameworks. Defend against software-native entrants from cloud infrastructure backgrounds by deepening embedded firmware expertise in IEC 61850 substation automation protocols. For New Entrants and Emerging Players: Begin with India's renewable purchase obligation compliance gap, where distribution companies lack distributed management systems for solar-wind hybrid parks. Target maritime electrification in Rotterdam and Singapore port authorities requiring vessel-to-grid synchronization controllers. Pursue edge-computing convergence with protective relaying as the go-to-market angle, offering microsecond fault detection that defers transmission upgrade capital for grid operators. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale semiconductor power device specialists because multi-vendor integration complexity extends commissioning timelines and creates acquisition premiums for pre-integrated hardware-software platforms. Five-to-ten year viability hinges on certification velocity for evolving grid-interconnection standards. Target firms with UL 1741-SA test sequence completion and existing relationships with Korea Electric Power Corporation or India's Central Electricity Authority. Watch FERC Order 2222 implementation pace across independent system operators as the inflection indicator for distributed energy resource management platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | Japan's METI mandate compels algorithm redesigns for synthetic inertia provision across 12GW of existing solar. |
| Solid-State Power Electronics Scale-Up | SiC-based UPS deployments in Ashburn and Frankfurt compress payback periods through 3% efficiency gains. |
| Digital Twin Architecture Integration | Predictive maintenance capabilities reduce unplanned outages for European utilities under EU Green Deal continuity requirements. |
| Edge Computing Relay Convergence | Sub-15ms power quality response captures East Asian semiconductor foundry procurement at 3nm nodes. |
| Maritime Electrification Partnership | Port authority shore power mandates in Rotterdam and Singapore create vessel-to-grid controller demand. |
Research Methodology
Multiple input streams — utility planning officer interviews, EPC contractor project databases, and FERC regulatory filings — were reconciled against secondary validation from EIA capacity data and IEA grid integration reports. Primary fieldwork engaged grid operators, IPP project developers, and hyperscale data center infrastructure directors across the United States, Germany, Japan, South Korea, and India. Secondary sources included SEC 10-K equipment vendor disclosures, customs records for power electronics trade flows, and national smart grid investment announcements. Bottom-up project pipelines and top-down regulatory mandate trajectories were triangulated to constrain estimate variance.
Historical deployment trajectories were cross-referenced against panel input from procurement executives at ABB, Siemens, Schneider Electric, and emerging solid-state power semiconductor specialists. Segmentation dimensions spanned product type, technology architecture, application context, and end-user vertical with regional regulatory framework overlays. CAGRs were derived from regression against renewable capacity addition forecasts and data center power density escalation curves. Key model inputs included silicon carbide substrate supply constraints, FERC Order 2222 aggregation compliance timelines, and EU Green Deal efficiency mandate implementation schedules.
Several conditions sit outside the modeled scope, including unforeseen cybersecurity incidents disrupting grid-interconnection certification timelines and abrupt trade policy shifts affecting rare earth magnet supply chains. Forecasts reflect documented assumptions regarding technology cost reduction curves and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
North America Energy Storage Market
Battery Management System
Battery Management Market
Battery Management System
North America Battery Management System Market