
 Renewable Battery Storage Market | 2026-2036
Renewable Battery Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Battery Storage Market Insights
Battery electrochemist talent scarcity is bifurcating the competitive landscape between firms with captive R&D pipelines and those dependent on contract engineering. Tesla leverages its integrated cell-to-pack architecture to compress manufacturing cycles. LG Energy Solution anchors its position through multi-gigafactory expansion across three continents. Fluence Energy differentiates via software-defined energy management platforms that optimize dispatch economics for utility clients.
Renewable battery storage encompasses electrochemical systems engineered for charge acceptance rates exceeding 1C, cycle lives surpassing 6,000 cycles at 80% depth of discharge, and round-trip efficiencies above 85% to buffer intermittency from wind and solar generation. Lithium-ion chemistry dominates installed capacity owing to energy density advantages and declining cell costs, while flow batteries occupy long-duration niches where daily cycling exceeds eight hours. Grid Storage applications lead revenue generation as transmission operators procure capacity to defer substation upgrades, and Distributed deployment models are gaining traction among commercial users seeking demand charge management.
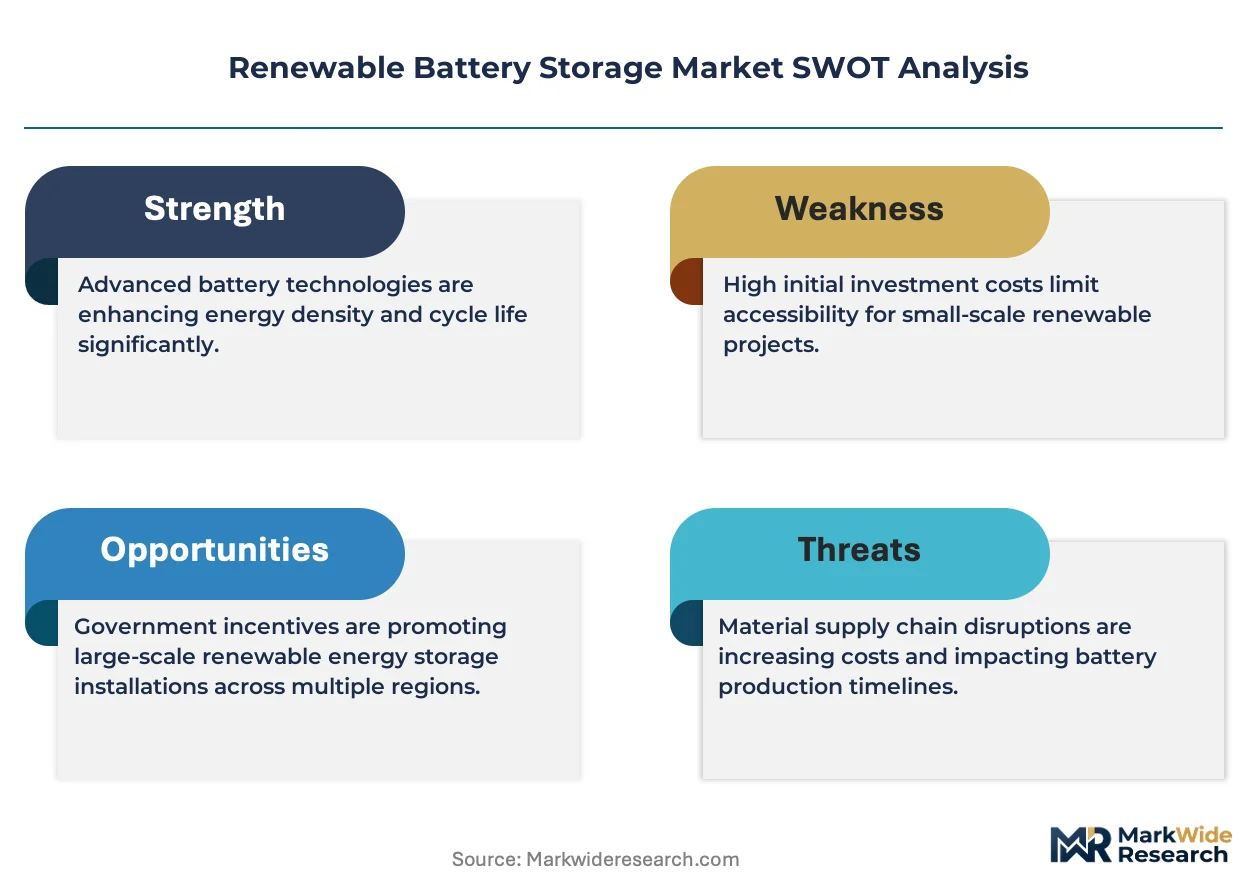
The US IRA, EU Green Deal taxonomy, and China's dual carbon goals are each reshaping capital allocation toward localized supply chains and carbon-accountable procurement. EPA emissions standards and FERC Order 2222 are accelerating utility adoption by clarifying market participation rules for storage aggregators. Stakeholders must monitor evolving domestic content requirements that threaten to disqualify cells sourced from jurisdictions without qualifying trade agreements.
Market Dynamics
Utility-scale developers are compressing procurement timelines as interconnection queue delays extend beyond five years in high-penetration zones, forcing early-stage storage commitments to secure grid positions.
Growth Catalysts
- US IRA Production Tax Credits:Domestic cell manufacturing investments are accelerating as qualifying facilities capture credits tied to wage and apprenticeship standards.
- Grid Flexibility Threshold Breaches:Texas ERCOT and California CAISO markets are mandating storage co-location for new solar projects exceeding transmission capacity.
- Lithium-Iron-Phosphate Chemistry:Cell architectures with enhanced thermal stability are opening safety-critical installations previously closed to cobalt-containing systems.
Market Restraints
- Lithium Carbonate Volatility:Chilean and Australian spodumene concentrate supply swings are compressing cell producer margins unpredictably.
- Chinese Cathode Concentration:Over 70% of processed lithium iron phosphate cathode active material originates from a single jurisdiction, creating single-point vulnerability.
- Flow Battery Cost Structure:Vanadium redox systems face capital intensity barriers below 4-hour discharge durations where lithium-ion dominates.
Strategic Opportunities
- India PLI Scheme:Accrued manufacturing incentives for advanced chemistry cells are attracting module assembly investments ahead of domestic demand maturation.
- Behind-the-Meter Commercial Aggregation:Virtual power plant software platforms are unlocking demand charge arbitrage for C&I users without direct utility interconnection.
- Green Hydrogen Convergence:Co-located electrolyzer-battery hybrids are capturing clipped renewable generation for long-duration molecule production.
Industry Challenges
- Battery Electrochemist Scarcity:Cell formulation expertise concentrated in Asian manufacturing hubs is constraining Western pilot line scale-up timelines.
- Domestic Content Certification:FERC and Treasury guidance on IRA qualifying thresholds remains unresolved, freezing procurement decisions for 2025-2026 delivery windows.
- Legacy SCADA Integration:Utility control rooms require custom protocol bridges to dispatch battery assets alongside rotating machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Battery Storage Market |
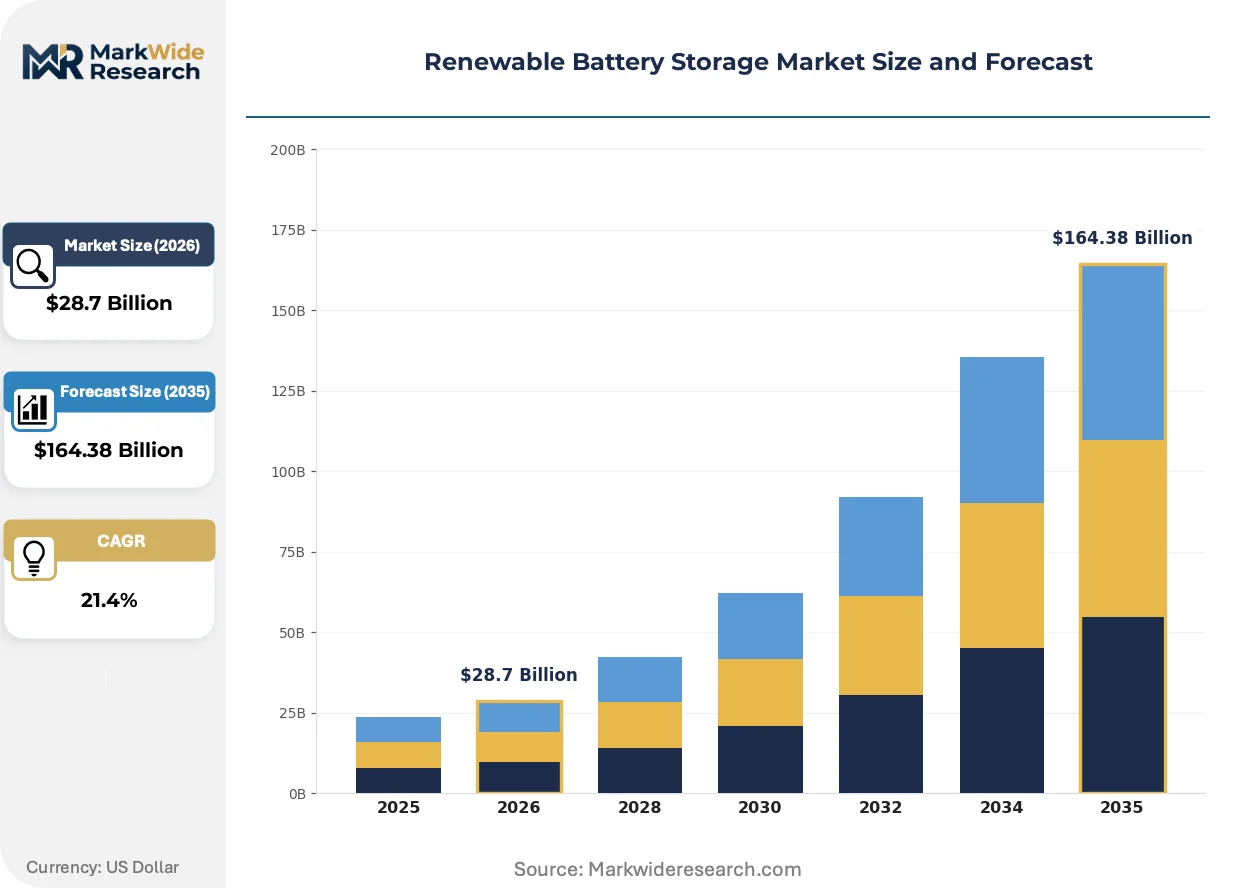
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $164.38 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-Ion, Lead-Acid, Flow Batteries, Nickel-Cadmium Application: Grid Storage, Renewable Energy Integration, UPS, Frequency Regulation End User: Utilities, Residential, Commercial, Industrial Deployment: Onsite, Offsite, Hybrid, Distributed |
| Companies Covered | Tesla, LG Energy Solution, Samsung SDI, BYD Company Ltd., Panasonic Holdings Corporation, Fluence Energy, Enphase Energy, NextEra Energy Resources, Powin Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Battery Storage Market Trends and Innovations
Solid-state electrolyte architectures and silicon-anode formulations are advancing through pilot validation, while software-defined dispatch platforms are decoupling hardware margins from revenue optimization.
Lithium-metal anodes paired with sulfide electrolytes are displacing conventional graphite cells in aerospace and defense applications where gravimetric density penalties are unacceptable. Defense contractors in the US and Germany are qualifying solid-state packs for unmanned platforms. The technology is displacing incumbent liquid electrolyte systems in premium segments before cost parity reaches automotive volumes.
EU Battery Regulation mandatory carbon footprint declarations are forcing supply chain reconfiguration toward European cell finishing capacity. The delegated acts require disclosed upstream mining emissions from 2027. Original equipment manufacturers are responding by diversifying cathode precursor sourcing beyond incumbent Asian suppliers.
Long-term service agreements with guaranteed performance degradation curves are replacing upfront equipment sales in utility procurement. Independent power producers in Texas and Australia are signing 15-year availability contracts with liquidated damages clauses. The model transfers operational risk to integrators while locking in dispatch rights for offtakers.
Renewable Battery Storage Market Segmentation
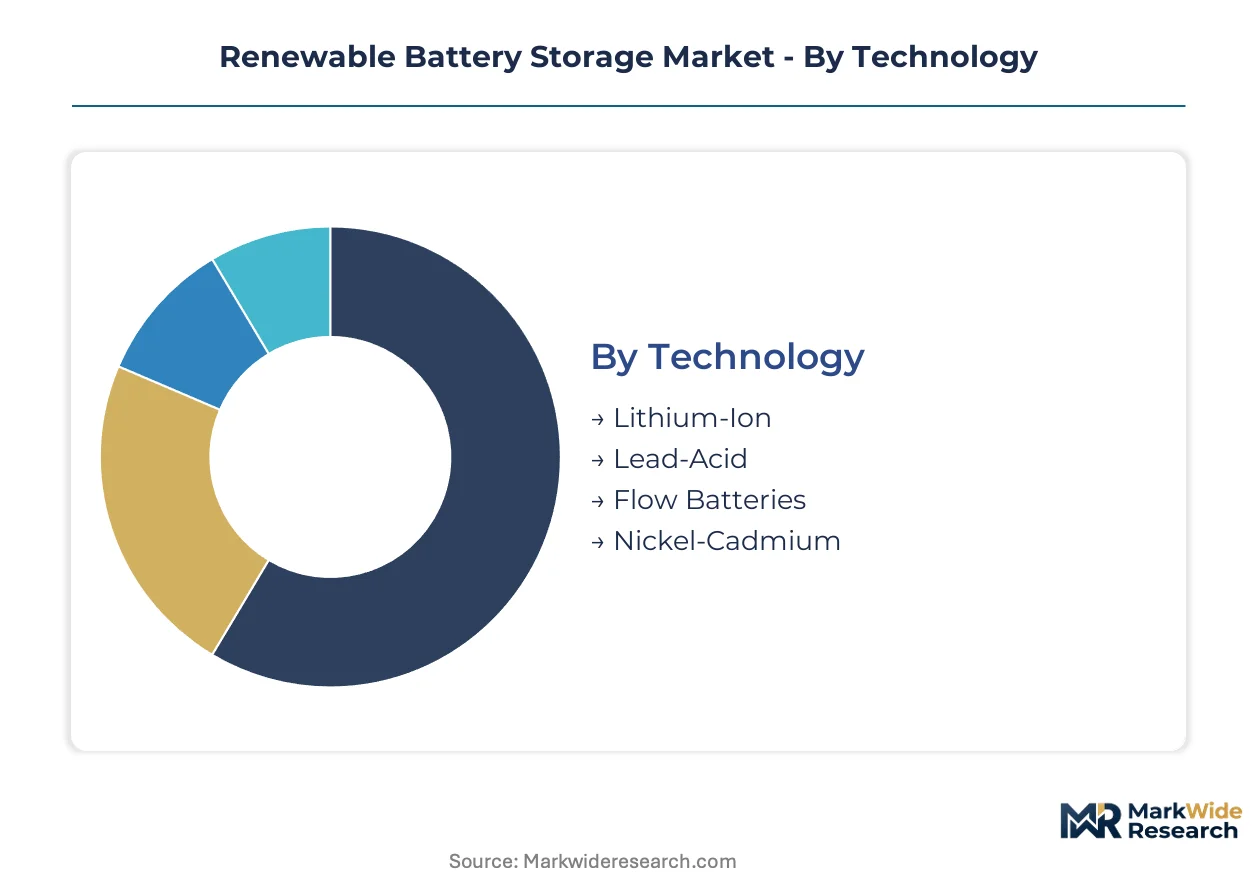
Segmentation in renewable battery storage reveals how technology choices, application requirements, and deployment economics fragment procurement patterns across customer tiers. Each dimension carries distinct margin structures and capital intensity profiles that shape vendor strategy.
Technology:
Margin pools concentrate in cell architectures where energy density and cycle life command pricing premiums against commodity alternatives.
- Lithium-Ion:Lithium iron phosphate and nickel-manganese-cobalt chemistries deliver energy densities above 250 Wh/kg with 6,000-plus cycle lifespans. Utility-scale developers in Texas and California are standardizing on lithium iron phosphate for solar-plus-storage projects facing ERCOT and CAISO interconnection mandates.
- Flow Batteries:Vanadium redox and zinc-bromine systems decouple power and energy scaling through external electrolyte tanks, enabling 8-hour-plus discharge durations. Germany's transmission operators are procuring vanadium systems for daily cycling applications where lithium-ion degradation economics fail.
- Lead-Acid:Mature flooded and valve-regulated designs serve price-sensitive backup power segments with established recycling infrastructure.
- Nickel-Cadmium:Sintered plate architectures retain niche positions in extreme temperature environments where alkaline chemistry outperforms lithium thermal management.
Lithium-ion holds installed capacity. Flow batteries are rotating up the share rankings in long-duration procurement.
Application:
Revenue concentration follows grid operator procurement timelines, with transmission deferral and renewable firming commanding the largest contract values.
- Grid Storage:Bulk capacity installations co-located at substations defer transformer upgrades and absorb off-peak renewable generation. FERC Order 2222 is accelerating aggregator participation in wholesale markets across multiple US ISO territories.
- Renewable Energy Integration:Battery assets paired with solar and wind farms clip output smoothing and shift generation to peak price periods. India's solar parks are mandating storage co-location for new capacity allocations under CEA guidelines.
- UPS:Uninterruptible power supply systems protect critical loads in data centers and healthcare facilities with sub-second transfer capabilities.
- Frequency Regulation:Fast-responding assets provide primary frequency response to grid operators, with automated dispatch signals from AGC systems.
Grid Storage dominates contract value. Renewable Energy Integration is expanding most quickly as solar penetration thresholds trigger co-location mandates.
End User:
Procurement scale and technical sophistication bifurcate sharply between centralized utility buyers and fragmented behind-the-meter segments.
- Utilities:Transmission and distribution operators procure multi-hundred-megawatt systems through competitive solicitations with 15-year service agreements. Australian NEM participants are signing availability contracts with liquidated damages clauses transferring operational risk to integrators.
- Industrial:Manufacturing facilities and mining operations deploy megawatt-scale systems for demand charge management and power quality assurance. German industrial clusters are qualifying battery assets for participation in secondary reserve markets.
- Commercial:Office buildings and retail chains utilize sub-megawatt installations for peak shaving and backup power.
- Residential:Homeowners pair rooftop solar with 10-20 kWh battery systems for self-consumption optimization and outage protection.
Utilities anchor procurement volume. Industrial is climbing the fastest as C&I aggregators unlock virtual power plant revenue streams.
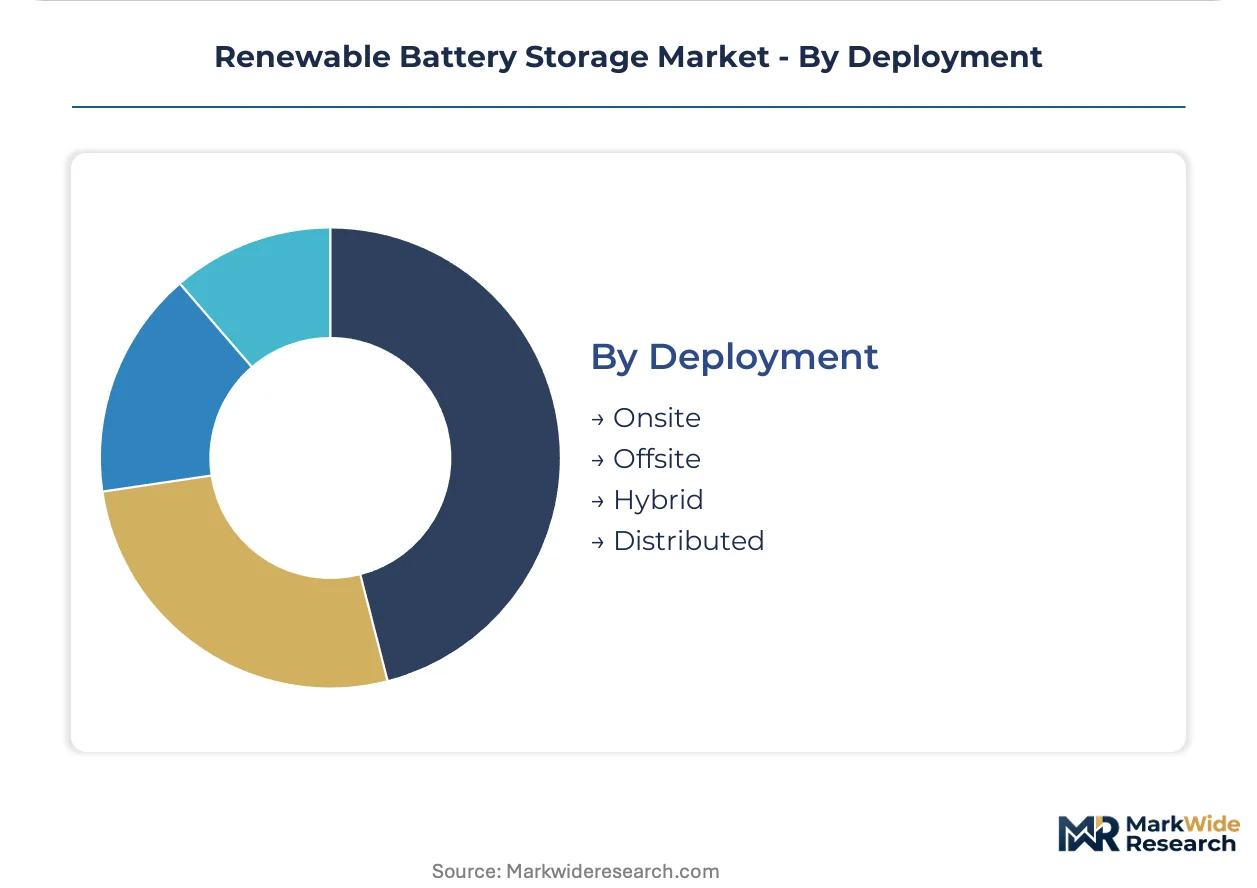
Deployment:
Capital deployment models vary from balance-sheet ownership to third-party leasing structures that reshape customer risk exposure.
- Onsite:Behind-the-meter installations at generation or load facilities provide dedicated capacity without transmission utilization. Texas industrial facilities are deploying onsite systems to isolate from ERCOT price volatility.
- Offsite:Utility-scale assets located at remote substations deliver capacity through wheeling arrangements to multiple offtakers.
- Hybrid:Co-located renewable-plus-storage configurations share interconnection infrastructure and optimize joint dispatch economics.
- Distributed:Aggregated portfolios of small-scale assets operate as unified resources through software orchestration platforms.
Onsite leads deployment count. Distributed is gaining share fastest as virtual power plant software matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premium multiples against commoditized procurement in India, where domestic content mandates compress integrator margins. This asymmetry reflects divergent regulatory stringency and grid flexibility thresholds across jurisdictions.
United States
Texas ERCOT and California CAISO markets are mandating storage co-location for solar projects exceeding interconnection capacity. The IRA production tax credits are redirecting capital toward domestic cell manufacturing facilities. Industrial clusters in Arizona and Nevada are attracting gigafactory investments to capture wage-linked incentive bonuses.
Germany
Transmission operators are procuring vanadium flow systems for daily cycling applications where lithium-ion degradation economics fail. The EU Battery Regulation mandatory carbon footprint declarations are forcing supply chain reconfiguration toward European cell finishing capacity. Industrial demand concentrates in Baden-Württemberg and Bavaria, where automotive OEMs are qualifying battery assets for grid services participation.
China
Dual carbon goals are accelerating utility-scale deployment to absorb renewable curtailment in western provinces. The MIIT is tightening cell quality standards to consolidate manufacturing capacity among top-tier producers. Yangtze River Delta and Pearl River Delta clusters dominate cathode active material processing, creating single-point vulnerability for global supply chains.
India
Solar parks under CEA guidelines are mandating storage co-location for new capacity allocations. The PLI scheme for advanced chemistry cells is attracting module assembly investments ahead of domestic demand maturation. Manufacturing activity clusters in Gujarat and Tamil Nadu, where state governments are offering land and power subsidies to anchor cell production.
Australia
NEM participants are signing 15-year availability contracts with liquidated damages clauses transferring operational risk to integrators. The country's national energy regulator is clarifying market participation rules for storage aggregators. Queensland and New South Wales are seeing concentrated utility procurement to defer transmission upgrades in high-renewable zones.
Renewable Battery Storage Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around integrated cell manufacturers, pure-play system integrators, and software-defined energy management platforms. Strategic moves center on captive R&D pipeline development and multi-gigafactory geographic diversification.
Among integrated cell-to-pack specialists, Tesla and LG Energy Solution exemplify divergent scale strategies. Fluence Energy anchors the software-defined platform tier, occupying a position where dispatch optimization capabilities decouple hardware margins from revenue generation. These three represent the dominant archetypes: captive manufacturing integration, continental production footprint expansion, and algorithmic energy management specialization.
| Leading Market Players |
|---|
| Tesla |
| LG Energy Solution |
| Samsung SDI |
| BYD Company Ltd. |
| Panasonic Holdings Corporation |
| Fluence Energy |
| Enphase Energy |
| NextEra Energy Resources |
| Powin Energy Corporation |
| Others |
Pricing and Supply Chain Analysis
EU Battery Regulation carbon footprint declarations gate both supply qualification and price differentiation simultaneously, forcing cell producers to invest in European finishing capacity or forfeit premium procurement tiers. This certification regime stratifies the market between disclosed low-carbon supply chains commanding availability premiums and undifferentiated imports facing margin compression.
Pricing Analysis
Germany commands premium multiples against commoditized procurement in India, where domestic content mandates compress integrator margins. Three-tier pricing structure across premium, standard, and economy levels separates long-term service agreements with guaranteed degradation curves from transactional equipment sales. Cost compression in standard-tier lithium-ion systems is intensifying because Chinese cathode concentration enables aggressive module pricing. Utilities exhibit the lowest price sensitivity due to risk-transfer preferences, while commercial behind-the-meter buyers prioritize capital efficiency over performance guarantees.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and spodumene concentrate is displacing just-in-time procurement as price volatility erodes margin predictability for cell producers. Supply concentrates in China, South Korea, and Australia across cathode active material processing, cell manufacturing, and upstream mining respectively. The chain rests on lithium carbonate, electrolyte salts, and separator membranes as critical inputs. Single-source vulnerability in Chinese cathode processing creates systemic exposure to export licensing shifts. Distribution runs through integrator-led EPC contracts for utility-scale deployment and channel partners for behind-the-meter segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Renewable battery storage exhibits fragmentation opportunity as interconnection queue delays bifurcate procurement between early-stage storage commitments and traditional generation assets. Virtual power plant software platforms are creating service-layer niches that hardware-centric incumbents under-serve.
For Market Incumbents: Shield margin pools in utility-scale procurement by accelerating captive cell-to-pack integration before IRA domestic content thresholds crystallize. Consolidate position in Texas and California markets through multi-gigafactory geographic diversification that satisfies FERC and Treasury guidance on qualifying thresholds. Secure battery electrochemist talent pipelines through university partnerships and Asian hub recruitment to constrain Western pilot line scale-up timelines for emerging competitors. For New Entrants and Emerging Players: Behind-the-meter commercial aggregation represents the most penetrable white-space where incumbent hardware vendors lack software-defined dispatch capabilities. Target C&I users in ERCOT and CAISO territories seeking demand charge arbitrage without direct utility interconnection. Deploy virtual power plant platforms as the primary go-to-market angle, decoupling hardware margins from revenue optimization through algorithmic energy management specialization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across distributed deployment models as software orchestration reduces per-asset capital requirements. Frame long-term viability around five-to-ten year windows where grid flexibility threshold breaches sustain procurement momentum. Prioritize acquisition targets with captive R&D pipelines and multi-continent production footprints. Watch FERC Order 2222 implementation progress as the signal indicating when storage aggregator market participation rules unlock scaled revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Gigafactory Geographic Expansion | Captures IRA wage-linked incentive bonuses across Arizona, Nevada, and Texas industrial clusters. |
| Software-Defined Energy Management Platform Development | Decouples hardware margins from dispatch optimization revenue for utility and C&I clients. |
| Long-Term Service Agreement Transition | Transfers operational risk to integrators through 15-year availability contracts with liquidated damages clauses. |
| Solid-State Electrolyte Pilot Validation | Displaces liquid electrolyte systems in aerospace and defense applications before automotive cost parity. |
| Cathode Precursor Supply Diversification | Mitigates EU Battery Regulation carbon disclosure exposure through European cell finishing capacity investment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, grid operators, and battery electrochemists at manufacturing facilities. Secondary validation drew from EIA capacity data, IEA technology roadmaps, FERC interconnection filings, and project development databases tracking ERCOT and CAISO queue positions. Bottom-up unit economics modeling triangulated against top-down regulatory impact assessments to anchor volume and value estimates.
Across the analysis window, forecasts incorporate technology substitution dynamics between lithium-ion and flow battery chemistries, interconnection queue delay assumptions, and IRA domestic content threshold evolution. Segmentation dimensions span chemistry architecture, discharge duration tier, deployment scale, and end-user procurement sophistication. CAGRs were derived from installed capacity buildout trajectories and revenue-per-megawatt-hour compression curves. Key inputs include lithium carbonate price volatility bands and grid flexibility threshold breach timelines in high-renewable penetration zones.
Forecasts assume regulatory continuity in US IRA implementation, EU Battery Regulation delegated acts, and India's PLI scheme accrual schedules; material policy shifts would require re-modeling capital allocation assumptions and supply chain qualification pathways. Revision becomes warranted when FERC Order 2222 aggregator participation rules or Treasury domestic content guidance crosses implementation thresholds that freeze or unlock procurement decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Automotive Energy Storage System Market
Battery Management System
Global Power Management System Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
EV Battery Management Market
Battery Management System
Battery Management System (BMS) Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
North America Battery Management System Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
Energy Storage Market
Battery Management System
North America Energy Storage Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
AC Coupled Solar Battery System Market