
 Electric Two-Wheeler Lithium-Ion Battery Management System Market | 2026-2036
Electric Two-Wheeler Lithium-Ion Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Two-Wheeler Lithium-Ion Battery Management System Market Analysis
Modular battery pack architectures with swappable configurations is hardening as the dominant product format across urban mobility fleets. Sensata Technologies leverages its automotive-grade sensing portfolio to anchor high-voltage safety systems for premium two-wheeler platforms. Infineon Technologies AG sustains its position through silicon-carbide power semiconductor integration that extends thermal performance margins in tropical climates. NXP Semiconductors N.V. dominates the ASIL-D functional safety segment with battery management controllers purpose-built for compact vehicle form factors.
An electric two-wheeler lithium-ion battery management system is an electronic subsystem that monitors cell voltage, temperature, and state-of-charge across 48V to 144V architectures using precision analog front-ends and isolated communication buses; its commercial purpose is to prevent thermal runaway, balance cell degradation, and maximize cycle life for lithium nickel manganese cobalt oxide and lithium iron phosphate cell chemistries. Battery Management Unit hardware captures the deepest margin pools as OEMs in-source firmware development while outsourcing hardware fabrication to specialized electronics manufacturers. Active Balancing technology leads in premium segments where fleet operators prioritize range consistency, while Passive Balancing occupies cost-sensitive personal transport applications where component simplicity governs supplier selection.
India's CEA mandates AIS-156 certification for lithium-ion traction batteries used in electric two-wheelers, forcing BMS suppliers to embed thermal propagation containment logic at the cell supervision circuit level. China's GB/T standards and SAMR technical regulations require domestic BMS firmware to interface with national battery passport traceability systems, creating compliance barriers for non-local providers. Europe's EU Green Deal transport decarbonization targets and Battery Regulation due diligence rules are redirecting procurement specifications toward recycled-content transparency and supply chain auditability. Stakeholders must decide whether to build in-house BMS firmware competence or accept margin compression from platform-standardized controller architectures.
Market Dynamics
Modular swappable battery architectures are forcing BMS suppliers to redesign thermal management logic for rapid-connect/disconnect cycles while maintaining ASIL-D safety integrity across Vietnam's urban fleet operators and Indonesia's domestic assembly plants.
Growth Catalysts
- India's PLI scheme for advanced chemistry cell manufacturing:Local cell production mandates are compelling OEMs to source BMS hardware from domestic electronics fabricators, creating captive demand for battery management controllers.
- Last-mile delivery fleet electrification:Southeast Asian logistics operators are procuring integrated battery management units at volume scale to standardize range performance across tropical operating conditions.
- Silicon-carbide power semiconductor integration:Wide-bandgap devices are extending thermal performance margins, enabling higher switching frequencies that reduce passive component count in compact two-wheeler form factors.
Market Restraints
- ASIC development cost concentration:Custom analog front-end design for 48V to 144V architectures requires multi-million dollar mask sets that concentrate supplier leverage with Taiwanese foundries.
- Cell supervision circuit sourcing fragility:Precision voltage reference ICs for lithium nickel manganese cobalt oxide monitoring depend on a narrow base of Japanese and German semiconductor specialists.
- Passive balancing efficiency ceiling:Resistive dissipation methods waste recoverable energy in high-cycle fleet applications, creating a technical barrier to total cost of ownership parity with active alternatives.
Strategic Opportunities
- Vietnam's domestic electric motorcycle assembly scale-up:VinFast and local OEMs are localizing pack integration, opening white space for BMS firmware customization services.
- EU Battery Regulation due diligence rules:Recycled-content transparency mandates are redirecting procurement specifications toward suppliers with auditable supply chains and embedded carbon accounting.
- Cloud-connected predictive maintenance convergence:Edge analytics on battery management controllers combined with telematics platforms is enabling subscription-based health monitoring for fleet operators.
Industry Challenges
- Functional safety engineering talent scarcity:ASIL-D certification expertise for automotive-grade BMS firmware remains concentrated with a limited pool of specialists in Germany and Japan.
- AIS-156 thermal propagation containment timeline:India's CEA mandate requires cell-level supervision circuit redesigns that compress certification cycles for new pack architectures.
- GB/T battery passport interface complexity:China's SAMR traceability requirements force firmware architecture changes that fragment development roadmaps for non-local BMS providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Two-Wheeler Lithium-Ion Battery Management System Market |
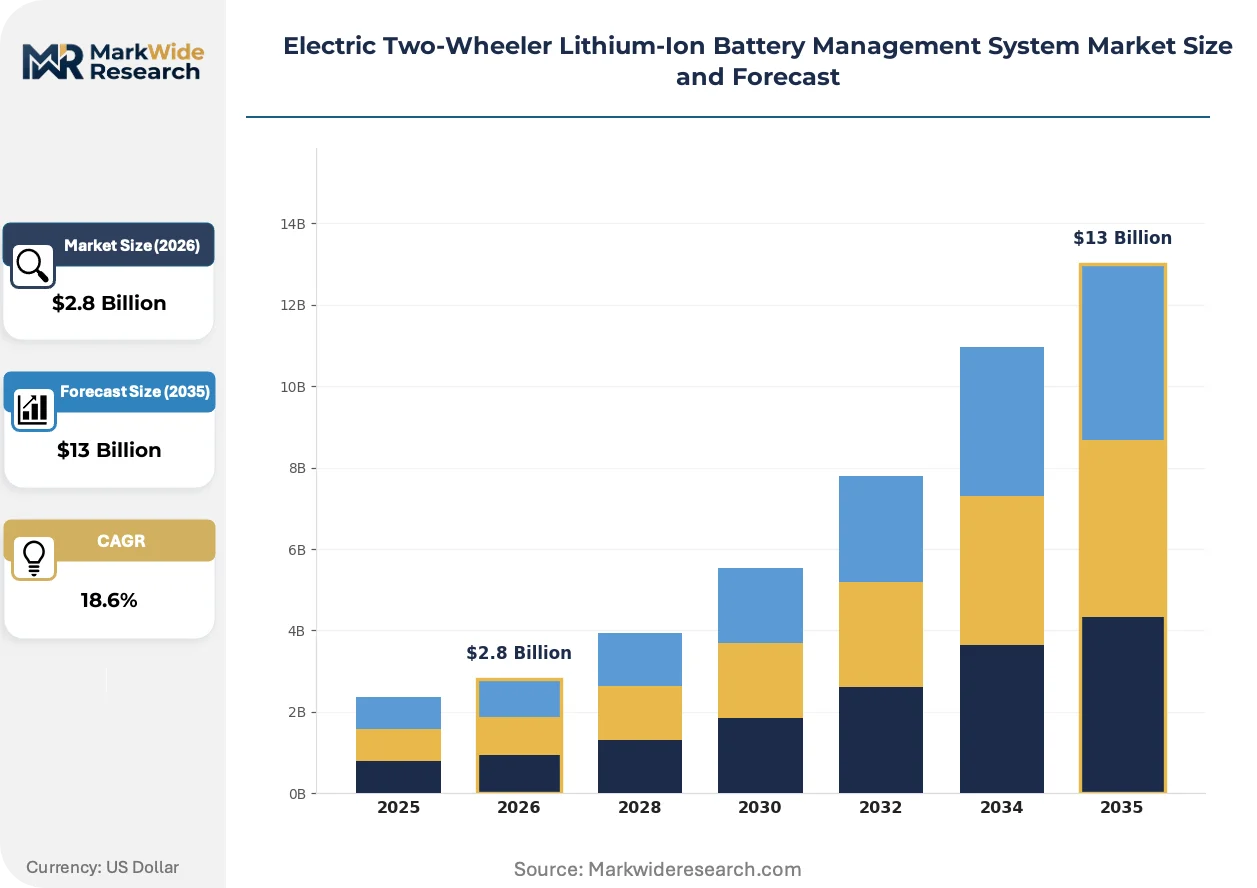
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Charger, Battery Module, Battery Management Unit, Battery Pack End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Technology: Active Balancing, Passive Balancing, Centralized Control, Distributed Control Application: Urban Mobility, Delivery Services, Personal Transport, Leisure Riding |
| Companies Covered | Sensata Technologies, Inc., Infineon Technologies AG, NXP Semiconductors N.V., Shenzhen Litongwei Electronics Technology Co., Ltd., Microchip Technology Inc., Renesas Electronics Corporation, Leclanché SA, Navitas System LLC, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Two-Wheeler Lithium-Ion Battery Management System Market Emerging Trajectories
Silicon-carbide power electronics and cloud-native firmware architectures are converging to redefine thermal management precision and predictive maintenance capabilities across electric two-wheeler platforms.
Wireless battery management systems are electrifying pack architecture design by eliminating high-voltage wiring harnesses between cell supervision circuits and central controllers. Southeast Asian fleet operators are piloting these topologies to accelerate swap-station throughput. The technology is electrifying supplier competition around electromagnetic immunity certification and protocol standardization.
India's CEA has mandated AIS-156 thermal propagation containment testing for all lithium-ion traction batteries used in electric two-wheelers, forcing BMS suppliers to embed multi-layer fault detection at the cell supervision level. This compresses firmware development timelines and raises validation costs for entrants. Domestic OEMs are responding by insourcing safety-critical algorithm development while outsourcing hardware fabrication.
Fleet operators are consolidating procurement around integrated battery management units with standardized CAN bus interfaces, displacing discrete component sourcing from multiple vendors. This concentration is most visible in Indonesia's domestic assembly plants, where platform standardization reduces integration engineering overhead. Third-party telematics providers are capturing aftermarket value by unbundling predictive analytics from hardware supply.
Electric Two-Wheeler Lithium-Ion Battery Management System Market Segmentation
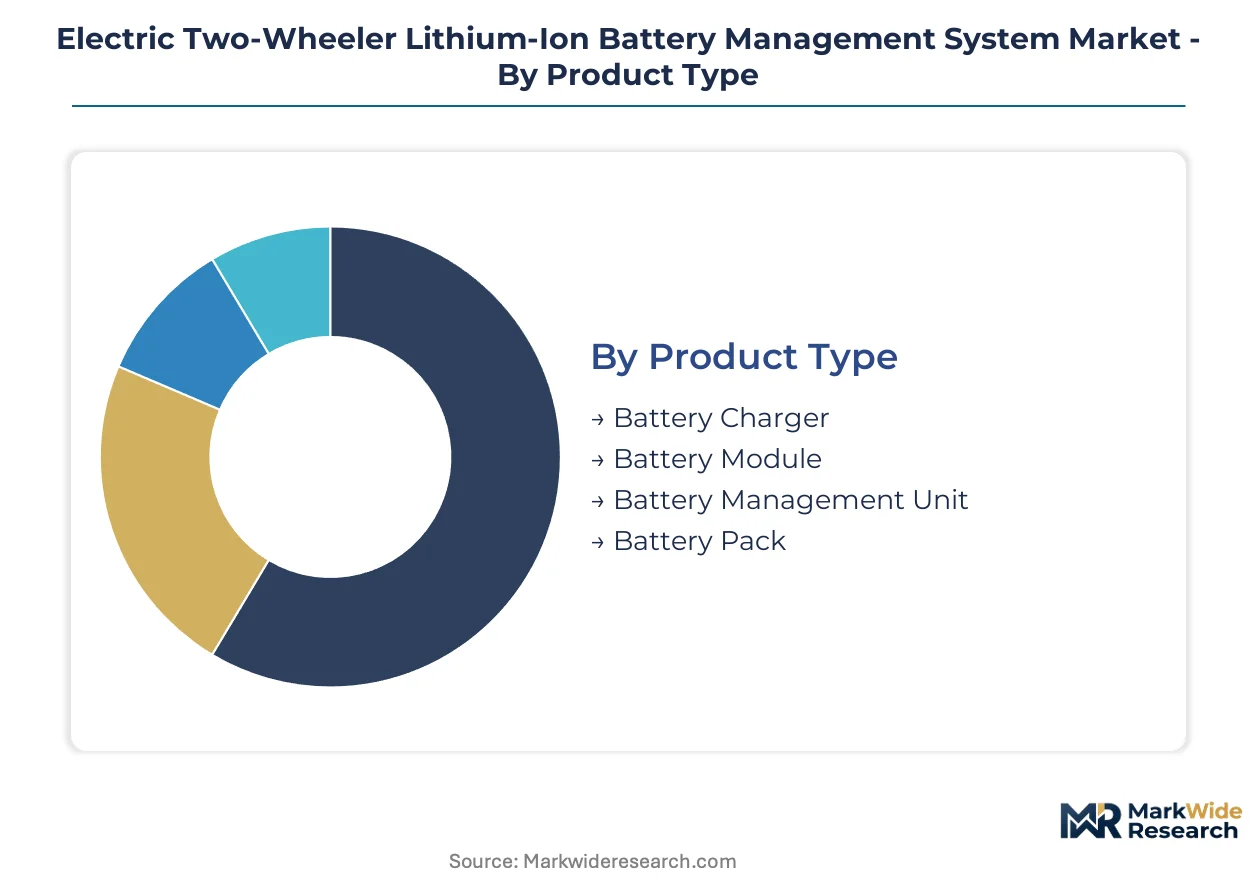
Segmentation in the Electric Two-Wheeler Lithium-Ion Battery Management System Market reflects divergent engineering priorities across fleet standardization and consumer customization. Procurement patterns split sharply between integrated platforms for high-volume operators and modular architectures for personal mobility.
Product Type:
The customization-vs-standardization spectrum runs from discrete components that OEMs configure in-house to fully integrated systems that lock in supplier relationships across product lifecycles.
- Battery Management Unit:Purpose-built controllers with ASIL-D functional safety certification dominate premium two-wheeler platforms. Fleet operators in Vietnam and Indonesia are consolidating procurement around standardized CAN bus interfaces to reduce integration overhead across multi-thousand unit deployments.
- Battery Pack:Modular swappable configurations with rapid-connect thermal management are hardening as the dominant format for last-mile delivery electrification. India's PLI scheme for advanced chemistry cell manufacturing is reshaping local sourcing requirements for pack integrators serving domestic OEMs.
- Battery Module:Cell supervision circuits with embedded voltage reference ICs serve mid-tier personal transport applications where cost sensitivity limits active balancing adoption.
- Battery Charger:Onboard and offboard units with isolated communication buses support 48V to 144V architectures across Southeast Asian urban mobility fleets.
Most installed capacity flows through Battery Pack configurations. Expansion is steepest in Battery Management Unit hardware as OEMs in-source firmware development while outsourcing controller fabrication.
End User:
Volume concentration tilts toward entities with captive maintenance infrastructure and standardized replacement cycles, while margin pools concentrate where technical specification authority rests with the purchaser.
- Fleet Operators:Last-mile delivery providers across Southeast Asia procure integrated battery management units at volume scale to standardize range performance under tropical thermal stress. Subscription-based predictive maintenance contracts are emerging as a recurring revenue anchor for BMS suppliers serving this segment.
- OEMs:Domestic electric motorcycle assemblers in Vietnam and Indonesia localize pack integration, creating white space for firmware customization services and hardware fabrication partnerships.
- Aftermarket Providers:Third-party telematics platforms capture value by unbundling predictive analytics from hardware supply, targeting owner-operated fleets with limited in-house engineering.
- Individual Consumers:Cost-sensitive personal transport buyers drive demand for passive balancing architectures and simplified cell supervision circuits.
Procurement volume concentrates with Fleet Operators. Margin expansion is most rapid among OEMs verticalizing into firmware competence.
Technology:
Engineering trade-offs between energy recovery efficiency and component simplicity split the market across high-cycle commercial applications and price-driven consumer segments.
- Active Balancing:Inductive or capacitive charge redistribution circuits maximize recoverable energy in high-cycle fleet applications. Operators in Vietnam's urban delivery networks prioritize range consistency over upfront hardware cost, sustaining technology leadership for this topology.
- Distributed Control:Wireless battery management architectures eliminate high-voltage wiring harnesses between cell supervision circuits and central controllers. Southeast Asian swap-station operators pilot these topologies to accelerate throughput and reduce connector wear.
- Passive Balancing:Resistive dissipation methods dominate cost-sensitive personal transport where component simplicity governs supplier selection despite energy waste.
- Centralized Control:Single-controller architectures with isolated communication buses serve compact two-wheeler form factors where space constraints limit module proliferation.
Technology deployment favors Passive Balancing by unit volume. Active Balancing gains share fastest as fleet electrification accelerates across tropical climates.
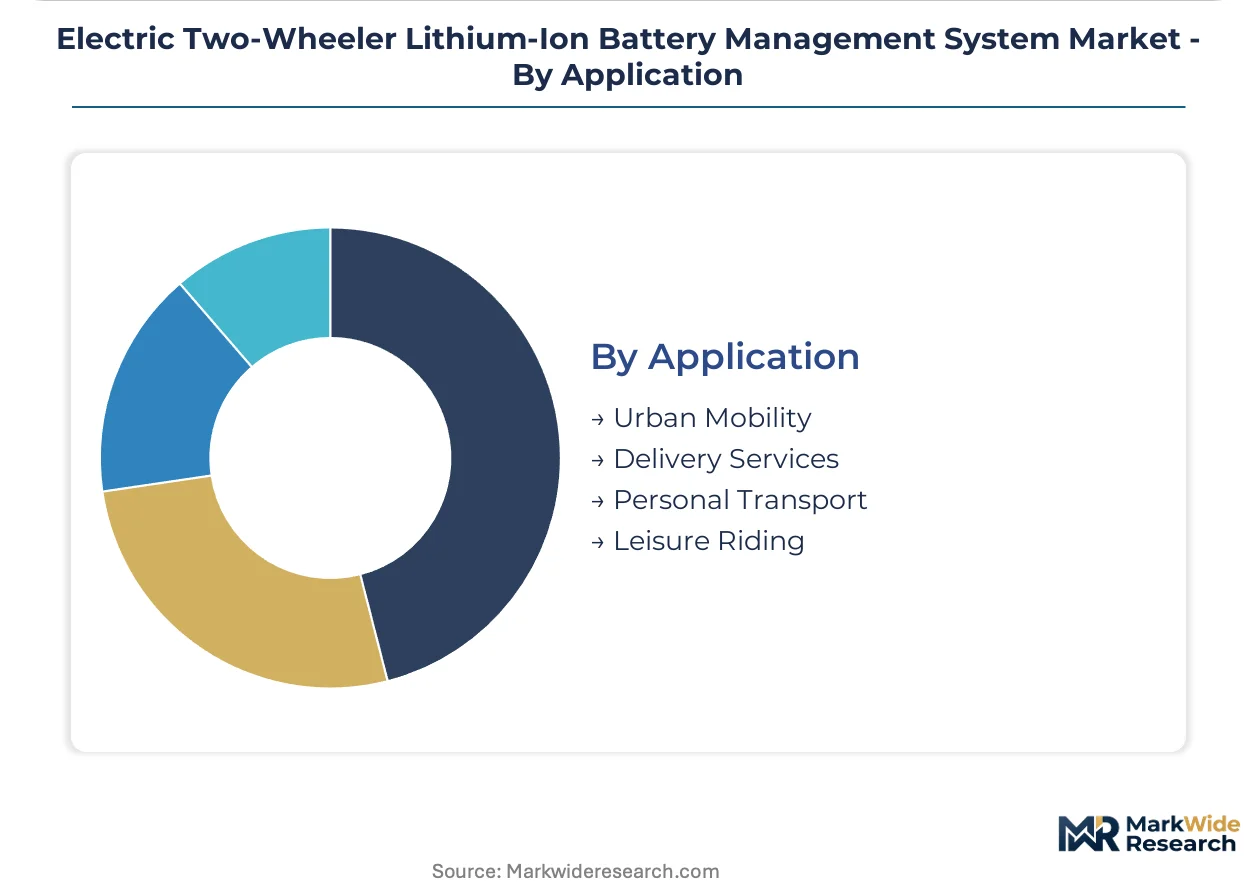
Application:
Use-case differentiation centers on duty cycle intensity, thermal exposure patterns, and the economic value of range predictability versus acquisition cost minimization.
- Delivery Services:Continuous high-discharge operation with rapid swap requirements drives demand for modular architectures and predictive state-of-charge algorithms. Indonesia's domestic assembly plants standardize around integrated battery management units to reduce field failure rates.
- Urban Mobility:Stop-start traffic patterns with partial state-of-charge cycling favor cell chemistries and balancing strategies that mitigate lithium plating. India's CEA mandates AIS-156 thermal propagation containment for this high-visibility application segment.
- Personal Transport:Intermittent usage with full-cycle charging supports simpler passive balancing and lower switching frequency designs.
- Leisure Riding:Premium positioning enables silicon-carbide power semiconductor integration and extended thermal performance margins for recreational two-wheeler platforms.
Unit shipments concentrate in Urban Mobility. Revenue expansion is steepest in Delivery Services as commercial fleet scale accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric two-wheeler battery management systems trace their industrial origins to automotive electronics clusters in Germany and Japan, where precision analog semiconductor manufacturing first scaled for vehicle electrification applications.
China
GB/T standards and SAMR technical regulations mandate domestic BMS firmware interface with national battery passport traceability systems, erecting compliance barriers for non-local providers. The Yangtze River Delta concentration hosts pack integrators serving domestic electric motorcycle OEMs with localized controller architectures.
India
CEA mandates AIS-156 thermal propagation containment testing for lithium-ion traction batteries, forcing cell supervision circuit redesigns at the firmware level. Tamil Nadu and Karnataka assembly plants are absorbing PLI scheme incentives for advanced chemistry cell manufacturing, redirecting BMS hardware sourcing toward domestic electronics fabricators.
Vietnam
VinFast and local OEMs are scaling domestic electric motorcycle assembly, opening white space for BMS firmware customization services. Ho Chi Minh City's urban delivery fleets are piloting wireless battery management architectures to accelerate swap-station throughput.
Indonesia
Domestic assembly plants are standardizing procurement around integrated battery management units with CAN bus interfaces to reduce field failure rates. Jakarta's last-mile logistics operators are consolidating volume orders for tropical-rated thermal management systems.
Germany
EU Green Deal transport decarbonization targets and Battery Regulation due diligence rules are redirecting procurement specifications toward recycled-content transparency. Bavarian automotive-grade electronics specialists are exporting ASIL-D functional safety expertise to Southeast Asian OEMs.
Electric Two-Wheeler Lithium-Ion Battery Management System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with ASIL-D qualified controllers commanding pricing separation from basic monitoring circuits. The vendor base stratifies between automotive-grade semiconductor houses, specialized BMS firmware developers, and contract electronics manufacturers serving cost-optimized personal transport segments. Three archetypes dominate: integrated platform providers with full-stack safety competence, modular hardware fabricators dependent on customer firmware, and swap-station infrastructure specialists with telemetry integration capabilities. Competitive moves center on silicon-carbide power semiconductor integration and captive supply of cell supervision circuits through foundry partnerships.
Among European semiconductor houses, Infineon Technologies AG and NXP Semiconductors N.V. occupy positions anchoring the premium-tier functional safety segment. Shenzhen Litongwei Electronics Technology Co., Ltd. represents the contract fabrication archetype serving domestic Chinese OEMs with hardware platforms. These three exemplify the geographic and capability bifurcation structuring supplier competition across tropical climate deployments and temperate-zone regulatory environments.
| Leading Market Players |
|---|
| Sensata Technologies, Inc. |
| Infineon Technologies AG |
| NXP Semiconductors N.V. |
| Shenzhen Litongwei Electronics Technology Co., Ltd. |
| Microchip Technology Inc. |
| Renesas Electronics Corporation |
| Leclanché SA |
| Navitas System LLC |
| Texas Instruments Incorporated |
| Others |
Supply Flow & Price Mechanics
Fleet operator procurement consolidation across Vietnam and Indonesia anchors a three-tier pricing structure across premium, standard, and economy levels. ASIL-D certified battery management controllers command substantial premiums over basic monitoring circuits as OEMs absorb firmware development costs while outsourcing hardware fabrication.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified controllers from industrial-grade alternatives and cost-optimized personal transport units. Price differentiation hinges on functional safety certification tier and volume procurement scale. Cost compression in the economy tier is intensifying because domestic OEMs in India and Vietnam are qualifying second-source hardware fabricators. Fleet operators exhibit the lowest price sensitivity due to total cost of ownership calculations favoring active balancing and predictive maintenance subscriptions, while individual consumers in personal transport segments drive aggressive component cost minimization.
Supply Chain Analysis
Dual-sourcing mandates from Tier 1 automotive suppliers and Southeast Asian OEMs are forcing qualification of backup foundries for precision analog front-end fabrication. Manufacturing concentrates in Taiwan, China, and South Korea for silicon-carbide power semiconductors and cell supervision circuits. The supply chain draws from Japanese and German specialists for precision voltage reference ICs and automotive-grade microcontrollers. Single-source vulnerability around 48V to 144V analog front-end mask sets creates qualification bottlenecks. Distribution runs through specialized electronics distributors serving domestic assembly plants in Vietnam, Indonesia, and India with localized technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on silicon-carbide power semiconductor cost curves and the shift toward subscription-based predictive maintenance bundling. OEMs capturing firmware competence in-house extract premium positioning while hardware fabricators face commoditization pressure.
For Market Incumbents: To counter firmware insourcing by domestic OEMs in Vietnam and India, ASIL-D certified suppliers should deepen captive supply of cell supervision circuits through foundry partnerships in Taiwan and accelerate cloud-native predictive maintenance platform development. Certification investment in India's AIS-156 thermal propagation containment protocols preserves access to PLI scheme incentivized procurement channels. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass entrenched distributor relationships and capture volume orders from Indonesian last-mile logistics operators standardizing around CAN bus interfaces. White space concentrates in BMS firmware customization services for Vietnam's domestic electric motorcycle assemblers lacking in-house functional safety engineering. Subscription-based health monitoring platforms for tropical climate fleet deployments offer the most penetrable entry vector. For Investors and Strategic Acquirers: Semiconductor houses with automotive-grade analog portfolios are the most active acquirer in this space, targeting specialized BMS firmware developers with ASIL-D certification track records. Long-term viability favors platform providers combining hardware fabrication with telemetry integration capabilities. The signal to watch is wireless battery management system pilot scale-up across Southeast Asian swap-station networks, indicating protocol standardization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Power Semiconductor Integration | Extends thermal performance margins for tropical climate operations in Vietnam and Indonesia. |
| Cloud-Connected Predictive Maintenance Platform | Enables subscription revenue capture from fleet operators in India's last-mile delivery networks. |
| AIS-156 Thermal Propagation Containment Certification | Unlocks PLI scheme procurement channels for domestic OEMs in Tamil Nadu and Karnataka. |
| Wireless Battery Management Architecture Deployment | Accelerates swap-station throughput for Ho Chi Minh City's urban delivery fleets. |
| Foundry Partnership for Cell Supervision Circuits | Secures captive supply of precision voltage reference ICs from Japanese semiconductor specialists. |
Methodological Framework
Coverage spans India, Vietnam, Indonesia, China, and Germany, with primary inputs from each market cluster combining structured interviews with BMS hardware engineering directors, fleet operator procurement leads, OEM platform integration managers, and semiconductor foundry account executives alongside secondary validation. Primary fieldwork drew from regulatory filings with India's CEA, China's SAMR technical regulations, and EU Battery Regulation due diligence guidance, supplemented by customs data on lithium-ion cell imports and Tier 1 supplier SEC disclosures. Bottom-up unit shipment modeling triangulated against top-down market value reconstructions.
Granularity-level modeling disaggregated the analysis window by product type, end user archetype, balancing technology, and application intensity, with additional segmentation by regional regulatory cluster and thermal climate zone. CAGRs were derived from logistic diffusion curves fitted to fleet electrification adoption patterns and OEM localization timelines. Forecast inputs incorporated silicon-carbide device penetration trajectories, PLI scheme disbursement schedules, and swap-station infrastructure deployment pipelines without year-specific assumptions.
The model assumes a particular technology adoption path; alternative pathways for wireless battery management system standardization would alter the outlook. Forecasts reflect assumptions around AIS-156 certification timeline adherence, GB/T battery passport interface compliance costs, and tropical climate thermal degradation curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
US Energy Storage Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Global Power Management System Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
North America Energy Storage Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Battery Management Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
India Stationary Battery Energy Storage System Market