
 Energy Storage Market | 2026-2036
Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Storage Market Analysis
Utility-scale buyers are reorganizing procurement priorities around four-hour duration systems, displacing traditional peaker plants in frequency regulation and peak-shaving roles. CATL leverages its integrated cell-to-pack architecture to dominate lithium iron phosphate supply for grid installations. Tesla sustains brand pull in the residential and commercial segments through software-defined energy management. Fluence Energy competes on project development velocity, controlling utility-scale deployment pipelines across deregulated power markets.
Energy storage encompasses electrochemical and electrostatic systems engineered to capture electrical energy for deferred discharge, with lithium-ion cells achieving round-trip efficiencies above 90% and cycle lives exceeding 6,000 charge events at 80% depth of discharge. The technology stabilizes intermittent renewable generation, defers transmission upgrades, and arbitrages time-of-use electricity pricing. Lithium-ion chemistry leads installed capacity globally while flow batteries occupy long-duration niches above eight hours where degradation economics favor aqueous electrolytes. The application dimension stratifies sharply: utility-scale deployments concentrate capital and policy support, residential segments fragment across installer networks, and commercial-industrial buyers optimize demand charge reduction.
The EU Green Deal and IRA tax credit frameworks in the United States shape demand by subsidizing standalone storage and co-located renewable-plus-battery projects, while China's MIIT governs cell manufacturing standards and recycling quotas through GB specifications. EMA and national regulators in Europe enforce battery passport traceability under forthcoming CSRD-linked disclosure rules. Stakeholders must monitor how duration requirements in procurement tenders evolve beyond four-hour norms and whether flow battery cost curves compress fast enough to challenge lithium-ion incumbency in seasonal shifting applications.
Market Dynamics
Duration requirements in utility tenders are compressing lithium-ion cost curves while forcing flow battery developers to accelerate aqueous electrolyte scale-up for seasonal shifting applications.
Growth Catalysts
- EU Green Deal integration mandates:Grid-scale utilities across Germany, Spain, and Italy face binding renewable-plus-storage procurement quotas that standalone battery projects satisfy.
- Four-hour frequency regulation:Peaker plant displacement in deregulated power markets creates dedicated procurement streams for lithium iron phosphate systems.
- China's manufacturing clusters:Cell-to-pack architecture standardization in Fujian and Guangdong provinces drives export cost competitiveness for global utility buyers.
Market Restraints
- Lithium carbonate volatility:Chilean and Australian spodumene concentrate markets transmit price shocks directly into cell bill-of-materials, compressing developer margins.
- Cathode supply concentration:NCM precursor processing clusters in Jiangsu province create single-geography dependency risks for European integrators.
- Eight-hour degradation economics:Lithium-ion calendar fade in daily cycling regimes favors flow batteries for long-duration niches above seasonal shifting thresholds.
Strategic Opportunities
- India's CEA storage obligations:State-level renewable purchase mandates in Rajasthan, Gujarat, and Karnataka mandate co-located battery capacity without domestic cell supply.
- Electrolyte convergence:Vanadium flow battery developers are partnering with mining tailings processors to secure captive vanadium pentoxide feedstock.
- Installer network fragmentation:Residential segment consolidation through certified technician platforms in California and Texas reduces customer acquisition costs.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell thermal management and BMS firmware development functions face recruitment gaps in European and North American labor markets.
- GB/T and UL9540A harmonization delays:Divergent fire safety testing protocols between China's MIIT and US OSHA create certification timeline extensions for dual-market products.
- Legacy SCADA integration friction:Utility-scale deployments require custom protocol bridges to connect battery management systems with existing grid operator control rooms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Storage Market |
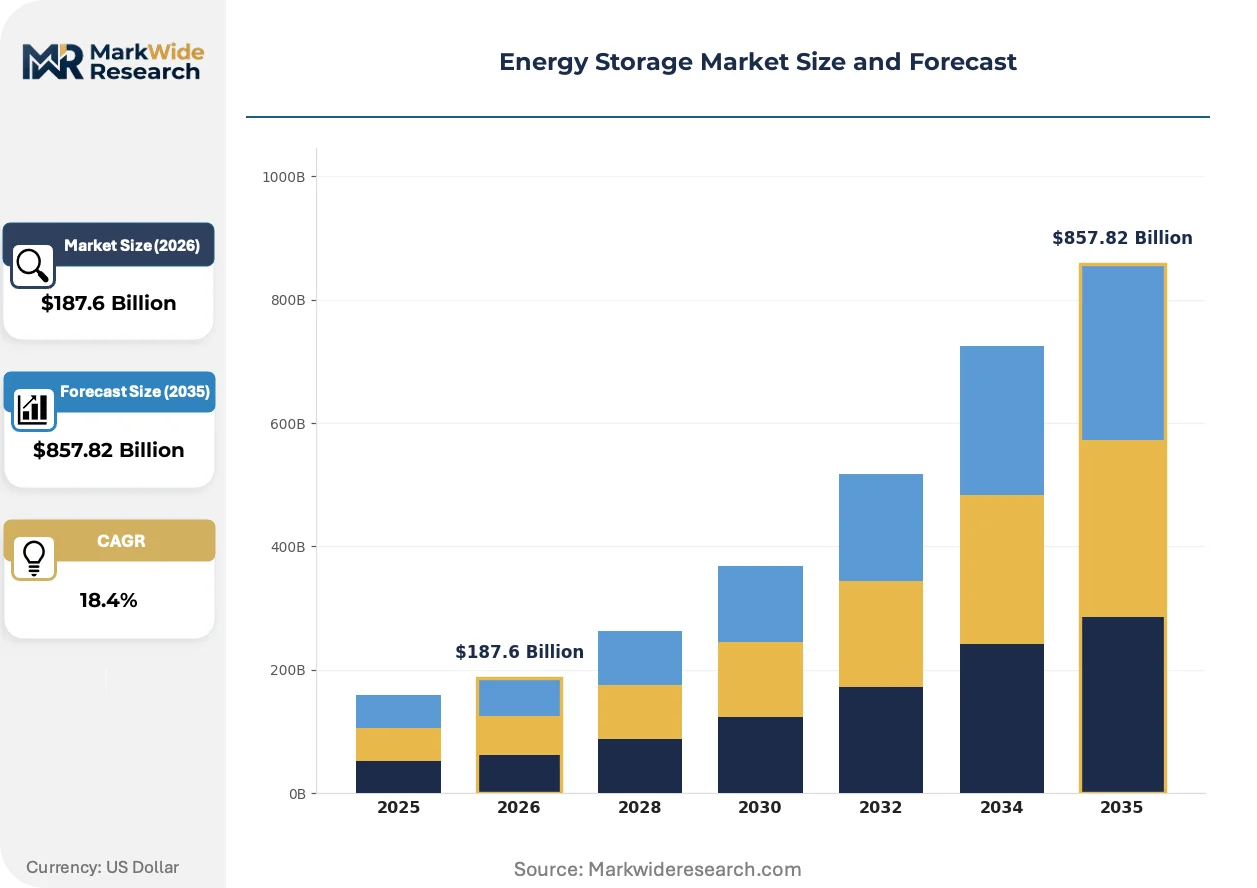
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $857.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Lead-acid, Flow Batteries, Supercapacitors Application: Utility Scale, Residential, Commercial, Industrial Installation Type: Onshore, Offshore, Stationary, Mobile End User: Utilities, Renewable Energy Producers, Manufacturers, Emergency Services |
| Companies Covered | Contemporary Amperex Technology Co. Ltd. (CATL), Tesla, LG Energy Solution, BYD, Samsung SDI, Fluence Energy, Panasonic Holdings Corporation, General Electric, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Storage Market Emerging Trajectories
Cell chemistry architectures are fragmenting as lithium iron phosphate gains ground in grid applications while sodium-ion prototypes target cost-sensitive residential segments.
Solid-state electrolyte research is decomposing the traditional liquid electrolyte paradigm in premium grid-scale prototypes. Samsung SDI and Toyota are piloting sulfide-based ceramic separators for 1,000-cycle life extensions at 90% depth of discharge. This materials transition is decomposing incumbent separator and electrolyte additive supply relationships.
The EU AI Act and linked CSRD battery passport rules are mandating supply chain traceability for carbon intensity disclosure. EMA enforcement timelines require full lifecycle documentation by 2027. Grid-scale developers in Germany and the Netherlands are pre-emptively restructuring procurement contracts to capture upstream mining and smelting data.
Utility buyers are consolidating vendor relationships around turnkey engineering-procurement-construction contracts. Traditional equipment-only sales are losing share to performance-guaranteed service agreements with availability penalties. This contracting evolution is most visible in ERCOT and CAISO interconnection queues where independent power producers dominate procurement.
Energy Storage Market Segmentation
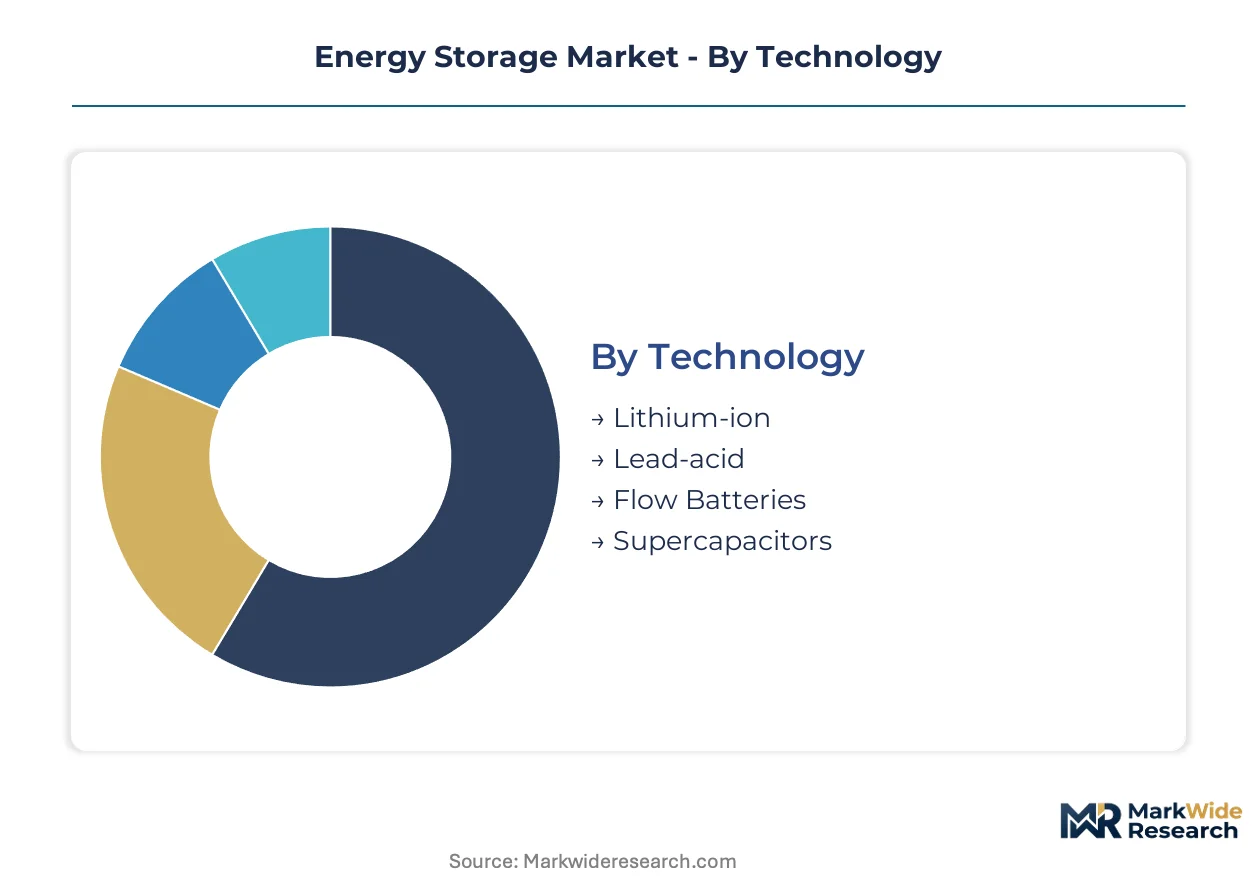
Technology and application boundaries in energy storage determine procurement channel access, with lithium-ion systems flowing through integrator networks while flow batteries deploy via direct utility contracting. Installation type and end-user segmentation dictate fire safety certification requirements and interconnection queue positioning.
Technology:
Channel distribution varies sharply by electrochemical maturity, with established chemistries penetrating through distributor-installer networks and emerging technologies requiring direct manufacturer-to-utility engagement.
- Lithium-ion:Lithium iron phosphate and nickel-manganese-cobalt cells dominate procurement volumes through certified integrator channels in ERCOT and CAISO markets. German and Spanish utilities under EU Green Deal mandates are consolidating procurement around four-hour duration lithium iron phosphate systems for peaker displacement.
- Flow Batteries:Vanadium redox systems deploy through direct engineering-procurement-construction contracts with transmission operators seeking eight-hour seasonal shifting capacity. Australian and Japanese utilities are piloting zinc-bromine alternatives for remote microgrid applications where calendar fade economics favor aqueous electrolytes.
- Lead-acid:Mature supply chains serve backup power niches through electrical distributor networks.
- Supercapacitors:Electrostatic systems access industrial markets via automation component distributors.
Lithium-ion dominates installed base. Flow batteries are where expansion concentrates for duration requirements exceeding daily cycling thresholds.
Application:
Margin structures stratify across application tiers, with utility-scale deployments commanding performance-guaranteed service agreements while residential segments fragment across installer certification levels.
- Utility Scale:Grid-connected battery farms above 100 MW integrate through independent power producer development pipelines in Texas and California. India's CEA storage obligations in Rajasthan and Gujarat are mandating co-located capacity without domestic cell supply, creating import-dependent procurement channels.
- Commercial:Behind-the-meter installations for demand charge optimization flow through regional electrical contractors with NABCEP certification. Peak-shaving economics in California's PG&E and SCE territories drive 200 kWh to 2 MWh system deployments through energy service company financing structures.
- Residential:Solar-plus-storage bundles penetrate through rooftop installer networks with loan and lease product attachments.
- Industrial:Manufacturing facility microgrids source through EPC firms with power quality engineering capabilities.
Utility-scale applications concentrate capital deployment. Commercial segments are climbing the fastest as tariff structures incentivize distributed storage.
Installation Type:
Physical configuration determines supply chain complexity, with stationary systems leveraging standardized container logistics and mobile deployments requiring transportation-certified packaging.
- Stationary:Containerized battery systems ship through intermodal freight networks to substation-adjacent sites. China's manufacturing clusters in Fujian and Guangdong provinces export pre-integrated skid-mounted units to European and North American utility buyers under MIIT GB/T certification protocols.
- Onshore:Land-based deployments access established civil construction contractor networks for foundation and interconnection work.
- Offshore:Marine-certified enclosures require specialized integration with subsea cable infrastructure.
- Mobile:Trailer-mounted systems serve emergency response and construction power through rental equipment channels.
Stationary installations anchor manufacturing scale. Mobile configurations are gaining share fastest in disaster recovery and remote power applications.
End User:
Customer sophistication determines contracting structure, with regulated utilities favoring availability-based service agreements and industrial buyers optimizing around internal rate of return thresholds.
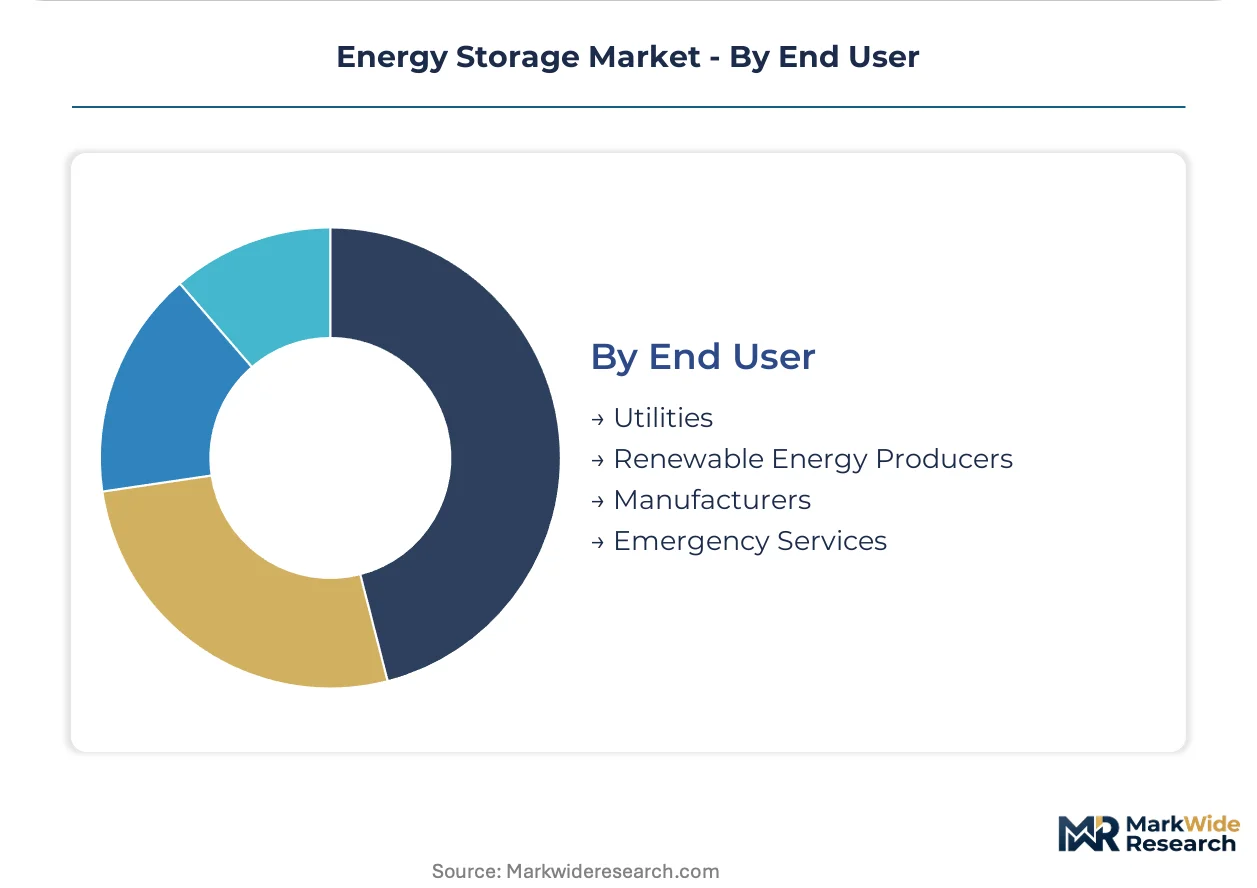
- Utilities:Transmission and distribution operators in Germany, Italy, and Spain procure through competitive tenders with renewable-plus-storage co-location requirements under EU Green Deal frameworks. FERC Order 841 implementation in US markets enables standalone storage participation in wholesale energy and ancillary services markets.
- Renewable Energy Producers:Wind and solar developers integrate storage to satisfy integration mandates and capture IRA tax credit adders. Co-located projects in Texas and California interconnection queues are restructuring power purchase agreements to include battery dispatch guarantees.
- Manufacturers:Industrial facility operators source behind-the-meter systems for power quality and resilience.
- Emergency Services:Critical infrastructure operators procure mobile and stationary backup through government contracting vehicles.
Utilities dominate procurement volume. Renewable energy producers are expanding most quickly as integration mandates tighten across European and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing clusters in Fujian and Guangdong provinces export pre-integrated systems to utility buyers across multiple continents. Procurement patterns diverge sharply between markets with renewable integration mandates and those optimizing around wholesale arbitrage economics.
United States
ERCOT and CAISO interconnection queues concentrate utility-scale deployments as independent power producers capture IRA standalone storage credits. FERC Order 841 enables battery participation in wholesale energy and ancillary services markets. Texas and California host the dominant project development pipelines for four-hour lithium iron phosphate systems.
China
CATL and BYD anchor manufacturing clusters serving domestic utilities and export markets under MIIT GB/T certification protocols. The country's dual carbon goals accelerate grid-scale procurement quotas in provincial power markets. Fujian and Guangdong provinces standardize cell-to-pack architectures for cost-competitive exports.
Germany
Transmission operators under EU Green Deal frameworks tender renewable-plus-storage projects with binding co-location requirements. EMA enforcement timelines for battery passport traceability reshape procurement contract structures. Industrial demand clusters in North Rhine-Westphalia and Bavaria drive behind-the-meter commercial installations.
India
CEA storage obligations in Rajasthan, Gujarat, and Karnataka mandate co-located battery capacity without domestic cell supply. State-level renewable purchase obligations create import-dependent procurement channels for Chinese and Korean integrators. The absence of local cathode processing concentrates supply risk in Jiangsu-sourced precursor materials.
Australia
Remote mining operations and grid stability requirements drive vanadium flow battery pilots for eight-hour seasonal shifting applications. The country's lithium spodumene extraction in Western Australia feeds concentrate exports to Chinese refiners. Queensland and New South Wales utility tenders increasingly specify duration requirements exceeding daily cycling thresholds.
Energy Storage Market Vendor Landscape
Concentration sits with integrated cell manufacturers and turnkey project developers. The vendor base stratifies between chemistry specialists controlling upstream materials and system integrators competing on deployment velocity. Three archetypes dominate: vertically integrated Asian cell producers, Western software-defined energy managers, and independent power producer-affiliated developers. Competitive moves center on captive raw material offtake agreements and performance-guaranteed service contracting.
Within the integrated manufacturing tier, Contemporary Amperex Technology Co. Ltd. (CATL) and BYD occupy positions exemplifying cell-to-pack standardization for utility procurement. Tesla represents the software-defined archetype through energy management platforms. Fluence Energy sits within the independent developer tier competing on project pipeline velocity in deregulated power markets.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| Tesla |
| LG Energy Solution |
| BYD |
| Samsung SDI |
| Fluence Energy |
| Panasonic Holdings Corporation |
| General Electric |
| ABB |
| Others |
Supply Flow & Price Mechanics
Gigawatt-scale manufacturing utilization in Fujian and Guangdong provinces compresses unit economics for lithium iron phosphate cells while anchoring price floors through cathode precursor concentration. This scale concentration simultaneously empowers CATL and BYD with procurement leverage over spodumene concentrate offtake and locks utility-scale buyers into long-duration contract structures that buffer quarterly lithium carbonate volatility.
Pricing Analysis
Volume-discount tiering separates gigawatt-hour utility procurement from megawatt-scale commercial installations and kilowatt-hour residential bundles. Pricing stratifies across premium, standard, and economy tiers based on cell certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because Jiangsu-sourced NCM precursor availability constrains margin expansion. Utility-scale independent power producers exhibit lowest price sensitivity due to IRA tax credit absorption, while residential solar-plus-storage buyers face acute sensitivity to financing rate fluctuations.
Supply Chain Analysis
Inventory cycles stretching six to nine months for containerized battery systems reflect ocean freight scheduling and customs clearance variability at destination ports. Cell manufacturing concentrates in China, South Korea, and Japan, with raw material processing drawing from Australian spodumene and Chilean lithium brine. Single-source vulnerability sits with Jiangsu province cathode precursor clusters. Distribution runs through certified integrator networks in ERCOT and CAISO markets for utility-scale deployments, while direct manufacturer-to-utility contracting dominates flow battery seasonal shifting applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FERC Order 841 and EU Green Deal integration mandates erect switching costs that cement incumbent positions across interconnection queues and tender pipelines.
For Market Incumbents: Consolidate captive cathode precursor supply through backward integration into Australian spodumene offtake or Jiangsu processing joint ventures. Expand cell-to-pack manufacturing capacity in Fujian province to capture India's CEA storage obligation procurement. Sodium-ion substitution technology threatens lithium iron phosphate cost positioning in residential segments.
For New Entrants and Emerging Players: Anchor in India's Rajasthan and Gujarat state markets where CEA mandates create import-dependent procurement channels without domestic cell supply. Target vanadium flow battery seasonal shifting applications above eight-hour duration thresholds where lithium-ion degradation economics falter. Pursue direct engineering-procurement-construction contracting with Australian transmission operators seeking remote microgrid resilience.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent power producer-affiliated developers with performance-guaranteed service agreements. Long-term viability across the projection horizon favors turnkey project developers with captive raw material offtake and software-defined energy management platforms. Monitor duration requirement evolution in utility tenders beyond four-hour norms as the critical inflection signal for chemistry mix shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | CATL and BYD expansion in Fujian secures export cost competitiveness for EU utility tenders. |
| Backward Integration | Vanadium flow battery developers partnering with mining tailings processors lock pentoxide feedstock. |
| Power Purchase Agreement | ERCOT and CAISO independent power producers restructure PPAs to include battery dispatch guarantees. |
| Technology Licensing | Samsung SDI sulfide-based ceramic separator pilots extend cycle life for premium grid prototypes. |
| Green Certification Program | EMA battery passport traceability rules reshape German and Dutch procurement contract structures. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, independent power producer project developers, EPC contractors, and grid operators and refined through secondary validation. Primary fieldwork encompassed structured interviews across ERCOT and CAISO interconnection queue participants, European transmission operators under EU Green Deal frameworks, and Chinese cell manufacturing executives. Secondary sources integrated EIA deployment databases, IEA technology roadmaps, FERC Order 841 implementation filings, and project development pipeline trackers. Bottom-up capacity installation tallies were triangulated against top-down policy mandate quantification.
Variance decomposition across technology, application, installation type, and end-user segments shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level deployment trajectories weighted by regional regulatory intensity and interconnection queue depth. Key forecast inputs included lithium carbonate price scenario modeling and duration requirement evolution in utility tenders.
Decision-makers should treat outputs as directional under base assumptions of sustained IRA tax credit extension and EU Green Deal mandate enforcement; material deviation in either policy framework would warrant model refresh. Lithium supply concentration risk and flow battery cost curve compression represent specific factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Automotive Energy Storage System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Renewable Battery Storage Market
Battery Management System
EV Battery Management Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
Global Power Management System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market