
 Energy Storage Systems Market | 2026-2036
Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Storage Systems Market Analysis
A widening capital-intensity divergence between integrated manufacturers and pure-play assemblers is reorganizing competitive tiers in the energy storage sector. Tesla leverages its captive cell supply and automotive scale to compress system costs. LG Energy Solution sustains heavy R&D commitments across lithium-ion and next-generation chemistries. BYD Company anchors its position through backward integration into lithium mining and refining.
Energy storage systems encompass electrochemical, mechanical, and thermal technologies designed to capture energy at one time for use at a later time, with lithium-ion battery systems typically operating at 85-95% round-trip efficiency and 4-8 hour discharge durations for grid applications. These systems serve to balance intermittent renewable generation, defer transmission upgrades, and provide frequency regulation services to grid operators. Lithium-ion technology dominates installed capacity due to manufacturing scale and declining cell costs, while flow batteries occupy a specialized niche in long-duration applications requiring 8-12 hour discharge cycles. Grid stabilization applications command premium pricing for fast-response assets, whereas peak shaving in commercial and industrial segments competes on levelized cost against diesel generation and demand charges.
FERC Order 2222 in the United States enables distributed energy storage to participate in wholesale markets, while the EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds for cells sold in Europe. China's MIIT issues GB standards for battery safety and performance that effectively gate market access for imported systems. Stakeholders must monitor evolving duration requirements as grids shift from 4-hour to 8-12 hour storage needs, and decide whether to build in-house integration capabilities or outsource to specialist packagers.
Market Dynamics
Utility-scale procurement acceleration is compressing project development timelines and forcing cell suppliers to secure long-term offtake contracts before breaking ground on new manufacturing capacity.
Growth Catalysts
- IRA Production Tax Credits:Domestic content requirements under the US Inflation Reduction Act are incentivizing localized cell and module assembly, pulling manufacturing investment toward American soil.
- Grid Operator Procurement Mandates:State-level renewable portfolio standards in California and Texas are embedding storage capacity requirements directly into utility procurement solicitations.
- Lithium Iron Phosphate Chemistry:LFP cells are capturing market share from nickel-cobalt alternatives due to improved thermal stability and lower raw material cost exposure.
Market Restraints
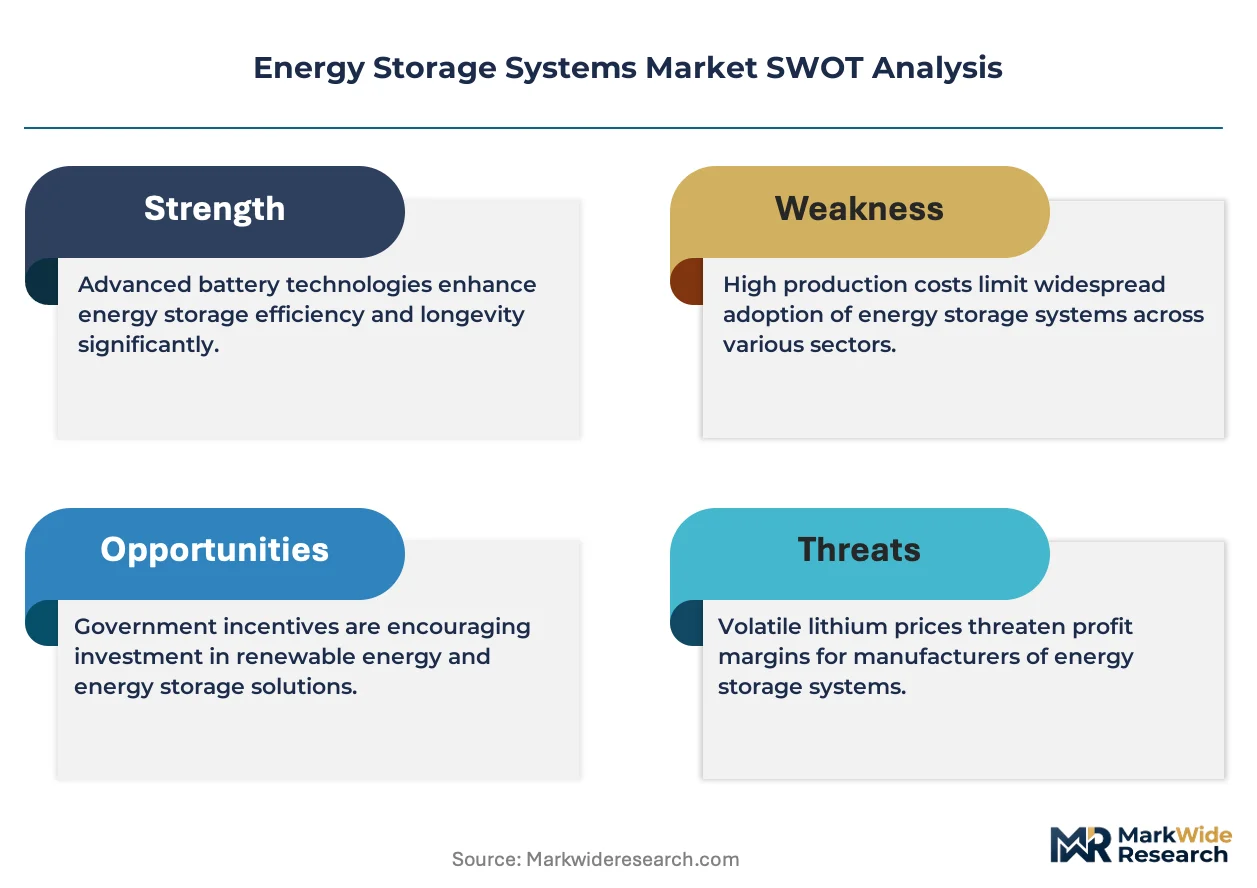
- Lithium Carbonate Price Volatility:Concentrated South American and Australian mining operations create input cost spikes that compress integrator margins during contract execution.
- Chinese Cell Supply Dominance:Over 70% of global cell manufacturing capacity sits within China's industrial clusters, creating geopolitical exposure for Western project developers.
- Round-Trip Efficiency Ceiling:Lithium-ion systems face fundamental thermodynamic limits near 95% that prevent further meaningful efficiency gains without chemistry breakthroughs.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme allocations for advanced chemistry cell production are opening greenfield opportunities outside established Chinese supply chains.
- Long-Duration Flow Batteries:Vanadium and iron-chromium systems are penetrating 8-12 hour discharge applications where lithium-ion degradation economics fail.
- Behind-the-Meter Aggregation:Virtual power plant business models are monetizing distributed residential and commercial storage through wholesale market participation enabled by FERC Order 2222.
Industry Challenges
- Battery Management System Firmware Integration:Proprietary communication protocols between cell suppliers and power conversion system vendors create commissioning delays and interoperability failures.
- Fire Safety Certification Bottlenecks:UL 9540A test queue backlogs at accredited laboratories are extending project timelines by 6-12 months for large-scale deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Storage Systems Market |
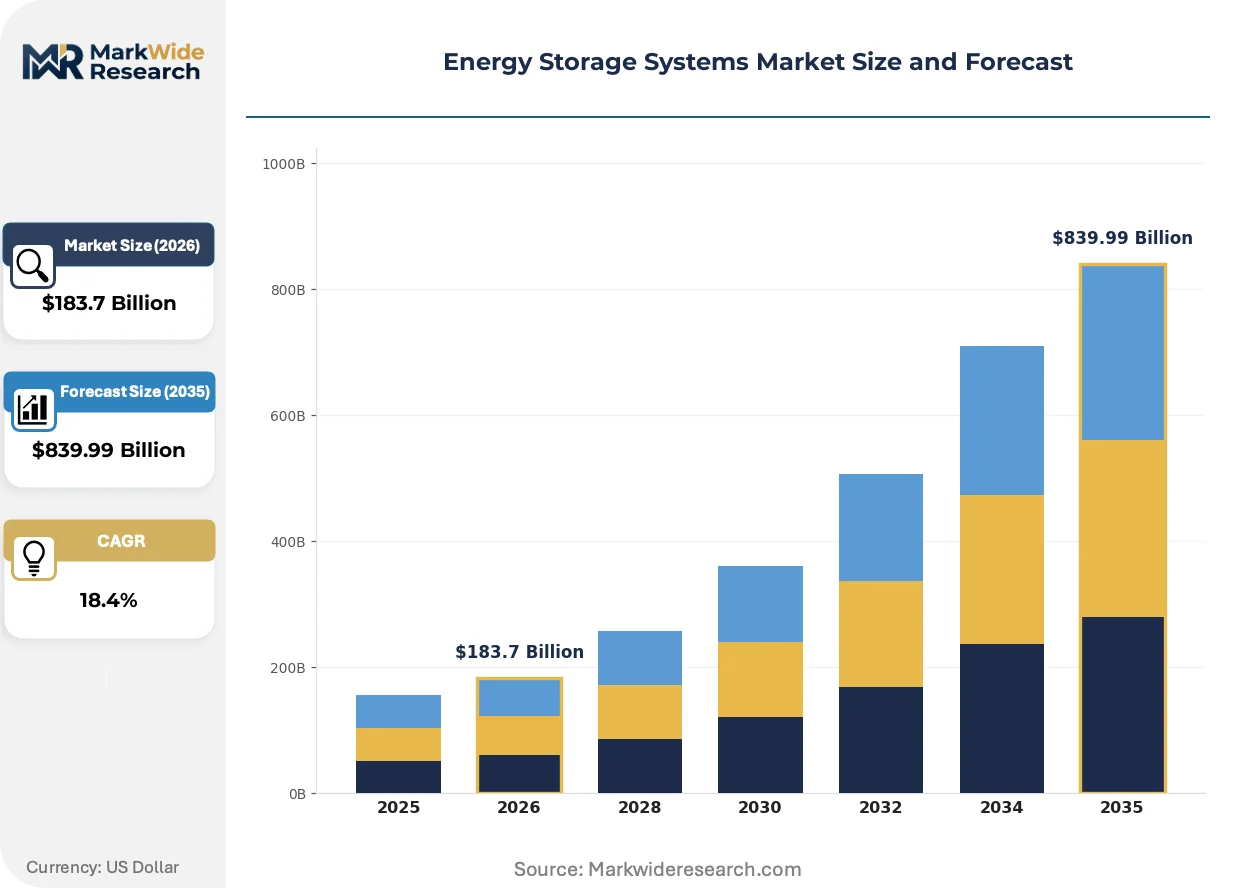
| Market Size in 2026 | $183.7 Billion |
| Market Size in 2035 | $839.99 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Lead Acid, Flow Batteries, Nickel-based Service Type: Installation, Maintenance, Consulting, Monitoring Application: Renewable Integration, Grid Stabilization, Backup Power, Peak Shaving End User: Utilities, Commercial, Residential, Industrial |
| Companies Covered | Tesla, LG Energy Solution, Samsung SDI, BYD Company, Panasonic Holdings Corporation, Fluence Energy, The AES Corporation, ABB, Powin Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Storage Systems Market Emerging Trajectories
Cell chemistry diversification and software-defined control architectures are separating hardware commoditization from value-creating intelligence layers in grid-connected storage.
Sodium-ion battery technology is fragmenting the entry-level stationary storage segment. Chinese manufacturers are commercializing 160 Wh/kg cells for 4-hour grid applications. Cost structures 20-30% below lithium-ion are enabling price-competitive bids in emerging markets previously served by lead-acid systems.
EU Battery Regulation carbon footprint declarations are forcing supply chain transparency. Mandatory recycled content thresholds phase in through 2031. European integrators are restructuring procurement to qualify cells under the new conformity assessment framework.
Asset owners are unbundling hardware procurement from long-term service agreements. Independent software vendors are capturing recurring revenue through predictive analytics and automated dispatch optimization. Texas ERCOT market participants are leading this shift toward performance-guaranteed contracting structures.
Energy Storage Systems Market Segmentation
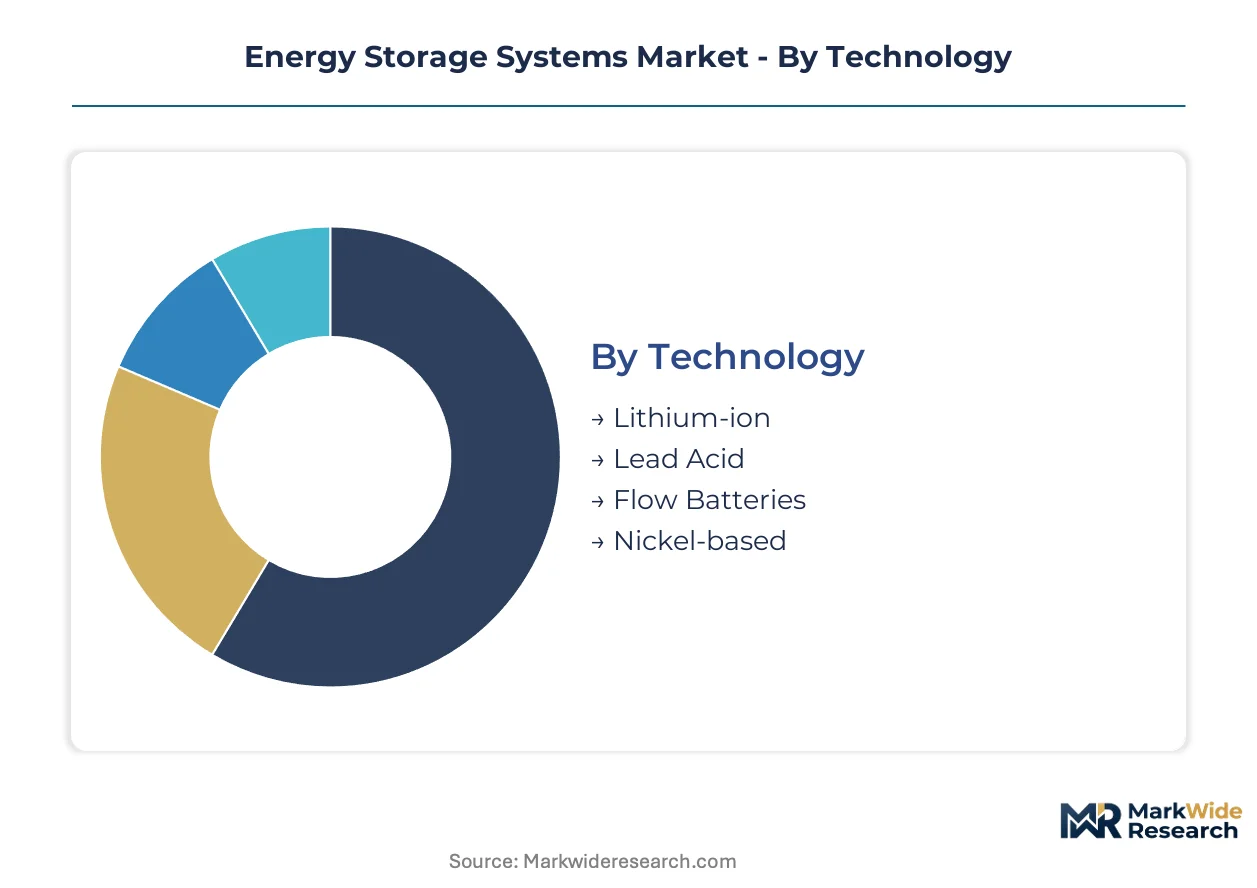
Technology heterogeneity in energy storage creates divergent margin profiles and capital intensity requirements across the value chain. Chemistry selection dictates project economics, warranty terms, and regulatory compliance pathways for integrators and asset owners.
Technology:
Flow batteries face the most acute substitution pressure as lithium-ion cost curves compress long-duration economics.
- Lithium-ion:Dominant electrochemical platform utilizing lithium iron phosphate and nickel-manganese-cobalt cathodes with 85-95% round-trip efficiency. Utility procurement in California and Texas concentrates demand for 4-hour grid assets as renewable portfolio standards harden capacity requirements.
- Flow Batteries:Vanadium and iron-chromium redox systems offering 8-12 hour discharge without capacity fade. Germany's CEA procurement frameworks and India's SECI tenders are creating dedicated procurement tracks where lithium-ion degradation economics fail.
- Lead Acid:Mature flooded and valve-regulated designs for backup power in telecom and data center applications.
- Nickel-based:Nickel-cadmium and nickel-metal hydride systems for extreme temperature environments where lithium-ion thermal management costs prove prohibitive.
Lithium-ion anchors the volume base while flow batteries gain share at the steepest rate.
Service Type:
Margin concentration follows the software-hardware unbundling trend reshaping contracting structures.
- Installation:EPC services encompassing civil works, electrical interconnection, and commissioning for utility-scale and distributed assets. Texas ERCOT market participants are driving fixed-price EPC trends that transfer construction risk to integrators.
- Maintenance:Long-term service agreements covering cell replacement, inverter refurbishment, and performance guarantees. Independent service providers in Germany are capturing recurring revenue as asset owners unbundle hardware from O&M.
- Consulting:Front-end engineering and grid interconnection studies for project development.
- Monitoring:Cloud-based asset management and predictive analytics platforms.
Installation commands the largest revenue pool while monitoring climbs fastest as predictive platforms displace reactive maintenance.
Application:
Duration requirements are fragmenting the addressable market by discharge hour and response speed.
- Renewable Integration:Co-located solar-plus-storage and wind-plus-storage configurations firming intermittent generation. China's state grid procurement in Qinghai and Gansu provinces concentrates demand for multi-hour buffering assets.
- Grid Stabilization:Fast-frequency response and synthetic inertia services requiring sub-second dispatch. UK's National Grid ESO procurement and Australia's AEMO markets command premium pricing for sub-100 millisecond response assets.
- Backup Power:Uninterruptible supply for critical infrastructure and commercial facilities.
- Peak Shaving:Demand charge reduction for commercial and industrial ratepayers.
Renewable integration carries the volume weight while grid stabilization expands most quickly as ancillary service markets deepen.
End User:
Procurement sophistication and contract duration vary sharply across customer archetypes.
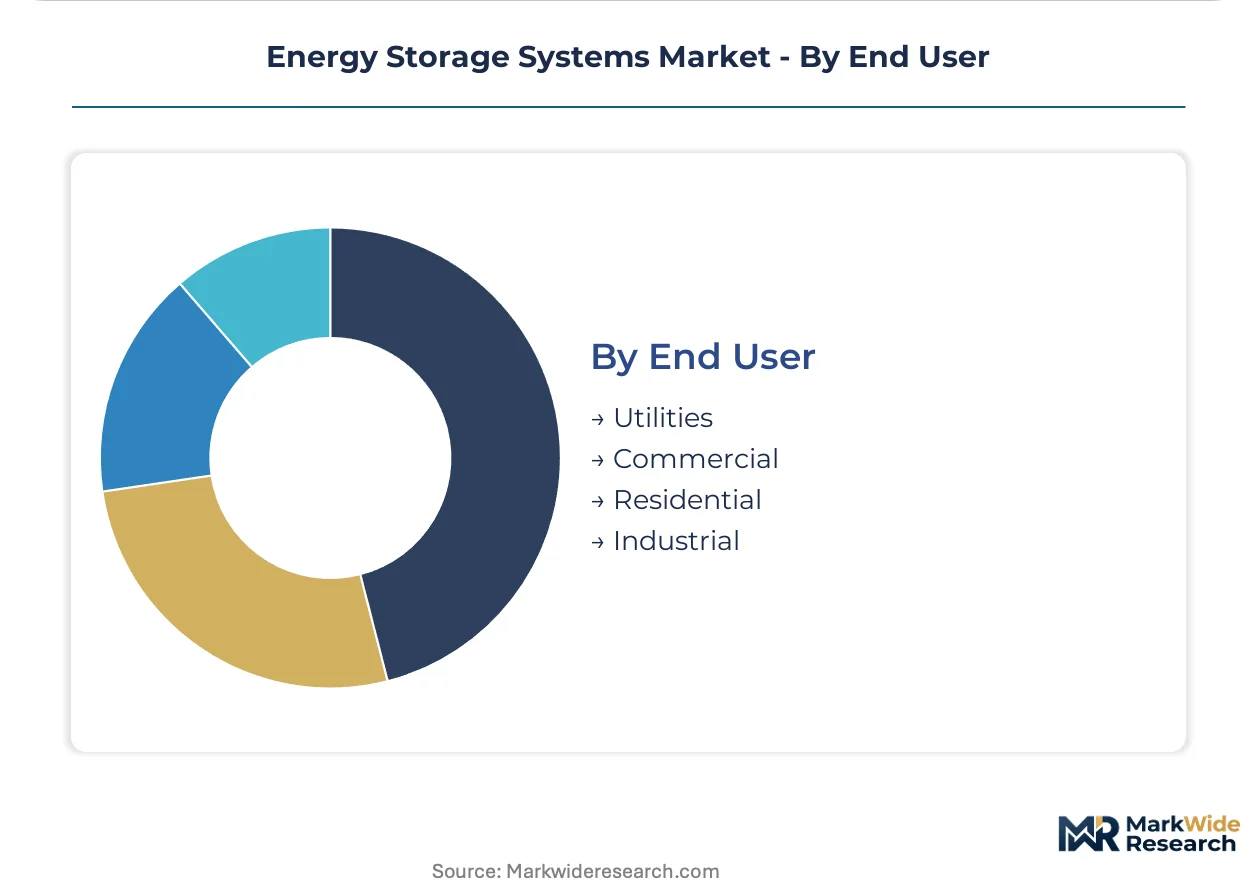
- Utilities:Investor-owned and public power entities procuring utility-scale assets through competitive solicitations. California IOUs and Texas municipal utilities are embedding 10-15 year service agreements into RFP structures.
- Commercial:Retail, healthcare, and data center operators seeking demand charge management and resilience. India's C&I segment is accelerating behind-the-meter deployment as state regulators approve time-of-use tariffs.
- Residential:Single-family and multi-family behind-the-meter storage paired with rooftop solar.
- Industrial:Heavy manufacturing and process industries requiring power quality and backup.
Utilities dominate absolute capacity additions while commercial expands fastest as retail rate structures incentivize distributed investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in China-based cell manufacturing diverges sharply from project development margins in Western markets where procurement sophistication concentrates. Regional deployment patterns reflect distinct regulatory frameworks and grid modernization timelines. Manufacturing clusters and utility procurement mandates are reshaping competitive access across major economies.
United States
Utility-scale procurement in Texas and California drives capacity additions as ERCOT and CAISO markets deepen storage participation. FERC Order 2222 enables distributed assets to bid into wholesale markets, accelerating behind-the-meter aggregation. Manufacturing investment clusters in Nevada and Michigan follow IRA production tax credit domestic content requirements.
China
State Grid procurement in Qinghai and Gansu provinces concentrates demand for multi-hour renewable integration assets. MIIT GB standards for battery safety and performance gate market access for imported systems. Cell manufacturing dominance in Fujian and Jiangsu provinces supplies over 70 percent of global capacity through vertically integrated industrial clusters.
Germany
CEA procurement frameworks create dedicated tracks for long-duration flow battery applications where lithium-ion degradation economics fail. EU Battery Regulation carbon footprint declarations and recycled content thresholds phase in through 2031, forcing supply chain restructuring. Industrial storage deployment concentrates in North Rhine-Westphalia's manufacturing corridor.
India
SECI tenders and state-level renewable purchase obligations embed storage capacity requirements into utility procurement. PLI scheme allocations for advanced chemistry cell production open greenfield manufacturing outside Chinese supply chains. Project development accelerates in Gujarat and Karnataka as regulators approve time-of-use tariffs for commercial and industrial segments.
Australia
AEMO market reforms command premium pricing for fast-frequency response assets requiring sub-100 millisecond dispatch. Grid stabilization procurement in Victoria and South Australia supports renewable integration from remote wind and solar zones. Residential battery adoption clusters in Queensland behind-the-meter solar penetration.
Energy Storage Systems Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the value chain. Integrated automotive-scale manufacturers compress system costs through captive cell supply and shared production infrastructure. Pure-play system integrators compete on project execution speed and software-defined control architectures. Specialist cell suppliers and independent power producers occupy distinct margin pools based on chemistry R&D depth and asset ownership models. Capacity expansion and strategic partnerships represent the dominant competitive moves as procurement timelines compress.
Among automotive-heritage manufacturers, Tesla and BYD Company represent the integrated archetype combining captive cell production with system packaging scale. LG Energy Solution exemplifies the specialist cell supplier position with heavy R&D commitments across lithium-ion and next-generation chemistries. These three anchors illustrate how backward integration into raw material sourcing and forward integration into project development create divergent margin profiles across competitive tiers.
| Leading Market Players |
|---|
| Tesla |
| LG Energy Solution |
| Samsung SDI |
| BYD Company |
| Panasonic Holdings Corporation |
| Fluence Energy |
| The AES Corporation |
| ABB |
| Powin Energy |
| Others |
Supply Flow & Price Mechanics
Lithium iron phosphate chemistry substitution for nickel-manganese-cobalt cathodes simultaneously shifts procurement geography toward Chinese industrial clusters and compresses cell pricing by eliminating cobalt cost exposure. This chemistry pivot concentrates supply chain power with vertically integrated manufacturers while forcing pure-play integrators to absorb margin compression through fixed-price EPC contracts.
Pricing Analysis
Configured-to-order utility-scale systems command 15-25% premiums over standard containerized products due to site-specific engineering and extended warranty terms. Project-based long-term offtake contracts dominate procurement, with price differentiation driven by certification tier (UL 9540A vs. GB standard compliance) and volume scale. Cost compression in the residential segment intensifies as sodium-ion alternatives enter emerging markets. Commercial and industrial buyers exhibit highest price sensitivity, while grid stabilization assets tolerate premium pricing for sub-100 millisecond response guarantees.
Supply Chain Analysis
China, South Korea, and Japan anchor global cell manufacturing, with Fujian and Jiangsu provinces supplying the majority of lithium iron phosphate capacity. The supply chain draws from Australian spodumene and Chilean brine for lithium feedstock, plus Indonesian nickel for high-energy variants. Single-source vulnerability concentrates in Chinese cathode precursor production. Distribution runs through specialist EPC contractors and direct utility procurement channels, with long-term service agreements increasingly unbundled from hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against sodium-ion substitution in price-sensitive emerging markets while capturing long-duration flow battery opportunities where lithium-ion degradation economics fail.
For Market Incumbents: Consolidate cell supply security through captive production or binding offtake agreements with South Korean and Japanese suppliers before breaking ground on new manufacturing capacity. Deepen backward integration into lithium refining to offset carbonate price volatility exposure. Prioritize UL 9540A certification investment to bypass laboratory queue bottlenecks that extend project timelines. For New Entrants and Emerging Players: Differentiate on software-defined control architectures that unbundle predictive analytics from hardware procurement, capturing recurring revenue streams as asset owners abandon bundled service agreements. Target India's commercial and industrial segment where time-of-use tariffs are accelerating behind-the-meter deployment. Pursue greenfield manufacturing under PLI scheme allocations to escape Chinese supply chain dominance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed EPC contractors holding utility-scale project pipelines but lacking captive cell supply. Long-term viability hinges on 5-10 year service agreement renewal rates and chemistry diversification beyond lithium-ion. Watch FERC Order 2222 implementation velocity as the signal for virtual power plant monetization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Domestic cell manufacturing in Nevada and Michigan secures IRA production tax credit eligibility. |
| Long-term Supply Agreement | Binding lithium offtake contracts with Australian miners hedge against carbonate price spikes. |
| Technology Licensing | Flow battery patents from German CEA procurement frameworks open 8-12 hour duration markets. |
| Vertical Integration into Storage | Automotive-scale manufacturers compress system costs through shared cathode production lines. |
| Green Certification Program | EU Battery Regulation carbon footprint declarations qualify cells for European procurement tracks. |
Methodological Framework
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition modeling and top-down regulatory framework analysis provided triangulation across the energy storage value chain.
Sensitivity analysis tested forecast outputs against lithium carbonate price volatility scenarios and IRA domestic content requirement phase-ins across the projection horizon. Segmentation dimensions modeled include technology chemistry, service type, application duration, and end-user procurement sophistication. CAGRs derived from project pipeline aggregation and manufacturing capacity expansion announcements, with grid operator procurement mandates and renewable portfolio standards as key demand-side inputs.
The analysis sits within stated boundaries; outcomes outside sustained IRA incentive continuity or accelerated FERC Order 2222 implementation would require recalibration. Forecasts reflect assumptions regarding lithium supply expansion and flow battery cost reduction trajectories. Recalibration cycles align with material shifts in utility procurement timelines and cell chemistry substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Battery Energy Management System Market
Battery Management System
North America Battery Management System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
EV Battery Management Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Global Power Management System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
United States Rechargeable Battery Market