
 North America Energy Storage Market | 2026-2036
North America Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Energy Storage Market Analytics
Utility procurement consolidation is repositioning the competitive landscape for battery system integrators. Tesla Inc. leverages its Megapack manufacturing scale and software stack to dominate utility-scale deployments across the southwestern United States. Fluence Energy Inc. competes through its technology-agnostic platform and deep utility relationships spanning multiple ISO territories. Powin Energy Corporation specializes in modular, containerized solutions that reduce installation complexity for independent power producers.
North America energy storage encompasses electrochemical and mechanical systems engineered to absorb, retain, and discharge electrical energy on demand, with lithium-ion cells currently achieving round-trip efficiencies exceeding 90% and operational lifespans of 4,000 to 8,000 cycles depending on chemistry and thermal management design. These systems primarily buffer supply-demand mismatches, provide frequency regulation, and enable deferred transmission investments across bulk power networks. Lithium-ion technology anchors current deployment volumes due to declining cell costs and established supply chains, while flow battery chemistries occupy a specialized niche in long-duration applications requiring 8 to 12 hours of continuous discharge. Grid storage applications capture the dominant share of installed megawatts, though commercial use segments are expanding fastest behind-the-meter as C&I customers seek demand charge reduction and resilience against escalating outage frequency.
FERC Order 841 mandates that wholesale market operators remove barriers to storage participation in capacity, energy, and ancillary service markets, while the Inflation Reduction Act extends standalone storage eligibility for investment tax credits previously restricted to solar-paired systems. NERC reliability standards and IEEE 1547 interconnection requirements further shape product certification pathways and grid integration protocols for developers. Stakeholders must monitor evolving state-level procurement mandates and interconnection queue reforms that will determine deployment velocity across ISO territories.
Market Dynamics
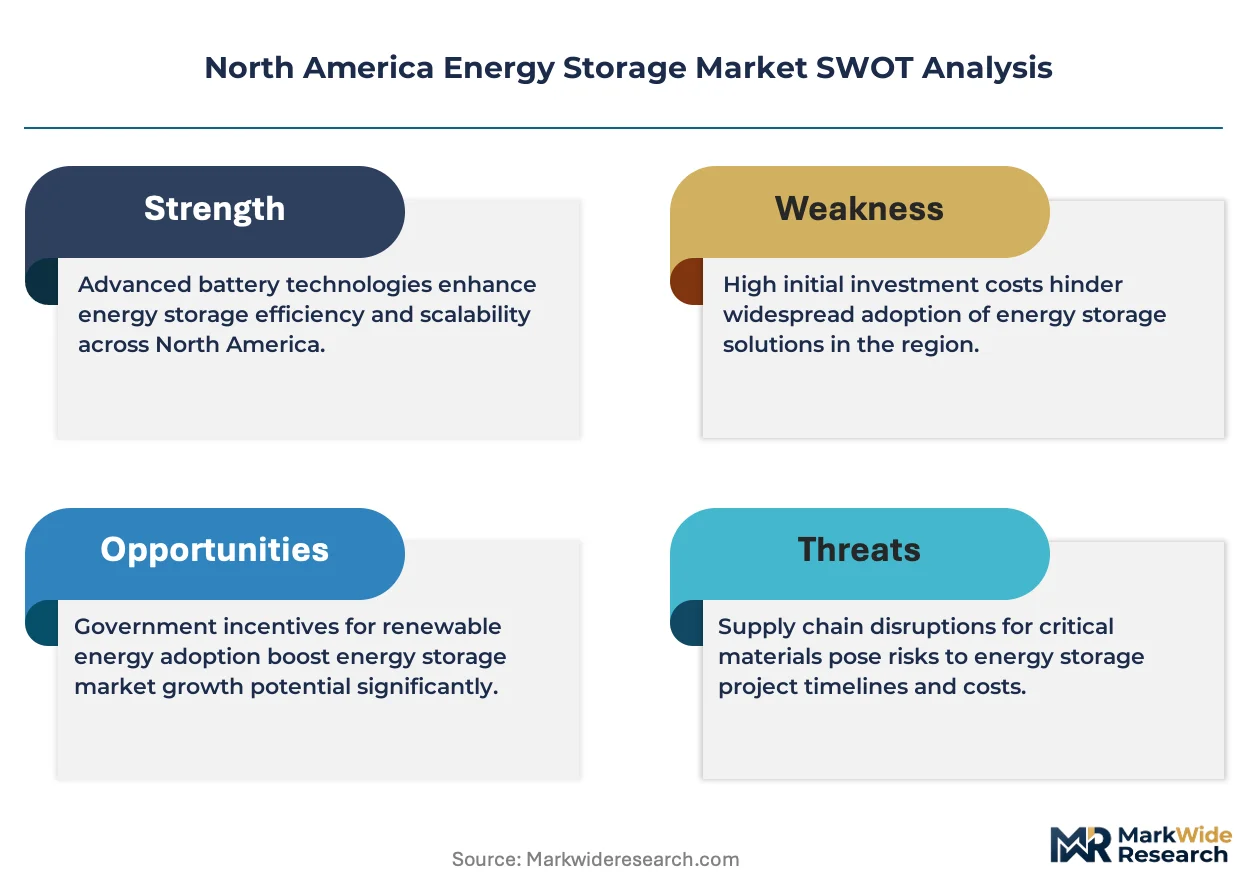
Utility-scale procurement consolidation is compressing margins for battery system integrators while rewarding manufacturing scale and software differentiation. The Inflation Reduction Act's standalone storage tax credit eligibility is redirecting capital flows from solar-hybrid projects toward dedicated grid assets.
Growth Catalysts
- FERC Order 841:The mandate compels ISOs and RTOs to remove market participation barriers for storage resources in capacity, energy, and ancillary service auctions across the United States.
- California's SB 100:The state's 100% clean electricity target by 2045 requires massive battery deployment to firm intermittent solar and wind generation.
- Lithium iron phosphate chemistry:Improved thermal stability and extended cycle life are displacing nickel-cobalt formulations in utility-scale installations.
Market Restraints
- Critical mineral concentration:Cathode active material processing concentrates in China, exposing supply chains to trade policy volatility and logistics disruption.
- Interconnection queue delays:Grid operators in Texas and California face multi-year backlogs for storage projects seeking transmission access.
- Flow battery cost premiums:Vanadium redox systems remain uncompetitive for 4-hour applications despite superior duration performance.
Strategic Opportunities
- Texas ERCOT territory:The isolated grid's scarcity pricing mechanism creates arbitrage opportunities for merchant storage assets.
- Behind-the-meter commercial:C&I customers in Ontario seek demand charge reduction and resilience against escalating outage frequency.
- Inflation Reduction Act domestic content bonuses:Additional tax credit increments reward North American cell and module manufacturing.
Industry Challenges
- Power electronics engineering talent:Shortages of inverter and battery management system designers constrain product development cycles.
- UL 9540A fire safety certification:Extended testing timelines for large-scale battery systems delay project commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Energy Storage Market |
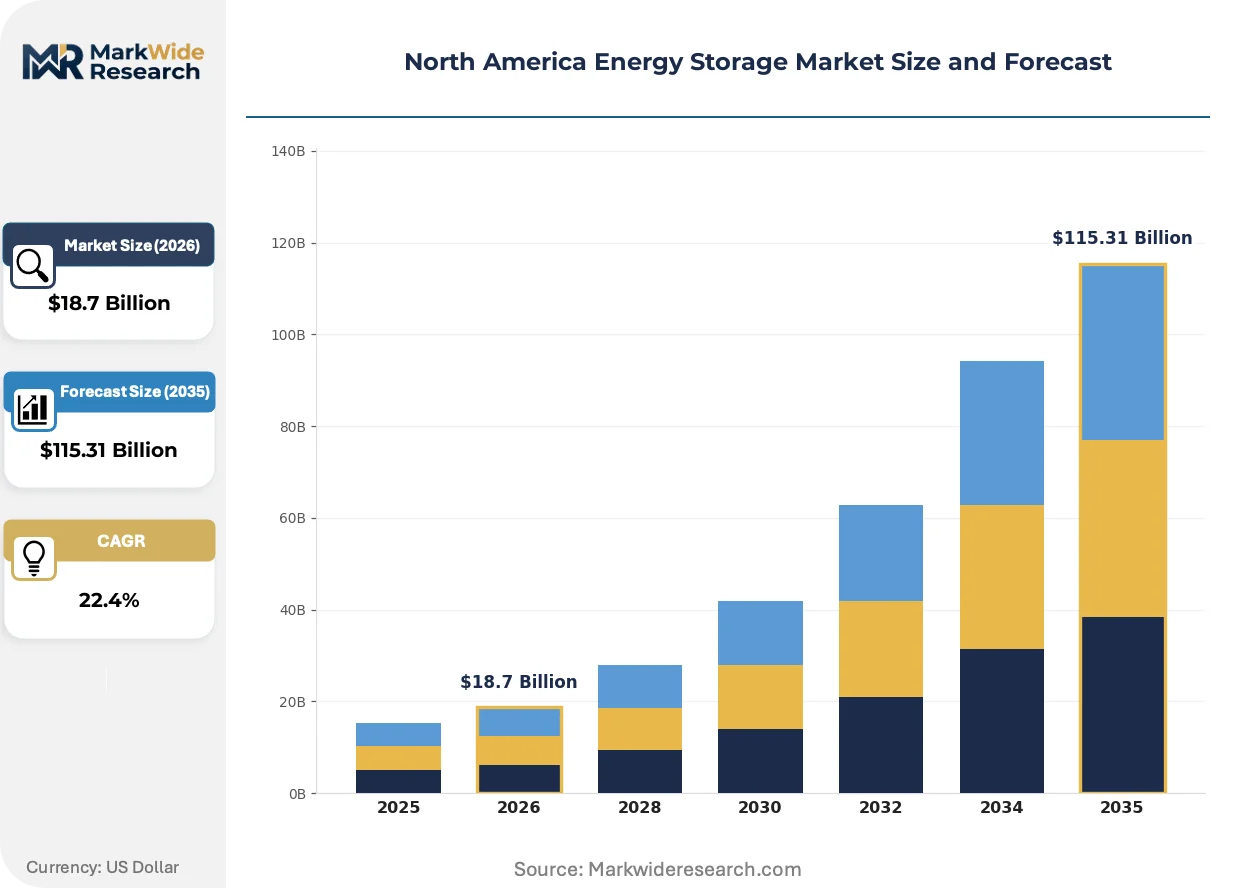
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-Ion, Lead Acid, Flow Battery, Nickel-Cadmium Application: Grid Storage, Commercial Use, Residential Use, Renewable Integration End User: Utilities, Industrial Sector, Residential Consumers, Commercial Consumers Installation Type: On-Ground, Rooftop, Containerized, Integrated |
| Companies Covered | Tesla Inc., Fluence Energy Inc, Powin Energy Corporation, Enphase Energy, ESS Inc., GE Aerospace, LG Energy Solution Ltd., Samsung SDI Co. Ltd, NextEra Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Energy Storage Market Evolving Landscape
Battery system architecture is evolving from passive containers toward intelligent grid assets with predictive control capabilities. Software-defined power electronics are compressing commissioning timelines and enabling remote optimization.
Solid-state lithium-metal cells are electrifying next-generation storage design by eliminating flammable liquid electrolytes. Automotive suppliers are licensing cell formats originally developed for electric vehicles to stationary integrators seeking higher energy density. This convergence is compressing the performance gap between transportation and grid applications.
The Inflation Reduction Act's domestic content requirements are reshaping manufacturing location decisions for battery system suppliers. Developers must now trace component provenance through tier-three suppliers to qualify for bonus credits. Texas and Arizona are attracting cell gigafactories to capture this incentive stacking.
Merchant project development is displacing traditional utility-owned storage procurement in deregulated markets. Independent power producers in ERCOT and CAISO are securing long-term offtake contracts with data center operators and industrial loads. This shift concentrates development risk with financial sponsors rather than ratepayers.
North America Energy Storage Market Segmentation
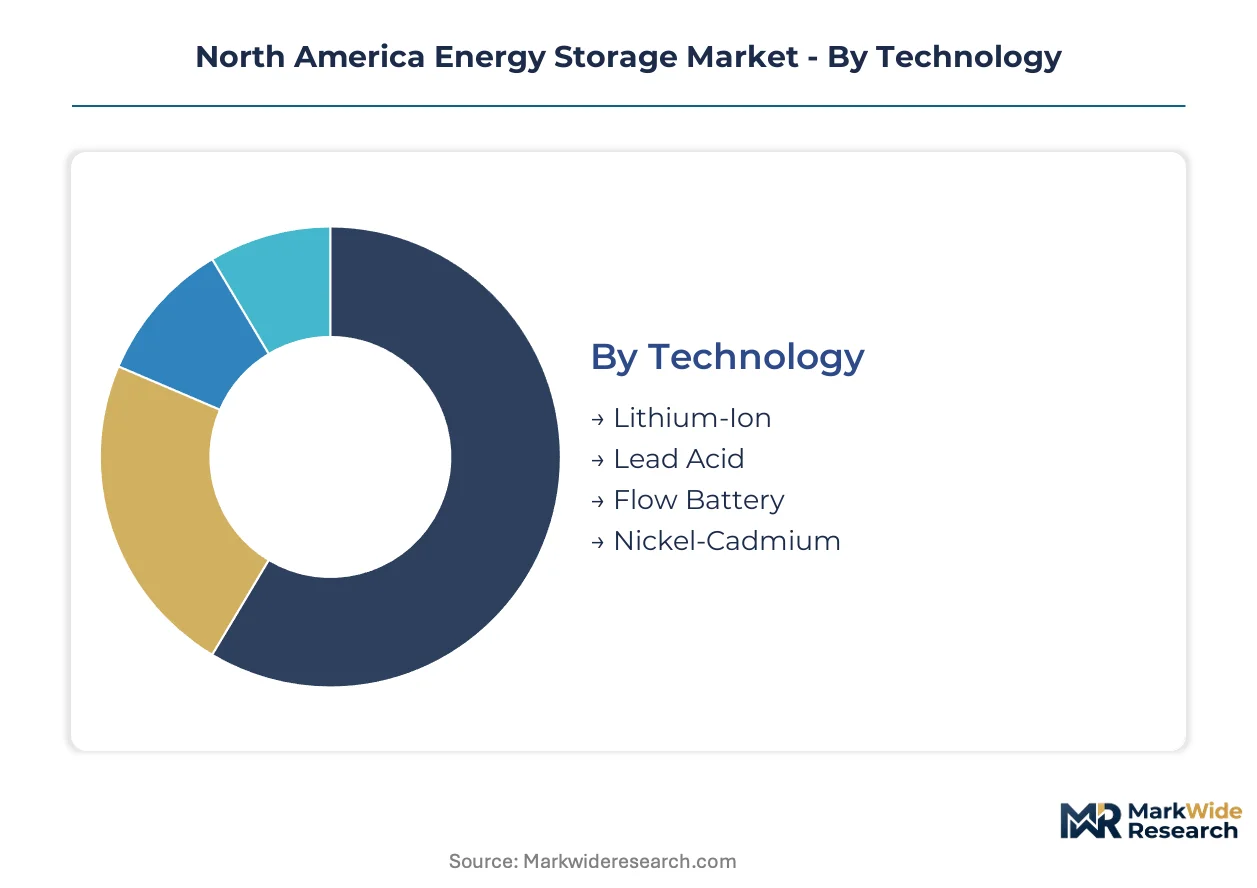
Technology and application boundaries in North American energy storage are blurring as integrators bundle hardware with software services. Segmentation clarity determines procurement strategy for utilities navigating FERC Order 841 compliance and ITC bonus qualification.
Technology:
Supply concentration in cathode active materials is forcing technology choices that balance performance against geopolitical exposure.
- Lithium-Ion:Lithium iron phosphate cells dominate utility-scale deployments with 90%+ round-trip efficiency and 4,000-8,000 cycle lifespans. California and Texas utilities favor this chemistry for 4-hour duration requirements under SB 100 procurement mandates.
- Lead Acid:Mature recycling infrastructure and established supply chains sustain demand in rural residential backup systems across the southeastern United States. Cost sensitivity in off-grid applications preserves this segment despite energy density limitations.
- Flow Battery:Vanadium redox systems target 8-12 hour duration niches where lithium-ion degradation accelerates. Ontario grid operators pilot these for seasonal storage arbitrage against hydroelectric price volatility.
- Nickel-Cadmium:Extreme temperature tolerance sustains deployment in northern Canadian remote communities where thermal management infrastructure is impractical.
Today's leader: Lithium-Ion. Tomorrow's challenger: Flow Battery.
Application:
Application mix tracks state-level regulatory pressure and renewable penetration rates across ISO territories.
- Grid Storage:Bulk power systems absorb gigawatt-hours of wind and solar intermittency across ERCOT and CAISO balancing areas. FERC Order 841 market access reforms are accelerating merchant project development independent of utility ownership.
- Commercial Use:Behind-the-meter C&I installations target demand charge reduction and outage resilience. Ontario manufacturers face escalating electricity reliability pressures from aging transmission infrastructure.
- Residential Use:Solar-plus-storage adopters in California and Arizona leverage ITC stacking for whole-home backup. NEM 3.0 export rate reductions are shifting economics toward self-consumption optimization.
- Renewable Integration:Co-located battery assets firm wind and solar output for PPA offtakers. Texas developers pair storage with solar to capture production tax credit and investment tax credit synergies.
Grid Storage commands current deployment volumes. Commercial Use is climbing the fastest as C&I electricity rates outpace residential inflation.
End User:
End user procurement authority determines contract structures and technology specifications across the value chain.
- Utilities:Investor-owned utilities in California, Texas, and Ontario issue RFPs for multi-hundred-megawatt systems with 15-20 year service agreements. Procurement teams prioritize bankable warranties and demonstrated fire safety certification.
- Industrial Sector:Data center operators and semiconductor fabs in Arizona and Texas contract for dedicated storage capacity to manage power quality and secure renewable energy matching claims.
- Residential Consumers:Homeowners in fire-prone California counties and hurricane-exposed Gulf Coast states install battery backup for resilience against escalating outage frequency.
- Commercial Consumers:Retail chains and logistics facilities deploy storage to manage coincident peak demand charges and participate in utility demand response programs.
Utilities dominate megawatt procurement. Industrial Sector buyers are gaining share fastest through direct contracting with independent power producers.
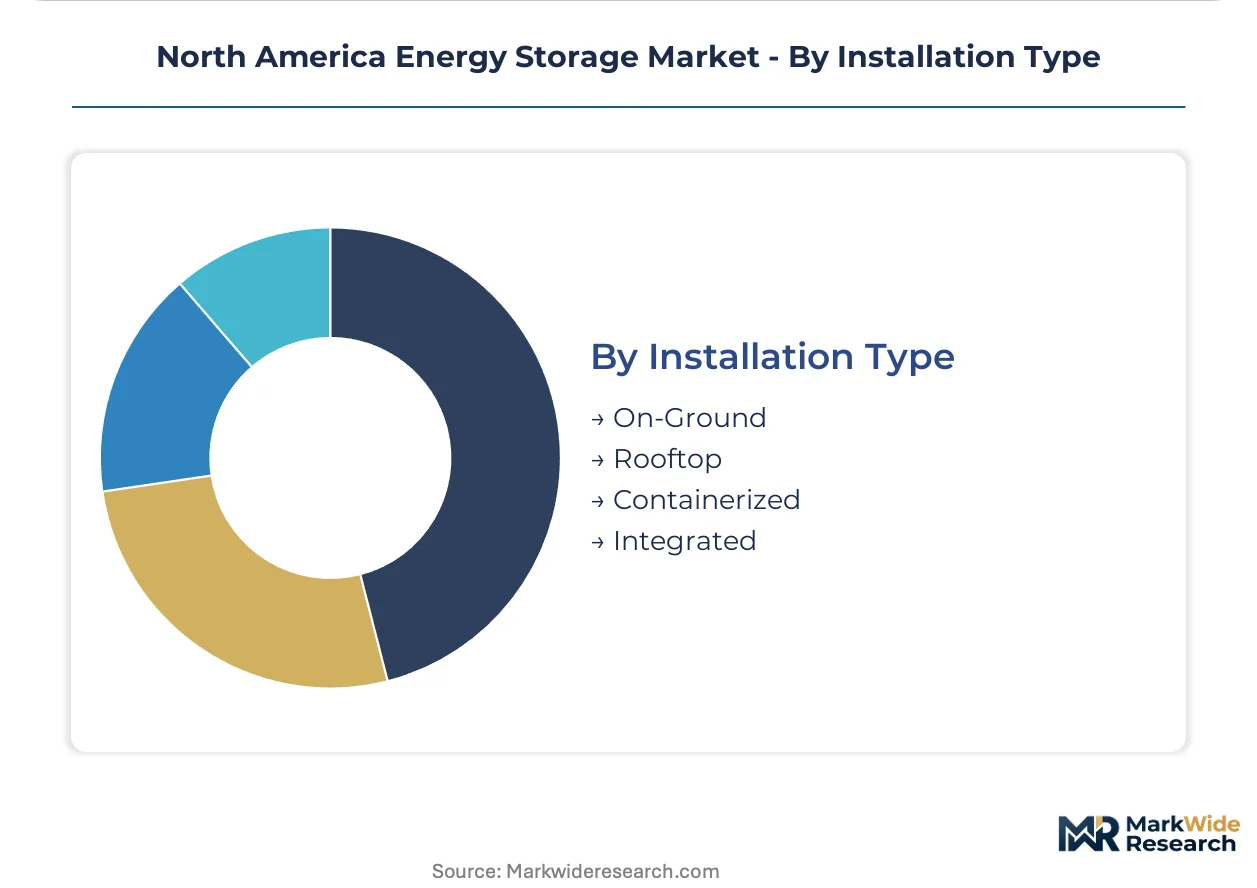
Installation Type:
Installation configuration reflects site constraints, project scale, and developer EPC capabilities.
- On-Ground:Utility-scale arrays on graded land in Texas and Arizona desert regions minimize civil engineering costs and enable direct high-voltage interconnection.
- Rooftop:Commercial buildings in dense urban California markets deploy solar-plus-storage where land availability is constrained and permitting timelines for ground-mount projects extend delivery schedules.
- Containerized:Modular factory-integrated systems reduce field commissioning time for independent power producers targeting ERCOT merchant opportunities. Powin and Fluence compete on container density and software integration.
- Integrated:Building-embedded storage in new construction commercial projects leverages structural and electrical infrastructure cost sharing. Ontario building codes are beginning to mandate readiness provisions for future battery installation.
Containerized systems anchor utility-scale deployment velocity. Integrated installations are expanding most quickly in commercial new construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's storage procurement lags the United States in absolute megawatts yet matches its southern neighbor in deployment velocity per capita, while Mexico's nascent market concentrates on industrial microgrids rather than grid-scale assets.
United States
ERCOT's scarcity pricing mechanics and CAISO's resource adequacy mandates drive merchant storage development across Texas and California. FERC Order 841 compels ISO participation reforms that unlock revenue stacking for battery assets. The Permian Basin and Imperial Valley host the densest project pipelines, with developers targeting nodal price volatility and transmission congestion relief.
Canada
Ontario's IESO capacity auction redesign and Alberta's deregulated wholesale market create divergent procurement pathways for storage investors. The federal Investment Tax Credit extension through 2034 matches US incentives to retain capital flows. Toronto-Waterloo corridor utilities pilot long-duration systems for winter peak shaving against nuclear refurbishment schedules.
Mexico
Industrial clusters in Nuevo León and Baja California deploy behind-the-meter storage to manage CFE tariff volatility and power quality disruptions. CRE market reforms remain stalled, limiting grid-scale participation. Monterrey manufacturing parks represent the primary addressable market for commercial integrators.
North America Energy Storage Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North American energy storage value chain. The market structure consolidates around three to five dominant system integrators capturing utility-scale procurement, while dozens of regional EPCs and software vendors fragment the long tail. Strategic archetypes separate manufacturing-scale battery producers, technology-agnostic integration platforms, and modular container specialists. Competitive intensity concentrates on manufacturing capacity expansion and software-defined control system differentiation.
Within the manufacturing-scale tier, Tesla Inc. and LG Energy Solution Ltd. anchor opposite ends of the vertical integration spectrum. Fluence Energy Inc. exemplifies the technology-agnostic platform model. These three entities collectively represent the dominant competitive vectors—captive cell supply, independent software stacks, and utility relationship depth—that define procurement outcomes across ISO territories.
| Leading Market Players |
|---|
| Tesla Inc. |
| Fluence Energy Inc |
| Powin Energy Corporation |
| Enphase Energy |
| ESS Inc. |
| GE Aerospace |
| LG Energy Solution Ltd. |
| Samsung SDI Co. Ltd |
| NextEra Energy |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price indices cascading from Chinese spot markets compress cell procurement costs for North American integrators, translating into tiered system pricing that separates utility-scale turnkey providers from modular container specialists serving independent power producers.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for lithium iron phosphate cells, forcing three-tier pricing structure across premium, standard, and economy levels based on UL 9540A certification status and domestic content qualification. Cost compression in standard-tier systems intensifies because gigafactory scale economies outpace demand growth in Texas and California procurement corridors. Merchant developers in ERCOT exhibit highest price sensitivity, while data center operators in Arizona prioritize power quality guarantees over capital expenditure minimization.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale buyer demand for hundred-megawatt systems, while distributor networks serve commercial behind-the-meter installations. Cathode active material processing concentrates in China, with South Korea and Japan anchoring cell manufacturing. The supply chain draws from Chilean lithium brine, Australian spodumene, and Indonesian nickel. Tariff exposure on Chinese-processed materials creates margin volatility for integrators lacking long-term offtake agreements with non-Chinese suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Energy Storage Market functions as a geographic-arbitrage play where Texas ERCOT scarcity pricing mechanics and California ITC bonus stacking create divergent return profiles for identical hardware deployments.
For Market Incumbents: Acquire power electronics engineering talent pools in Phoenix and Austin to offset inverter designer shortages threatening product development timelines. Consolidate fire safety certification capabilities through captive UL 9540A testing infrastructure, defending against emerging Chinese integrators with accelerated compliance timelines. Capacity addition in Arizona cell manufacturing secures domestic content bonus eligibility as IRA requirements tighten.
For New Entrants and Emerging Players: Behind-the-meter commercial buyers in Ontario's manufacturing corridor represent the most penetrable segment, with aging transmission infrastructure driving resilience demand faster than utility-scale queue reforms. Target 4-8 hour duration systems for industrial microgrids in Nuevo León, Mexico, where CRE market paralysis limits incumbent participation. Partner with established EPC contractors to bypass multi-year interconnection backlogs plaguing greenfield developers.
For Investors and Strategic Acquirers: Asymmetric upside sits with technology-agnostic software platforms controlling multiple battery chemistries through unified control architectures. Long-term viability centers on developers with secured nodal interconnection positions in ERCOT and CAISO territories rather than equipment manufacturers facing commoditization. Monitor FERC Order 841 implementation variance across ISOs as the signal indicating which balancing areas will accelerate merchant storage participation.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cell Manufacturing Buildout | Captures IRA domestic content bonuses while reducing exposure to Chinese cathode processing concentration. |
| Software-Defined Control Platform Development | Enables predictive arbitrage optimization across ERCOT nodal price volatility and CAISO resource adequacy markets. |
| Long-Duration Flow Battery Pilot Deployment | Positions for Ontario winter peak shaving and seasonal arbitrage against hydroelectric price volatility. |
| Merchant Storage Asset Aggregation | Concentrates development risk with financial sponsors rather than ratepayers in deregulated ISO territories. |
| Fire Safety Certification Infrastructure Investment | Compresses UL 9540A testing timelines that currently delay project commercialization by 12-18 months. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down cell manufacturing tracking forms the analytical core, combining primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation through EIA capacity data, FERC interconnection filings, IEA technology roadmaps, and project development databases. Cross-referencing bottom-up installation tallies against top-down supply chain disclosures identifies measurement gaps in merchant project reporting.
Historical deployment trajectories across technology, application, and end-user segments establish baseline growth patterns projected across the analysis window. Segmentation dimensions include battery chemistry, duration requirement, procurement authority structure, and regional regulatory framework. CAGRs derive from fitted trendlines adjusted for policy inflection points including IRA implementation and FERC Order 841 compliance deadlines. Forecast inputs incorporate interconnection queue velocity, cathode material cost curves, and ISO market redesign timelines.
Underlying measurement precision varies by segment; utility-scale deployments carry tighter precision than behind-the-meter commercial installations where reporting lags are pronounced. Forecasts reflect documented assumptions regarding IRA extension continuity, lithium supply elasticity, and interconnection reform implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
US Energy Storage Market
Battery Management System
Energy Storage Systems Market
Battery Management System
North America Battery Energy Storage System Market