
 United Kingdom Photovoltaic Mounting System Market | 2026-2036
United Kingdom Photovoltaic Mounting System Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Photovoltaic Mounting System Market Analytics
Modular rail-and-bracket kits bundled with pre-assembled clamps is repositioning buyer choice toward faster on-site installation with fewer specialized tools. Solarport Systems Ltd. leverages its domestic manufacturing footprint to anchor supply security for UK installers. Renusol Europe GmbH specializes in flat-roof ballasted systems that dominate commercial applications across London and Birmingham. Esdec UK competes through integrated cable management features that reduce balance-of-system labor costs.
A photovoltaic mounting system comprises structural hardware—typically aluminum extrusions, galvanized steel posts, and stainless steel fasteners—engineered to secure solar modules at specified tilt angles while withstanding wind loads and snow loads per BS EN 1991 standards. Its primary commercial purpose is to maximize energy yield per installed kilowatt while ensuring twenty-five-year structural integrity across varied UK roof substrates and ground conditions. Roof mount systems lead volume due to retrofit penetration of Britain's aging housing stock, while tracking systems represent the fastest-expanding margin pool as utility developers pursue bifacial module optimization. Aluminum dominates material selection for weight-sensitive pitched-roof applications, though steel retains cost advantage in ground mount arrays where transport logistics favor heavier sections.
The Microgeneration Certification Scheme and MCS 012 product standard govern installer eligibility and mounting kit eligibility for feed-in tariff successors, directly filtering market access for non-certified suppliers. Building Regulations Part L and forthcoming Future Homes Standard mandate renewable-ready construction, embedding mounting infrastructure into new-build specifications. Stakeholders must monitor grid connection queue reforms and local planning authority solar guidelines as these determine project viability timelines more precisely than module cost curves.
Market Dynamics
Tracker-equipped ground mount arrays are compressing installation timelines while bifacial module deployment forces structural hardware redesign across England's utility-scale pipeline.
Growth Catalysts
- Contracts for Difference scheme:The UK government's auction mechanism guarantees strike prices for renewable generation, de-risking capital deployment for utility-scale solar farms and accelerating procurement of tracking systems.
- Building Regulations Part L:Updated thermal efficiency standards mandate renewable-ready construction in new residential developments, embedding mounting infrastructure specifications into architectural drawings.
- East Anglia solar corridor:Concentrated grid connection capacity and flat agricultural land availability align to create England's densest cluster of ground-mount procurement activity.
Market Restraints
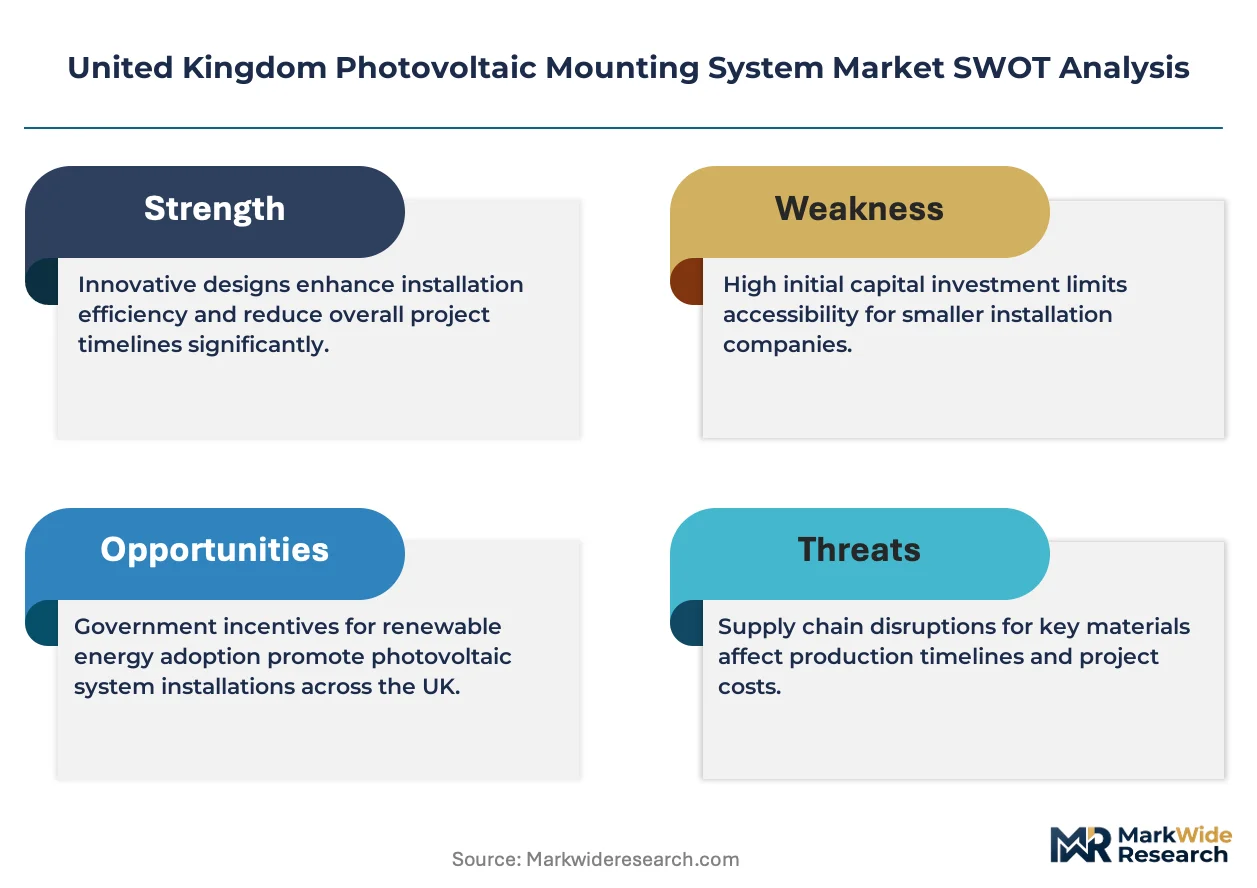
- Aluminum price volatility:Rail-and-bracket kits depend on extruded aluminum sections where commodity fluctuations compress margin predictability for domestic fabricators.
- Grid connection queue congestion:National Electricity System Operator backlogs extend project viability timelines beyond hardware procurement cycles, freezing capital in pre-construction phases.
- Steel transport economics:Galvanized steel posts retain cost advantage in ground mounts but face logistics penalties when sourced from continental European mills.
Strategic Opportunities
- Future Homes Standard:Forthcoming mandates will require all new housing to produce net-zero carbon emissions, expanding specification-driven demand for integrated roof-mount systems.
- Commercial flat-roof segment:Ballasted systems remain underdeployed across Birmingham and Manchester industrial estates where structural load constraints favor distributed generation.
- Bifacial-tracker convergence:Dual-axis tracking hardware optimized for rear-side energy capture opens margin pools in utility procurement where energy yield per hectare dominates site selection.
Industry Challenges
- MCS 012 certification timelines:Microgeneration Certification Scheme product approval processes create six-to-nine-month delays for mounting kit suppliers seeking eligibility for feed-in tariff successor schemes.
- Specialized installation labor:Tracker commissioning requires mechanical and electrical competencies that outstrip current workforce training pipelines, constraining deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Photovoltaic Mounting System Market |
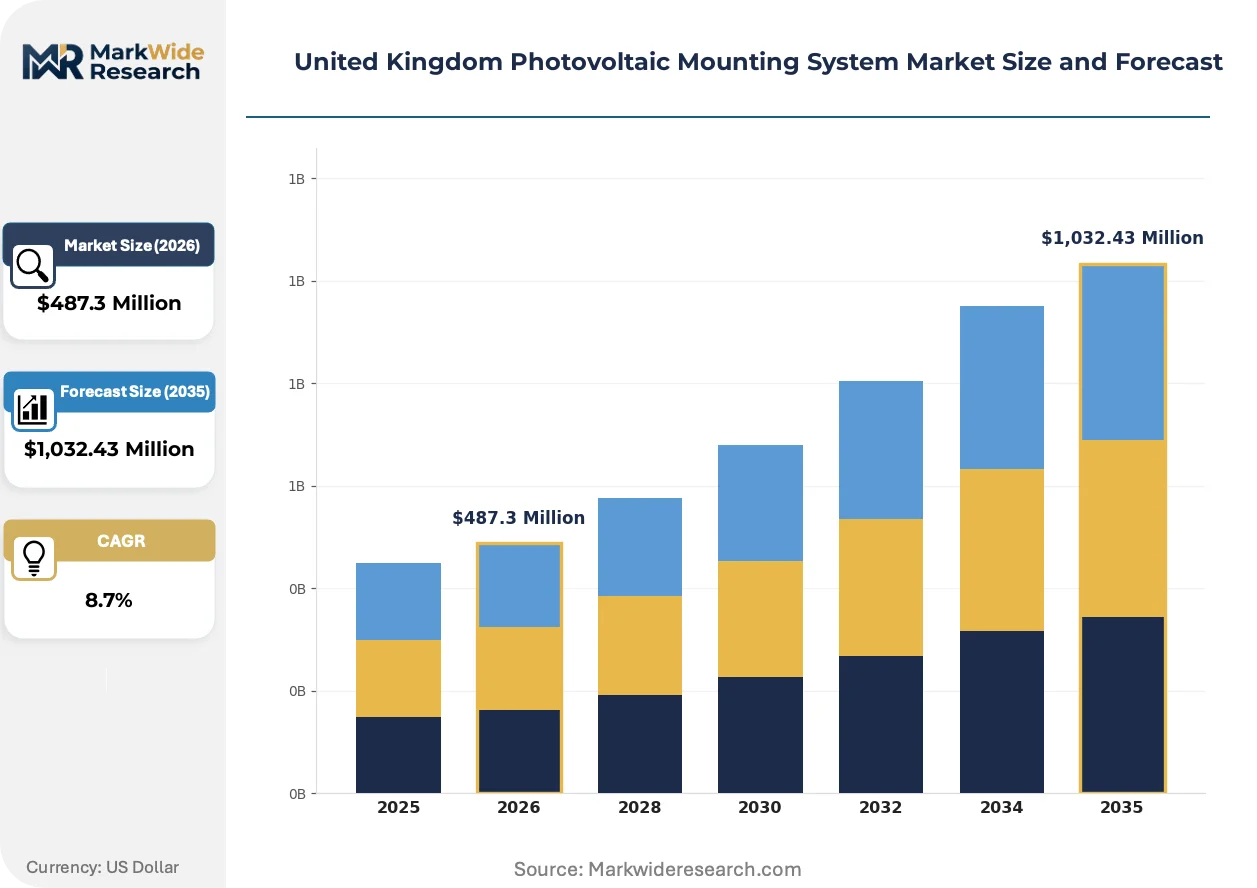
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Mount, Roof Mount, Carport Mount, Building Integrated PV Material: Aluminum, Steel, Plastic, Composite Installation Type: Fixed Tilt, Adjustable Tilt, Tracking System, Hybrid End User: Residential, Commercial, Industrial, Agricultural |
| Companies Covered | Solarport Systems Ltd., Renusol Europe GmbH, Esdec UK, Corab UK, Bauder Ltd., Van der Valk Solar Systems, K2 Systems GmbH, Schletter Group, NEXTracker Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Photovoltaic Mounting System Market Evolving Landscape
Hardware modularity and software-integrated tracking are compressing balance-of-system costs while procurement centralization reconfigures buyer-supplier power dynamics across the installation base.
Single-axis tracking systems is electrifying utility-scale deployment economics by enabling continuous module orientation toward solar azimuth. Developers across Norfolk and Cambridgeshire are specifying these arrays for bifacial panel configurations. The technology is electrifying competitive positioning among mounting suppliers who can integrate drive motors with structural warranties.
The Future Homes Standard and Building Regulations Part L together mandate renewable-ready roof specifications for all new residential construction from 2025 onward. Housebuilders must pre-install mounting infrastructure during framing phases to comply with thermal performance certificates. Suburban developments around Bristol and Exeter are piloting integrated solar-ready truss specifications ahead of formal enforcement.
Aggregator-led procurement consortia now dominate commercial rooftop specifications, displacing fragmented installer purchasing. Large multi-site operators across London and the South West negotiate frame-and-fixture bundles directly with manufacturers, bypassing traditional distribution tiers. This concentration is most visible in retail and logistics estate portfolios where standardized flat-roof ballast systems reduce engineering redundancy.
United Kingdom Photovoltaic Mounting System Market Segmentation
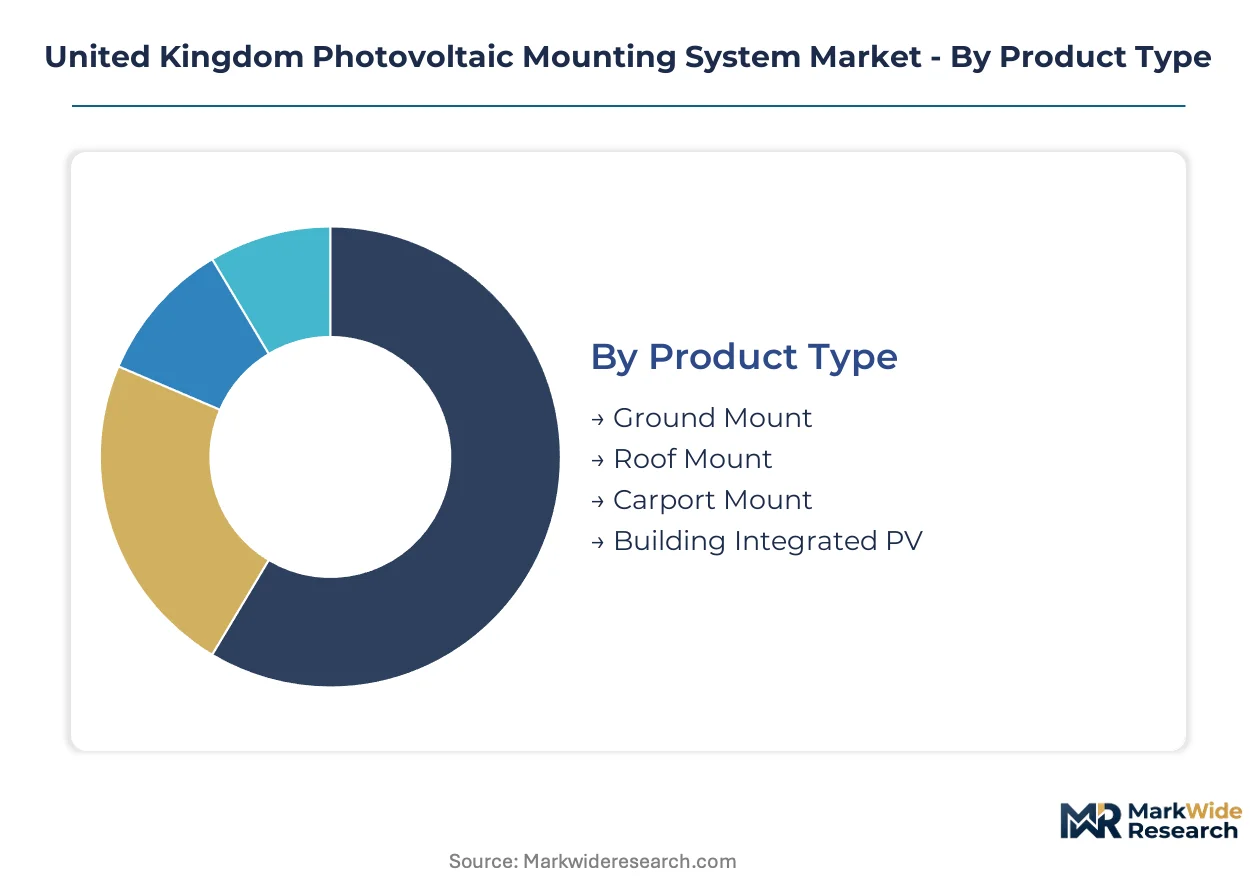
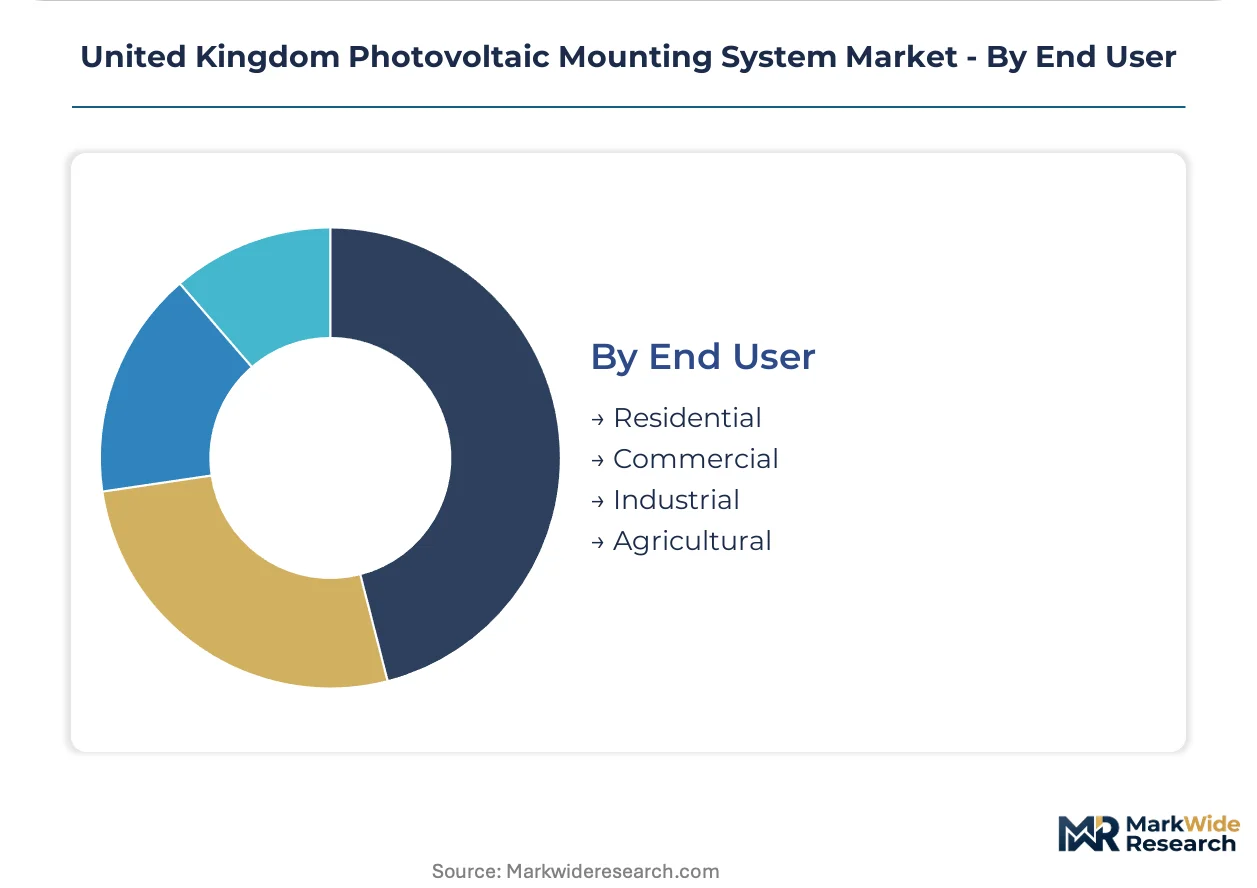
Mounting system procurement in the United Kingdom fragments across structural form factors, material specifications, installation mechanics, and end-use applications. Each dimension carries distinct certification requirements under MCS 012 and Building Regulations Part L, shaping supplier qualification pathways and installer specialization.
Product Type:
Buyer differentiation hinges on site constraints and project scale rather than module technology preferences.
- Ground Mount:Steel-framed post-driven arrays dominate utility-scale procurement across Norfolk and Cambridgeshire solar corridors. East Anglia's flat agricultural terrain and available grid connection capacity concentrate demand for tracking-equipped configurations that optimize bifacial energy capture.
- Roof Mount:Aluminum rail-and-bracket kits penetrate Britain's aging pitched-roof housing stock through retrofit channels. MCS certification requirements filter supplier eligibility for feed-in tariff successor schemes, embedding product standard compliance into installer procurement decisions.
- Carport Mount:Dual-purpose structures serving vehicle shelter and generation functions see concentrated deployment across commercial retail and logistics estates.
- Building Integrated PV:Structural glazing and facade-embedded systems remain specification-driven in new-build commercial developments.
Roof Mount leads volumes today; Ground Mount is gaining share fastest.
Material:
Cost tier and weight sensitivity split procurement between extruded aluminum and galvanized steel sections.
- Aluminum:Lightweight extrusions dominate pitched-roof applications where structural load limits constrain hardware selection. London and Birmingham commercial flat-roof ballasted systems favor aluminum rail geometries that minimize roof penetration.
- Steel:Galvanized post sections retain cost advantage in ground-mount arrays where transport logistics from continental European mills create procurement friction. Norfolk utility developers specify steel-framed tracking structures for wind-load resilience.
- Plastic:Polymer-based mounting components serve niche residential applications with corrosion resistance requirements.
- Composite:Fiber-reinforced materials penetrate specialized architectural integration projects demanding non-conductive structural properties.
Aluminum dominates residential and commercial specifications; Steel anchors utility-scale procurement.
Installation Type:
Margin structure and labor specialization requirements differentiate fixed, adjustable, and tracking configurations.
- Fixed Tilt:Static angle configurations minimize mechanical complexity and commissioning labor for standardized rooftop deployments across England's residential retrofit market.
- Adjustable Tilt:Seasonally variable angle mechanisms see seasonal adoption in agricultural ground-mount installations where manual adjustment labor is available.
- Tracking System:Single-axis and dual-axis motorized arrays electrify utility-scale economics through continuous solar azimuth orientation. Cambridgeshire developers specify these for bifacial module optimization where energy yield per hectare determines site viability.
- Hybrid:Combined fixed-tracking configurations address transitional project phases and phased capacity expansion requirements.
Fixed Tilt commands current installed base; Tracking System is climbing the fastest.
End User:
Project financing mechanisms and regulatory compliance pathways segment demand across customer categories.
- Residential:Retrofit penetration of Britain's housing stock drives rail-and-bracket kit volumes through MCS-certified installer networks. Future Homes Standard mandates will embed mounting infrastructure into new-build specifications from 2025 onward.
- Commercial:Flat-roof ballasted systems dominate London and Birmingham industrial estates where structural load constraints favor distributed generation. Aggregator-led procurement consortia now negotiate direct manufacturer relationships, bypassing distribution tiers.
- Industrial:Large-scale rooftop and ground-mount installations align with corporate renewable energy procurement targets and grid connection queue positioning.
- Agricultural:Ground-mount arrays on marginal farmland concentrate in East Anglia where agricultural land classification and grid capacity create viable project economics.
Residential leads current volumes; Commercial is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's solar corridor crystallized during the 2010s feed-in tariff era, concentrating installer networks and distribution infrastructure across East Anglia and the South West before utility-scale procurement accelerated in the 2020s.
East Anglia
Norfolk and Cambridgeshire host England's densest cluster of ground-mount procurement. The Contracts for Difference scheme de-risks capital deployment for utility developers. Flat agricultural terrain and available grid connection capacity concentrate tracking-equipped bifacial arrays across this corridor.
South West England
Bristol and Exeter suburban developments pilot solar-ready truss specifications ahead of Future Homes Standard enforcement. Building Regulations Part L mandates renewable-ready construction from 2025. Retrofit penetration of aging housing stock drives rail-and-bracket kit volumes through MCS-certified networks.
Midlands
Birmingham industrial estates represent underdeployed commercial flat-roof capacity where ballasted systems address structural load constraints. Aggregator-led procurement consortia negotiate direct manufacturer relationships for retail and logistics portfolios. The Microgeneration Certification Scheme filters supplier eligibility for distributed generation projects.
London
Commercial rooftop specifications concentrate in logistics and retail estates where standardized flat-roof systems reduce engineering redundancy. MCS 012 product standard governs mounting kit eligibility for feed-in tariff successors. The capital's constrained grid connection queue extends project viability timelines beyond hardware procurement cycles.
Scotland
Wind-load resilience requirements shape structural hardware specifications for ground-mount arrays on marginal agricultural land. The Scottish Government's renewable energy targets accelerate utility-scale pipeline development. Grid connection capacity constraints in the Highlands filter project economics toward tracking-optimized energy yield per hectare.
United Kingdom Photovoltaic Mounting System Market Competitive Landscape
The competitive structure tilts toward domestic fabricators with MCS certification and supply security advantages. Specialist mounting suppliers fragment across rail-and-bracket, ballasted, and tracking configurations rather than consolidating around full-line portfolios. Three archetypes dominate: domestic manufacturers anchoring installer relationships, European specialists leveraging flat-roof expertise, and global tracker vendors capturing utility-scale procurement. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for Contracts for Difference auction cycles.
Among UK-based fabricators, Solarport Systems Ltd. exemplifies the domestic manufacturing archetype through its supply security positioning for installer networks. Renusol Europe GmbH and Esdec UK occupy positions within the specialist tier, with the former representing European flat-roof ballasted expertise and the latter anchoring integrated cable management capabilities that reduce balance-of-system labor costs. These three companies illustrate how geographic origin and functional specialization stratify competitive positioning without requiring full-line portfolio breadth.
| Leading Market Players |
|---|
| Solarport Systems Ltd. |
| Renusol Europe GmbH |
| Esdec UK |
| Corab UK |
| Bauder Ltd. |
| Van der Valk Solar Systems |
| K2 Systems GmbH |
| Schletter Group |
| NEXTracker Inc. |
| Others |
Value Network & Pricing Analysis
Aggregator-led procurement consortia among London and South West retail estate operators are consolidating purchase volumes and mandating MCS 012 certification as table stakes, forcing domestic fabricators to absorb compliance costs while European competitors face logistics penalties that compress their pricing flexibility.
Pricing Analysis
Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels dominates the UK market. Premium tiers capture installer loyalty through integrated cable management and extended structural warranties, while economy tiers serve price-sensitive residential retrofit channels where MCS 012 eligibility filters supplier access. Price erosion runs through the economy tier as Chinese-imported rail kits without UK-specific wind-load testing flood distributor channels. Commercial aggregators exhibit lowest price sensitivity due to lifecycle cost optimization, whereas independent residential installers gravitate toward lowest first-cost options.
Supply Chain Analysis
Aluminum extrusion supply rests on German and Dutch rolling mills, with galvanized steel posts drawing from Spanish and Polish fabrication hubs. Stainless steel fasteners hinge on Italian specialty fastener producers, while drive motors for tracking systems source from German and Danish precision engineering clusters. Single-source vulnerability concentrates in high-grade aluminum alloy formulations where domestic re-melting capacity remains underdeveloped. Distribution runs through specialist renewable energy distributors and direct manufacturer relationships with national installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK photovoltaic mounting system market functions as a stable compounder, with regulatory embedding of renewable-ready construction through Building Regulations Part L and the Future Homes Standard providing predictable demand visibility across residential new-build and retrofit channels.
For Market Incumbents: To counter aluminum price volatility eroding margin predictability, deepen backward integration into domestic aluminum re-melting and extrusion capacity. Anchor installer relationships through exclusive MCS 012 certification support programs that lengthen switching costs for distributor networks.
For New Entrants and Emerging Players: Capture the underdeployed commercial flat-roof segment across Birmingham and Manchester industrial estates where ballasted system expertise from continental Europe transfers readily. Enter through direct procurement relationships with logistics estate aggregators bypassing traditional distribution tiers.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic fabricators possessing MCS certification infrastructure and East Anglia logistics positioning for utility-scale tracker deployment. Five-to-ten-year viability hinges on Contracts for Difference auction cycle participation. Monitor National Electricity System Operator grid connection queue reforms as the critical inflection signal for capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| MCS 012 Certification Investment | Unlocks eligibility for feed-in tariff successor schemes and installer procurement decisions. |
| Domestic Aluminum Extrusion Capacity | Reduces exposure to continental European commodity volatility and transport cost penalties. |
| Tracker System Drive Motor Integration | Captures utility-scale bifacial optimization demand across Norfolk and Cambridgeshire solar corridors. |
| Direct Aggregator Procurement Relationships | Bypasses distribution margin compression in London and South West commercial estate portfolios. |
| Solar-Ready Truss Specification Partnerships | Embeds mounting infrastructure into Future Homes Standard compliance for housebuilder channels. |
Research Methodology
Coverage spans England's solar corridor regions, Scotland's Highlands utility pipeline, and Wales's emerging commercial rooftop segment, with primary inputs from each. The research combines structured interviews with EPC contractors, utility-scale project developers, MCS-certified installers, and housebuilder procurement directors with secondary validation through Ofgem CfD auction disclosures, BEIS building regulations consultations, and MCS certification database extracts. Bottom-up project pipeline tracking triangulates against top-down manufacturer shipment data.
Granularity-level modeling disaggregates volume and value outputs by product type, material specification, installation mechanics, and end-user category across the projection horizon. CAGRs derive from segment-specific deployment trajectories informed by grid connection queue positioning, Contracts for Difference strike price evolution, and housing starts under Future Homes Standard compliance pathways.
Aluminum commodity volatility, National Electricity System Operator queue reform timing, and local planning authority solar guideline variability are the dominant revision risks to modeled outputs. Forecasts embed assumptions around MCS 012 certification timeline stability and installer workforce expansion rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Fixed Tilt Solar PV Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
Rooftop Solar EPC Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Slovakia Renewable Energy Market