
 North America Battery Management System Market | 2026-2036
North America Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Battery Management System Market Analytics
The US Inflation Reduction Act is realigning domestic sourcing requirements for critical battery components, compelling automakers and energy storage developers to qualify North American-built management systems for tax credits. Texas Instruments Incorporated leverages its analog semiconductor heritage to dominate voltage reference and cell-monitoring IC design. Sensata Technologies Inc. specializes in high-voltage contactors and sensing assemblies that sustain thermal runaway protection architectures. Infineon Technologies AG extends its SiC and gate-driver portfolio to anchor power-stage integration within management modules.
A battery management system comprises embedded electronics, sensing arrays, and control firmware that monitor cell voltage, current, and temperature to enforce safe operating windows and optimize cycle life across lithium-ion packs. Cell monitoring ICs achieve measurement precision below one millivolt per cell while communicating through isolated daisy-chain or CAN bus architectures to central processing units. Thermal management segments command premium positioning as liquid-cooled EV platforms and grid-scale installations multiply energy density and safety requirements. State of charge estimation algorithms represent the fastest-evolving competency, with automotive and grid storage applications demanding predictive accuracy under dynamic load profiles to minimize range anxiety and dispatch risk.
The US Environmental Protection Agency tailpipe rules and California Air Resources Board zero-emission vehicle mandates are tightening certification requirements for battery system safety and traceability, directly conditioning market access for management platform vendors. NHTSA defect investigation protocols and UL 1973 stationary storage standards further constrain product design choices, favoring suppliers with pre-certified architectures and documented failure-mode libraries. Stakeholders must monitor how EPA and CARB coordinate next-generation battery passport requirements with European Battery Regulation precedents to anticipate compliance cost trajectories and qualification timeline risks.
Market Dynamics
The US Inflation Reduction Act's domestic content bonus credit is forcing automakers to requalify their entire battery management supply chains, compressing vendor selection timelines and elevating North American-certified platform architects above imported alternatives.
Growth Catalysts
- IRA Domestic Content Credits:The Inflation Reduction Act's critical mineral and battery component sourcing requirements are compelling EV manufacturers to source management systems from qualified North American suppliers, redirecting procurement volumes toward domestic platform vendors.
- California ZEV Mandates:The California Air Resources Board's escalating zero-emission vehicle sales requirements are expanding the addressable fleet for integrated battery management platforms across light-duty, medium-duty, and heavy-duty vehicle categories.
- Silicon Carbide Power Integration:SiC-based gate drivers and power stages are enabling higher-voltage pack architectures that demand more sophisticated cell balancing and thermal monitoring firmware, expanding the functional scope of management modules.
Market Restraints
- Cell Monitoring IC Supply Concentration:Precision analog semiconductor fabrication for sub-millivolt measurement ICs concentrates among a limited set of foundry partners, creating vulnerability to capacity allocation decisions.
- Lithium Price Volatility:Cell chemistry cost fluctuations compress pack-level budgets and constrain the premium available for advanced management electronics in price-sensitive energy storage deployments.
- Functional Safety Certification Burden:ISO 26262 ASIL-D qualification for automotive applications demands extensive fault-mode documentation and testing cycles that extend product development timelines.
Strategic Opportunities
- Second-Life Stationary Storage:Retired EV packs entering grid-scale and commercial behind-the-meter applications require refurbished or retrofitted management systems calibrated for degraded cell populations.
- Texas Grid-Scale Deployments:ERCOT market volatility and interconnection queue pressures are accelerating utility-scale battery procurement in Texas, creating concentrated demand for containerized management platforms.
- Wireless Cell Monitoring Convergence:The intersection of low-power RF transceivers and isolated power architectures is eliminating wiring harness complexity in large-format packs, opening retrofit and redesign channels.
Industry Challenges
- Battery Passport Traceability Requirements:The US EPA and CARB are coordinating with EU Battery Regulation precedents to mandate cell-level lifecycle documentation, forcing management system vendors to embed granular origin tracking and carbon accounting into firmware architectures.
- Embedded Software Talent Scarcity:State-of-charge algorithm development and predictive degradation modeling require specialized electrochemical and control systems expertise that outpaces North American graduate program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Battery Management System Market |
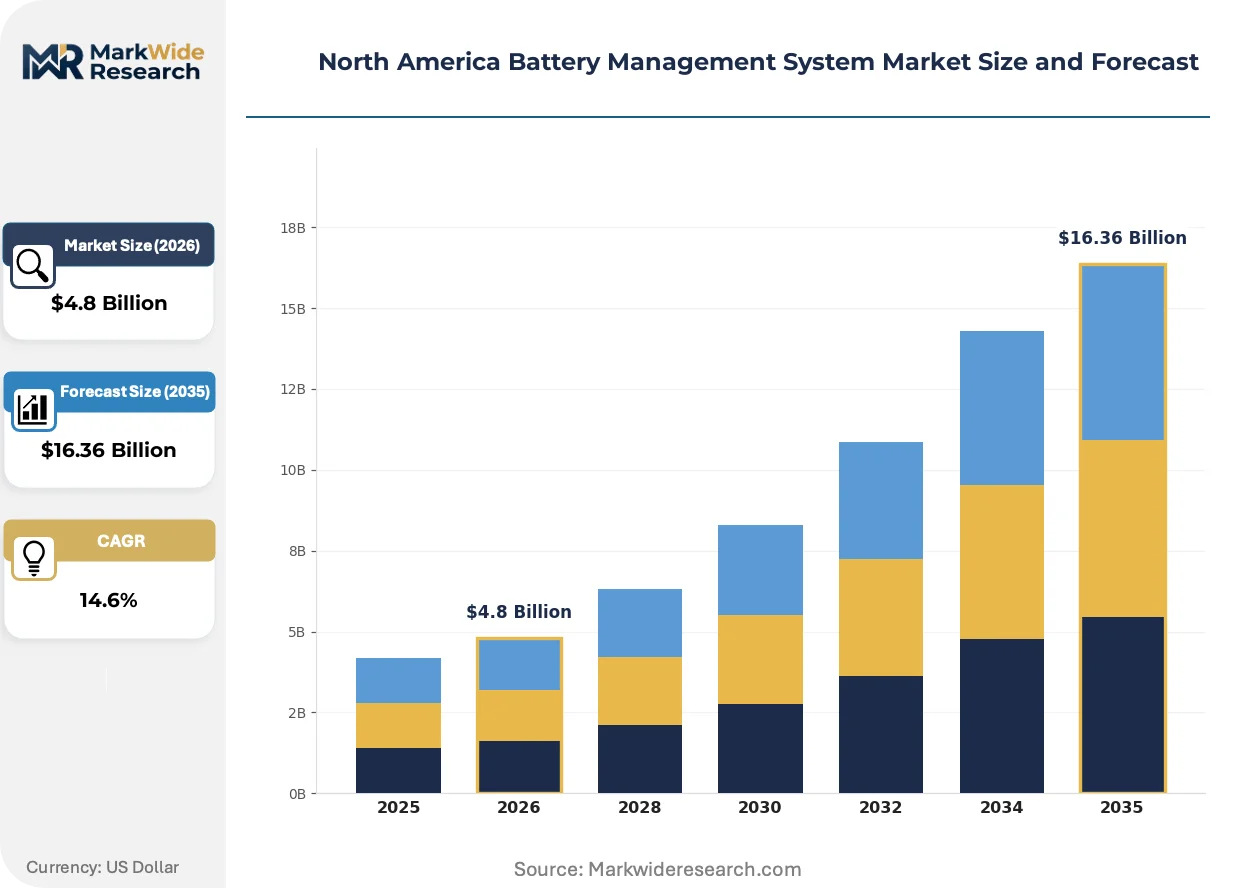
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Monitoring, Thermal Management, State of Charge, Diagnostic Testing End User: Electric Vehicles, Renewable Energy, Consumer Electronics, Industrial Equipment Technology: Voltage Measurement, Current Sensor, Communication Protocols, Energy Harvesting Application: Grid Storage, Automotive, Portable Devices, Aerospace |
| Companies Covered | Texas Instruments Incorporated, Sensata Technologies Inc., Eberspaecher Vecture Inc., BorgWarner Inc., Nuvation Energy, LG Energy Solution, Analog Devices Inc., NXP Semiconductors NV, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Battery Management System Market Evolving Landscape
Distributed intelligence architectures are displacing centralized battery management topologies across high-voltage EV platforms and modular grid storage systems, fragmenting computational load and enabling faster fault response.
Wireless battery management systems eliminate daisy-chain wiring harnesses between cell monitoring units and central controllers, reducing pack assembly labor and failure modes. Tier 1 suppliers and EV startups are piloting Bluetooth Low Energy and proprietary RF protocols in premium vehicle programs. This topology is decentralizing fault containment and enabling cell-level replacement in service environments.
The US EPA tailpipe rules and NHTSA defect investigation protocols are tightening documentation requirements for thermal runaway propagation testing and failure-mode libraries. Battery management vendors must now submit pre-certified architectures with validated safety mechanisms to secure automotive platform design wins. Grid-scale stationary storage suppliers face parallel pressure from UL 1973 revisions affecting software-controlled contactor sequencing and arc fault detection.
Fleet operators and independent service providers are unbundling battery management software updates from hardware replacement cycles, subscribing to over-the-air calibration and algorithm refinement services. This decoupling is compressing traditional equipment procurement relationships and elevating firmware-as-a-service revenue models. California and Texas utility fleets are piloting this arrangement most aggressively, driven by dispatch optimization requirements and warranty performance guarantees.
North America Battery Management System Market Segmentation
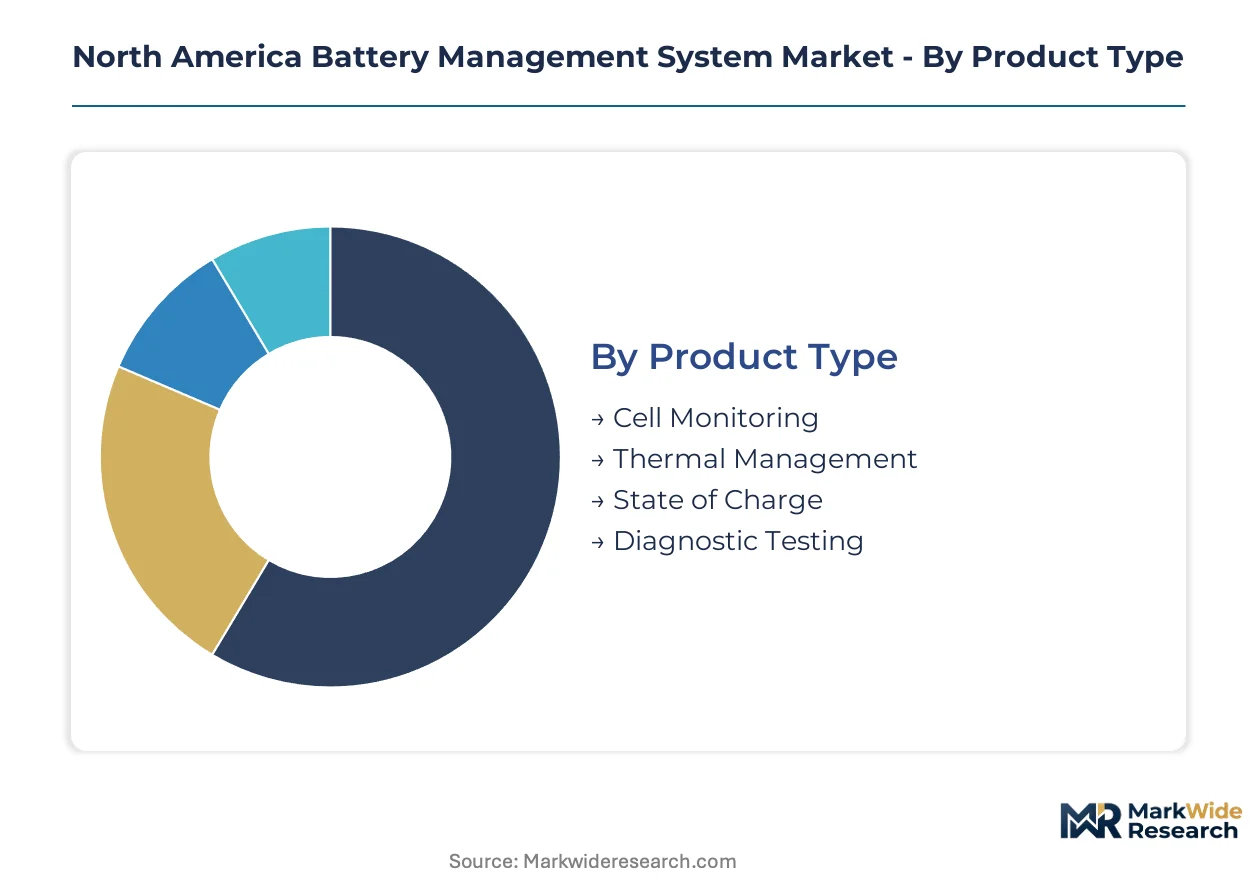
Battery management systems fragment across four critical dimensions that shape procurement priorities and technical specifications. Product type determines hardware architecture investment, while end-user concentration in California and Texas drives regional vendor qualification strategies.
Product Type:
Buyer decisions hinge on functional safety requirements and pack complexity, with thermal runaway protection commanding premium positioning.
- Cell Monitoring:Sub-millivolt precision analog ICs track individual cell voltage through isolated daisy-chain architectures. Demand concentrates in Michigan EV assembly plants where IRA domestic content rules disqualify imported monitoring chips.
- Thermal Management:Liquid-cooled platforms deploy temperature sensing arrays and active cooling control loops. Texas grid-scale installations under ERCOT volatility pressures are expanding procurement of containerized thermal management modules for utility-scale batteries.
- State of Charge:Predictive algorithms estimate remaining capacity under dynamic load profiles.
- Diagnostic Testing:Embedded firmware executes fault-mode detection and propagation analysis.
Cell Monitoring leads on scale; Thermal Management leads on momentum.
End User:
Volume concentration and certification burden vary sharply across customer categories, with automotive ASIL-D requirements filtering supplier pools.
- Electric Vehicles:Integrated platforms must satisfy NHTSA defect investigation protocols and CARB zero-emission mandates. California light-duty and Texas heavy-duty fleets are expanding procurement of qualified management systems to secure IRA tax credits.
- Renewable Energy:Grid-tied storage demands UL 1973-compliant contactor sequencing and arc fault detection. ERCOT interconnection queue pressures in Texas are accelerating utility-scale battery procurement with embedded management platforms.
- Consumer Electronics:Cost-optimized modules prioritize compact form factors over functional safety depth.
- Industrial Equipment:Forklift and material handling applications require ruggedized enclosures and extended temperature ranges.
Electric Vehicles dominates revenue contribution; Renewable Energy climbs the fastest.
Technology:
Component selection determines measurement accuracy, communication latency, and standby power consumption across pack architectures.
- Voltage Measurement:Precision reference circuits achieve measurement stability below one millivolt per cell. Silicon Carbide power integration in high-voltage EV platforms is expanding demand for isolated voltage sensing with extended common-mode range.
- Current Sensor:Hall-effect and shunt-based architectures capture charge and discharge currents. Michigan battery pack assembly lines are qualifying domestic current sensor suppliers to satisfy IRA critical mineral tracing requirements.
- Communication Protocols:CAN bus and isolated SPI interfaces link distributed monitoring units to central controllers.
- Energy Harvesting:Photovoltaic and thermoelectric sources power wireless cell monitoring transceivers.
Voltage Measurement anchors installed base; Current Sensor gains share fastest.
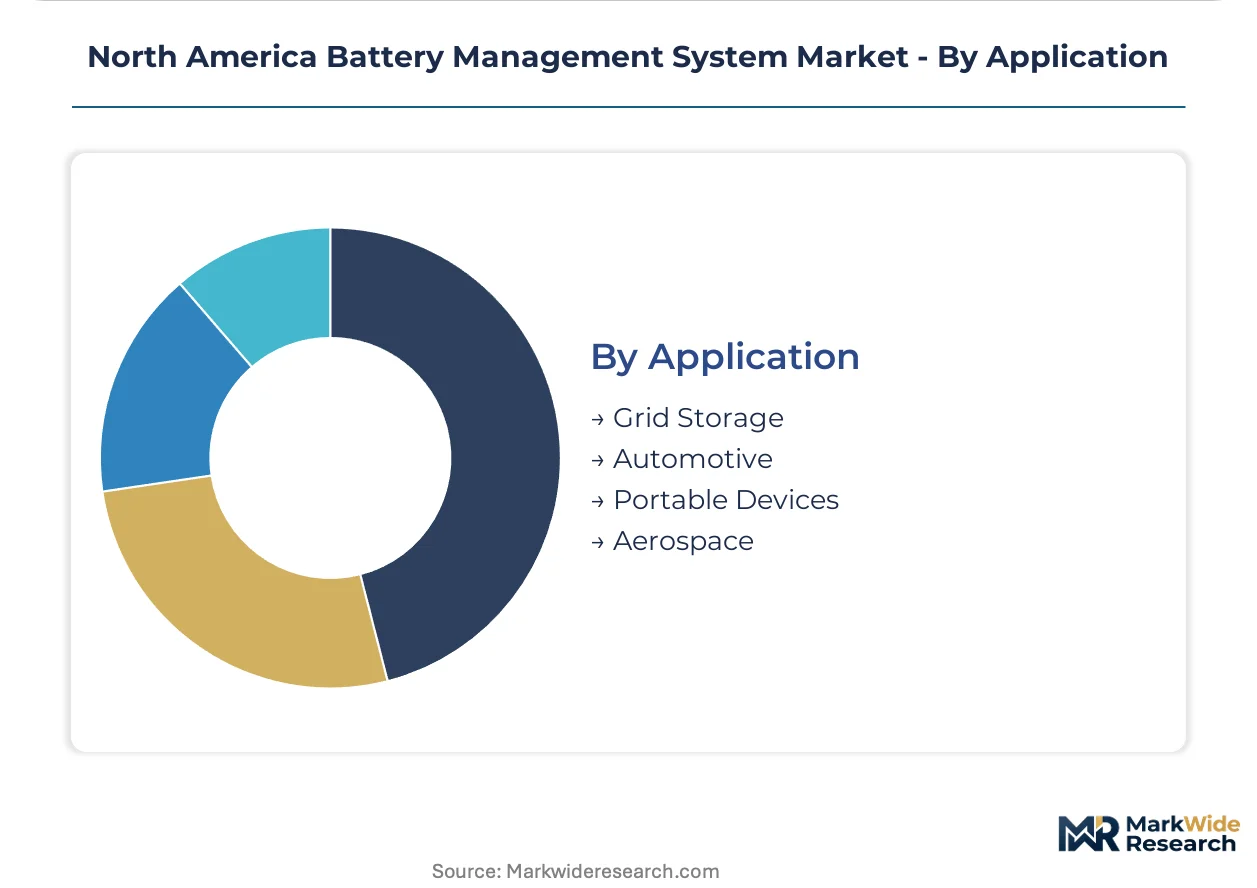
Application:
Deployment environment dictates safety certification tier, thermal design margin, and firmware complexity requirements.
- Grid Storage:Containerized platforms integrate contactor control, fire suppression interfacing, and utility dispatch signaling. Texas ERCOT market participation rules are conditioning procurement on sub-second frequency response capabilities.
- Automotive:ASIL-D functional safety mandates govern fault containment and diagnostic coverage. California CARB certification requirements are forcing management system vendors to pre-submit thermal runaway propagation test documentation.
- Portable Devices:Compact single-cell or small-series packs prioritize Coulomb counting over distributed sensing.
- Aerospace:DO-178C software assurance and extended temperature qualification constrain supplier pools.
Automotive commands premium pricing; Grid Storage shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded software engineers and power electronics specialists cluster in Detroit-Warren-Dearborn, Austin-Round Rock, and Toronto-Waterloo corridors, anchoring North American battery management system development capacity.
United States
Michigan EV assembly plants and Texas grid-scale storage deployments drive procurement of integrated management platforms. The Inflation Reduction Act's domestic content bonus credit compels automakers to requalify supply chains toward North American-certified vendors. Detroit-area battery pack facilities are expanding cell monitoring IC qualification programs to satisfy IRA critical mineral tracing requirements.
Canada
Ontario's automotive manufacturing heritage and Quebec's battery materials processing infrastructure create concentrated demand for thermal management modules. Health Canada and Environment and Climate Change Canada coordinate battery safety standards with EPA precedents. Toronto-Waterloo corridor startups are piloting wireless cell monitoring architectures for second-life stationary storage applications.
Mexico
Nuevo León and Baja California manufacturing clusters attract tier-1 supplier investment serving cross-border EV assembly. Mexico's Secretariat of Economy implements automotive sector incentives aligned with USMCA regional content rules. Monterrey-area electronics manufacturing services are qualifying for North American battery management system sub-assembly contracts.
North America Battery Management System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the battery management system value chain, creating a tiered competitive structure. Analog semiconductor foundries with captive fabrication capacity anchor the component layer, while fabless IC designers and system integrators occupy modular assembly tiers. Strategic archetypes include precision measurement specialists, power-stage integrators, and platform software architects. Capacity expansion into domestic qualification facilities and strategic partnerships for SiC power integration represent dominant competitive moves.
Among US-based analog semiconductor designers, Texas Instruments Incorporated and Analog Devices Inc. occupy positions emphasizing precision voltage reference and cell-monitoring heritage. Sensata Technologies Inc. exemplifies the sensing and high-voltage protection archetype through its contactor and thermal runaway assembly specialization. Infineon Technologies AG anchors the European-originated power semiconductor tier extending SiC gate-driver portfolios into management module integration.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Sensata Technologies Inc. |
| Eberspaecher Vecture Inc. |
| BorgWarner Inc. |
| Nuvation Energy |
| LG Energy Solution |
| Analog Devices Inc. |
| NXP Semiconductors NV |
| Infineon Technologies AG |
| Others |
Value Network & Pricing Analysis
Silicon Carbide power-stage integration into high-voltage EV platforms is compressing analog semiconductor margins while concentrating procurement leverage among automakers with IRA domestic content compliance requirements. This technology shift simultaneously elevates firmware development costs and fragments component sourcing across North American qualified foundries.
Pricing Analysis
Three-tier pricing structure across ASIL-D certified, automotive-grade, and industrial-grade tiers separates premium thermal management modules from standard cell monitoring ICs from economy-grade consumer electronics platforms. Price differentiation centers on ISO 26262 certification depth and after-sales firmware update subscriptions. Cost compression in the industrial tier is intensifying because lithium price volatility constrains pack-level electronics budgets. Fleet operators show highest price sensitivity; aerospace and medical device OEMs show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for precision analog semiconductor fabrication, while China and Japan anchor lithium-ion cell production. Raw material dependencies include lithium carbonate, nickel sulfate, and high-purity silicon wafers. Tariff exposure on Chinese-sourced power electronics creates qualification bottlenecks for North American pack assemblers. Distribution runs through Tier 1 automotive suppliers and direct utility procurement channels for grid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in battery management systems rests on firmware-as-a-service revenue models displacing hardware replacement cycles, alongside SiC power integration commanding premium positioning in 800V EV architectures.
For Market Incumbents: Deepen captive foundry partnerships in Texas and Michigan to secure IRA domestic content qualification timelines against emerging fabless competitors. Expand ASIL-D pre-certified architecture libraries to compress automotive platform design-win cycles. Lock in exclusive thermal runaway propagation test documentation with NHTSA to raise certification barriers for challengers.
For New Entrants and Emerging Players: Capture second-life stationary storage refurbishment demand in Texas ERCOT markets and Ontario grid pilot programs where incumbent firmware architectures require costly recalibration for degraded cell populations. Lead with wireless cell monitoring topologies to bypass daisy-chain wiring harness complexity that incumbents cannot retrofit without pack redesign.
For Investors and Strategic Acquirers: Valuations sit cheapest among fabless IC designers with automotive-qualified measurement IP but lacking integrated power-stage portfolios. Five-to-ten year viability favors platform software architects with embedded electrochemical modeling expertise over pure hardware vendors. Watch EPA-CARB battery passport rule coordination with EU precedents as the inflection signal for compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Qualification | IRA tax credit eligibility hinges on North American cell-monitoring IC fabrication capacity. |
| Wireless BMS Topology Launch | Bluetooth Low Energy protocols eliminate wiring harness labor in large-format pack assembly. |
| Firmware-as-a-Service Platform | Over-the-air algorithm updates decouple revenue from hardware replacement cycles. |
| SiC Gate-Driver Integration | 800V EV architectures demand isolated power-stage modules with extended common-mode range. |
| Battery Passport Compliance Investment | EPA-CARB traceability mandates require embedded carbon accounting firmware architectures. |
Research Methodology
Bottom-up EV platform and grid-storage deployment modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core. Primary interviews with Tier 1 supplier procurement directors, OEM battery platform engineers, utility storage planners, and analog IC design directors combined with secondary validation against EPA regulatory filings, NHTSA defect investigation databases, ERCOT interconnection queues, and SEC 10-K supply chain disclosures. Triangulation across these sources calibrated segment-level penetration assumptions.
Input-output matrices link vehicle production forecasts, battery pack size distributions, and management system content-per-pack ratios to generate volume trajectories across the projection horizon. Segmentation dimensions span product type, end-user category, technology protocol, and application environment with specific weighting for IRA domestic content compliance status. CAGRs derive from fitted adoption curves benchmarked against historical EV penetration patterns and stationary storage deployment velocities in Texas and California.
IRA rulemaking revisions, lithium price volatility spikes, and SiC foundry yield shortfalls are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about regulatory coordination timelines and technology cost-down curves that may shift. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
EV Battery Management Market
Battery Management System
US Energy Storage Market
Battery Management System
Battery Management System (BMS) Market
Battery Management System
Energy Storage Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Renewable Battery Storage Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
Energy Storage Technologies Market