
 United States Portable Generator Market | 2026-2036
United States Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
United States Portable Generator Market Intelligence
CARB certification is redrawing competitive boundaries in the United States portable generator sector, forcing manufacturers to redesign engine architectures or exit California and the dozen states that follow its emissions protocols. Generac Holdings Inc. anchors the residential standby segment through captive dealer networks and vertically integrated manufacturing in Wisconsin. Honda Motor Co. Ltd. differentiates through inverter technology leadership and whisper-quiet operational profiles that command premium positioning in recreational applications. Champion Power Equipment competes aggressively on price-accessible dual-fuel platforms, sustaining volume traction through big-box retail partnerships.
A portable generator is a self-contained internal combustion or battery-electric power unit, typically rated between 800 watts and 17,500 watts, designed to deliver alternating current electricity independent of grid infrastructure for temporary or emergency applications. Inverter generators employ microprocessor-controlled variable engine speed to produce clean sine-wave output suitable for sensitive electronics, while conventional open-frame units prioritize raw wattage-per-dollar for construction and agricultural use. The residential application segment leads absolute unit shipments, though emergency power configurations for healthcare and data center backup command the highest margin pools. Dual fuel capability is the fastest-growing product configuration, as propane storage resilience appeals to disaster-preparedness buyers in Gulf Coast and Midwestern markets.
EPA Phase 3 small spark-ignition engine standards and OSHA construction-site noise exposure limits govern product legality and jobsite deployment across the United States, while state-level CARB regulations create a bifurcated compliance landscape that fragments inventory requirements. The Department of Energy has signaled tightened standby power consumption rules for battery-based units, pressuring solar generator designers to improve charge-controller efficiency. Stakeholders must monitor FERC grid reliability pronouncements and state-level resilience incentive programs, as subsidized battery-solar hybrid installations could displace conventional generator demand in suburban markets.
Market Dynamics
EPA Phase 3 emissions standards and CARB protocols are fragmenting the United States portable generator landscape, forcing manufacturers to maintain dual engine architectures and bifurcated inventory pools.
Growth Catalysts
- Grid instability in Texas and Florida:Severe weather events and aging transmission infrastructure drive sustained procurement of emergency power equipment across coastal counties.
- Dual-fuel propane compatibility:Storage resilience and extended shelf life appeal to disaster-preparedness buyers in Gulf Coast and Midwestern markets.
- FERC resilience incentive programs:State-level subsidized battery-solar hybrid installations create adjacent demand for conventional backup units in suburban markets.
Market Restraints
- Steel and copper input volatility:Raw material price swings compress margin visibility for open-frame conventional unit manufacturers.
- CARB compliance fragmentation:California and twelve follower states require separate engine certifications, doubling SKU complexity for national distributors.
- Battery-solar substitution threat:Lithium-ion storage with integrated inverters captures preparedness budgets in hurricane-prone residential zones.
Strategic Opportunities
- Healthcare facility microgrids:Critical care centers in tornado alley states seek certified backup power with sub-10-second transfer switches.
- Remote construction electrification:OSHA-compliant inverter units penetrate pipeline and transmission projects in North Dakota shale fields.
- Telecom tower resilience mandates:FCC backup power requirements for rural 5G infrastructure create pull-through for mid-wattage propane units.
Industry Challenges
- Small engine technician scarcity:EPA-certified service networks struggle to recruit carburetor-to-fuel-injection transition specialists across the Southeast.
- Dual-certification timeline compression:Simultaneous EPA Phase 3 and CARB Tier III approvals delay new product launches by 8-14 months.
- Legacy inventory stranding risk:Pre-Phase 3 engine stockpiles face accelerated obsolescence as state adoption deadlines tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Portable Generator Market |
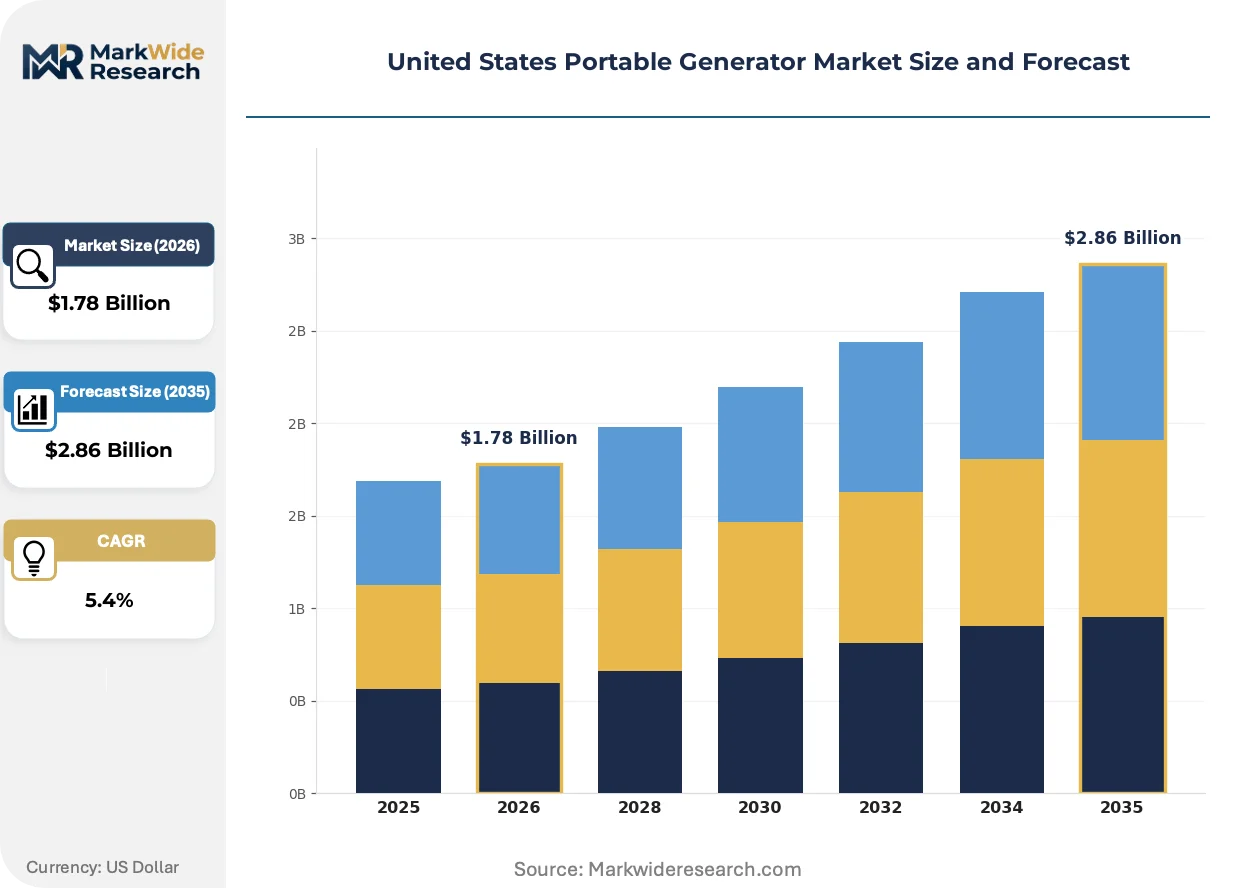
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverter, Conventional, Dual Fuel, Solar Application: Residential, Recreational, Commercial, Emergency Power Fuel Type: Gasoline, Propane, Diesel, Electric Size: Compact, Medium, Heavy-Duty, Ultra-Portable |
| Companies Covered | Generac Holdings Inc., Honda Motor Co. Ltd., Briggs & Stratton Corporation, Champion Power Equipment, Yamaha Motor Co. Ltd., Kohler Co., Caterpillar Inc., Cummins Inc., Westinghouse Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Portable Generator Market Strategic Shifts & Innovations
Clean sine-wave output standards and emissions compliance are compressing the viable product architecture set, while procurement channels fragment between dealer networks and direct-to-consumer platforms.
Inverter generators with microprocessor-controlled variable engine speed are displacing conventional open-frame units in residential and light commercial segments. Suburban buyers with sensitive electronics prioritize harmonic distortion below 3 percent. This displacement compresses the addressable market for contractor-grade conventional units to agricultural and heavy construction verticals.
EPA Phase 3 small spark-ignition engine standards mandate 90 percent emissions reductions for engines under 25 horsepower. Manufacturers must redesign combustion chambers and fuel systems or exit the United States market entirely. Wisconsin and South Carolina production facilities face the steepest retooling capex to maintain federal legality.
Preparedness buyers increasingly complete entire purchase journeys through manufacturer-direct websites and warehouse club channels, bypassing traditional outdoor power equipment dealers. Big-box retailers capture volume in dual-fuel and recreational segments. This channel rotation is most pronounced in Florida and Texas, where seasonal demand spikes overwhelm dealer service capacity.
United States Portable Generator Market Segmentation
Portable generator demand fragments across power technologies, end-use contexts, and fuel architectures. Each segment faces distinct substitution pressures from battery-solar hybrids and stationary standby systems. Understanding these fault lines clarifies where conventional generator manufacturers must defend share versus cede ground.
Product Type:
Dual fuel and solar configurations face the most acute substitution pressure from lithium-ion storage systems, while inverter and conventional platforms compete primarily on harmonic distortion tolerance and price-per-watt economics.
- Inverter:Microprocessor-controlled variable engine speed delivers sine-wave output below 3 percent total harmonic distortion. Demand concentrates in Texas and Florida suburban markets where sensitive electronics protection commands premium positioning against grid instability events.
- Dual Fuel:Gasoline-propane flexibility extends runtime resilience during extended outages. Gulf Coast preparedness buyers prioritize propane shelf stability for hurricane-season stockpiling, driving fastest category expansion.
- Conventional:Open-frame architecture maximizes raw wattage-per-dollar for agricultural and heavy construction verticals in the Midwest.
- Solar:Lithium-ion battery packs with integrated inverters capture disaster-preparedness budgets in California CARB jurisdictions where emissions compliance costs disadvantage combustion units.
Conventional retains volume leadership; dual fuel holds the steepest expansion curve.
Application:
Cost tier stratification separates residential mass-market procurement from premium-priced emergency power configurations serving critical infrastructure.
- Residential:Backup power for single-family homes dominates absolute unit shipments across Florida, Texas, and California. EPA Phase 3 compliance costs and CARB certification requirements bifurcate product availability between coastal and interior states.
- Emergency Power:Healthcare facilities and data centers demand sub-10-second transfer switches with certified redundancy. Tornado alley states in Oklahoma and Kansas drive specification intensity for hospital microgrid installations.
- Recreational:Camping and tailgating applications in the Mountain West prioritize decibel minimization and portability over wattage maximization.
- Commercial:Construction sites in North Dakota shale fields require OSHA-compliant noise exposure limits and inverter-grade power quality for sensitive tooling.
Residential commands absolute shipment volume; emergency power captures the highest margin pools.
Fuel Type:
Propane storage resilience is accelerating share capture from gasoline in disaster-preparedness segments, while diesel maintains defensive positioning in commercial backup.
- Propane:Indefinite shelf stability and bulk storage compatibility appeal to Gulf Coast buyers preparing for multi-week hurricane outages. Midwestern agricultural operations adopt propane for seasonal irrigation pump backup.
- Gasoline:Ubiquitous retail availability and lowest first-cost position sustain mass-market penetration, though ethanol-blend degradation limits long-term storage viability.
- Diesel:Compression-ignition efficiency and extended runtime endurance serve remote telecom tower installations and pipeline construction camps.
- Electric:Battery-solar hybrids with integrated charge controllers displace combustion units in California suburban markets where FERC resilience incentives subsidize installation costs.
Gasoline maintains volume dominance; propane gains share fastest in preparedness applications.
Size:
Distribution channel concentration varies sharply by size class, with compact units flowing through warehouse clubs and heavy-duty configurations requiring dealer network fulfillment.
- Compact:Sub-2,000-watt packages target recreational users and essential-circuit residential backup. Big-box retail partnerships in Florida and Texas capture seasonal demand spikes that overwhelm independent dealer service capacity.
- Heavy-Duty:10,000-plus-watt open-frame units serve agricultural operations and commercial construction sites. Wisconsin and South Carolina manufacturing facilities face steepest EPA Phase 3 retooling requirements for this displacement class.
- Medium:3,000-8,000-watt range balances portability with circuit-panel connectivity for suburban home backup.
- Ultra-Portable:Hand-carry lithium-ion units below 1,000 watts compete with power station formats in camping and emergency kit applications.
Medium size commands shipment volume; compact segments expand most quickly through direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC resilience incentive programs and state-level disaster preparedness funding are concentrating procurement across coastal and tornado-prone jurisdictions. Texas, Florida, and California anchor absolute demand volume through distinct regulatory and climatic drivers.
Texas
Grid instability from ERCOT capacity shortfalls and winter storm events drives sustained emergency power procurement across Houston and Dallas-Fort Worth metro corridors. The Public Utility Commission of Texas has approved resilience rebate programs for backup power installations. Manufacturing clusters in the Dallas-Plano-Irving corridor assemble EPA Phase 3 compliant units for Gulf Coast distribution.
Florida
Hurricane-season grid outages and salt-air corrosion requirements shape product specifications across Miami-Dade and Tampa Bay markets. The Florida Building Code mandates transfer switch compatibility for new construction in designated evacuation zones. Jacksonville and Orlando distribution centers stock dual-fuel inventory for seasonal demand spikes.
California
CARB Tier III certification requirements and wildfire-driven PSPS events bifurcate product availability between compliant inverter units and excluded conventional models. The California Energy Commission subsidizes battery-solar hybrids through the Self-Generation Incentive Program. Los Angeles and San Francisco Bay Area retailers maintain separate inventory pools for combustion and electric backup systems.
Carolinas and Georgia
Hurricane landfall frequency and rural grid fragility sustain preparedness demand across Charleston, Savannah, and Raleigh-Durham corridors. State emergency management agencies coordinate bulk procurement for community resilience hubs. Manufacturing facilities in South Carolina retool for EPA Phase 3 compliance to serve Southeastern distribution networks.
Midwest Agricultural Belt
Seasonal irrigation pump backup and tornado-driven outage patterns concentrate demand in Iowa, Illinois, and Ohio farming regions. The Department of Agriculture's Rural Energy for America Program partially funds propane generator installations. Distribution partnerships through farm supply cooperatives in Des Moines and Indianapolis capture agricultural procurement cycles.
United States Portable Generator Market Key Industry Players
Listed leaders compete with private specialists across certification tier and channel access. The market exhibits moderate consolidation, with three to four diversified industrial conglomerates commanding premium positioning while mid-scale private manufacturers capture volume through retail partnerships. Strategic archetypes separate EPA-CARB dual-certified specialists, recreational inverter innovators, and construction-grade conventional producers. Capacity expansion in Wisconsin and South Carolina production facilities and exclusive dealer network development represent dominant competitive moves.
Within the dual-certification tier, Generac Holdings Inc. and Briggs & Stratton Corporation exemplify vertically integrated manufacturers with captive Wisconsin production bases. Honda Motor Co. Ltd. occupies a premium positioning anchored to inverter technology leadership. Champion Power Equipment represents price-accessible volume specialists competing through big-box retail penetration.
| Leading Market Players |
|---|
| Generac Holdings Inc. |
| Honda Motor Co. Ltd. |
| Briggs & Stratton Corporation |
| Champion Power Equipment |
| Yamaha Motor Co. Ltd. |
| Kohler Co. |
| Caterpillar Inc. |
| Cummins Inc. |
| Westinghouse Electric Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Wisconsin-based engine manufacturers and steel distributors lock in both raw material access and production cost visibility across the EPA Phase 3 compliance transition. These contracts insulate vertically integrated producers from spot-market copper and aluminum volatility while forcing smaller assemblers into higher-cost spot procurement.
Pricing Analysis
Certification level creates the primary spread between EPA-only and EPA-CARB dual-certified units. Three-tier pricing structure separates premium inverter platforms with sub-3% harmonic distortion from standard open-frame units and economy-grade conventional models. Pricing pressure stems from battery-solar substitution in California suburban markets where FERC resilience incentives subsidize lithium-ion installations. Residential preparedness buyers in Texas and Florida show lowest price sensitivity for dual-fuel configurations, while commercial construction procurement in the Midwest prioritizes wattage-per-dollar economics above certification tier.
Supply Chain Analysis
Inventory lead times for EPA Phase 3 compliant engines extend 8-14 months behind dual-certification approval timelines. Manufacturing concentration rests on Wisconsin and South Carolina production facilities for small spark-ignition engines, with carburetor-to-fuel-injection component sourcing drawn from Mexico and China. Single-source vulnerability concentrates in specialized emission-control subsystem suppliers facing retooling bottlenecks. Distribution runs through captive dealer networks for premium residential standby units and big-box retail partnerships for volume recreational and dual-fuel segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 emissions mandates and CARB Tier III protocols are compressing viable product architectures, creating high-growth disruption for manufacturers that achieve dual-certification ahead of state adoption deadlines.
For Market Incumbents: Fortify Wisconsin and South Carolina manufacturing footprints with captive fuel-injection subsystem production to offset small-engine technician scarcity. Secure exclusive dealer network capacity in Houston and Miami-Dade corridors before seasonal demand spikes overwhelm service infrastructure. Battery-solar hybrid substitution in California represents the primary share erosion threat requiring inverter platform R&D acceleration.
For New Entrants and Emerging Players: Lead with propane-compatible dual-fuel platforms targeting Gulf Coast preparedness buyers where storage resilience commands premium positioning. The Carolinas and Georgia hurricane corridors offer the most penetrable geography given rural grid fragility and community resilience hub procurement. Direct-to-consumer digital channels bypass established dealer relationships in Florida and Texas recreational segments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among EPA-CARB dual-certified specialists with captive aftermarket parts and service networks. Long-term viability across the projection horizon favors manufacturers with backward integration into engine architecture design rather than pure assemblers. Monitor FERC resilience incentive program expansion as the signal indicating accelerated battery-solar substitution velocity in suburban backup markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | EPA-CARB compliance unlocks California and twelve follower state markets for combustion units. |
| Backward Integration into Fuel-Injection Systems | In-house production of Phase 3 compliant subsystems reduces dependency on single-source suppliers. |
| Dealer Network Exclusive Partnerships | Captive service capacity in Texas and Florida captures seasonal demand spikes beyond big-box fulfillment. |
| Inverter Platform R&D Acceleration | Clean sine-wave output below 3% THD defends residential share against battery-solar substitution. |
| Direct-to-Consumer Channel Development | Manufacturer-direct websites bypass traditional outdoor power equipment dealer margins in recreational segments. |
Research Approach
Operator-level perspectives from plant managers at Wisconsin and South Carolina engine facilities, EPA certification specialists, outdoor power equipment dealers in Florida and Texas, and procurement directors at Gulf Coast hospital systems anchored the qualitative base. Secondary validation drew from EPA Phase 3 regulatory filings, FERC resilience incentive program documentation, CARB executive orders and compliance databases, and SEC 10-K disclosures from listed industrial conglomerates. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the analysis window.
Sensitivity analysis tested forecast outputs against variable adoption rates for battery-solar hybrid substitution and divergent state-level CARB follower adoption timelines. The analytical framework modeled segmentation across power technology, application context, fuel architecture, and size class throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to historical preparedness procurement patterns following named storm events and ERCOT grid instability episodes. Industry-specific inputs included EPA certification approval timelines and FERC resilience rebate program participation rates.
The analysis sits within stated boundaries; outcomes outside assumed battery cost decline trajectories and state-level emissions adoption schedules would require recalibration. Forecasts reflect documented assumptions regarding grid reliability deterioration patterns and disaster preparedness funding continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Generator Rental Market
Generators
Power Generator for Military Market
Generators
South America and Africa Diesel Generator Market
Generators
India Portable Generator Market
Generators
Global Diesel Gensets Market
Generators
Power Generator Rental Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Generator Sales Market
Generators
Military Generator Market
Generators
Generator Sets Market
Generators
Commercial Generator Market
Generators
Halogenerator Market
Generators
Dual-Fuel Generator Market
Generators
China Gas Generator Market
Generators
North America Gas Generator Market