
 Middle-East and Africa Battery Energy Storage System Market | 2026-2036
Middle-East and Africa Battery Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Battery Energy Storage System Market Foresight
Market Context
The capital-intensity divergence between integrated manufacturers and project-assemblers is rotating competitive advantage toward firms with captive cell supply. Tesla leverages its Nevada-derived manufacturing playbook to anchor utility-scale deployments across the Emirates. BYD sustains cost leadership through backward integration into lithium iron phosphate cell production. Fluence Energy competes on software-layer differentiation, bunduling grid-forming inverters with AI-driven dispatch optimization.
Technical Definition and Segment Structure
A battery energy storage system comprises electrochemical cells packaged with power conversion systems, thermal management, and battery management electronics to absorb, store, and discharge electrical energy on demand. These systems buffer intermittency from photovoltaic and wind generation, provide synthetic inertia for frequency regulation, and defer transmission upgrades in constrained networks. Lithium-ion chemistries dominate installed capacity given energy density advantages and decade-long cost curves, though flow batteries occupy niche roles in long-duration configurations for off-grid mining operations. The application mix tilts toward renewable integration as Gulf utilities procure co-located storage with solar independent power projects, while grid stabilization services attract merchant revenue streams in South Africa's struggling Eskom network. Among end users, utility procurement drives volume, but commercial and industrial segments in Nigeria and Kenya's unreliable-grid zones generate premium pricing for backup power solutions.
Regulatory Framework and Outlook
Saudi Arabia's Energy Efficiency Center and South Africa's National Energy Regulator shape interconnection standards and procurement timelines for storage-linked renewables. The UAE's net metering frameworks and Dubai Electricity and Water Authority technical specifications dictate product certification requirements for behind-the-meter installations. Stakeholders must monitor how NERSA's licensing reforms and Saudi PPA auction designs allocate revenue risk between storage operators and offtakers.
Market Dynamics
Capital intensity in lithium-ion cell manufacturing is concentrating competitive advantage among firms with captive supply chains, while Gulf utilities accelerate procurement of co-located storage with solar independent power projects.
Growth Catalysts
- Saudi PPA auction designs:The Kingdom's renewable energy procurement framework mandates storage co-location, creating guaranteed offtake contracts for utility-scale developers.
- Industrial corridors:South Africa's mining and manufacturing belts face chronic grid instability from Eskom's failing infrastructure, driving premium demand for behind-the-meter backup systems.
- Lithium iron phosphate chemistries:Declining cell costs and improved cycle life are displacing lead-acid alternatives in commercial installations across Nigeria and Kenya.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress developer margins and delay project financial close in price-sensitive African markets.
- Cell supply concentration:Chinese manufacturers control cathode active material production, creating single-source dependency for Middle Eastern integrators.
- Flow battery substitution:Vanadium redox systems capture long-duration mining applications where lithium-ion degradation economics fail.
Strategic Opportunities
- Net metering frameworks:Dubai Electricity and Water Authority's technical specifications for behind-the-meter installations unlock distributed commercial deployment.
- Kenya's unreliable-grid zones:Rural industrial clusters lack grid access entirely, creating islanded microgrid opportunities with solar-plus-storage configurations.
- AI-driven dispatch optimization:Convergence of predictive analytics with grid-forming inverters enables merchant revenue stacking in South Africa's ancillary services market.
Industry Challenges
- Thermal management engineering:Gulf ambient temperatures exceed 50°C, degrading cell performance and requiring specialized HVAC design capabilities scarce in regional EPC firms.
- Certification timeline compression:UAE product certification requirements for battery safety and grid codes extend procurement cycles, delaying commercial commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Battery Energy Storage System Market |
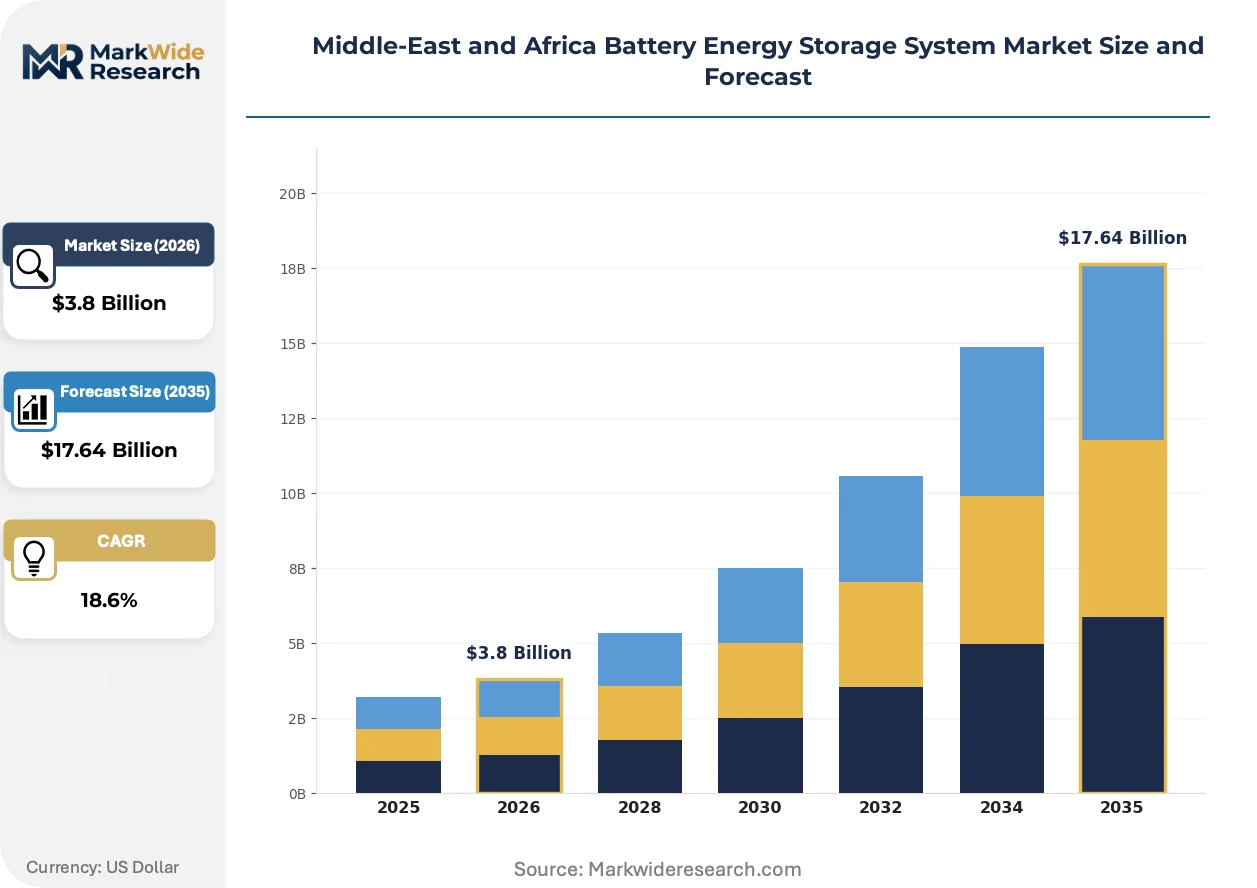
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Flow Batteries, Nickel-based Application: Renewable Integration, Grid Stabilization, Backup Power, Frequency Regulation End User: Utilities, Commercial, Residential, Industrial Technology: Physical Storage, Chemical Storage, Thermal Storage, Mechanical Storage |
| Companies Covered | Tesla Inc, BYD Company Ltd, LG Energy Solution, Fluence Energy Inc, NGK Insulators Ltd, ABB Ltd, Huawei Digital Power, Eaton Corporation PLC, The AES Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Battery Energy Storage System Market Shifts & Advancements
Technology evolution and procurement restructuring are reconfiguring how storage systems are specified, financed, and operated across Middle Eastern utilities and African industrial users.
Lithium iron phosphate cell technology is fragmenting the utility-scale procurement landscape. Gulf Cooperation Council utilities now specify this chemistry for solar-plus-storage projects given superior thermal tolerance and cycle stability. The shift is compressing nickel-cobalt-manganese market share in grid applications.
Saudi Arabia's Energy Efficiency Center interconnection standards are mandating grid-forming inverter capabilities for all new storage-linked renewables. This regulatory pressure forces integrators to source advanced power electronics rather than conventional grid-following units. South African developers face similar technical specifications from NERSA's licensing reforms.
Merchant offtake contracts are displacing traditional utility PPAs as the dominant procurement structure. Industrial buyers in Nigeria's manufacturing zones now negotiate energy-as-a-service agreements with storage operators, transferring revenue risk to project owners. This model concentrates fastest in Lagos and Port Harcourt's unreliable-grid corridors.
Middle-East and Africa Battery Energy Storage System Market Segmentation
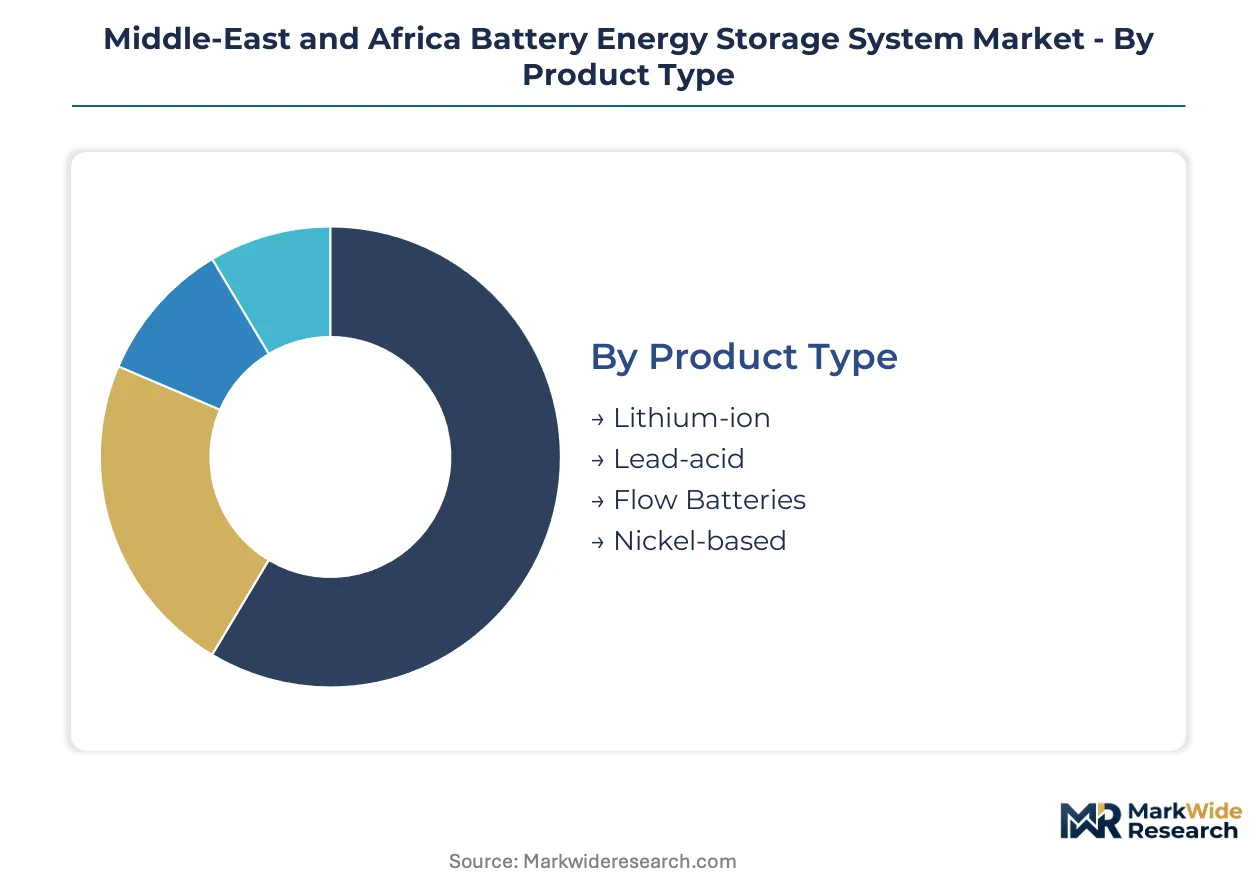
Segmentation in the Middle-East and Africa battery energy storage system market reveals how procurement priorities diverge between Gulf utilities seeking grid-scale solutions and African industrial users prioritizing reliability. Understanding these splits illuminates where technology substitution pressures and margin concentration concentrate competitive advantage.
Product Type:
Substitution pressure from alternative chemistries reshapes procurement specifications, with lithium-ion facing emerging competition in long-duration applications.
- Lithium-ion:Electrochemical cells utilizing lithium cobalt oxide or lithium iron phosphate cathodes deliver superior energy density and cycle stability. Demand concentrates in Saudi Arabia's solar-plus-storage auctions and UAE utility-scale deployments where space constraints and thermal tolerance matter. Saudi PPA auction designs mandating storage co-location accelerate procurement of these systems.
- Lead-acid:Mature flooded or valve-regulated lead-acid batteries offer lower capital cost but degraded cycle life and energy density. Nigeria's commercial backup installations and Kenya's rural microgrids still specify these units where upfront budget constraints override lifetime economics.
- Flow Batteries:Vanadium redox or zinc-bromine systems separate energy and power capacity, enabling 8+ hour discharge durations. South African mining operations deploy these for off-grid islanded power where lithium-ion degradation economics fail.
- Nickel-based:Nickel-cadmium and nickel-metal hydride chemistries tolerate extreme temperatures but carry higher material costs. Niche applications in Gulf industrial facilities with specialized HVAC limitations specify these alternatives.
Lithium-ion retains volume leadership; flow batteries hold the steepest expansion curve in mining and long-duration segments.
Application:
Application mix tracks directly to grid infrastructure maturity, with renewable integration dominating Gulf markets while backup power commands premium pricing in reliability-constrained African economies.
- Renewable Integration:Co-located storage buffers photovoltaic and wind intermittency, enabling dispatchable clean power. Dubai Electricity and Water Authority's solar IPP mandates drive procurement volumes across Emirates utility-scale projects.
- Grid Stabilization:Synthetic inertia and frequency response services stabilize transmission networks under stress. South Africa's Eskom network procures these capabilities through NERSA-regulated ancillary services markets.
- Backup Power:Behind-the-meter systems ensure continuity during grid outages. Lagos and Port Harcourt manufacturing corridors generate premium demand where grid reliability collapses.
- Frequency Regulation:Fast-responding storage injects or absorbs power to maintain 50Hz grid standards. Saudi Arabia's Energy Efficiency Center interconnection standards mandate these capabilities for new storage-linked renewables.
Renewable integration captures the largest procurement volumes; backup power generates the highest margins per megawatt-hour deployed.
End User:
End user segmentation exposes a bifurcation between Gulf utility procurement at scale and African commercial-industrial buyers paying reliability premiums.
- Utilities:State-owned power entities procure multi-hundred megawatt-hour systems through competitive auctions. Saudi Arabia's renewable energy procurement framework and UAE grid modernization mandates concentrate demand here.
- Commercial:Retail, hospitality, and office facilities deploy behind-the-meter storage for peak shaving and backup. Kenya's unreliable-grid zones and Nigeria's urban commercial centers drive this segment.
- Residential:Single-family and multi-unit dwellings install small-scale systems for solar self-consumption. Net metering frameworks in Dubai unlock distributed deployment in high-income expatriate communities.
- Industrial:Mining, manufacturing, and processing facilities require uninterrupted power for operations. South Africa's platinum and gold mining belts face chronic Eskom instability, forcing captive storage investment.
Utilities dominate absolute capacity additions; industrial buyers deliver the fastest growth in behind-the-meter deployments.
Technology:
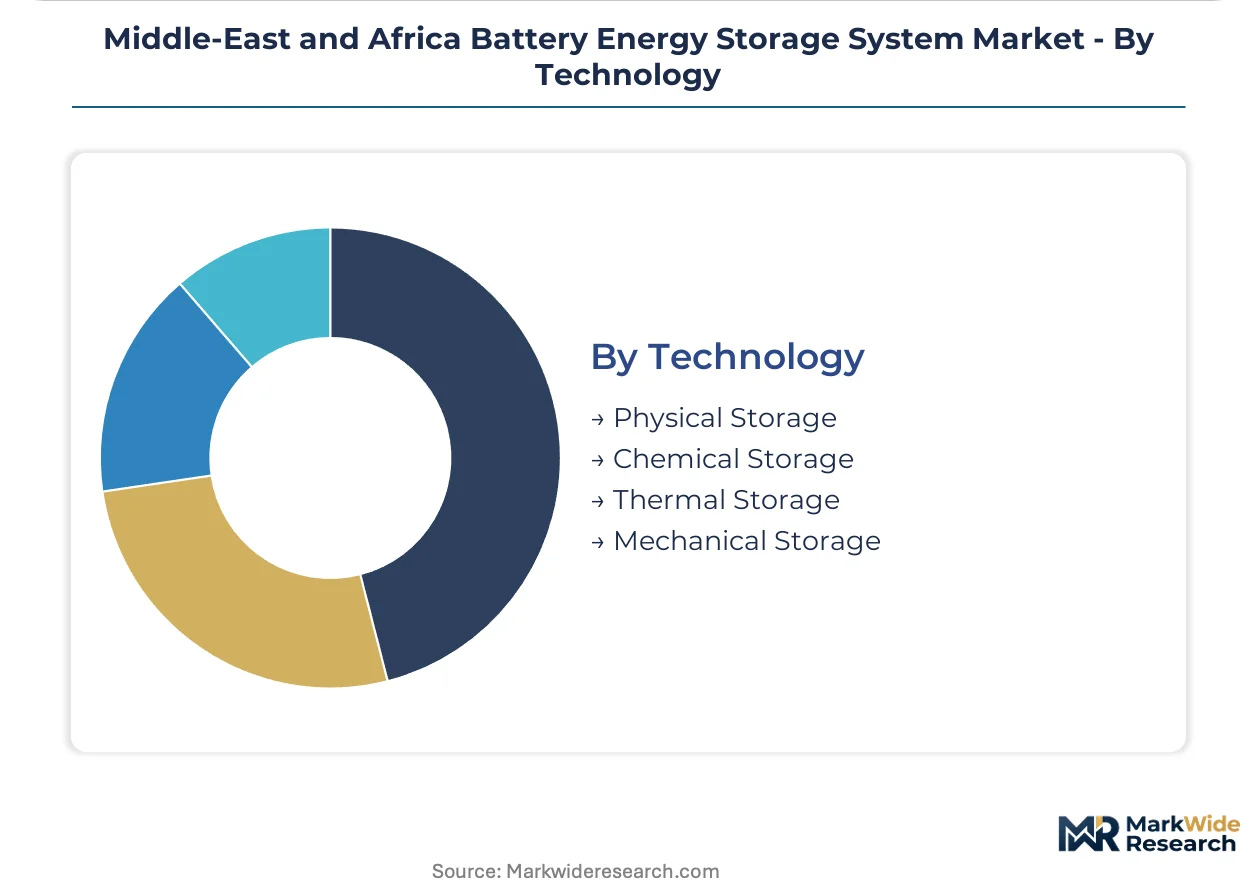
Technology categorization by storage mechanism reveals electrochemical dominance challenged by mechanical alternatives in specific duration and scale configurations.
- Physical Storage:Capacitors and supercapacitors deliver instantaneous power discharge for grid stabilization. Niche deployment in Saudi frequency regulation applications complements slower-responding battery assets.
- Chemical Storage:Electrochemical batteries dominate installed base through lithium-ion, lead-acid, and flow battery chemistries. Gulf Cooperation Council utilities specify lithium iron phosphate variants for thermal tolerance.
- Thermal Storage:Molten salt or phase-change materials store energy as heat for later conversion. Concentrated solar power plants in Morocco integrate these systems for evening dispatch.
- Mechanical Storage:Pumped hydro and compressed air systems offer bulk long-duration capacity. Limited deployment in South Africa's mountainous regions where geography permits.
Chemical storage commands overwhelming capacity share; mechanical alternatives face geographic constraints limiting addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Gulf Cooperation Council diverges sharply from African markets, where currency volatility and offtaker credit risk compress developer returns. Saudi Arabia and the UAE command premium valuations through sovereign-backed procurement, while Nigerian and Kenyan projects absorb higher financing costs.
Saudi Arabia
Utility-scale solar auctions mandate storage co-location, creating guaranteed demand pools for lithium-ion integrators. The Kingdom's Energy Efficiency Center sets interconnection standards requiring grid-forming inverter capabilities. Riyadh and the Eastern Province concentrate manufacturing and data center loads driving behind-the-meter procurement.
United Arab Emirates
Dubai Electricity and Water Authority's net metering frameworks unlock distributed commercial deployment alongside utility-scale mandates. MOHAP and federal regulators coordinate product certification for battery safety and grid codes. Abu Dhabi's industrial zones and Dubai's logistics corridors anchor the region's highest storage penetration rates.
South Africa
Eskom's failing transmission infrastructure forces mining and manufacturing clusters into captive storage investment. NERSA's licensing reforms restructure ancillary services markets for merchant revenue opportunities. The platinum and gold belts of North West and Gauteng provinces face chronic load-shedding, driving premium pricing for backup systems.
Nigeria
Lagos and Port Harcourt manufacturing corridors generate demand for energy-as-a-service contracts transferring revenue risk to operators. The country's national electricity regulator struggles with grid reliability standards, creating regulatory ambiguity. Industrial clusters in these port cities absorb diesel generator displacement costs through solar-plus-storage microgrids.
Kenya
Rural industrial zones lacking grid access entirely create islanded microgrid opportunities with solar-plus-storage configurations. The national energy regulator oversees rural electrification programs with storage components. Nairobi's commercial core and Mombasa's port logistics zones drive behind-the-meter peak shaving demand.
Middle-East and Africa Battery Energy Storage System Market Competitive Landscape
Concentration sits with integrated cell manufacturers and software-layer specialists rather than pure-play project assemblers. Chinese and Korean producers leverage captive cathode supply chains to compress pricing for Gulf utilities. Three archetypes dominate: backward-integrated lithium iron phosphate producers, grid-forming inverter bundlers with AI dispatch capabilities, and turnkey EPC firms with regional certification expertise. Competitive moves center on securing long-term offtake contracts through sovereign-linked procurement and building thermal management engineering capabilities for 50°C Gulf ambient conditions.
Among North American and Chinese technology providers, Tesla Inc and BYD Company Ltd exemplify the integrated manufacturing archetype, while Fluence Energy Inc occupies the software-differentiation tier. These three anchors demonstrate how competitive advantage rotates toward firms controlling cell supply or predictive analytics layers rather than installation margins alone.
| Leading Market Players |
|---|
| Tesla Inc |
| BYD Company Ltd |
| LG Energy Solution |
| Fluence Energy Inc |
| NGK Insulators Ltd |
| ABB Ltd |
| Huawei Digital Power |
| Eaton Corporation PLC |
| The AES Corporation |
| Others |
Supply & Pricing Matrix
Twelve-to-sixteen-week lead times for lithium iron phosphate cells from Chinese cathode manufacturers compress pricing power for Gulf integrators while amplifying cost pass-through to African project developers. This inventory band tethers procurement economics to volatile raw material corridors and concentrates margin pressure on non-integrated assemblers.
Pricing Analysis
Configured-to-order premiums for grid-forming inverter bundles run 15-25% above standard grid-following configurations in UAE utility tenders. Project-based long-term offtake contracts dominate Saudi PPA auctions, with price differentiation hinging on thermal management engineering grade and NERSA certification tier. Cost compression in commercial backup tiers is intensifying because Kenyan and Nigerian buyers prioritize upfront capital minimization over lifecycle economics. Industrial mining buyers in South Africa show least price sensitivity, absorbing reliability premiums for islanded microgrid configurations.
Supply Chain Analysis
Inventory positions stretching beyond ninety days for vanadium electrolyte and lithium carbonate reflect supply chain vulnerability to commodity price swings. Cathode active material production concentrates in China, South Korea, and Japan, with cell assembly drawing from lithium carbonate, electrolyte solvents, and separator membranes. Single-source vulnerability permeates Middle Eastern integrators dependent on Chinese cathode supply. Distribution runs through regional EPC contractors with MOHAP and Saudi Energy Efficiency Center certification expertise, linking manufacturing bases to Gulf deployment sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as AI-driven dispatch optimization and grid-forming inverter interoperability create ecosystem lock-in for integrated software-hardware bundles.
For Market Incumbents: Shield proprietary cell supply agreements through long-term offtake contracts with Saudi renewable energy procurement frameworks. Deepen backward integration into lithium iron phosphate production to offset raw material volatility compressing developer margins in African markets. Prioritize thermal management engineering capabilities for 50°C Gulf ambient conditions as a defensive moat against Chinese cost leaders. For New Entrants and Emerging Players: AI-driven predictive maintenance services represent a service-layer gap where incumbents under-serve Nigerian manufacturing corridors and Kenyan rural industrial clusters. Penetrate Lagos and Port Harcourt's energy-as-a-service contract market through merchant offtake structures transferring revenue risk to operators. Deploy solar-plus-storage microgrid configurations targeting islanded mining applications in South Africa's platinum belts. For Investors and Strategic Acquirers: Long-term, this sits as a grid-modernization infrastructure play because sovereign-backed procurement in Saudi Arabia and the UAE generates contracted revenue visibility unmatched in emerging market energy sectors. Target acquisition profiles should emphasize software-layer specialists with grid-forming inverter bundling capabilities and AI dispatch algorithms. Watch NERSA licensing reform implementation as the signal indicating merchant revenue market depth in South Africa's ancillary services sector.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | MOHAP and Saudi Energy Efficiency Center mandates force technology upgrade cycles across integrators. |
| Lithium Iron Phosphate Backward Integration | Cathode active material production control insulates margins from carbonate price volatility in African tenders. |
| AI Dispatch Optimization Platform | Predictive analytics convergence enables merchant revenue stacking in South Africa's NERSA-regulated ancillary markets. |
| Thermal Management Engineering Capability | Specialized HVAC design for 50°C Gulf conditions differentiates regional EPC contractors from commodity assemblers. |
| Energy-as-a-Service Contract Structure | Risk transfer mechanisms unlock Nigerian manufacturing corridor demand without balance-sheet burden on industrial buyers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Saudi Arabia, the UAE, South Africa, Nigeria, and Kenya; and secondary validation through IEA reports, FERC-style regulatory filings from NERSA and the Saudi Energy Efficiency Center, project development databases tracking solar-plus-storage auctions, and customs records for cell and inverter trade flows. Bottom-up capacity deployment estimates triangulated against top-down utility procurement pipeline data.
Across the projection horizon, the analytical framework modeled segmentation across battery chemistry, application type, end-user category, and technology mechanism, with regional regulatory framework and grid infrastructure maturity as cross-cutting dimensions. CAGRs derived from deployment run-rate analysis, auction pipeline conversion assumptions, and substitution elasticity between lithium-ion and flow battery configurations in long-duration mining applications. Forecast inputs incorporated Eskom load-shedding frequency trajectories and Gulf Cooperation Council renewable energy procurement auction schedules.
Forecasts assume regulatory continuity in Saudi PPA auction designs, UAE net metering frameworks, and NERSA ancillary services market structures; material policy shifts would require re-modeling. Forecasts reflect assumptions about lithium carbonate price band stability, cell supply chain geographic concentration persistence, and thermal management engineering capability scarcity in regional EPC markets. Revision becomes warranted when raw material price volatility crosses thresholds that trigger project financial close delays in price-sensitive African markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
North America Energy Storage Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
Renewable Battery Storage Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
Power Battery Management System Market
Battery Management System
North America Battery Management System Market
Battery Management System
Energy Storage Market