
 Adhesive Resin Market | 2026-2036
Adhesive Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesive Resin Market Intelligence
Application-specific technical support, bundled with material supply contracts, is hardening the relationship between resin producers and end-users. BASF leverages its extensive chemical portfolio to offer integrated solutions for the automotive sector, particularly for electric vehicle battery assembly. Hexion specializes in thermoset resins, serving demanding construction and industrial applications. Dow competes on a global scale through its vast production capacity and distribution network, reaching a diverse set of fabricators and manufacturers.
Adhesive resins are polymeric materials that form the core of adhesive formulations, providing primary bonding characteristics. These materials are defined by properties such as viscosity, cure time, and chemical resistance, which enable them to join diverse substrates. While epoxy and polyurethane resins lead in high-performance structural uses, the packaging and electronics assembly applications are expanding rapidly. Formulations in liquid and hot melt forms dominate distribution channels that serve original equipment manufacturers and contract manufacturers.
Regulatory frameworks significantly influence product development and market access. The EU's REACH regulation restricts certain hazardous substances, while the US EPA sets limits on volatile organic compound (VOC) emissions. In China, national GB standards dictate performance and safety criteria for adhesives used in consumer goods and construction. Producers must now decide whether to invest in bio-based resin research or focus on optimizing existing synthetic chemistries for compliance and performance.
Market Dynamics
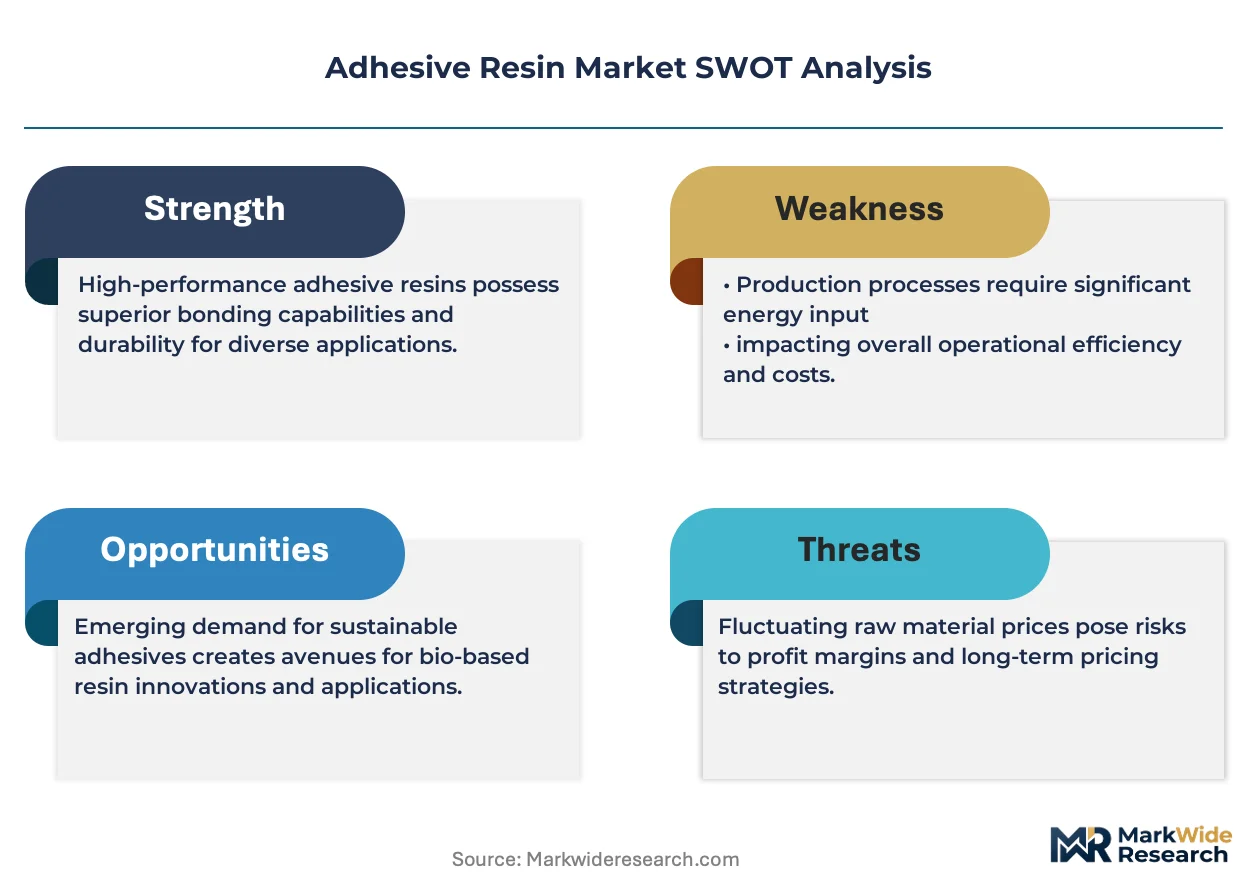
The adhesive resin market is shaped by the fundamental tension between escalating performance requirements in advanced manufacturing and tightening environmental regulations. This dynamic forces producers to innovate beyond traditional synthetic chemistries, balancing bond strength and durability with demands for sustainability.
Growth Catalysts
- Electric Vehicle Production:The assembly of electric vehicle battery packs and lightweight composite body panels requires high-performance structural adhesives, stimulating demand for specialized epoxy and polyurethane resins that offer thermal management and impact resistance.
- Manufacturing in Mexico:Expansion of industrial output in Mexico, particularly within automotive and electronics clusters, creates concentrated demand for adhesive resins, supported by nearshoring trends and integration into North American supply chains.
- Bio-Based Formulations:Regulatory frameworks like the European Union's REACH are accelerating R&D in bio-based resins. This creates growth avenues for formulations derived from renewable feedstocks that meet lower-VOC mandates for consumer and construction applications.
Market Restraints
- Petrochemical Feedstock Volatility:The cost structure for many synthetic resins, such as epoxies and vinyls, is directly tied to volatile prices of crude oil derivatives, creating margin pressure and pricing instability for manufacturers.
- Performance Trade-Offs in Green Adhesives:Many current bio-based resins exhibit lower thermal stability, chemical resistance, or bond strength compared to their high-performance synthetic counterparts, limiting their use in demanding structural applications.
- Fragmented Regulatory Compliance:Divergent chemical regulations, such as the EU's REACH, US EPA standards, and China's GB standards, increase the cost and complexity of developing and marketing a single product formulation for multiple regions.
Strategic Opportunities
- Adhesives for Flexible Electronics:The development of foldable displays and wearable sensors opens a market for flexible, durable, and electrically non-conductive adhesive resins capable of withstanding repeated mechanical stress.
- Functional Additive Integration:Incorporating conductive fillers, thermal interface materials, or self-healing agents directly into resin formulations creates high-value products for specialized electronics, aerospace, and automotive applications.
- Southeast Asian Manufacturing Growth:Expanding industrialization in countries like Indonesia and Thailand presents an opportunity for suppliers of industrial-grade adhesives, particularly in packaging, footwear, and component assembly sectors.
Industry Challenges
- Formulation Expertise Scarcity:A persistent challenge is the shortage of polymer chemists and application engineers who possess the dual expertise needed to develop custom resin formulations and troubleshoot their implementation on complex OEM production lines.
- Global Chemical Registration Management:Producers face significant administrative burdens and costs in tracking substance restrictions and maintaining compliance across multiple jurisdictions, where chemical inventories and allowable concentration limits are continuously updated.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesive Resin Market |
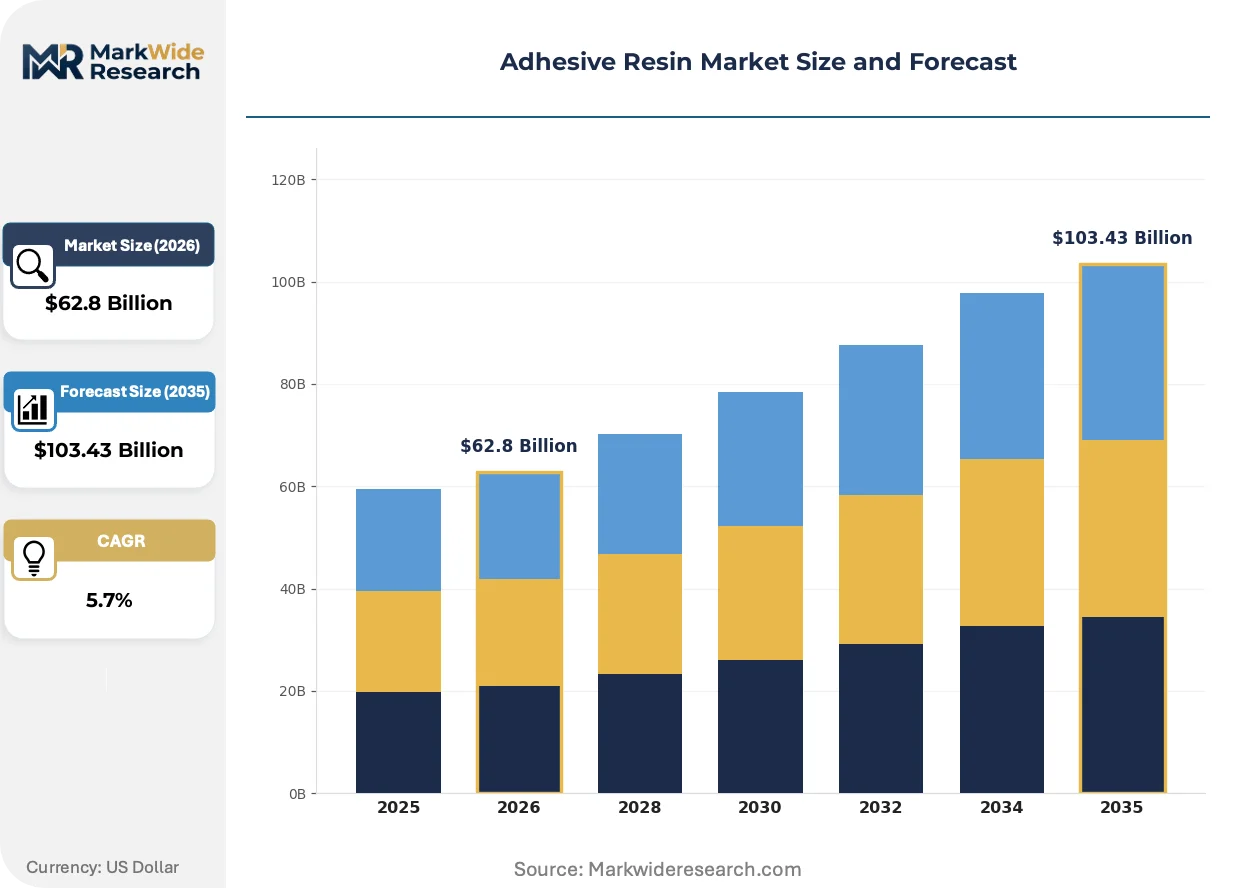
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $103.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Acrylic, Polyurethane, Silicone, Polyvinyl Acetate, Phenolic Application: Construction, Electronics Assembly, Packaging, Woodworking, Footwear Manufacturing, Textile Bonding End User: Manufacturers, Fabricators, Assembly Plants, Original Equipment Manufacturers, Aftermarket Producers, Contract Manufacturers Form: Liquid, Paste, Film, Powder, Hot Melt, Dispersion |
| Companies Covered | Dow, Hexion, BASF, Eastman Chemical, DuPont, ExxonMobil Chemical, Huntsman, Mitsubishi Chemical, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesive Resin Market Strategic Shifts & Innovations
Product development is increasingly defined by a dual mandate for enhanced performance and verifiable sustainability. This shift is compelling resin producers to invest in novel chemistries and transparent lifecycle data to meet the evolving procurement criteria of downstream industries.
Bio-based and recycled-content hot melt adhesives provide bonding solutions for packaging and product assembly. Consumer packaged goods and electronics firms are steadily adopting these materials to meet corporate sustainability goals. In non-structural applications, this class of sustainable adhesive is overtaking traditional petroleum-derived formulations where a green supply chain is a primary purchasing driver.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates extensive disclosure on environmental impacts throughout the value chain. This regulation is forcing adhesive resin users to demand detailed lifecycle assessment data and carbon footprint information from their material suppliers. Automotive and electronics OEMs are most affected, embedding these sustainability metrics into their procurement and supplier qualification processes.
A transition toward collaborative formulation services is altering supplier-customer relationships. End-users in high-specification sectors are moving away from commodity resin purchasing and toward partnerships where producers provide integrated technical support and custom development. This model is most prominent within the North American and European medical device and aerospace industries, where material validation is inseparable from the application.
Adhesive Resin Market Segmentation
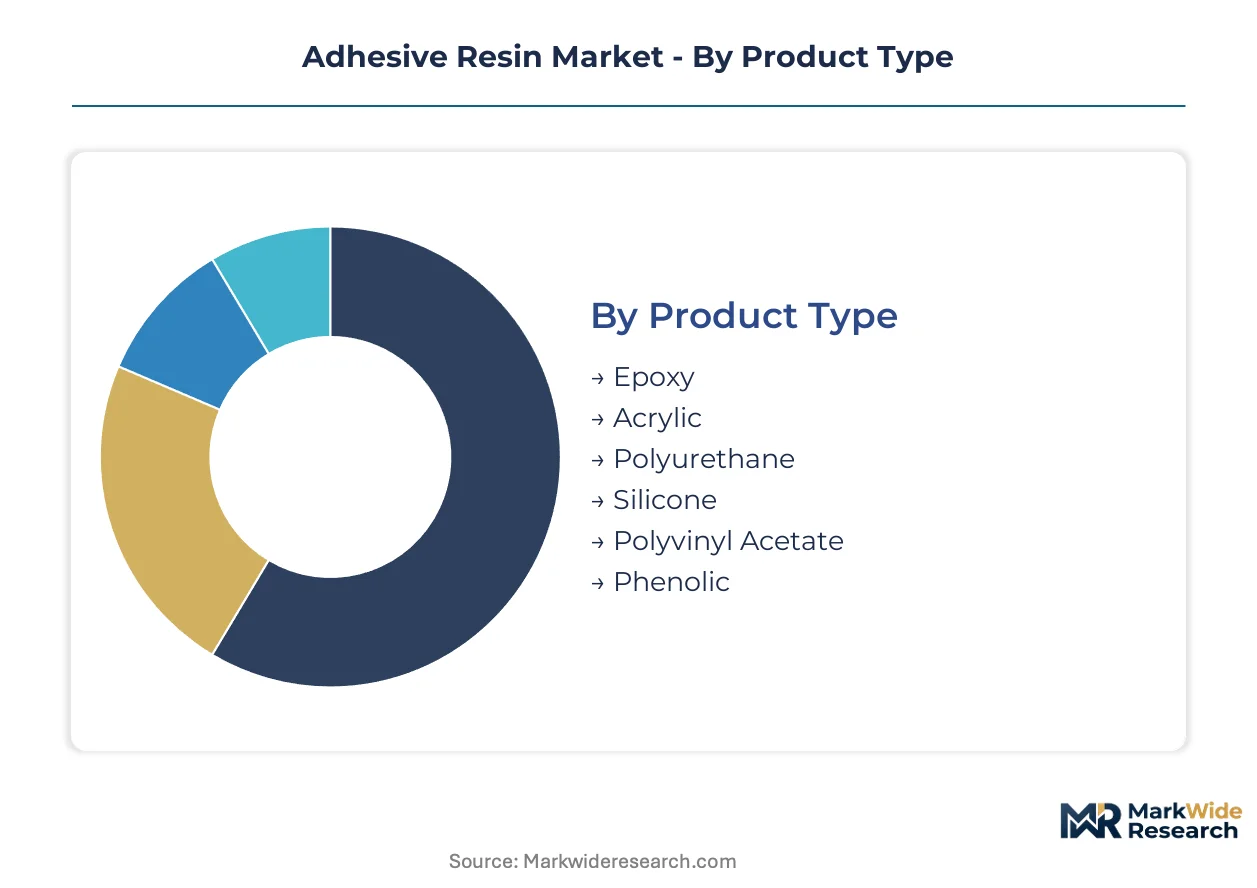
Understanding the Adhesive Resin Market through segmentation reveals how diverse material properties and application methods meet specific industrial demands. This granular view highlights where innovation is most critical and where established solutions continue to dominate. Customer procurement strategies also vary significantly across different end-user segments.
Product Type:
The upgrade and replacement cycles for adhesive resins are heavily influenced by performance demands and evolving regulatory standards.
- Epoxy:Thermosetting polymers forming strong, rigid bonds with high chemical and heat resistance. Demand concentrates in electric vehicle battery assembly and aerospace for structural integrity.
- Polyurethane:Elastomeric polymers offering flexibility, impact resistance, and strong adhesion to diverse substrates. Automotive and construction applications drive demand for their versatile bonding properties.
- Acrylic:UV-curable or pressure-sensitive formulations providing quick setting and good environmental resistance.
- Silicone:High-temperature resistant and flexible adhesives often used for sealing and gasketing in electronics.
- Polyvinyl Acetate:Water-based emulsions offering good adhesion for woodworking and paper-based applications.
- Phenolic:High-strength, heat-resistant resins primarily used in industrial laminates and friction materials.
Volume placements concentrate in Acrylic formulations; the faster expansion belongs to high-performance Epoxy resins.
Application:
The cost tier of adhesive resins varies significantly based on the performance requirements and precision needed for specific applications.
- Electronics Assembly:Precision bonding of components for devices like smartphones and displays, requiring electrically non-conductive and thermally stable resins. Demand is rising in flexible electronics and miniaturized sensor integration for advanced functionality.
- Packaging:High-speed bonding for cartons, flexible packaging, and labeling, emphasizing rapid cure times and food-safe formulations. Bio-based hot melts are gaining traction to meet corporate sustainability mandates from consumer brands.
- Construction:Structural and non-structural bonding for building materials, flooring, and insulation.
- Woodworking:Adhesives for furniture, laminates, and panel bonding, often requiring moisture resistance.
- Footwear Manufacturing:Flexible and durable bonds for shoe components, resisting repeated stress and environmental exposure.
- Textile Bonding:Adhesives for apparel, non-wovens, and technical textiles, providing flexibility and wash resistance.
Emerging applications in Electronics Assembly are driving innovation, while Packaging maintains consistent, high-volume demand.
End User:
Procurement models for adhesive resins differ substantially across various end-user types, reflecting distinct operational scales and technical requirements.
- Original Equipment Manufacturers:Large-scale producers designing and building final products, requiring custom resin formulations and integrated technical support for complex production lines. Automotive and aerospace OEMs demand rigorous material validation processes for structural components.
- Contract Manufacturers:Companies specializing in manufacturing products or components for other firms, focusing on efficient, high-volume adhesive application. Electronics and consumer goods CMs prioritize reliable supply and consistent performance for diverse assembly tasks.
- Manufacturers:Broad category encompassing various industries producing goods that require adhesive bonding.
- Fabricators:Businesses that assemble or construct products from raw materials or components.
- Assembly Plants:Facilities dedicated to bringing together components to create finished products.
- Aftermarket Producers:Companies supplying parts or services for products after their initial sale, often requiring repair or replacement adhesives.
The Original Equipment Manufacturers segment drives custom formulation requests, while Contract Manufacturers focus on scalable, off-the-shelf solutions.
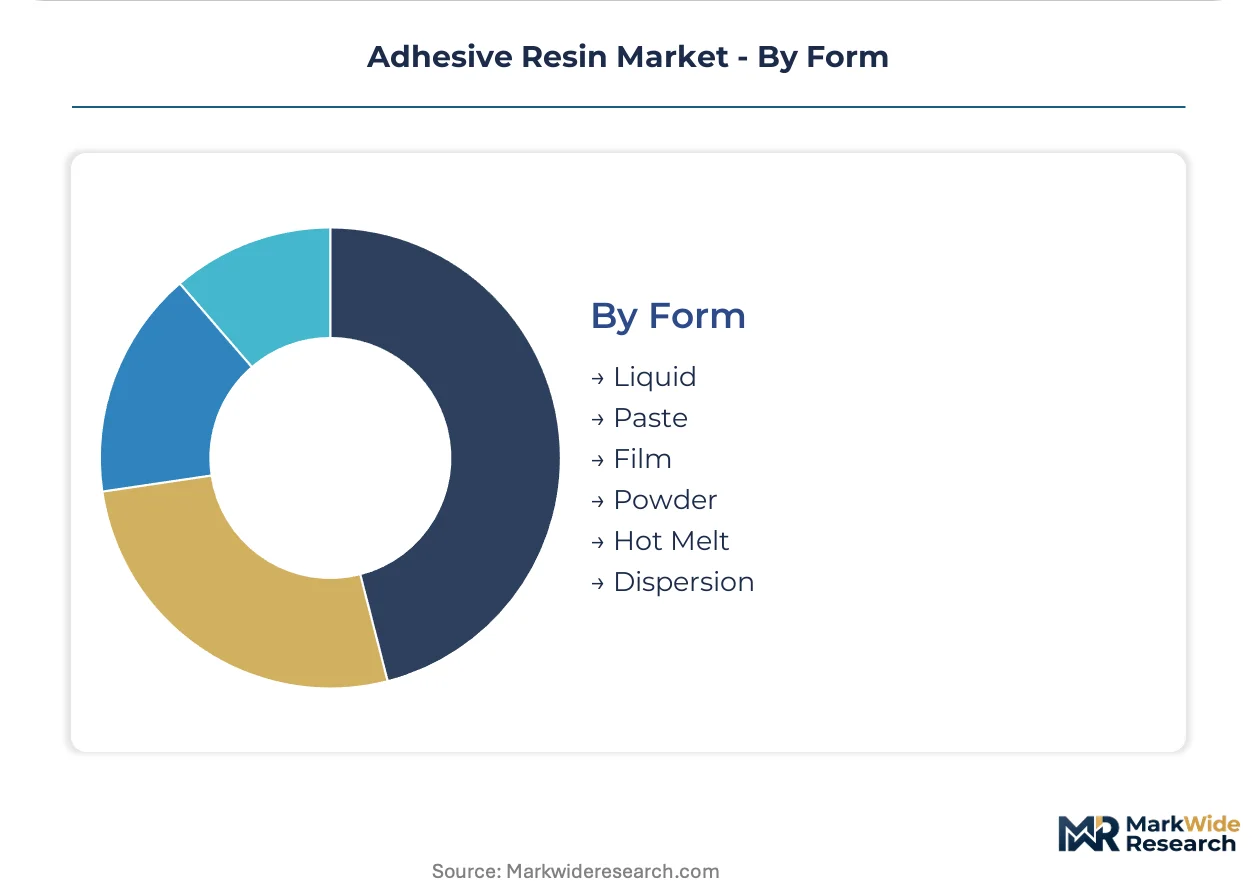
Form:
The distribution channels for adhesive resins are significantly influenced by the physical form of the material and its intended application method.
- Hot Melt:Thermoplastic adhesives applied in molten state, solidifying rapidly upon cooling to form a bond. Packaging and non-structural assembly applications dominate due to their fast cure times and suitability for high-speed production lines.
- Liquid:Versatile, pourable resins applied via dispensing systems, offering extended open times for complex assemblies or large surfaces. Structural bonding in automotive and construction often utilizes liquid epoxies and polyurethanes for robust performance.
- Paste:Thixotropic formulations providing gap-filling capabilities and sag resistance for vertical applications.
- Film:Pre-applied adhesive layers offering precise bond line thickness and clean application, common in electronics.
- Powder:Dry adhesive particles activated by heat or solvent, used in textile lamination and powder coating.
- Dispersion:Water-based systems where resin particles are suspended, offering low VOC and easy cleanup for general purpose bonding.
High-volume industrial applications predominantly use Hot Melt resins, whereas Film addresses specialized, precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's burgeoning automotive and electronics clusters, particularly in the Bajío region, drive significant adhesive resin demand. Nearshoring trends further integrate Mexican industrial output into North American supply chains. This expansion creates concentrated demand for specialized epoxy and polyurethane formulations.
Mexico
Mexico's automotive sector and electronics manufacturing require high-performance structural adhesives for assembly. Integration into North American trade agreements facilitates material flow for resin producers. Industrial parks in Monterrey attract advanced manufacturing facilities, driving demand for specialized bonding solutions.
China
Chinese electronics assembly and electric vehicle production create substantial demand for adhesive resins. China's national GB standards dictate performance and safety criteria for adhesives used in consumer goods. The Yangtze River Delta region hosts extensive manufacturing, consuming vast volumes of epoxy and polyurethane resins.
Germany
Germany's automotive industry and industrial machinery sectors require advanced adhesive resins for assembly. The EU's REACH framework restricts certain hazardous substances, pushing research into lower-VOC formulations. Bavaria's automotive and engineering hubs demand high-performance resins for structural and thermal management.
United States
United States aerospace and electronics sectors demand specialized adhesive resins for critical applications. The US EPA sets strict limits on volatile organic compound emissions in adhesive formulations. California's technology clusters and aerospace industry drive demand for high-reliability, precision bonding solutions.
Vietnam
Vietnamese footwear manufacturing and electronics assembly require consistent supplies of adhesive resins. Government incentives support foreign direct investment in manufacturing, influencing material procurement strategies. Industrial zones near Ho Chi Minh City are expanding, driving demand for both general-purpose and specialized adhesives.
Adhesive Resin Market Key Industry Players
Capital-heavy producers compete with asset-light formulators in the adhesive resin market. This dynamic creates a tiered structure, with large chemical conglomerates supplying base resins and specialized firms developing custom adhesive solutions. Three strategic archetypes emerge: integrated material suppliers, niche application specialists, and regional distributors. Companies engage in capacity expansion and strategic partnerships to secure raw material supply and expand geographic reach.
Among diversified chemical giants, Dow and BASF exemplify global reach and extensive product portfolios, serving a broad range of industrial applications. These firms leverage vast production capacities and distribution networks to deliver foundational resin chemistries worldwide, often integrating backward into key intermediates. Hexion occupies a position as a specialist in thermoset resins, exemplifying a focus on demanding construction and industrial applications. This includes high-performance epoxy and phenolic chemistries where specific cure profiles and chemical resistance are critical for end-user performance.
| Leading Market Players |
|---|
| Dow |
| Hexion |
| BASF |
| Eastman Chemical |
| DuPont |
| ExxonMobil Chemical |
| Huntsman |
| Mitsubishi Chemical |
| Ashland |
| Others |
Cost & Logistics Intelligence
Crude oil price volatility, a key commodity benchmark, cascades through the petrochemical feedstock market, directly influencing the cost structure for synthetic adhesive resins and affecting downstream pricing tiers. This fundamental dynamic dictates margin compression or expansion across the entire adhesive resin supply chain.
Pricing Analysis
Margin tightening in the commodity adhesive resin segment reflects intense competition and volatile petrochemical feedstock costs. Pricing is primarily contract-based for high-volume OEMs, while per-unit transactional models serve smaller fabricators. Price differentiation stems from quality grade, specific certifications like REACH compliance, and the level of integrated technical support provided. Contract manufacturers and aftermarket producers exhibit higher price sensitivity compared to aerospace and medical device OEMs.
Supply Chain Analysis
Single-source vulnerability sits with specialized monomer suppliers, particularly for advanced epoxy and polyurethane formulations. Geographic supply concentration for base chemicals centers on China and the United States, while Germany specializes in high-performance additives. The market depends on crude oil derivatives for most synthetic resins, creating a structural risk from commodity price volatility. Distribution runs through direct sales channels to large OEMs and regional distributors serving contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play, driven by escalating regulatory compliance costs that pressure smaller, less-capitalized formulators. Strategic moves are essential for maintaining competitiveness and capturing emerging opportunities.
For Market Incumbents:To counter regulatory divergence and emerging bio-based competition, deepen R&D investments in sustainable and high-performance bio-based resins. Leverage extensive chemical portfolios to offer integrated solutions for complex applications, particularly in electric vehicle battery assembly. Expand manufacturing capacity in strategic nearshoring hubs like Mexico to serve North American OEMs. Control key intermediate chemical supplies to mitigate feedstock volatility.
For New Entrants and Emerging Players:Launch via collaborative formulation services, targeting unmet needs in flexible electronics and specialized medical devices. Focus on niche applications requiring unique material properties, such as electrically non-conductive adhesives for miniaturized sensors. Penetrate Southeast Asian manufacturing clusters with industrial-grade bio-based hot melts for packaging and footwear. Develop transparent lifecycle assessment data as a key go-to-market angle.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized resin producers in Europe, where REACH regulations create significant compliance burdens. Long-term viability hinges on companies innovating in sustainable chemistries and functional additives for advanced manufacturing. Target acquisition archetypes include firms with proprietary bio-based resin technologies or strong positions in high-growth segments like flexible electronics. The increasing M&A activity in specialized functional additive firms is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Based Resin R&D | Develops sustainable alternatives for packaging and non-structural applications, meeting EU CSRD mandates. |
| Expand Manufacturing in Mexico | Supports nearshoring trends, providing localized supply for automotive and electronics OEMs. |
| Offer Integrated Technical Support | Hardens end-user relationships and facilitates custom formulation for complex assembly processes. |
| Integrate Functional Additives | Creates high-value products for specialized electronics and aerospace applications requiring unique properties. |
| Form Strategic Feedstock Partnerships | Secures stable raw material supply, mitigating volatility and ensuring production continuity. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market sizing and trend identification. Primary interviews with polymer chemists, OEM procurement leads, application engineers, and distribution channel partners validated market dynamics. This approach combined bottom-up and top-down triangulation for comprehensive data reconciliation.
Data-stream reconciliation informed the analytical framework, modeling market volumes and values across the projection horizon. Segmentation dimensions included product type, application, end-user, form, and regional manufacturing clusters. CAGRs were derived through a proprietary algorithm considering historical growth, macroeconomic indicators, and industry-specific forecast inputs like electric vehicle production volumes and construction spending trends.
The model assumes a particular technology adoption path; alternative pathways for bio-based resin development would alter the outlook. Forecasts reflect assumptions concerning regulatory stability and raw material availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Carpet Adhesive Market