
 Low VOC Adhesive Market | 2026-2036
Low VOC Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Low VOC Adhesive Market Outlook
Furniture manufacturers is unwinding decades of solvent-based procurement habits as indoor air quality certifications tighten. Henkel leverages its European R&D footprint to sustain formulation leadership in reactive polyurethane systems. Sika AG anchors construction-grade demand through geographic dominance in waterproofing and flooring installations. H.B. Fuller competes aggressively in packaging hot melts where brand strength and channel control protect margin pools.
Low VOC adhesives are formulated to emit minimal volatile organic compounds during curing, typically achieving VOC content below 50 g/L through water-based dispersion or 100% solids reactive chemistries. These materials bond substrates while meeting stringent indoor air quality thresholds in occupied spaces. Water-based acrylics lead volume in consumer-facing applications where odor and emissions sensitivity peak. Reactive polyurethane captures premium margin pools in automotive and electronics bonding where structural performance demands intensify. Hot melt formulations occupy the fastest-growing slot in packaging as e-commerce fulfillment speeds accelerate line throughput requirements.
EPA regulates VOC emissions under 40 CFR Part 59 for consumer and commercial products, while CARB enforces stricter state-level limits through its SCM 2007 and subsequent amendments. REACH registration requirements in Europe further constrain residual monomer content and hazard classification for imported formulations. Stakeholders must monitor regulatory divergence between California's advancing thresholds and federal baseline standards when allocating formulation development budgets across manufacturing footprints.
Market Dynamics
EPA Tier 3 tailpipe standards and CARB SCM 2007 amendments are forcing automotive OEMs to purge solvent-based adhesives from assembly lines, while REACH registration deadlines in Europe compress formulation timelines for flooring and construction suppliers.
Growth Catalysts
- Water-based acrylic dispersion:Furniture manufacturers in Germany and France are specifying these systems to meet EU F-Gas Regulation limits and indoor air quality certifications for residential interiors.
- Hot melt reactive polyurethane:E-commerce fulfillment centers in the United States are specifying these adhesives to accelerate packaging line speeds while satisfying EPA 40 CFR Part 59 emission thresholds.
- Waterproofing and flooring installations:Construction activity in Germany is concentrating specification authority with contractors who mandate low-VOC bonding systems to comply with REACH residual monomer limits.
Market Restraints
- Petrochemical feedstock volatility:Isocyanate and polyol input costs fluctuate with crude oil indices, compressing margin pools for reactive polyurethane formulators.
- Curing speed limitations:Water-based systems require extended open times and controlled humidity environments, restricting deployment in high-throughput automotive assembly sequences.
- Performance gaps in extreme climates:Hot melt adhesives soften at elevated temperatures, limiting specification in southern United States roofing and exterior construction applications.
Strategic Opportunities
- India construction sector:BIS certification requirements for green building materials are creating specification windows for low-VOC flooring adhesives in commercial real estate developments.
- Medical device bonding:FDA biocompatibility pathways for skin-contact adhesives are opening demand for 100% solids reactive chemistries in wearable diagnostics.
- Digital specification platforms:Architecture and engineering firms are migrating adhesive selection to building information modeling databases that filter by VOC content and certification status.
Industry Challenges
- Formulation chemist scarcity:Expertise in water-based dispersion stability and reactive polyurethane catalyst systems concentrates with aging specialists in Germany and the United States.
- Dual certification timelines:Suppliers must synchronize EPA 40 CFR Part 59 testing with REACH registration dossiers, extending product launch cycles by twelve to eighteen months.
- Legacy equipment incompatibility:Solvent-based application systems in automotive paint shops require costly retrofitting to handle water-based adhesive viscosities and drying profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low VOC Adhesive Market |
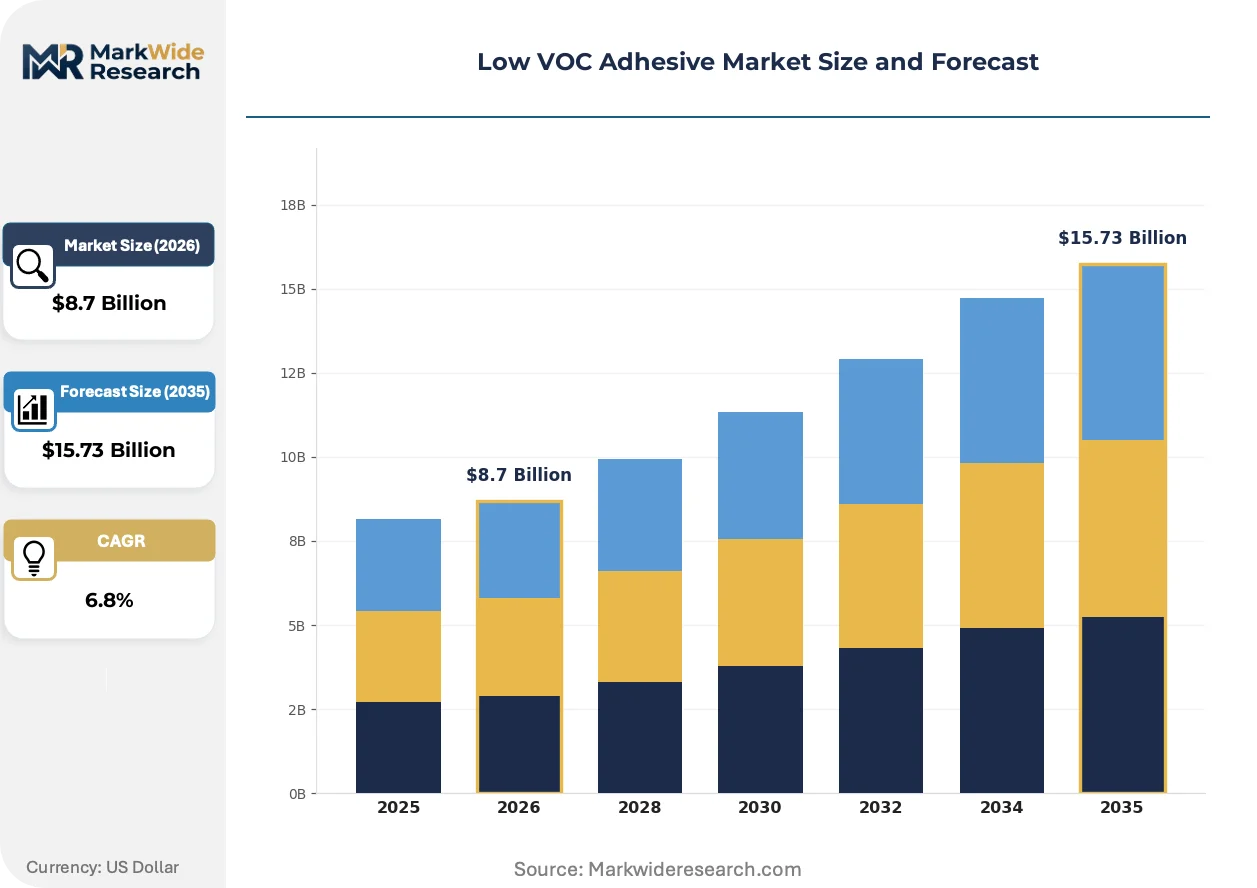
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Reactive, Hot Melt End User: Construction, Automotive, Furniture, Electronics Formulation: Polyurethane, Acrylic, Epoxy, Silicone Application: Packaging, Flooring, Coatings, Bonding |
| Companies Covered | Sika AG, Ashland, Henkel, Pidilite Industries, Huntsman Corporation, 3M, Arkema, Bostik, H.B. Fuller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low VOC Adhesive Market Strategic Shifts
Reactive chemistry platforms are fragmenting into application-specific variants as end-users demand performance customization without sacrificing emission compliance. Formulators are racing to decouple structural bonding capability from volatile solvent carriers.
Bio-based polyurethane prepolymers derived from castor oil and soybean feedstocks are fragmenting the raw material sourcing strategies of adhesive manufacturers. Automotive seating suppliers in Germany and the United States are qualifying these systems for structural foam bonding. The shift is fragmenting traditional petrochemical supply relationships and creating new qualification bottlenecks at OEM material review boards.
EPA enforcement of 40 CFR Part 59 is intensifying inspection frequency at consumer product manufacturing facilities in the United States. Adhesive suppliers must now submit third-party VOC testing documentation to retain approved vendor status with retail brand owners. Flooring and furniture manufacturers are responding by consolidating procurement with formulators who maintain certified in-house laboratories.
Building information modeling software is embedding emission databases that automatically exclude non-certified adhesives from specification shortlists. Architects in Germany and France are filtering products by EPD and Cradle to Cradle certification status before issuing RFQs. The practice is concentrating specification authority with software-integrated suppliers and marginalizing traditional catalog distributors.
Low VOC Adhesive Market Segmentation
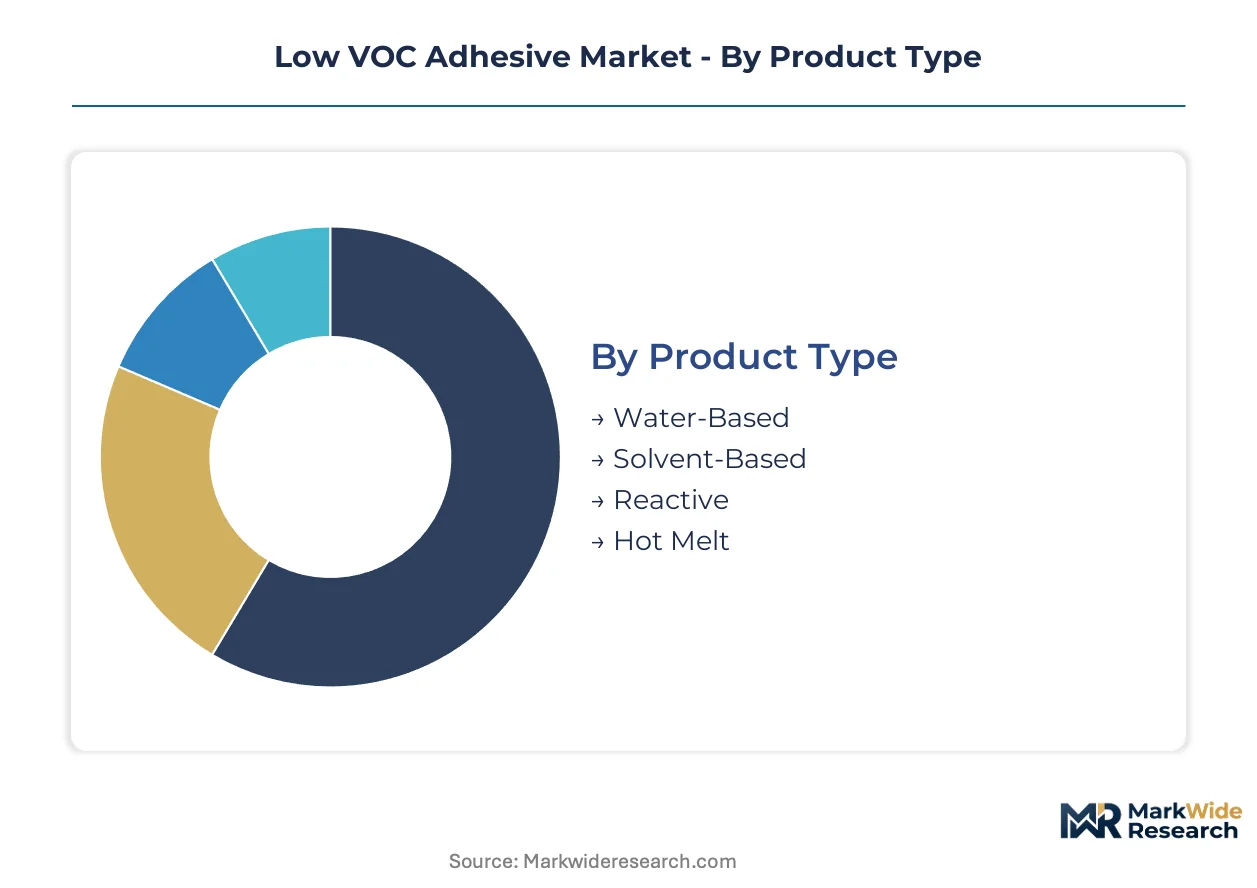
Regulatory fragmentation across EPA, CARB, and REACH creates divergent specification requirements that reshape how formulators prioritize chemistry platforms. Each segment carries distinct compliance burdens and performance trade-offs that procurement teams must navigate.
Product Type:
EPA 40 CFR Part 59 and CARB SCM 2007 thresholds favor water-based systems in consumer-facing applications, while reactive chemistries satisfy structural demands where 100% solids content eliminates solvent exposure entirely.
- Water-Based:Acrylic and polyurethane dispersions achieve VOC content below 50 g/L through aqueous carrier systems. Furniture manufacturers in Germany specify these formulations to satisfy EU F-Gas Regulation limits and indoor air quality certifications for residential interiors.
- Reactive:Two-component polyurethane and epoxy systems cure without solvent emission through chemical crosslinking. Automotive OEMs in the United States are specifying these adhesives for structural bonding as EPA Tier 3 compliance deadlines eliminate solvent-based alternatives from assembly lines.
- Hot Melt:Thermoplastic formulations enable rapid bonding without curing delays.
- Solvent-Based:Legacy formulations face contracting specification windows under tightening emission standards.
Established volume favors water-based systems; emerging adoption favors reactive platforms.
End User:
Cost tier differentiation separates specification authority between premium structural applications and high-volume commodity bonding.
- Construction:Waterproofing and flooring contractors mandate low-VOC bonding systems to comply with REACH residual monomer limits in Germany. BIS certification requirements for green building materials are opening specification windows in India's commercial real estate sector.
- Automotive:Structural foam bonding and interior assembly applications demand crash-resistant performance. OEM material review boards in Germany and the United States are qualifying bio-based polyurethane prepolymers for seating applications.
- Furniture:Residential interior applications prioritize odor control and emission transparency.
- Electronics:Miniaturized device assembly requires precision dispensing and thermal stability.
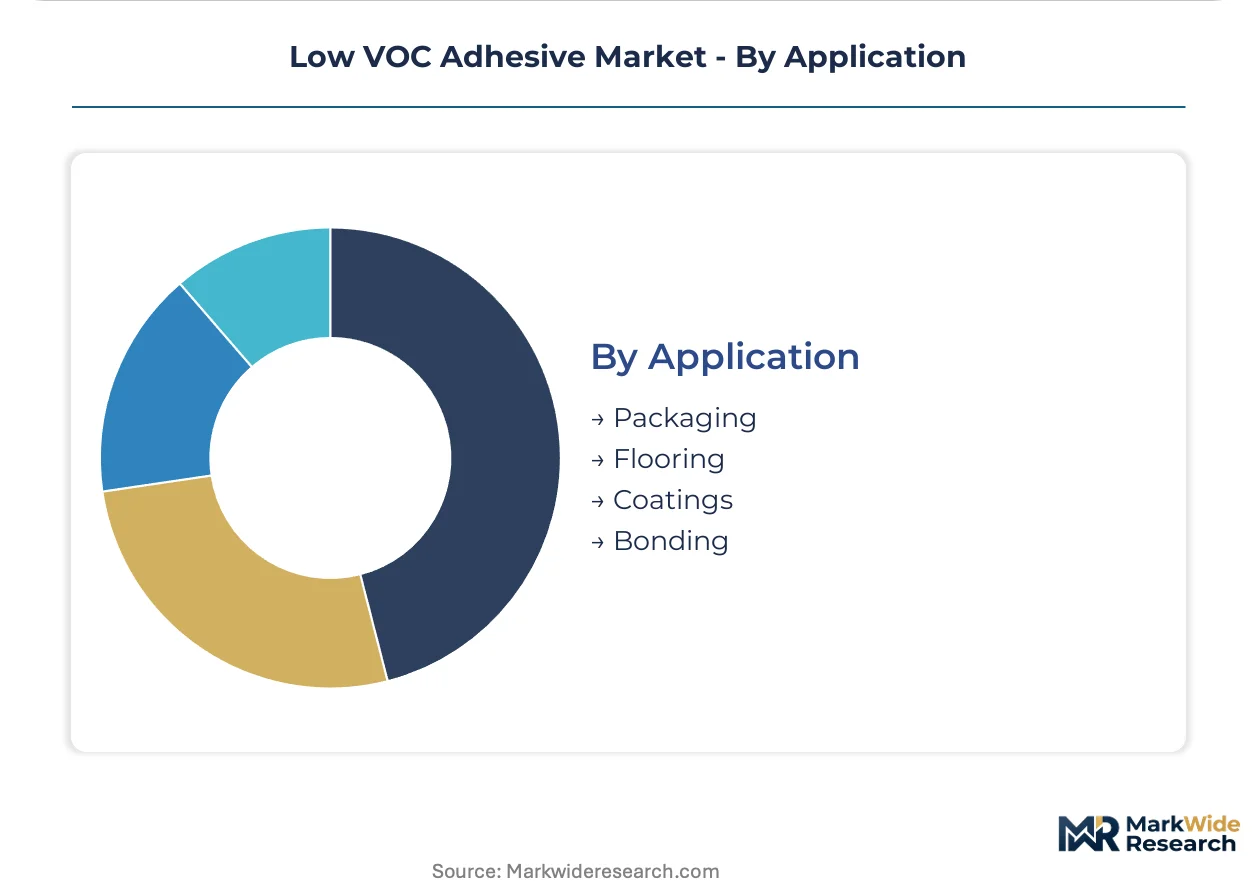
Construction commands the largest absolute volume; automotive captures the steepest expansion trajectory.
Formulation:
Margin concentration aligns with performance tier, where structural capabilities command premium positioning over commodity dispersion products.
- Polyurethane:Reactive prepolymer systems deliver tensile strength and flexibility for demanding substrates. Petrochemical feedstock volatility in isocyanate and polyol markets compresses margin pools for formulators serving automotive and construction segments.
- Acrylic:Water-based dispersions dominate consumer-facing applications where odor sensitivity peaks. Henkel maintains formulation leadership through European R&D investment in dispersion stability technologies.
- Epoxy:Rigid structural bonding for industrial and electronics applications.
- Silicone:Temperature-resistant sealing for exterior and high-heat environments.
Polyurethane anchors premium margin pools; acrylic sustains volume leadership.
Application:
Customer type fragmentation separates specification authority between architect-driven building projects and operations-managed packaging lines.
- Packaging:Hot melt reactive polyurethane systems accelerate line speeds in e-commerce fulfillment centers. H.B. Fuller competes aggressively in this segment where brand strength and channel control protect margin pools.
- Flooring:Installation contractors in Germany concentrate specification authority for low-VOC bonding systems compliant with REACH registration requirements. Building information modeling databases now filter products by EPD certification before RFQ issuance.
- Coatings:Protective and decorative surface treatments with emission constraints.
- Bonding:General assembly applications across industrial manufacturing.
Packaging is gaining share fastest; flooring maintains specification depth in European construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German formulators export water-based polyurethane dispersions to furniture manufacturers across France and Benelux, while US producers ship hot melt reactive systems to Mexican packaging converters serving cross-border e-commerce fulfillment networks.
United States
Automotive OEMs in Michigan and Ohio are converting structural bonding lines to reactive polyurethane systems ahead of EPA Tier 3 enforcement deadlines. CARB SCM 2007 amendments tighten emission thresholds for consumer products manufactured in California. Houston-area petrochemical corridors supply isocyanate feedstocks to formulators serving construction and packaging segments.
Germany
Flooring contractors in Bavaria and North Rhine-Westphalia mandate REACH-compliant bonding systems for commercial installation projects. The EU F-Gas Regulation drives specification shifts toward water-based acrylics in residential furniture applications. Henkel maintains R&D operations in Düsseldorf that anchor European formulation leadership for dispersion technologies.
China
Construction activity in the Yangtze River Delta concentrates demand for low-VOC waterproofing adhesives in high-rise commercial developments. GB standards for indoor air quality in building materials tighten specification requirements for imported formulations. Shanghai-based distributors are qualifying European water-based systems for luxury residential projects.
India
Commercial real estate developers in Maharashtra and Karnataka specify BIS-certified green building materials for LEED-equivalent projects. The country's national standards body is expanding certification requirements for flooring adhesives in institutional construction. Mumbai and Bangalore contractors are consolidating procurement with formulators who maintain in-house testing laboratories.
Japan
Electronics manufacturers in the Kanto region demand precision-dispensing reactive chemistries for miniaturized device assembly. METI guidelines for chemical substance management constrain residual monomer content in imported formulations. Osaka-area automotive suppliers are qualifying bio-based polyurethane prepolymers for seating applications.
Low VOC Adhesive Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with adhesive divisions operating alongside construction and consumer goods portfolios. Market structure concentrates specification authority with formulators who maintain certified laboratories and direct OEM relationships. Strategic archetypes include European dispersion specialists, North American hot melt scale players, and Asian construction-grade suppliers. Competitive moves center on geographic expansion into Indian commercial construction and portfolio diversification into medical device bonding segments.
Within the diversified chemical conglomerate tier, Henkel and Sika AG exemplify formulation leadership archetypes that anchor regional specification networks. H.B. Fuller occupies a position among North American scale-driven specialists where channel control and brand recognition protect position in packaging applications. These three entities represent distinct competitive vectors: European R&D-intensive dispersion technology, construction-grade geographic dominance, and high-volume hot melt production systems.
| Leading Market Players |
|---|
| Sika AG |
| Ashland |
| Henkel |
| Pidilite Industries |
| Huntsman Corporation |
| 3M |
| Arkema |
| Bostik |
| H.B. Fuller |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day formulation qualification cycles concentrate pricing power with certified suppliers in Germany and the United States, while inventory buffers at automotive OEMs compress spot-market leverage for uncertified entrants. This lead-time band tightens whenever EPA enforcement windows or REACH registration deadlines compress procurement calendars.
Pricing Analysis
Water-based acrylic dispersion systems trade at a 15-25% discount to reactive polyurethane platforms, while next-generation bio-based prepolymers command modest premiums pending OEM qualification completion. Three-tier pricing structure across premium reactive systems, standard water-based dispersions, and economy-grade hot melts reflects certification burden and performance tier. Cost compression in mid-tier water-based segments is intensifying because petrochemical feedstock volatility squeezes formulator margins. Packaging converters in e-commerce fulfillment exhibit highest price sensitivity, whereas automotive material review boards prioritize performance compliance over unit cost.
Supply Chain Analysis
Isocyanate precursor availability through the Houston Ship Channel corridor anchors North American reactive polyurethane production capacity. Manufacturing gravity centers on Germany, the United States, and China for distinct chemistry platforms—water-based dispersions, reactive systems, and construction-grade formulations respectively. Raw material sourcing draws from crude oil derivatives, bio-based castor oil feedstocks, and specialty catalyst packages. Single-source vulnerability concentrates in European dispersion stabilizer supply. Distribution runs through direct OEM relationships for automotive and construction segments, with packaged goods flowing through specialized chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because regulatory entrenchment—EPA 40 CFR Part 59, CARB SCM 2007, and REACH registration—creates twelve-to-eighteen-month qualification barriers that protect incumbent specification positions.
For Market Incumbents: Shield formulation leadership by deepening backward integration into bio-based feedstock supply chains, particularly castor oil derivatives for automotive seating applications. Accelerate certification investment in Indian BIS pathways before green building material requirements tighten. Channel control through direct specification relationships with architecture and engineering firms offers additional defensive leverage against emerging water-based specialists. For New Entrants and Emerging Players: Lead with medical device bonding applications where FDA biocompatibility pathways remain underpenetrated by established construction-grade suppliers. India's commercial real estate sector presents the most penetrable geography given nascent BIS enforcement and fragmented contractor procurement. A laboratory-services-first go-to-market angle—certified VOC testing bundled with formulation supply—sidesteps incumbent specification entrenchment. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because emission thresholds tighten predictably while qualification timelines extend. Acquisition targets should screen for certified laboratory infrastructure and active OEM material review board relationships. The signal to watch is CARB amendment timing, which accelerates specification shifts and concentrates procurement with pre-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Castor oil and soybean prepolymer sourcing secures margin protection against petrochemical volatility. |
| Certified Laboratory Infrastructure Expansion | In-house EPA and REACH testing capability accelerates product launch cycles and retains OEM vendor status. |
| Digital Specification Platform Integration | Building information modeling database embedding captures architect-driven flooring and construction procurement. |
| Medical Device Bonding Qualification | FDA biocompatibility pathway entry opens high-margin wearable diagnostics demand outside construction commoditization. |
| Indian BIS Certification Pre-Positioning | Early green building material compliance locks in specification windows for Maharashtra and Karnataka commercial developments. |
Study Parameters
Initial hypotheses were tested against primary input from adhesive formulator R&D directors, automotive OEM material engineers, flooring contractor procurement leads, and packaging line operations managers, then refined through secondary validation. Primary fieldwork combined structured interviews with technical specification stakeholders and channel distribution partners. Secondary sources included EPA enforcement action databases, ECHA REACH registration dossiers, customs trade flow records, and SEC filings from diversified chemical conglomerates. Bottom-up volume modeling triangulated against top-down regulatory-driven demand projections.
Variance decomposition across chemistry platform, end-use segment, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include product type, formulation chemistry, application, and geographic production hub. CAGRs were derived from elasticity-adjusted demand curves and input cost trajectory assumptions. Industry-specific forecast inputs incorporated automotive platform electrification content shifts and e-commerce packaging throughput acceleration indices.
Forecasts assume regulatory continuity in EPA Tier 3, CARB SCM 2007, and EU F-Gas enforcement regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as bio-based feedstock cost parity and Indian BIS certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Tissue Adhesives Market