
 Epoxy Putty and Construction Chemicals Market | 2026-2036
Epoxy Putty and Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Putty and Construction Chemicals Market Foresight
The split between premium formulation tiers and commodity-grade alternatives is hardening as certification requirements diverge. Sika AG leverages its European testing infrastructure to sustain specification-grade positioning across infrastructure repair channels. BASF SE anchors its portfolio through backward integration into specialty epoxy resin production, while MAPEI S.p.A. competes on tiling system bundling that locks in grout and adhesive specification.
Epoxy putty and construction chemicals comprise reactive polymer systems—typically bisphenol-A or bisphenol-F epoxies cured with amine or polyamide hardeners—engineered for structural bonding, gap filling, and surface protection in built environments. These materials achieve compressive strengths exceeding 80 MPa and bond tenaciously to concrete, steel, and masonry substrates under ambient cure conditions. Tile adhesive and grout command the largest value share within product type segmentation due to their ubiquity in residential and commercial finishing trades, while infrastructure repair represents the fastest-expanding application channel as public agencies prioritize life-extension over replacement. Sealant formulations carry the highest margin pools where movement accommodation and weatherproofing performance justify premium positioning.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent content in construction chemical manufacturing, while REACH registration in Europe mandates full toxicological dossiers for epoxy constituents above one-tonne thresholds. OSHA exposure limits for amine hardeners further shape workplace handling protocols and drive demand for low-sensitization curing agents. Stakeholders must monitor regulatory preemption risks as state-level VOC rules in California and emerging GB standards in China potentially outpace federal harmonization, forcing parallel formulation tracks or geographic SKU fragmentation.
Market Dynamics
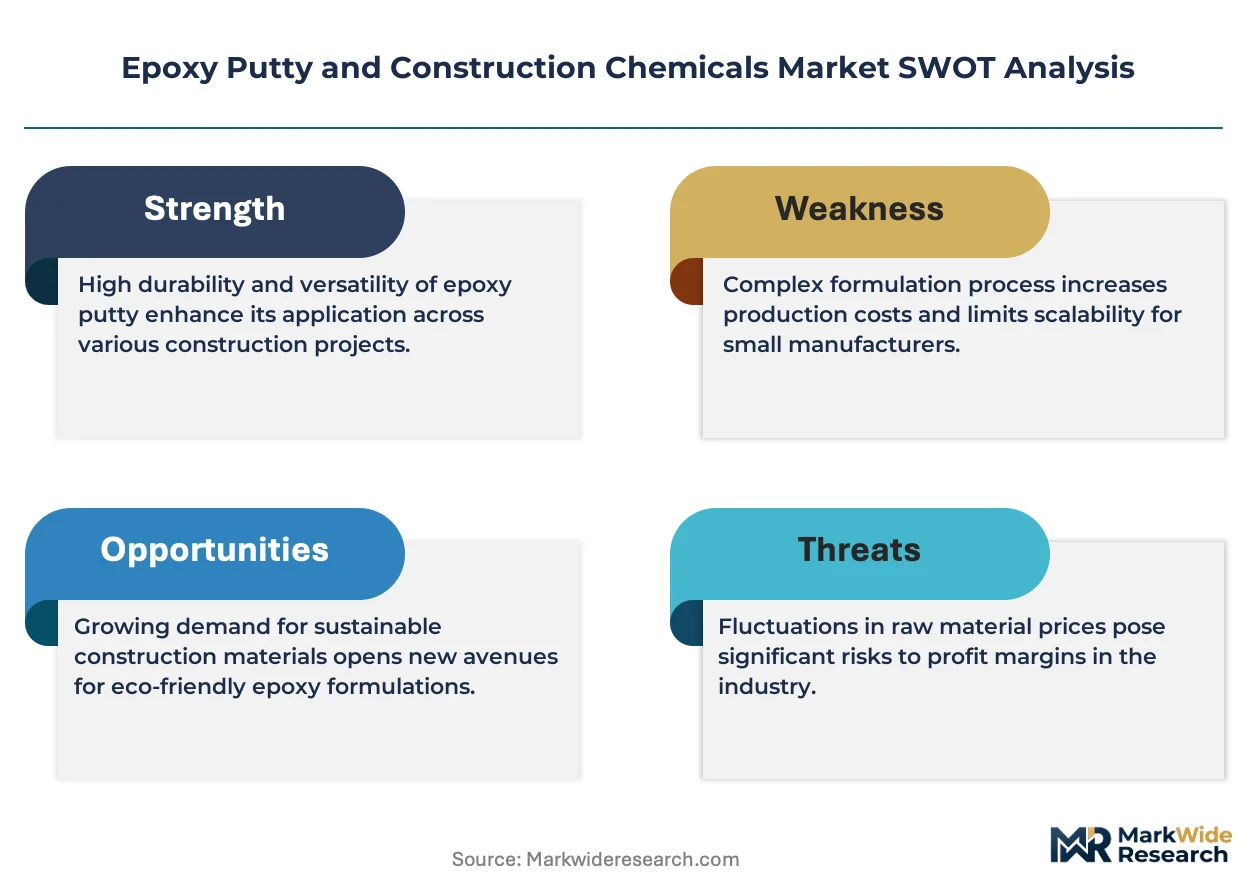
REACH compliance deadlines and EPA NESHAP solvent limits are bifurcating formulation portfolios, forcing parallel development tracks for specification-grade and commodity product lines.
Growth Catalysts
- Infrastructure life-extension mandates:Public agencies in Germany and Japan prioritize structural reinforcement over replacement, accelerating specification-grade epoxy consumption for bridge deck and tunnel lining repairs.
- GB standards evolution:China's tightening VOC limits under MEE oversight push domestic manufacturers toward low-emission curing systems, creating upgrade cycles across construction chemical portfolios.
- High-speed rail maintenance:China's network expansion generates sustained volume demand for rapid-cure epoxy compounds in track bed stabilization and platform edge repairs.
Market Restraints
- Epichlorohydrin feedstock volatility:Bisphenol-A epoxy resin production faces margin compression from fluctuating chlor-alkali chain inputs, particularly affecting European and North American compounders lacking backward integration.
- Amine hardener supply concentration:Specialty polyamide and cycloaliphatic curing agent production clusters in Germany and the United States, creating single-source vulnerability for formulators in other geographies.
- Cementitious grout substitution:Mineral-based repair mortars compete in non-structural gap-filling applications, pressuring commodity-grade epoxy putty volumes in residential finishing channels.
Strategic Opportunities
- Offshore wind foundation protection:Monopile and jacket structure corrosion shielding in the North Sea and Baltic markets creates specification-grade volume for solvent-free epoxy coating systems.
- EU Green Deal procurement criteria:Embedded carbon thresholds in public construction tendering favor low-emission formulation platforms, rewarding early movers with EPD-certified product ranges.
- Prefabrication construction:Modular building assembly in Japan and South Korea demands structural adhesives with controlled cure profiles, opening specification channels distinct from traditional site-applied repair.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in amine-epoxy stoichiometry and low-temperature cure kinetics concentrates at legacy European and Japanese compounders, constraining new entrant R&D velocity.
- Multi-jurisdiction registration burdens:Parallel REACH, EPA, and emerging state-level VOC compliance creates SKU fragmentation, complicating inventory management for distributors serving cross-border infrastructure contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Putty and Construction Chemicals Market |
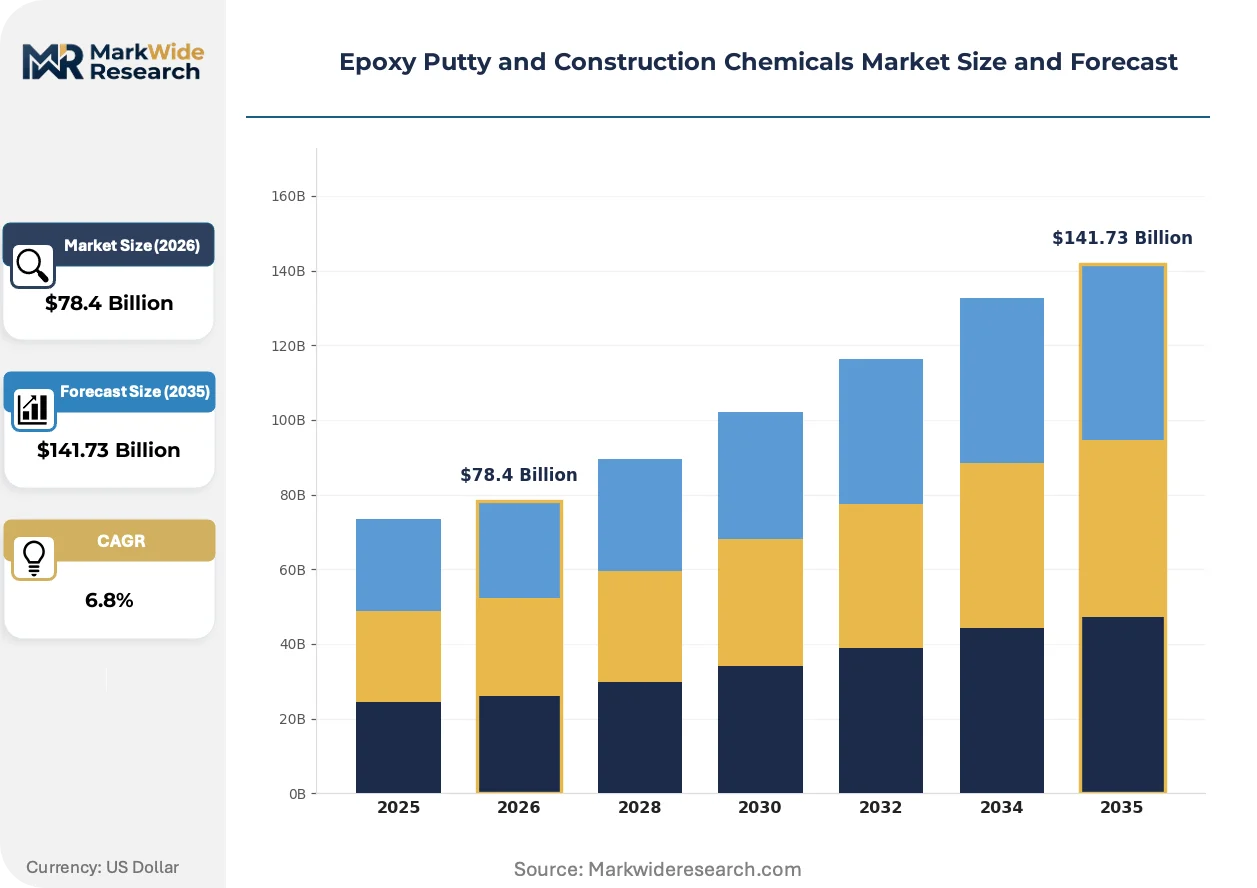
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Putty, Tile Adhesive, Grout, Sealant Application: Residential Construction, Commercial Construction, Industrial Maintenance, Infrastructure Repair End User: Contractors, DIY Consumers, Engineers, Architects Distribution Channel: Online Retail, Direct Sales, Distributors, Hardware Stores |
| Companies Covered | Sika AG, BASF SE, Henkel AG & Co. KGaA, RPM International Inc., 3M Company, PPG Industries, Inc., Saint-Gobain, MAPEI S.p.A., Fosroc International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Putty and Construction Chemicals Market Shifts & Advancements
Bio-based feedstock substitution and digital specification workflows are restructuring how construction chemicals achieve technical approval and procurement preference across infrastructure channels.
Hybrid curing systems combining epoxy backbone chemistry with polyurethane or silane termination are integrating into structural bonding formulations for cold-weather infrastructure repair. German and Scandinavian contractors adopt these platforms to extend outdoor construction seasons, compressing the traditional April-October application window and enabling year-round maintenance scheduling for bridge and tunnel assets.
REACH registration dossiers for epoxy constituents above one-tonne thresholds now mandate full toxicological profiles, forcing reformulation away from certain aromatic amine hardeners. European formulators respond by accelerating aliphatic and waterborne curing agent development, with sealant and coating segments most affected due to their higher hardener loading ratios.
Specification workflows increasingly route through BIM-integrated procurement platforms that embed product performance data directly into structural engineering models. Large infrastructure contractors in the United States and United Kingdom now require digital EPD and technical datasheet integration, displacing traditional catalog-based supplier relationships with algorithmic compliance filtering that favors pre-certified formulation platforms.
Epoxy Putty and Construction Chemicals Market Segmentation
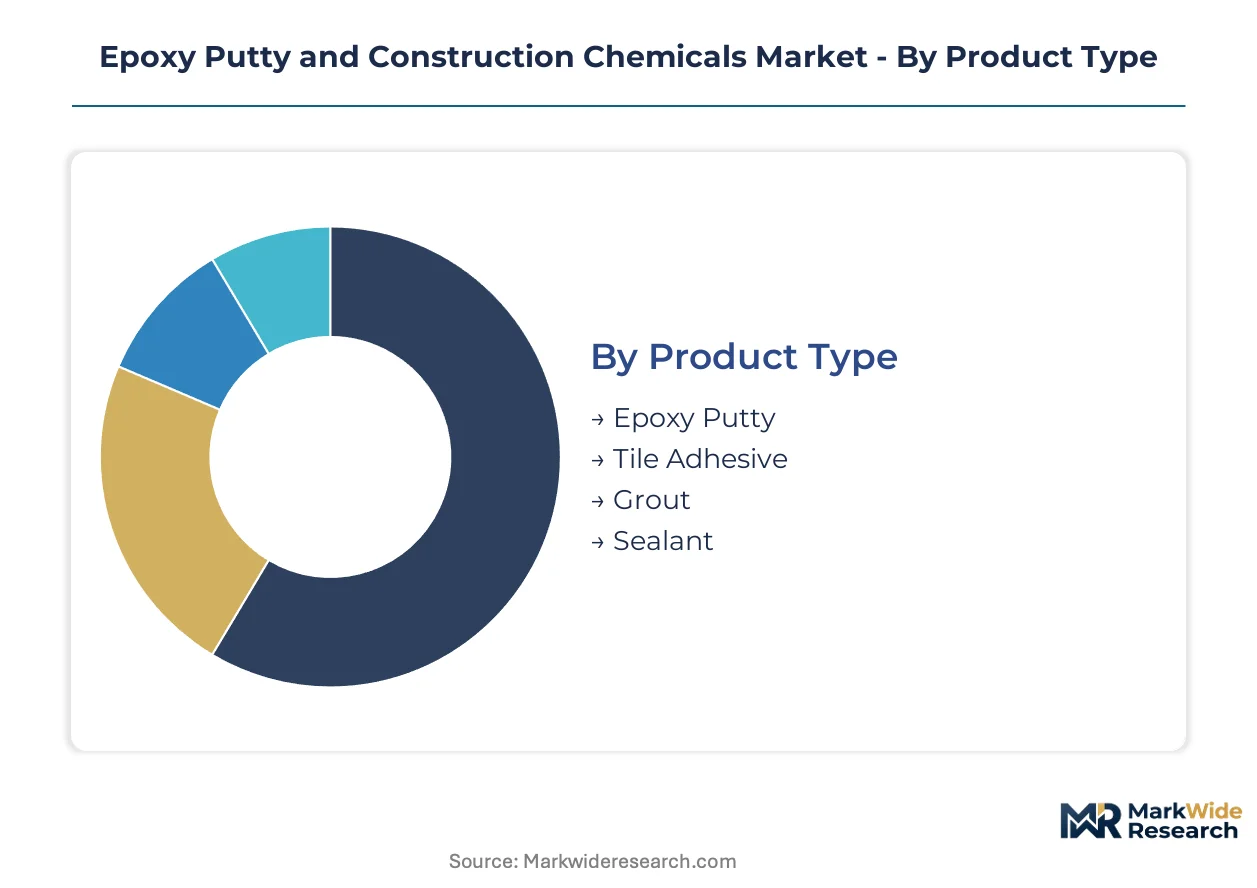
Segmentation in epoxy putty and construction chemicals reveals how specification requirements diverge across application environments. Product chemistry, cure profiles, and certification tiers fragment demand into distinct procurement channels with limited substitutability.
Product Type:
Formulation chemistry and performance certification separate specification-grade systems from commodity alternatives.
- Tile Adhesive:Cementitious and epoxy-modified systems bond ceramic, porcelain, and natural stone finishes to concrete and masonry substrates. Demand concentrates in China's urban renewal corridors where high-rise residential completions sustain volume for polymer-modified thin-set formulations. REACH-compliant low-VOC variants command specification preference in German public housing tenders.
- Grout:Epoxy grout delivers chemical resistance and stain immunity for commercial kitchen, healthcare, and industrial floor finishes. Japanese railway station renovations and airport terminal upgrades in the United Kingdom specify these systems for high-traffic environments where cementitious alternatives fail. Sanded and unsanded variants match joint width requirements from 1.5mm to 12mm.
- Epoxy Putty:Hand-kneadable repair compounds fill voids, rebuild profiles, and restore structural integrity to damaged concrete and metal substrates.
- Sealant:Elastomeric formulations accommodate joint movement while blocking moisture and chemical ingress.
Mature deployment sits with tile adhesive and grout in residential finishing trades. Newer deployment is concentrated in epoxy putty for infrastructure life-extension programs.
Application:
Load-bearing requirements and environmental exposure dictate formulation selection across built environment segments.
- Infrastructure Repair:Structural bonding, crack injection, and surface restoration of bridges, tunnels, and marine assets demand high-modulus epoxy systems with compressive strength exceeding 80 MPa. Germany's Autobahn bridge deck rehabilitation programs and Japan's Shinkansen tunnel lining repairs specification-lock suppliers into multi-year maintenance contracts. Cold-weather cure kinetics extend application seasons in Scandinavian markets.
- Industrial Maintenance:Chemical containment, secondary containment, and equipment foundation grouting in petrochemical and food processing facilities require chemical-resistant formulations. US Gulf Coast refineries and Rotterdam port terminals specify novolac epoxy variants for sulfuric acid and solvent exposure.
- Residential Construction:Flooring, countertop, and decorative coating applications drive volume for self-leveling and metallic epoxy systems.
- Commercial Construction:High-traffic retail, healthcare, and institutional finishes specify antimicrobial and slip-resistant epoxy coatings.
Specification-grade deployment dominates infrastructure repair. Volume deployment concentrates in residential construction.
End User:
Technical sophistication and procurement authority shape product selection and channel access.
- Engineers:Structural and materials engineers specify epoxy systems through performance-based procurement criteria embedded in BIM workflows. United Kingdom infrastructure contractors now require digital EPD integration and cure-kinetic modeling data, filtering supplier pools to pre-certified formulation platforms.
- Contractors:Specialist applicators in concrete repair, waterproofing, and industrial flooring trades purchase through distributor networks with technical support capabilities. German and Austrian contractors maintain preferred supplier agreements with Sika and MAPEI for specification continuity across project portfolios.
- Architects:Aesthetic and sustainability criteria drive finish selection in commercial and institutional projects.
- DIY Consumers:Small-format epoxy putty and repair kits serve residential maintenance and hobby applications.
Professional specification authority rests with engineers. Contractor execution determines field performance outcomes.
Distribution Channel:
Technical complexity and project scale fragment procurement routes across direct and intermediated channels.
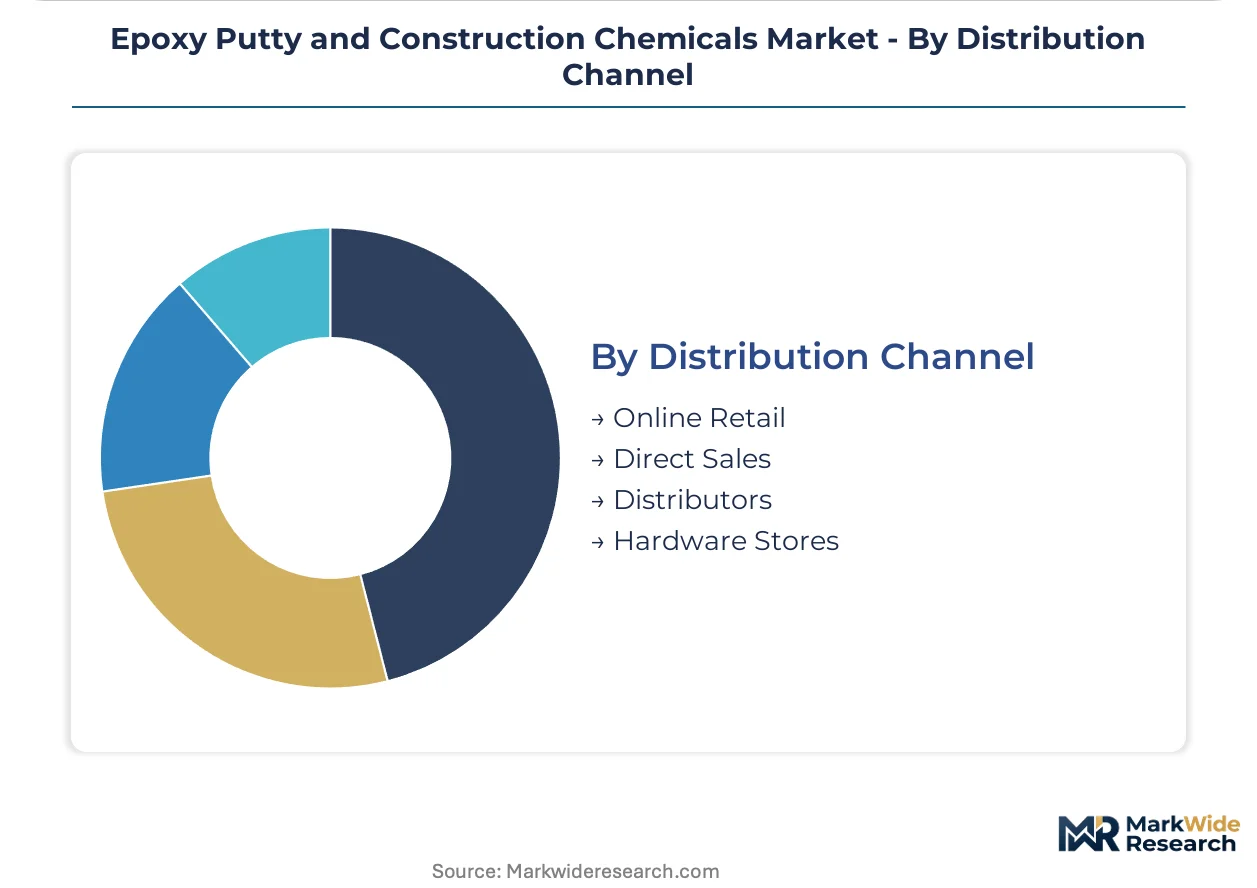
- Distributors:Regional construction chemical specialists inventory specification-grade formulations and provide on-site technical support for mixing ratios, substrate preparation, and cure monitoring. US-based distributors serving Department of Transportation contractors maintain certified applicator training programs to secure specification lock-in.
- Direct Sales:Large infrastructure contractors and industrial facility owners procure bulk formulations directly from manufacturers for major rehabilitation projects. China's high-speed rail maintenance bureaus negotiate direct supply agreements with domestic epoxy compounders for track bed stabilization compounds.
- Hardware Stores:Retail channels serve residential and light commercial repair applications with pre-packaged epoxy putty and tile adhesive SKUs.
- Online Retail:E-commerce platforms capture DIY and small contractor demand for standardized products with established performance reputations.
Specification-grade volume flows through distributors. Commodity-grade volume is shifting toward online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the highest-volume demand corridor for epoxy construction chemicals, with Pudong and Yangshan port zones handling bulk resin imports for Yangtze River Delta compounding operations.
China
High-speed rail maintenance bureaus in Beijing and Chengdu drive specification-grade epoxy consumption for track bed stabilization. MEE enforcement of GB 30982-2014 VOC limits forces domestic formulators toward waterborne curing systems. The Pearl River Delta cluster around Guangzhou and Shenzhen concentrates manufacturing for export-grade tile adhesive formulations.
Germany
Autobahn bridge deck rehabilitation programs in Bavaria and North Rhine-Westphalia sustain multi-year maintenance contracts for structural epoxy injection systems. REACH registration dossiers mandate full toxicological profiles for amine hardeners above one-tonne thresholds. The BASF Ludwigshafen complex anchors specialty epoxy resin production serving infrastructure repair channels across Central Europe.
United States
Department of Transportation contractors in Texas and California specification-lock suppliers through certified applicator training programs. EPA NESHAP solvent limits constrain manufacturing in Houston and New Jersey chemical corridors. Gulf Coast refineries in Louisiana and Texas specify novolac epoxy variants for secondary containment and chemical-resistant flooring.
Japan
Shinkansen tunnel lining repairs in the Tohoku and Chubu regions generate sustained demand for rapid-cure epoxy compounds. METI industrial standards govern low-temperature cure kinetics for cold-weather infrastructure applications. The Osaka-Kobe industrial zone concentrates formulation expertise for hybrid polyurethane-epoxy structural bonding systems.
United Kingdom
Crossrail and HS2 infrastructure contractors require digital EPD integration and BIM-embedded procurement workflows. UK Green Deal procurement criteria favor low-emission formulation platforms with embedded carbon thresholds below 2.5 kg CO2e per kg product. Manchester and Birmingham urban renewal corridors drive volume for polymer-modified tile adhesive in high-rise residential completions.
Epoxy Putty and Construction Chemicals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier differentiation, with specification-grade formulators capturing infrastructure repair contracts while economy-grade suppliers compete on residential finishing volumes. The vendor base fragments across three strategic tiers: European testing-anchored specification houses, backward-integrated resin producers, and regional tiling-system bundlers. Consolidation pressure intensifies as REACH compliance costs and multi-jurisdiction registration burdens favor scaled players with dedicated regulatory affairs infrastructure. Dominant competitive moves include geographic SKU rationalization to reduce parallel formulation tracks and captive supply integration into specialty amine hardener production.
Among European-based specification-grade compounders, Sika AG, BASF SE, and MAPEI S.p.A. occupy positions across distinct competitive vectors. Sika exemplifies the testing-infrastructure archetype leveraging Swiss and German certification facilities for infrastructure channel lock-in. BASF represents backward integration into specialty epoxy resin production, anchoring margin control through captive bisphenol-A and bisphenol-F feedstock access. MAPEI sits within the tiling-system bundling tier, using grout and adhesive specification continuity to defend distributor relationships across Mediterranean and Middle Eastern markets. These three players collectively illustrate how formulation expertise, supply chain configuration, and application-specific certification create defensible positioning against commodity-grade Asian imports.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Henkel AG & Co. KGaA |
| RPM International Inc. |
| 3M Company |
| PPG Industries, Inc. |
| Saint-Gobain |
| MAPEI S.p.A. |
| Fosroc International Ltd. |
| Others |
Supply & Pricing Matrix
EU Green Deal embedded carbon thresholds gate qualified supply for premium-tier epoxy construction chemicals, restricting specification-grade access to formulators with EPD-certified product ranges and validated low-emission curing systems. This environmental mandate bifurcates procurement pools: contractors meeting public tender criteria pay structural premiums while commodity-grade alternatives compete on thinner margins in residential finishing channels.
Pricing Analysis
Value-based pricing anchored to infrastructure uptime and structural warranty outcomes dominates specification-grade epoxy procurement for bridge deck and tunnel rehabilitation contracts. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified systems from REACH-compliant alternatives and uncertified commodity grades. Cost compression in the economy tier intensifies because cementitious grout substitutes erode epoxy putty volumes in non-structural residential applications. DIY consumers and small residential contractors exhibit highest price sensitivity; infrastructure agencies prioritize performance guarantees over unit cost.
Supply Chain Analysis
Epichlorohydrin feedstock supply rests on chlor-alkali chain producers in Germany, the United States, and China, with specialty amine hardener production clustering in German and US chemical corridors. Bisphenol-A and bisphenol-F epoxy resins draw from integrated petrochemical complexes, while cycloaliphatic curing agents hinge on concentrated specialty chemical manufacturing. Single-source vulnerability in amine hardener supply creates structural risk for formulators lacking backward integration into captive curing agent production. Distribution runs through regional construction chemical specialists providing technical support and certified applicator training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epoxy putty and construction chemicals market sits in a formulation technology transition, with hybrid polyurethane-epoxy curing systems and waterborne low-emission platforms displacing legacy aromatic amine-based systems in cold-weather and high-VOC-regulated applications.
For Market Incumbents: Extend specification-grade positioning through captive integration into specialty aliphatic amine hardener production, insulating margin structures from feedstock volatility and supply concentration risks. Deepen certification infrastructure investment for BIM-embedded procurement workflows, as digital EPD integration becomes a filter criterion for UK and US infrastructure contractors. Cementitious grout substitution in residential finishing channels threatens commodity-grade volume; defend distributor relationships through bundled tiling system offerings that lock in grout and adhesive specification continuity. For New Entrants and Emerging Players: Launch via direct supply agreements with China's high-speed rail maintenance bureaus, targeting rapid-cure epoxy compounds for track bed stabilization where domestic formulators face MEE-mandated reformulation delays. Prefabrication construction in Japan and South Korea presents the most penetrable white-space, with modular building assembly demanding structural adhesives with controlled cure profiles distinct from traditional site-applied repair. Pursue specification entry through hybrid curing system development for Scandinavian cold-weather infrastructure seasons. For Investors and Strategic Acquirers: EU Green Deal procurement criteria mandating embedded carbon thresholds below 2.5 kg CO2e per kg product is the leading indicator that EPD-certified formulation platforms will capture disproportionate infrastructure repair volume across European public tendering. Long-term viability favors backward-integrated compounders with captive specialty resin production and established REACH dossier infrastructure. Acquisition target archetype: mid-tier European formulators with testing infrastructure assets but lacking hardener integration, positioned for consolidation into scaled regulatory affairs platforms. Watch GB standards evolution under MEE oversight as the signal for Chinese domestic manufacturer upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Amine Production | Captive curing agent supply insulates margins from German and US supply concentration risks. |
| EPD Certification for EU Green Deal Compliance | Embedded carbon thresholds in public tendering favor pre-certified low-emission formulation platforms. |
| Hybrid Curing System Development | Polyurethane-epoxy platforms extend Scandinavian infrastructure repair seasons beyond traditional windows. |
| BIM-Integrated Digital Specification Workflows | Algorithmic compliance filtering in UK and US procurement displaces catalog-based supplier relationships. |
| Regional SKU Rationalization | Parallel REACH, EPA, and state-level VOC compliance forces geographic formulation consolidation. |
Research Methodology
Multi-period observation of MEE enforcement actions, REACH registration timelines, and infrastructure tender award patterns anchored the trend analysis, supplemented by interviews with epoxy formulation R&D directors, construction chemical procurement leads at German Autobahn maintenance agencies, distributor technical support specialists, and US Department of Transportation contract officers. Secondary validation drew from ECHA registration dossiers, EPA NESHAP compliance disclosures, Chinese customs trade data for epoxy resin imports, and Cefic construction chemical production reports. Bottom-up volume modeling across product chemistry tiers triangulated against top-down infrastructure spending forecasts.
The input-output matrix framed demand projections across the analysis window, modeling segmentation dimensions including formulation grade tier, application environment, end-user technical sophistication, and regional regulatory cluster. CAGRs derived from elasticity-adjusted infrastructure maintenance spending correlations and substitution rate assumptions for cementitious alternatives. Industry-specific forecast inputs incorporated epichlorohydrin feedstock price volatility indices and GB standards implementation timelines.
Feedstock price shocks, regulatory preemption by state-level VOC rules, and formulation chemist scarcity are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about MEE enforcement intensity and EU Green Deal procurement adoption rates. A small set of named triggers—MEE inspection frequency increases, ECHA substance restriction proposals, and US infrastructure bill allocation timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market